
 Aircraft Cabin Management System Market | 2026-2036
Aircraft Cabin Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cabin Management System Market Analytics
Aerospace software engineering talent is bifurcating between legacy avionics protocols and modern IoT architectures, constraining OEM delivery timelines for next-generation cabin platforms. RTX (Collins Aerospace) leverages its deep integration with Boeing and Airbus supply chains to sustain long-term program visibility. Safran SA anchors European aftermarket demand through Lufthansa Technik partnerships. Honeywell International Inc. differentiates via proprietary wireless cabin architectures that reduce aircraft wiring weight.
An aircraft cabin management system comprises the integrated hardware and software infrastructure that controls passenger-facing environmental, entertainment, and communication functions, typically operating through ARINC 429 or Ethernet-based databus architectures with DO-178C software assurance levels. The system serves the primary commercial purpose of enhancing passenger experience while reducing crew workload and aircraft empty weight through centralized digital control. Wired communication technology still dominates installed base economics, though wireless communication segments capture disproportionate R&D investment as airlines seek faster retrofit cycles and reduced downtime. Business aviation end users represent the fastest-growing demand pool as fractional ownership models multiply aircraft utilization rates. Integrated systems command premium positioning due to their consolidation of multiple discrete functions into single Line Replaceable Units.
FAA Part 25 certification requirements and EASA CS-25 standards collectively govern system airworthiness, with both regulators expanding cybersecurity mandates for connected cabin architectures under evolving special conditions. The EU AI Act introduces emerging compliance obligations for predictive maintenance algorithms embedded in cabin management software. EASA's recent special condition publications on wireless cabin systems are reshaping manufacturer development roadmaps. Stakeholders must monitor whether FAA-EASA harmonization on cybersecurity certification timelines accelerates or fragments market access for new entrants.
Market Dynamics
Wireless cabin architectures are forcing a fundamental re-architecture of aircraft wiring harnesses, compressing retrofit timelines from months to weeks while triggering recertification bottlenecks under FAA-EASA harmonization delays.
Growth Catalysts
- DO-178C software assurance mandates:FAA Part 25 tightening for connected cabin systems accelerates replacement cycles for legacy ARINC 429 installations.
- Business aviation fractional ownership:Rising aircraft utilization rates among fleet operators multiply demand for integrated cabin control platforms.
- Wichita-Pacific Northwest supplier clustering:Geographic concentration of OEM and MRO capabilities reduces logistics friction for North American retrofit programs.
Market Restraints
- Copper wiring weight penalties:Traditional harness architectures impose ongoing fuel burn costs that wireless alternatives cannot yet fully offset.
- Dual-certification timeline fragmentation:FAA-EASA divergence on cybersecurity special conditions extends program validation for new entrants.
- Legacy fleet lock-in:ARINC 429 databus infrastructure creates path dependency that slows Ethernet migration economics.
Strategic Opportunities
- Predictive maintenance algorithm deployment:EU AI Act compliance pathways create first-mover advantage for software-embedded cabin diagnostics.
- Line Replaceable Unit consolidation:Integrated systems that merge environmental, entertainment, and communication functions command premium positioning.
- MRO channel bypass models:Direct-to-operator wireless retrofit kits disrupt traditional maintenance provider intermediation.
Industry Challenges
- DO-178C software engineering scarcity:Talent bifurcation between legacy avionics protocols and IoT architectures constrains OEM delivery timelines.
- Legacy-ethernet integration complexity:Hybrid databus architectures demand specialized integration expertise that stretches program resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cabin Management System Market |
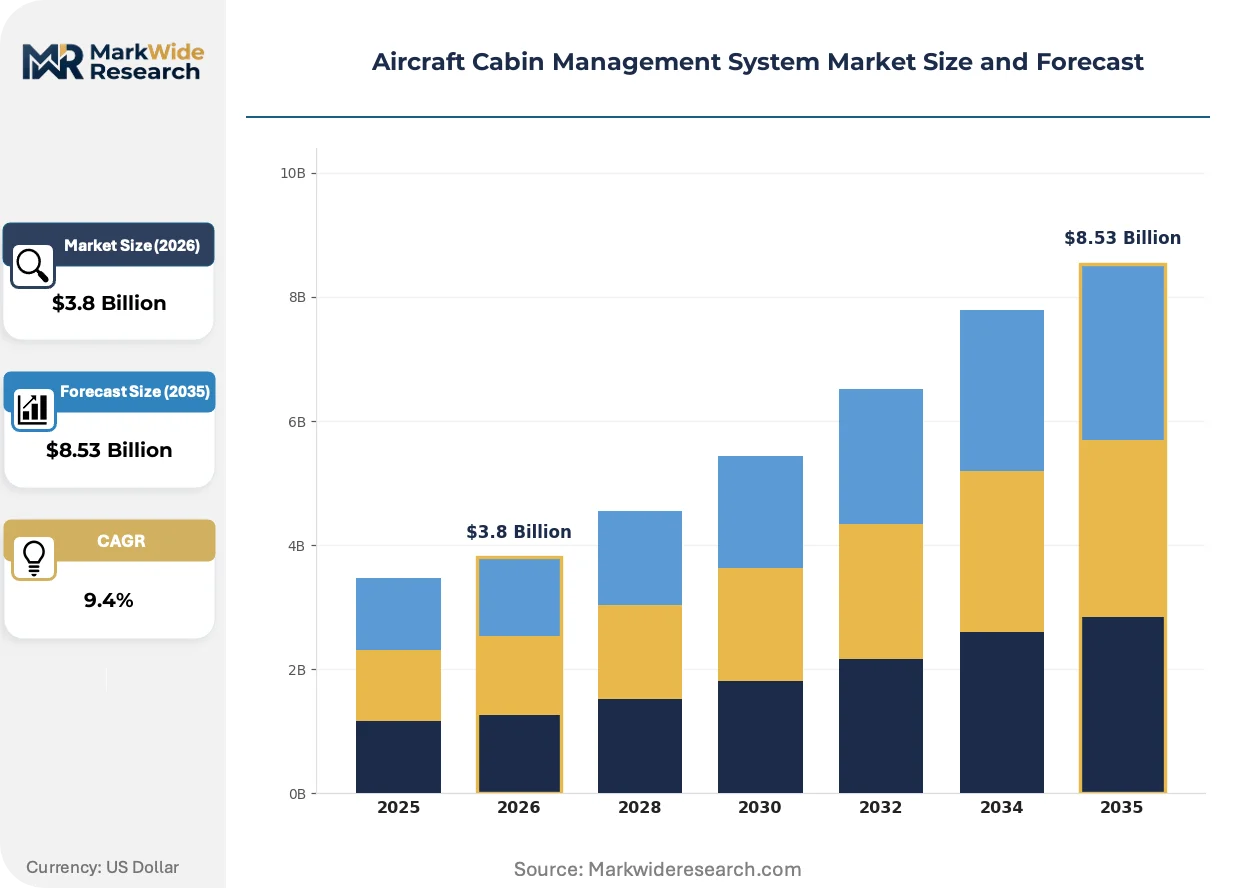
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated System, Control Unit, Display Panel, Cabin Management Software Technology: Wired Communication, Wireless Communication, IoT Integration, Cloud-based Solutions End User: Commercial Aviation, Business Aviation, Military Aviation, Helicopter Operators Application: In-flight Entertainment, Lighting Control, Climate Management, Passenger Communication |
| Companies Covered | Airbus, Astronics Corporation, RTX (Collins Aerospace), Safran SA, Panasonic Avionics Corporation, Honeywell International Inc., Diehl Stiftung & Co. KG, Heads Up Technologies, Lufthansa Technik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cabin Management System Market Evolving Landscape
Digital cabin platforms are redefining passenger experience architecture through converging wireless, predictive, and lightweight technologies that compress installation downtime.
Ethernet-based databus architectures is supplanting ARINC 429 as the backbone for next-generation cabin control. Business aviation operators retrofitting legacy fleets adopt these platforms fastest due to shorter aircraft downtime tolerances. This migration is supplanting discrete wiring harnesses with consolidated fiber and wireless backbones that reduce empty weight.
EASA's special condition publications on wireless cabin systems are reshaping manufacturer development roadmaps. The regulator's cybersecurity mandates for connected architectures extend certification timelines but create compliance moats for prepared suppliers. European aftermarket providers align product roadmaps with these EASA timelines ahead of FAA harmonization.
After-sales service unbundling is fragmenting traditional MRO relationships. Airlines and fractional operators now procure wireless retrofit modules directly from OEMs, bypassing maintenance intermediaries. This pattern concentrates in the United States where Wichita-based suppliers maintain direct fleet operator relationships.
Aircraft Cabin Management System Market Segmentation
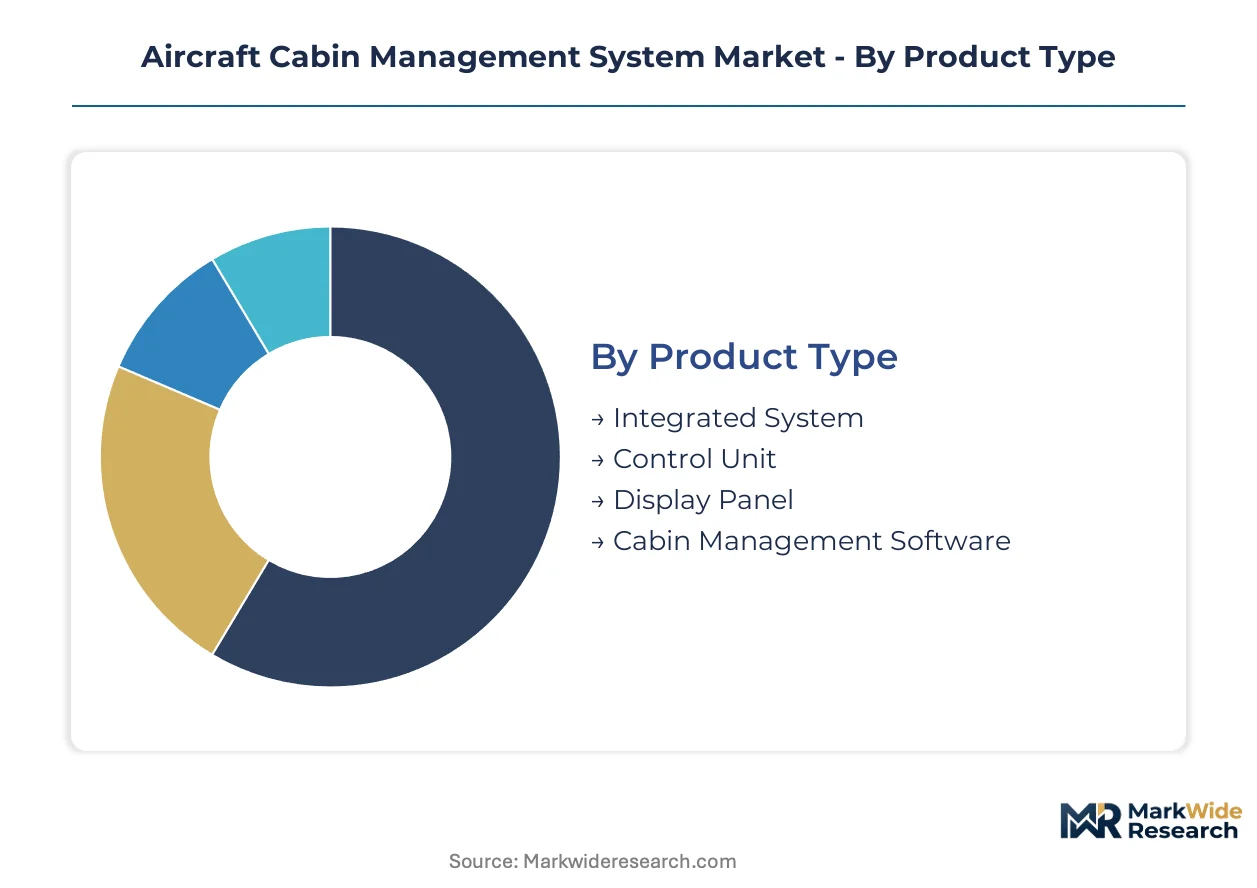
Cabin management system procurement diverges sharply across operator types, with certification requirements and retrofit economics driving fundamentally different technology selections. Product architecture, communication protocol, and end-use mission profile each reshape supplier positioning and pricing power in distinct ways.
Product Type:
FAA Part 25 and EASA CS-25 impose tiered software assurance requirements that elevate integrated systems above discrete components in certification burden and margin capture.
- Integrated System:Consolidates environmental, entertainment, and communication functions into single Line Replaceable Units with DO-178C Level A software assurance. Business aviation fractional operators in the United States concentrate demand here as aircraft utilization rates multiply retrofit urgency.
- Control Unit:Discrete hardware modules managing specific cabin zones through ARINC 429 or Ethernet databus interfaces. Commercial airlines in legacy fleet configurations sustain replacement demand despite wiring weight penalties that integrated alternatives offset.
- Display Panel:Passenger-facing touchscreen interfaces with avionics-grade reliability specifications.
- Cabin Management Software:Embedded control logic and predictive maintenance algorithms subject to emerging EU AI Act compliance obligations.
Integrated systems handle the majority of throughput; cabin management software is expanding most quickly on share as predictive algorithms embed deeper into platform architectures.
Technology:
Retrofit economics compress installation downtime tolerance, fragmenting demand between legacy copper harnesses and emerging wireless architectures.
- Wired Communication:Traditional ARINC 429 and Ethernet-based harness configurations dominate installed base economics. Commercial aviation operators in the United States sustain this segment through regulatory conservatism and path-dependent fleet infrastructure.
- Wireless Communication:RF-based cabin backbones eliminating discrete wiring runs and reducing empty weight. Business aviation retrofit programs in Wichita-centered supply chains adopt these platforms fastest due to compressed aircraft downtime requirements.
- IoT Integration:Sensor networks enabling real-time cabin diagnostics and predictive maintenance.
- Cloud-based Solutions:Ground-linked analytics platforms for fleet-wide performance optimization.
Wired communication handles the majority of throughput; wireless communication is climbing the fastest as EASA special conditions on connected architectures mature.
End User:
Utilization intensity and certification flexibility create divergent technology adoption calendars across operator categories.
- Commercial Aviation:Scheduled airlines operating under strict FAA Part 25 and EASA CS-25 compliance with extended fleet replacement cycles. North American and European flag carriers concentrate demand for certified integrated platforms with decade-long service life guarantees.
- Business Aviation:Fractional ownership and charter operators multiplying aircraft utilization rates. United States-based fleet operators drive fastest adoption of wireless retrofit kits that compress downtime from months to weeks.
- Military Aviation:Government operators with hardened cybersecurity and mission-critical reliability specifications.
- Helicopter Operators:Rotary-wing platforms with severe weight constraints and vibration-hardening requirements.
Commercial aviation handles the majority of throughput; business aviation is gaining share fastest as fractional ownership models proliferate.
Application:
Passenger experience differentiation and crew workload reduction reshape functional prioritization across cabin zones.
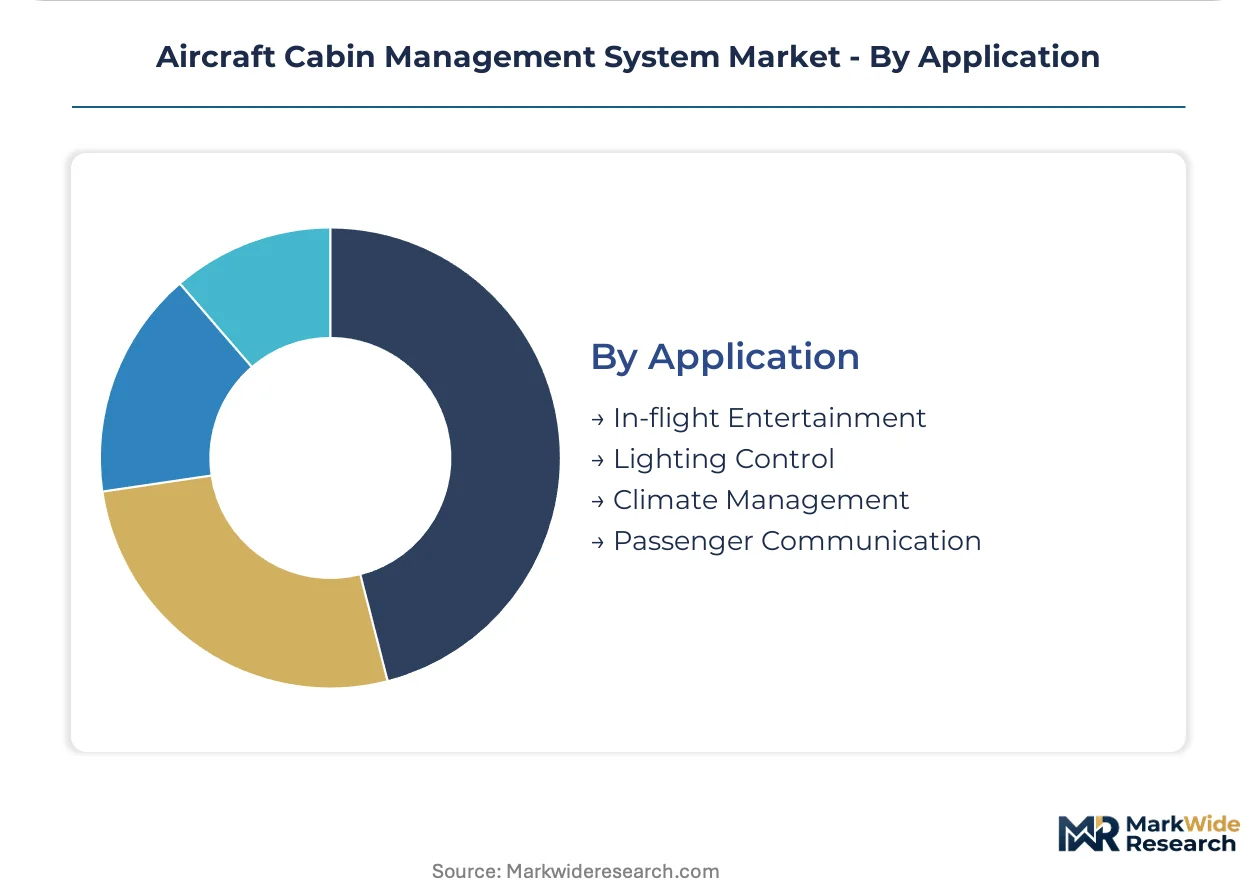
- In-flight Entertainment:Seat-back and wireless streaming systems with content delivery and digital rights management integration. Commercial aviation long-haul operators in the United States and Germany sustain premium investment here as passenger satisfaction metrics tighten.
- Lighting Control:LED-based ambient and task illumination with circadian rhythm programming. Business aviation retrofit programs adopt these systems fastest as cabin customization becomes a competitive differentiator.
- Climate Management:Zoned temperature and humidity control with air quality monitoring.
- Passenger Communication:Intercom, satellite connectivity, and ground link integration for voice and data services.
In-flight entertainment handles the majority of throughput; lighting control is advancing fastest on share as LED retrofits penetrate legacy fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 25 certification requirements anchor United States demand, while EASA CS-25 standards govern European procurement. Regulatory divergence on cybersecurity special conditions fragments certification timelines across jurisdictions.
United States
Business aviation fractional operators multiply aircraft utilization rates, accelerating wireless retrofit adoption. FAA Part 25 airworthiness standards tighten software assurance mandates for connected cabin architectures. Wichita, Kansas and the Pacific Northwest concentrate OEM and MRO capabilities, compressing logistics friction for North American retrofit programs.
Germany
Lufthansa Technik partnerships anchor European aftermarket demand for integrated cabin platforms. EASA CS-25 special conditions on wireless systems reshape manufacturer development roadmaps ahead of FAA harmonization. Hamburg and Munich host major MRO clusters where predictive maintenance algorithm deployment aligns with emerging EU AI Act compliance pathways.
France
Safran SA leverages deep supply chain integration with Airbus to sustain program visibility across European flag carriers. EASA cybersecurity mandates for connected architectures extend certification timelines but create compliance moats for prepared suppliers. Toulouse and Paris-Saclay concentrate avionics engineering talent and cabin system integration expertise.
United Kingdom
BAE Systems and Rolls-Royce adjacent suppliers extend capabilities into cabin management subsystems for military aviation applications. CAA alignment with EASA CS-25 standards maintains regulatory continuity post-Brexit, though divergence risk persists. Southwest England and Greater London retain aerospace engineering clusters focused on hardened cybersecurity specifications.
Japan
ANA and JAL fleet modernization programs sustain demand for lightweight integrated systems reducing empty weight. METI industrial policy supports domestic avionics capabilities through targeted R&D subsidies for next-generation cabin platforms. Nagoya and Tokyo-Osaka corridors concentrate precision manufacturing expertise for vibration-hardened control units.
Aircraft Cabin Management System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Tier-one diversified aerospace conglomerates dominate integrated system portfolios through Boeing and Airbus supply chain integration. Tier-two specialists capture wireless retrofit niches with compressed installation timelines. Dominant competitive moves include strategic partnerships with MRO providers and portfolio diversification into predictive maintenance software.
Within the diversified aerospace tier, RTX (Collins Aerospace) and Safran SA exemplify archetypes with deep OEM supply chain anchoring. Honeywell International Inc. occupies a position representing proprietary wireless architecture differentiation. Panasonic Avionics Corporation sits within the specialist tier exemplifying in-flight entertainment system concentration.
| Leading Market Players |
|---|
| Airbus |
| Astronics Corporation |
| RTX (Collins Aerospace) |
| Safran SA |
| Panasonic Avionics Corporation |
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Heads Up Technologies |
| Lufthansa Technik |
| Others |
Value Network & Pricing Analysis
Ninety-day DO-178C software certification timelines concentrate supplier bargaining power among Wichita-based OEMs with established FAA validation track records, compressing margins for second-tier control unit manufacturers while elevating integrated system premiums.
Pricing Analysis
United States-based business aviation operators pay 15-25% premiums over European commercial carriers for identical wireless retrofit hardware due to compressed downtime tolerance and direct procurement relationships. Three-tier pricing structure across DO-178C Level A certified integrated platforms, Level B control units, and uncertified aftermarket components dominates procurement negotiations. Cost compression in ARINC 429 legacy replacements is intensifying because copper wiring weight penalties erode fuel economics faster than wireless alternatives can offset installation premiums. Fractional ownership fleet operators demonstrate lowest price sensitivity due to utilization-rate multipliers, while scheduled commercial airlines in legacy fleet configurations drive hardest bargain on per-unit hardware.
Supply Chain Analysis
Strait of Malacca component transit underwrites just-in-time delivery schedules for ARINC 429 chipset foundries concentrated in Taiwan, Japan, and South Korea. Fiber optic harness assemblies draw from German precision manufacturing clusters and Chinese cable extrusion capacity. Single-source vulnerability in DO-178C software engineering talent pools—split between Wichita avionics protocols and Seattle IoT architectures—threatens program timelines for next-generation Ethernet migrations. Distribution runs through Boeing and Airbus tier-one supplier networks with direct-to-operator wireless retrofit kits fragmenting traditional MRO channel intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA's cybersecurity special conditions on wireless cabin architectures represent a regulatory inflection that will bifurcate supplier viability between compliance-ready incumbents and stranded legacy portfolios.
For Market Incumbents: Secure DO-178C Level A certification pre-positioning ahead of FAA-EASA harmonization timelines to lock out emerging entrants lacking validation infrastructure. Consolidate Wichita-Pacific Northwest engineering clusters through targeted acquisition of IoT-architecture specialists threatened by talent scarcity. EASA special condition compliance moats serve as the primary defensive lever against wireless retrofit specialists eroding integrated system margins. For New Entrants and Emerging Players: Anchor in business aviation fractional ownership segments where compressed downtime tolerance overrides brand loyalty and certification heritage. Target direct-to-operator wireless retrofit kits bypassing Lufthansa Technik and legacy MRO intermediaries as the most penetrable channel structure. Lead with predictive maintenance algorithm offerings that front-run EU AI Act compliance obligations before incumbent software roadmaps mature. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FAA-EASA divergence on cybersecurity certification creates sustained compliance moats for prepared suppliers while fragmenting market access for undercapitalized entrants. Acquisition target archetype: mid-cap wireless cabin specialists with EASA special condition validation already secured and direct operator relationships in Wichita-centered supply chains. Watch whether FAA accelerates harmonization with EASA timelines as the critical inflection signal for competitive positioning resets.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Special Condition Pre-Certification | Creates compliance moats ahead of FAA harmonization for wireless cabin architectures. |
| DO-178C Software Engineering Acquisition | Addresses talent scarcity bifurcating legacy avionics and IoT protocol expertise pools. |
| Direct-to-Operator Wireless Retrofit Channel | Bypasses traditional MRO intermediation concentrated in Lufthansa Technik partnerships. |
| Predictive Maintenance Algorithm Deployment | Front-runs EU AI Act compliance obligations for cabin-embedded diagnostics software. |
| Wichita-Pacific Northwest Cluster Consolidation | Compresses logistics friction for North American business aviation retrofit programs. |
Research Methodology
The analysis maps integrated cabin systems, discrete control units, display panels, and embedded software architectures, each validated through fleet operators, MRO procurement directors, avionics certification engineers, and FAA/EASA regulatory affairs specialists. Primary interview intelligence triangulates against SEC 10-K aerospace segment disclosures, FAA Part 25 special condition publications, EASA CS-25 certification databases, and Wichita supplier cluster trade flow records. Bottom-up installation forecasts and top-down OEM program visibility estimates converge through iterative stakeholder cross-checking.
Consistency checks against Boeing and Airbus delivery schedules, fractional ownership fleet utilization databases, and MRO channel procurement patterns validated projection outputs across the analysis window. Segmentation dimensions modeled include product architecture tier, communication protocol generation, end-use mission profile, and regional regulatory cluster. CAGRs derive from compound growth trajectory fitting against historical retrofit cycle data and fleet replacement elasticity parameters. Forecast inputs incorporate EASA special condition implementation timelines and EU AI Act compliance pathway uncertainty.
Decision-makers should treat outputs as directional under stable FAA-EASA harmonization assumptions; material divergence in cybersecurity certification timelines would warrant model refresh. Practitioners should keep alternative scenarios live as wireless architecture recertification bottlenecks and copper wiring weight penalty trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market