
 Aviation Infrastructure Market | 2026-2036
Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Infrastructure Market Analysis
Defense and cargo logistics is pivoting toward dual-use airport capabilities, reshaping procurement priorities for military-civilian infrastructure. AECOM leverages its integrated design-build footprint across federal aviation contracts. Turner Construction Company sustains dominance in large-scale terminal megaprojects through repeatable delivery frameworks. Hensel Phelps anchors its position in Western US markets with specialized airfield pavement and runway systems expertise.
Aviation infrastructure encompasses the physical and technological systems enabling aircraft movement, passenger processing, and cargo handling, including concrete pavement rated for specific load classifications, precision approach lighting arrays, and distributed antenna systems for ground-to-air communication. The primary purpose is maintaining safe, efficient, and scalable air transport operations under variable demand and weather conditions. Air Traffic Control Systems command the largest installed base but face replacement pressure from satellite-based automated alternatives. Terminal Equipment captures expanding capital allocation as biometric processing and automated baggage handling reshape passenger throughput economics. Ground Support Equipment remains fragmented across diesel, electric, and hybrid traction platforms with electrification mandates shifting procurement specifications.
The FAA enforces airport design standards under Part 139 certification, while ICAO Annex 14 establishes international runway safety dimensions and obstacle limitation surfaces that govern expansion feasibility. The EU's F-Gas Regulation and emerging national building codes for airport carbon neutrality are redirecting specification sheets toward lower-emission materials and energy recovery systems. Stakeholders must weigh upgrade sequencing against regulatory compliance deadlines while monitoring how SESAR and NextGen interoperability requirements reshape technology vendor selection criteria.
Market Dynamics
NextGen satellite-based navigation and SESAR interoperability mandates are compressing refresh cycles for ground-based air traffic systems while terminal operators race to deploy biometric processing at scale.
Growth Catalysts
- NextGen Implementation:The FAA's satellite-based surveillance mandate is forcing replacement of radar-dependent systems across US terminal radar approach control facilities.
- Passenger Biometrics:Automated facial recognition boarding gates are cutting processing times at Dubai International and Singapore Changi, driving capital allocation toward integrated identity management platforms.
- Greenfield Airport Development:Saudi Arabia's Red Sea International and India's Navi Mumbai projects are generating concentrated demand for turnkey airfield pavement and lighting systems.
Market Restraints
- Specialized Asphalt Input Costs:Polymer-modified binder formulations for heavy-load runways face price volatility tied to styrene-butadiene supply from petrochemical hubs.
- Precision Approach Lighting Concentration:Three European specialist manufacturers control calibration equipment for Category III systems, creating single-source vulnerability.
- Interoperability Friction:Divergent FAA and EUROCONTROL certification timelines for new surveillance technologies delay dual-market product launches by 18-24 months.
Strategic Opportunities
- India Regional Connectivity:UDAN scheme subsidies for underserved tier-2 cities are unlocking greenfield airstrip development in Uttar Pradesh and Bihar.
- Hydrogen Ground Support:Fuel cell-powered pushback tractors and belt loaders are opening retrofit markets as EU F-Gas Regulation phases down high-GWP refrigerants in conventional equipment.
- Digital Twin Integration:Converged BIM and IoT sensor networks are enabling predictive maintenance contracts for runway pavement lifecycle management.
Industry Challenges
- Air Traffic Controller Pipeline:FAA Academy training capacity constraints and retirements are stretching staffing ratios at high-density facilities.
- Legacy System Integration:New automated surface surveillance must interface with 1980s-era flight data processors without disrupting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Infrastructure Market |
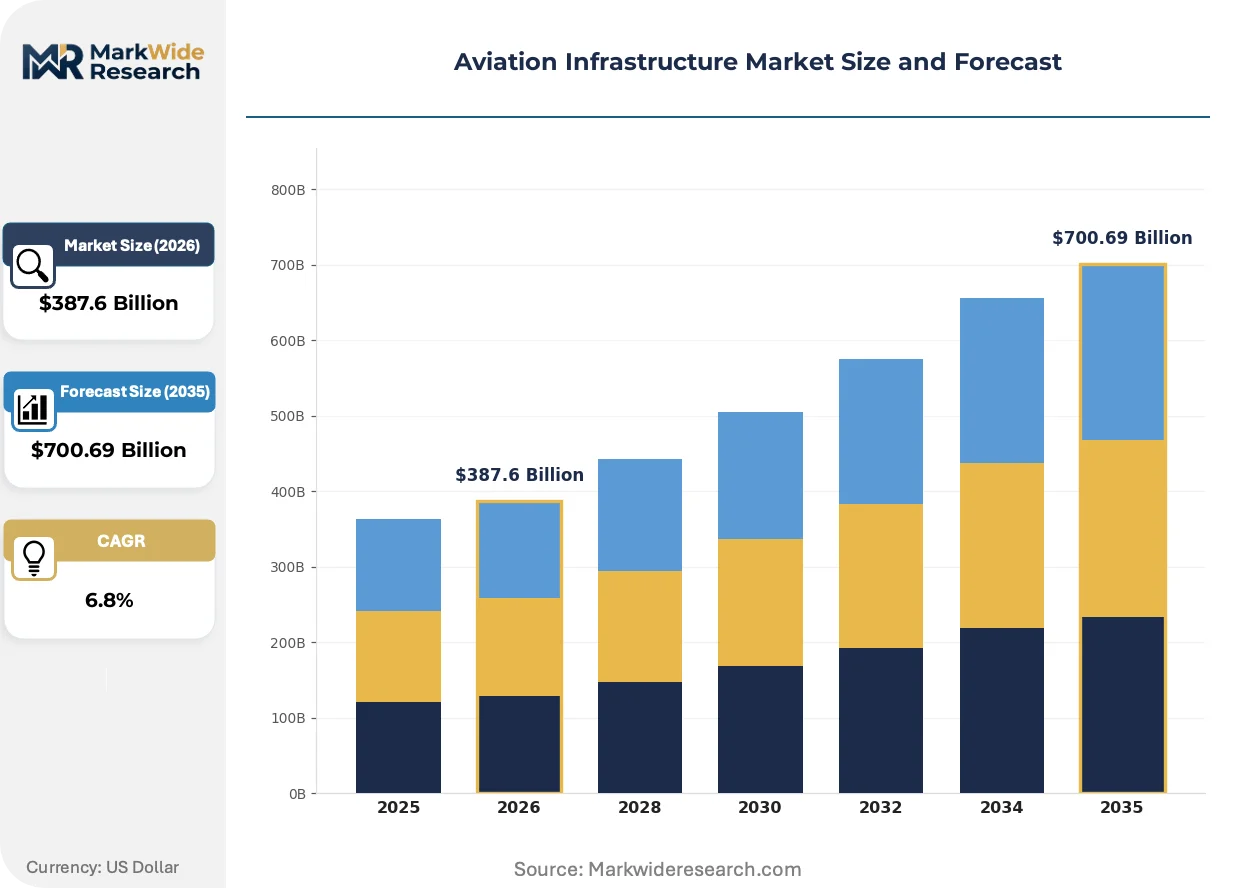
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Traffic Control Systems, Runway Lighting, Terminal Equipment, Ground Support Equipment Technology: Automated Systems, Communication Systems, Surveillance Technologies, Navigation Aids End User: Airports, Government Agencies, Airlines, Maintenance Providers Installation: New Development, Upgrade Projects, Retrofit Installations, Emergency Repairs |
| Companies Covered | Austin Industries, TAV Construction, AECOM, McCarthy Building Companies Inc., The Walsh Group, Hensel Phelps, Skanska, J.E. Dunn Construction Company, Turner Construction Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Infrastructure Market Emerging Trajectories
Aviation infrastructure is pivoting from capacity expansion toward throughput optimization, with software-defined systems and electrified ground fleets displacing mechanical and hydrocarbon-dependent predecessors.
Artificial intelligence-based predictive maintenance for runway lighting and navigation aids is rewriting asset management economics. Airport operators in the Netherlands and Japan are deploying machine learning models to forecast LED array failures before visible degradation. This capability is compressing maintenance windows and reducing unplanned outages during peak scheduling.
The EU's F-Gas Regulation phase-down schedule is accelerating refrigerant transitions in ground support equipment. Cold-chain cargo handlers at Frankfurt and Amsterdam Schiphol are retrofitting electric refrigeration units to comply with 2027 GWP limits. Manufacturers are responding with modular electric platforms that separate traction and thermal systems for independent upgrade cycles.
Airlines and cargo integrators are consolidating procurement through outcome-based availability contracts for ground handling equipment. Lease structures now guarantee uptime percentages rather than asset ownership, transferring obsolescence risk to OEMs and lessors. This shift is most pronounced at Middle Eastern hub airports where rapid fleet turnover demands flexible capacity scaling.
Aviation Infrastructure Market Segmentation
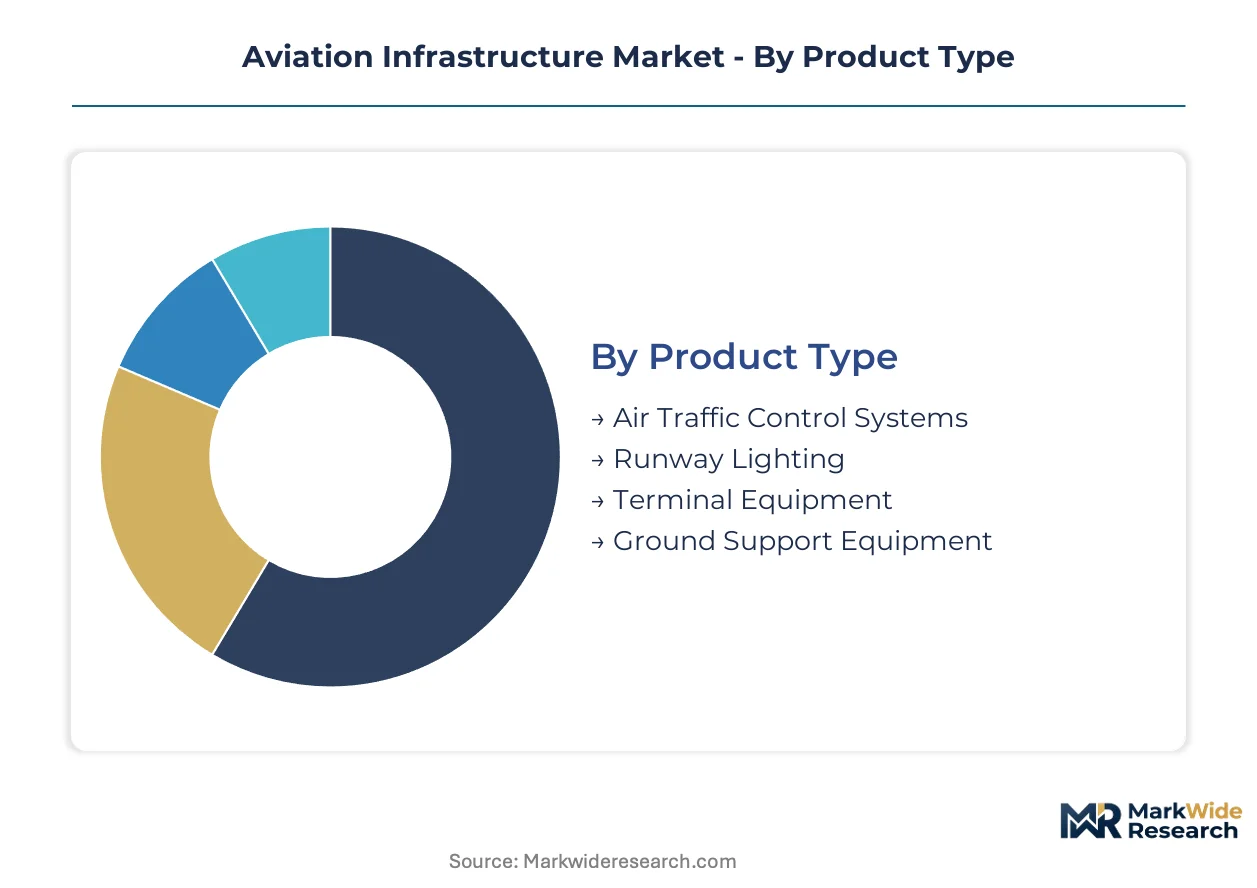
Segmentation reveals how capital flows diverge between regulatory-mandated replacements and passenger-experience upgrades. Procurement patterns split sharply between federal aviation contracts and airport operator discretionary spending.
Product Type:
Supply concentration varies dramatically across product categories, with air traffic systems dominated by defense-integrated primes while terminal equipment fragments among building automation specialists.
- Air Traffic Control Systems:Radar, ADS-B, and satellite-based surveillance platforms govern safe aircraft separation across controlled airspace. FAA NextGen mandates are forcing replacement cycles at US terminal radar approach control facilities while EUROCONTROL interoperability requirements delay dual-market certifications. These systems absorb the bulk of installed capacity; terminal equipment is expanding most quickly.
- Runway Lighting:Precision approach lighting arrays and LED taxiway edge systems enable Category III operations in low-visibility conditions. Three European calibration equipment manufacturers control Category III certification, creating procurement bottlenecks for Middle Eastern and Asian hub expansions.
- Terminal Equipment:Biometric boarding gates, automated baggage handling, and passenger processing systems reshape throughput economics at Dubai International and Singapore Changi.
- Ground Support Equipment:Diesel, electric, and hybrid pushback tractors, belt loaders, and cargo loaders face electrification mandates under EU F-Gas Regulation phase-down schedules.
Air Traffic Control Systems absorb the bulk of installed capacity; Terminal Equipment is expanding most quickly.
Technology:
Technology selection hinges on legacy system integration requirements, with 1980s-era flight data processors constraining deployment of newer automated platforms.
- Automated Systems:AI-based predictive maintenance and machine learning failure forecasting compress maintenance windows for runway lighting arrays. Netherlands and Japan airports deploy these models to preempt LED degradation before visible failure.
- Communication Systems:Distributed antenna systems and ground-to-air voice/data links maintain controller-pilot connectivity across terminal and en-route airspace. FAA and EUROCONTROL certification timeline divergence delays product launches by 18-24 months.
- Surveillance Technologies:Surface movement radar and multilateration systems track aircraft and vehicles on airport movement areas.
- Navigation Aids:Instrument landing systems and GPS augmentation equipment guide precision approaches.
Automated Systems command premium pricing for predictive capabilities; Surveillance Technologies face replacement pressure from satellite-based alternatives.
End User:
End-user procurement authority determines specification authority, with government agencies controlling airspace infrastructure and airports directing terminal investments.
- Airports:Terminal operators and airfield maintenance departments allocate capital between passenger experience upgrades and pavement lifecycle management. Outcome-based availability contracts now guarantee ground support equipment uptime rather than asset ownership.
- Government Agencies:FAA, EUROCONTROL, and national civil aviation authorities mandate surveillance and navigation system standards. FAA Part 139 certification requirements and ICAO Annex 14 standards govern design specifications.
- Airlines:Network carriers and cargo integrators influence ground handling equipment procurement through hub operating agreements.
- Maintenance Providers:Third-party repair stations and OEM service networks execute retrofit installations and emergency repairs.
Government Agencies control regulatory-mandated system replacements; Airports direct discretionary terminal modernization spending.
Installation:
Installation type shapes project risk allocation, with new development offering clean-sheet design and retrofits demanding operational continuity.
- New Development:Greenfield airports in Saudi Arabia and India enable turnkey airfield pavement and lighting system deployment without operational constraints. Red Sea International and Navi Mumbai projects concentrate demand for integrated design-build delivery.
- Upgrade Projects:NextGen and SESAR interoperability mandates compress refresh cycles for ground-based radar systems at existing facilities. FAA satellite-based surveillance requirements force coordinated replacement across terminal radar approach control networks.
- Retrofit Installations:Electric refrigeration retrofits on cold-chain cargo handlers at Frankfurt and Amsterdam Schiphol respond to EU F-Gas Regulation GWP limits.
- Emergency Repairs:Unplanned pavement failures and lighting outages demand rapid-response procurement outside capital planning cycles.
Upgrade Projects dominate current spending volumes; New Development offers the steepest expansion trajectory in India and Middle East markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones and airport-centric special economic zones are concentrating capital deployment in aviation infrastructure. These designated areas offer tax abatements and streamlined customs procedures that accelerate project timelines. Government-backed development corporations in the Middle East and Asia are leveraging these mechanisms to anchor hub expansion strategies.
United States
FAA NextGen mandates are forcing replacement of radar-dependent systems at terminal radar approach control facilities across the country. The FAA enforces Part 139 certification requirements that govern airfield design standards and operational safety. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor concentrated demand for runway pavement and precision approach lighting upgrades.
China
Beijing Daxing and Chengdu Tianfu greenfield developments are generating turnkey demand for integrated airfield systems and smart terminal technologies. MIIT and CAAC coordinate national standards for airport construction under GB specifications. The Yangtze River Delta cluster around Shanghai Pudong is deploying biometric passenger processing at scale.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International are racing to deploy automated baggage handling and facial recognition boarding gates. The country's civil aviation regulator mandates interoperability with SESAR and NextGen standards for future airspace integration. Dubai South free zone anchors concentrated ground support equipment procurement for Emirates' hub operations.
Saudi Arabia
Red Sea International Airport and NEOM Bay are unlocking greenfield demand for airfield pavement and Category III lighting systems. The General Authority of Civil Aviation coordinates with GACA standards and ICAO Annex 14 compliance frameworks. The King Abdullah Economic City zone is attracting design-build contractors for integrated terminal and runway delivery.
India
Navi Mumbai International Airport and Jewar Airport are driving concentrated demand for runway construction and terminal automation. The UDAN regional connectivity scheme subsidizes tier-2 city airstrip development under Ministry of Civil Aviation oversight. Uttar Pradesh and Bihar are emerging as greenfield development corridors with state-level infrastructure corporations accelerating land acquisition.
Aviation Infrastructure Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with design-build integrators commanding federal aviation contracts while regional contractors capture terminal modernization work. The market exhibits tiered concentration: defense-integrated primes dominate air traffic systems, construction majors control airfield pavement, and building automation specialists fragment terminal equipment. Two archetypes define competitive positioning: integrated design-build firms with federal contract vehicles, and specialized airfield contractors with regional pavement expertise. M&A activity targets capability gaps in smart terminal technologies, while strategic partnerships with technology vendors address NextGen interoperability requirements.
Among North American construction majors, AECOM, Turner Construction Company, and Hensel Phelps occupy positions across the federal aviation and commercial airport spectrum. AECOM exemplifies the integrated design-build archetype through its footprint in federal contract vehicles. Turner Construction Company represents scale-driven terminal delivery capability. Hensel Phelps anchors specialized airfield pavement expertise in Western US markets. These firms sit within a competitive structure where repeatable delivery frameworks and existing agency relationships determine procurement access.
| Leading Market Players |
|---|
| Austin Industries |
| TAV Construction |
| AECOM |
| McCarthy Building Companies Inc. |
| The Walsh Group |
| Hensel Phelps |
| Skanska |
| J.E. Dunn Construction Company |
| Turner Construction Company |
| Others |
Supply Flow & Price Mechanics
FAA NextGen satellite-based surveillance mandates are compressing procurement timelines for terminal radar approach control facilities, forcing suppliers to absorb expedited manufacturing costs or sacrifice margin to retain federal contract vehicles. This demand-side pressure reshapes how air traffic system vendors structure pricing across defense-integrated primes and specialized component manufacturers.
Pricing Analysis
Short-lead-time premiums dominate air traffic control system procurement, with Category III precision approach lighting arrays commanding substantial markups against standard configurations due to European calibration equipment bottlenecks. Three-tier pricing structure across certified, interoperable, and legacy-compatible tiers reflects FAA and EUROCONTROL dual-certification costs. Pricing pressure stems from styrene-butadiene input volatility in polymer-modified runway binders. Government agencies exhibit lowest price sensitivity given regulatory compliance deadlines, while regional airport operators in India's UDAN scheme demonstrate highest sensitivity to capital expenditure timing.
Supply Chain Analysis
Single-source vulnerability sits with German, French, and Italian specialist manufacturers controlling Category III calibration equipment for precision approach lighting systems. Airfield pavement construction draws from Saudi Arabia, India, and the United Arab Emirates for greenfield aggregate sourcing, with polymer-modified bitumen resting on petrochemical feedstock from South Korean and Singaporean hubs. Tariff exposure runs through EU F-Gas Regulation compliance timelines affecting ground support equipment refrigerant transitions. Distribution runs through design-build integrators with federal contract vehicles and regional airfield pavement specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation infrastructure is consolidating around design-build integrators capable of spanning federal aviation contracts and terminal megaprojects, with NextGen interoperability mandates forcing weaker regional players toward subcontractor roles or exit.
For Market Incumbents: Extend predictive maintenance service contracts into multi-year runway pavement lifecycle agreements at Netherlands and Japanese airports where machine learning failure forecasting has proven operational value. Deepen backward integration into LED array manufacturing to offset European calibration equipment bottlenecks threatening margin compression on Category III lighting projects. Lock in federal contract vehicle renewals before EUROCONTROL-FAA certification timeline divergence widens competitive moats for dual-certified suppliers. For New Entrants and Emerging Players: Hydrogen fuel cell ground support equipment retrofit platforms offer the most penetrable wedge for specialized entrants, targeting Frankfurt and Amsterdam Schiphol cold-chain cargo handlers facing EU F-Gas Regulation GWP limits. India's UDAN-subsidized tier-2 city airstrip development presents uncongested territory for regional design-build partnerships with state infrastructure corporations. Lead with outcome-based availability contracting rather than asset ownership models to mirror Middle Eastern hub procurement preferences. For Investors and Strategic Acquirers: The window for entry favors mid-cap airfield pavement specialists with Western US regional density and repeatable federal project delivery frameworks. Long-term viability hinges on capturing smart terminal automation capabilities through technology vendor partnerships rather than organic R&D. Watch for FAA Academy training capacity constraints triggering outsourced air traffic control staffing contracts as inflection indicator for services-heavy business model shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Terminal Integration | Dubai International and Singapore Changi deployments validate passenger throughput economics for identity management platforms. |
| Digital Twin Infrastructure | Converged BIM and IoT sensor networks enable predictive maintenance contracts at Netherlands airports. |
| Hydrogen Ground Fleet Retrofit | Fuel cell pushback tractors address EU F-Gas Regulation phase-down schedules at Frankfurt cargo handlers. |
| Dual-Certification R&D Investment | Parallel FAA and EUROCONTROL approval tracks compress 18-24 month product launch delays for surveillance technologies. |
| Regional Connectivity Partnership | UDAN scheme subsidies unlock greenfield airstrip development in Uttar Pradesh and Bihar for design-build consortia. |
Methodological Framework
Multi-period observation of FAA NextGen implementation milestones, EUROCONTROL SESAR deployment schedules, and greenfield airport project announcements anchored the trend analysis, supplemented by interviews with airport capital planning directors, federal aviation contract officers, airfield pavement engineers, and ground support equipment procurement managers at Middle Eastern hub operators. Secondary validation incorporated FAA Part 139 certification records, ICAO Annex 14 compliance filings, EU F-Gas Regulation implementation guidance, and customs data on polymer-modified bitumen imports. Bottom-up project pipeline aggregation and top-down regulatory mandate sizing were triangulated against disclosed contract awards.
Segment-weighting approaches distributed value across air traffic control systems, terminal equipment, runway lighting, and ground support equipment according to disclosed procurement volumes and replacement cycle timing. Technology trajectories were modeled across automated systems, communication systems, surveillance technologies, and navigation aids throughout the projection horizon. CAGRs were derived from regulatory deadline pacing and passenger throughput expansion assumptions, with specific inputs including FAA Academy training capacity constraints and UDAN scheme subsidy allocation patterns.
Several conditions sit outside the modeled scope, including unannounced geopolitical disruptions to Middle Eastern greenfield financing, abrupt refrigerant technology shifts beyond EU F-Gas Regulation timelines, and unforeseen air traffic controller strike actions at high-density facilities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Heliports Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Aerobridge Market