
 Asia-Pacific Aviation Infrastructure Market | 2026-2036
Asia-Pacific Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aviation Infrastructure Market Outlook
Low-cost carrier terminal expansion is rebalancing capital deployment across the Asia-Pacific aviation infrastructure landscape. GMR Group leverages its integrated airport development model across Delhi and Hyderabad to sustain long-term concession revenue. Beijing Jinghang Airport Engineering dominates domestic Chinese projects through specialized runway and apron construction capabilities. AECOM Limited competes on cross-border design-build contracts by anchoring multidisciplinary teams in Singapore and Australia.
Asia-Pacific aviation infrastructure encompasses the physical assets, integrated systems, and operational services that enable commercial and cargo air transport across the region's airports, including concrete runway pavements designed to PCN/ACN load-bearing specifications and terminal structures processing passenger flows exceeding 3,000 travelers per hour. Airport authorities now prioritize baggage handling system upgrades over greenfield terminal construction as throughput bottlenecks intensify in tier-one hubs. Security screening solutions represent the fastest-growing technology segment as biometric integration and CT scanner deployment accelerate. Construction services still occupy the largest service-type margin pool, though maintenance contracts are extending in duration as asset-life optimization gains priority.
China's MIIT smart airport directives and India's CEA electrical safety mandates are reshaping procurement standards for terminal automation and airfield lighting systems across their respective jurisdictions. Japan's METI energy-efficiency codes for transport infrastructure are forcing retrofit specifications in Osaka and Narita facilities. Stakeholders must monitor how Australia's TGA-equivalent airport certification body adapts climate resilience standards into design codes before committing to long-dated concession bids.
Market Dynamics
China's MIIT smart airport directives are compressing procurement cycles for terminal automation systems while India's UDAN scheme accelerates greenfield airport construction timelines across tier-two and tier-three cities.
Growth Catalysts
- Biometric Security Mandates:China's MIIT standards for facial recognition boarding gates are forcing terminal retrofit investments across Beijing, Shanghai, and Guangzhou hubs. Airport authorities must comply with 2025 digital identity verification protocols.
- Regional Connectivity Schemes:India's UDAN policy subsidizes airline operations to underserved airports, generating demand for new runway pavements and apron expansions in states like Uttar Pradesh and Bihar.
- Low-Cost Carrier Fleet Expansion:Southeast Asian budget airlines are placing narrow-body aircraft orders that require expanded parking stands and quick-turnaround gates at Jakarta, Manila, and Bangkok facilities.
Market Restraints
- Steel and Cement Input Volatility:Runway concrete specifications requiring high-grade Portland cement face price swings tied to China's construction slowdown and India's mining license restrictions.
- Specialized Contractor Concentration:Apron and taxiway construction capabilities concentrate among state-owned Chinese engineering groups and Japanese consortiums, limiting competitive bidding in Vietnam and Philippines.
- Land Acquisition Friction:India's Land Acquisition Act compliance timelines stretch greenfield airport development schedules, particularly in Maharashtra and Karnataka where agricultural conversion disputes persist.
Strategic Opportunities
- Vietnam Central Highlands:Underpenetrated airport density in Dak Lak and Gia Lai provinces creates first-mover advantages for concessionaires willing to accept lower initial passenger throughput guarantees.
- Digital Twin Convergence:Integration of building information modeling with real-time sensor networks enables predictive maintenance contracts for baggage handling and HVAC systems in Singapore and Sydney hubs.
- Japan METI Energy Codes:Retrofit subsidies for LED airfield lighting and solar-integrated terminal roofs create service revenue pools for engineering firms active in Osaka and Fukuoka.
Industry Challenges
- Airfield Lighting Certification:China's GB standards for LED runway edge lights require extensive electromagnetic interference testing, extending product approval timelines for foreign suppliers.
- Baggage System Integration:Legacy tilt-tray sorters at legacy terminals in Jakarta and Manila resist seamless interface with new independent carrier systems, forcing expensive middleware development.
- Skilled Technician Scarcity:Shortages of certified electrical engineers familiar with CEA grounding specifications delay commissioning schedules for Indian airport expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aviation Infrastructure Market |
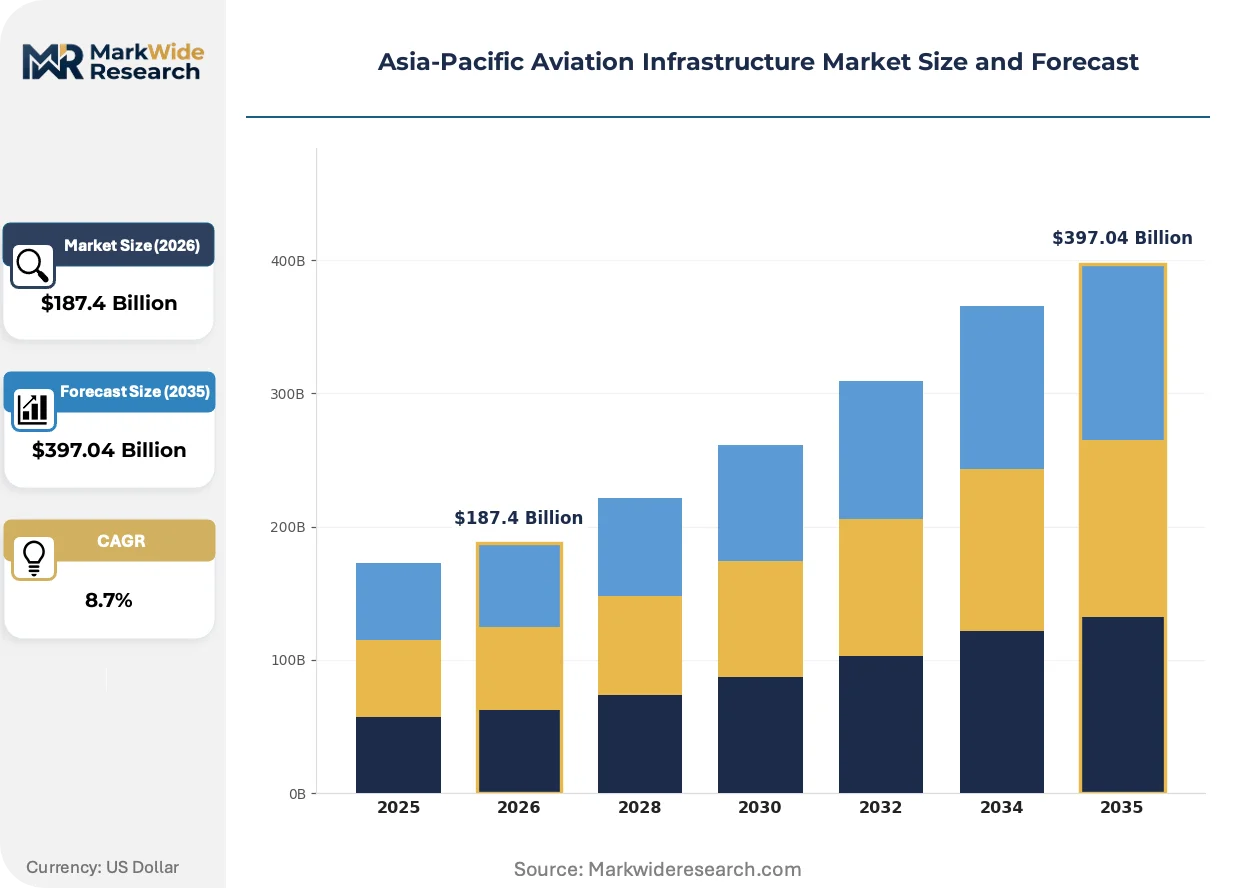
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Airports, Terminal Buildings, Runways, Hangars Technology: Air Traffic Control Systems, Baggage Handling Systems, Security Screening Solutions, Ground Support Equipment End User: Airlines, Government Agencies, Ground Handlers, Airport Authorities Service Type: Construction, Maintenance, Consultancy, Operations |
| Companies Covered | JGC Holdings Corporation, Turner Construction Company, GMR Group, Mott MacDonald Group Limited, Beijing Jinghang Airport Engineering Co. Ltd., AECOM Limited, JLL Inc., Ove Arup & Partners International Limited, GVK Industries Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aviation Infrastructure Market Strategic Shifts
Terminal automation and predictive asset management are displacing reactive maintenance contracts across Asia-Pacific aviation infrastructure procurement. Digital twin adoption accelerates as airport authorities seek operational visibility without physical expansion.
Computerized tomography (CT) baggage screening is absorbing capital allocations previously directed toward conventional X-ray machines. Security integrators at Singapore Changi and Hong Kong International are deploying CT scanners that eliminate liquid removal requirements, compressing passenger processing times by fifteen percent. This technology is absorbing mid-tier security upgrade budgets that would have funded multiple lane expansions.
Japan's METI energy-efficiency codes for transport infrastructure are mandating LED replacements for halogen airfield lighting and solar panel integration on terminal roofs. Osaka Kansai and Narita facilities face retrofit deadlines that compress contractor selection timelines. Airfield electrical specialists are responding by pre-certifying products to JIS standards to accelerate approval.
Airlines are consolidating ground handling contracts under multi-airport frameworks, displacing fragmented station-by-station procurement. Qantas and Singapore Airlines now negotiate centralized contracts covering Australian and Southeast Asian hubs, forcing ground service providers to restructure pricing and resource allocation. This concentration is most visible in Australia, where three providers now control eighty percent of major airport handling capacity.
Asia-Pacific Aviation Infrastructure Market Segmentation
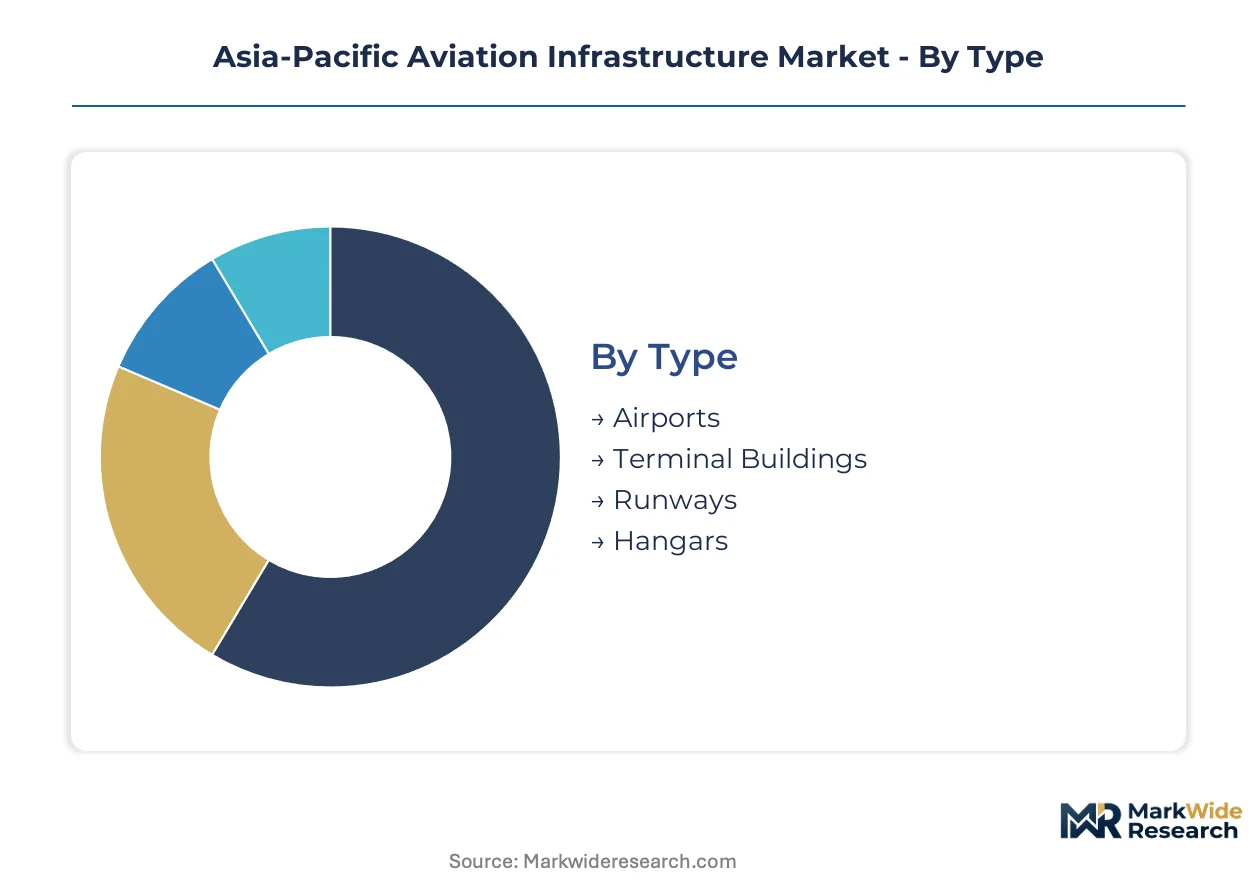
Segmentation reveals how capital cycles differ across physical assets, operational technologies, and service delivery models. Infrastructure owners deploy distinct procurement strategies for greenfield construction versus retrofit automation, creating divergent margin pools within the same regional market.
Type:
Upgrade and replacement cycles vary sharply by asset longevity, with airfield pavements demanding decades-long investment horizons while terminal interiors refresh on compressed schedules.
- Airports:Integrated airfield and terminal complexes requiring coordinated master planning across multi-phase expansions. India's UDAN scheme is driving greenfield airport development in Uttar Pradesh and Bihar where passenger throughput guarantees remain untested.
- Terminal Buildings:Passenger processing structures designed for hourly flow rates exceeding 3,000 travelers. Beijing, Shanghai, and Guangzhou hubs are prioritizing biometric boarding gate retrofits under MIIT smart airport directives over new construction.
- Runways:Concrete pavements engineered to PCN/ACN load-bearing specifications for heavy aircraft operations. Vietnam and Philippines face contractor scarcity for specialized apron and taxiway work.
- Hangars:Maintenance and storage facilities for fleet operations. Narrow-body fleet expansion by Southeast Asian low-cost carriers is expanding parking stand requirements at Jakarta, Manila, and Bangkok.
Airports sit at the top of the volume ranking, with terminal buildings climbing the fastest as biometric mandates force accelerated retrofit timelines.
Technology:
Technology procurement splits between safety-critical air traffic systems and passenger-facing automation, with divergent certification burdens shaping vendor selection.
- Air Traffic Control Systems:Radar, communication, and surveillance infrastructure managing en-route and terminal airspace. China's MIIT standards for electromagnetic compatibility extend product approval timelines for foreign suppliers seeking GB certification.
- Baggage Handling Systems:Automated sortation and conveyor networks processing passenger luggage. Legacy tilt-tray infrastructure at Jakarta and Manila terminals resists interface with new independent carrier systems, forcing middleware investments.
- Security Screening Solutions:CT scanners and biometric verification equipment for passenger and cargo inspection. Singapore Changi and Hong Kong International are eliminating liquid removal requirements through CT deployment, compressing processing times.
- Ground Support Equipment:Aircraft tugs, baggage loaders, and fueling vehicles for apron operations. Qantas and Singapore Airlines are consolidating multi-airport ground handling contracts, forcing equipment standardization across Australian and Southeast Asian hubs.
Security screening solutions are expanding most quickly, with baggage handling systems commanding the largest installed base replacement value.
End User:
End-user procurement authority determines contract scale, with government agencies controlling master planning while airlines influence terminal automation specifications.
- Airlines:Commercial carriers specifying terminal gate configurations and ground handling requirements. Budget airlines across Southeast Asia are driving quick-turnaround gate expansion at secondary hubs.
- Government Agencies:National aviation authorities and ministries overseeing airfield safety and regulatory compliance. China's MIIT and India's CEA are reshaping procurement standards for terminal automation and electrical systems.
- Ground Handlers:Service providers managing aircraft turnaround and cargo operations. Market concentration in Australia has left three providers controlling eighty percent of major airport handling capacity.
- Airport Authorities:Operating entities managing concession revenue and capital deployment. GMR Group leverages integrated development models across Delhi and Hyderabad to sustain long-term concession structures.
Government agencies dominate capital allocation, with airport authorities gaining procurement influence as public-private partnership structures mature.
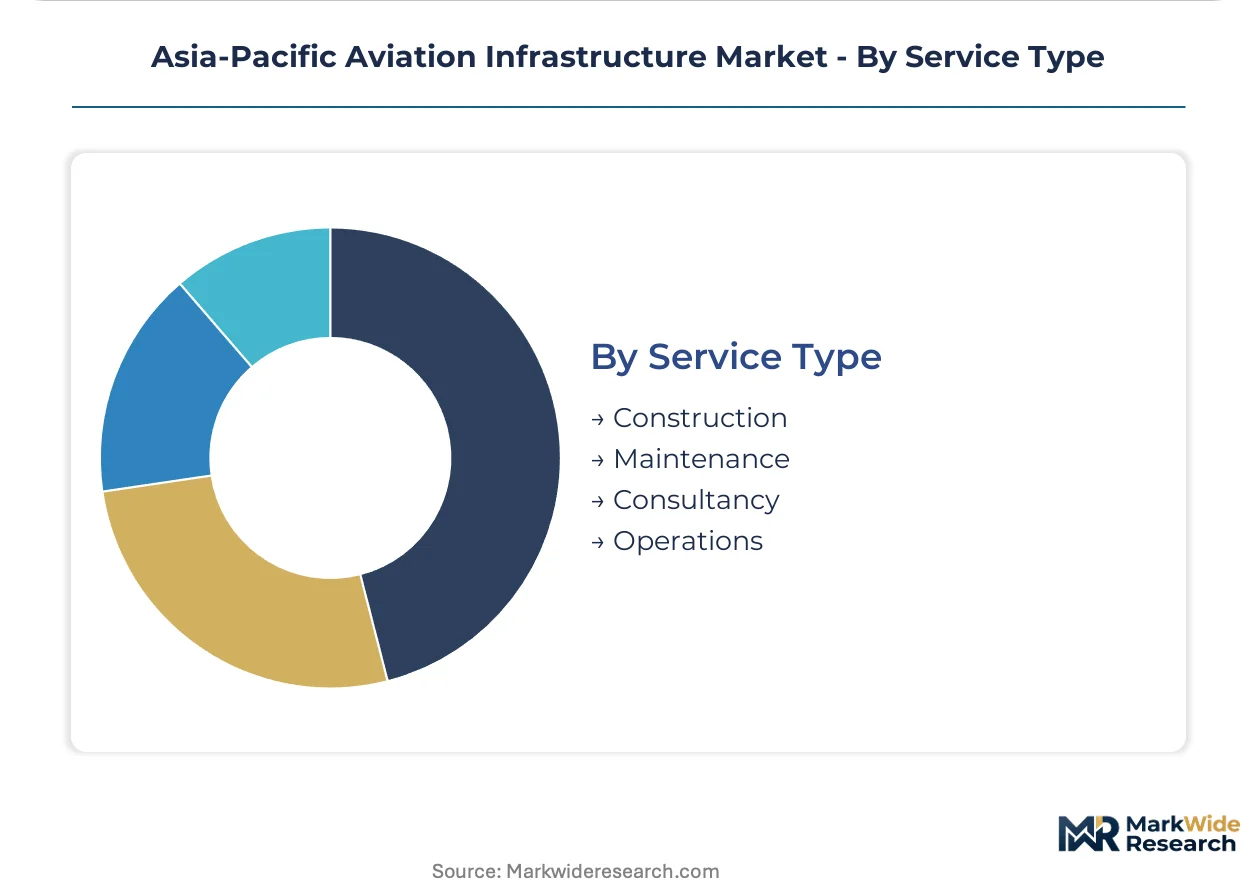
Service Type:
Service contracts are lengthening in duration as asset-life optimization displaces reactive maintenance, shifting margin capture toward predictive capabilities.
- Construction:Design-build and engineering-procurement-construction delivery of airfield and terminal assets. Beijing Jinghang Airport Engineering maintains domestic Chinese dominance through specialized runway and apron capabilities.
- Maintenance:Scheduled and corrective upkeep of pavements, structures, and mechanical systems. Predictive maintenance contracts for baggage handling and HVAC are emerging in Singapore and Sydney through digital twin integration.
- Consultancy:Master planning, feasibility studies, and regulatory compliance advisory. AECOM Limited anchors multidisciplinary teams in Singapore and Australia for cross-border design-build contracts.
- Operations:Day-to-day management of terminal functions and airfield services. Japan's METI energy-efficiency codes are compressing contractor selection timelines for LED airfield lighting retrofits at Osaka Kansai and Narita.
Construction commands the largest absolute contract value, with maintenance gaining share fastest as concession operators prioritize lifecycle cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing-Tianjin-Hebei anchors Asia-Pacific aviation infrastructure development through MIIT smart airport directives and digital twin deployment across major hubs.
China
Beijing, Shanghai, and Guangzhou hubs drive terminal automation retrofits under MIIT biometric boarding mandates. China's GB standards for LED runway edge lights compress procurement timelines for domestic suppliers. State-owned engineering groups concentrate specialized apron construction capabilities in the Yangtze River Delta.
India
Uttar Pradesh and Bihar greenfield airports expand under UDAN regional connectivity subsidies with untested passenger guarantees. The CEA mandates electrical safety specifications for airfield lighting systems that reshape contractor selection. GMR Group leverages integrated development models across Delhi-NCR and Hyderabad to sustain concession revenue structures.
Japan
Osaka Kansai and Narita facilities face METI energy-efficiency retrofit deadlines for LED airfield lighting and solar-integrated terminal roofs. JIS standards for transport infrastructure compress contractor approval timelines. Engineering specialists pre-certify products to accelerate procurement in the Kansai industrial corridor.
Australia
Qantas and Singapore Airlines consolidate multi-airport ground handling contracts across Australian and Southeast Asian hubs. Three providers now control eighty percent of major airport handling capacity. AECOM anchors multidisciplinary teams in Sydney for cross-border design-build contracts.
Vietnam
Dak Lak and Gia Lai provinces in the Central Highlands present first-mover opportunities for concessionaires accepting lower initial throughput guarantees. Contractor scarcity for specialized apron and taxiway work limits competitive bidding. Japanese and Chinese engineering consortiums dominate technical procurement.
Asia-Pacific Aviation Infrastructure Market Competitive Environment
Capacity expansion dominates the current landscape as low-cost carrier fleet orders force rapid gate and apron upgrades across Southeast Asian hubs. The vendor base splits between state-owned Chinese engineering groups with specialized runway capabilities and multinational design-build firms anchoring multidisciplinary teams. Three strategic archetypes emerge: integrated airport developers capturing long-term concession revenue, specialized airfield contractors with PCN/ACN pavement expertise, and cross-border engineering consultancies bundling feasibility through construction delivery. M&A activity concentrates among ground handlers consolidating multi-airport frameworks, while technology licensing accelerates for biometric security integrators.
Among integrated developers, GMR Group and GVK Industries exemplify the concession-led archetype through their presence across Indian aviation infrastructure. Beijing Jinghang Airport Engineering occupies a position within specialized domestic Chinese engineering, representing state-linked capabilities in runway and apron construction. AECOM Limited and Mott MacDonald anchor the multinational consultancy tier, sitting within cross-border design-build procurement for Asia-Pacific terminal and airfield projects.
| Leading Market Players |
|---|
| JGC Holdings Corporation |
| Turner Construction Company |
| GMR Group |
| Mott MacDonald Group Limited |
| Beijing Jinghang Airport Engineering Co. Ltd. |
| AECOM Limited |
| JLL Inc. |
| Ove Arup & Partners International Limited |
| GVK Industries Limited |
| Others |
Value Chain & Pricing Dynamics
Certified airfield electrical engineers concentrated in China's Yangtze River Delta and India's Maharashtra corridor command wage premiums that widen pricing spreads between premium-tier design-build contracts and economy-tier maintenance-only engagements across the Asia-Pacific aviation infrastructure market.
Pricing Analysis
Input-cost pass-through from high-grade Portland cement and specialized steel reinforcement governs runway construction quotations across Southeast Asian projects. Three-tier pricing structure across premium, standard, and economy levels separates full-service engineering-procurement-construction delivery from design-only consultancy and reactive maintenance contracts. Price differentiation hinges on CEA electrical safety certification tier and MIIT smart airport compliance depth. Pricing pressure stems from steel and cement input volatility tied to China's construction slowdown, with budget airlines operating UDAN-subsidized routes in India exhibiting highest price sensitivity while GMR Group's concession-backed developments in Delhi-NCR show lowest.
Supply Chain Analysis
Workforce availability constraints in Vietnam and the Philippines for specialized apron and taxiway construction compress contractor selection timelines and extend procurement cycles. Manufacturing concentration rests on China for LED airfield lighting systems, Japan for precision baggage handling components, and India for electrical grounding equipment under CEA specifications. Raw material dependencies draw from high-grade Portland cement, electromagnetic-shielded copper cabling, and solar-integrated roofing membranes. Single-source vulnerability concentrates among state-owned Chinese engineering groups controlling specialized runway pavement capabilities. Distribution runs through government agency procurement frameworks in China and India, with private airport authority tenders gaining share in Australia and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific aviation infrastructure offers margin expansion through predictive maintenance contract extensions and digital twin service layering that captures lifecycle value beyond initial construction delivery.
For Market Incumbents: Anticipate biometric security mandate acceleration across Beijing, Shanghai, and Guangzhou by pre-certifying terminal automation systems to MIIT digital identity protocols before 2025 compliance deadlines. Deepen backward integration into LED airfield lighting manufacturing to offset electromagnetic interference testing delays that disadvantage foreign suppliers under China's GB standards. Anchor multidisciplinary design-build teams in Singapore and Australia to defend cross-border contract share against emerging Indian engineering consortiums.
For New Entrants and Emerging Players: Direct-to-government digital procurement portals in Vietnam's Central Highlands offer first-mover positioning for concessionaires accepting lower initial throughput guarantees in Dak Lak and Gia Lai provinces. Target baggage handling system middleware development for Jakarta and Manila legacy terminals where tilt-tray sorter interface failures create white-space demand. Lead with JIS pre-certified product offerings to compress approval timelines for Japan METI energy-efficiency retrofit subsidies.
For Investors and Strategic Acquirers: Integrated airport developers with concession-led revenue structures are the most active acquirer in this space, consolidating ground handling capacity across multi-airport frameworks as Qantas and Singapore Airlines centralize procurement. Long-term viability over a five-to-ten-year horizon favors asset-light predictive maintenance platforms over capital-heavy construction exposure. Watch for UDAN scheme passenger throughput guarantee renegotiations as an inflection indicator for Indian greenfield airport valuation stress.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Enables predictive maintenance contracts for baggage handling and HVAC systems at Singapore Changi and Sydney hubs. |
| Biometric Boarding Gate Retrofit | Secures MIIT compliance revenue across Beijing, Shanghai, and Guangzhou terminal automation upgrade cycles. |
| LED Airfield Lighting Pre-Certification | Accelerates JIS approval timelines for Osaka Kansai and Narita METI energy-efficiency retrofit mandates. |
| Multi-Airport Ground Handling Consolidation | Captures scale economies as Qantas and Singapore Airlines centralize Australian and Southeast Asian hub contracts. |
| CEA Electrical Safety Specialization | Differentiates contractor selection for Indian airport expansions facing skilled technician scarcity in Uttar Pradesh and Bihar. |
Study Parameters
Bottom-up airline and airport authority modeling reconciled against top-down construction and technology supplier tracking forms the analytical core of this study. Primary interviews with airport authority procurement directors, airline fleet planning executives, ground handling operations managers, and CEA-certified electrical engineers combined with secondary validation from MIIT smart airport directives, UDAN regional connectivity scheme filings, METI energy-efficiency code databases, and customs records for cement and steel imports. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of capital deployment cycles across greenfield construction, terminal retrofit, and maintenance contract extensions informs the projection framework. Segmentation dimensions modeled include infrastructure type, technology procurement category, end-user authority structure, and service delivery model across the analysis window. CAGRs derive from regression against passenger throughput trajectories, fleet order backlogs, and regulatory mandate implementation schedules. Forecast inputs incorporate low-cost carrier expansion timelines and digital twin adoption curves for predictive asset management.
The model assumes a particular technology adoption path; alternative pathways for CT scanner deployment or biometric boarding gate integration would alter the outlook. Forecasts reflect assumptions regarding UDAN subsidy continuity, MIIT compliance enforcement rigor, and METI retrofit deadline adherence. Material deviation in steel and cement input costs, land acquisition resolution timelines in Maharashtra and Karnataka, or electromagnetic interference testing protocol changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Engineered Material Arresting System Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Airport Kiosk Market