
 Airfield Ground Lighting (AGL) Systems Market | 2026-2036
Airfield Ground Lighting (AGL) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Airfield Ground Lighting (AGL) Systems Market Outlook
Multi-source procurement strategies is expanding across the AGL systems value chain as airport operators reduce dependency on single-vendor maintenance contracts. TKH Airport Solutions leverages its European manufacturing footprint to anchor supply agreements with major hub airports. ADB SAFEGATE competes through its integrated airfield management software paired with hardware deployments. Siemens AG sustains market presence via its energy-efficient power distribution architectures for airfield electrical systems.
Airfield Ground Lighting (AGL) Systems comprise electrically operated luminaires, signage, and control equipment installed on airport movement areas to provide visual guidance for aircraft operations during low-visibility conditions and nighttime operations, typically operating on constant current series circuits at 6.6 amperes with isolation transformers protecting individual fixtures. These systems serve the primary commercial purpose of ensuring safe aircraft taxiing, takeoff, and landing while minimizing runway incursion risks. LED technology dominates current procurement as operators pursue lifecycle cost reductions and chromaticity stability required by ICAO standards. Installation configurations favor in-ground fixtures for runways and taxiways where foreign object damage risks demand flush-mounted designs, while above-ground solutions persist in approach lighting systems where elevation improves pilot visibility.
FAA AC 150/5340-26 and ICAO Annex 14 Volume I establish photometric and chromaticity standards that directly determine product eligibility for certified airport installations. EASA CS-ADR-DSN harmonizes European requirements with ICAO baselines while adding electromagnetic compatibility testing protocols. The EU Green Deal's energy efficiency directives are accelerating LED retrofit timelines across member state airports. Stakeholders must monitor evolving cybersecurity requirements for airfield lighting control systems as remote monitoring and IoT integration expand attack surfaces.
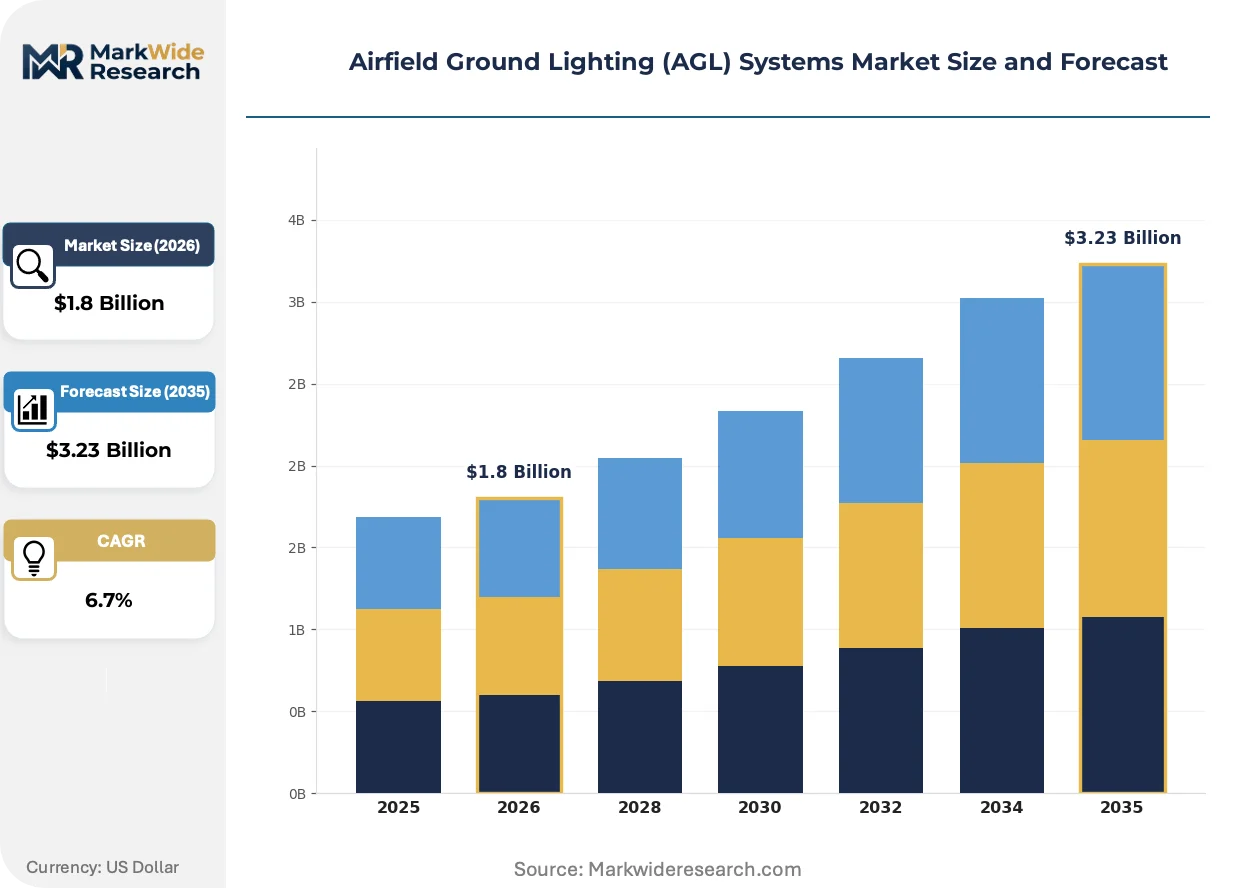
Market Dynamics
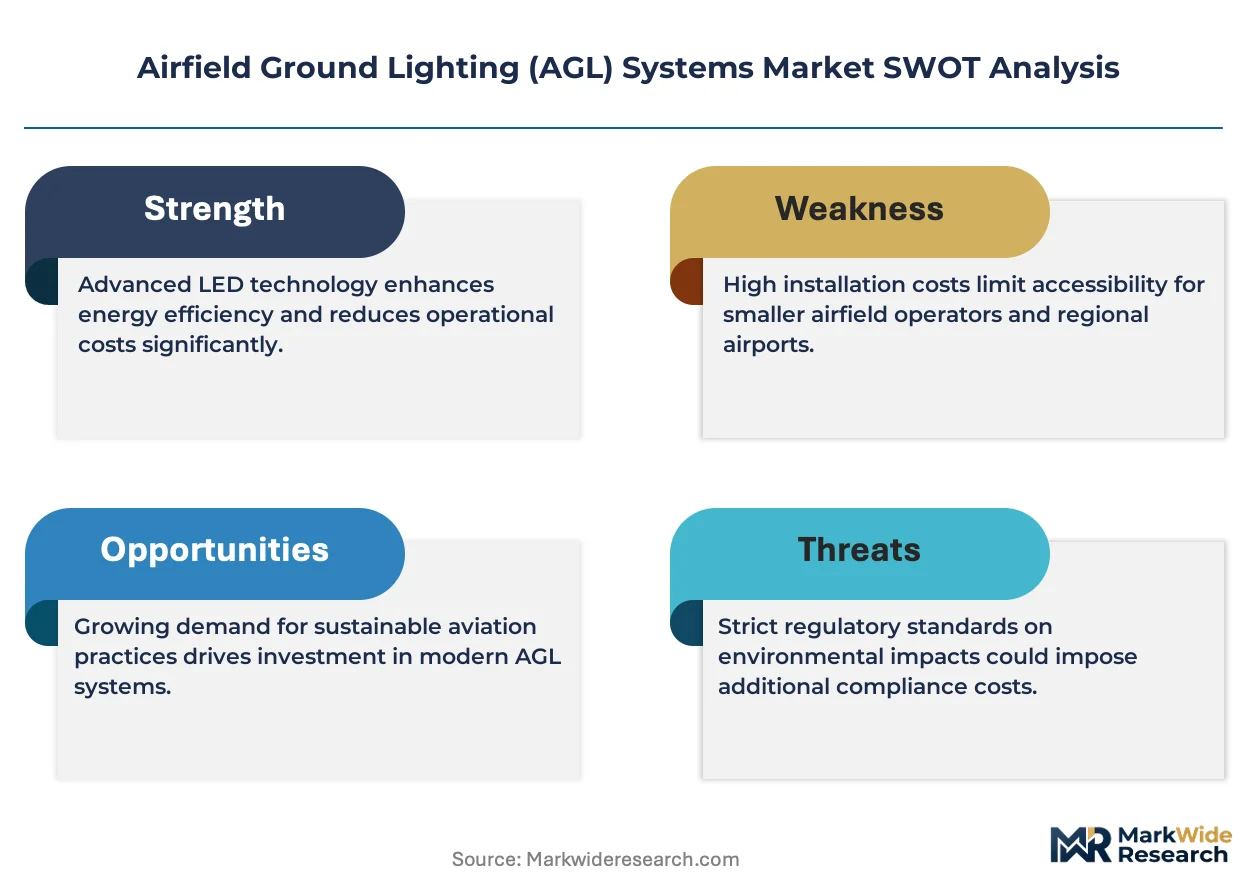
Airport operators face compressed replacement timelines as FAA AC 150/5340-30 mandates and ICAO Annex 14 compliance deadlines converge, forcing simultaneous capital outlays across runway, taxiway, and approach lighting subsystems.
Growth Catalysts
- LED Retrofit Mandates:FAA AC 150/5340-30 and EU Green Deal energy efficiency directives compel halogen-to-LED conversions at commercial airports, accelerating procurement cycles for constant current series circuit infrastructure.
- China:Multi-billion-dollar airport modernization programs at hub facilities in Beijing, Shanghai, and Guangzhou concentrate demand for in-ground fixture installations with isolation transformer protection.
- Photometric Standard Harmonization:EASA CS-ADR-DSN alignment with ICAO Annex 14 Volume I chromaticity requirements streamlines product certification eligibility across European member states.
Market Restraints
- Copper and Aluminum Input Volatility:Constant current series circuits and isolation transformers depend on conductor materials subject to commodity price swings, pressuring fixed-price installation contracts.
- Single-Source Control System Risk:Proprietary airfield lighting management software from dominant vendors creates vendor lock-in that limits airport operator negotiation leverage on maintenance renewals.
- Cybersecurity Compliance Friction:Remote monitoring and IoT integration expand attack surfaces, yet unified cybersecurity standards for airfield lighting control systems remain under development at ICAO and national civil aviation authorities.
Strategic Opportunities
- India:Greenfield airport construction under the UDAN regional connectivity scheme and PLI scheme incentives for domestic manufacturing create entry points for LED-based AGL system providers.
- Photovoltaic-LED Convergence:Solar-powered taxiway edge lights with integrated battery storage reduce trenching and cable installation costs at remote airfields and general aviation facilities.
- Performance-Based Maintenance Contracts:Outcome-oriented service agreements that tie contractor payments to availability metrics and mean-time-between-failures are displacing traditional time-and-materials arrangements at German and Dutch hub airports.
Industry Challenges
- Certified Technician Scarcity:FAA-certified airfield lighting technicians and ICAO-compliant maintenance personnel face supply constraints relative to installation and retrofit demand, extending project timelines.
- Legacy 6.6A Circuit Integration:New LED fixtures must interface with aging constant current regulators and existing isolation transformer banks, complicating phased upgrade strategies without full system shutdowns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airfield Ground Lighting (AGL) Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Runway Lights, Taxiway Lights, Approach Lights, Obstruction Lights Technology: LED, Halogen, Xenon, Fluorescent Installation: In-ground, Above-ground, Portable, Fixed End User: Airports, Military Bases, Private Airstrips, Aviation Authorities |
| Companies Covered | TKH Airport Solutions BV, ATG Airports Limited, ADB SAFEGATE, Siemens AG, Carmanah Technologies Corp., Honeywell International Inc., OCEM Airfield Technology, ABB Ltd., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airfield Ground Lighting (AGL) Systems Market Strategic Shifts
Digitalization of airfield operations is compressing the boundary between lighting hardware and air traffic management software, creating integrated platforms that merge visual guidance with surface surveillance data.
Adaptive LED arrays with individual addressability and real-time intensity modulation are rewriting how airports manage low-visibility operations. Major hub facilities in Germany and the United States are deploying these systems to enable dynamic runway status indication and automated NOTAM generation. The technology is compressing the traditional separation between lighting infrastructure and airfield ground control systems.
EU Green Deal energy efficiency directives are accelerating retrofit timelines by embedding LED conversion requirements within national airport carbon reduction commitments. EASA member states must demonstrate compliance through measurable kWh reductions in airfield electrical systems. Commercial airports in France, the Netherlands, and Spain are responding by bundling lighting upgrades with broader airfield electrification projects.
Multi-vendor maintenance strategies are fragmenting traditional single-source service relationships. Airport operators in the United States and United Kingdom are unbundling hardware supply from control software and after-sales support, creating openings for specialized contractors. This pattern is most visible at mid-sized regional airports seeking to reduce lifecycle costs through competitive tendering of individual subsystem contracts.
Airfield Ground Lighting (AGL) Systems Market Segmentation
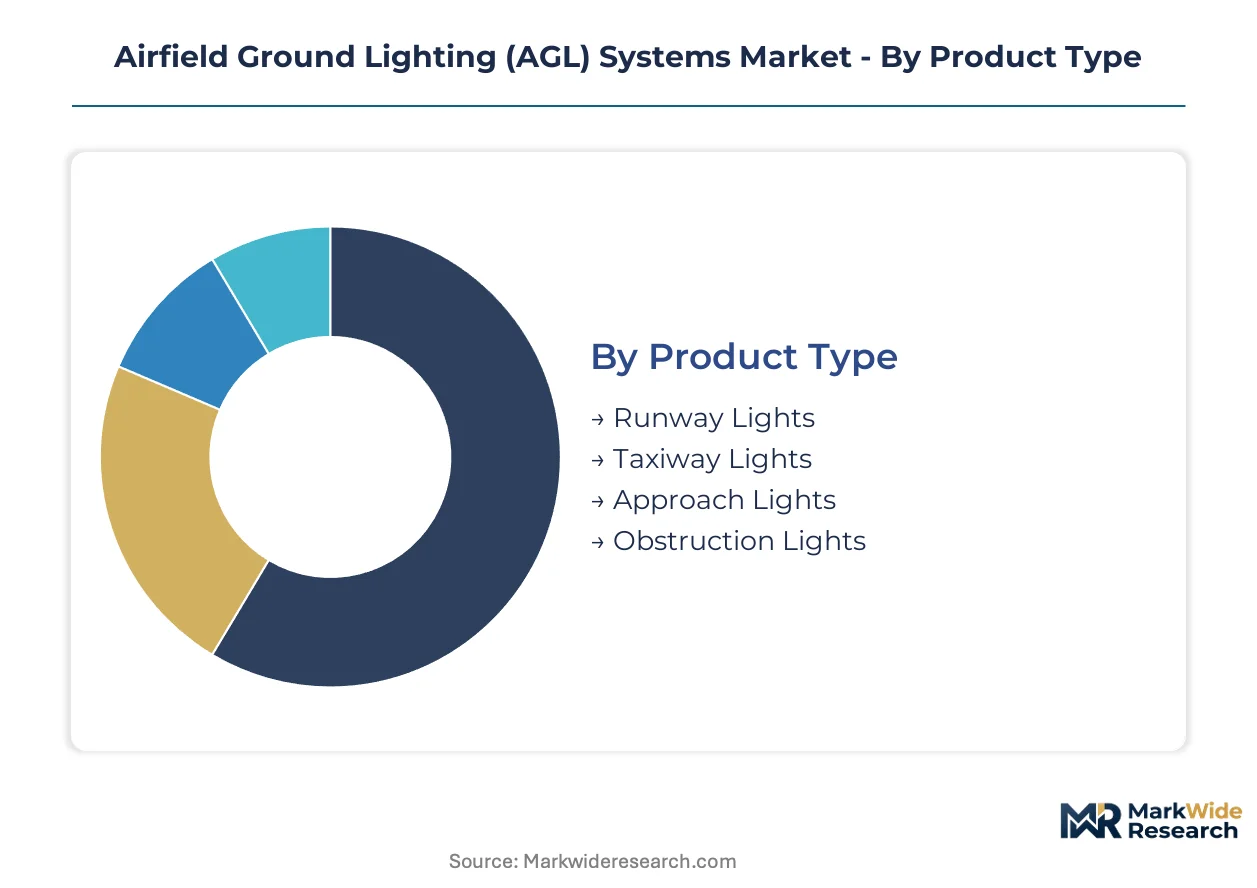
Airfield Ground Lighting procurement patterns diverge sharply across operational contexts. Regulatory mandates, infrastructure age, and operational tempo create distinct buyer profiles that reshape vendor go-to-market strategies.
Product Type:
Procurement scale and replacement urgency separate hub airports from regional facilities in this category.
- Runway Lights:Centerline and edge fixtures operating on 6.6A constant current series circuits with isolation transformer protection. Demand concentrates at commercial airports in the United States and Germany where FAA AC 150/5340-30 and EASA CS-ADR-DSN compliance deadlines force simultaneous replacement of threshold, runway end, and touchdown zone lighting.
- Taxiway Lights:Edge, centerline, and stop bar fixtures guiding aircraft surface movement. Chinese hub airports in Beijing and Shanghai are driving in-ground LED installations as part of multi-billion-dollar modernization programs prioritizing chromaticity stability and foreign object damage resistance.
- Approach Lights:Precision and non-precision approach lighting systems extending from runway thresholds. These above-ground installations persist where elevation improves pilot visibility during low-visibility operations.
- Obstruction Lights:Tower and structure marking beacons for airspace clearance. General aviation facilities and wind farm proximate airports generate steady demand for LED-based obstacle lighting.
Runway Lights lead volumes today; Taxiway Lights is gaining share fastest.
Technology:
Lifecycle cost calculations and regulatory compliance timelines determine technology selection across operator types.
- LED:Solid-state illumination with chromaticity stability meeting ICAO Annex 14 Volume I standards. EU Green Deal energy efficiency directives are compressing payback periods for LED retrofits at EASA member state airports in France, the Netherlands, and Spain.
- Halogen:Incandescent technology in phased replacement at aging North American and European installations. Legacy 6.6A circuit compatibility sustains residual demand during multi-year upgrade programs.
- Xenon:High-intensity discharge lighting for approach and obstruction applications. Specialized aviation authorities specify xenon where extreme brightness requirements exceed LED output thresholds.
- Fluorescent:Limited application in signage and supplemental illumination. Private airstrips in cost-sensitive markets retain fluorescent for non-critical visual guidance.
LED dominates current procurement; Halogen retains residual presence in phased replacement schedules.
Installation:
Physical configuration trade-offs between durability, maintenance access, and airside safety shape specification decisions.
- In-ground:Flush-mounted fixtures protecting against foreign object damage and jet blast. Commercial airports prioritize these for runways and taxiways where aircraft movement frequency demands mechanical resilience.
- Above-ground:Elevated masts and frangible structures for approach lighting and obstruction marking. These installations improve pilot sight lines where terrain or weather patterns reduce visibility.
- Portable:Temporary lighting for construction zones, emergency operations, and military expeditionary airfields. Rapid deployment requirements favor battery-integrated LED units with wireless control.
- Fixed:Permanent hardwired installations with underground cable infrastructure. Hub airports in China and the United States specify fixed systems for core movement areas.
In-ground fixtures command the largest installed base; Portable systems are expanding most quickly in military and contingency applications.
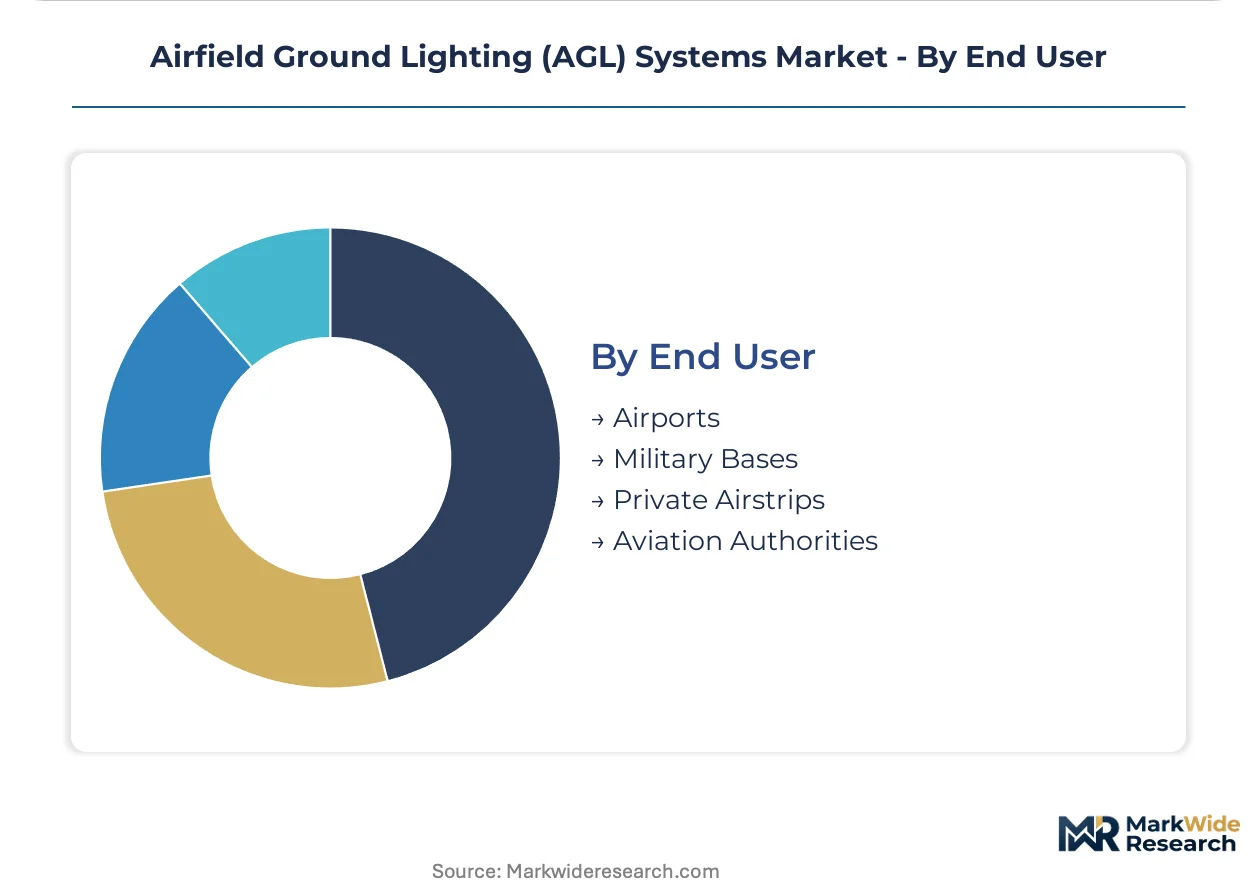
End User:
Budget authority and regulatory oversight intensity create distinct purchasing behaviors across operator categories.
- Airports:Commercial passenger and cargo facilities with capital programs tied to regulatory compliance. These operators bundle lighting upgrades with broader airfield electrification and carbon reduction commitments.
- Military Bases:Defense installations with operational requirements for rapid runway repair and contingency lighting. Procurement emphasizes ruggedization and interoperability with tactical air navigation systems.
- Private Airstrips:Corporate and recreational aviation facilities with limited capital budgets. These buyers prioritize cost minimization over advanced control system integration.
- Aviation Authorities:National civil aviation bodies specifying standards-compliant systems for multiple facilities. Centralized procurement generates volume concentration for vendors meeting certification requirements.
Airports generate the majority of current revenue; Military Bases show the steepest expansion trajectory as defense infrastructure modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hub airports concentrate procurement velocity as FAA AC 150/5340-30 compliance deadlines force synchronized replacement of runway, taxiway, and approach lighting infrastructure across major metropolitan facilities.
United States
FAA-certified airfield lighting technicians face supply constraints relative to installation demand at Hartsfield-Jackson Atlanta, Dallas-Fort Worth, and Denver International. FAA AC 150/5340-30 mandates compress replacement timelines across these hub facilities. Chicago O'Hare and Los Angeles International execute multi-year LED retrofit programs tied to carbon reduction commitments.
Germany
EASA CS-ADR-DSN harmonization with ICAO Annex 14 Volume I streamlines product certification eligibility for Frankfurt, Munich, and Berlin Brandenburg. EU Green Deal energy efficiency directives embed LED conversion requirements within national airport carbon budgets. The Rhine-Main cluster around Frankfurt anchors European procurement volume for in-ground fixture installations.
China
Multi-billion-dollar modernization programs at Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun concentrate demand for chromaticity-stable LED systems with isolation transformer protection. The country's national civil aviation regulator mandates compliance with ICAO Annex 14 standards for all new hub construction. The Yangtze River Delta and Pearl River Delta clusters drive installation scale for taxiway edge lighting.
India
Greenfield airport construction under the UDAN regional connectivity scheme creates entry points for LED-based system providers at secondary cities. PLI scheme incentives for domestic manufacturing reshape supplier selection criteria for aviation authorities. The Delhi-NCR and Mumbai metropolitan clusters concentrate procurement for Indira Gandhi International and Chhatrapati Shivaji Maharaj International expansions.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International anchor Middle Eastern demand for adaptive LED arrays with real-time intensity modulation capabilities. The country's national civil aviation body enforces ICAO Annex 14 compliance across all commercial facilities. Dubai South and Al Maktoum International expansion projects sustain procurement velocity for integrated airfield management platforms.
Airfield Ground Lighting (AGL) Systems Market Competitive Environment
Global majors compete with regional champions across certification breadth and maintenance contract reach, producing a tiered structure where full-stack providers coexist with specialized component fabricators. Three archetypes dominate: integrated airfield management platform vendors, LED fixture specialists with European manufacturing footprints, and electrical infrastructure conglomerates with power distribution expertise. M&A activity concentrates on software-hardware convergence capabilities, while geographic expansion into Indian and Middle Eastern greenfield projects represents the second dominant competitive vector.
Within the integrated platform tier, ADB SAFEGATE and Honeywell International Inc. exemplify providers bundling control software with hardware deployments. TKH Airport Solutions BV occupies a position among European-anchored specialists leveraging regional manufacturing proximity for hub airport supply agreements. Siemens AG and ABB Ltd. represent electrical infrastructure conglomerates sustaining market presence through energy-efficient power distribution architectures for airfield electrical systems.
| Leading Market Players |
|---|
| TKH Airport Solutions BV |
| ATG Airports Limited |
| ADB SAFEGATE |
| Siemens AG |
| Carmanah Technologies Corp. |
| Honeywell International Inc. |
| OCEM Airfield Technology |
| ABB Ltd. |
| Eaton Corporation |
| Others |
Value Chain & Pricing Dynamics
FAA AC 150/5340-30 compliance deadlines forcing synchronized replacement of runway, taxiway, and approach lighting infrastructure are compressing procurement timelines and tilting negotiation leverage toward certified vendors with immediate delivery capacity. This demand surge is reshaping how suppliers structure pricing across constant current series circuit components and isolation transformer banks.
Pricing Analysis
Copper and aluminum conductor cost pass-through dominates pricing volatility for constant current series circuits and isolation transformers, pressuring fixed-price installation contracts at commercial airports. Three-tier pricing structure across premium certified, standard compliant, and economy retrofit levels separates vendors by EASA CS-ADR-DSN and FAA certification breadth. Pricing pressure stems from certified technician scarcity extending project timelines and inflating labor cost allocations. Regional airports exhibit highest price sensitivity due to constrained capital budgets, while hub airports in Germany and the United States prioritize chromaticity stability and lifecycle cost over upfront expenditure.
Supply Chain Analysis
Regional distribution centers in the Netherlands, Germany, and China anchor hub-and-spoke fulfillment patterns for LED fixture manufacturers serving European and Asian airport clusters. Manufacturing concentration in Germany, China, and the United States feeds from copper conductor, aluminum housing, and semiconductor die supply streams. Single-source vulnerability in certified isolation transformer production creates procurement risk for phased retrofit programs requiring legacy 6.6A circuit compatibility. Distribution runs through authorized service contractors holding FAA or EASA maintenance certifications, limiting direct vendor-airport relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FAA AC 150/5340-30 and ICAO Annex 14 compliance deadlines generate replacement demand irrespective of cyclical conditions. The convergence of mandates across North America and Europe sustains procurement velocity through the analysis window.
For Market Incumbents: Acquire software-hardware convergence capabilities to defend against integrated platform competitors bundling airfield management systems with LED deployments. Deepen backward integration into isolation transformer manufacturing to secure supply continuity against copper price volatility. Lock in performance-based maintenance contracts with German and Dutch hub airports to create switching costs that protect renewal revenue streams from unbundling trends. For New Entrants and Emerging Players: Secondary cities in India under the UDAN regional connectivity scheme represent the most penetrable buyer archetype for LED-based AGL system providers seeking greenfield airport construction contracts. Solar-powered taxiway edge lights with integrated battery storage address cost-sensitive general aviation facilities and remote airfields where trenching expenses deter fixed infrastructure investment. Partner with domestic manufacturers qualifying under India's PLI scheme to meet local content requirements for aviation authority procurement. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized LED fixture fabricators holding EASA CS-ADR-DSN and FAA dual certification that positions them for European and North American hub airport retrofits simultaneously. Long-term viability rests on regulatory mandate durability rather than discretionary capital expenditure cycles. Monitor ICAO cybersecurity standard development for airfield lighting control systems as the signal indicating when remote monitoring capabilities will become mandatory specification elements.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | EASA CS-ADR-DSN and FAA dual certification unlocks procurement eligibility across German and United States hub airports. |
| Software-Hardware Integration | Airfield lighting management platforms merging with surface surveillance data command premium positioning in control system tenders. |
| Regional Manufacturing Footprint | European production proximity reduces logistics costs for Frankfurt, Munich, and Amsterdam Schiphol supply agreements. |
| Performance-Based Maintenance Contracts | Outcome-oriented service agreements tied to availability metrics displace time-and-materials arrangements at Dutch airports. |
| Photovoltaic-LED Convergence | Solar-powered taxiway edge lights reduce installation costs at remote airfields and military expeditionary bases. |
Study Parameters
Coverage spans the United States, Germany, China, and India, with primary inputs from each region combining interviews with airport procurement directors, FAA-certified maintenance contractors, EASA compliance officers, and LED fixture engineering leads with secondary validation. Primary fieldwork draws from airfield electrical system planners at hub airports, aviation authority specification committees, and control software integration specialists. Secondary sources include FAA AC 150/5340-series circulars, EASA CS-ADR-DSN documentation, ICAO Annex 14 Volume I standards, and national airport carbon reduction commitment disclosures. Bottom-up installation volume estimates triangulate against top-down regulatory mandate timelines.
Rate-of-change decomposition separates LED retrofit penetration from halogen replacement velocity across the projection horizon. Segmentation dimensions modeled include product type, technology tier, installation configuration, and end-user category with airport operational tempo as an industry-specific demand weighting factor. CAGRs derive from regulatory deadline clustering analysis and certified technician supply constraints. Forecast inputs incorporate copper price trajectory assumptions and EU Green Deal energy efficiency directive implementation pace.
Underlying measurement precision varies by segment; runway and taxiway lighting categories carry tighter precision than obstruction and portable applications due to more standardized specification requirements. Forecasts reflect assumptions regarding mandate adherence schedules and material cost stability that could revise with regulatory delay or commodity shock. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market