
 Telescopic Masts Market | 2026-2036
Telescopic Masts Market Size, Share, and Industry Trends Forecast 2026-2036
Telescopic Masts Market Outlook
Military-grade specification tiers is rotating toward center stage as defense agencies prioritize rapid-deployment capability and electromagnetic resilience. Will-Burt Company leverages its vertically integrated manufacturing footprint across Ohio and Germany to sustain delivery timelines for NATO-aligned customers. Clark Masts Systems Ltd. anchors its competitive position through specialized naval and marine-environment mast configurations. Comrod Communication AS differentiates via integrated antenna-mast systems for tactical radio networks.
Telescopic masts are extendable support structures fabricated from aluminum, steel, or composite materials, typically employing nested tubular segments that deploy through manual, hydraulic, pneumatic, or electric actuation to heights ranging from 3 to 50 meters for elevating antennas, lighting, cameras, or sensors. Wall thickness, segment overlap ratios, and locking mechanism designs determine wind-load ratings and operational stability under field conditions. Pneumatic and electric mast categories command premium positioning due to faster deployment cycles and reduced crew requirements in defense and emergency services applications. Aluminum material grades dominate volume production for weight-sensitive mobile platforms, while composite variants capture margin pools in corrosion-critical maritime and coastal deployments. Telecommunications providers represent a mature demand channel with replacement-driven purchasing patterns, whereas public safety agencies exhibit accelerated procurement tied to interoperable communications mandates.
ISO 9001 quality management and IEC structural standards govern mast design validation and international market access, while the EU AI Act and CE marking frameworks increasingly influence smart-mast sensor integration requirements in European defense tenders. The US FAA and FCC coordinate height and frequency clearance protocols for masts deployed near airfields and broadcast corridors, constraining site selection but creating compliance-service opportunities for manufacturers. Stakeholders must monitor evolving military interoperability standards and carbon-footprint disclosure rules as procurement criteria harden across NATO and Asia-Pacific defense agencies.
Market Dynamics
Defense procurement cycles are compressing toward rapid-deployment specifications, forcing manufacturers to reconfigure production lines for electromagnetic-hardened pneumatic masts that deploy under 90 seconds without ground anchoring.
Growth Catalysts
- Interoperable Communications Mandates:Public safety agencies in the United States accelerate mast procurement to satisfy FirstNet coverage requirements for disaster-response coordination.
- Dual Carbon Goals:China's GB standards for aluminum recycling and energy intensity are redirecting domestic production toward low-carbon composite mast grades for maritime applications.
- Battlefield Electromagnetic Resilience:NATO-aligned defense agencies specify carbon-fiber mast segments with integrated shielding to reduce radar cross-section and signal interception vulnerability.
Market Restraints
- Aluminum Alloy Supply Concentration:Primary billet sourcing clusters in Chinese smelting regions expose European fabricators to tariff volatility and carbon-border adjustment costs.
- FAA Height Clearance Friction:Airfield proximity restrictions in the United States extend site-permit timelines by 8-14 months for telecommunications masts exceeding 30 meters.
- Fixed-Tower Substitution:Permanent lattice structures capture base-load broadcast infrastructure spend where mobility provides no operational advantage.
Strategic Opportunities
- Smart-Mast Sensor Convergence:Integration of environmental monitoring payloads with 5G small-cell backhaul creates new revenue pools for mast-telemetry service contracts.
- India Defense Modernization:Indigenous procurement preferences under the PLI scheme open channels for local assembly partnerships serving army mobile communication units.
- EU AI Act Compliance Services:CE marking for autonomous mast-positioning systems generates consulting and retrofit demand among legacy European manufacturers.
Industry Challenges
- Welding Certification Bottlenecks:Military-grade aluminum mast fabrication requires AWS D17.1 aerospace welder qualifications that constrain qualified labor pools in Midwest US manufacturing clusters.
- Legacy Hydraulic System Integration:Defense maintenance depots face tooling incompatibility when fielding electric-actuation masts alongside existing pneumatic inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telescopic Masts Market |
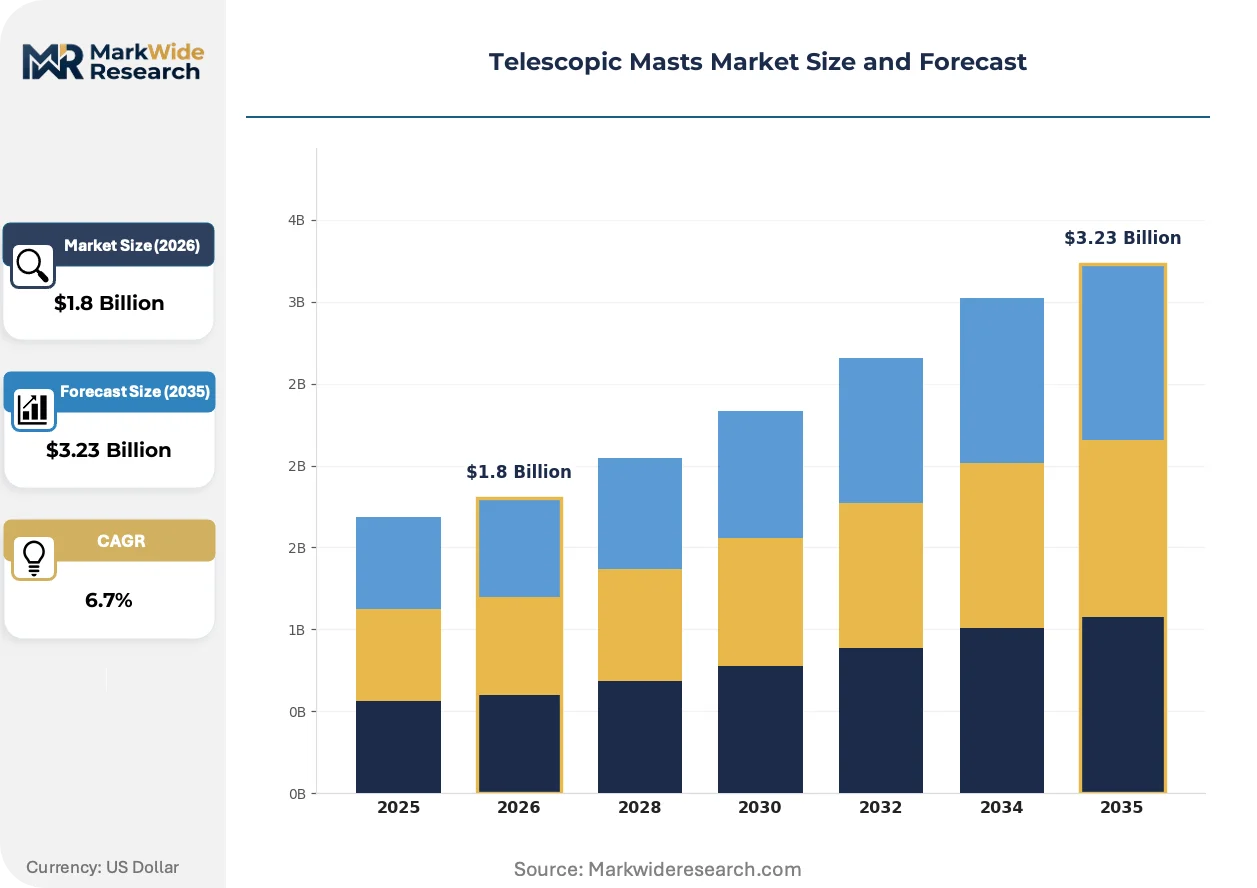
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Masts, Hydraulic Masts, Pneumatic Masts, Electric Masts Application: Telecommunications, Defense, Construction, Emergency Services End User: Public Safety Agencies, Telecommunications Providers, Military, Event Organizers Material: Aluminum, Steel, Composite, Alloy |
| Companies Covered | Larsen & Toubro Limited, Clark Masts Systems Ltd., Total Mast Solutions, Hilomast LLC, Comrod Communication AS, Will-Burt Company, Rohn Industries, Will-Burt Germany, Fireco S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telescopic Masts Market Strategic Shifts
Material science advances and regulatory digitization are converging to redefine mast performance benchmarks and certification pathways across defense and civilian deployments.
Carbon-fiber-reinforced polymer (CFRP) mast segments are supplanting aluminum alloys in naval and coastal applications where salt corrosion degrades metallic structures within 36 months. Royal Navy and US Coast Guard procurement specifications now prioritize CFRP for shipboard antenna masts, compressing maintenance intervals from annual to triennial cycles and reducing topside weight by 40-60 percent.
The EU AI Act's risk-classification framework is mandating algorithmic transparency for smart masts with autonomous leveling and wind-load adjustment. Manufacturers serving European defense tenders must document training data provenance and failure-mode testing for machine-vision stabilization systems, adding 6-9 months to product validation timelines.
Outcome-based service contracts are displacing capital-equipment purchases among telecommunications tower operators in Germany and the United Kingdom. Lease agreements now bundle mast deployment, maintenance, and decommissioning into per-month site fees, transferring obsolescence risk to manufacturers and compressing product development cycles to match contract renewal windows.
Telescopic Masts Market Segmentation
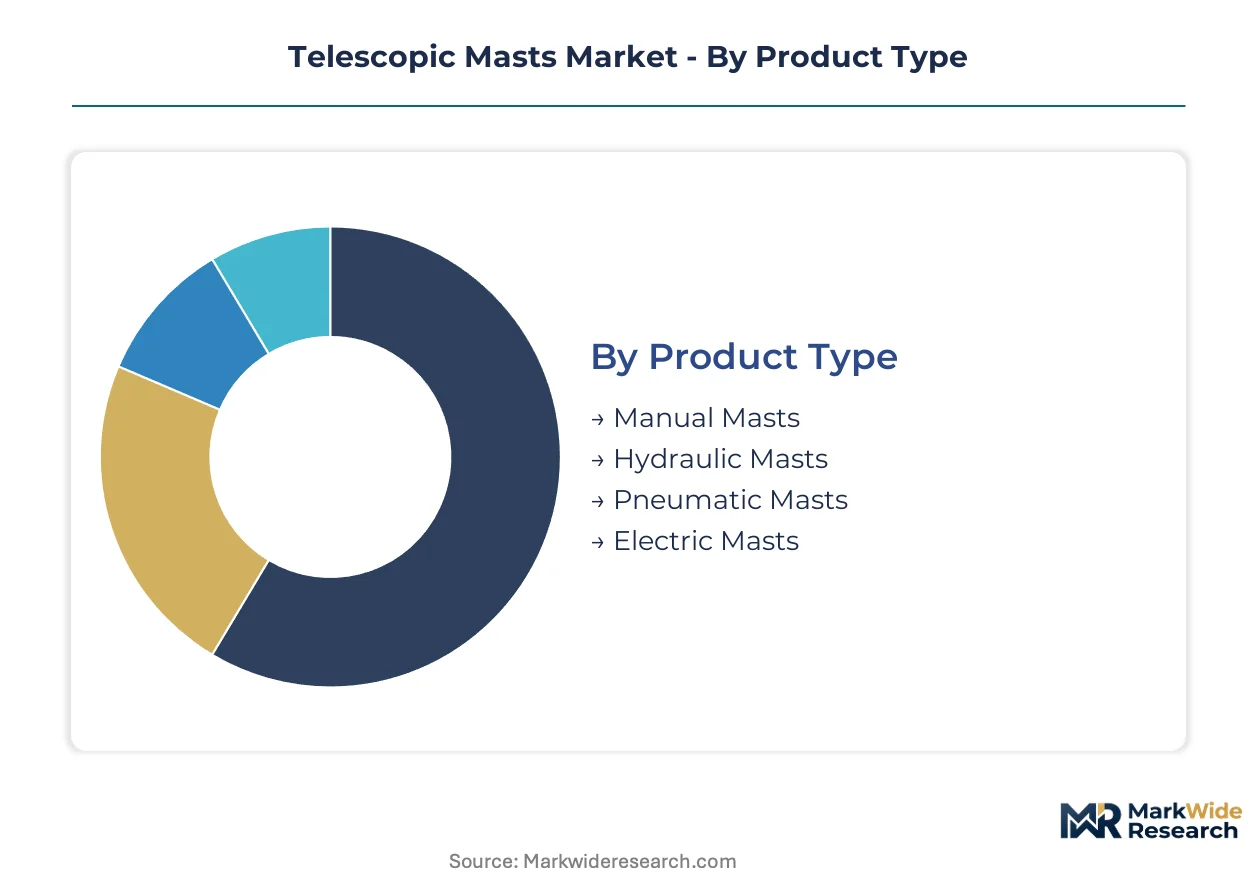
Telescopic mast procurement patterns diverge sharply across deployment contexts, with actuation technology and material specification acting as the primary axes of supplier differentiation. Defense and telecommunications buyers impose incompatible performance benchmarks, fragmenting manufacturing capabilities across distinct certification tiers.
Product Type:
Premium margin pools concentrate in automated deployment systems where military specifications reward sub-90-second cycle times and electromagnetic-hardened construction.
- Pneumatic Masts:Compressed-air actuation delivers the fastest field deployment without ground anchoring, satisfying NATO rapid-deployment mandates for battlefield communications. Defense agencies in the United States and Germany prioritize these units for forward operating bases where crew minimization determines operational tempo.
- Electric Masts:Servo-motor precision enables integrated sensor feedback and autonomous leveling capabilities required under the EU AI Act's risk-classification framework. Smart-mast telemetry contracts in Germany and the United Kingdom favor electric architectures for 5G small-cell backhaul integration.
- Hydraulic Masts:Fluid-power systems dominate legacy military maintenance depots and heavy-lift construction applications where load capacity outweighs speed requirements.
- Manual Masts:Hand-cranked segments serve cost-constrained event organizers and backup emergency deployments where power availability cannot be guaranteed.
Electric masts hold installed capacity in European smart-infrastructure tenders. Pneumatic masts are rotating up the share rankings in NATO defense procurement.
Application:
Volume concentration tilts toward replacement cycles in mature telecommunications infrastructure, while defense and emergency services drive specification innovation.
- Defense:Carbon-fiber mast segments with integrated electromagnetic shielding reduce radar cross-section for naval and expeditionary forces. Royal Navy and US Coast Guard specifications now mandate corrosion-resistant composites for shipboard antenna masts, compressing maintenance intervals from annual to triennial cycles.
- Telecommunications:Tower operators in Germany and the United Kingdom are displacing capital purchases with outcome-based service contracts bundling deployment, maintenance, and decommissioning into per-month site fees.
- Emergency Services:Public safety agencies in the United States accelerate procurement to satisfy FirstNet interoperable communications mandates for disaster-response coordination.
- Construction:Temporary lighting and surveillance masts serve infrastructure projects where mobility eliminates fixed-tower capital expenditure.
Telecommunications holds installed capacity across European tower portfolios. Defense is rotating up the share rankings in procurement value.
End User:
Contract structure and certification requirements separate institutional buyers from commercial operators, with military and public safety agencies commanding dedicated production lines.
- Military:Procurement specifications from NATO-aligned defense agencies require AWS D17.1 aerospace welding qualifications and electromagnetic resilience testing that constrain qualified supplier pools.
- Public Safety Agencies:FirstNet coverage requirements and interoperable communications mandates in the United States accelerate mast procurement for disaster-response coordination.
- Telecommunications Providers:Mature replacement-driven purchasing patterns dominate, though German and UK operators increasingly favor service-based contracts over equipment ownership.
- Event Organizers:Cost-sensitive temporary deployments favor manual and rental-fleet masts with minimal customization requirements.
Telecommunications providers hold installed capacity in legacy tower infrastructure. Military end users are rotating up the share rankings in specification-driven procurement.
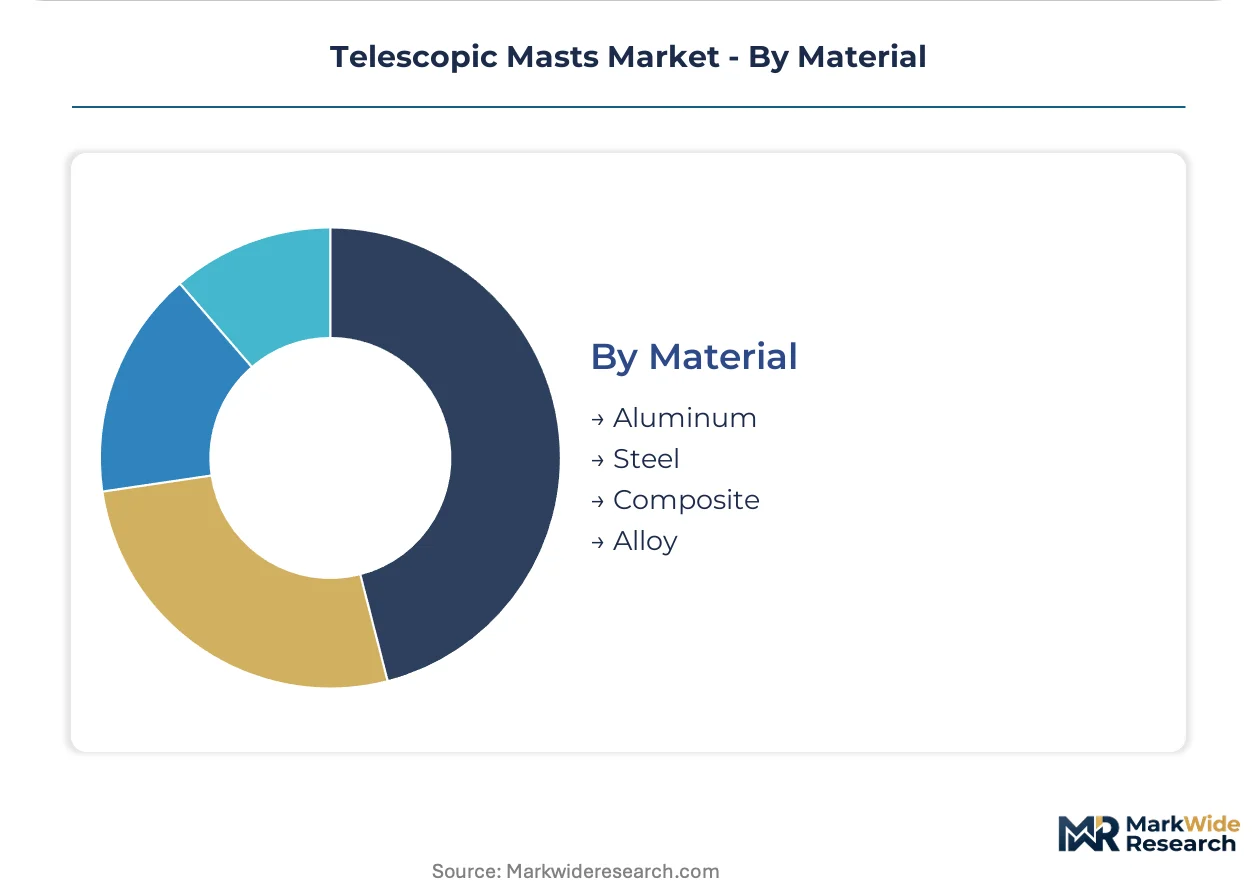
Material:
Weight-corrosion tradeoffs and carbon-border exposure redirect sourcing strategies across maritime, mobile, and fixed installations.
- Composite:Carbon-fiber-reinforced polymer segments capture premium positioning in naval and coastal applications where salt corrosion degrades aluminum within 36 months. CFRP reduces topside weight by 40-60 percent compared with metallic alternatives.
- Aluminum:6000-series and 7000-series alloys dominate volume production for weight-sensitive mobile platforms, though China's GB standards for recycling and energy intensity are redirecting domestic production toward low-carbon grades.
- Steel:Lattice and tubular steel configurations serve fixed installations and heavy-lift applications where structural mass provides stability advantage.
- Alloy:Specialized aluminum-lithium and aluminum-scandium blends target aerospace-derived specifications for high-performance mobile platforms.
Aluminum holds installed capacity in volume production for mobile platforms. Composite materials are rotating up the share rankings in maritime and defense procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for telescopic masts tilt toward deficit positions in European defense procurement, while Chinese aluminum billet shipments face carbon-border adjustment exposure. Regional manufacturing clusters concentrate around NATO-aligned certification requirements and dual-use technology controls.
United States
Defense modernization programs and FirstNet infrastructure mandates drive procurement acceleration. The FAA coordinates height clearance protocols with FCC frequency allocations near airfields and broadcast corridors. Manufacturing activity clusters in Ohio and Midwest industrial corridors where AWS D17.1 aerospace welding certification constrains qualified supplier pools.
Germany
Telecommunications tower operators displace capital purchases with service-based contracts bundling deployment and maintenance. The EU AI Act mandates algorithmic transparency for autonomous mast-positioning systems requiring CE marking validation. Production concentrates in Baden-Württemberg and North Rhine-Westphalia where automotive-tier suppliers pivot toward defense-electronics fabrication.
China
Domestic production redirects toward low-carbon composite mast grades under GB standards for aluminum recycling and energy intensity. The dual carbon goals tighten material specifications for maritime and coastal applications. Manufacturing gravity sits in Yangtze River Delta smelting regions where primary billet sourcing exposes European fabricators to tariff volatility.
United Kingdom
Royal Navy specifications prioritize carbon-fiber-reinforced polymer mast segments for shipboard antenna installations. Outcome-based service contracts now dominate telecommunications procurement with lease agreements bundling deployment and decommissioning. Defense supply chains concentrate in South England and Scottish shipbuilding corridors.
India
Indigenous procurement preferences under the PLI scheme open channels for local assembly partnerships serving army mobile communication units. BIS standards govern structural validation for domestic defense tenders. Manufacturing activity clusters in Maharashtra and Tamil Nadu where electronics system integrators expand into tactical communications hardware.
Telescopic Masts Market Competitive Environment
Concentration sits with vertically integrated fabricators holding NATO-aligned certification tiers and electromagnetic-hardened production lines. Mid-scale specialists occupy naval and marine-environment configurations where corrosion-resistant composites command premium positioning. Strategic moves center on capacity reconfiguration for sub-90-second pneumatic deployment cycles and backward integration into aluminum billet sourcing to mitigate carbon-border exposure.
Among defense-focused specialists, Will-Burt Company and Clark Masts Systems Ltd. exemplify the vertically integrated archetype with transatlantic manufacturing footprints. Comrod Communication AS occupies a position within the integrated antenna-mast systems tier, representing specialists converging sensor payloads with structural deployment platforms. These three entities anchor the supplier landscape across NATO procurement channels and maritime certification requirements.
| Leading Market Players |
|---|
| Larsen & Toubro Limited |
| Clark Masts Systems Ltd. |
| Total Mast Solutions |
| Hilomast LLC |
| Comrod Communication AS |
| Will-Burt Company |
| Rohn Industries |
| Will-Burt Germany |
| Fireco S.r.l. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Yangtze River Delta aluminum smelting clusters shapes both supply concentration and price floors for European fabricators facing carbon-border adjustment exposure. Defense-grade pneumatic masts command premium positioning through AWS D17.1 certification requirements that constrain qualified supplier pools.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on electromagnetic-hardening certification and volume scale, with NATO-aligned defense agencies least sensitive and event organizers most price-sensitive. Cost compression in standard-grade aluminum masts is intensifying because Chinese GB standards are redirecting domestic production toward low-carbon composite alternatives.
Supply Chain Analysis
Inventory buffers for 6000-series aluminum billet and carbon-fiber prepreg extend lead times for European defense contractors. Primary supply concentrates in China, Germany, and the United States, drawing from aluminum smelting, composite fabrication, and precision welding inputs. Single-source vulnerability sits with Yangtze River Delta billet sourcing. Distribution runs through direct military procurement channels and telecommunications tower operator service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry-enabled mast service contracts are expanding faster than hardware sales as German and UK operators displace capital purchases with outcome-based lease agreements bundling deployment, maintenance, and decommissioning.
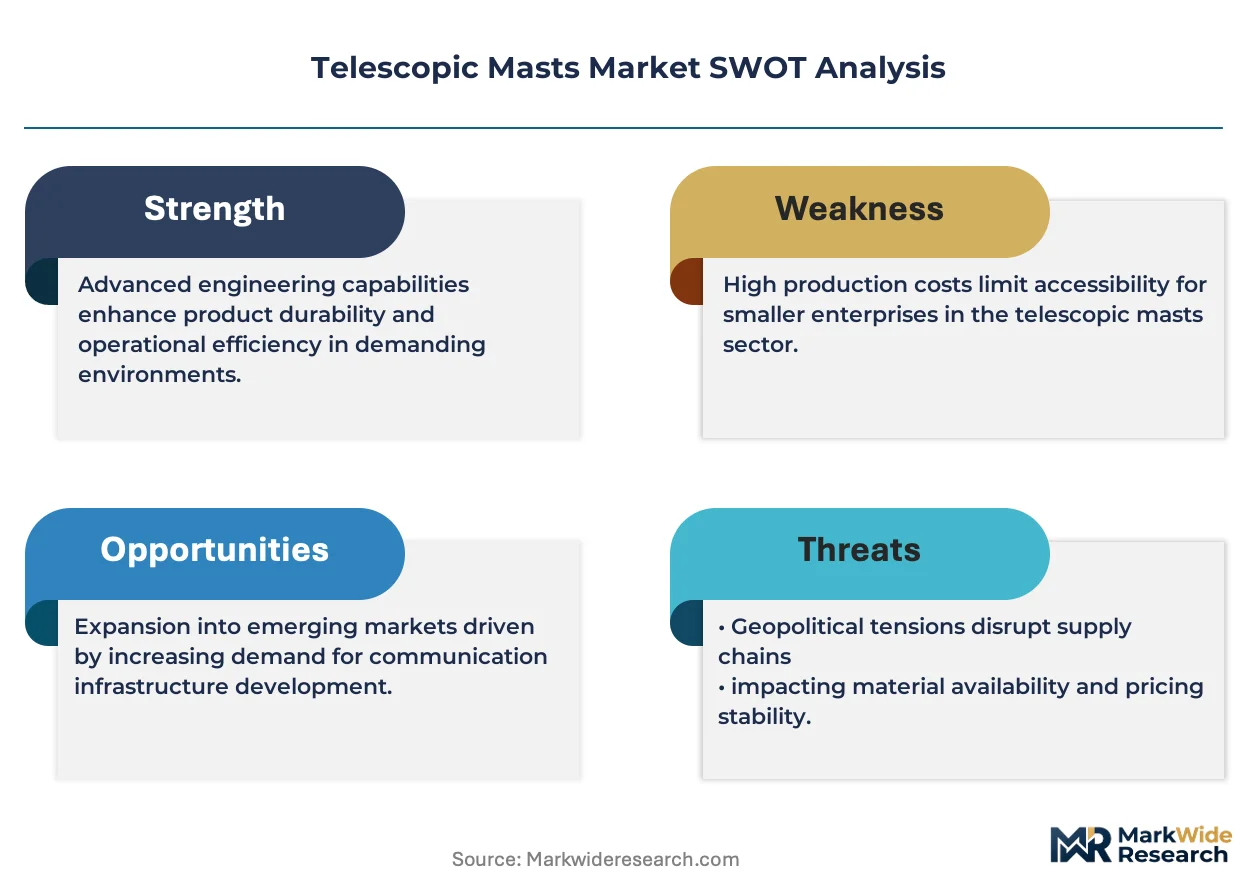
For Market Incumbents: Secure backward integration into aluminum billet sourcing to mitigate carbon-border adjustment exposure from Chinese smelting regions. Lock in AWS D17.1 welding certification capacity across Ohio and Midwest manufacturing clusters before qualified labor pools tighten further. Electric-actuation R&D investment defends against pneumatic mast substitution in NATO rapid-deployment tenders. For New Entrants and Emerging Players: Anchor in Indian army mobile communication units where PLI scheme indigenous procurement preferences create white-space for local assembly partnerships. Target maritime CFRP mast configurations where Royal Navy and US Coast Guard specifications prioritize corrosion-resistant composites over aluminum. Pursue EU AI Act compliance consulting services as a go-to-market angle for legacy European manufacturers requiring CE marking retrofit. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated antenna-mast system providers serving tactical radio networks. Long-term viability over the coming decade favors specialists converging sensor payloads with structural deployment platforms. Watch NATO interoperability standard revisions as the signal for procurement criteria hardening that would elevate electromagnetic-hardened pneumatic mast valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Billet Sourcing | Mitigates carbon-border adjustment exposure from Chinese smelting regions for European fabricators. |
| AWS D17.1 Welding Certification Investment | Expands qualified labor pools for military-grade mast fabrication in Midwest US clusters. |
| Smart-Mast Sensor Convergence Development | Captures telemetry service contract revenue from German and UK telecommunications operators. |
| EU AI Act Compliance Service Launch | Generates consulting demand for autonomous mast-positioning system CE marking validation. |
| India PLI Scheme Local Assembly Partnership | Opens channels for indigenous procurement serving army mobile communication units. |
Study Parameters
A spread of perspectives from defense procurement officers, telecommunications tower operators, aluminum fabrication plant managers, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, NATO tender databases, SEC filings from listed component suppliers, and FAA height clearance protocols. Bottom-up segment sizing and top-down macro triangulation anchored volume and value estimates.
Segmentation dimensions modeled span actuation technology, material specification, end-user archetype, and application context across the projection horizon. CAGRs derived from historical procurement cycle analysis and forward deployment schedules for NATO rapid communications infrastructure. Forecast inputs incorporated GB standards evolution for aluminum recycling and FirstNet coverage mandate implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained defense modernization budgets and stable carbon-border adjustment mechanisms; material deviation would warrant model refresh. Specific risk factors include tariff volatility on Chinese aluminum billet and FAA height clearance friction extending site-permit timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Aerotropolis Market