
 Global Green Airport Market | 2026-2036
Global Green Airport Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green Airport Market Foresight
Green project finance and long-term energy service company agreements are rewriting competitive access in airport infrastructure, allowing technology providers to compete without upfront capital burdens. Siemens AG leverages its electrification portfolio to anchor large-scale terminal retrofit programs across multiple continents. Schneider Electric SE differentiates through integrated microgrid and energy storage architectures that reduce airport reliance on grid power during peak operations.
A green airport integrates renewable energy generation, low-carbon building materials, and intelligent resource management to minimize environmental impact while maintaining aviation operational capacity. Solar photovoltaic arrays with battery storage now power passenger terminals during daylight and evening hours, while geothermal heat pumps regulate indoor climate with substantially lower emissions than conventional HVAC. LED lighting dominates technology spending due to immediate payback periods and compatibility with smart control networks, while sustainable construction applications command premium margins as cement alternatives and recycled steel gain certification traction.
The EU Green Deal and its F-Gas Regulation restrict hydrofluorocarbon use in airport cooling systems, while the EPA enforces greenhouse gas reporting thresholds for major US aviation hubs. India's Bureau of Energy Efficiency mandates energy audits for designated airports, creating compliance-driven procurement cycles. Stakeholders must monitor how tightening carbon accounting rules reshape vendor qualification criteria and long-term contract structures.
Market Dynamics
The EU F-Gas Regulation and parallel EPA greenhouse gas reporting mandates are forcing airport operators to replace hydrofluorocarbon cooling systems with low-emission alternatives, triggering synchronized procurement cycles across major aviation hubs.
Growth Catalysts
- EU Green Deal compliance deadlines:The F-Gas Regulation mandates phase-down of high-global-warming-potential refrigerants in airport HVAC systems, compelling terminal retrofits across Germany, France, and the Netherlands.
- India Bureau of Energy Efficiency audits:Mandatory energy assessments for designated airports create recurring procurement windows for LED lighting, solar photovoltaic arrays, and building automation systems.
- Geothermal heat pump maturation:Ground-source thermal systems now deliver coefficient-of-performance ratings exceeding conventional HVAC by substantial margins, accelerating adoption in new terminal construction.
Market Restraints
- Battery storage input volatility:Lithium carbonate and cobalt price fluctuations compress margins on solar-plus-storage terminal installations, deterring fixed-price contracting.
- Supply concentration in China:Dominance of Chinese photovoltaic module manufacturers exposes procurement timelines to trade policy friction and shipping bottlenecks.
- Cement alternative certification gaps:Recycled steel and geopolymer concrete lack harmonized building codes across jurisdictions, delaying sustainable construction deployment.
Strategic Opportunities
- Indonesia underpenetrated hub development:New capital airport construction and existing facility expansion create first-mover openings for integrated microgrid providers.
- Energy-as-a-service contracting:Long-term power purchase agreements and energy service company structures transfer technology risk from capital-constrained airport authorities to equipment financiers.
- Smart control network convergence:Integration of LED lighting with passenger flow sensors and predictive maintenance algorithms opens premium pricing for building management system vendors.
Industry Challenges
- Electrical grid interconnection queues:Utility approval timelines for airport solar export capacity extend 18-36 months in saturated renewable markets, delaying project commissioning.
- Legacy HVAC refrigerant recovery:Safe extraction and disposal of phased-out hydrofluorocarbons requires specialized contractor networks that remain thinly distributed outside major metropolitan zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green Airport Market |
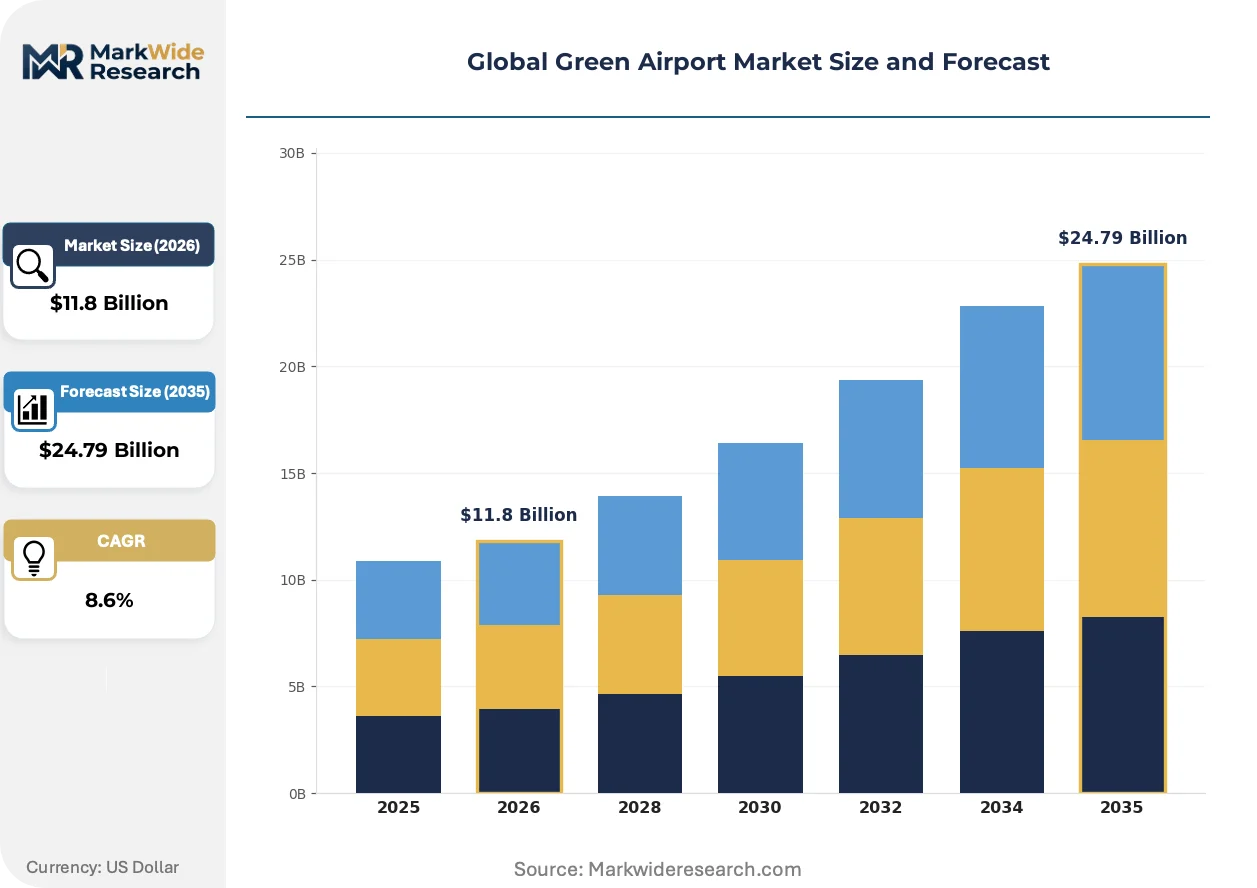
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.79 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar Power, Wind Energy, Geothermal Systems, LED Lighting, Energy Storage Application: Sustainable Construction, Carbon Emission Reduction, Waste Management, Water Conservation, Noise Abatement Facility Type: Passenger Terminals, Cargo Handling, Runways, Maintenance Hangars, Support Services End User: Airport Authorities, Ground Handling Agencies, Airline Operators, Regulatory Bodies, Facility Managers |
| Companies Covered | Honeywell International Inc., Siemens AG, ABB Group, SITA, Schneider Electric SE, Thales Group, Collins Aerospace, TKH Airport Solutions, Acciona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green Airport Market Shifts & Advancements
Terminal infrastructure is undergoing rapid instrumentation, with sensor networks and predictive algorithms replacing static building systems. This transformation compresses payback periods and redefines vendor relationships around performance guarantees rather than equipment sales.
Building-integrated photovoltaics with embedded power electronics is digitizing terminal energy management by enabling real-time load balancing and predictive generation forecasting. Major hub operators in Singapore and Dubai are deploying these systems at scale. The technology is digitizing how airports contract for power, shifting from kilowatt-hour purchases to guaranteed availability service level agreements.
The EU Corporate Sustainability Reporting Directive now mandates granular carbon disclosure from large aviation infrastructure operators. This obligation cascades through supply chains, forcing tier-two contractors to adopt certified environmental management systems. European terminal retrofit programs are accelerating vendor qualification audits to meet 2025 disclosure deadlines.
Airport authorities are unbundling energy performance from capital expenditure, preferring concession-based contracts where technology providers retain asset ownership. This procurement evolution displaces traditional equipment sales channels in India and Southeast Asia. The shift is most visible in Maharashtra and Karnataka, where state airport development corporations have standardized power purchase agreement templates for renewable terminal supply.
Global Green Airport Market Segmentation
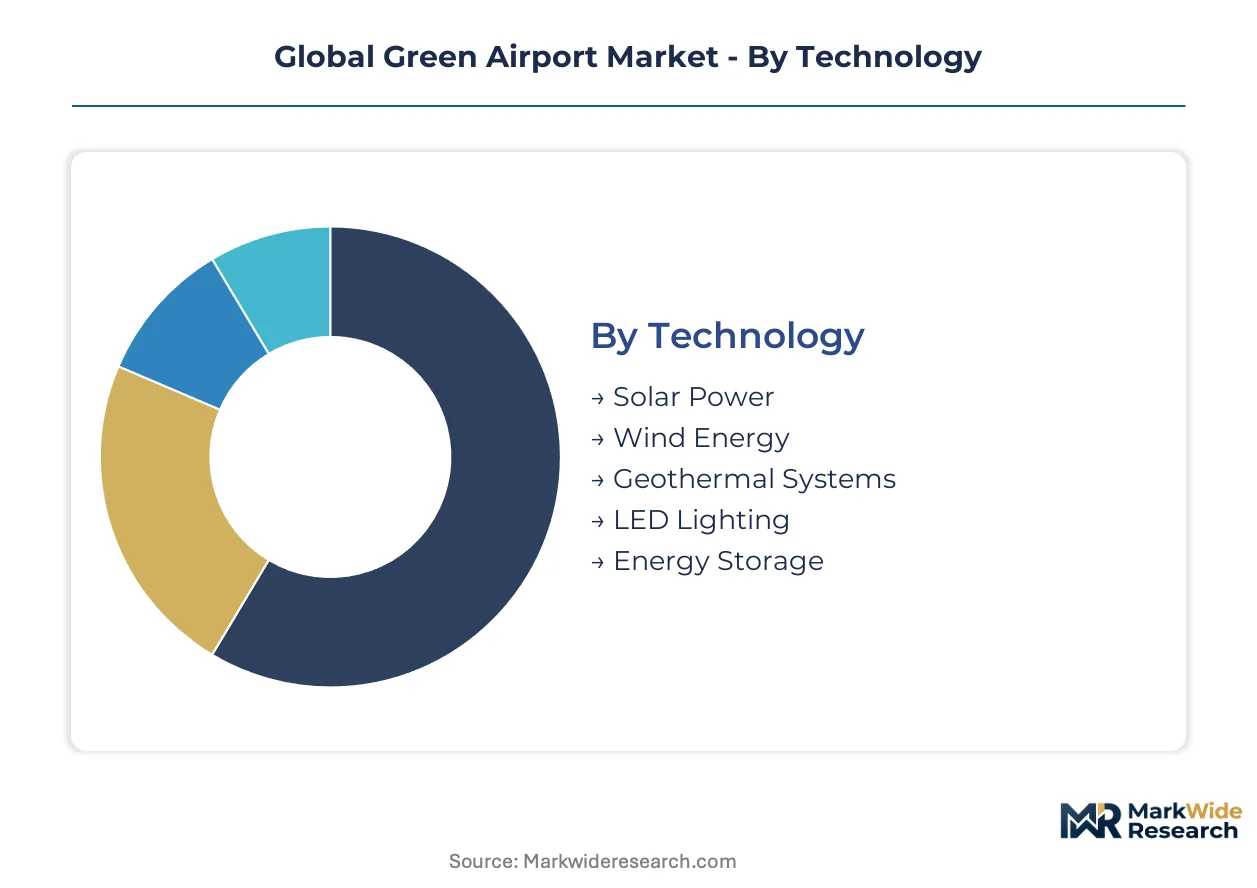
Green airport technology deployment varies sharply by infrastructure vintage and operational intensity. Segmentation reveals where capital concentrates versus where policy is forcing accelerated retrofit cycles.
Technology:
Mature electrification technologies anchor procurement volumes while emerging thermal and storage systems reshape long-term capital planning.
- Solar Power:Photovoltaic arrays with integrated inverters now dominate renewable procurement at major hubs. India's Bureau of Energy Efficiency audit mandates are accelerating rooftop and carport installations at Mumbai, Delhi, and Bangalore terminals.
- LED Lighting:Solid-state luminaires with networked controls deliver sub-two-year payback periods, making this the most deployed efficiency technology across aging terminal stock in Germany and the Netherlands.
- Energy Storage:Lithium-ion battery systems buffer solar generation for evening load matching.
- Wind Energy:Small-scale turbines supplement grid supply at coastal facilities with consistent onshore flows.
- Geothermal Systems:Ground-source heat pumps exploit stable subsurface temperatures for HVAC baseload.
LED Lighting retains volume leadership; Energy Storage holds the steepest expansion curve.
Application:
Cost tier segmentation separates compliance-driven retrofit spending from discretionary sustainability investments.
- Sustainable Construction:Low-carbon cement alternatives and recycled structural steel command premium pricing in new terminal projects. EU Green Deal procurement guidelines are mandating embodied carbon thresholds for publicly funded aviation infrastructure in France and Germany.
- Carbon Emission Reduction:Fleet electrification, ground support equipment replacement, and renewable power contracting dominate operational decarbonization budgets at major US hubs facing EPA greenhouse gas reporting thresholds.
- Waste Management:Circular material flows and organic waste digestion reduce landfill dependency.
- Water Conservation:Rainwater harvesting and greywater recycling systems address scarcity stress in arid climates.
- Noise Abatement:Acoustic barriers and operational procedures mitigate community impact.
Carbon Emission Reduction commands the largest capital allocation; Sustainable Construction is climbing fastest as new build cycles accelerate.
Facility Type:
Passenger-facing infrastructure absorbs disproportionate green investment versus airside and back-of-house assets.
- Passenger Terminals:High-visibility spaces with extended operating hours concentrate LED retrofits, solar canopies, and smart building automation. Singapore Changi and Dubai International are deploying building-integrated photovoltaics at scale.
- Cargo Handling:Refrigerated storage and material handling equipment drive electrification demand at express carrier hubs.
- Runways:LED taxiway lighting and solar-powered signage reduce grid dependency.
- Maintenance Hangars:Large roof spans suit photovoltaic installation for self-contained power supply.
- Support Services:Administrative buildings and vehicle fleets follow standard commercial efficiency pathways.
Passenger Terminals capture the dominant share of technology spending; Cargo Handling is expanding most quickly as e-commerce volumes strain legacy infrastructure.
End User:
Procurement authority fragmentation across airport ecosystems complicates vendor access and contract structuring.
- Airport Authorities:Asset owners control master planning and major capital programs, signing long-term energy service agreements that transfer technology risk to financiers. India's Airports Authority of India is standardizing power purchase agreement templates across Maharashtra and Karnataka state developments.
- Ground Handling Agencies:Third-party operators invest in electric ground support equipment where airline mandates and local air quality regulations align.
- Airline Operators:Carriers influence terminal sustainability specifications through hub lease negotiations and carbon-neutral commitments.
- Regulatory Bodies:National aviation authorities and environmental agencies set compliance thresholds that trigger procurement.
- Facility Managers:Contracted operators implement efficiency measures within operational expenditure constraints.
Airport Authorities direct the largest procurement volumes; Ground Handling Agencies are gaining influence fastest as electrification mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airport authorities in India and Germany currently drive the largest procurement volumes for renewable terminal infrastructure, with state-level mandates and federal compliance deadlines synchronizing investment cycles across multiple jurisdictions.
United States
Major hub operators face EPA greenhouse gas reporting thresholds that mandate operational decarbonization budgets. The FAA coordinates with local utilities to streamline interconnection queues for airport solar export capacity. Dallas-Fort Worth and Denver International anchor the largest terminal retrofit programs, deploying building-integrated photovoltaics at scale.
Germany
The EU F-Gas Regulation compels Frankfurt and Munich airports to replace hydrofluorocarbon cooling systems with low-emission alternatives. Federal procurement guidelines under the EU Green Deal mandate embodied carbon thresholds for publicly funded aviation infrastructure. The Rhine-Main cluster concentrates specialized contractor networks for refrigerant recovery and sustainable construction deployment.
India
The Bureau of Energy Efficiency mandates energy audits for designated airports, creating recurring procurement windows for LED lighting and solar arrays. The Airports Authority of India standardizes power purchase agreement templates across Maharashtra and Karnataka state developments. Mumbai, Delhi, and Bangalore terminals anchor the fastest rooftop and carport installation cycles.
Singapore
Changi Airport Group deploys building-integrated photovoltaics with embedded power electronics to enable real-time load balancing. The national aviation authority imposes sustainability specifications through hub lease negotiations that cascade to ground handling agencies. The Changi cluster serves as the reference architecture for premium-tier terminal energy management across Southeast Asia.
United Arab Emirates
Dubai International and Abu Dhabi International integrate microgrid architectures to reduce grid reliance during peak operations. The national renewable energy program channels concessional finance toward airport solar-plus-storage installations. The Dubai South aviation district concentrates first-mover deployments of geothermal heat pumps for HVAC baseload.
Global Green Airport Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement cycles shaped by long-term energy service agreements. The market structure tilts toward consolidated electrification portfolios rather than fragmented point solutions. Three archetypes dominate: integrated infrastructure conglomerates, building automation specialists, and renewable energy financiers. Strategic moves center on concession-based contracting structures and geographic expansion into underpenetrated hub developments.
Within the integrated infrastructure tier, Siemens AG and Schneider Electric SE exemplify channel control through electrification and microgrid architectures respectively. Honeywell International Inc. occupies a position bridging building automation with energy performance contracting. These anchors represent how technology providers now compete without upfront capital burdens by transferring risk to equipment financiers.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| ABB Group |
| SITA |
| Schneider Electric SE |
| Thales Group |
| Collins Aerospace |
| TKH Airport Solutions |
| Acciona |
| Others |
Supply & Pricing Matrix
Jiangsu Province's photovoltaic manufacturing clusters dictate downstream pricing power for airport solar-plus-storage installations, with module capacity utilization rates directly transmitting into equipment financiers' contract terms across Indian and European procurement cycles.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate solar-plus-storage terminal installations, transferring commodity volatility risk from airport authorities to energy service companies. Price differentiation rests on battery chemistry tier and microgrid integration complexity, with nickel-manganese-cobalt configurations commanding premiums over lithium-iron-phosphate alternatives. Cost compression in standard LED retrofit packages is intensifying because Chinese module oversupply is eroding contractor margins. Municipal airport authorities exhibit the highest price sensitivity, while premium hub operators in Singapore and Dubai prioritize performance guarantees over capital expenditure minimization.
Supply Chain Analysis
Export-control regimes restricting power electronics and battery management system technology limit component flows from the United States and Germany into Chinese integrator networks. Manufacturing concentrates in China, South Korea, and Vietnam for photovoltaic modules, lithium-ion cells, and LED luminaires respectively. Raw material dependencies include polysilicon, lithium carbonate, and rare-earth phosphors for solid-state lighting. Single-source vulnerability in Chinese polysilicon purification exposes procurement timelines to geopolitical friction. Distribution runs through engineering-procurement-construction contractors who bundle equipment with installation and long-term maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery mode, with EU Green Deal compliance deadlines and India's Bureau of Energy Efficiency audit mandates synchronizing procurement waves across multiple jurisdictions.
For Market Incumbents: Insulate service revenue streams from hardware margin erosion by anchoring long-term energy performance contracts with airport authorities. Deepen backward integration into battery system assembly to capture value lost to commodity volatility, while accelerating certification under the EU Corporate Sustainability Reporting Directive to disqualify uncertified competitors from European retrofit tenders.
For New Entrants and Emerging Players: Build out microgrid architecture capabilities targeting Indonesia's underpenetrated new capital airport development and existing hub expansion programs. Focus initial penetration on ground handling agency electrification mandates, where procurement authority fragmentation creates access points bypassing incumbent relationships with airport authorities. Lead with energy-as-a-service contracting to eliminate capital barriers for state airport development corporations.
For Investors and Strategic Acquirers: Long-term, this sits as a concession infrastructure play because airport authorities are systematically unbundling energy performance from capital expenditure, preferring power purchase agreement structures that generate decades of contracted cash flows. Target building automation specialists with established sensor network deployments and predictive maintenance algorithms. Watch for inflection when EU F-Gas Regulation enforcement tightens refrigerant recovery contractor qualification standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Energy-as-a-Service Contracting | Transfers technology risk from capital-constrained airport authorities to equipment financiers under long-term power purchase agreements. |
| Microgrid Architecture Integration | Reduces grid reliance during peak operations while enabling real-time load balancing through embedded power electronics. |
| Building-Integrated Photovoltaics Deployment | Digitizes terminal energy management and shifts procurement from kilowatt-hour purchases to guaranteed availability service level agreements. |
| Geothermal Heat Pump Installation | Delivers coefficient-of-performance ratings exceeding conventional HVAC for new terminal construction in the Dubai South aviation district. |
| LED Retrofit with Smart Control Networks | Compresses payback periods below two years while opening premium pricing through passenger flow sensor integration. |
Research Methodology
The analysis maps solar photovoltaic systems, energy storage architectures, LED lighting networks, geothermal HVAC systems, and building automation platforms, each validated through airport authority planning directors, energy service company project developers, renewable EPC contractors, and building management system integrators. Primary fieldwork combined structured interviews with secondary validation against Bureau of Energy Efficiency audit filings, EU Green Deal procurement guidelines, EPA greenhouse gas reporting thresholds, and airport authority capital expenditure disclosures. Bottom-up equipment shipment tracking and top-down infrastructure investment flows were triangulated to reconcile volume estimates.
Assumptions held fixed include current EU F-Gas Regulation enforcement intensity, Indian state-level renewable procurement mandates, and lithium carbonate price volatility bands observed across the analysis window. The forecast framework modeled technology deployment across passenger terminals, cargo handling facilities, and maintenance hangars, segmented by electrification maturity and regulatory compliance tier. CAGRs were derived from equipment procurement cycle analysis and policy deadline synchronization patterns, with inputs including utility interconnection queue lengths and sustainable construction certification adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese photovoltaic manufacturers to bypass trade restrictions through third-country assembly would shift outcomes. Material shifts in EU carbon border adjustment mechanisms or Indian state-level power purchase agreement standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Engineered Material Arresting System Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Passenger Boarding Bridge Market