
 Passenger Boarding Bridge Market | 2026-2036
Passenger Boarding Bridge Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Boarding Bridge Market Analysis
Low-cost carriers and ground handling companies is bifurcating procurement patterns away from legacy full-service airline specifications. CIMC Tianda Holdings Co., Ltd. dominates domestic supply chains across Chinese aviation hubs. Thyssenkrupp AG leverages its European installed base to sustain aftermarket service contracts. Mitsubishi Heavy Industries, Ltd. anchors premium positioning through precision-engineered modular systems for constrained-gate airports.
A passenger boarding bridge is a covered, elevated corridor connecting an airport terminal gate directly to an aircraft door, typically spanning 15 to 35 meters with elevation ranges of 2.5 to 6 meters to service aircraft from regional jets to A380-class superjumbos. Its primary purpose is to enable weather-protected, ADA-compliant passenger embarkation and disembarkation while reducing tarmac congestion and ground handling turnaround times. Fixed bridges command the largest installed base at major hub airports where gate assignments remain stable, while mobile bridges represent the fastest-expanding segment as remote stand operations proliferate at congested primary airports and secondary terminals lacking jet bridge infrastructure. Dual-unit configurations capture disproportionate margin pools by serving concurrent boarding on wide-body aircraft, a capability increasingly specified by ground handling companies managing mixed fleets.
FAA Advisory Circulars and EASA CS-25 airworthiness standards govern minimum door interface clearances and emergency egress requirements that directly shape bridge dimensional tolerances and sensor integration. China's GB standards and MIIT equipment certification mandate domestic content thresholds that condition market access for foreign suppliers. Stakeholders must monitor evolving airport carbon accreditation frameworks, as gate electrification and preconditioned air compatibility are becoming decisive bid-evaluation criteria independent of capital cost.
Market Dynamics
Airport gate electrification mandates and the EU F-Gas Regulation are compressing procurement cycles for legacy hydraulic-drive boarding bridges while accelerating specification of all-electric, preconditioned-air-compatible units across European and Asia-Pacific hubs.
Growth Catalysts
- EU Green Deal compliance deadlines:The F-Gas Regulation and national airport carbon accreditation frameworks are mandating lower-emission drive systems and refrigerant-free preconditioned air systems, forcing replacement of aging diesel-hydraulic bridges at major hubs.
- China's state-backed airport construction:MIIT equipment certification and GB standards sustain procurement volumes for dual-unit configurations serving wide-body fleets at Beijing Daxing, Chengdu Tianfu, and Xiamen Xiang'an expansion projects.
- Wide-body fleet expansion:Ground handling companies managing mixed A350 and B787 operations at congested primary airports are specifying high-capacity bridges with concurrent boarding capability to compress turnaround times.
Market Restraints
- Steel and aluminum input volatility:Bridge superstructure fabrication depends on structural steel and aluminum extrusion prices that fluctuate with energy costs, compressing manufacturer margins on fixed-price municipal contracts.
- Supply concentration in electromechanical actuators:Precision elevation and extension systems rely on a narrow base of European and Japanese motion-control suppliers, creating vulnerability to component lead-time extensions.
- Substitution by apron buses:Remote stand operations at budget-constrained secondary terminals favor mobile stair units and electric apron buses over capital-intensive fixed bridge installations.
Strategic Opportunities
- India's underserved tier-2 airports:The UDAN regional connectivity scheme and Greenfield airport development in Lucknow, Navi Mumbai, and Noida create demand for modular, rapid-install bridge systems with lower foundation requirements.
- Gate electrification retrofit packages:400Hz power and preconditioned air compatibility upgrades for existing bridge fleets represent recurring revenue streams distinct from new unit sales.
- Computer vision integration:Automated aircraft door alignment using lidar and machine vision is reducing operator skill requirements and enabling single-person bridge operation at labor-constrained facilities.
Industry Challenges
- Certification timeline compression:FAA Advisory Circular 150/5220-21C and EASA CS-25 interface clearance validation for new sensor-integrated bridge designs extends type-approval cycles by 12-18 months.
- Legacy system integration friction:Electrified bridge retrofits must interface with existing 50-year-old terminal building management systems and apron lighting controls without operational downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Boarding Bridge Market |
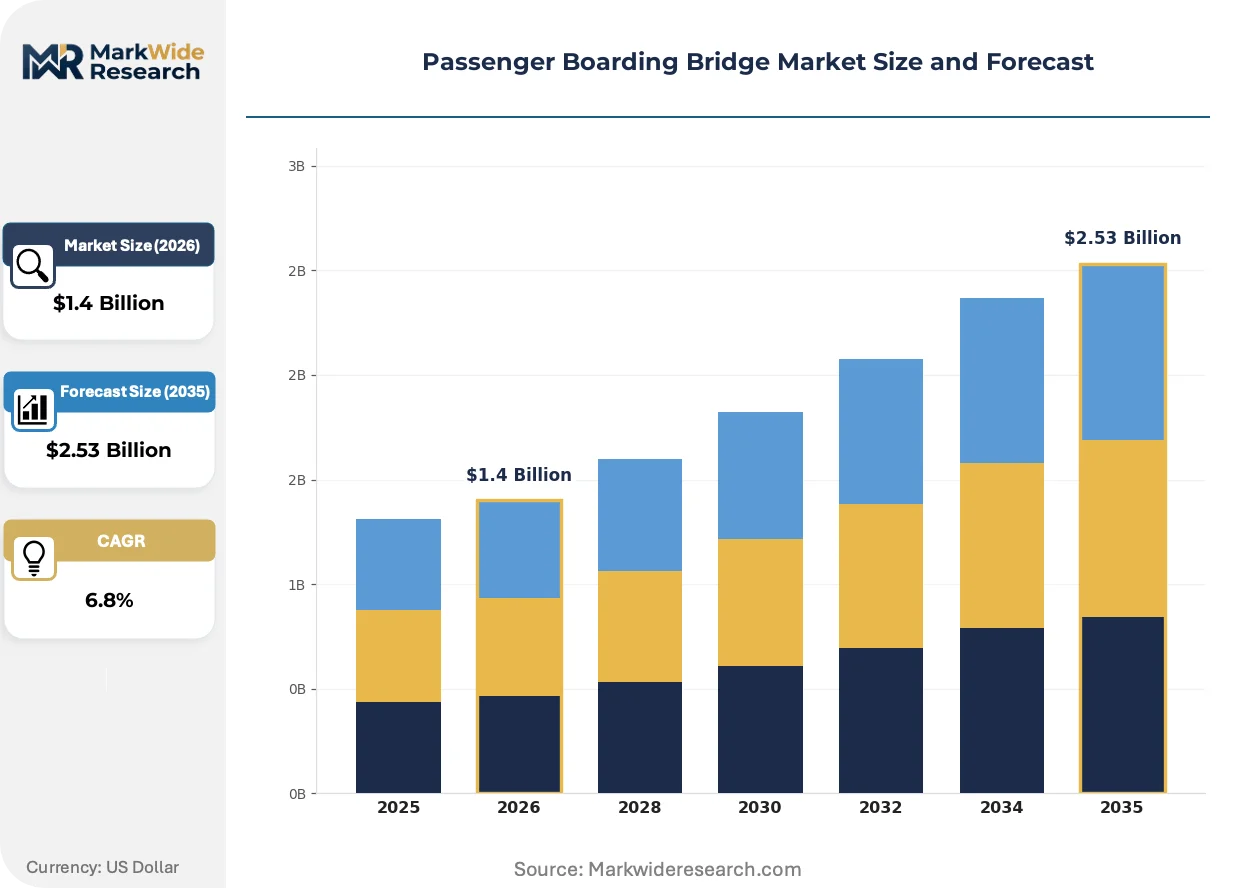
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Bridges, Mobile Bridges, Modular Bridges, RAMP Bridge Installation Type: Permanent Installation, Temporary Installation, Custom Installation, Integrated Installation Capacity: Single-Unit, Dual-Unit, Multi-Unit, High-Capacity End User: Airports, Airlines, Ground Handling Companies, Others |
| Companies Covered | ADELTE Group S.L., FMT Aircraft AB, Thyssenkrupp AG, Mitsubishi Heavy Industries, Ltd., CIMC Tianda Holdings Co., Ltd., John Bean Technologies Corp., ShinMaywa Industries, Ltd., Oshkosh Corporation, CIMC Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Boarding Bridge Market Emerging Trajectories
Electrification of drive systems and sensor-based automation are displacing hydraulic architectures and manual alignment protocols. Regulatory carbon accounting and buyer total-cost-of-ownership analysis are reshaping competitive differentiation beyond upfront capital expenditure.
Permanent-magnet synchronous motors with regenerative braking are displacing hydraulic pump-and-cylinder elevation systems in new bridge specifications. Ground handling companies at Amsterdam Schiphol and Singapore Changi have standardized all-electric units for their 2025-2030 fleet refresh programs. This transition is compressing aftermarket revenue from hydraulic seal and fluid maintenance while expanding long-term service contracts covering motor controller diagnostics and predictive bearing replacement.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing redesign of preconditioned air units integrated into bridge structures. Manufacturers serving Charles de Gaulle and Frankfurt airports have shifted to CO2-based or ambient-air cooling systems. This regulatory pressure is most acute for dual-unit wide-body bridges where PCA capacity requirements are highest, driving specification of modular, field-upgradable cooling modules.
Performance-based service agreements are replacing traditional time-and-materials maintenance contracts for bridge fleets. Airlines and ground handlers at Dubai International and Hong Kong International are contracting availability guarantees with penalties for gate-out-of-service events. This shift concentrates vendor relationships with firms capable of remote condition monitoring and 24-hour technician dispatch, disadvantaging smaller regional service providers.
Passenger Boarding Bridge Market Segmentation
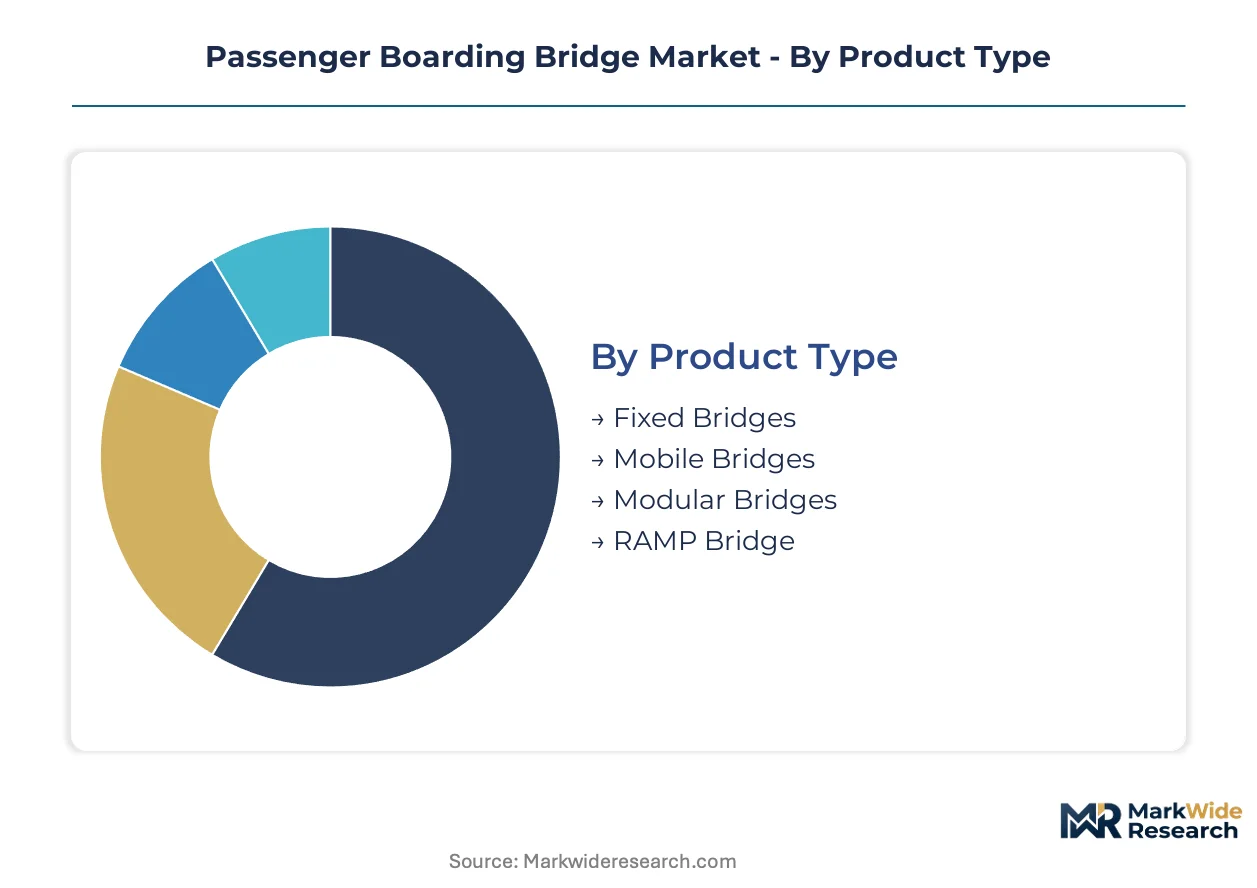
Procurement specifications for passenger boarding bridges diverge sharply across operator types and regulatory jurisdictions. Product architecture, foundation requirements, and unit capacity determine capital allocation patterns and aftermarket service potential.
Product Type:
FAA Advisory Circular 150/5220-21C and EASA CS-25 airworthiness standards impose distinct dimensional tolerances and sensor integration requirements on each bridge architecture, conditioning manufacturer design priorities and certification timelines.
- Fixed Bridges:Steel-reinforced superstructures anchored to terminal foundations dominate major hub installations at Beijing Daxing and Dubai International. Airport operators with stable gate assignments specify these for 20-year depreciation cycles despite higher upfront foundation costs.
- Mobile Bridges:Self-propelled units with independent diesel or battery-electric drive systems serve remote stands and apron overflow operations. Ground handling companies at congested primary airports deploy these where jet bridge infrastructure remains absent, though EU F-Gas Regulation compliance adds cost complexity to onboard preconditioned air systems.
- Modular Bridges:Prefabricated steel sections enable rapid deployment at India's UDAN tier-2 airports with minimal foundation work.
- RAMP Bridge:Sloped configurations accommodate regional jets and turboprops at secondary terminals lacking elevation-adjustable standard units.
Established volume favors Fixed Bridges; emerging adoption favors Mobile Bridges.
Installation Type:
Foundation engineering and terminal integration complexity separate procurement tiers, with municipal airport authorities favoring capital-efficient approaches and privatized hubs accepting higher complexity for operational optimization.
- Permanent Installation:Reinforced concrete piers and embedded utility connections serve hub airports with predictable fleet mixes. Singapore Changi and Amsterdam Schiphol specify these for 25-year service life assumptions, integrating 400Hz power and preconditioned air from initial construction.
- Temporary Installation:Ballasted foundation systems and modular utility hookups support seasonal capacity surges and construction-phase operations. Ground handling contractors at Frankfurt and Charles de Gaulle lease these during terminal refurbishment programs.
- Custom Installation:Bespoke structural adaptations address constrained gate geometries at legacy terminals.
- Integrated Installation:Building management system coupling with automated aircraft guidance.
Permanent Installation commands the largest committed capital; Temporary Installation offers the shortest payback period.
Capacity:
Turnaround time compression and wide-body fleet penetration are reshaping unit configuration demand, with concurrent boarding capability becoming a decisive specification criterion at mixed-fleet facilities.
- Dual-Unit:Independent bridge sections serving forward and aft doors simultaneously capture premium positioning at A350 and B787 operations. Ground handling companies managing mixed fleets at Hong Kong International specify these to compress turnaround times below 45 minutes.
- Single-Unit:Standard configurations for narrow-body operations dominate secondary airport procurement. China's MIIT equipment certification sustains domestic manufacturing volumes for these baseline specifications.
- Multi-Unit:Triple-bridge arrays for A380-class superjumbos.
- High-Capacity:Reinforced structures for dense all-economy layouts.
Single-Unit configurations retain the broadest installed base; Dual-Unit specifications are climbing the fastest on wide-body penetration.
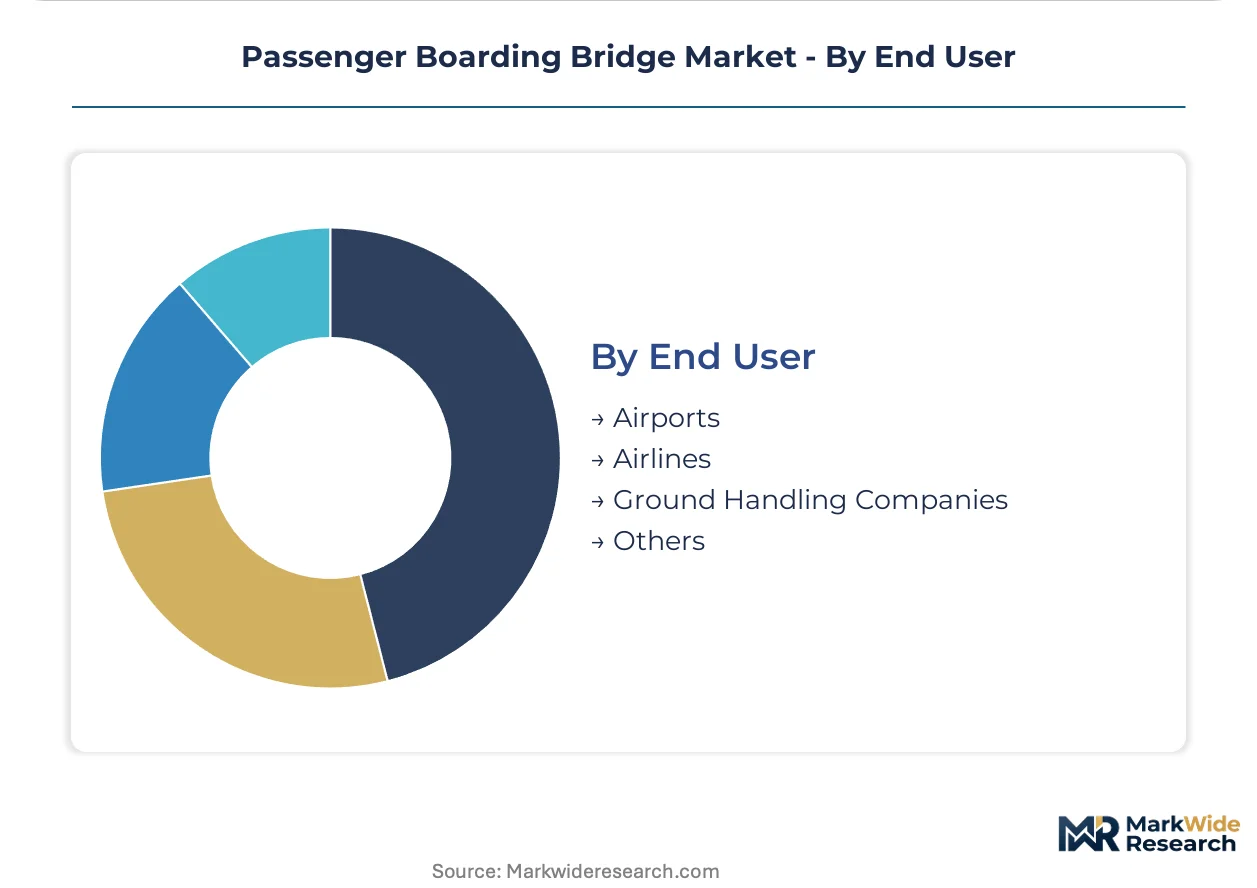
End User:
Procurement authority fragmentation between asset owners and service operators creates divergent specification priorities, with capital efficiency competing against operational flexibility in contract negotiations.
- Ground Handling Companies:Swissport and dnata standardize on mobile and dual-unit configurations to service multiple airline clients with variable fleet mixes. These operators prioritize rapid redeployment capability and 24-hour availability guarantees over terminal integration depth.
- Airports:Municipal and privatized hub operators at Chengdu Tianfu and Xiamen Xiang'an anchor procurement for fixed, permanent installations with 20-year depreciation horizons. State-backed construction programs in China concentrate demand here.
- Airlines:Legacy carriers at hub airports influence gate specifications through long-term use agreements.
- Others:Military and VIP terminal operators with specialized security protocols.
Airports commit the largest capital volumes; Ground Handling Companies are gaining share fastest on outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bridge manufacturing concentrates in China, Germany, and Japan, with each hub serving distinct procurement geographies and regulatory environments. Facility location decisions track airport construction cycles and domestic content requirements rather than pure cost optimization.
China
State-backed airport construction at Beijing Daxing, Chengdu Tianfu, and Xiamen Xiang'an sustains procurement volumes for dual-unit configurations. MIIT equipment certification and GB standards mandate domestic content thresholds that condition market access for foreign suppliers. CIMC Tianda Holdings anchors supply chains across Chinese aviation hubs, capturing recurring orders from municipal airport authorities.
Germany
EU F-Gas Regulation compliance deadlines and airport carbon accreditation frameworks accelerate replacement of aging diesel-hydraulic bridges at Frankfurt and Munich hubs. EASA CS-25 airworthiness standards govern minimum door interface clearances that shape sensor integration requirements. Thyssenkrupp AG leverages its European installed base to sustain aftermarket service contracts across Central European airports.
Japan
Precision-engineered modular systems for constrained-gate airports at Narita and Haneda drive specification of compact footprint bridges. METI industrial policy supports domestic manufacturing of electromechanical actuator systems for elevation and extension mechanisms. Mitsubishi Heavy Industries anchors premium positioning through high-reliability units serving mixed narrow-body and wide-body operations.
United States
FAA Advisory Circular 150/5220-21C governs dimensional tolerances and emergency egress requirements that directly shape bridge certification timelines. Gate electrification mandates at major hubs compress procurement cycles for legacy hydraulic-drive units. John Bean Technologies and Oshkosh Corporation serve domestic airport authorities and ground handling companies across the Southeast and Pacific Coast corridor.
India
UDAN regional connectivity scheme and Greenfield airport development in Lucknow, Navi Mumbai, and Noida create demand for modular, rapid-install bridge systems. BIS certification requirements and central government infrastructure spending condition procurement patterns at tier-2 airports. Domestic fabricators and joint ventures with European suppliers compete for municipal contracts with lower foundation requirements.
Passenger Boarding Bridge Market Vendor Landscape
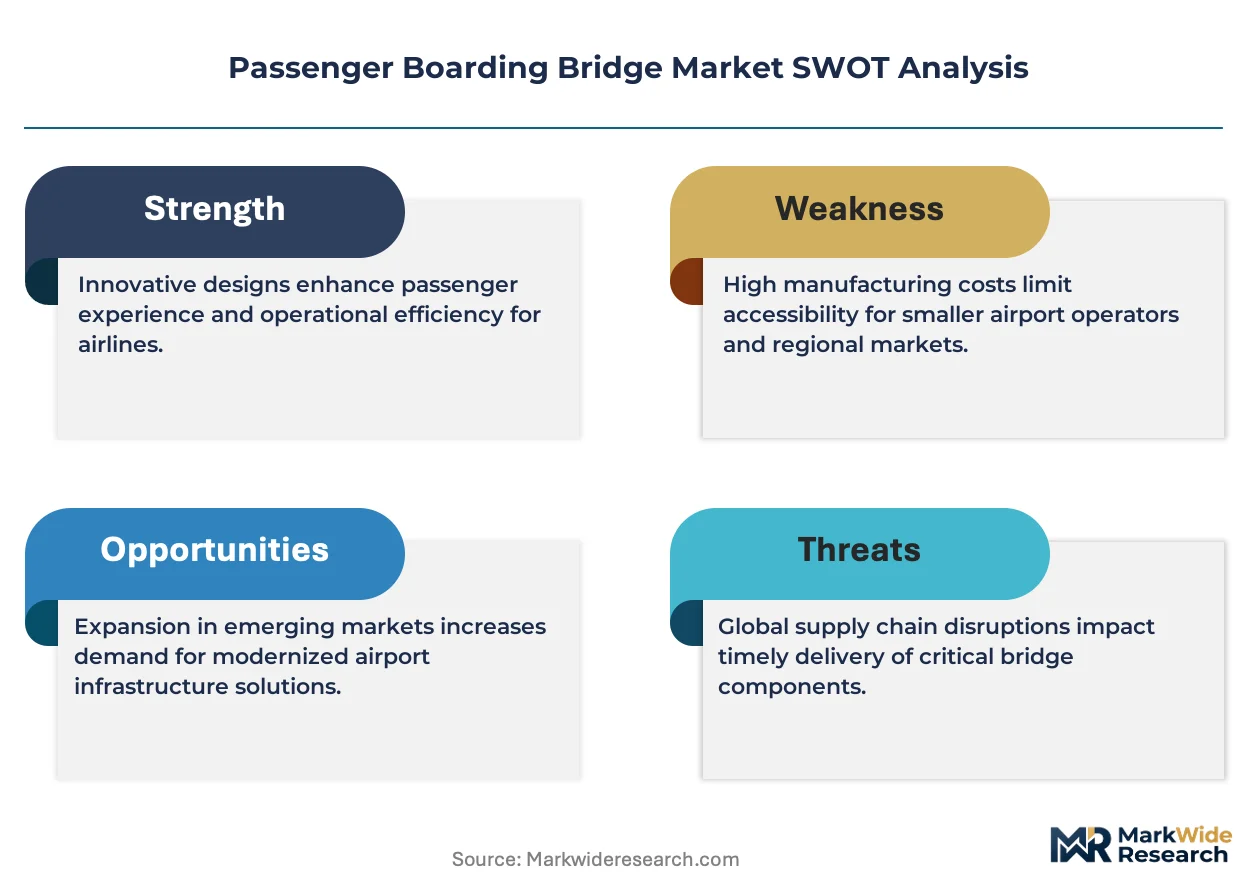
Concentration sits with diversified industrial conglomerates and specialized airport equipment fabricators rather than pure-play bridge manufacturers. The vendor base spans three tiers: integrated engineering groups with multi-industry portfolios, dedicated aviation ground support specialists, and regional metal fabrication contractors serving single-airport contracts. Strategic moves center on electrification retrofit packages and performance-based service agreements with availability guarantees.
Within the diversified industrial tier, Thyssenkrupp AG and Mitsubishi Heavy Industries occupy positions anchored by decades of installed base relationships and aftermarket service networks. Among China-dedicated suppliers, CIMC Tianda Holdings exemplifies the state-linked infrastructure equipment model, securing recurring orders through domestic content mandates and direct relationships with municipal airport authorities. These three archetypes represent distinct competitive vectors: European engineering heritage, Japanese precision manufacturing, and Chinese state-backed construction finance integration.
| Leading Market Players |
|---|
| ADELTE Group S.L. |
| FMT Aircraft AB |
| Thyssenkrupp AG |
| Mitsubishi Heavy Industries, Ltd. |
| CIMC Tianda Holdings Co., Ltd. |
| John Bean Technologies Corp. |
| ShinMaywa Industries, Ltd. |
| Oshkosh Corporation |
| CIMC Ltd. |
| Others |
Supply Flow & Price Mechanics
Scale economies in bridge superstructure fabrication concentrate procurement leverage among Chinese and German manufacturers with captive steel processing and in-house electromechanical actuator production. This concentration elevates price floors for mid-tier competitors lacking backward integration into structural steel and aluminum extrusion supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated electric bridges from hydraulic legacy units and basic mobile configurations. Price differentiation hinges on EASA CS-25 certification tier and after-sales service bundling. Cost compression in standard-tier units is intensifying because municipal airport authorities in India and Southeast Asia prioritize capital efficiency over 20-year lifecycle costing. Ground handling companies exhibit highest price sensitivity due to fleet refresh cycles tied to airline contract renewals, while privatized hub operators at Singapore Changi and Dubai International accept premium positioning for availability guarantees.
Supply Chain Analysis
Inventory strategy favors strategic stockpiling of electromechanical actuators and precision elevation systems given narrow supplier bases in Germany and Japan. Manufacturing concentrates in China, Germany, and Japan, with each hub drawing from regional steel and aluminum feedstock. Supply chain risk centers on single-source vulnerability for permanent-magnet synchronous motors and motion-control components. Distribution runs through direct terminal equipment procurement channels at major hubs and ground handling contractor leasing arrangements at secondary airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gate electrification retrofit packages and performance-based availability contracts are expanding faster than new bridge unit sales, transforming hardware vendors into recurring-revenue service platforms. This service-attach dynamic favors incumbents with installed base telemetry and 24-hour technician dispatch networks.
For Market Incumbents: Fortify aftermarket service moats by embedding predictive maintenance sensors and remote diagnostics into existing bridge fleets before electrification retrofits commoditize hardware margins. Expand captive supply of electromechanical actuators through backward integration or exclusive supplier agreements to neutralize Japanese and German component bottlenecks. Defend against mobile bridge substitution by bundling fixed-bridge installations with guaranteed availability penalties that ground handling companies cannot replicate.
For New Entrants and Emerging Players: Differentiate on rapid-install modular systems for India's UDAN tier-2 airports where foundation constraints and BIS certification complexity disadvantage established hub-focused suppliers. Target underserved secondary terminals in Vietnam, Indonesia, and Philippines with ballasted-foundation mobile bridges that bypass permanent construction timelines. Pursue joint-venture structures with domestic fabricators to satisfy MIIT equipment certification and GB standards content thresholds without greenfield manufacturing investment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrification-ready bridge portfolios over hydraulic legacy exposure given EU F-Gas Regulation compliance deadlines and FAA gate electrification mandates. Long-term viability hinges on service contract attach rates rather than unit shipment volumes. Acquisition candidates with dense installed bases at carbon-accredited European hubs offer superior recurring revenue visibility. Monitor airport carbon accreditation framework adoption rates as the inflection signal—accelerated tier upgrades at major hubs compress replacement cycles and expand retrofit addressable market.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Package Development | Captures recurring revenue from 400Hz power and preconditioned air upgrades at Frankfurt and Amsterdam Schiphol. |
| Performance-Based Service Agreement Expansion | Locks in multi-year availability contracts with dnata and Swissport through remote condition monitoring capabilities. |
| Modular Bridge System Launch | Addresses UDAN scheme demand in Lucknow and Navi Mumbai with minimal foundation engineering. |
| Computer Vision Integration Partnership | Reduces operator skill requirements at labor-constrained facilities through lidar-based door alignment. |
| Regional Fabrication Joint Venture | Satisfies MIIT domestic content mandates for Beijing Daxing and Chengdu Tianfu expansion programs. |
Methodological Framework
The analysis maps fixed, mobile, and modular bridge architectures, each validated through airport procurement directors, ground handling fleet managers, electromechanical actuator suppliers, and terminal construction engineers. Primary interviews with municipal airport authorities in China, India, and Southeast Asia were cross-referenced with secondary validation from EASA CS-25 airworthiness filings, FAA Advisory Circular documentation, MIIT equipment certification registries, and customs trade data for steel and aluminum extrusion flows. Bottom-up unit shipment estimates by airport construction phase were triangulated against top-down infrastructure spending projections across the analysis window.
Consistency checks validated volume and value outputs against independent benchmarks from airport carbon accreditation frameworks and ground handling company fleet refresh disclosures. The analytical framework modeled bridge demand across product type, installation permanence, unit capacity, and end-user procurement authority throughout the projection horizon. CAGRs were derived from infrastructure spending trajectories, wide-body fleet penetration curves, and regulatory compliance deadline clustering. Industry-specific inputs included gate electrification retrofit penetration assumptions and preconditioned air system upgrade cycles at EU F-Gas Regulation-affected hubs.
Decision-makers should treat outputs as directional under assumptions of sustained state-backed airport construction in China and progressive EU Green Deal implementation; material deviation in either would warrant model refresh. Forecasts embed assumptions regarding steel and aluminum input cost stability and electromechanical actuator supplier capacity expansion. Revision becomes warranted when apron bus substitution rates at secondary terminals or certification timeline extensions for sensor-integrated designs cross thresholds that alter replacement cycle mathematics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Aircraft Catering Vehicle Market