
 South-East Asia Aviation Infrastructure Market | 2026-2036
South-East Asia Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia Aviation Infrastructure Market Analytics
Low-cost carriers are rotating demand toward modular terminal expansions and rapid-turnaround apron designs across the region. GMR Infrastructure Limited leverages its integrated airport development model to anchor large-scale greenfield projects in the Philippines and Indonesia. AECOM competes through design-led engineering services for runway rehabilitation and airside master planning. Megawide Construction Corporation specializes in fast-track terminal construction using precast concrete systems, giving it strong positioning in the Philippines' congested primary airports.
South-East Asia aviation infrastructure encompasses the physical assets—runways, taxiways, terminals, hangars, and associated airside systems—that enable civil aircraft operations, typically engineered to ICAO Annex 14 specifications for pavement classification numbers and obstacle limitation surfaces. These assets serve commercial airlines, cargo operators, and maintenance providers by ensuring safe aircraft movement, passenger processing, and regulatory compliance across tropical climates with high rainfall and seismic exposure. Terminal infrastructure leads current investment flows as passenger volumes strain existing capacity in Jakarta, Manila, and Ho Chi Minh City. Runway and taxiway segments represent the fastest-growing category as slot-constrained airports pursue dual-runway configurations to accommodate narrow-body fleet expansion by low-cost carriers. Public investment dominates funding structures, though private participation through build-operate-transfer concessions is deepening margin pools in airport retail and ground handling ancillary revenue.
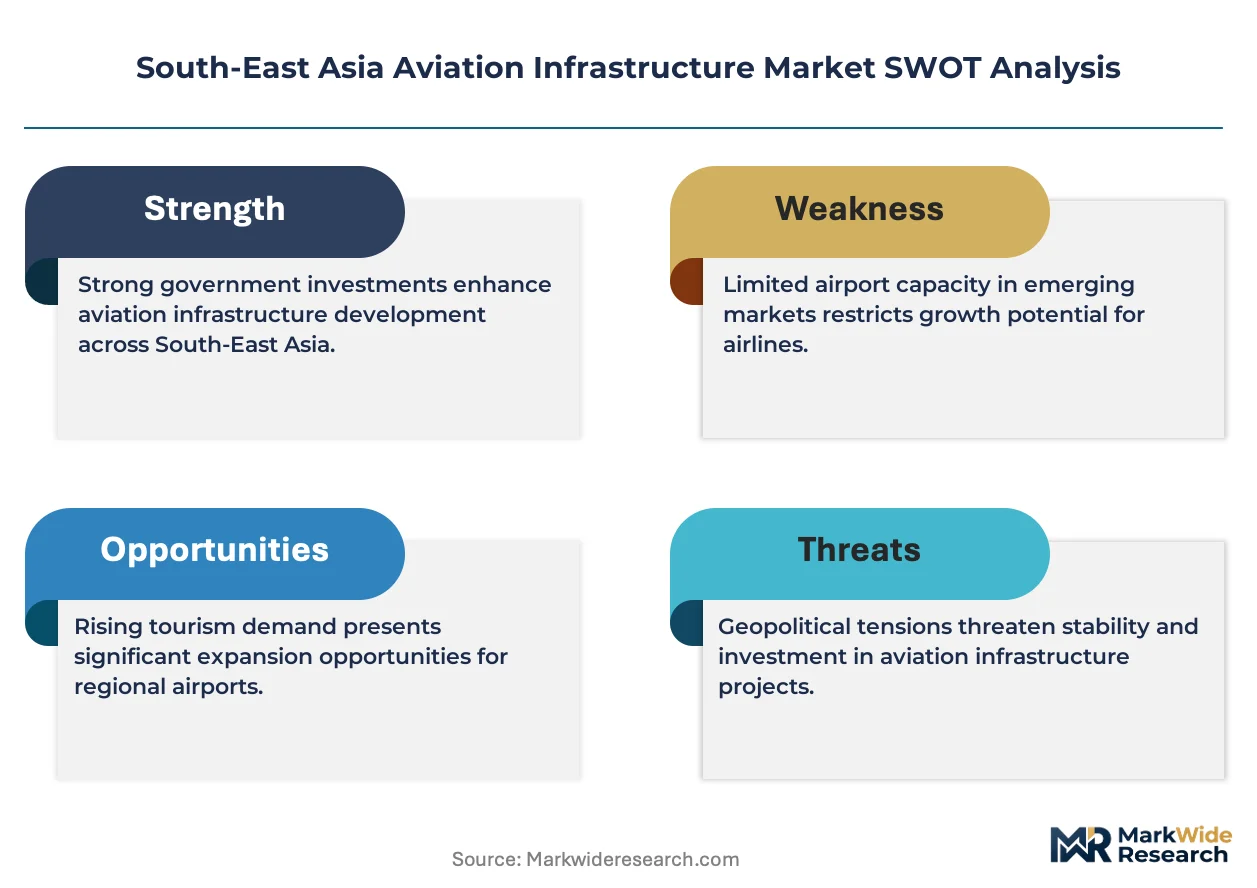
Indonesia's Directorate General of Civil Aviation, the Philippines' Civil Aviation Authority, and Thailand's Department of Air Transport enforce ICAO-aligned certification standards that dictate pavement strength, fire rescue category, and instrument landing system requirements for new airport approvals. These regulators shape demand by mandating specific runway safety area dimensions and terminal capacity thresholds that trigger capital expenditure cycles. Stakeholders must monitor how evolving ASEAN open-skies agreements and bilateral air-rights negotiations reshape route economics and therefore airport infrastructure prioritization across the region.
Market Dynamics
Slot constraints at Jakarta Soekarno-Hatta, Manila Ninoy Aquino, and Ho Chi Minh City Tan Son Nhat are forcing dual-runway expansions and rapid-turnaround apron reconfigurations across the region's primary hubs. Low-cost carrier fleet orders from Indonesia's Lion Air, Vietnam's VietJet, and the Philippines' Cebu Pacific are compressing infrastructure deployment timelines while national regulators tighten ICAO Annex 14 compliance mandates.
Growth Catalysts
- ASEAN Open Skies Protocol:Expanded fifth-freedom rights between capital cities are triggering terminal capacity upgrades at secondary hubs in Clark, Davao, and Surabaya.
- Precast concrete systems:Modular construction methods are slashing terminal build times by half, enabling fast-track expansion at congested primary airports in the Philippines and Vietnam.
- Indonesia's National Connectivity Program:Twenty-nine greenfield airport projects across the archipelago are unlocking apron and runway contracts for regional construction consortia.
Market Restraints
- Specialized asphalt polymer supply:Tropical-grade runway surfacing materials concentrate among Japanese and Korean petrochemical suppliers, exposing projects to yen-won volatility.
- Seismic engineering standards:Indonesia's location along the Pacific Ring of Fire mandates expensive ground stabilization and base isolation systems for terminal structures.
- Land acquisition fragmentation:Philippine airport expansions face extended resettlement timelines due to complex ancestral domain claims and informal settlement densities.
Strategic Opportunities
- Thailand's Eastern Economic Corridor:The U-Tapao airport megaproject and linked MRO facilities offer integrated airside-landside development scopes absent in mature hubs.
- Instrument landing system upgrades:Category III precision approach mandates for monsoon-season operations are creating retrofit demand at 40-plus Indonesian airports.
- Build-operate-transfer concessions:Philippine and Thai frameworks now permit 25-year retail and ground handling monopolies, deepening ancillary revenue pools for private operators.
Industry Challenges
- Airside safety certification timelines:ICAO Annex 14 runway safety area compliance audits average 18 months, delaying revenue service at greenfield sites.
- Legacy system integration:New terminal automation must interface with 1990s-era baggage handling and passenger processing infrastructure at Manila and Jakarta without operational shutdown.
- Geotechnical survey capacity:Indonesia's dispersed island geography strains the availability of certified soil mechanics engineers for foundation validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia Aviation Infrastructure Market |
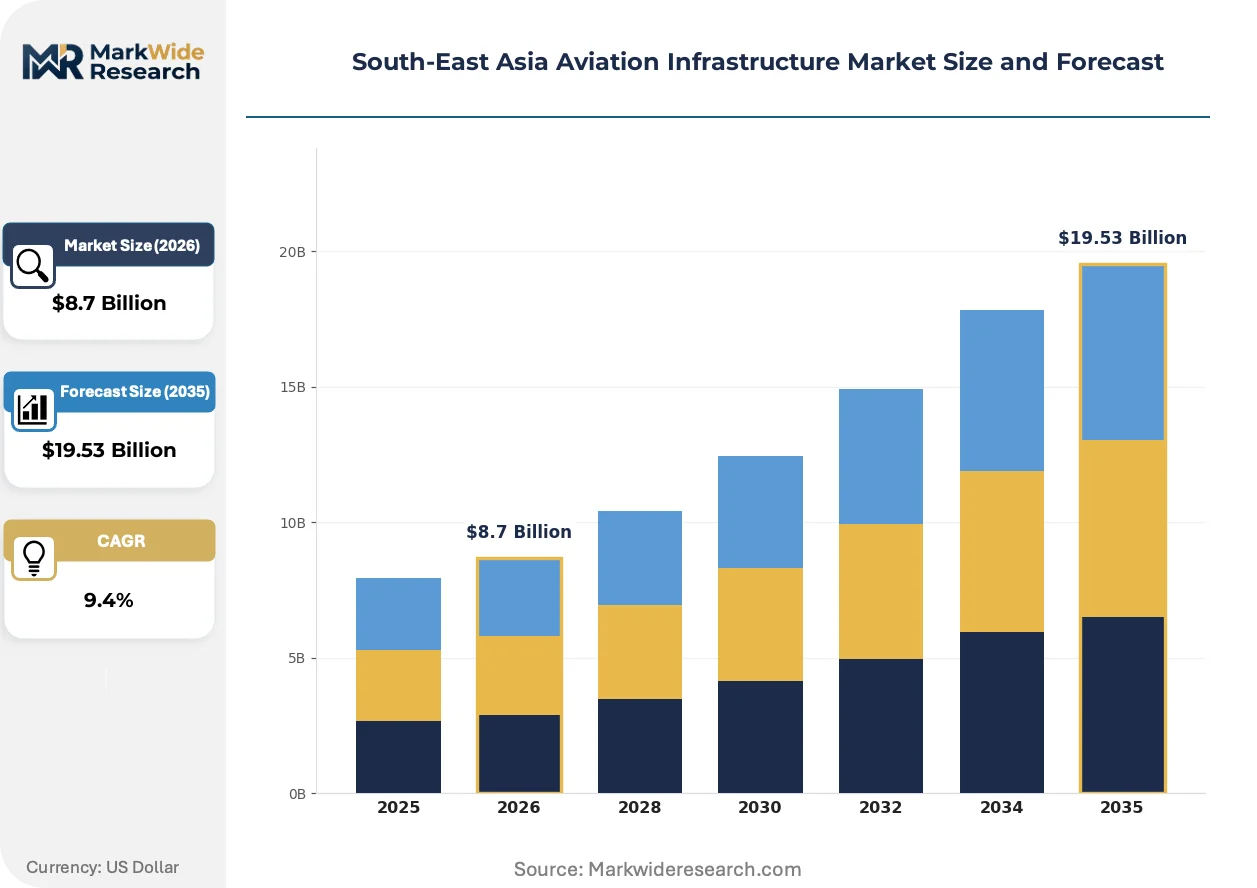
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Terminals, Runways, Taxiways, Hangars End User: Airlines, Ground Handlers, Airports, Maintenance Providers Funding Source: Public Investment, Private Investment, Government Grants, International Loans Construction Material: Steel, Concrete, Aluminum, Asphalt |
| Companies Covered | AECOM, GMR Infrastructure Limited, Neapoli Sdn Bhd, Mott MacDonald Group Limited, Ove Arup & Partners International Limited, Groupe ADP, JGC HOLDINGS CORPORATION, Megawide Construction Corporation, Samwoh Group of Companies, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia Aviation Infrastructure Market Evolving Landscape
Aviation infrastructure development across South-East Asia is pivoting from monolithic terminal design toward modular, rapid-deploy systems that compress construction schedules and enable phased capacity additions. Three distinct movements are reshaping how airports are engineered, regulated, and procured in the region.
Embedded runway sensor networks are miniaturizing pavement health monitoring from centralized laboratory analysis to distributed real-time telemetry. Indonesian and Vietnamese airport authorities are deploying fiber-optic strain gauges and temperature probes directly into asphalt layers during resurfacing cycles. This distributed sensing architecture is miniaturizing maintenance planning from scheduled interventions to condition-based responses, compressing runway closure windows during tropical downpour seasons.
Thailand's Department of Air Transport has aligned domestic certification with ICAO Annex 14 Volume II helicopter infrastructure standards, mandating elevated heliport designs for urban vertiport integration. The regulation forces Bangkok's secondary airport planners to reserve rooftop and pier-edge zones for future advanced air mobility operations. Real estate developers in Phuket and Chiang Mai are now pre-wiring commercial towers for electrical charging infrastructure to anticipate this vertical aviation overlay.
Airport procurement committees are unbundling design-build contracts into separate engineering, procurement, and construction management agreements to retain technical oversight. Philippine aviation authorities at the Civil Aviation Authority now require independent pavement design verification before asphalt placement, inserting specialist consultants between general contractors and material suppliers. This disaggregation is most visible at Clark International Airport's current expansion, where three distinct contracts cover master planning, airside engineering, and terminal construction to mitigate single-point delivery risk.
South-East Asia Aviation Infrastructure Market Segmentation
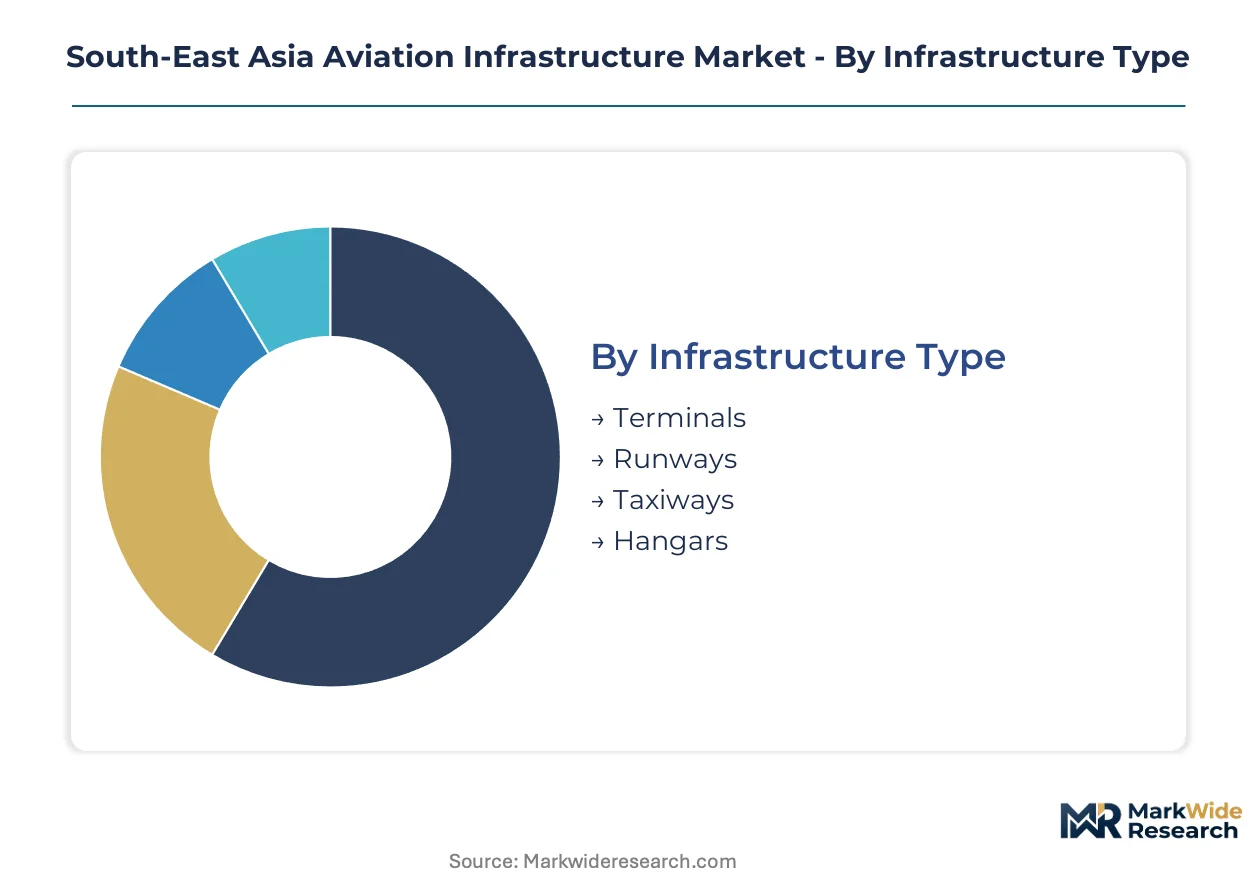
Segmentation in South-East Asia aviation infrastructure reveals how regulatory mandates, tropical climate engineering, and funding mechanisms reshape procurement patterns across Indonesia, Thailand, Vietnam, and the Philippines. Each category exposes distinct margin structures and technical barriers that determine contractor positioning and project viability.
Infrastructure Type:
Indonesia's Directorate General of Civil Aviation, the Philippines' Civil Aviation Authority, and Thailand's Department of Air Transport each enforce ICAO Annex 14 specifications that dictate dimensional and load-bearing requirements differently across asset classes, creating segmented compliance burdens.
- Terminals:Modular precast concrete systems dominate current procurement as Lion Air, VietJet, and Cebu Pacific fleet expansion strains passenger processing capacity at Jakarta Soekarno-Hatta and Manila Ninoy Aquino. Slot constraints force phased construction without operational shutdown, compressing contractor margins while accelerating deployment timelines.
- Runways:Dual-runway configurations at Ho Chi Minh City Tan Son Nhat and Surabaya Juanda require Category III instrument landing system integration and tropical-grade asphalt polymers from Japanese and Korean petrochemical suppliers. Pavement classification number upgrades trigger 18-month ICAO compliance audits that delay revenue service.
- Taxiways:Rapid-turnaround apron reconfigurations serve low-cost carrier rotation schedules.
- Hangars:Maintenance, repair, and overhaul facilities concentrate in Thailand's Eastern Economic Corridor.
Established volume favors terminals; emerging adoption favors runways.
End User:
Customer procurement authority concentrates in government-linked entities with build-operate-transfer concession rights, fragmenting decision-making across aviation authorities, military commands, and mixed-ownership airport operators.
- Airlines:Low-cost carriers drive specifications through fleet order commitments. Indonesia's Lion Air Group and Vietnam's VietJet negotiate dedicated apron positions and rapid-turnaround gate designs as contract conditions for base establishment, transferring infrastructure risk to airport developers.
- Ground Handlers:Build-operate-transfer concessions in the Philippines and Thailand now permit 25-year retail and ground handling monopolies. Swissport and dnata compete for these ancillaries by pre-committing to terminal automation upgrades that interface with 1990s-era baggage systems.
- Airports:Mixed-ownership operators balance public service obligations with commercial returns.
- Maintenance Providers:MRO clusters at Clark and U-Tapao demand integrated airside-landside development scopes.
Airlines command specification authority; ground handlers capture deepening margin pools.
Funding Source:
Cost tier differentiation separates sovereign-guaranteed projects with extended tenors from commercially financed developments requiring rapid ancillary revenue monetization.
- Public Investment:Indonesia's National Connectivity Program channels state budget allocations toward 29 greenfield airport projects across the archipelago. These developments prioritize universal service obligations over commercial returns, accepting lower passenger throughput thresholds than private finance would permit.
- Private Investment:Philippine and Thai build-operate-transfer frameworks attract GMR Infrastructure and Megawide Construction through retail and ground handling revenue rights. Private operators demand traffic guarantees and land development rights to offset construction risk.
- Government Grants:Bilateral development assistance concentrates in safety-critical instrument landing system upgrades.
- International Loans:Multilateral financing attaches procurement transparency conditions that extend vendor qualification timelines.
Public investment dominates project count; private investment deepens per-project margin extraction.
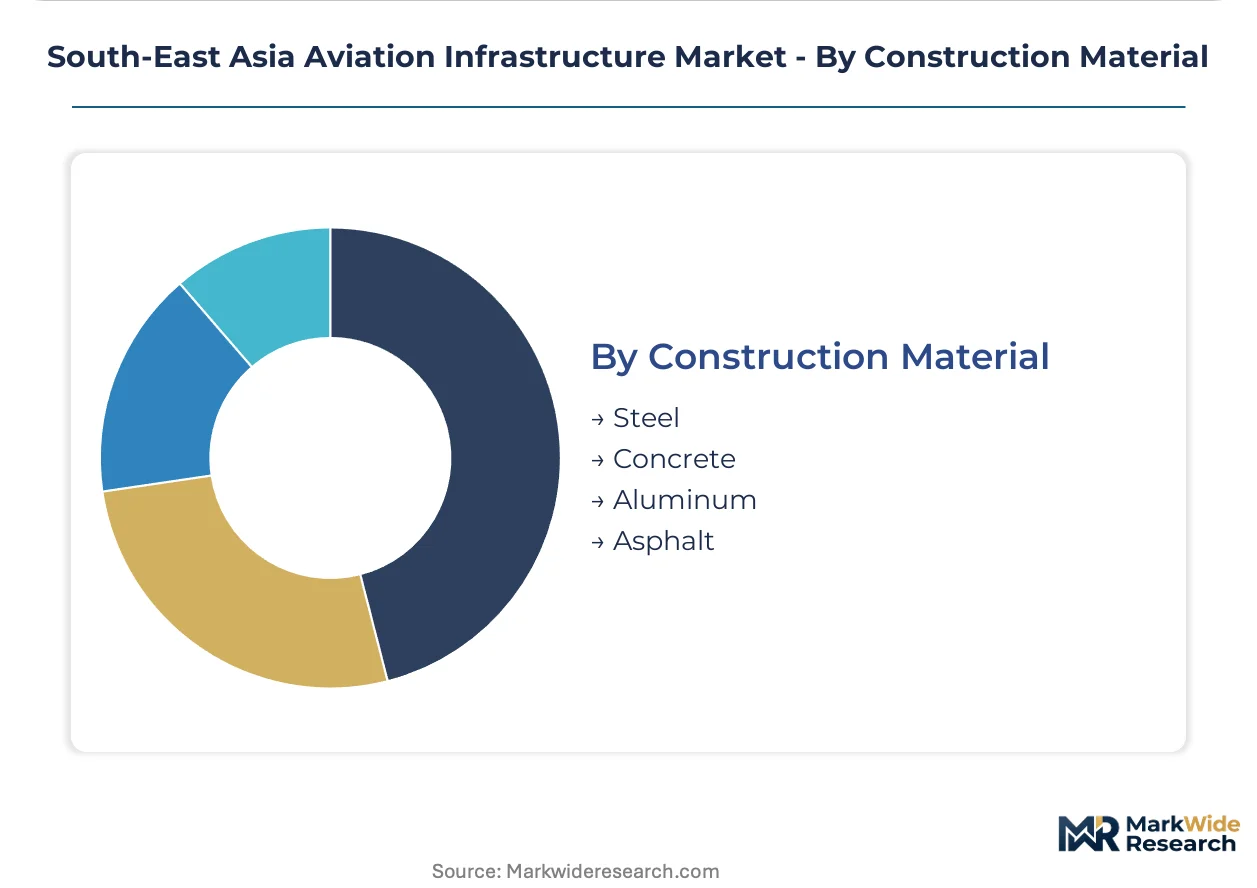
Construction Material:
Supply concentration for specialized inputs exposes projects to currency volatility and import dependency, particularly for seismic engineering and tropical climate performance specifications.
- Concrete:Precast systems from Megawide Construction and regional suppliers enable fast-track terminal construction that halves build times at Philippine primary airports. Indonesia's Pacific Ring of Fire location mandates expensive ground stabilization and base isolation systems that inflate foundation costs.
- Asphalt:Tropical-grade polymer-modified binders concentrate among Japanese and Korean petrochemical suppliers, exposing runway resurfacing contracts to yen-won exchange rate swings. Embedded fiber-optic sensor networks now integrate directly into asphalt layers for real-time pavement health monitoring.
- Steel:Structural framing for hangars and terminal roofing systems faces import dependency in Vietnam and the Philippines.
- Aluminum:Cladding and interior systems serve premium terminal fit-outs at Bangkok and Singapore-scale developments.
Concrete commands aggregate tonnage; asphalt carries the steepest specification premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soekarno-Hatta International Airport's dual-runway expansion anchors Indonesia's position as the region's largest aviation infrastructure demand center, with slot constraints forcing accelerated apron reconfigurations across Jakarta's primary hub.
Indonesia
Lion Air Group's narrow-body fleet orders and the National Connectivity Program's 29 greenfield airport projects drive procurement volumes. The Directorate General of Civil Aviation mandates ICAO Annex 14 runway safety area compliance for all new approvals. Construction concentrates in Surabaya Juanda and Makassar Sultan Hasanuddin, where dual-runway configurations accommodate low-cost carrier expansion.
Philippines
Cebu Pacific's base establishment requirements and Manila Ninoy Aquino's terminal saturation force rapid-turnaround gate designs into procurement specifications. The Civil Aviation Authority administers build-operate-transfer concessions permitting 25-year retail monopolies. Megawide Construction deploys precast concrete systems at Clark International Airport to compress build timelines without operational shutdown.
Vietnam
VietJet's fleet commitments and Ho Chi Minh City Tan Son Nhat's slot constraints trigger Category III instrument landing system retrofits. The country's aviation regulator aligns certification with ICAO precision approach standards for monsoon-season operations. Development clusters at Noi Bai International Airport in Hanoi, where apron reconfigurations serve narrow-body rotation schedules.
Thailand
The Eastern Economic Corridor's U-Tapao airport megaproject integrates airside-landside development with linked MRO facilities. The Department of Air Transport mandates elevated heliport designs aligned with ICAO Annex 14 Volume II for urban vertiport integration. Phuket and Chiang Mai commercial towers pre-wire electrical charging infrastructure for advanced air mobility overlay.
Malaysia
Kuala Lumpur International Airport's capacity expansion and secondary hub development at Kota Kinabalu sustain engineering demand. The country's civil aviation authority enforces pavement classification number upgrades for wide-body compatibility. Samwoh Group of Companies concentrates activity in Penang and Johor Bahru, where seismic engineering standards govern terminal foundation design.
South-East Asia Aviation Infrastructure Market Competitive Landscape
Concentration sits with integrated infrastructure developers and design-led engineering consultancies competing for distinct contract scopes. The market structures around three archetypes: airport concession operators pursuing ancillary revenue monetization, engineering consultancies delivering airside master planning, and fast-track construction specialists deploying modular systems. Dominant competitive moves include public-private partnership bidding for build-operate-transfer concessions and precast concrete technology licensing to compress terminal delivery schedules.
Within the integrated development tier, GMR Infrastructure Limited and Megawide Construction Corporation exemplify concession-based positioning, with the former anchoring large-scale greenfield projects and the latter specializing in rapid-deploy terminal construction. Among design-led engineering consultancies, AECOM occupies a position in runway rehabilitation and airside master planning, representing the technical oversight archetype that procurement committees increasingly insert between contractors and material suppliers.
| Leading Market Players |
|---|
| AECOM |
| GMR Infrastructure Limited |
| Neapoli Sdn Bhd |
| Mott MacDonald Group Limited |
| Ove Arup & Partners International Limited |
| Groupe ADP |
| JGC HOLDINGS CORPORATION |
| Megawide Construction Corporation |
| Samwoh Group of Companies |
| Others |
Value Network & Pricing Analysis
Build-operate-transfer concession structures in the Philippines and Thailand lock in 25-year revenue visibility for terminal developers while binding construction consortia to fixed-price delivery schedules. These long-term frameworks concentrate pricing power with mixed-ownership airport operators who capture ancillary revenue monopolies, transferring construction cost risk to private contractors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement for Indonesian greenfield airports, Philippine terminal expansions, and Thai MRO facilities. Price differentiation rests on certification grade for ICAO Annex 14 compliance and volume scale for fleet order commitments from Lion Air and VietJet. Cost compression in standard-tier concrete and asphalt contracts is intensifying because Japanese and Korean petrochemical suppliers dominate tropical-grade polymer binders. Low-cost carriers exhibit highest price sensitivity, demanding rapid-turnaround gate designs at minimum capex, while ground handling operators under 25-year concessions show lowest sensitivity due to captive revenue streams.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose Indonesian archipelago projects to cement and steel delivery delays, while specialized asphalt polymer supply concentrates in Japan and South Korea. Raw material dependencies span precast concrete systems, fiber-optic pavement sensors, and seismic base isolation components for Pacific Ring of Fire construction. Single-source vulnerability runs through tropical-grade polymer-modified binders, where yen-won volatility transmits directly into runway resurfacing contract pricing. Distribution feeds from regional construction consortia through government-linked procurement committees at Indonesia's Directorate General of Civil Aviation and the Philippines' Civil Aviation Authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South-East Asia aviation infrastructure is accelerating through ICAO Annex 14 compliance mandates and modular construction technology adoption. Regulatory alignment with international safety standards is compressing deployment timelines while opening margin pools for certified contractors.
For Market Incumbents: Shield terminal construction margins by securing exclusive precast concrete technology licensing agreements before Megawide Construction consolidates Philippine market access. Anchor position through backward integration into seismic engineering capability, as Indonesia's Pacific Ring of Fire location mandates expensive ground stabilization systems that inflate foundation costs and deter unqualified competitors. For New Entrants and Emerging Players: Differentiate on Category III instrument landing system retrofit specialization, targeting the 40-plus Indonesian airports requiring precision approach upgrades for monsoon-season operations. Penetrate Vietnam's secondary hub segment at Noi Bai International Airport, where apron reconfigurations for narrow-body rotation schedules outpace incumbent engineering consultancy capacity. Pursue direct contracting relationships with VietJet's fleet expansion team to bypass established airport authority procurement channels. For Investors and Strategic Acquirers: Fast-track construction specialists with modular deployment capability and established regulator relationships represent the priority acquisition archetype. Long-term viability hinges on positioning ahead of Indonesia's National Connectivity Program execution wave. Monitor ICAO compliance audit completion rates as the inflection signal—accelerated certification timelines indicate procurement committee confidence and contract flow velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precast Concrete Technology Licensing | Megawide Construction's modular systems halve terminal build times at Manila Ninoy Aquino without operational shutdown. |
| ICAO Annex 14 Certification Investment | Runway safety area compliance audits averaging 18 months create barrier to entry for uncertified engineering consultancies. |
| Seismic Engineering Capability Buildout | Indonesia's Pacific Ring of Fire location mandates ground stabilization systems that inflate foundation costs and deter generalist contractors. |
| Ground Handling Concession Acquisition | Philippine and Thai 25-year retail monopolies deepen ancillary revenue pools for private operators with passenger traffic guarantees. |
| Embedded Sensor Network Integration | Fiber-optic strain gauges deployed in Indonesian and Vietnamese asphalt layers enable condition-based maintenance and compress runway closure windows. |
Research Methodology
Cross-validation between primary interviews with airport procurement officers, civil aviation regulators, and construction consortium project directors anchors the qualitative findings against secondary validation from ICAO safety audit records, national infrastructure budget disclosures, and build-operate-transfer concession filings. Bottom-up project pipeline aggregation triangulates against top-down sovereign expenditure tracking across Indonesia's National Connectivity Program, Philippine Department of Transportation aviation sector allocations, and Thailand's Eastern Economic Corridor infrastructure budgets.
Sensitivity analysis around traffic growth assumptions, currency volatility exposure for yen-denominated asphalt polymer imports, and regulatory compliance timeline variations shapes the analytical framework across the projection horizon. Segmentation dimensions span infrastructure type, end-user procurement authority, funding source tier, and construction material specification grade. CAGRs derive from weighted capacity expansion schedules, fleet order delivery timelines from Lion Air and VietJet, and concession award velocity in Philippine and Thai public-private partnership frameworks.
The analysis sits within stated boundaries; outcomes outside sustained ASEAN open-skies protocol enforcement, stable bilateral air-rights negotiations, and continued low-cost carrier fleet expansion would require recalibration. Forecasts reflect documented assumptions around regulatory alignment pace, construction material import dependency, and geotechnical survey capacity availability across Indonesia's dispersed island geography. Practitioners should keep alternative scenarios live as ICAO compliance audit completion rates and greenfield airport site acquisition timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market