
 Global Commercial Airport Lighting Market | 2026-2036
Global Commercial Airport Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Airport Lighting Market Intelligence
The International Civil Aviation Organization's CORSIA framework is hardening the business case for energy-efficient airfield illumination systems. This shift creates opportunities for specialized vendors. ADB SAFEGATE leverages its end-to-end portfolio in airfield ground lighting. Honeywell International Inc. competes on integrated smart airport solutions, including lighting controls. Siemens AG positions its offerings within broader airport infrastructure and digitalization projects.
Commercial airport lighting comprises a network of specialized fixtures and control systems designed for aircraft guidance and safety on airfields. These systems must adhere to strict photometric and durability standards, such as those defined in ICAO Annex 14, to ensure pilot visibility in all weather conditions. The transition to LED technology is nearly complete, displacing legacy halogen and incandescent sources across most applications. Within product segments, high-intensity runway and approach lights command premium pricing due to their critical safety function.
Product design and market access are governed by a complex web of international and national regulations. The ICAO sets global standards, while bodies like the FAA in the United States and EASA in Europe provide regional certification and operational mandates. These regulations enforce stringent performance and reliability criteria for all airfield lighting components. Stakeholders must now navigate the integration of these lighting systems with next-generation digital air traffic management platforms.
Market Dynamics
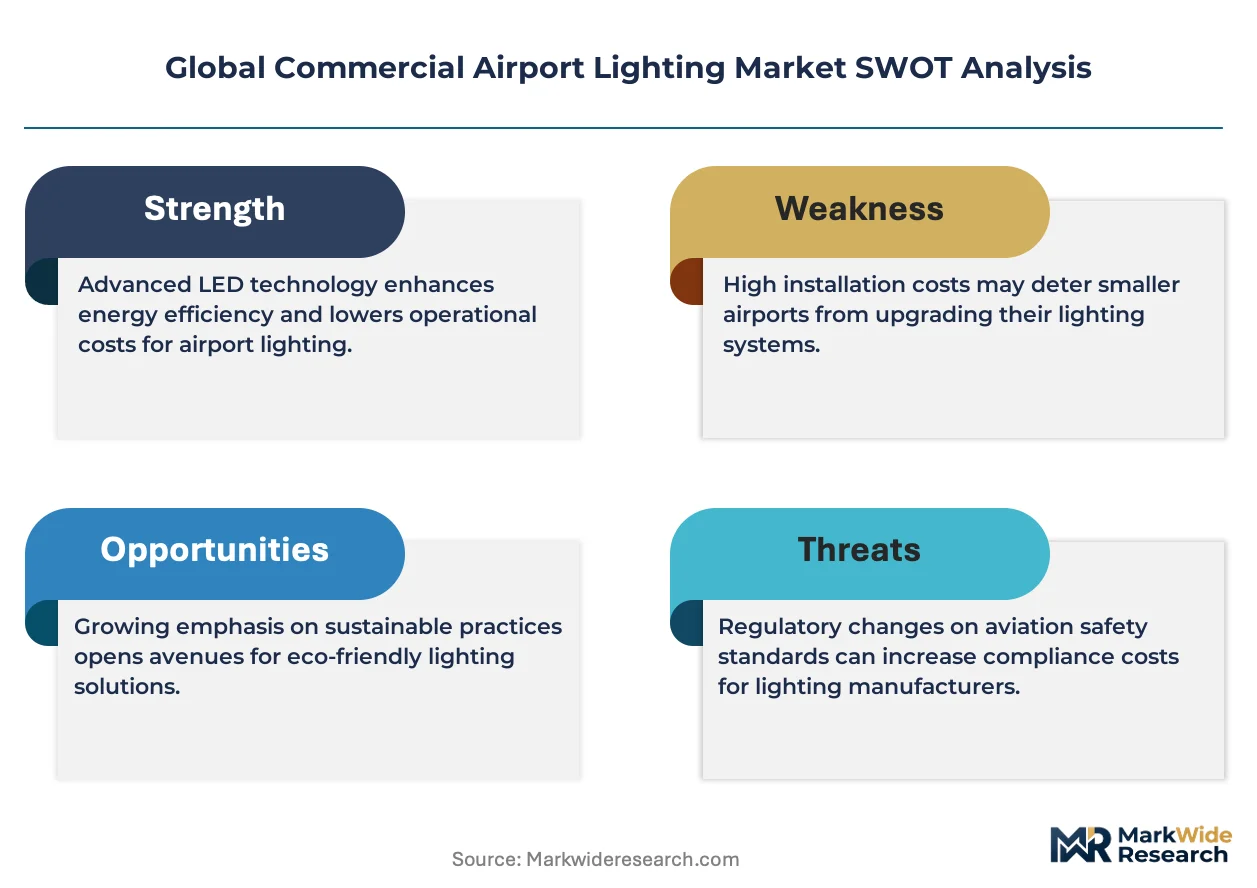
The convergence of stringent environmental regulations and the operational necessity for safer, more efficient airfields is the central force shaping the commercial airport lighting market. This dynamic compels airport authorities to invest in advanced, digitally controlled LED systems, moving beyond simple hardware replacement to full-scale infrastructure modernization.
Growth Catalysts
- Decarbonization Mandates:Frameworks like the ICAO's CORSIA initiative and national net-zero targets create a direct business case for airports to adopt energy-efficient LED lighting, reducing both operational costs and carbon emissions.
- Greenfield Airport Development:A wave of new airport construction and large-scale expansion projects, particularly in India, Saudi Arabia, and Southeast Asia, provides a captive market for complete airfield ground lighting system installations.
- Enhanced Safety and All-Weather Operations:The superior photometric performance and reliability of modern LED systems, especially for approach and runway lighting, enable lower operational minima in poor visibility, increasing airport capacity and safety.
Market Restraints
- High Capital Outlay:The significant upfront investment required for a complete airfield-wide retrofit to LED technology and associated control systems can be prohibitive for smaller or budget-constrained regional airports.
- Stringent Certification Cycles:New products must undergo lengthy and expensive certification processes by bodies like the FAA and EASA, which can slow the introduction of innovative technologies and increase costs for manufacturers.
- Legacy Infrastructure Integration:Integrating modern, networked lighting controls with aging power distribution grids and disparate air traffic management systems at older airports presents significant technical and logistical hurdles.
Strategic Opportunities
- Intelligent Airfield Systems:The convergence of lighting controls with digital air traffic management offers opportunities for "Follow the Greens" taxiing guidance, improving ground traffic flow and reducing taxi times.
- Regional Airport Modernization:A large, underpenetrated market exists within secondary airports across Africa and Latin America, which will require phased upgrades from basic halogen systems as air traffic volumes increase.
- Lighting-as-a-Service (LaaS):The development of service-based models where vendors provide guaranteed lighting performance and maintenance for a recurring fee can lower the entry barrier for airports hesitant about large capital expenditures.
Industry Challenges
- Specialized Skills Gap:A shortage of technicians possessing the dual expertise in high-voltage airfield electrical systems and the IT networking skills required to install and maintain modern digital AGL control systems.
- System Interoperability:Ensuring seamless communication and functionality between lighting systems, control platforms, and power regulators from different manufacturers remains a persistent challenge for airport operators.
- Cybersecurity Vulnerabilities:As lighting systems become networked and integrated into wider airport operations, they become potential targets for cyber-attacks, requiring robust security protocols and constant vigilance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Airport Lighting Market |
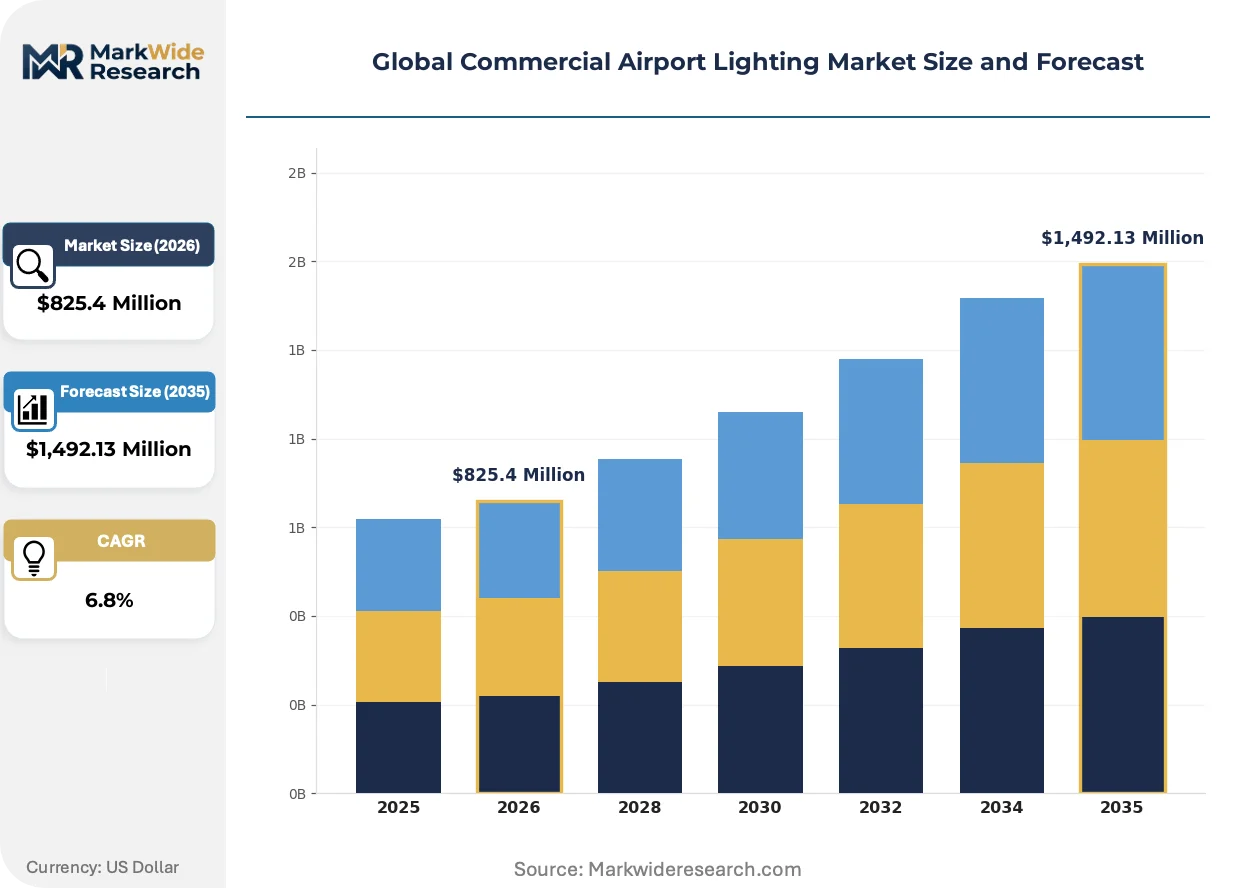
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Runway Lights, Taxiway Lights, Apron Lights, Approach Lights, Perimeter Lights Technology: LED, Halogen, Xenon, Incandescent, Solar-powered Application: Airfield Marking, Guidance System, Safety Lighting, Weather Monitoring, Emergency Signaling End User: Airport Authorities, Air Navigation Service Providers, Maintenance Contractors, Aviation Consultants |
| Companies Covered | ADB SAFEGATE, Honeywell International Inc., Eaton Corporation Plc, OCEM Airfield Technology, Astronics Corporation, Siemens AG, Signify NV, TKH Airport Solutions BV, Avlite Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Airport Lighting Market Strategic Shifts & Innovations
The evolution of airport lighting is defined by its transformation from a standalone electrical utility into an integrated, data-driven component of digital airport operations. This shift prioritizes intelligent control, system-wide efficiency, and enhanced safety through real-time monitoring and dynamic response capabilities.
Smart, Addressable Fixtures
Individually addressable LED fixtures provide granular control over every light on the airfield. Airport operators are adopting this technology primarily during major runway and taxiway upgrades to enable advanced functionalities. This capability for individual fixture monitoring and control is overtaking static, circuit-based lighting designs, allowing for dynamic routing, selective dimming, and instantaneous fault reporting.
Energy Efficiency Regulations
The EU Green Deal and its related energy performance directives are putting direct pressure on airport operators to minimize their environmental impact. This policy forces airports across the European Union to demonstrate measurable reductions in energy consumption and carbon emissions. The runway and taxiway lighting segments are most affected, prompting accelerated investment in LED retrofits to achieve compliance and improve operational efficiency.
Integrated Solution Procurement
A notable shift in purchasing behavior involves airport authorities moving away from buying discrete components toward procuring complete, turnkey airfield ground lighting solutions. This model displaces the traditional, fragmented approach where airports managed the complex integration of products from various suppliers. This trend is especially visible in large-scale greenfield airport projects across the Middle East, where single-vendor accountability for system performance is highly valued.
Global Commercial Airport Lighting Market Segmentation
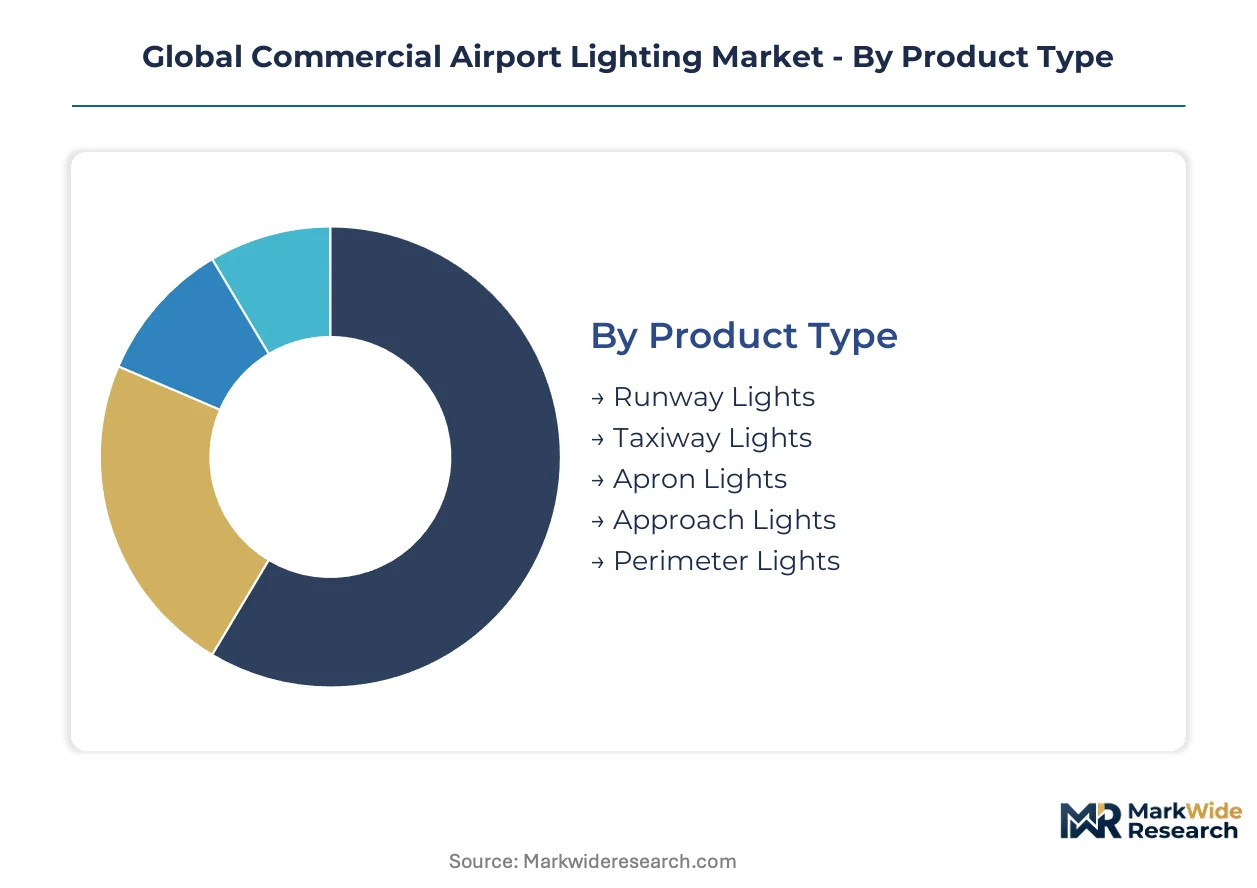
The commercial airport lighting market requires granular segmentation to understand the diverse technical requirements and procurement patterns across global airfields. Distinct product types, underlying technologies, varied applications, and specific end-user categories each present unique demand drivers and operational considerations.
Product Type:
The commercial airport lighting market differentiates product types by their critical safety function and deployment volume across airfields.
- Runway Lights:These high-intensity fixtures define the runway edges, centerline, and touchdown zones, providing crucial visual cues for aircraft during takeoff and landing. Demand concentrates at major international airports globally, driven by the operational necessity for Category III all-weather operations.
- Approach Lights:Specialized light systems extend outward from the runway threshold, guiding pilots during the final stages of landing with precise visual alignment and glide slope information. Busy airports in Europe and North America prioritize these systems to enhance safety and reduce operational minima in adverse weather.
- Taxiway Lights:Blue or green lights delineate taxiway edges and centerlines, guiding aircraft safely between runways, aprons, and gates.
- Apron Lights:Powerful floodlights illuminate aircraft parking areas, ensuring safe ground operations, maintenance, and passenger boarding.
- Perimeter Lights:These fixtures define the airport boundary and secure areas, contributing to overall facility security and regulatory compliance.
Mature deployment sits with Runway Lights. Newer deployment is concentrated in Approach Lights.
Technology:
Technology segmentation reflects the ongoing transition from legacy power sources to advanced, energy-efficient illumination solutions.
- LED:Light Emitting Diode technology offers superior energy efficiency, extended lifespan, and precise photometric performance compared to traditional sources. Global airport modernization projects, including those in Saudi Arabia, are rapidly adopting LED to meet decarbonization mandates.
- Solar-powered:These self-contained lighting units integrate photovoltaic panels and battery storage, providing autonomous illumination in areas without grid access or for temporary installations. Regional airports in Africa and remote airfields utilize solar-powered systems for cost-effective and sustainable operations.
- Halogen:An older technology, halogen lamps still exist in some legacy systems but are being steadily phased out due to lower energy efficiency and shorter lifespans.
- Xenon:Xenon strobes provide high-intensity flashes for specific applications like approach lighting, offering distinct visual cues for pilots.
- Incandescent:The oldest form of electric lighting, incandescent bulbs are largely obsolete in modern airport lighting due to high energy consumption and frequent maintenance requirements.
The LED segment is rapidly displacing older technologies across most airfield applications.
Application:
Application segments define the specific operational roles lighting systems play in ensuring safety and efficiency across airport environments.
- Guidance System:This application encompasses all lights and controls that provide visual direction for aircraft movement on the ground and during takeoff/landing. Major international airports are investing in advanced guidance systems for improved ground traffic flow and reduced taxi times.
- Safety Lighting:This broad category includes all lighting designed to enhance overall safety, such as obstacle lighting, warning lights, and emergency egress illumination. All airport types prioritize safety lighting to meet international aviation regulations like ICAO Annex 14.
- Airfield Marking:This application refers to the physical painted markings on runways and taxiways, often supplemented by embedded lighting for enhanced visibility.
- Weather Monitoring:Integrated lighting solutions can include sensors and indicators that provide pilots and air traffic control with real-time visibility and weather condition updates.
- Emergency Signaling:Specialized lighting systems activate during emergency situations, guiding rescue services and indicating critical areas.
The integration of lighting with digital air traffic management platforms enhances guidance system capabilities.
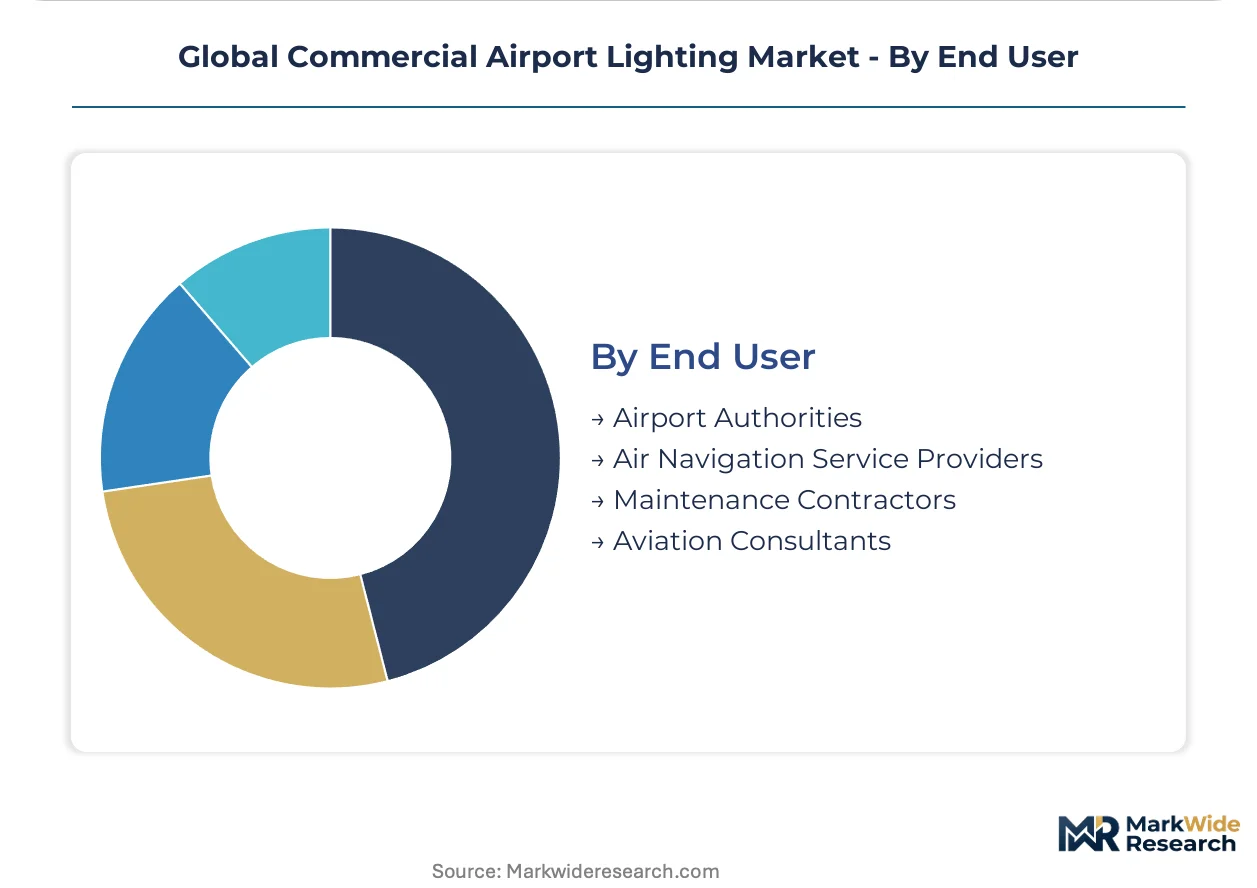
End User:
End user segmentation identifies the primary stakeholders responsible for procurement, installation, and maintenance of airport lighting infrastructure.
- Airport Authorities:These entities own and operate the airport infrastructure, making them the primary decision-makers and purchasers of lighting systems. Greenfield airport developments in India and large-scale modernization projects in Europe are driven by Airport Authorities.
- Air Navigation Service Providers:These organizations manage air traffic control and often influence the specifications and integration of airfield lighting control systems. Demand from ANSPs focuses on seamless integration with digital air traffic management platforms.
- Maintenance Contractors:Specialized firms provide ongoing service, repair, and preventive maintenance for complex airport lighting systems.
- Aviation Consultants:These professionals offer expert advice on airport planning, design, and regulatory compliance, influencing technology selection and system integration.
Airport Authorities drive capital expenditure for new installations and major system upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rapidly expanding aviation hubs in the Middle East, particularly in Saudi Arabia and the United Arab Emirates, anchor significant demand for advanced commercial airport lighting solutions. These regions are undertaking vast greenfield airport developments and modernization projects, driving substantial capital investment. Decarbonization mandates, such as the EU Green Deal, also influence technology adoption across established markets.
India
Greenfield airport development and extensive modernization programs across India generate robust demand for complete airfield ground lighting systems. The Indian government's UDAN scheme and airport expansion initiatives drive infrastructure upgrades, necessitating advanced lighting. Major aviation hubs like Delhi and Mumbai are continuously enhancing their lighting infrastructure to support increasing air traffic volumes and improve operational efficiency.
Saudi Arabia
Saudi Arabia's ambitious Vision 2030 initiatives, including new mega-airport projects like NEOM and the expansion of existing international airports, propel the adoption of cutting-edge LED lighting. The Saudi Arabian General Authority of Civil Aviation (GACA) mandates high safety and efficiency standards, fostering investment in smart airfield systems. Riyadh and Jeddah are seeing significant investment in integrated lighting solutions to support future air travel growth.
United States
The United States market sees steady investment in upgrading existing airport infrastructure, driven by the Federal Aviation Administration (FAA) regulations for airfield safety and operational efficiency. The FAA's Airport Improvement Program (AIP) provides funding for many such projects, encouraging the transition to LED technology. Major airports in New York, Atlanta, and Los Angeles are prioritizing advanced guidance systems for improved ground traffic management.
Germany
Germany's airport operators prioritize energy-efficient LED lighting systems, aligned with the EU Green Deal's stringent environmental performance directives. The German Federal Ministry of Transport and Digital Infrastructure supports sustainable aviation initiatives, influencing procurement decisions. Frankfurt Airport and Munich Airport are investing in intelligent, addressable lighting fixtures to enhance operational flexibility and reduce carbon footprints.
Global Commercial Airport Lighting Market Key Industry Players
Premium-margin players sit above commodity-margin players across the commercial airport lighting market, primarily differentiated by their ability to offer integrated, end-to-end solutions versus standalone components. The market structure exhibits a tiered consolidation, with a few global specialists offering comprehensive platforms alongside numerous regional component providers. Strategic archetypes include integrated solution providers, specialized technology innovators, and legacy system maintainers. Dominant competitive moves involve portfolio diversification into intelligent control systems and geographic expansion into emerging greenfield markets.
Within the integrated solutions segment, ADB SAFEGATE and Honeywell International Inc. exemplify companies offering extensive portfolios that cover airfield ground lighting and broader smart airport technologies. Siemens AG, a German-based conglomerate, occupies a position focused on integrating lighting solutions within larger airport infrastructure and digitalization projects. These entities often leverage their global presence and engineering capabilities to address complex airport modernization requirements, contrasting with smaller, specialized firms focusing on niche product segments or regional markets.
| Leading Market Players |
|---|
| ADB SAFEGATE |
| Honeywell International Inc. |
| Eaton Corporation Plc |
| OCEM Airfield Technology |
| Astronics Corporation |
| Siemens AG |
| Signify NV |
| TKH Airport Solutions BV |
| Avlite Systems |
| Others |
Cost & Logistics Intelligence
Expert technician availability, particularly for advanced digital airfield ground lighting systems, creates labor-cost differentials that feed into the pricing tiers for installation and maintenance services. This specialized workforce concentration impacts the overall cost structure for airports adopting modern solutions.
Pricing Analysis
Operational efficiency gains anchor the value-based pricing for advanced commercial airport lighting systems, moving beyond simple component cost. The pricing model is primarily project-based for new installations and upgrades, transitioning towards outcome-based models like Lighting-as-a-Service for maintenance. Price differentiation stems from stringent certification levels required by bodies like the FAA and EASA, alongside the brand premium associated with integrated solution providers. Pricing pressure stems from the high capital outlay for airports, yet premium pricing persists for systems enabling Category III all-weather operations. Regional airports operating with tighter budgets exhibit the highest price sensitivity, contrasting with major international hubs.
Supply Chain Analysis
Single-source vulnerability sits with highly specialized manufacturers of photometric components and integrated control units, which are critical for system performance. Geographic supply concentration for LED chips is predominantly in Asia, while advanced control systems and large fixtures often originate from Europe and North America. Raw material dependencies include specialized LED chips, optical lenses, and high-grade corrosion-resistant metals. Logistics chokepoints for large, custom airfield fixtures present a structural supply chain risk, particularly for remote project sites. Downstream distribution runs through direct sales channels to airport authorities and specialized system integrators responsible for complex installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained story, with the specialized skills gap for digital airfield lighting technicians serving as a key capacity bottleneck propping up service pricing.
For Market Incumbents: Anchor existing client relationships through long-term service contracts and Lighting-as-a-Service models, ensuring consistent revenue streams. Deepen vertical integration into specialized component manufacturing to mitigate supply chain risks and control intellectual property. Invest heavily in R&D for next-generation intelligent airfield systems to maintain technological leadership against emerging cybersecurity vulnerabilities. Pursue strategic geographic expansion into greenfield markets like India and Saudi Arabia, leveraging turnkey solution capabilities.
For New Entrants and Emerging Players: Specialized aviation consultants represent a crucial channel partner type for market entry, offering expertise in navigating complex regulatory landscapes. Target regional airport modernization projects across Africa and Latin America, where underpenetration of advanced LED systems is significant. Focus on niche solutions, such as solar-powered temporary lighting or specialized emergency signaling systems, to gain initial traction. A go-to-market angle centered on flexible financing and LaaS models can lower the entry barrier for budget-constrained airports.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate fragmented capabilities in integrated control systems. Long-term viability is strong, driven by a decade of global airport infrastructure modernization and decarbonization mandates. Identify acquisition targets that are vertically integrated mid-cap specialists in LED control systems or regional integrators with strong local implementation capabilities. A key signal to watch for inflection is the accelerated adoption of digital air traffic management platforms, driving demand for integrated lighting solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Intelligent Airfield Systems R&D | Enhances guidance system capabilities for major international airports, improving ground traffic flow. |
| Expand Lighting-as-a-Service (LaaS) Offerings | Lowers entry barriers for budget-constrained regional airports, securing recurring revenue streams. |
| Pursue Greenfield Market Entry in India and Saudi Arabia | Captures demand from new airport construction projects driven by government initiatives like Vision 2030. |
| Deepen Integration with Digital Air Traffic Management | Creates seamless communication between lighting systems and control platforms for enhanced safety and efficiency. |
| Focus on Energy-Efficient LED Retrofits in Europe | Helps European airport operators comply with EU Green Deal decarbonization mandates and reduce operational costs. |
Research Approach
Document review covered ICAO Annex 14, FAA and EASA regulatory documents, and civil aviation authority reports, complemented by interviews with industry stakeholders. Primary research involved discussions with Airport Authorities, Air Navigation Service Providers, Maintenance Contractors, and Aviation Consultants. This approach ensured a comprehensive understanding of market dynamics, triangulating insights from both bottom-up and top-down perspectives.
Historical market performance was cross-referenced with expert panel input to construct the forecast framework. The analytical framework considers market evolution across the analysis window, segmenting by product type, technology, application, end-user, and regional market maturity. Compound Annual Growth Rates (CAGRs) were derived from historical trends, validated against future airport development project pipelines and government decarbonization targets. Key forecast inputs included new airport construction timelines and regulatory compliance schedules.
Caveats apply where geopolitical instability affecting airport construction, unforeseen technological breakthroughs, or significant shifts in global aviation regulations could materially shift the outlook. Forecasts reflect assumptions based on current market conditions and anticipated developments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Engineered Material Arresting System Market