
 North America Aviation Infrastructure Market | 2026-2036
North America Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aviation Infrastructure Market Analytics
The gap between legacy airfield systems and digital-native infrastructure is narrowing as airports retrofit aging runways with IoT-enabled pavement monitoring and automated baggage handling. Turner Construction Company leverages its design-build expertise to capture complex terminal modernization contracts across the Sun Belt. AECOM anchors its position through integrated engineering services that span environmental permitting, structural design, and airside logistics planning. Skanska differentiates via sustainable construction protocols that reduce embodied carbon in concrete-intensive airfield projects.
North America aviation infrastructure encompasses the physical systems, electronic networks, and operational facilities that enable fixed-wing and rotary aircraft movement, including runway pavements engineered to 570,000-pound dual-tandem gear loading, precision instrument landing systems with Category IIIb minimums, and fuel farms meeting NFPA 407 standards for aviation turbine storage. Its primary purpose is sustaining safe, efficient air commerce across passenger, cargo, and emergency response missions. Construction and upgrading services command the largest share of capital deployment as aging terminals at Hartsfield-Jackson, Dallas-Fort Worth, and Toronto Pearson require phased reconstruction without operational interruption. Flight navigation systems represent the fastest-expanding technology segment as FAA mandates drive replacement of analog very high frequency omnidirectional range equipment with GPS-augmented performance-based navigation. Security systems maintain stable procurement volumes tied to TSA checkpoint expansion and perimeter intrusion detection upgrades at Category X airports.
The FAA, Transport Canada, and TSA collectively shape demand through airworthiness directives, airport improvement program funding eligibility, and security screening technology mandates that dictate capital allocation timelines. FAA NextGen implementation standards require ground infrastructure operators to install data communications systems and surface surveillance equipment, creating compliance-driven procurement cycles independent of passenger volume fluctuations. Stakeholders must monitor how bipartisan infrastructure spending prioritization shifts between greenfield capacity and rehabilitation of existing assets.
Market Dynamics
FAA NextGen mandates are compressing procurement cycles for precision approach systems as airports race to meet 2028 data communications deadlines while maintaining continuous operations at capacity-constrained hubs.
Growth Catalysts
- NextGen Compliance Deadlines:FAA mandates for GPS-augmented performance-based navigation are forcing replacement of analog VOR equipment across Category X airports, creating locked-in procurement timelines.
- Texas Hub Expansion:Greenfield developments at Dallas-Fort Worth and Houston Intercontinental are driving concentrated demand for dual-tandem runway pavements and automated baggage systems.
- IoT Pavement Monitoring:Embedded sensor networks enabling predictive maintenance of 570,000-pound rated runways are retrofitting aging airfields without operational shutdown.
Market Restraints
- Specialized Construction Labor:FAA-certified electrical systems installers and airfield concrete specialists face generational retirement gaps, constraining project velocity.
- Aviation Turbine Fuel Storage:NFPA 407-compliant fuel farm construction requires scarce stainless steel fabrication capacity and extended fire marshal approval timelines.
- Environmental Permitting:EPA wetland reviews and state-level endangered species consultations extend greenfield airport timelines by 18-36 months in Florida and California.
Strategic Opportunities
- Sustainable Concrete Protocols:Low-embodied-carbon pavement specifications are creating differentiation for contractors serving California and Washington state airport authorities.
- Urban Air Mobility Infrastructure:Vertiport electrical systems and precision approach adaptations for eVTOL operations represent nascent demand in Florida and Texas metropolitan corridors.
- Canadian Transborder Modernization:Transport Canada harmonization with FAA NextGen standards is opening integrated procurement opportunities at Toronto Pearson and Vancouver International.
Industry Challenges
- Phased Reconstruction Logistics:Maintaining 24/7 operations at Hartsfield-Jackson and Dallas-Fort Worth while demolishing and rebuilding active terminals demands complex passenger flow management.
- Legacy System Integration:Analog baggage handling and 1990s-era building management systems must interface with IoT-enabled infrastructure without triggering TSA security recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aviation Infrastructure Market |
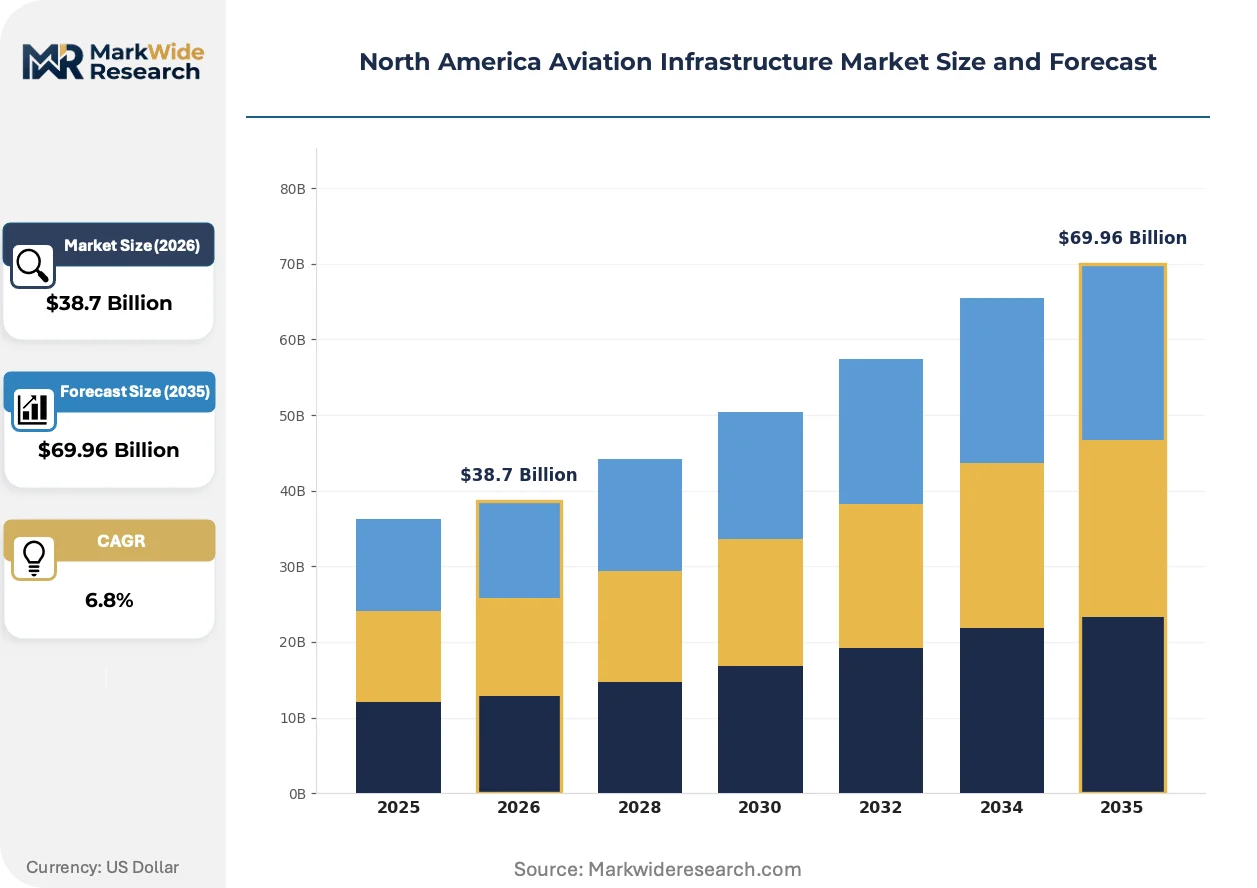
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Airports, Heliports, Maintenance Hangars, Cargo Terminals Technology: Flight Navigation Systems, Ground Handling Equipment, Security Systems, Fuel Management Solutions End User: Commercial Airlines, Private Operators, Government Agencies, Freight Companies Service Type: Maintenance Services, Construction & Upgrading, Consultancy Services, Training Programs |
| Companies Covered | Austin Industries, The Walsh Group, Hensel Phelps, J.E. Dunn Construction Company, McCarthy Building Companies, Turner Construction Company, AECOM, PCL Constructors, Skanska, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aviation Infrastructure Market Evolving Landscape
Aviation infrastructure is transitioning from reactive maintenance schedules to predictive, sensor-driven asset management as regulatory mandates and operational pressures converge on aging North American hubs.
Performance-based navigation equipment is migrating from ground-based radio beacons to satellite-dependent systems with differential GPS augmentation. Major hub airports in Texas and California are completing Category IIIb precision approach installations ahead of FAA deadlines. This technology compression is eliminating the need for extensive approach lighting systems and reducing protected airspace requirements around metropolitan airports.
Transport Canada and FAA are harmonizing data communications standards under ICAO Global Air Navigation Plan frameworks, forcing cross-border airports to procure interoperable ground infrastructure. The industrial consequence is locked-in vendor relationships as systems integrators must certify across both regulatory regimes. Toronto Pearson and Detroit Metropolitan are responding with coordinated procurement of surface surveillance equipment to maintain seamless transborder operations.
Airport authorities are consolidating vendor relationships from fragmented specialty contractors to integrated design-build partnerships for terminal modernization. The general contractor segment is displacing traditional bid-build procurement at Sun Belt hubs. This concentration is most visible in Florida, where Orlando International and Miami-Dade are awarding single-source contracts spanning structural, MEP, and security system integration.
North America Aviation Infrastructure Market Segmentation
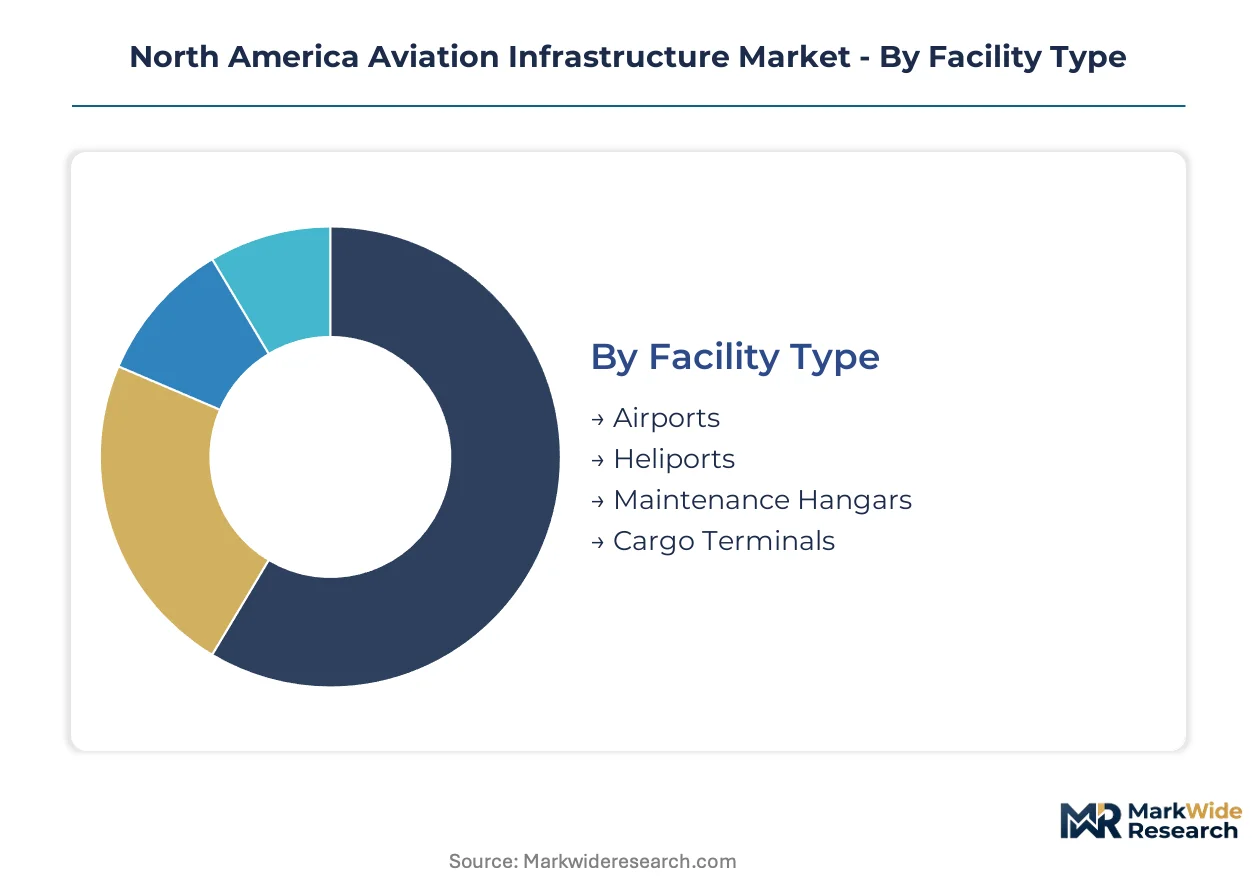
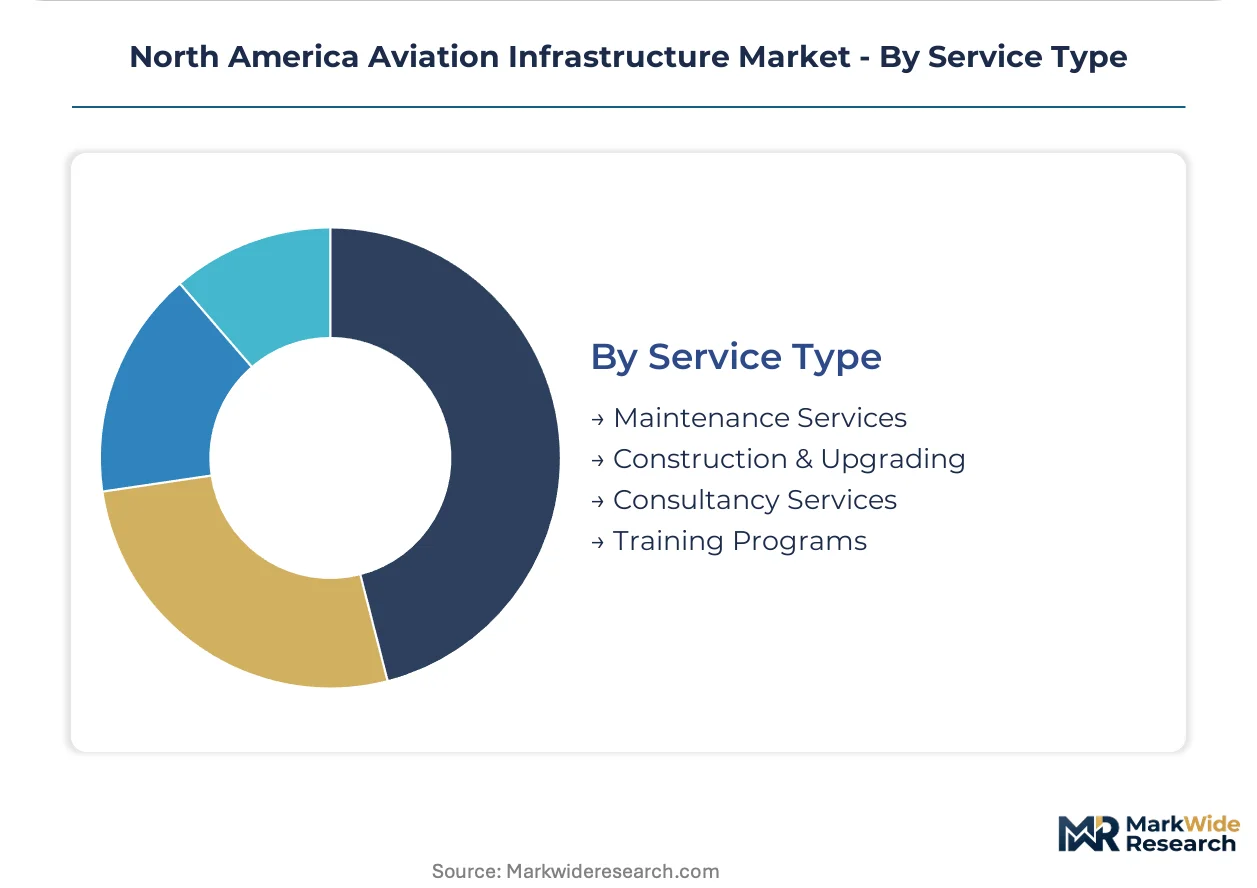
Aviation infrastructure segmentation reveals divergent procurement patterns across facility lifecycles. Construction and upgrading services demand continuous contractor engagement, while navigation and security systems operate on discrete regulatory-driven replacement cycles. Understanding these service intensity variations shapes vendor relationship strategies.
Facility Type:
After-sales-service intensity varies dramatically across facility categories, with airside infrastructure requiring perpetual pavement monitoring and terminal assets demanding phased modernization without operational interruption.
- Airports:Runway pavements engineered to 570,000-pound dual-tandem gear loading require embedded IoT sensor networks for predictive maintenance. Demand concentrates at Hartsfield-Jackson, Dallas-Fort Worth, and Toronto Pearson where phased terminal reconstruction must maintain 24/7 operations. FAA NextGen mandates for precision approach systems are compressing procurement timelines at Category X hubs.
- Cargo Terminals:Automated baggage handling and cold-chain storage infrastructure serve express freight operators and e-commerce fulfillment networks. Texas and California greenfield developments are driving concentrated demand for dual-tandem rated aprons and fuel farms meeting NFPA 407 standards.
- Maintenance Hangars:Wide-body capable structures with 150-foot clear spans and overhead crane systems support fleet modernization programs.
- Heliports:Urban vertiport electrical systems and precision approach adaptations for eVTOL operations are emerging in Florida and Texas metropolitan corridors.
Airports hold the largest share; momentum sits with cargo terminals.
Technology:
Technology segmentation tracks regulatory compliance cycles and operational criticality, with flight navigation systems commanding premium pricing for FAA-certified precision approach equipment.
- Flight Navigation Systems:GPS-augmented performance-based navigation equipment is displacing analog VOR systems at Category X airports. FAA NextGen mandates are forcing replacement timelines independent of passenger volume fluctuations, with Category IIIb precision approach installations accelerating in Texas and California ahead of compliance deadlines.
- Security Systems:TSA checkpoint expansion and perimeter intrusion detection upgrades at Category X airports maintain stable procurement volumes. Demand concentrates on integrated screening lanes and automated credential verification systems at Hartsfield-Jackson and Dallas-Fort Worth.
- Ground Handling Equipment:Electric GSE transition and automated guided vehicle systems are retrofitting aging airfields.
- Fuel Management Solutions:NFPA 407-compliant fuel farms require scarce stainless steel fabrication capacity and extended fire marshal approvals.
Flight navigation systems claim the largest technology share; security systems are expanding most quickly.
End User:
End-user segmentation reflects divergent capital allocation cycles, with commercial airlines driving fleet-linked infrastructure expansion while government agencies fund regulatory compliance mandates.
- Commercial Airlines:Fleet modernization programs at legacy carriers and ultra-low-cost operators are triggering terminal and hangar capacity upgrades. Concentrated demand at Dallas-Fort Worth, Houston Intercontinental, and Toronto Pearson reflects hub-and-spoke network expansion.
- Government Agencies:FAA, Transport Canada, and TSA capital allocations dictate security screening technology mandates and airworthiness directive compliance. Procurement cycles for precision approach systems and surface surveillance equipment operate on locked-in regulatory timelines.
- Private Operators:Fractional ownership and business aviation fleet growth is driving FBO facility modernization.
- Freight Companies:Express carriers and e-commerce logistics operators are expanding dedicated cargo terminal capacity.
Commercial airlines dominate end-user demand; government agencies provide the steadiest procurement base.
Service Type:
Service type segmentation distinguishes between discrete project-based construction and recurring maintenance revenue streams, with consultancy services bridging environmental permitting and regulatory compliance requirements.
- Construction & Upgrading:Design-build procurement is displacing traditional bid-build at Sun Belt hubs, with single-source contracts spanning structural, MEP, and security system integration. Orlando International and Miami-Dade are consolidating vendor relationships for terminal modernization.
- Maintenance Services:IoT-enabled pavement monitoring and automated baggage handling retrofits are creating recurring revenue streams. Embedded sensor networks enable predictive maintenance of 570,000-pound rated runways without operational shutdown.
- Consultancy Services:Environmental permitting and airside logistics planning extend greenfield timelines by 18-36 months in Florida and California.
- Training Programs:FAA-certified electrical systems installer programs address generational retirement gaps in specialized airfield construction labor.
Construction and upgrading commands the largest service share; maintenance services are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial airlines and government agencies anchor procurement across the region, with FAA NextGen mandates and fleet modernization programs concentrating capital deployment in Texas, California, and Florida metropolitan corridors.
United States
Texas hub expansions at Dallas-Fort Worth and Houston Intercontinental are driving dual-tandem runway pavement demand. FAA NextGen compliance deadlines for 2028 data communications are compressing procurement cycles for precision approach systems at Category X airports. California greenfield developments and terminal reconstructions concentrate contractor activity in Los Angeles and San Francisco Bay Area corridors.
Canada
Transport Canada harmonization with FAA NextGen standards is opening integrated procurement opportunities at Toronto Pearson and Vancouver International. The federal Airport Capital Assistance Program funds surface surveillance equipment upgrades at transborder facilities. Montreal and Calgary maintenance hangar expansions support Air Canada and WestJet fleet modernization programs.
Mexico
Felipe Ángeles International Airport expansion and Mexico City International capacity upgrades are attracting North American contractor partnerships. SENEAM air navigation modernization aligns with ICAO Global Air Navigation Plan frameworks. Cancún and Guadalajara cargo terminal developments serve express freight operators and e-commerce fulfillment networks.
North America Aviation Infrastructure Market Competitive Landscape
Channel-controlling players compete with product-specialist players across design-build procurement and discrete technology installation segments. The contractor base concentrates around integrated engineering services and sustainable construction protocols, with tiering between full-service terminal modernizers and specialized airfield concrete specialists. Strategic archetypes include design-build generalists, precision approach system integrators, and sustainable pavement specialists. Competitive moves center on single-source contract consolidation and cross-border regulatory certification capabilities.
Among U.S.-based construction enterprises, Austin Industries, The Walsh Group, and Hensel Phelps occupy positions within the design-build generalist archetype, reflecting the market shift from fragmented bid-build procurement toward consolidated vendor relationships. These entities exemplify the scale-driven tier serving Sun Belt hub expansions where structural, MEP, and security system integration demands unified project delivery.
| Leading Market Players |
|---|
| Austin Industries |
| The Walsh Group |
| Hensel Phelps |
| J.E. Dunn Construction Company |
| McCarthy Building Companies |
| Turner Construction Company |
| AECOM |
| PCL Constructors |
| Skanska |
| Others |
Value Network & Pricing Analysis
Undercapacity in FAA-certified electrical systems installation is compressing contractor margins while elevating pricing power for specialized airfield concrete specialists serving Texas and California hub expansions.
Pricing Analysis
Cost-plus contracts with steel and cement indexation dominate terminal modernization procurement, insulating contractors from raw material volatility while capping upside. Price differentiation rests on FAA certification tier and sustainable concrete protocol compliance, with California and Washington authorities paying premiums for low-embodied-carbon specifications. Cost compression in standard-grade pavement contracts is intensifying because generational retirement gaps constrain specialized labor availability. Ultra-low-cost carriers and regional freight operators exhibit highest price sensitivity, whereas legacy network carriers at Category X hubs prioritize operational continuity over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for precision approach systems rests with specialized avionics integrators holding FAA and Transport Canada dual certification. Stainless steel fabrication for NFPA 407-compliant fuel farms draws from U.S., Canadian, and Mexican foundry capacity. Supply chain risk centers on single-source vulnerability for GPS-augmented navigation hardware. Distribution runs through design-build generalists consolidating fragmented specialty contractor relationships at Sun Belt hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as FAA NextGen standards force interoperability investments that favor integrated design-build partnerships over fragmented bid-build procurement.
For Market Incumbents: Harden vendor lock-in through cross-border regulatory certification spanning FAA and Transport Canada jurisdictions. Deepen backward integration into sustainable concrete supply chains serving California and Washington state mandates. Acquire specialized airfield electrical systems installers to offset generational retirement gaps constraining project velocity.
For New Entrants and Emerging Players: Build out vertiport electrical systems and eVTOL precision approach adaptations in Florida and Texas metropolitan corridors before incumbent generalists establish design-build dominance. Target urban air mobility infrastructure as the most penetrable white space. Lead with modular, rapidly deployable vertiport solutions requiring minimal environmental permitting.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among IoT-enabled pavement monitoring specialists embedding sensor networks for predictive maintenance contracts. Long-term viability favors vendors with locked-in regulatory compliance cycles independent of passenger volume fluctuations. Monitor FAA NextGen deadline acceleration as the primary inflection signal for precision approach system procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Procurement Consolidation | Turner Construction and AECOM capture complex terminal modernization through unified structural, MEP, and security integration. |
| Cross-Border Regulatory Certification | Dual FAA and Transport Canada approval opens integrated procurement at Toronto Pearson and Detroit Metropolitan transborder facilities. |
| Sustainable Concrete Protocol Investment | Skanska differentiates via low-embodied-carbon specifications meeting California and Washington state airport authority mandates. |
| IoT Pavement Monitoring Deployment | Embedded sensor networks enable predictive maintenance revenue streams without operational shutdown at aging hubs. |
| Vertiport Infrastructure Development | Urban air mobility electrical systems and precision approach adaptations capture nascent eVTOL demand in Florida and Texas corridors. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings. Airport capital program directors, FAA systems specialists, airfield construction project managers, and TSA checkpoint technology procurement officers provided operational perspective. Secondary sources include FAA NextGen implementation reports, Transport Canada harmonization standards, airport improvement program funding disclosures, and environmental permitting databases. Bottom-up project pipeline analysis and top-down regulatory mandate sizing were triangulated to establish market boundaries.
Calibration against historical capital deployment patterns and announced greenfield developments shaped the analytical framework. Segmentation dimensions modeled include facility type, technology category, end-user archetype, and service intensity across the projection horizon. CAGRs were derived from regulatory deadline pacing and fleet modernization program announcements. Forecast inputs incorporated FAA data communications compliance timelines and bipartisan infrastructure spending prioritization shifts.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by design-build generalists would shift outcomes. Model assumptions reflect phased reconstruction logistics constraints and specialized labor availability rather than demand elasticity. Quarterly review of FAA funding appropriations and Transport Canada harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market