
 Airport Ground Support Equipment Market | 2026-2036
Airport Ground Support Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Ground Support Equipment Market Analysis
Ground handling service procurement is rewriting how airports contract for tugs, cargo loaders, and pushback tractors across major hubs. TLD Group leverages its integrated manufacturing footprint across France and China to sustain delivery timelines for electric pushback tractors. Weihai Guangtai anchors the Asia-Pacific supply corridor with specialized production of belt loaders and aircraft de-icing platforms. ITW GSE competes through advanced 400Hz ground power units that reduce aircraft auxiliary power unit runtime on the tarmac.
Airport ground support equipment comprises mobile and fixed assets designed to service aircraft during turnaround operations, including belt loaders rated for 30-40 tons per hour cargo throughput and pushback tractors generating 200-400 kN drawbar pull. The primary commercial purpose centers on minimizing aircraft ground time while ensuring safety compliance during baggage handling, refueling, and towing operations. Electric fuel types are capturing disproportionate attention from ground handlers seeking to eliminate jet fuel auxiliary consumption during gate operations. Automated systems segment leads technology investment as airports deploy autonomous baggage tractors and collision-avoidance tracking solutions. Conventional diesel equipment still occupies the largest installed base, though margin pools are migrating toward hybrid conversions and battery-electric new builds.
FAA certification requirements under 14 CFR Part 139 govern airfield equipment safety standards across United States commercial airports, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices in ground support air conditioning carts. EASA airworthiness directives increasingly incorporate noise and emissions thresholds for equipment operating within European airport curfew zones. Stakeholders must monitor how rapidly charging infrastructure deployment at gate positions keeps pace with airline fleet electrification commitments.
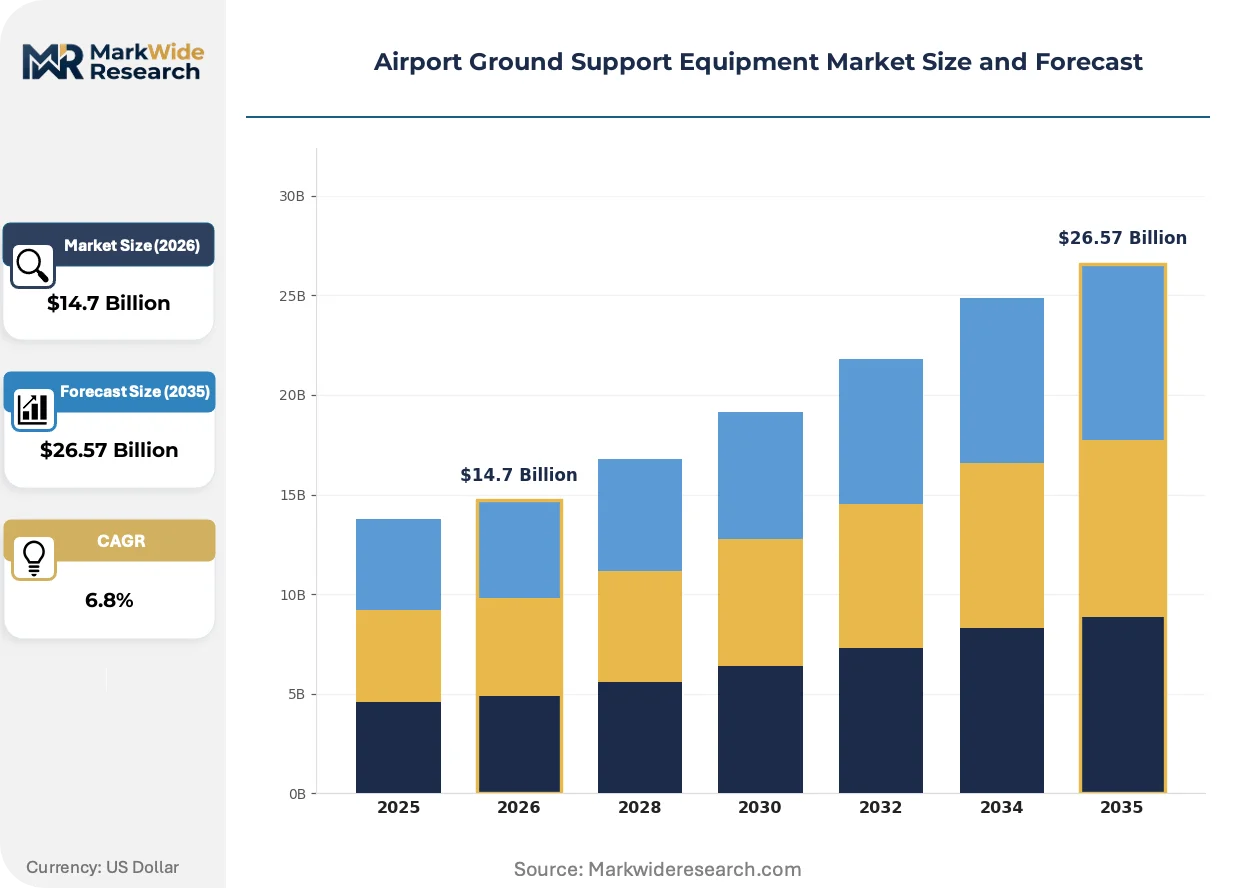
Market Dynamics
Airline fleet electrification commitments are forcing simultaneous replacement of diesel ground support fleets, creating procurement surges that outstrip charging infrastructure deployment at major hubs.
Growth Catalysts
- EU Green Deal carbon thresholds:European airports face binding emissions caps that mandate hybrid or electric belt loaders and pushback tractors by 2030, accelerating capital deployment.
- China state-owned airport modernization:Beijing Capital and Shanghai Pudong are executing billion-dollar ground handling overhauls that specify electric fuel types for all new tugs and cargo loaders.
- Autonomous collision-avoidance systems:Machine-vision tracking technology is reducing insurance premiums and enabling 24-hour operations at cargo-dominant airports.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production clusters in East Asia, exposing European and North American equipment manufacturers to freight cost volatility and tariff exposure.
- FAA 14 CFR Part 139 certification timelines:Airfield equipment safety approvals require 18-24 month validation cycles that delay revenue recognition for electric tractor launches.
- Legacy diesel installed base:Existing pushback tractors and belt loaders carry 15-20 year operational lifespans, compressing replacement demand into narrow procurement windows.
Strategic Opportunities
- India airport privatization wave:Greenfield terminals in Delhi and Mumbai lack legacy diesel infrastructure, enabling pure-electric ground support fleets from inception.
- 400Hz ground power unit-as-a-service:Power-by-the-hour contracts for ITW GSE-style units are displacing capital purchases at budget carriers operating narrow-body fleets.
- F-Gas Regulation refrigerant phase-down:EU-mandated HFC restrictions are creating replacement demand for air conditioning carts using CO2 or hydrocarbon refrigerants.
Industry Challenges
- High-voltage technician scarcity:Electric tug maintenance requires certified electricians that airport ground handlers struggle to recruit at prevailing wage scales.
- Gate-position charging retrofit complexity:Installing 350kW fast-charging infrastructure requires concrete excavation and electrical vault upgrades that disrupt active terminal operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Ground Support Equipment Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Pushback Tractors, Tugs, Belt Loaders, Cargo Loaders Fuel Type: Electric, Diesel, Hybrid, Jet Fuel End User: Airlines, Airports, Ground Handlers, Service Providers Technology: Automated Systems, Conventional Equipment, Mobile Apps, Tracking Solutions |
| Companies Covered | TLD Group, MULAG, Textron Ground Support Equipment, Weihai Guangtai Airport Equipment Co., Ltd., Tronair, ITW GSE, Mallaghan, TCR Group, Oshkosh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Ground Support Equipment Market Emerging Trajectories
Solid-state battery chemistry is collapsing the weight-performance tradeoff that has constrained electric pushback tractor deployment. Autonomous towing systems are compressing labor requirements for overnight cargo operations. After-sales revenue models are migrating from parts sales to uptime guarantees backed by predictive maintenance algorithms.
Solid-state lithium-metal cells are collapsing the energy density gap between electric and diesel pushback tractors. Ground handlers at Frankfurt and Amsterdam Schiphol are piloting 500kWh battery packs that eliminate midday charging for wide-body towing cycles. The structural consequence is collapsing diesel tractor residual values as fleet managers anticipate full electrification by 2030.
REACH chemical authorization is restricting hydraulic fluid formulations used in aircraft de-icing platforms. Equipment manufacturers must reformulate to bio-based alternatives or face market withdrawal across EU member states. The F-Gas Regulation compounds this pressure by simultaneously constraining refrigerant choices in ground support air conditioning carts, forcing dual compliance investments.
Ground handlers are unbundling maintenance contracts from original equipment purchases, forcing manufacturers to compete on aftermarket parts availability. TLD Group and Weihai Guangtai are responding with regional spare parts hubs in Singapore and Dubai. This behavioral shift is most pronounced among Middle Eastern mega-carriers operating mixed fleets across multiple hub airports.
Airport Ground Support Equipment Market Segmentation
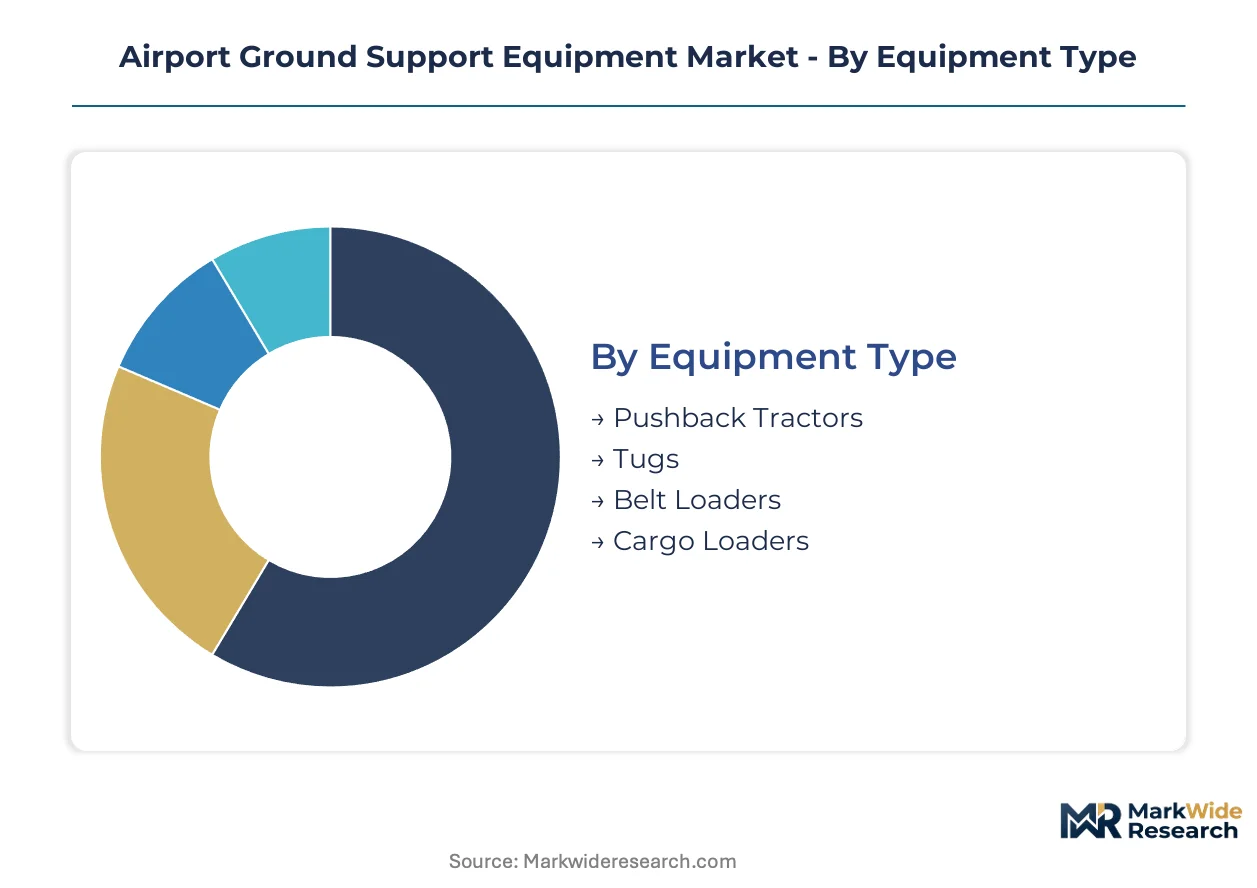
Ground support equipment procurement varies sharply by operational intensity, regulatory exposure, and fleet electrification timelines across airport ecosystems. Segment-specific requirements determine whether buyers prioritize drawbar pull specifications, charging infrastructure compatibility, or autonomous collision-avoidance capabilities.
Equipment Type:
Pushback tractors and belt loaders dominate capital allocation across narrow-body and wide-body gate configurations.
- Pushback Tractors:These units generate 200-400 kN drawbar pull for aircraft repositioning during turnaround windows. Frankfurt and Amsterdam Schiphol are piloting 500kWh battery packs that eliminate midday charging cycles for wide-body operations.
- Tugs:Electric variants are capturing procurement preference as EU Green Deal thresholds mandate zero-emission towing equipment by 2030. Beijing Capital and Shanghai Pudong specify electric fuel types for all new tug acquisitions under state-owned modernization campaigns.
- Belt Loaders:Rated for 30-40 tons per hour cargo throughput, these units face F-Gas Regulation constraints on refrigerant choices for integrated air conditioning.
- Cargo Loaders:High-lift platforms serving containerized freight operations at cargo-dominant airports.
Established volume favors pushback tractors; emerging adoption favors electric tugs.
Fuel Type:
Procurement patterns split between legacy diesel infrastructure and electrification mandates.
- Electric:Battery-electric systems are displacing diesel at gates where 350kW fast-charging infrastructure permits. Ground handlers face high-voltage technician scarcity that constrains maintenance scaling.
- Diesel:Conventional equipment still occupies the largest installed base with 15-20 year operational lifespans. Residual values are compressing as fleet managers anticipate full electrification timelines.
- Hybrid:Transitional configurations bridge charging infrastructure gaps at mid-size airports. Margin pools are migrating toward hybrid conversions as interim compliance solutions.
- Jet Fuel:Auxiliary power consumption during gate operations is being eliminated through 400Hz ground power unit deployment.
Diesel retains installed-base dominance; electric configurations are climbing the fastest.
End User:
Contracting structures determine whether procurement flows through capital budgets or operating leases.
- Airlines:Fleet renewal programs are accelerating direct procurement of electric belt loaders and pushback tractors. Carriers unbundle maintenance contracts from original equipment purchases.
- Airports:State-owned operators in China execute billion-dollar ground handling overhauls with electric equipment specifications.
- Ground Handlers:Third-party service providers face EU Green Deal binding emissions caps that mandate equipment replacement schedules.
- Service Providers:Specialized contractors for de-icing and cargo handling require REACH-compliant hydraulic fluid formulations.
Airlines drive specification-setting; ground handlers absorb compliance execution.
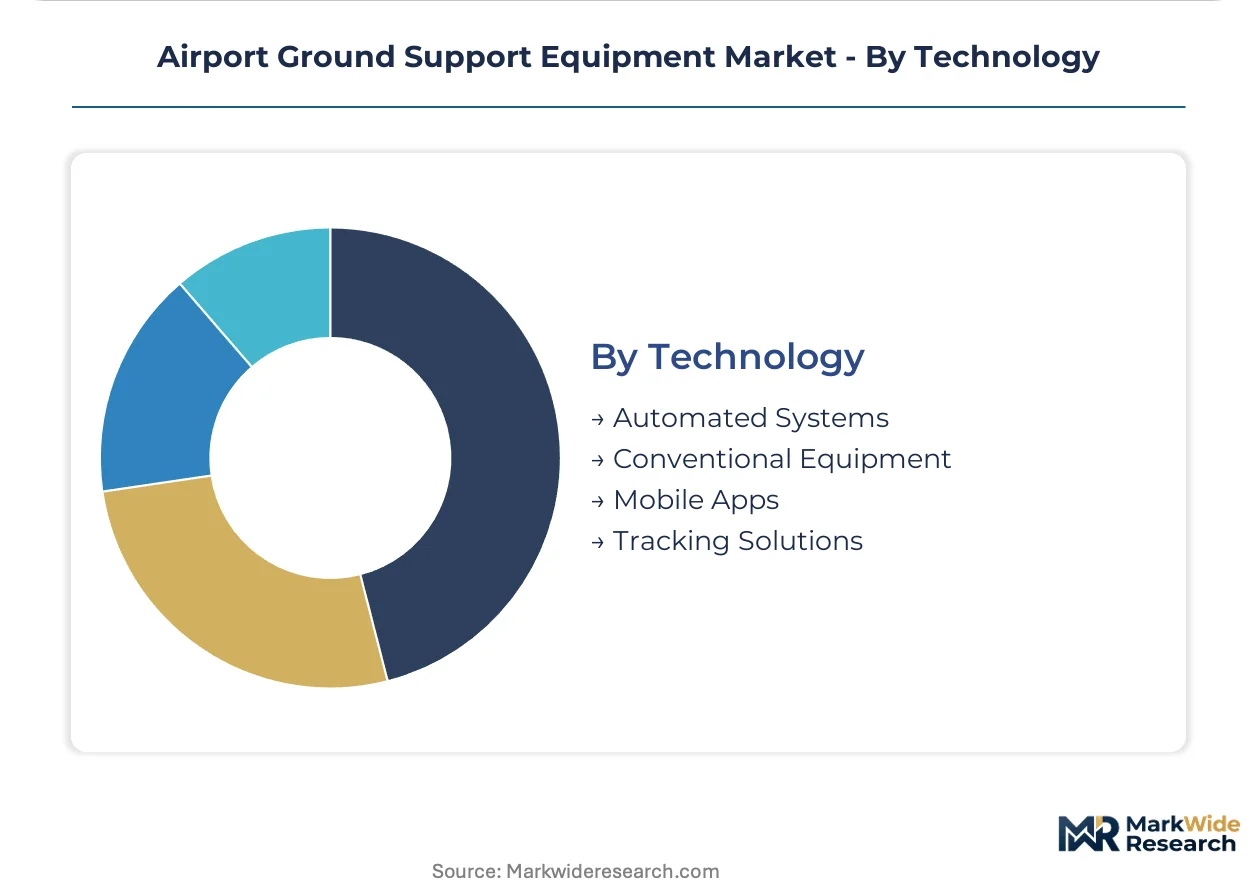
Technology:
Automation intensity separates premium procurement from commodity replacement cycles.
- Automated Systems:Autonomous baggage tractors with machine-vision tracking reduce insurance premiums and enable 24-hour cargo operations. Solid-state battery chemistry is collapsing weight-performance constraints.
- Conventional Equipment:Manual-operation units dominate emerging market procurement where labor costs offset automation premiums.
- Mobile Apps:Fleet management interfaces integrate gate-position scheduling with charging status monitoring.
- Tracking Solutions:Collision-avoidance systems compress labor requirements for overnight freight operations at Middle Eastern mega-carrier hubs.
Conventional equipment sustains replacement volume; automated systems command steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification timelines anchor procurement patterns across United States commercial airports, while EU Green Deal thresholds reshape fleet specifications at Frankfurt and Amsterdam Schiphol. State-owned operators in Beijing and Shanghai execute billion-dollar ground handling overhauls that specify electric fuel types.
United States
Airline fleet renewal programs at Delta and United accelerate direct procurement of electric belt loaders and pushback tractors. FAA 14 CFR Part 139 governs airfield equipment safety standards with 18-24 month validation cycles. Dallas-Fort Worth and Atlanta Hartsfield-Jackson concentrate ground handler consolidation activity.
China
Beijing Capital and Shanghai Pudong undertake massive ground handling modernization campaigns with electric equipment specifications. State-owned airport operators execute billion-dollar procurement programs under dual carbon goals. Weihai Guangtai anchors specialized production of belt loaders and aircraft de-icing platforms in Shandong Province.
Germany
Frankfurt Airport pilots 500kWh battery packs that eliminate midday charging for wide-body towing cycles. EU Green Deal binding emissions caps mandate hybrid or electric belt loaders and pushback tractors by 2030. MULAG maintains manufacturing presence for specialized ground support equipment.
Netherlands
Amsterdam Schiphol deploys autonomous baggage tractors with machine-vision tracking for 24-hour cargo operations. EASA airworthiness directives incorporate noise and emissions thresholds for equipment operating within European airport curfew zones. Rotterdam The Hague Airport serves as testing ground for collision-avoidance tracking solutions.
India
Greenfield terminals in Delhi and Mumbai lack legacy diesel infrastructure, enabling pure-electric ground support fleets from inception. Airport privatization waves attract international ground handlers seeking compliance-ready equipment deployments. Bengaluru and Hyderabad concentrate cargo-dominant airport automation investment.
Airport Ground Support Equipment Market Vendor Landscape
Integrated manufacturers and specialized component suppliers split the market along electrification capability lines. TLD Group leverages cross-border manufacturing footprints to sustain delivery timelines for electric pushback tractors. Weihai Guangtai anchors Asia-Pacific supply corridors with regional production capacity. Strategic moves concentrate on charging infrastructure partnerships and predictive maintenance algorithm development.
Within the integrated manufacturing tier, TLD Group and Weihai Guangtai Airport Equipment Co., Ltd. represent archetypal approaches to geographic diversification. Among specialized ground power suppliers, ITW GSE occupies a position exemplifying technology-focused competition through advanced 400Hz unit deployment.
| Leading Market Players |
|---|
| TLD Group |
| MULAG |
| Textron Ground Support Equipment |
| Weihai Guangtai Airport Equipment Co., Ltd. |
| Tronair |
| ITW GSE |
| Mallaghan |
| TCR Group |
| Oshkosh Corporation |
| Others |
Supply Flow & Price Mechanics
Shandong Province's specialized manufacturing clusters for belt loaders and de-icing platforms feed directly into procurement negotiations at Beijing Capital and Shanghai Pudong, where state-owned airport operators leverage geographic proximity to compress supplier margins on electric equipment specifications.
Pricing Analysis
East Asian battery pack production commands a 15-25% price premium over European-assembled equivalents due to freight cost volatility and tariff exposure. Three-tier pricing structure across OEM-certified, aftermarket-standard, and refurbished-economy levels segments buyer tiers, with budget carriers and regional ground handlers populating the most price-sensitive bracket. Cost compression in the mid-tier is intensifying because hybrid conversion providers are undercutting full electric new-builds at airports with incomplete charging infrastructure.
Supply Chain Analysis
Export control regimes on high-voltage battery management systems and solid-state cell manufacturing equipment constrain technology flows from East Asia to European and North American assembly plants. Lithium-ion cell production clusters in China, South Korea, and Japan anchor supply, drawing from cobalt concentrates, lithium carbonate, and rare-earth magnet feedstocks. Single-source vulnerability concentrates in cathode active material processing. Distribution runs through regional spare parts hubs in Singapore and Dubai serving Middle Eastern mega-carrier fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
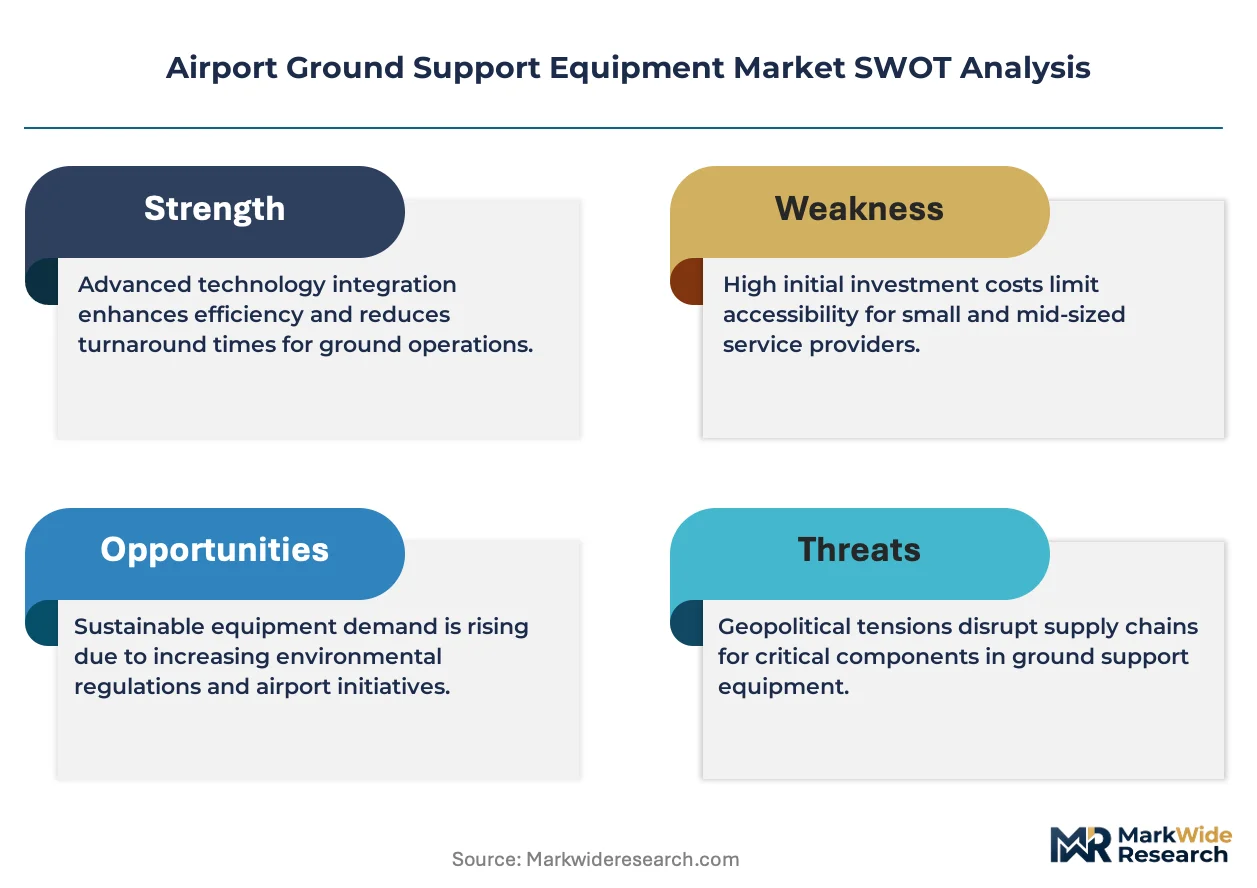
Regulatory entrenchment around FAA 14 CFR Part 139 and EASA airworthiness directives creates formidable switching costs for approved equipment suppliers, cementing defensive moats for incumbents with validated product lines.
For Market Incumbents: Harden certification pipelines by pre-submitting solid-state battery variants for 18-24 month validation cycles before diesel residual values collapse entirely. Deepen backward integration into lithium-cell supply through offtake agreements with Korean cathode producers to offset tariff exposure from East Asian concentration. For New Entrants and Emerging Players: Greenfield airport terminals in India lacking legacy diesel infrastructure represent the most penetrable entry point for pure-electric ground support fleets sold on power-by-the-hour contracts rather than capital purchase. Target autonomous collision-avoidance retrofit kits as a software-first wedge into established handler fleets unwilling to retire conventional equipment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aftermarket service platforms with predictive maintenance algorithms over pure hardware manufacturers. Long-term viability hinges on recurring revenue density rather than one-time equipment sales. Watch charging infrastructure deployment velocity at gate positions as the inflection signal for electric fleet penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | 350kW fast-charging deployment at Frankfurt and Amsterdam Schiphol gates locks in electric tractor demand. |
| Solid-State Battery Supply Agreement | 500kWh pack sourcing from Korean cell manufacturers eliminates midday charging cycles for wide-body operations. |
| Predictive Maintenance Platform Launch | Uptime guarantee contracts at TLD Group and Weihai Guangtai displace traditional parts-sales revenue models. |
| Regional Spare Parts Hub Expansion | Singapore and Dubai distribution nodes compress lead times for Middle Eastern mega-carrier mixed fleets. |
| Autonomous Towing System Certification | Machine-vision tracking validation under EASA noise and emissions thresholds enables 24-hour cargo operations. |
Methodological Framework
A standing panel of ground handling operations directors, airport procurement managers, OEM platform engineers, and aftermarket service heads provided ongoing calibration against secondary validation from FAA airworthiness directive filings, EASA certification databases, EU Green Deal implementation reports, and customs trade records for lithium-cell imports. Bottom-up equipment shipment tallies triangulated with top-down airport capital expenditure disclosures.
Scenario-bracketing around charging infrastructure deployment timelines and fleet electrification commitment trajectories shaped volume projections across the analysis window. Segmentation dimensions modeled include equipment type, fuel architecture, end-user contracting structure, and automation intensity. CAGRs derived from logistic diffusion curves fitted to historical replacement cycles and regulatory mandate deadlines, with solid-state battery cost curves and high-voltage technician labor availability as key variable inputs.
Practitioners should monitor lithium-cell tariff schedules, FAA certification backlog durations, and EU F-Gas Regulation enforcement intensity for early signals of forecast drift. Material shifts in solid-state battery commercialization timelines or airport privatization waves in emerging economies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Airport Kiosk Market