
 Global Aerospace Ground Handling System Market | 2026-2036
Global Aerospace Ground Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Ground Handling System Market Analysis
Aftermarket service revenue is tilting toward integrated platform operators as airlines seek single-accountability contracts for turnaround operations. Swissport International Ltd leverages its global station network to bundle passenger, ramp, and cargo services under unified SLAs. Dnata anchors its position through in-house production of specialized ground support equipment across Middle Eastern and Asia-Pacific hubs. Menzies Aviation competes on geographic dominance, controlling de-icing and fueling operations at over 250 airports worldwide.
Aerospace ground handling systems encompass the equipment, software protocols, and labor coordination frameworks that enable aircraft turnaround between flights, including 400 Hz ground power units delivering precise voltage regulation, cargo loaders rated to 35-ton lift capacity, and telemetry-linked dispatch platforms. The primary commercial purpose is minimizing gate occupancy time to maximize fleet utilization rates for airlines and airport slot capacity. Ramp Services commands the largest revenue pool due to fueling and de-icing frequency, while Automated Systems within the Technology dimension represents the fastest-expanding margin segment as airports deploy autonomous baggage tractors and AI-guided aircraft docking. Cargo Services shows concentrated growth at dedicated freighter hubs where e-commerce volumes strain legacy material handling infrastructure.
FAA ground handling safety directives mandate recurrent certification for pushback tractor operators and establish minimum separation standards during simultaneous aircraft servicing. EASA ramp inspection harmonization enforces cross-border equipment interoperability standards, while ICAO's aerodrome design specifications dictate physical clearances for ground support vehicle circulation patterns. Stakeholders must monitor which regulatory jurisdiction's certification requirements their equipment portfolios satisfy as bilateral air service agreements expand into secondary city pairs with divergent oversight regimes.
Market Dynamics
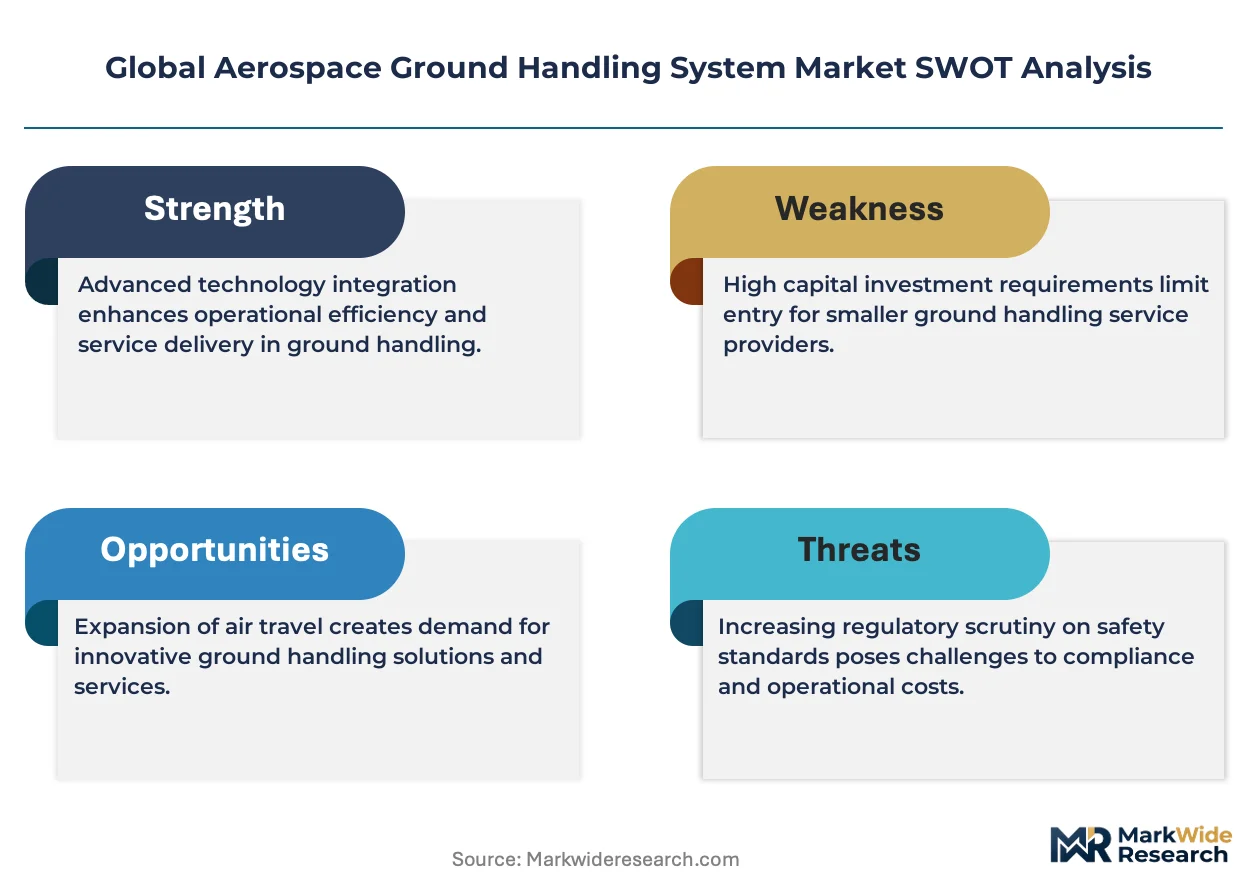
Airlines are consolidating vendor relationships at major international hubs, displacing fragmented point solutions with full-service ground handling contracts that bundle passenger, ramp, and cargo services under unified accountability structures.
Growth Catalysts
- FAA Safety Directives:Recurrent certification mandates for pushback tractor operators and minimum separation standards during simultaneous aircraft servicing are professionalizing the workforce and expanding training service markets.
- E-Commerce Freight Volumes:Dedicated freighter hubs handling cross-border e-commerce are straining legacy material handling infrastructure and accelerating capital deployment into automated cargo loaders and telemetry-linked dispatch platforms.
- Dubai and Abu Dhabi Airport Expansions:Multi-billion dollar infrastructure commitments across the United Arab Emirates are concentrating demand for integrated ground support equipment production and maintenance facilities.
Market Restraints
- Specialized Aluminum and Composite Input Costs:Ground support equipment manufacturing depends on aerospace-grade materials subject to energy-intensive smelting and carbon fiber supply bottlenecks.
- European Equipment Interoperability Mandates:EASA ramp inspection harmonization enforces cross-border standards that raise compliance costs for regional equipment manufacturers serving secondary airports.
- Electric Ground Power Unit Technical Limitations:Battery energy density constraints and thermal management challenges restrict runtime for 400 Hz units during extended aircraft ground operations.
Strategic Opportunities
- Saudi Arabia's Giga-Project Airports:Neom and Red Sea International Airport developments are creating greenfield procurement opportunities for autonomous baggage tractors and AI-guided aircraft docking systems.
- India's UDAN Regional Connectivity Scheme:Tier-2 and Tier-3 airport upgrades under the government's subsidized route program are opening underpenetrated ground handling service markets.
- EU Green Deal Aviation Decarbonization:Electrification incentives and sustainable aviation fuel handling requirements are mandating new ground support equipment categories and retrofit demand.
Industry Challenges
- Certified Pushback and De-Icing Operator Shortages:FAA and EASA recurrent training requirements are constraining labor supply during peak winter operations at northern latitude hubs.
- Legacy Telemetry Platform Integration Complexity:Airports with fragmented dispatch software architectures face multi-year migration timelines to unified AI-guided coordination systems.
- Ground Support Equipment Fleet Capex Intensity:35-ton rated cargo loaders and specialized aircraft tugs require seven-figure capital commitments that strain municipal airport authority budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Ground Handling System Market |
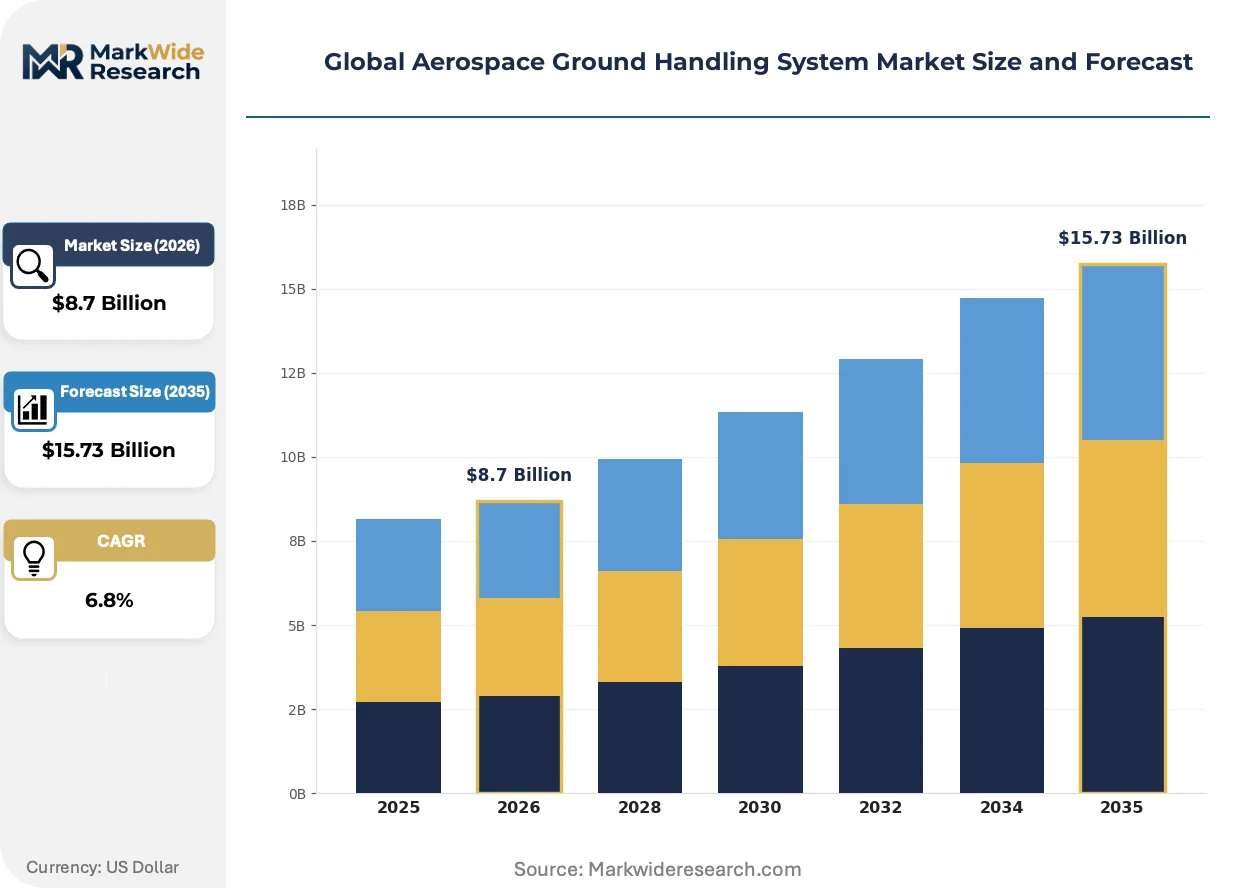
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Services, Ramp Services, Cargo Services, Aircraft Maintenance Technology: Automated Systems, GPS Tracking, Mobile Applications, Ground Support Equipment End User: Airlines, Airport Authorities, Ground Handling Companies, Freight Forwarders Aircraft Type: Commercial Jets, Cargo Aircraft, Private Jets, Helicopters |
| Companies Covered | Swissport International Ltd, Dnata, SATS Ltd, John Bean Technologies Corporation (JBT), Cavotec SA, Menzies Aviation, Oshkosh Corporation, Alvest Group, Çelebi Aviation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Ground Handling System Market Emerging Trajectories
Digital twin and simulation technologies are compressing equipment design cycles and enabling predictive maintenance models that reduce unplanned downtime during high-frequency turnaround operations.
Telematics-enabled ground power units are virtualizing voltage monitoring and load balancing functions that previously required on-site technician intervention. Major international hubs in Germany and Singapore are deploying these systems to automate gate allocation decisions based on real-time power demand forecasting. The technology is virtualizing maintenance scheduling by shifting from calendar-based inspections to condition-triggered service events.
EASA's F-Gas Regulation phase-down mandates are accelerating adoption of CO2-based and ammonia refrigeration systems for aircraft ground air conditioning units. Equipment manufacturers serving European airports must redesign thermal management architectures to maintain cooling capacity with lower global warming potential working fluids. The regulation is compressing product development timelines as 2027 compliance deadlines approach for high-leakage equipment categories.
Airline procurement departments are bundling passenger, ramp, and cargo services into single-accountability contracts with unified SLAs that penalize gate occupancy time overruns. Full-service ground handlers at Heathrow, Charles de Gaulle, and Changi are displacing point-solution vendors by absorbing operational risk previously borne by airline operations teams. This consolidation concentrates vendor selection authority with procurement functions that prioritize total turnaround cost over equipment-specific metrics.
Global Aerospace Ground Handling System Market Segmentation
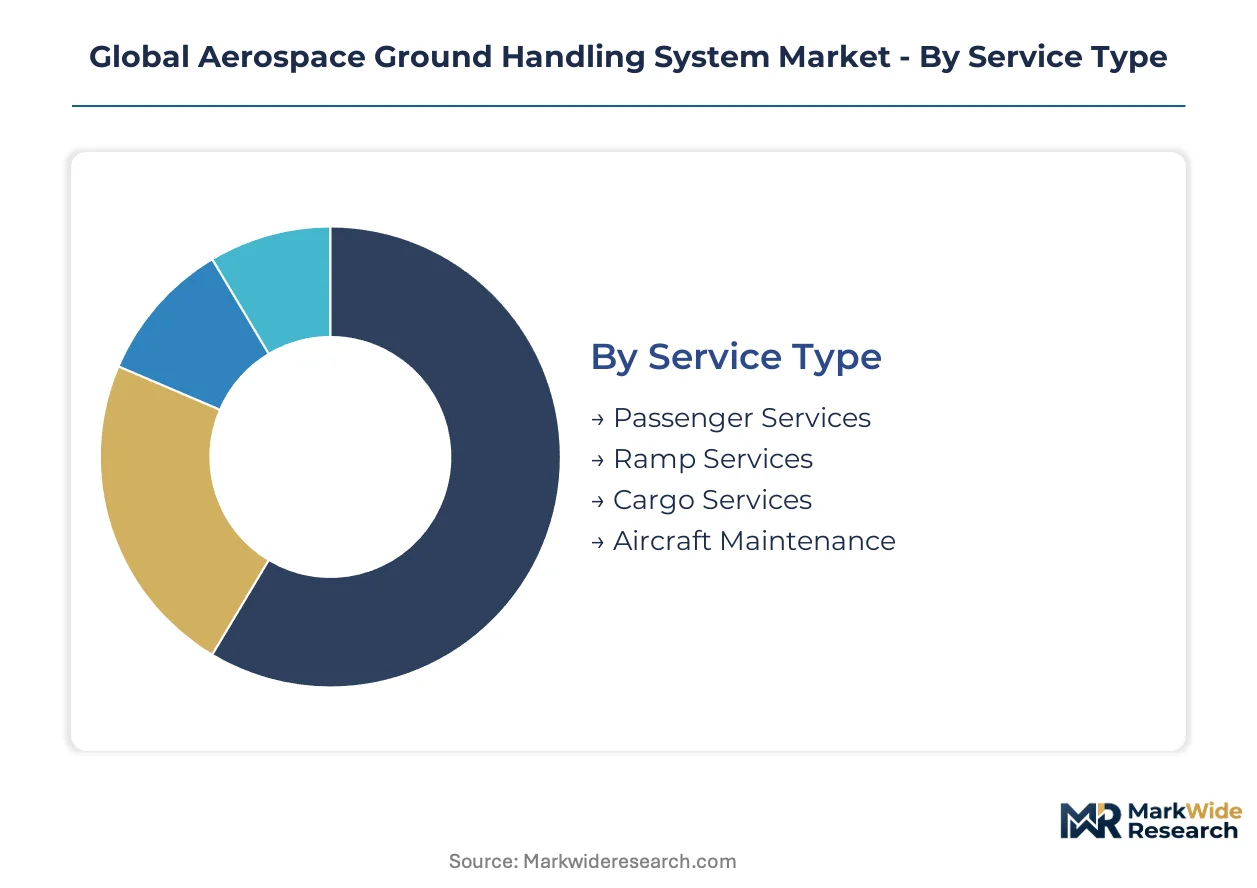
Ground handling procurement decisions split across operational function, technology maturity, customer scale, and aircraft category. Each dimension carries distinct margin profiles and certification requirements that reshape vendor positioning.
Service Type:
Cost tier differentiation separates high-frequency commodity operations from specialized technical services with premium pricing power.
- Ramp Services:Fueling, de-icing, pushback, and aircraft towing operations run on per-turnaround fee structures tied to jet bridge occupancy minutes. Dubai and Abu Dhabi airport expansions are concentrating demand for integrated ramp service contracts bundling multiple ground functions under single accountability.
- Cargo Services:Freighter loading, mail handling, and cold chain logistics require 35-ton rated loaders and telemetry-linked dispatch coordination. E-commerce volumes at dedicated cargo hubs are straining legacy material handling infrastructure and accelerating automation capital deployment.
- Passenger Services:Check-in, boarding, and baggage claim coordination with fixed resource allocation per flight.
- Aircraft Maintenance:Line maintenance and A-check servicing during ground windows with specialized tooling requirements.
Ramp Services commands the established base. The steepest expansion runs through Cargo Services.
Technology:
Application maturity spans from proven mechanical systems through emerging autonomous platforms with divergent deployment timelines.
- Automated Systems:Autonomous baggage tractors, AI-guided aircraft docking, and robotic cargo loaders eliminate operator fatigue errors and compress turnaround variance. Saudi Arabia's Neom and Red Sea International Airport greenfield developments are creating first-mover procurement channels absent legacy infrastructure constraints.
- Ground Support Equipment:Conventional 400 Hz power units, air start units, and belt loaders with established maintenance protocols and parts availability. Battery energy density limitations and thermal management challenges restrict electric unit runtime during extended ground operations.
- GPS Tracking:Real-time vehicle positioning and geofencing for ramp safety compliance.
- Mobile Applications:Digital task allocation and electronic flight bag integration for ground crew coordination.
Ground Support Equipment anchors current fleet composition. Automated Systems is climbing the fastest as airports phase in autonomy roadmaps.
End User:
Customer type determines contract structure, with integrated handlers capturing volume through risk absorption that fragmented vendors cannot match.
- Ground Handling Companies:Swissport, Dnata, and Menzies Aviation bundle passenger, ramp, and cargo services under unified SLAs with gate occupancy time penalties. Full-service consolidation at Heathrow, Charles de Gaulle, and Changi is displacing point-solution vendors by absorbing operational risk previously borne by airline operations teams.
- Airlines:In-house ground operations at fortress hubs with dedicated equipment fleets and proprietary training programs.
- Airport Authorities:Municipal and privatized airport operators managing common-use infrastructure and equipment pools.
- Freight Forwarders:E-commerce integrators and logistics providers with dedicated cargo handling requirements at freighter-dominant facilities.
Ground Handling Companies hold the concentrated contract value. The fastest share gains are emerging through Freight Forwarders as e-commerce supply chains verticalize into airport operations.
Aircraft Type:
Volume scale and equipment specification diverge sharply between high-cycle narrowbody operations and low-frequency heavy cargo or VIP segments.
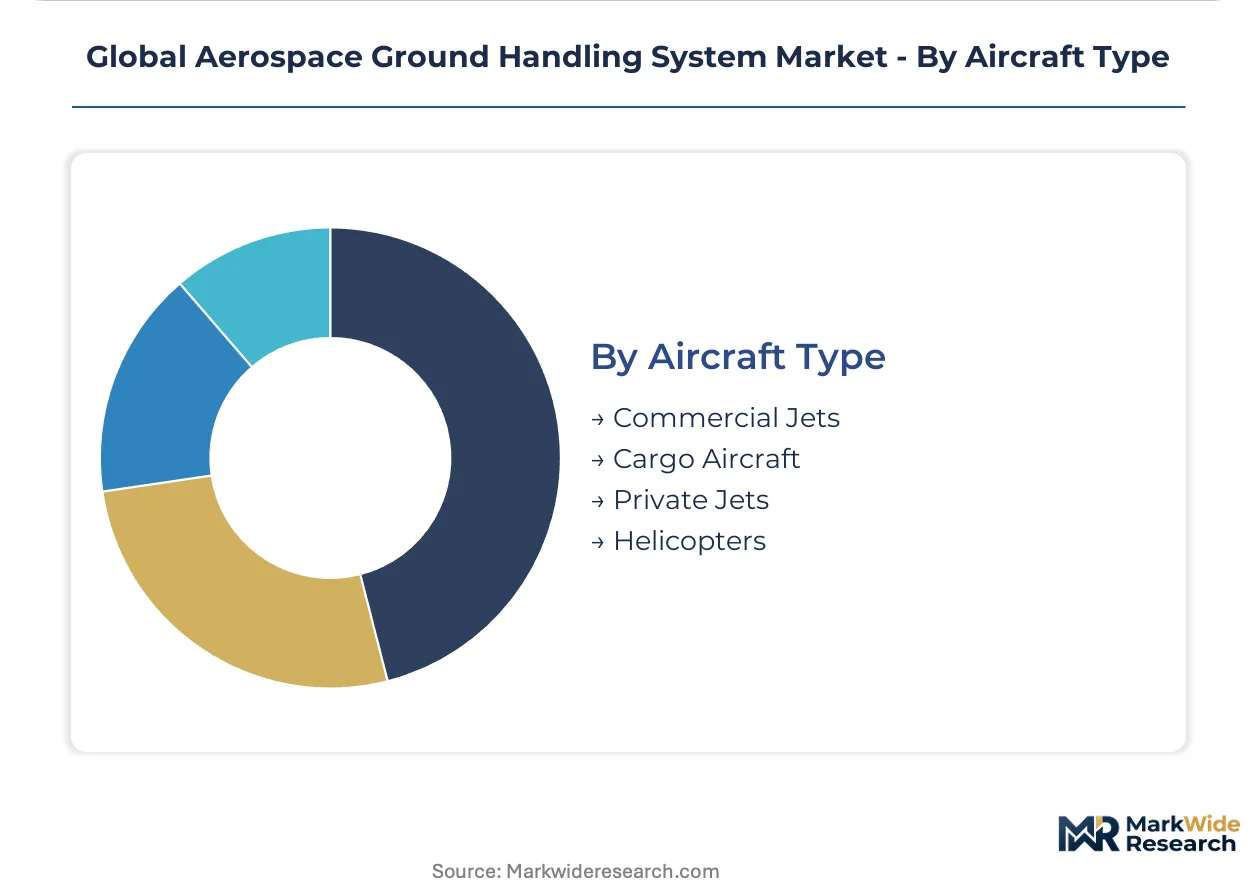
- Commercial Jets:Narrowbody and widebody scheduled service with standardized turnaround protocols and high equipment utilization rates. India's UDAN regional connectivity scheme is opening tier-2 and tier-3 airport upgrade demand for commercial jet ground handling infrastructure.
- Cargo Aircraft:Dedicated freighter and converted passenger-to-cargo operations with specialized main deck loading systems and weight-and-balance protocols.
- Private Jets:Business aviation with flexible scheduling, premium service tiers, and FBO-dominant handling relationships.
- Helicopters:Offshore, emergency medical, and urban air mobility with rotor clearance and noise abatement equipment requirements.
Commercial Jets generates the dominant equipment demand. Cargo Aircraft is expanding most quickly as freighter fleet growth outpaces passenger capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across procurement contexts, with municipal airport authorities in emerging economies driving hard bargains on standardized equipment while premium hub operators absorb premium pricing for integrated service bundles.
United States
FAA recurrent certification mandates for pushback tractor operators are professionalizing the ground handling workforce across major hubs. The agency's updated ground handling safety directives establish minimum separation standards during simultaneous aircraft servicing. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor concentrated demand for 400 Hz ground power units and telemetry-linked dispatch platforms.
Germany
EASA ramp inspection harmonization enforces cross-border equipment interoperability standards that raise compliance costs for regional manufacturers. The EU Green Deal Aviation Decarbonization framework mandates electrification incentives and sustainable aviation fuel handling requirements. Frankfurt and Munich airports are deploying autonomous baggage tractors and AI-guided aircraft docking systems under unified procurement frameworks.
United Arab Emirates
Dubai and Abu Dhabi airport expansions are driving multi-billion dollar ground support infrastructure commitments with concentrated demand for integrated production and maintenance facilities. MOHAP and GCAA oversight regimes tighten operational certification requirements for ground handling service providers. Dubai International Airport's South Terminal development is absorbing full-service ground handling contracts that displace fragmented point solutions.
Saudi Arabia
Neom and Red Sea International Airport developments are creating greenfield procurement opportunities absent legacy infrastructure constraints. SFDA and GACA regulatory frameworks are aligning with international ramp safety standards ahead of 2030 operational targets. The NEOM Northwest zone is commissioning autonomous baggage tractors and robotic cargo loaders for its zero-carbon aviation cluster.
India
Tier-2 and Tier-3 airport upgrades under the UDAN Regional Connectivity Scheme are opening underpenetrated ground handling service markets with subsidized route economics. DGFT and AAI procurement guidelines favor domestic equipment sourcing for regional airport modernization. Bangalore and Hyderabad are emerging as maintenance hubs for ground support equipment serving South Asian carrier networks.
Global Aerospace Ground Handling System Market Vendor Landscape
Integrated service bundlers and specialized equipment fabricators split the market along accountability-structure lines. Full-service ground handlers absorb operational risk through unified SLAs with gate occupancy time penalties, while point-solution vendors retain position in secondary airports with fragmented procurement authority. Three archetypes dominate: global station network operators with captive maintenance capabilities, in-house equipment producers with regional hub anchoring, and geographic specialists controlling narrow functional domains. Consolidation concentrates vendor selection authority with airline procurement functions, while autonomous technology licensing partnerships accelerate product roadmaps.
Within the integrated service tier, Swissport International Ltd and Dnata exemplify contrasting strategic positions. Swissport leverages its global station network to anchor unified accountability structures across passenger, ramp, and cargo functions. Dnata occupies a position as an in-house equipment producer with captive manufacturing capabilities across Middle Eastern and Asia-Pacific hubs. Menzies Aviation represents the geographic dominance archetype, with operational control over specialized functions at extensive airport networks worldwide.
| Leading Market Players |
|---|
| Swissport International Ltd |
| Dnata |
| SATS Ltd |
| John Bean Technologies Corporation (JBT) |
| Cavotec SA |
| Menzies Aviation |
| Oshkosh Corporation |
| Alvest Group |
| Çelebi Aviation |
| Others |
Supply Flow & Price Mechanics
Aerospace-grade aluminum smelting capacity concentrates in China and the Persian Gulf, tethering ground support equipment margins to energy-intensive feedstock economics and regional electricity pricing differentials. This upstream concentration funnels margin capture toward integrated handlers with captive maintenance networks that monetize downtime avoidance through premium service contracts.
Pricing Analysis
Aftermarket parts and field service contracts generate lifetime value multiples exceeding original equipment sales for 400 Hz ground power units and 35-ton cargo loaders. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and fleet scale, with municipal airport authorities in emerging economies driving hardest bargains on standardized equipment. Cost compression in entry-level electric units is intensifying because battery energy density limitations force oversizing for runtime assurance. Ground handling companies absorb premium pricing for integrated bundles, while fragmented regional operators exhibit acute sensitivity to per-unit capital outlays.
Supply Chain Analysis
Aerospace-grade aluminum and carbon fiber composite feedstock draws from China, Germany, and Japan, with carbon fiber supply constrained by polyacrylonitrile precursor availability and oxidation line capacity. Specialized hydraulic systems and precision voltage regulation components rest on single-source relationships with German and Japanese industrial automation suppliers. Tariff exposure on Chinese aluminum semis threatens cost structures for regional equipment fabricators serving secondary airports. Distribution runs through direct OEM channels to fortress hub operators, with aftermarket parts flowing via authorized service networks anchored at major international airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous ground handling technology sits at early-cycle expansion, with Saudi Arabia's greenfield airport developments validating first-mover procurement channels absent legacy infrastructure constraints.
For Market Incumbents: Pre-empt autonomous technology licensing partnerships with AI-guided docking and robotic cargo handling specialists before greenfield procurement windows close at Neom and Red Sea International Airport. Deepen backward integration into ground support equipment manufacturing to defend margin position against aluminum and composite input cost volatility. Absorb operational risk through expanded gate occupancy time penalties in unified SLAs that fragmented point-solution vendors cannot match. For New Entrants and Emerging Players: Pursue India's UDAN-subsidized tier-2 and tier-3 airport upgrades, where domestic equipment sourcing preferences and underpenetrated service markets create viable entry economics. Target freighter-dominant cargo hubs in Southeast Asia where e-commerce volume growth strains legacy material handling infrastructure. Lead with telemetry-linked dispatch platform subscriptions that reduce upfront capital burdens for municipal airport authorities. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated ground handlers with captive equipment production and maintenance networks spanning Middle Eastern and Asia-Pacific hubs. Long-term viability hinges on regulatory compliance capabilities across FAA, EASA, and emerging national aviation authorities with divergent certification timelines. Watch for ICAO aerodrome design specification revisions as the signal indicating inflection toward autonomous system mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Technology Licensing | Accelerates product roadmaps for AI-guided aircraft docking at greenfield airports like NEOM. |
| Backward Integration into Manufacturing | Dnata's captive production model insulates margins from aerospace-grade aluminum cost volatility. |
| Unified SLA Risk Absorption | Swissport's gate occupancy penalties displace fragmented vendors at Heathrow and Changi. |
| Regional Airport Service Expansion | India's UDAN scheme opens tier-2 procurement channels with subsidized route economics. |
| Sustainable Equipment Retrofit Programs | EU Green Deal mandates create replacement demand for electrified ground power units. |
Methodological Framework
Desk research of FAA safety directive filings, EASA ramp inspection protocols, ICAO aerodrome design specifications, and airport authority procurement disclosures preceded structured interviews with ground handling operations directors, airline procurement executives, ground support equipment maintenance heads, and regulatory compliance officers. Secondary validation drew from customs trade data for aluminum and carbon fiber composite imports, OEM equipment registration databases, and airport expansion project announcements. Bottom-up equipment unit economics triangulated against top-down market sizing across service type, technology maturity, and aircraft category dimensions.
Assumptions held EASA F-Gas Regulation compliance timelines and FAA recurrent certification mandates fixed at current stringency levels, while varying e-commerce freight growth rates and autonomous technology adoption curves across the projection horizon. Segmentation modeling spanned operational function, technology maturity, customer scale, and aircraft category with regional regulatory cluster overlays. CAGRs derived from equipment fleet replacement cycles, airport expansion capital commitments, and penetration rate assumptions for electrified and autonomous systems. Forecast inputs included Dubai and Abu Dhabi infrastructure spend disclosures and Saudi giga-project airport development timelines.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cargo-focused entrants or accelerated autonomous mandates by EASA would shift outcomes beyond modeled ranges. Cross-checking against airport authority capital expenditure disclosures and airline ground handling contract renewal frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market