
 Global Aerial Firefighting Market | 2026-2036
Global Aerial Firefighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerial Firefighting Market Analysis
Aftermarket service revenue is narrowing toward integrated fleet management contracts as operators seek lifecycle cost predictability. Coulson Aviation leverages its specialized heavy-lift platform refurbishment capabilities across multiple continents. Lockheed Martin Corporation anchors its position through advanced surveillance and command-and-control system integration. Textron Inc. competes with a diversified portfolio spanning fixed-wing fire suppression and military-to-civilian conversion programs.
Aerial firefighting encompasses the deployment of rotary-wing, fixed-wing, and unmanned aircraft systems equipped with water tanks, retardant delivery apparatus, and thermal imaging payloads to suppress uncontrolled vegetation fires from altitude. Modern platforms operate with load capacities ranging from 700 gallons for light helicopters to over 8,000 gallons for purpose-built amphibious scooper aircraft, with GPS-tracked drop patterns optimizing coverage accuracy. Fixed-wing aircraft dominate current procurement budgets due to higher payload efficiency and extended loiter times over fire complexes. Drones represent the fastest-expanding technology segment as regulatory frameworks mature for beyond-visual-line-of-sight operations in restricted airspace. Fire suppression services capture the largest service-type revenue pool, though reconnaissance and real-time data analytics command superior margins per flight hour.
The FAA governs U.S. air tanker certification and pilot training standards under 14 CFR Part 137, while EASA's CS-25 and CS-29 frameworks shape European large-aircraft type approvals for firefighting modifications. Australia's Civil Aviation Safety Authority enforces stringent low-level flight operating rules over rugged terrain, directly influencing platform design requirements for Asia-Pacific deployments. Stakeholders must monitor evolving unmanned aircraft system integration protocols and retardant environmental toxicity thresholds as procurement criteria tighten across jurisdictions.
Market Dynamics
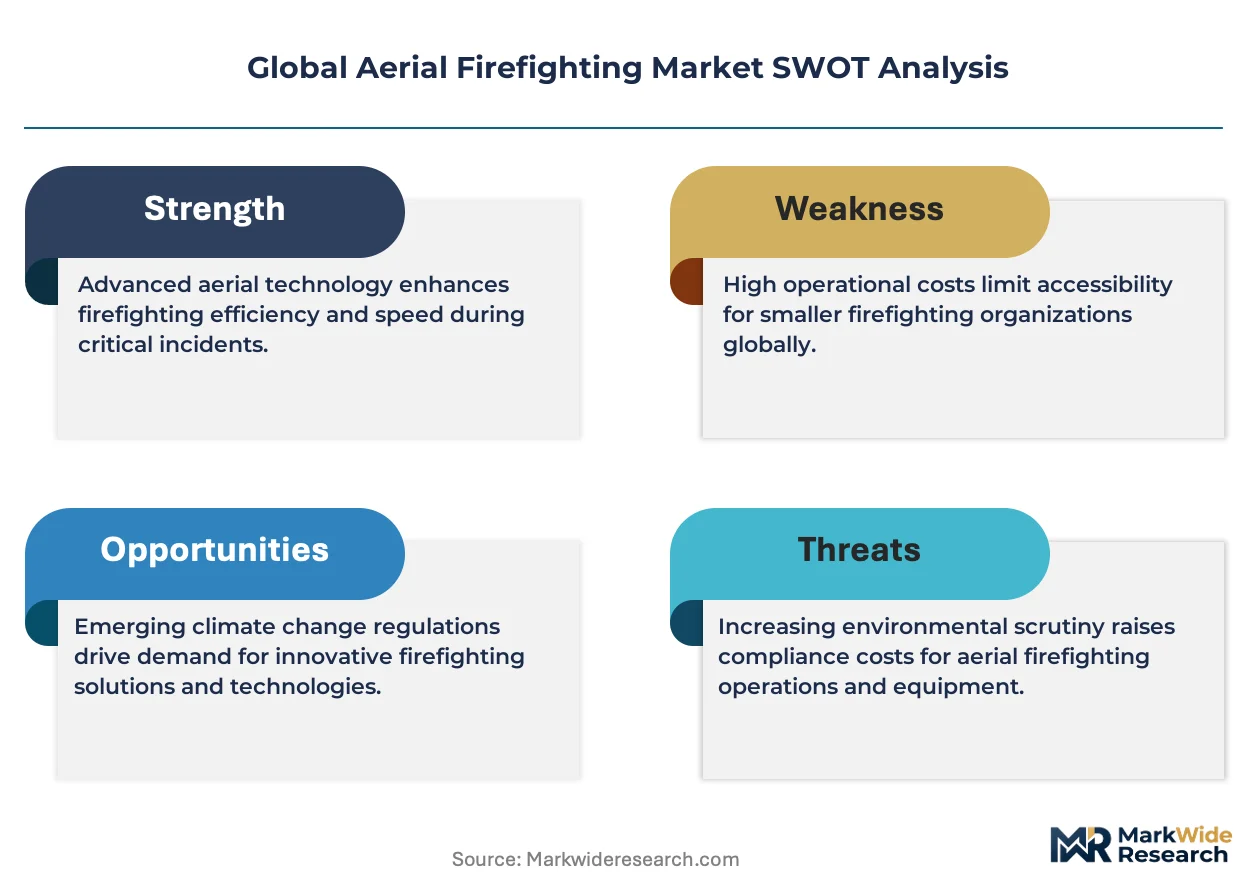
Climate-intensified fire seasons are compressing procurement cycles as state agencies accelerate multi-year aerial fleet contracts to secure capacity ahead of peak demand windows. This structural pressure favors operators with proven platform availability and integrated logistics networks.
Growth Catalysts
- Extended fire seasons:Prolonged drought conditions across California, Victoria, and Mediterranean Europe are stretching suppression windows from four to eight months annually. Forestry agencies in these jurisdictions are doubling flight-hour guarantees in contract renewals.
- FAA Part 137 modernization:Revised certification pathways for large-aircraft firefighting modifications are accelerating type approval timelines for converted military platforms. This regulatory streamlining enables faster fleet expansion by mid-size operators.
- Scooper aircraft efficiency:Amphibious platforms capable of 8,000-gallon freshwater retrieval without ground turnaround are displacing smaller tanker-dependent models. Payload economics favor these systems for sustained attack on large fire complexes.
Market Restraints
- Aviation fuel cost volatility:Jet-A price fluctuations directly compress operating margins for turbine-powered fixed-wing fleets. Smaller operators lack fuel hedging infrastructure and pass-through contract clauses.
- Pilot certification scarcity:Low-altitude mountain flying endorsements required under Australia's CASA regulations create bottlenecks. Training pipelines cannot match fleet expansion timelines.
- Retardant environmental thresholds:ECHA toxicity reviews under REACH frameworks are restricting phosphate-based formulations. Reformulation R&D burdens fall disproportionately on specialized chemical suppliers.
Strategic Opportunities
- Beyond-visual-line-of-sight drone integration:Regulatory frameworks maturing in the United States and Australia will unlock nighttime thermal mapping and automated retardant spotting. Early movers in unmanned systems capture reconnaissance margins.
- Integrated fleet management contracts:Operators bundling maintenance, pilot training, and real-time logistics are displacing transactional flight-hour arrangements. Procurement officers in Victoria and California are piloting ten-year lifecycle agreements.
- Dual-use military conversions:Surplus C-130 and CH-47 platforms from defense drawdowns offer airframe availability at fraction of new-build costs. Conversion specialists with EASA CS-25 expertise control this supply channel.
Industry Challenges
- Airspace coordination complexity:Multi-agency fire response requires real-time deconfliction between manned tankers, helicopters, and emerging drone swarms. Incident command systems lack standardized data protocols across jurisdictions.
- Platform interoperability gaps:Proprietary retardant delivery systems from different manufacturers prevent cross-fleet equipment sharing. Standardization efforts under ISO frameworks remain stalled by incumbent patent positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerial Firefighting Market |
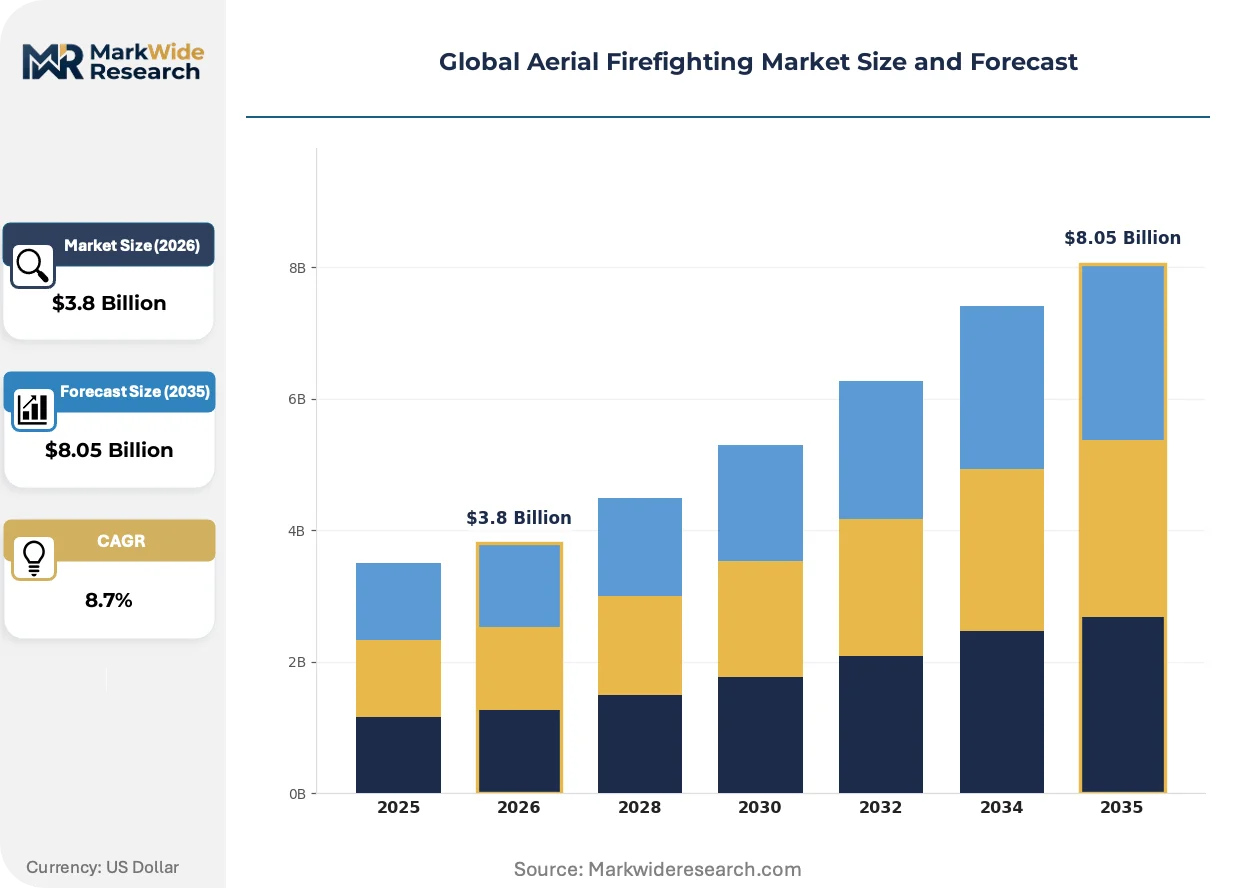
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Helicopters, Fixed-Wing Aircraft, Drones, Amphibious Aircraft Service Type: Fire Suppression, Reconnaissance, Support Services, Training Services Application Sector: Wildland Firefighting, Urban Firefighting, Forestry Management, Disaster Response Technology Used: Water Bombing, Retardant Dropping, Surveillance Technology, GPS Tracking |
| Companies Covered | Bridger Aerospace Group Holdings, Inc., Coulson Aviation, Lockheed Martin Corporation, Textron Inc., Avincis, Airbus, Leonardo S.p.A., Bombardier Inc., Boeing Commercial Airplanes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerial Firefighting Market Emerging Trajectories
Satellite-guided deployment systems and autonomous coordination platforms are compressing response latency from detection to first drop. These advances are redefining operational tempo expectations among high-volume procurement agencies.
Artificial intelligence-driven drop pattern optimization is digitizing retardant coverage accuracy through real-time wind modeling and terrain analysis. Cal Fire and Victoria's Country Fire Authority are deploying these systems across their heavy-tanker fleets this season. The technology is digitizing traditional pilot-intuitive positioning, reducing waste and improving line-building consistency on complex topography.
EASA's evolving CS-29 large-rotorcraft standards for firefighting modifications are tightening structural fatigue monitoring requirements. Manufacturers must now demonstrate extended service life under repetitive low-altitude stress cycles. European operators with mixed-age fleets face accelerated inspection intervals or platform retirement decisions.
Service contracting is consolidating around availability-based payment structures rather than per-flight-hour billing. State forestry agencies in California and Western Australia are leading this shift, transferring operational risk to fleet operators. This model demands predictive maintenance capabilities and captive spare parts inventories that smaller competitors cannot sustain.
Global Aerial Firefighting Market Segmentation
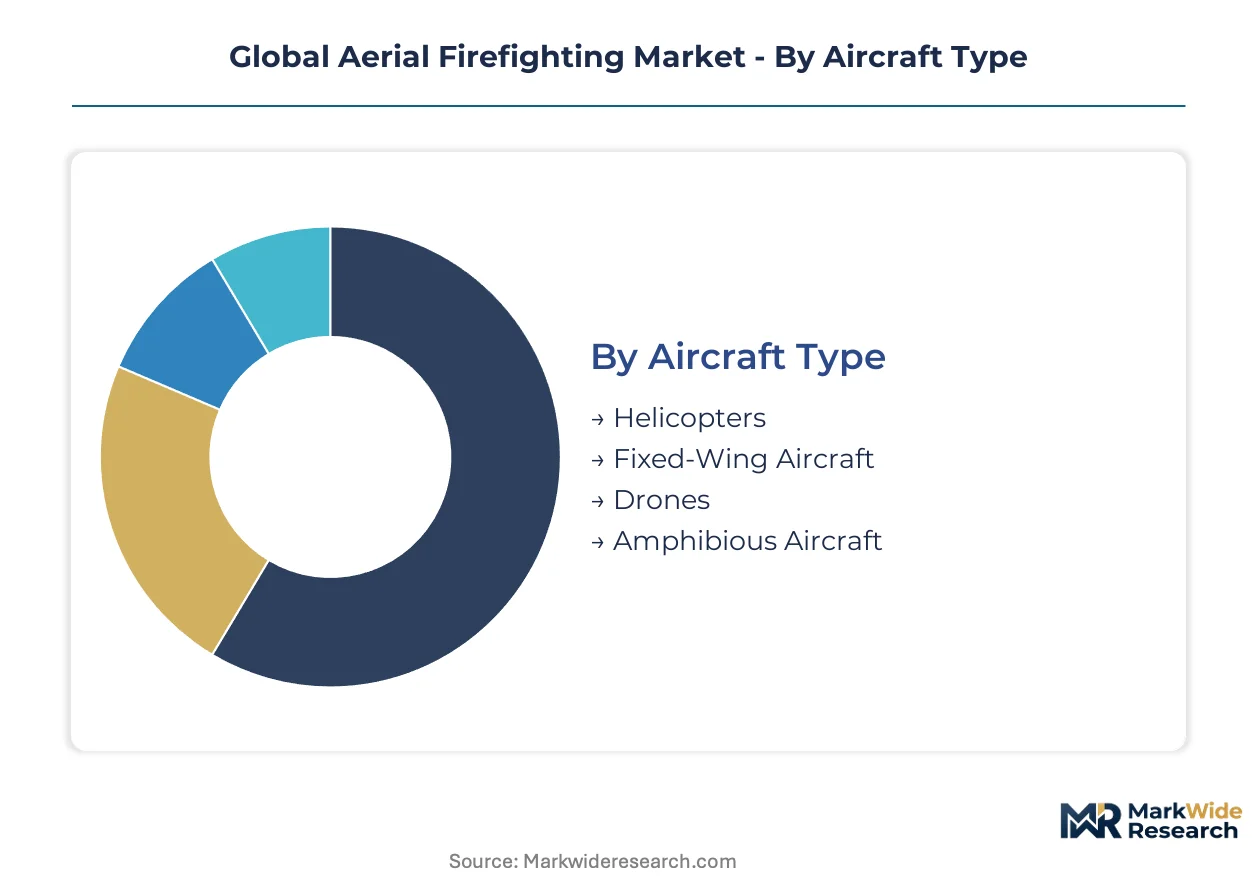
Aerial firefighting procurement decisions hinge on payload economics, mission duration, and terrain constraints. Platform selection varies sharply between sustained large-fire attack and rapid initial response scenarios. Understanding these segment boundaries clarifies why operators maintain heterogeneous fleet compositions rather than standardized platforms.
Aircraft Type:
Cost tier determines fleet composition for procurement agencies balancing acquisition capital against operational throughput.
- Fixed-Wing Aircraft:Turbine-powered platforms carry 1,200 to 8,000 gallons of retardant with extended loiter times over fire complexes. Cal Fire and Victoria's Country Fire Authority concentrate flight-hour contracts here for sustained attack missions.
- Helicopters:Rotary-wing systems offer precision bucket drops in confined terrain with 700 to 2,500-gallon capacities. Demand clusters in Australia's rugged southeastern ranges where mountain flying endorsements restrict pilot availability.
- Amphibious Aircraft:Scoopers retrieve 8,000 gallons of freshwater without ground turnaround. Mediterranean European agencies favor these for extended fire seasons along coastal zones.
- Drones:Unmanned systems penetrate smoke-obscured airspace for thermal mapping. Regulatory frameworks maturing in the United States and Australia are unlocking nighttime reconnaissance applications.
Fixed-wing platforms command the established base. The steepest expansion runs through drones as beyond-visual-line-of-sight protocols advance.
Service Type:
Application intensity varies by mission criticality and margin structure across operational categories.
- Fire Suppression:Direct retardant and water delivery captures the largest revenue pool through flight-hour guarantees. State forestry agencies in California and Western Australia are shifting toward ten-year availability contracts rather than transactional billing.
- Reconnaissance:Real-time thermal imaging and fire perimeter mapping commands superior margins per flight hour. Early drone adopters in this segment capture premium positioning before regulatory saturation.
- Support Services:Logistics coordination, fuel staging, and ground crew dispatch enable sustained multi-day campaigns. Integrated fleet management contracts bundle these functions under lifecycle cost predictability.
- Training Services:Low-altitude mountain flying certification and retardant delivery proficiency address pilot scarcity bottlenecks. Australia's CASA-mandated endorsements create specialized training demand.
Fire suppression anchors procurement budgets. Reconnaissance climbs the fastest as artificial intelligence-driven analytics reshape operational tempo expectations.
Application Sector:
Geography dictates seasonal concentration and contract renewal timing across mission profiles.
- Wildland Firefighting:Vegetation fire suppression across remote terrain consumes the majority of aerial deployment hours. Prolonged drought in California, Victoria, and Mediterranean Europe has stretched suppression windows from four to eight months annually.
- Forestry Management:Prescribed burns and fuel reduction operations utilize smaller platforms for controlled ignition support. State agencies in Western Australia integrate these missions into multi-year fleet contracts.
- Urban Firefighting:High-rise water delivery and rooftop retardant application serves dense municipal environments. Limited demand concentrates in Mediterranean coastal cities with wildland-urban interface exposure.
- Disaster Response:Post-wildfire flood mitigation and debris flow prevention repurposes aerial assets during off-peak intervals. Victoria's Country Fire Authority pilots seasonal contract flexibility for these secondary missions.
Wildland firefighting dominates fleet utilization. Forestry management gains share fastest as prescribed burn programs expand under climate adaptation strategies.
Technology Used:
Maturity gradients separate proven deployment methods from emerging precision systems.
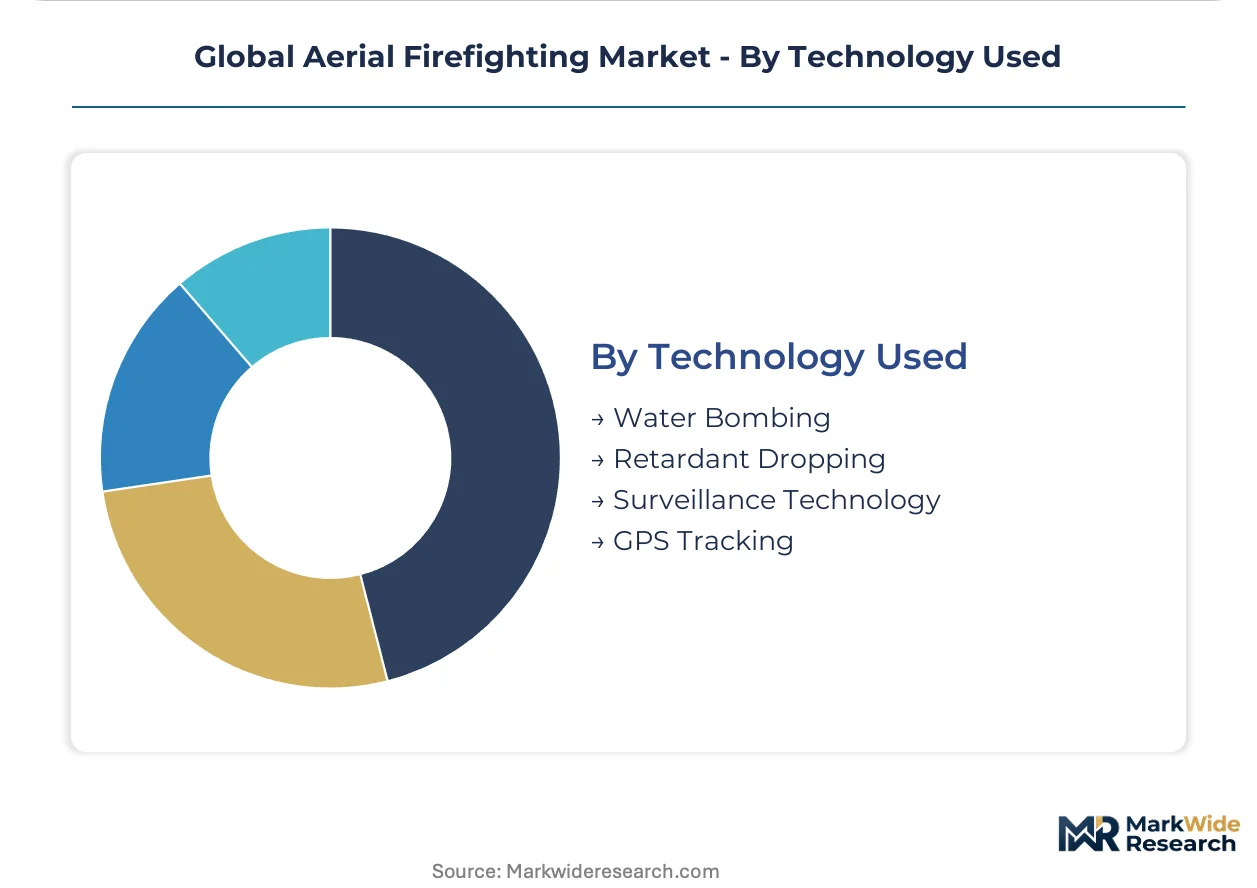
- Retardant Dropping:Phosphate-based formulations delivered through gravity-fed or pressurized tank systems remain the standard suppression method. ECHA toxicity reviews under REACH frameworks are restricting legacy formulations and forcing supplier reformulation investment.
- Water Bombing:Freshwater retrieval and delivery through bucket or tank systems serves initial attack and structure protection. Amphibious scooper efficiency gains are displacing smaller tanker-dependent models in high-volume procurement.
- Surveillance Technology:Infrared and multispectral imaging platforms detect heat signatures through smoke obscuration. Cal Fire's deployment of artificial intelligence-driven drop pattern optimization is digitizing traditional pilot-intuitive positioning.
- GPS Tracking:Satellite-guided deployment systems record drop patterns for coverage accuracy and regulatory compliance. EASA's evolving CS-25 and CS-29 standards are tightening data retention requirements for large-aircraft modifications.
Retardant dropping holds the installed base. Surveillance technology expands most quickly as real-time coordination platforms compress response latency from detection to first drop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive procurement in Mediterranean Europe contrasts with lifecycle-contract willingness in Australia and California. Buyers in Spain and Italy optimize for per-flight-hour economics. Agencies in Victoria and Sacramento prioritize availability guarantees over unit cost.
United States
Cal Fire operates the world's largest civilian aerial firefighting fleet from McClellan Airfield near Sacramento. FAA Part 137 modernization accelerates certification for converted military platforms. Pacific Northwest states Oregon and Washington are expanding multi-year contracts as fire seasons lengthen into November.
Australia
Victoria's Country Fire Authority leads Asia-Pacific procurement with ten-year integrated fleet management pilots. CASA enforces stringent low-altitude mountain flying endorsements that constrain pilot supply. New South Wales clusters heavy-lift helicopter contracts around Sydney and Canberra corridors.
Italy
Mediterranean coastal provinces favor amphibious scooper efficiency for extended summer campaigns. EASA CS-25 frameworks govern large-aircraft modifications for firefighting roles. Lombardy and Piedmont maintain mixed fleets balancing payload capacity with alpine terrain accessibility.
Spain
Andalusia and Valencia concentrate national aerial suppression hours during prolonged June-October fire windows. ECHA REACH toxicity reviews are forcing retardant formulation shifts among chemical suppliers. Madrid-based procurement agencies are piloting satellite-guided drop pattern optimization.
Canada
British Columbia and Alberta anchor national fleet utilization as boreal fire intensity escalates. Transport Canada aligns type certification with FAA Part 137 standards for cross-border operational compatibility. Quebec's SOPFEU coordinates eastern provincial capacity sharing during peak demand intervals.
Global Aerial Firefighting Market Vendor Landscape
Capability concentration sits with specialized conversion houses; scale advantage sits with diversified aerospace conglomerates. The vendor base separates into three functional tiers: purpose-built platform manufacturers, military-to-civilian conversion specialists, and integrated fleet operators. Dominant competitive moves include strategic partnerships for regulatory navigation and vertical integration into captive maintenance networks.
Among North American integrated operators, Coulson Aviation exemplifies the heavy-lift refurbishment specialist archetype across multiple continents. Lockheed Martin Corporation anchors the defense-technology tier through surveillance and command-and-control system integration. Textron Inc. occupies a diversified position spanning fixed-wing suppression and military conversion programs.
| Leading Market Players |
|---|
| Bridger Aerospace Group Holdings, Inc. |
| Coulson Aviation |
| Lockheed Martin Corporation |
| Textron Inc. |
| Avincis |
| Airbus |
| Leonardo S.p.A. |
| Bombardier Inc. |
| Boeing Commercial Airplanes |
| Others |
Supply Flow & Price Mechanics
Sacramento's McClellan Airfield cluster concentrates heavy-tanker refurbishment capacity for Cal Fire contracts, translating platform scarcity into premium availability pricing for state forestry agencies. This geographic chokepoint in specialized airframe conversion feeds directly into ten-year integrated fleet management premiums.
Pricing Analysis
Aftermarket service contracts now drive lifetime value as operators abandon per-flight-hour billing. Pricing stratifies across integrated lifecycle agreements, transactional spot charters, and availability-based retainers. Jet-A fuel volatility compresses margins for turbine fleets without hedging infrastructure. State procurement officers in Victoria and California demonstrate lowest price sensitivity, prioritizing guaranteed capacity over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and defense equipment suppliers constrains military-to-civilian conversion timelines. Airframe sourcing draws from Arizona boneyards, Canadian surplus auctions, and Australian defense drawdowns. Specialized retardant formulation rests on phosphate chemistry supply from Chinese and Moroccan producers. Single-source vulnerability sits with avionics retrofit kits certified under FAA Part 137. Distribution runs through operator-owned maintenance networks rather than third-party logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended fire seasons across California, Victoria, and Mediterranean Europe signal a cyclical upswing in aerial fleet procurement. State agencies are compressing multi-year contract cycles to lock capacity ahead of peak demand windows.
For Market Incumbents: Insulate market position through captive pilot training pipelines addressing Australia's CASA mountain-flying endorsement bottlenecks. Deepen backward integration into retardant formulation to offset ECHA REACH toxicity reformulation costs. Lock in ten-year availability contracts before regulatory saturation of drone reconnaissance erodes reconnaissance margins.
For New Entrants and Emerging Players: Pursue beyond-visual-line-of-sight drone certification in the United States and Australia where regulatory frameworks are maturing fastest. Target nighttime thermal mapping contracts before incumbent operators retrofit existing fleets. Lead with AI-driven drop pattern optimization as the differentiated go-to-market wedge against pilot-intuitive legacy positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors conversion specialists with EASA CS-25 expertise and established military surplus supply channels. Long-term viability hinges on regulatory navigation capability across FAA, EASA, and CASA jurisdictions. Watch BVLOS regulatory finalization timing as the inflection signal for unmanned system valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Fleet Management Contracting | Ten-year availability agreements with Victoria's Country Fire Authority transfer operational risk to operators. |
| Military Platform Conversion Program | EASA CS-25 certification for C-130 and CH-47 modifications unlocks defense surplus supply channels. |
| BVLOS Drone Regulatory Certification | FAA and CASA framework maturation enables nighttime reconnaissance margins before competitive saturation. |
| AI-Driven Drop Pattern Optimization | Cal Fire deployment of real-time wind modeling reduces retardant waste and improves line-building consistency. |
| Captive Pilot Training Pipeline | In-house CASA mountain-flying endorsement programs address certification scarcity constraining fleet expansion. |
Methodological Framework
Cross-validation between operator flight-hour records and state procurement databases anchors the qualitative findings. Primary interviews covered aerial fleet managers at Cal Fire and Victoria's Country Fire Authority, conversion specialists with EASA CS-25 expertise, retardant chemical suppliers facing ECHA reformulation mandates, and CASA-certified flight instructors. Secondary validation drew from FAA Part 137 certification filings, EASA CS-29 large-rotorcraft standards documentation, Australian defense surplus auction records, and state forestry agency contract award notices. Bottom-up platform deployment counts triangulate against top-down state budget appropriations for aerial suppression.
Calibration against historical fleet utilization patterns and contract renewal cycles shapes the analytical framework. Segmentation dimensions span aircraft type, service category, application sector, and technology tier across the projection horizon. CAGRs derive from fitted trend lines through documented flight-hour growth and procurement budget trajectories. Forecast inputs incorporate fire season length extension patterns and regulatory approval timeline assumptions for unmanned system integration.
Macroeconomic conditions sit as an overlay; deviation in Jet-A fuel pricing, defense surplus release schedules, or REACH toxicity threshold rulings would shift the trajectory. Forecasts embed assumptions about regulatory framework maturation and climate-intensified fire season persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
China Chartered Air Transport Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Flying Taxi Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Hang Glider Market
Air Mobility
Offshore Helicopter Services Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Asia-Pacific Military Aviation Market