
 Global Aerospace Metal Closed-Die Forging Market | 2026-2036
Global Aerospace Metal Closed-Die Forging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Metal Closed-Die Forging Market Analysis
North American specialty steel producers is restructuring capacity allocation toward aerospace-grade nickel and titanium alloys. Precision Castparts Corp. leverages captive titanium melt capacity to control feedstock costs for engine disc programs. Alcoa Corporation anchors aluminum-lithium forging supply for narrowbody wing structures. Thyssenkrupp AG competes through isothermal forging expertise on large landing gear components.
Aerospace metal closed-die forging shapes high-strength alloys under compressive force within precision-machined dies, typically achieving grain flow alignment that exceeds cast mechanical properties by 30-50% in fatigue resistance. The process serves critical rotating and structural components where failure modes demand metallurgical consistency. Titanium alloys command premium positioning due to thrust-specific fuel efficiency requirements in next-generation turbofans, while aluminum alloys sustain volume leadership through single-aisle fuselage and wing programs. Hot forging dominates current output, though isothermal forging captures margin expansion on complex nickel superalloy engine components where near-net-shape yield improvements justify longer cycle times.
FAA certification under 14 CFR Part 25 and EASA CS-25 airworthiness codes mandate lot-level chemical and mechanical testing, effectively restricting qualified supplier pools. China's NMPA-equivalent airworthiness authority and GB standards are converging toward Western material qualification protocols to support COMAC C919 and CR929 programs. Stakeholders must monitor dual-use export control expansions affecting titanium sponge and nickel powder flows, as supply assurance now shapes procurement strategy as directly as unit cost.
Market Dynamics
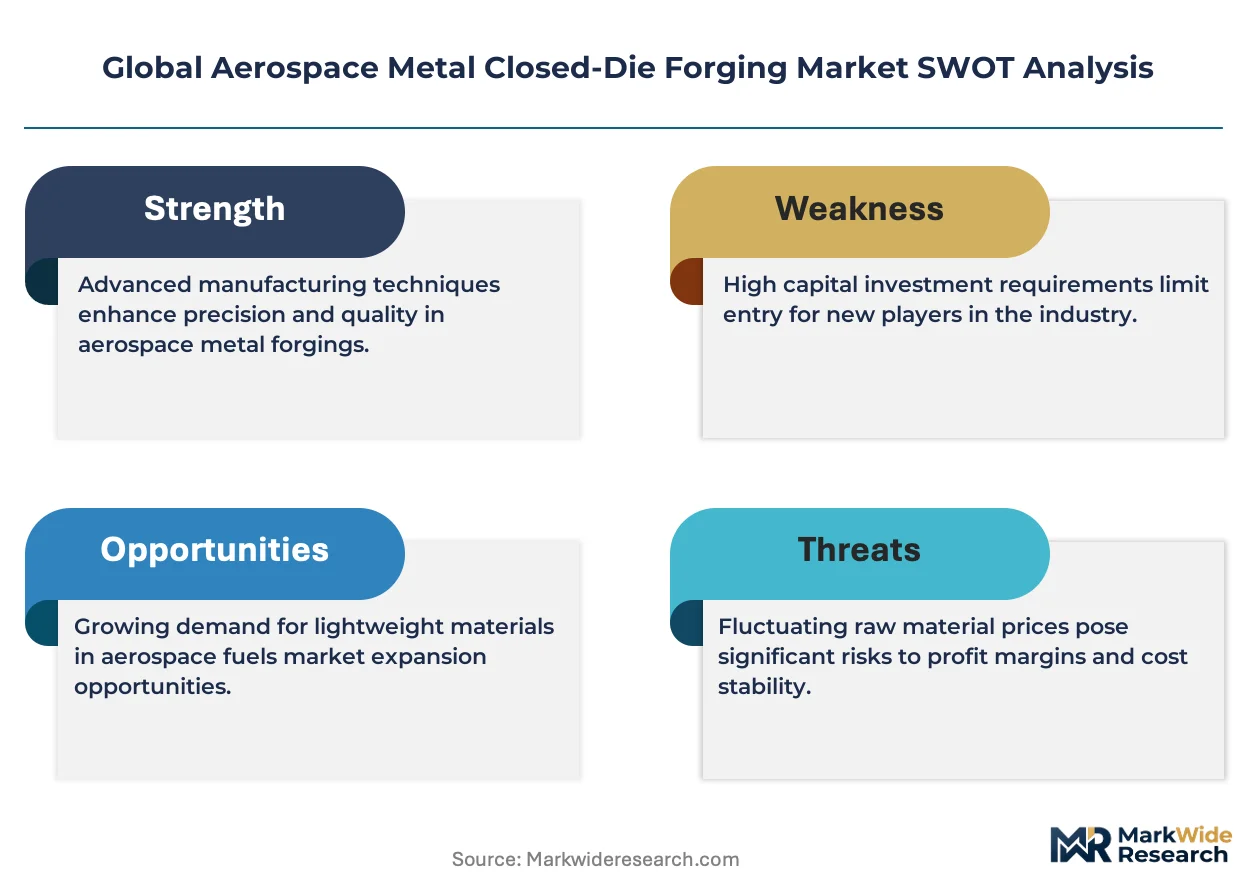
FAA airworthiness certification under 14 CFR Part 25 and EASA CS-25 mandates are compressing qualified supplier pools for aerospace-grade forgings, forcing tier-one OEMs to consolidate procurement relationships around vertically integrated metallurgical houses with captive melt capacity.
Growth Catalysts
- Thrust-specific fuel efficiency mandates:Next-generation turbofan architectures require titanium alloy engine discs with superior fatigue resistance, pulling demand toward closed-die forging over cast alternatives.
- China's GB standards convergence:COMAC C919 and CR929 programs are adopting Western material qualification protocols, opening certification pathways for qualified foreign suppliers.
- Isothermal forging yield improvements:Near-net-shape forming of nickel superalloy components reduces machining waste by half on complex engine geometries.
Market Restraints
- Titanium sponge supply concentration:Dual-use export controls on Russian and Chinese sponge sources restrict feedstock availability for Western forgers.
- Lot-level testing overhead:FAA and EASA chemical and mechanical certification requirements add eighteen to twenty-four months to new supplier qualification timelines.
- Additive manufacturing substitution:Powder-bed fusion processes for small titanium brackets are displacing forged alternatives below fifteen kilogram finished weight.
Strategic Opportunities
- India's defense aerospace expansion:Hindustan Aeronautics Limited procurement reforms are creating first-tier forging demand for combat aircraft and helicopter programs.
- Digital thread integration:Blockchain-enabled material traceability is converging with automated forging press controls to compress certification documentation cycles.
- Sustainable aviation fuel compatibility:EASA and FAA mandates for SAF-ready engine architectures are accelerating demand for heat-resistant nickel superalloy turbine components.
Industry Challenges
- Isothermal press operator scarcity:Specialized technicians capable of managing thermal gradients in nickel superalloy forging cycles command wage premiums exceeding forty percent above conventional hot forging roles.
- Legacy ERP integration friction:AS9100D quality management system requirements clash with digital twin implementations at mid-cap forgers, delaying Industry 4.0 adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Metal Closed-Die Forging Market |
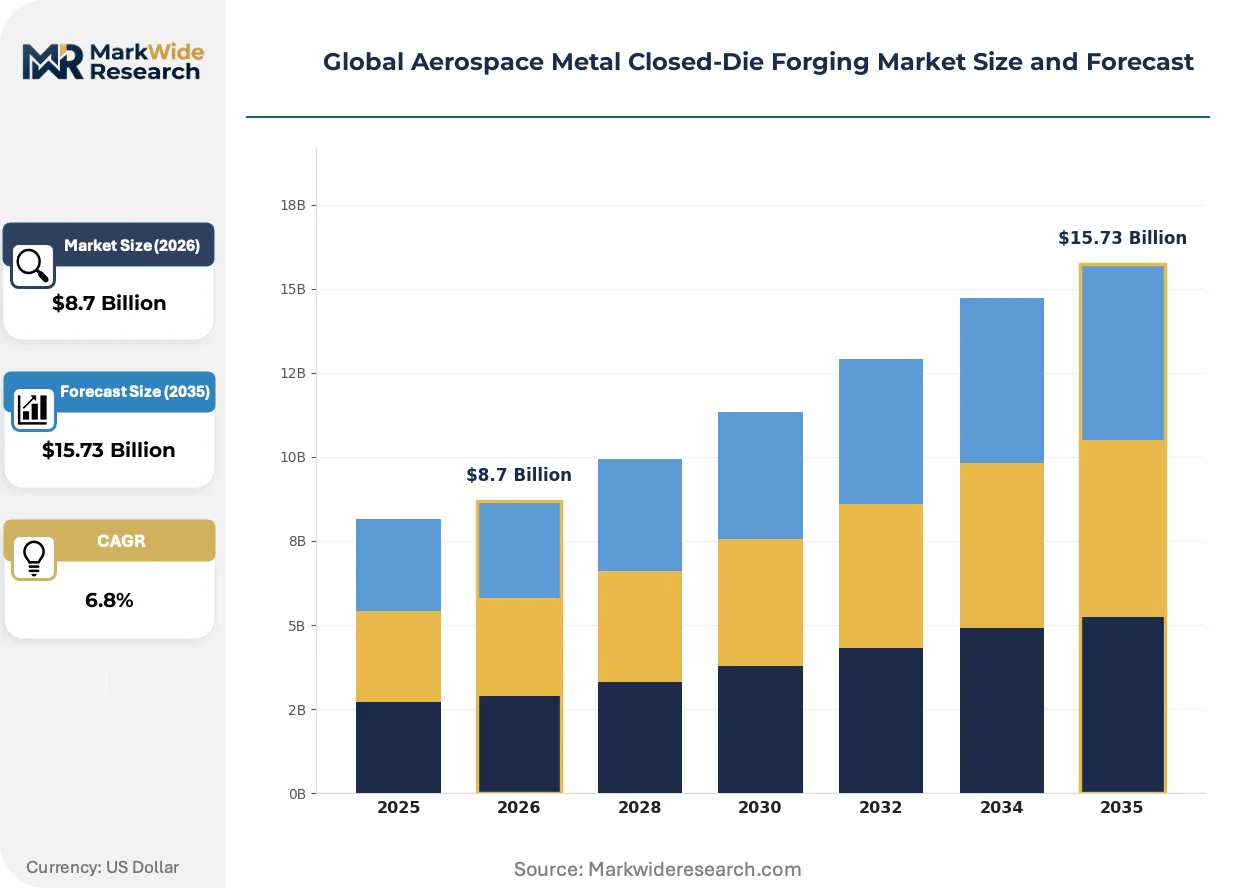
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Alloys, Titanium Alloys, Steel Alloys, Nickel Alloys Manufacturing Stage: Raw Material Processing, Intermediate Forming, Final Forging, Surface Treatment End User: Aerospace OEMs, Tier-1 Suppliers, Defense Contractors, Aftermarket Providers Technology: Hot Forging, Cold Forging, Isothermal Forging, Precision Forging |
| Companies Covered | Precision Castparts Corp., Alcoa Corporation, Allegheny Technologies Incorporated, Kobe Steel Ltd, Bharat Forge Ltd., VSMPO-AVISMA Corporation, Thyssenkrupp AG, Nippon Steel Corporation, Otto Fuchs KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Metal Closed-Die Forging Market Emerging Trajectories
Digitalization of forging process control is compressing development cycles for aerospace-grade components. Real-time thermal monitoring and predictive die wear algorithms are displacing empirical process optimization.
Isothermal forging technology is converging with automated robotic die handling to enable single-piece flow for large nickel superalloy engine casings. Pratt & Whitney and Rolls-Royce procurement teams are qualifying these lines for next-generation geared turbofan programs. The structural consequence is margin compression for conventional hot forging houses lacking thermal gradient control capability.
EASA's expanding MDR material traceability requirements are forcing tier-two forgers to implement lot-level digital genealogy systems. The regulation mandates blockchain-anchored certificates of analysis for titanium and nickel alloy inputs. European engine OEMs are responding by pre-qualifying only suppliers with integrated melt-to-forge digital thread infrastructure.
Long-term service agreements are displacing spot purchasing for critical rotating components. Airlines and lessors now contract directly with forgers for engine disc replacement schedules, bypassing traditional distributor networks. This pattern is most visible in North American and Middle Eastern carrier fleets operating high-cycle narrowbody routes.
Global Aerospace Metal Closed-Die Forging Market Segmentation
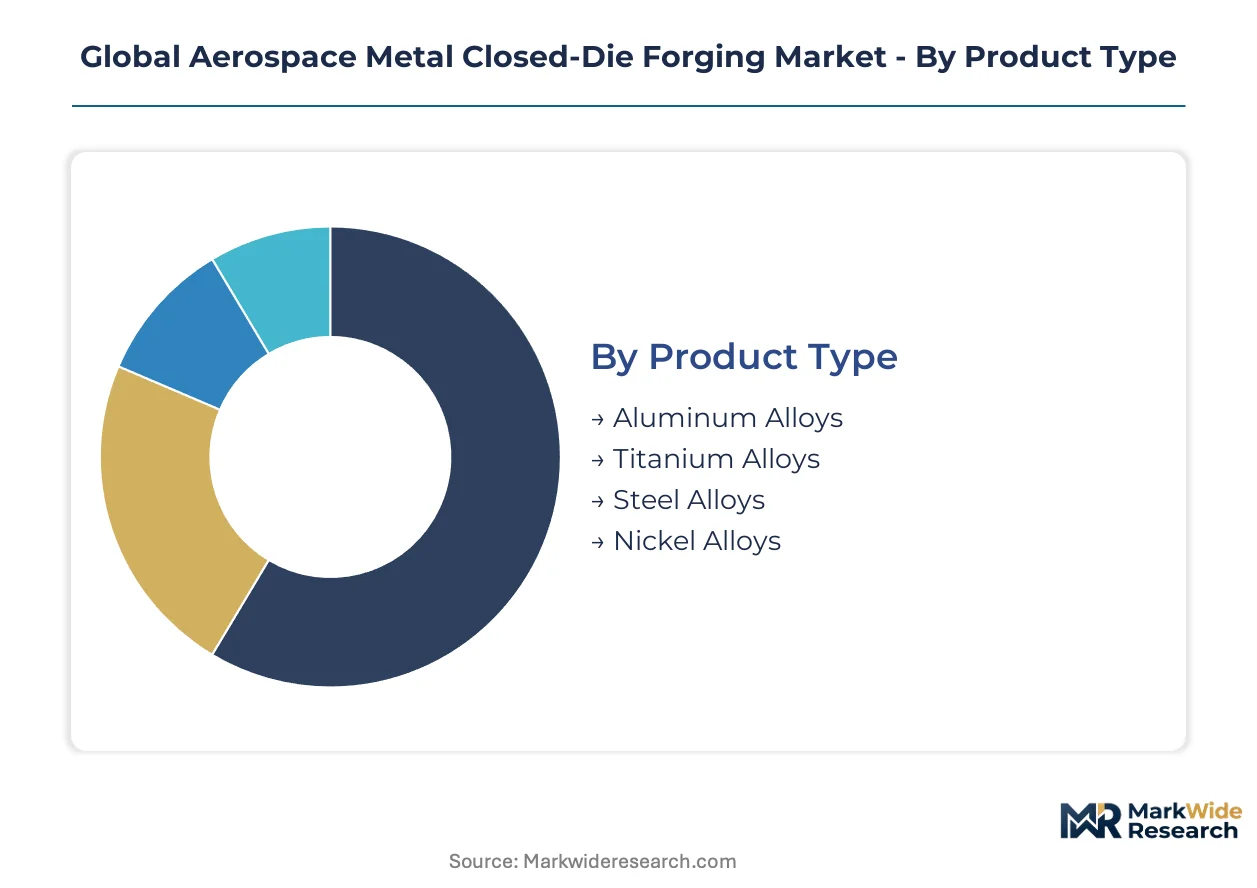
Closed-die forging procurement patterns diverge sharply across alloy systems and manufacturing stages. OEM qualification requirements and feedstock availability shape where suppliers concentrate their metallurgical investments.
Product Type:
Supply concentration tilts toward titanium and nickel alloy producers with captive melt capacity, as these segments command premium positioning through airframe and engine OEM qualification barriers.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades dominate high-pressure compressor discs and fan blades. Pratt & Whitney's GTF program and Rolls-Royce UltraFan architectures pull demand toward closed-die forging over cast alternatives. Dual-use export controls on sponge sources constrain Western supply expansion.
- Nickel Alloys:Inconel 718 and Rene 41 formulations serve turbine disks and combustion casings requiring creep resistance above 650°C. Isothermal forging yield improvements justify longer cycle times for these components. GE Aerospace and Safran Landing Systems anchor procurement in the United States and France.
- Aluminum Alloys:Aluminum-lithium 2195 and 2050 variants sustain narrowbody wing skin and fuselage frame programs through single-aisle production ramps.
- Steel Alloys:300M and AerMet 100 grades concentrate in landing gear applications where fracture toughness requirements exceed aluminum capabilities.
Today's leader: Titanium Alloys. Tomorrow's challenger: Nickel Alloys.
Manufacturing Stage:
Cost tier differentiation separates integrated metallurgical houses from specialized forging-only operations, with margin capture concentrating at stages controlling thermal process parameters.
- Final Forging:Precision-machined die closure under 10,000-ton presses determines grain flow alignment and mechanical property consistency. FAA and EASA lot-level testing mandates restrict qualified supplier pools to operations with integrated melt-to-forge traceability. Germany's Thyssenkrupp and United States-based Precision Castparts Corp. anchor this stage.
- Raw Material Processing:Vacuum arc remelting and electroslag remelting of titanium and nickel ingots establishes chemical uniformity foundations. Russian and Chinese sponge concentration creates supply assurance risks for Western forgers.
- Intermediate Forming:Open-die preforming and ring rolling reduce material input weights before closed-die finishing.
- Surface Treatment:Shot peening and chemical milling address residual stress management and dimensional refinement.
Margin capture peaks at Final Forging. Supply risk concentrates at Raw Material Processing.
End User:
Customer type determines contract structure, with long-term service agreements displacing spot purchasing for high-cycle rotating components.
- Aerospace OEMs:Boeing, Airbus, and COMAC direct procurement for wing and fuselage structural programs. These customers mandate AS9100D quality systems and digital thread traceability from qualified suppliers.
- Tier-1 Suppliers:Collins Aerospace and GKN Aerospace intermediate between forgers and airframers, consolidating volume across multiple OEM platforms.
- Defense Contractors:Lockheed Martin F-35 and B-21 programs sustain classified forging demand with distinct material qualification protocols.
- Aftermarket Providers:Engine disc replacement schedules now contract directly with forgers, bypassing traditional distributor networks in North American and Middle Eastern carrier fleets.
Contract security favors Aerospace OEMs. Growth velocity sits with Aftermarket Providers.
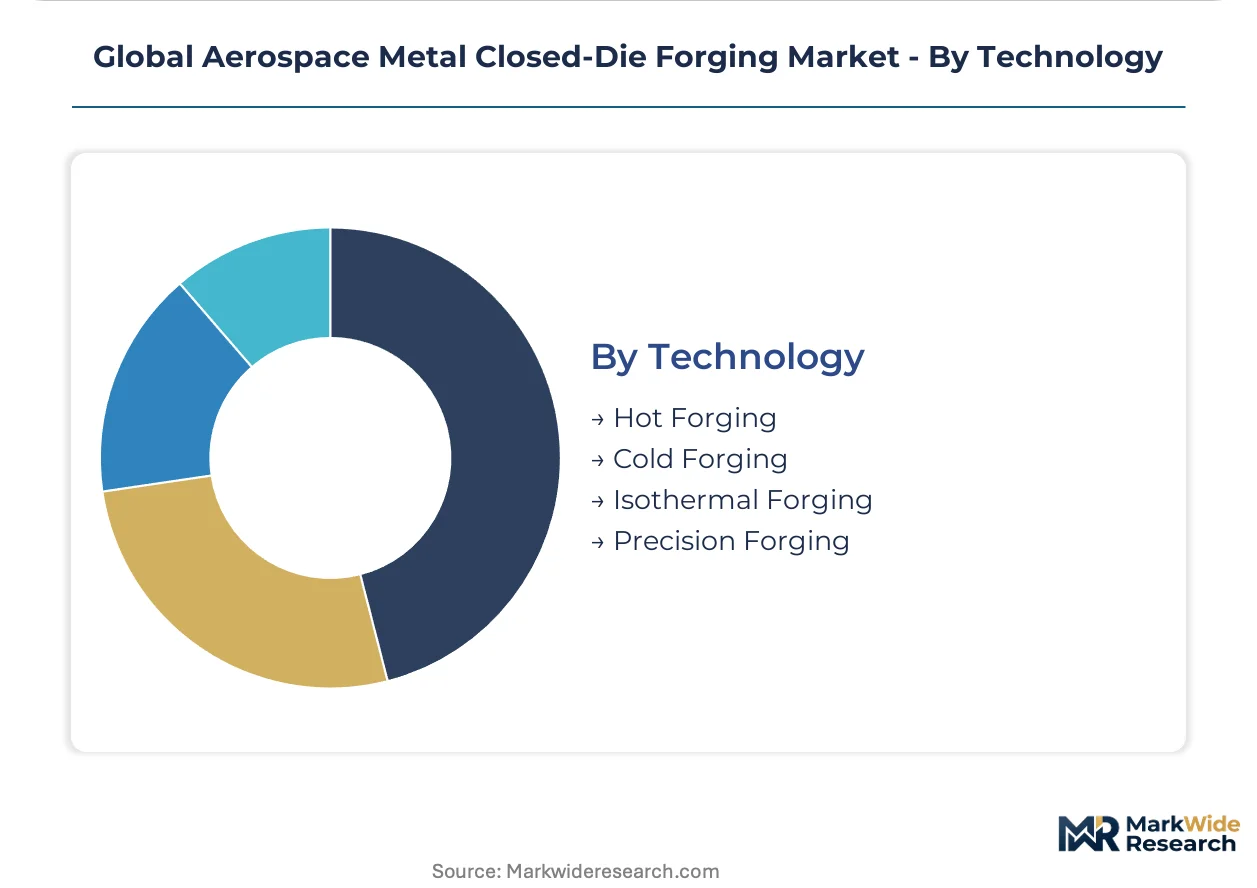
Technology:
Maturity gradients separate established hot forging capacity from emerging isothermal installations requiring specialized thermal gradient control expertise.
- Isothermal Forging:Near-net-shape forming of nickel superalloy components reduces machining waste by half on complex engine geometries. Robotic die handling enables single-piece flow for large casings. Operator scarcity commands wage premiums exceeding forty percent above conventional roles.
- Hot Forging:Conventional above-recrystallization-temperature processing dominates current output volume across aluminum and titanium airframe components. Legacy press infrastructure sustains cost competitiveness for simpler geometries.
- Precision Forging:Tighter dimensional tolerances reduce downstream machining requirements for brackets and fittings.
- Cold Forging:Limited aerospace application due to alloy work-hardening constraints; concentrates in fastener and small bracket production.
Volume leadership: Hot Forging. Capability differentiation: Isothermal Forging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA and EASA certification costs are widening the compliance gap between Western and Asian production bases, redirecting investment flows toward jurisdictions with qualified metallurgical infrastructure and converging airworthiness standards.
United States
Boeing's 737 MAX and 777X production ramps sustain demand for titanium engine discs and aluminum-lithium wing structures. FAA 14 CFR Part 25 mandates enforce lot-level traceability from melt to forge, compressing qualified supplier pools. Wichita's aviation cluster hosts specialized forging operations serving Pratt & Whitney GTF programs.
Germany
Airbus Hamburg and Bremen final assembly lines pull precision forgings for single-aisle fuselage frames. EASA CS-25 material qualification protocols align with MDR traceability requirements for titanium and nickel alloy inputs. Thyssenkrupp's isothermal forging expertise concentrates in North Rhine-Westphalia for landing gear and engine casing programs.
China
COMAC C919 certification progress and CR929 widebody development are adopting GB standards converging toward Western material protocols. NMPA-equivalent airworthiness authority reforms open pathways for qualified foreign suppliers. Xi'an and Chengdu aerospace clusters are expanding domestic forging capacity for military and civil programs.
Japan
Mitsubishi Heavy Industries and IHI Corporation anchor demand for nickel superalloy turbine components in next-generation turbofan development. METI industrial standards support precision forging investments for heat-resistant alloys. Nagoya's aerospace corridor concentrates specialized operations serving Boeing and Airbus tier-1 supply chains.
India
Hindustan Aeronautics Limited procurement reforms are creating first-tier forging demand for Tejas combat aircraft and Dhruv helicopter programs. DGFT dual-use export control frameworks are evolving to balance indigenous capability building with technology access. Bangalore and Hyderabad defense aerospace clusters are qualifying domestic forging suppliers for strategic programs.
Global Aerospace Metal Closed-Die Forging Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue isothermal forging capability and digital thread integration as differentiation vectors. The supplier base concentrates around vertically integrated metallurgical houses with captive melt capacity and tier-two specialized forgers dependent on external feedstock. Three archetypes dominate: integrated titanium-nickel alloy producers controlling upstream sponge and powder sources; aluminum-lithium specialists serving narrowbody airframe programs; and isothermal forging houses capturing margin on complex engine geometries. Competitive moves center on backward integration into vacuum arc remelting capacity and strategic partnerships with engine OEMs for long-term service agreements.
Among North American integrated producers, Precision Castparts Corp. and Alcoa Corporation exemplify the captive-melt archetype, with geographic naming anchoring their positions in specialty alloy supply. Allegheny Technologies Incorporated occupies a position within the nickel superalloy tier, its corporate structure reflecting diversified metallurgical operations. These three entities represent the consolidation pattern where qualification barriers and certification timelines protect incumbent positions against new market entry.
| Leading Market Players |
|---|
| Precision Castparts Corp. |
| Alcoa Corporation |
| Allegheny Technologies Incorporated |
| Kobe Steel Ltd |
| Bharat Forge Ltd. |
| VSMPO-AVISMA Corporation |
| Thyssenkrupp AG |
| Nippon Steel Corporation |
| Otto Fuchs KG |
| Others |
Supply Flow & Price Mechanics
Isothermal forging capability gaps between certified engine disc suppliers and commodity airframe forgers manifest in divergent margin structures and captive melt investments. FAA and EASA lot-level testing mandates compress qualified supplier pools, enabling premium capture at integrated titanium-nickel houses while aluminum-lithium specialists face spot-price volatility from Russian sponge diversion.
Pricing Analysis
Distributor margins on forged engine components collapsed as Pratt & Whitney and Rolls-Royce procurement teams shifted to direct long-term service agreements with metallurgical houses. Three-tier pricing structure across isothermal-forged nickel superalloys, hot-forged titanium discs, and commodity aluminum brackets reflects certification grade and captive remelt capacity. Price erosion runs through standard-tier aluminum-lithium wing skins as COMAC C919 production ramps concentrate volume with qualified Chinese domestic suppliers. Aftermarket providers operating high-cycle narrowbody fleets exhibit lowest price sensitivity due to non-negotiable airworthiness replacement schedules.
Supply Chain Analysis
Titanium sponge feedstock rests on Russian and Chinese export-controlled sources, constraining Western forger expansion regardless of press capacity. Vacuum arc remelted ingots and electroslag refined nickel powders draw from United States, Germany, and Japan specialty alloy producers. Single-source vulnerability concentrates at the sponge-to-ingot conversion stage where dual-use licensing delays cascade through eighteen-month qualification timelines. Distribution runs through tier-one aerospace OEMs and engine manufacturer procurement teams rather than traditional metals distributors, compressing channel layers for critical rotating components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EASA MDR traceability investments in European forgers and China's GB standards convergence costs, with regulatory compliance differential exceeding capital equipment outlays for isothermal press installations.
For Market Incumbents: To counter additive manufacturing substitution below fifteen-kilogram brackets, Precision Castparts Corp. and Alcoa Corporation should deepen backward integration into vacuum arc remelting capacity while locking long-term sponge supply through strategic offtake with non-Russian sources. Certification moats around FAA 14 CFR Part 25 qualified supplier pools protect margin structures against emerging Asian competitors. For New Entrants and Emerging Players: Digital thread integration for blockchain-anchored material genealogy offers entry wedge into EASA MDR-compliant European supply chains where legacy ERP friction delays Industry 4.0 adoption at mid-cap forgers. Target India's defense aerospace expansion through Hindustan Aeronautics Limited procurement reforms, qualifying domestic forging capacity for Tejas and Dhruv programs before Western incumbents establish local joint ventures. For Investors and Strategic Acquirers: Consolidation pressure builds where isothermal forging operator scarcity commands forty-percent wage premiums and captive melt capacity separates profitable engine disc suppliers from margin-compressed airframe forgers. Five-to-ten-year viability favors vertically integrated titanium-nickel houses with digital thread infrastructure over specialized forging-only operations dependent on external feedstock. Watch COMAC C919 certification progress as inflection signal for Chinese domestic supplier qualification pathways opening to qualified foreign metallurgical houses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Arc Remelting | Captive titanium and nickel ingot supply secures feedstock against Russian sponge export controls. |
| Digital Thread Infrastructure Deployment | Blockchain-anchored lot-level traceability compresses EASA MDR certification documentation cycles. |
| Isothermal Forging Capacity Expansion | Near-net-shape nickel superalloy forming captures margin on GE Aerospace and Safran engine programs. |
| Long-Term Service Agreement Structuring | Direct airline and lessor contracts bypass distributor networks on high-cycle narrowbody disc replacement. |
| India Defense Aerospace Qualification | Hindustan Aeronautics Limited procurement reforms create first-tier forging demand outside Western OEM channels. |
Methodological Framework
Direct dialogue with forging plant managers, aerospace OEM procurement executives, FAA certification specialists, and specialty alloy R&D directors grounded qualitative findings in operational reality. Secondary validation drew from EASA CS-25 airworthiness filings, FAA 14 CFR Part 25 certification databases, customs trade data on titanium sponge flows, and SEC 10-K disclosures from listed metallurgical houses. Bottom-up segment sizing across alloy systems, manufacturing stages, and end-user categories triangulated against top-down aerospace production forecasts from Boeing and Airbus delivery schedules.
Top-down demand modeling from turbofan engine production ramps and airframe delivery schedules anchored volume projections across the analysis window. Segmentation dimensions spanned alloy grade tier, forging technology type, OEM versus aftermarket demand split, and regional regulatory cluster. CAGRs derived from fitted growth curves on qualified supplier capacity expansion, adjusted for dual-use export control friction on feedstock availability. Industry-specific inputs included Pratt & Whitney GTF and Rolls-Royce UltraFan procurement timelines, COMAC C919 certification milestones, and EASA MDR implementation phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium sponge supply diversion, additive manufacturing substitution rates, and Chinese airworthiness authority convergence timing. Assumptions reflect current FAA and EASA certification timelines, qualified supplier pool composition, and engine OEM sourcing strategies. A small set of triggers warrants ongoing watch: COMAC C919 entry-into-service pace, Russian sponge export license renewals, and isothermal forging technician training pipeline expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Middle-East and Africa Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Composites Market