
 United Kingdom Rotor Blade Market | 2026-2036
United Kingdom Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Rotor Blade Market Insights
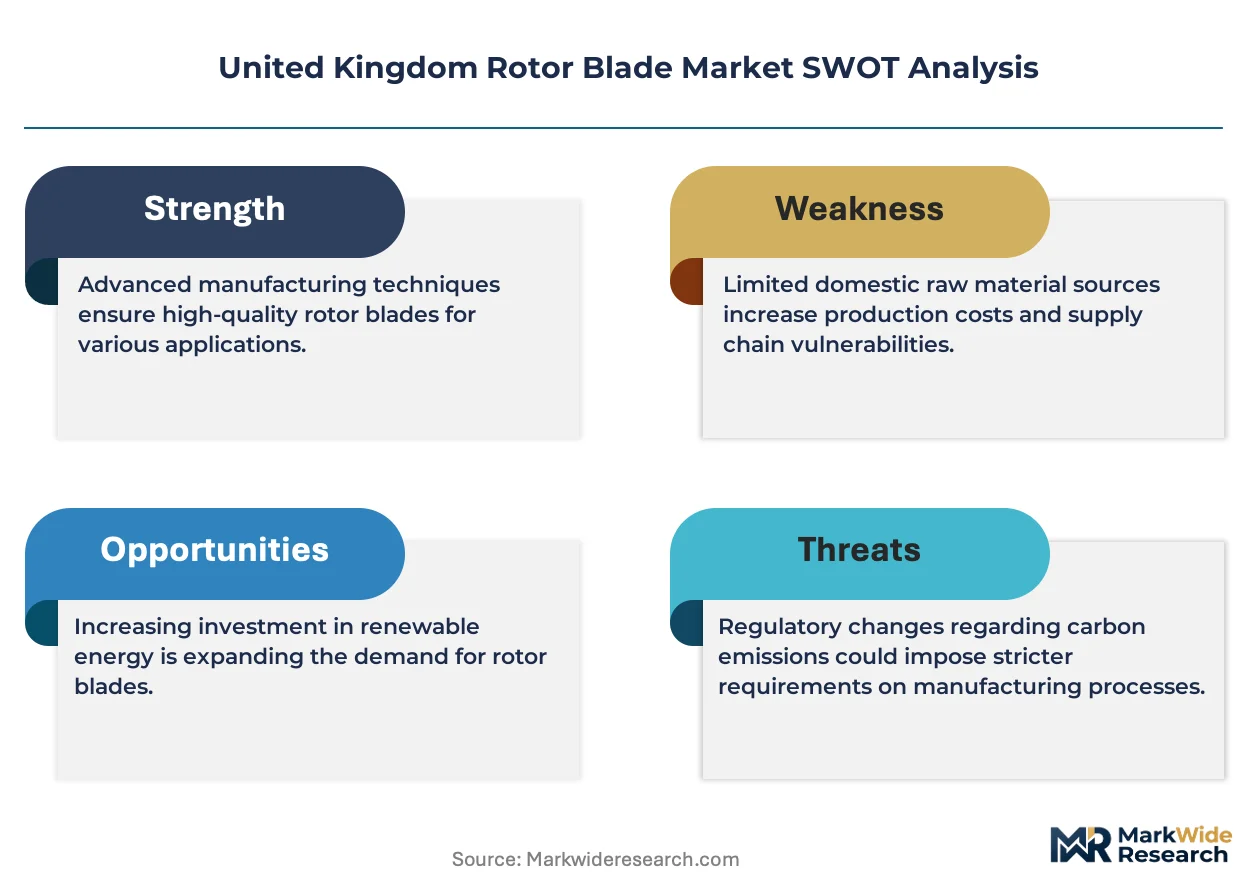
Glass fiber is shifting toward carbon fiber hybrid laminates in United Kingdom rotor blade fabrication, reducing weight while extending fatigue life. Vestas Wind Systems A/S leverages its Isle of Wight testing facility to validate next-generation airfoil designs. Siemens Gamesa Renewable Energy S.A. anchors blade supply through its Hull manufacturing plant, the country's largest such facility. LM Wind Power specializes in longer offshore-optimized blades that dominate Scottish lease round allocations.
A rotor blade is an aerodynamic lifting surface comprising fiber-reinforced polymer skins bonded to a structural spar, typically spanning 50-120 meters for utility-scale wind turbines and engineered to convert kinetic wind energy into rotational mechanical power. Horizontal axis configurations command the installed base across UK offshore arrays, while composite materials capture the dominant share of bill-of-materials value due to their specific strength and corrosion resistance. The energy end user segment absorbs the majority of domestic output, though UAV applications are gaining traction from defense contractors seeking indigenous supply chains.
Maritime and Coastguard Agency offshore construction standards intersect with Health and Safety Executive workplace regulations to govern blade transport, installation, and end-of-life protocols across British waters. The Environment Agency's evolving waste framework is pressing manufacturers toward thermoplastic resin systems and blade recycling infrastructure. Stakeholders must track how the UK's net-zero steelmaking transition affects tower-blade nacelle cost ratios and whether Scottish port expansion keeps pace with blade length growth.
Market Dynamics
The United Kingdom rotor blade market is being fundamentally restructured by the Environment Agency's evolving waste framework, which is forcing manufacturers to abandon thermoset resins and build circular supply chains before landfill bans take full effect.
Growth Catalysts
- Contracts for Difference scheme:The UK government's price guarantee mechanism de-risks capital deployment for offshore wind developers, directly translating into firm blade procurement schedules from Scottish North Sea lease holders.
- Carbon fiber hybrid laminates:Glass fiber substitution is reducing blade mass by 15-20% while extending fatigue life, enabling longer rotors that capture more energy per installed turbine.
- East Coast cluster concentration:England's offshore wind pipeline around Hull and Great Yarmouth is creating localized demand density that justifies dedicated manufacturing capacity and specialized logistics infrastructure.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock exposure creates margin compression for blade manufacturers locked into fixed-price supply agreements with wind farm developers.
- Scottish port bottleneck:Aberdeen and Peterhead lack sufficient quayside depth and laydown area for 120-meter blade handling, forcing costly transhipment through continental European ports.
- Blade recycling infrastructure gap:Thermoset composite shredding capacity remains underdeveloped across British industrial zones, creating stranded asset risk as landfill diversion deadlines approach.
Strategic Opportunities
- Wales Celtic Sea leases:The Crown Estate's emerging leasing rounds off Pembrokeshire and Lundy present untapped demand for next-generation floating foundation-compatible blade designs.
- Defense UAV applications:Ministry of Defence contractors are sourcing indigenous composite rotor solutions for unmanned aerial systems, diversifying revenue beyond energy sector dependence.
- Thermoplastic resin transition:Recyclable thermoplastic composites enable end-of-life material recovery, aligning with Environment Agency circular economy mandates while reducing manufacturing cycle times.
Industry Challenges
- Composite technician scarcity:Vacuum infusion and automated fiber placement skills are concentrated among a shrinking cohort of aerospace-trained engineers, constraining production scaling.
- Maritime and Coastguard Agency certification timelines:Offshore blade transport vessel approvals require 18-24 month validation cycles, misaligning with construction schedules.
- Health and Safety Executive workplace exposure limits:Styrene and cobalt compound handling restrictions are forcing process re-engineering at established manufacturing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Rotor Blade Market |
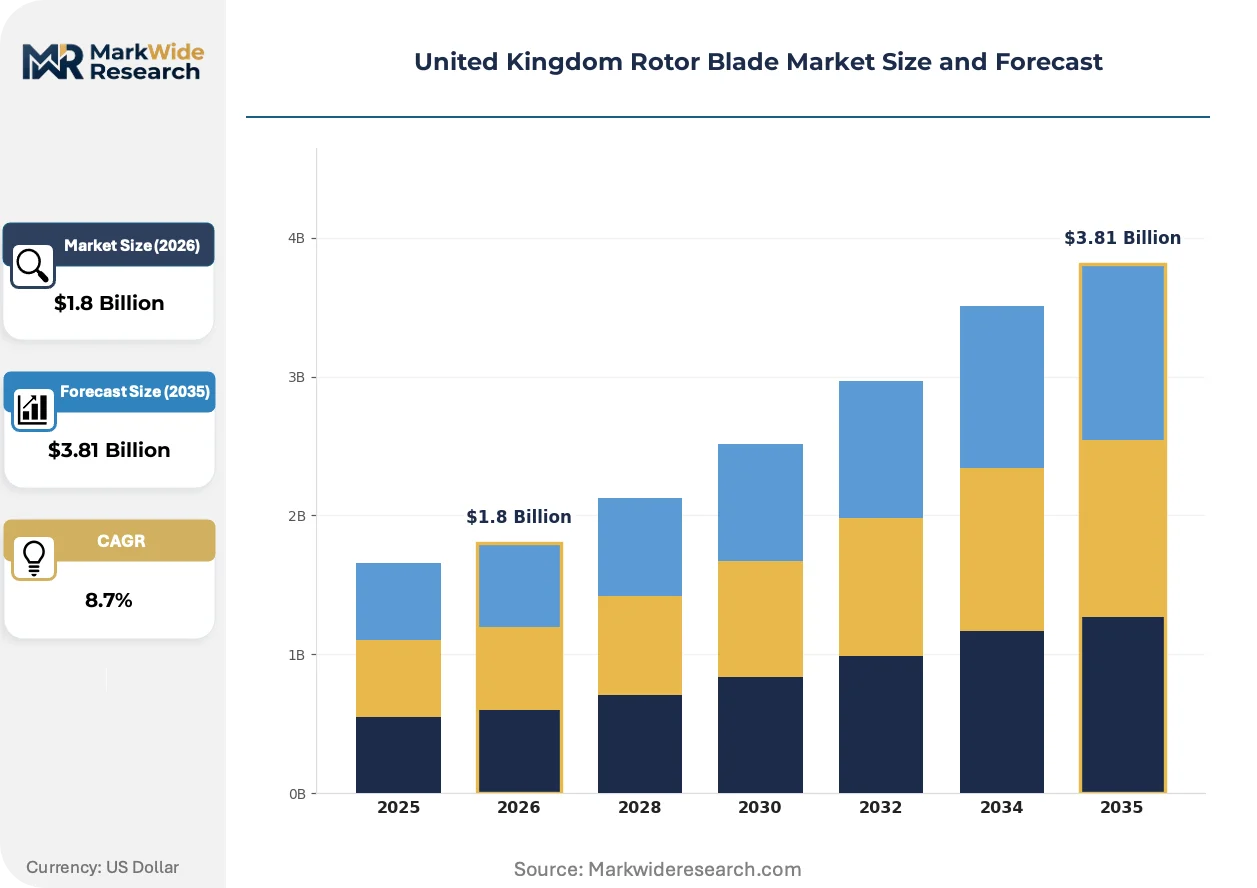
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Axis, Horizontal Axis, Tandem, Coaxial Material: Composite, Metal, Wood, Alloy End User: Aerospace, Energy, Defense, Industrial Application: Wind Energy, UAV, Marine, Biomedical |
| Companies Covered | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy S.A., Nordex SE, Orsted A/S, Vattenfall AB, GE Renewable Energy, LM Wind Power, TPI Composites, Siemens Gamesa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Rotor Blade Market Trends and Innovations
Material science advances and regulatory pressure on end-of-life accountability are converging to transform how United Kingdom rotor blades are designed, fabricated, and recovered. Three developments are restructuring competitive positioning.
Carbon fiber hybrid laminates are consolidating their position as the dominant structural solution for blades exceeding 90 meters. Offshore wind farm operators in Scottish waters are specifying these materials for all new lease round allocations. The technology is consolidating supplier relationships around firms with captive carbon fiber supply agreements and autoclave processing capability.
Environment Agency waste framework revisions are mandating producer responsibility for blade disposal, with landfill diversion targets tightening through 2030. Manufacturers are responding by piloting thermoplastic resin systems and mechanical recycling partnerships with Yorkshire-based composite processors. Hull manufacturing facilities face the steepest compliance curve due to their production volume exposure.
Service unbundling is separating blade inspection and repair contracts from original equipment supply agreements. Independent service providers are capturing aftermarket revenue from operational offshore arrays, displacing manufacturer-captive maintenance divisions. This pattern is most pronounced in the North Sea, where blade leading edge erosion creates recurring intervention demand.
United Kingdom Rotor Blade Market Segmentation
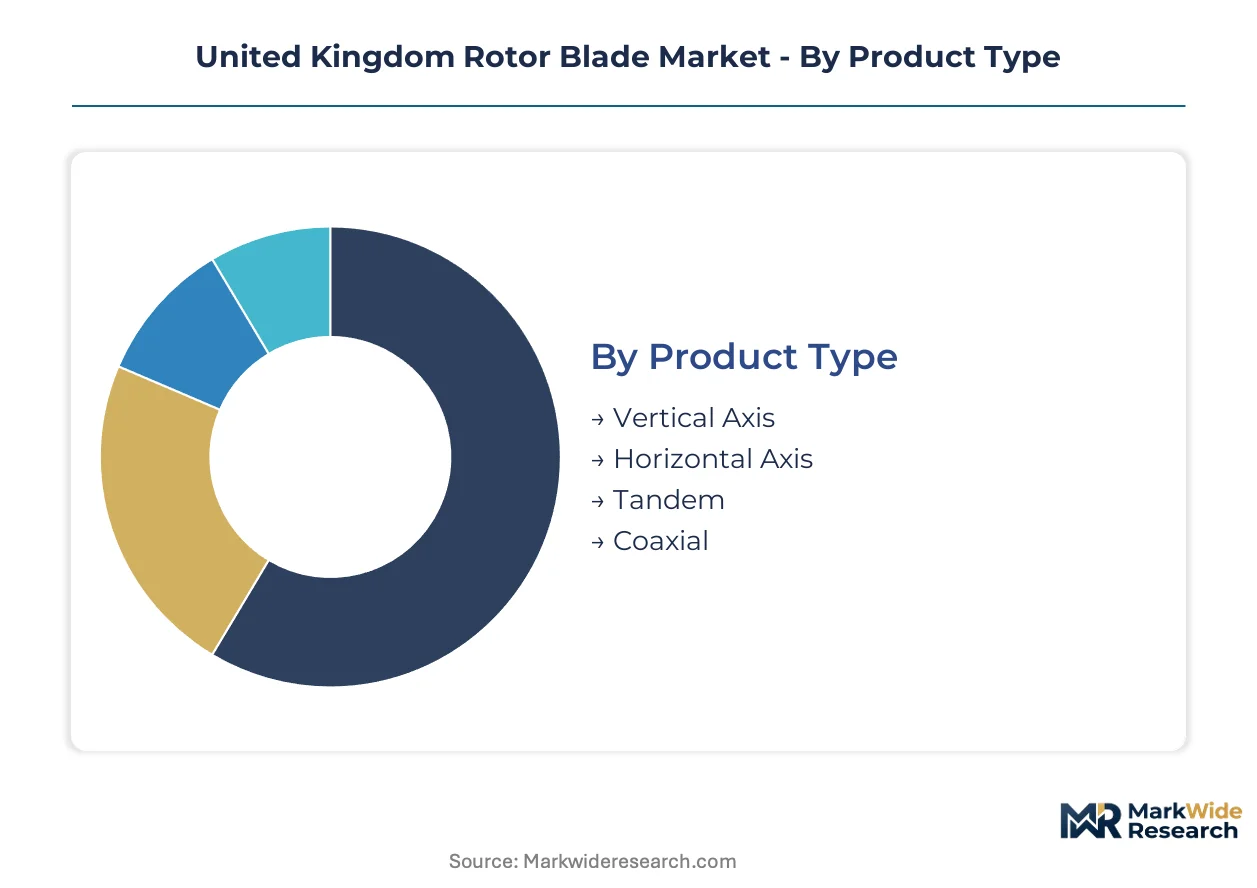
Blade procurement patterns across the United Kingdom diverge sharply by foundation type, material specification, and end-use certification requirements. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier selection criteria.
Product Type:
Foundation configuration determines aerodynamic efficiency targets and manufacturing process complexity for UK offshore developers.
- Horizontal Axis:Aerodynamic lifting surfaces rotate around a horizontal shaft perpendicular to wind flow, optimized for large-scale energy extraction. Scottish North Sea lease operators specify these configurations exclusively for fixed-bottom installations, driven by the Contracts for Difference scheme's yield-maximization incentives.
- Vertical Axis:Darrieus and Savonius variants capture wind from any direction without yaw mechanisms. Demand concentrates in distributed urban installations across England's East Coast clusters where grid connection constraints favor smaller footprint turbines.
- Tandem:Stacked rotor arrangements multiply swept area within constrained tower heights. Defense UAV contractors specify these for surveillance platforms requiring extended loiter endurance.
- Coaxial:Contra-rotating blade pairs eliminate torque reaction on supporting structures. Marine propulsion system integrators source these for tidal energy conversion trials in Wales' Celtic Sea zones.
Horizontal Axis leads on scale; Vertical Axis leads on momentum.
Material:
Specific strength requirements and end-of-life disposal pathways dominate material selection for British manufacturers facing Environment Agency mandates.
- Composite:Glass fiber and carbon fiber hybrid laminates bonded with thermoset or thermoplastic resins deliver exceptional fatigue resistance. Hull manufacturing facilities process these exclusively for blades exceeding 90 meters, pressured by landfill diversion deadlines.
- Metal:Aluminum and titanium alloys machine to precise tolerances for high-RPM applications. Aerospace end users in Bristol and Broughton specify metallic blades where lightning strike protection and repairability outweigh weight penalties.
- Wood:Laminated timber cores with composite skins reduce embodied carbon in small-scale installations. Heritage-sensitive developments in the Scottish Highlands specify these for visual impact mitigation.
- Alloy:Nickel-titanium superelastic formulations enable shape-adaptive airfoils. Biomedical device manufacturers in Cambridge source these for surgical micro-drill applications requiring sterilization durability.
Composite dominates installed value; Alloy climbs the fastest on specialized demand.
End User:
Certification rigor and volume scale separate procurement behaviors across British industrial sectors.
- Energy:Offshore wind farm operators drive the dominant share of blade demand, with Scottish North Sea and England's East Coast clusters absorbing multi-gigawatt procurement schedules.
- Aerospace:Civil and military aviation suppliers specify precision-manufactured blades with full traceability documentation, concentrated around Derby and Bristol engineering corridors.
- Defense:Ministry of Defence contractors seek indigenous composite supply chains for unmanned aerial systems, with demand accelerating from RAF Waddington and Boscombe Down test facilities.
- Industrial:Process ventilation and cooling tower applications consume standardized blade designs with shorter lead times and lower technical specifications.
Energy leads on scale; Defense leads on momentum.
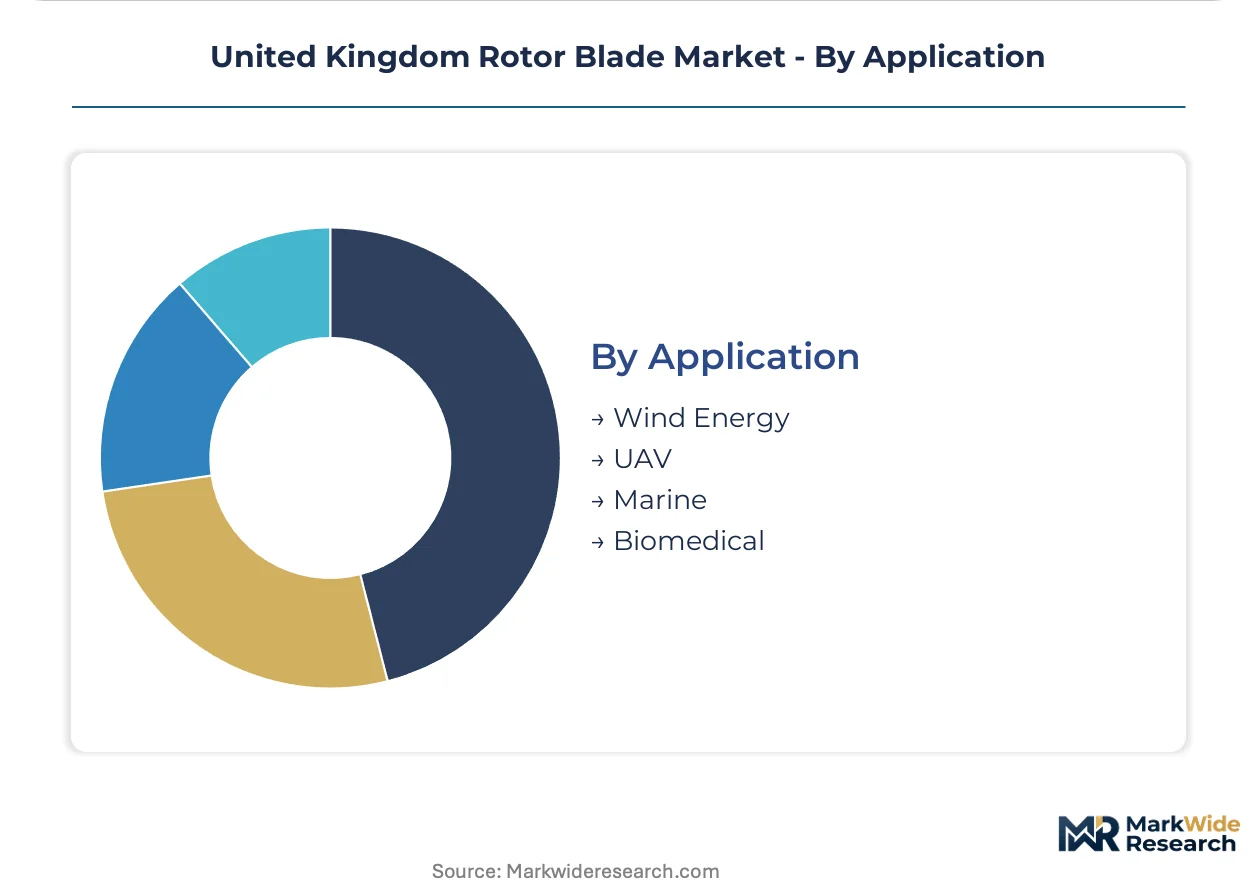
Application:
Operating environment severity dictates protective coating specifications and inspection interval requirements.
- Wind Energy:Utility-scale turbines across British territorial waters require erosion-resistant leading edge protection and integrated lightning dissipation systems.
- UAV:Unmanned platforms demand maximum power-to-weight ratios with rapid field-replaceable blade segments for operational tempo maintenance.
- Marine:Tidal and wave energy converters face cavitation and biofouging challenges in saltwater immersion, driving specialized coating development.
- Biomedical:Surgical and diagnostic equipment requires biocompatible surface finishes with validated sterilization cycle tolerance.
Wind Energy leads on scale; Marine gains share fastest on emerging lease rounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's North Sea lease zones dominate United Kingdom rotor blade demand through concentrated offshore wind deployment. England's East Coast clusters and Wales' emerging Celtic Sea sites complete the geographic demand map. Sub-regional specialization across manufacturing, testing, and installation creates distinct competitive corridors.
Scotland
Scottish North Sea lease rounds drive procurement of 90-meter-plus offshore-optimized blades. Crown Estate Scotland's ScotWind leasing framework mandates supply chain localization, pressuring developers toward domestic fabrication commitments. Aberdeen and Peterhead ports struggle with blade handling infrastructure, forcing costly logistics workarounds.
England
East Coast clusters around Hull and Great Yarmouth concentrate manufacturing capacity and operational turbine arrays. The Contracts for Difference scheme de-risks capital deployment, translating into firm procurement schedules from Dogger Bank and Hornsea developers. Siemens Gamesa Renewable Energy S.A. anchors blade supply through its Hull manufacturing plant, the country's largest such facility.
Wales
Celtic Sea lease rounds off Pembrokeshire and Lundy present untapped demand for floating foundation-compatible blade designs. The Crown Estate's emerging leasing framework targets 4.5 gigawatts of floating wind capacity. Port Talbot and Milford Haven compete for blade marshalling hub status against Irish Sea alternatives.
Northern England
Teesside and the Humber estuary host blade recycling infrastructure pilots responding to Environment Agency landfill diversion mandates. Yorkshire-based composite processors partner with manufacturers on thermoset shredding capacity development. The region's industrial heritage in chemicals and materials processing supports resin recovery technology deployment.
South England
The Isle of Wight testing facility validates next-generation airfoil designs for North Sea deployment. Vestas Wind Systems A/S leverages this site for prototype certification ahead of Scottish lease round deliveries. Southampton and Portsmouth provide maritime logistics for blade export to continental European markets.
United Kingdom Rotor Blade Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and technology integration. The United Kingdom rotor blade market structures around three tiers: integrated turbine OEMs with captive blade divisions, independent blade specialists serving multiple OEMs, and emerging recyclers addressing end-of-life mandates. Strategic moves concentrate on port-adjacent capacity expansion, thermoplastic resin transitions, and recycling partnership formation.
Among Danish and Spanish-origin integrated OEMs, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy S.A. exemplify the captive-manufacturing archetype with United Kingdom production footprints. LM Wind Power occupies a position as the independent specialist tier, supplying longer offshore-optimized blades that dominate Scottish lease allocations. These three entities represent distinct competitive positions: full-system integration, component specialization, and scale-driven fabrication.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy S.A. |
| Nordex SE |
| Orsted A/S |
| Vattenfall AB |
| GE Renewable Energy |
| LM Wind Power |
| TPI Composites |
| Siemens Gamesa |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber tow and epoxy resin feedstock costs cascade through three distinct pricing tiers for United Kingdom rotor blade procurement, with offshore wind farm operators bearing premium rates for 90-meter-plus specifications while smaller distributed developers absorb compressed margins on standardized glass fiber designs.
Pricing Analysis
Input-cost pass-through from petrochemical derivatives and aerospace-grade carbon fiber suppliers dominates blade pricing structures across British manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates offshore-optimized carbon fiber hybrids from onshore glass fiber designs and small-scale distributed turbine blades. Certification tier under Maritime and Coastguard Agency offshore construction standards commands substantial premiums over industrial-grade alternatives. Pricing pressure stems from epoxy resin volatility linked to crude oil benchmarks, squeezing fixed-price contract margins for Hull-based manufacturers. Utility-scale developers with Contracts for Difference backing exhibit lowest price sensitivity; distributed urban installers face acute cost compression.
Supply Chain Analysis
Crown Estate Scotland's ScotWind supply chain localization mandates and the UK government's domestic content expectations for offshore wind are reshaping sourcing patterns toward British fabrication commitments. Raw material dependencies draw from Japan and South Korea for carbon fiber precursors, Germany for epoxy resin formulations, and Belgium for balsa wood core materials. Single-source vulnerability concentrates in aerospace-grade carbon fiber supply where Toray and Teijin capacity allocations determine blade manufacturer output ceilings. Distribution runs through port-adjacent marshalling yards at Hull, Great Yarmouth, and Isle of Wight before final offshore installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom rotor blade market functions as a regulatory compounder where Environment Agency landfill diversion mandates and Contracts for Difference auction schedules jointly determine demand trajectories and compliance investment requirements.
For Market Incumbents: Deploy thermoplastic resin transition programs to preempt thermoset composite obsolescence risk from Environment Agency circular economy mandates. Secure captive carbon fiber supply agreements with Japanese and Korean precursor manufacturers to defend against aerospace demand competition. Expand recycling partnerships with Yorkshire-based composite processors before landfill bans strand legacy blade assets. For New Entrants and Emerging Players: Digital-channel routes through blade inspection and repair service platforms offer lower capital barriers than manufacturing entry. Target Wales Celtic Sea floating wind lease rounds where established Hull-centric supply chains lack floating foundation blade design experience. Pursue Ministry of Defence UAV contractor relationships as a diversified revenue anchor beyond energy sector cyclicality. For Investors and Strategic Acquirers: Consolidation pressure builds where thermoplastic recycling capability scarcity meets tightening landfill diversion deadlines. Five-to-ten year viability favors acquirers of blade recycling infrastructure over pure manufacturing plays. Watch Scottish port expansion timelines at Aberdeen and Peterhead as inflection indicators for logistics cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Resin Transition | Aligns Hull manufacturing with Environment Agency circular economy mandates ahead of landfill bans. |
| Port-Adjacent Capacity Expansion | Reduces blade transport costs for Scottish North Sea lease round deliveries through dedicated quayside facilities. |
| Carbon Fiber Supply Agreement | Secures aerospace-grade precursor allocation from Toray or Teijin against competing demand from aviation sectors. |
| Blade Recycling Partnership | Develops Yorkshire-based thermoset shredding capacity to address producer responsibility obligations under waste framework revisions. |
| Defense UAV Channel Development | Diversifies revenue toward Ministry of Defence unmanned aerial system procurement at RAF Waddington and Boscombe Down. |
Research Methodology
Coverage spans Scotland, England, and Wales with primary inputs from each sub-region's manufacturing and deployment clusters. The analysis combines structured interviews with blade manufacturing plant managers, offshore wind farm procurement directors, Maritime and Coastguard Agency certification officers, and composite materials R&D leads with secondary validation from Crown Estate leasing documentation, Environment Agency waste framework publications, and Health and Safety Executive workplace exposure guidelines. Customs data on carbon fiber and epoxy resin imports, SEC filings from listed turbine OEMs, and Contracts for Difference auction results provided demand-side triangulation alongside bottom-up manufacturing capacity surveys.
Granularity-level framing models blade demand at the foundation-type and material-specification intersection, with separate runs for horizontal axis versus vertical axis configurations and composite versus metal material splits across the projection horizon. CAGRs derive from capacity deployment schedules linked to Crown Estate and Crown Estate Scotland lease round timetables, tempered by port infrastructure constraint factors and recycling compliance cost curves. Forecast inputs include blade length evolution trajectories, resin system transition adoption rates, and Scottish port deepening project completion assessments.
The model assumes a particular technology adoption path for thermoplastic resin systems; alternative pathways for thermoset recycling breakthroughs would alter the outlook for incumbent Hull manufacturers. Forecasts reflect assumptions on Contracts for Difference auction frequency, Environment Agency enforcement intensity, and carbon fiber precursor supply expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
North America Rotor Blade Market