
 Aerospace and Defense Fluid Conveyance Systems Market | 2026-2036
Aerospace and Defense Fluid Conveyance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Fluid Conveyance Systems Market Analysis
Defense procurement channels for fluid conveyance hardware is fragmenting as prime contractors diversify supplier pools beyond traditional single-source arrangements. Parker Hannifin anchors North American military programs through captive manufacturing of titanium hydraulic tubing. Safran competes on European fighter and rotorcraft platforms with integrated fuel and pneumatic ducting systems. Eaton Corporation extends its position in aftermarket distribution by sustaining long-term MRO contracts with U.S. Air Force logistics centers.
Aerospace and Defense Fluid Conveyance Systems encompass the engineered network of pipes, hoses, fittings, and connectors that transport fuel, hydraulic fluid, coolant, and pneumatic pressure throughout aircraft, missiles, and unmanned platforms, typically manufactured from aluminum alloys, corrosion-resistant steel, advanced polymers, or carbon-fiber composites to withstand operating pressures exceeding 3,000 psi and temperature extremes from minus 65 to 275 degrees Fahrenheit. Their primary purpose is to ensure leak-free, vibration-resistant fluid transfer that maintains flight control authority, engine performance, and thermal management under dynamic load conditions. Hoses and fittings capture the largest share of product-type revenue due to replacement frequency in high-cycle commercial fleets, while composite materials represent the fastest-expanding material category as airframers pursue weight reduction targets for next-generation narrowbody designs. Aircraft applications dominate absolute demand volume, though missiles and drones are gaining share as hypersonic programs and unmanned combat aerial vehicle procurement accelerate.
FAA airworthiness directives and EASA certification specifications govern flammability resistance and fatigue life testing for all fluid transport components installed on civil-certified platforms, while U.S. Defense Federal Acquisition Regulations impose traceability and domestic sourcing constraints on military-grade assemblies. The EU Green Deal's industrial emissions benchmarks are pressuring European suppliers to decarbonize aluminum and steel processing operations used in conduit manufacturing. Stakeholders must monitor evolving sustainability mandates and dual-use technology export controls as these frameworks increasingly determine which suppliers qualify for platform development contracts.
Market Dynamics
Defense procurement fragmentation is compressing supplier margins as prime contractors dismantle single-source dependencies and force competitive rebidding on long-term hydraulic assembly contracts. This structural pressure cascades through the supply base, demanding simultaneous cost reduction and enhanced traceability.
Growth Catalysts
- F-35 Program Expansion:Multi-year production ramps across three U.S. military branches sustain demand for titanium hydraulic tubing and fire-resistant hose assemblies. Component orders track aircraft delivery schedules with minimal variance.
- EU Green Deal Emissions Benchmarks:European aluminum and steel processors face mandatory decarbonization timelines. Suppliers investing in electric arc furnace and renewable-powered extrusion capacity secure preferred supplier status with Airbus and Safran.
- Hypersonic Glide Vehicle Testing:Thermal management requirements for Mach 5+ flight profiles drive development of ceramic-matrix composite coolant lines. Pentagon test ranges in California and Virginia validate prototype performance under sustained aerodynamic heating.
Market Restraints
- Titanium Sponge Supply Concentration:Russian and Ukrainian feedstock disruption has shifted sourcing toward Japanese and Kazakh producers. Spot price volatility for aerospace-grade titanium exceeds historical bands, squeezing tubing manufacturer margins.
- FAA-EASA Certification Divergence:Fire-resistant hose testing protocols differ between Washington and Brussels. Dual-certification costs for suppliers serving both Boeing and Airbus narrowbody programs add 12-18 months to qualification timelines.
- Polymer Substitution Limits:High-pressure hydraulic circuits above 4,000 psi remain locked into corrosion-resistant steel. Advanced thermoplastics lack the fatigue resistance for primary flight control actuation, constraining weight reduction roadmaps.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme for aerospace components offers 15-year production incentives. Foreign suppliers establishing joint ventures with Hindustan Aeronautics gain access to Tejas fighter and Dhruv helicopter retrofit programs.
- Urban Air Mobility Thermal Systems:Electric vertical take-off aircraft require lightweight coolant distribution for battery packs and motor controllers. Early entrants in this segment bypass incumbent qualification barriers facing traditional commercial aviation.
- Additive Manufacturing Convergence:Laser powder bed fusion of Inconel fittings eliminates welded joints in high-vibration zones. GE Aviation and Pratt & Whitney are qualifying printed hydraulic manifolds for next-generation turbofan engines.
Industry Challenges
- Specialized Welder Scarcity:Orbital welding of thin-wall titanium tubing demands ASME Section IX certification held by fewer than 400 technicians across North America. Training pipelines at community colleges and military depots cannot match retirement outflows.
- Legacy Platform Spare Synchronization:C-130 and F-16 fleets operate beyond original design life. Maintaining hydraulic hose interchangeability across five decades of configuration changes requires exhaustive configuration management that strains ERP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Fluid Conveyance Systems Market |
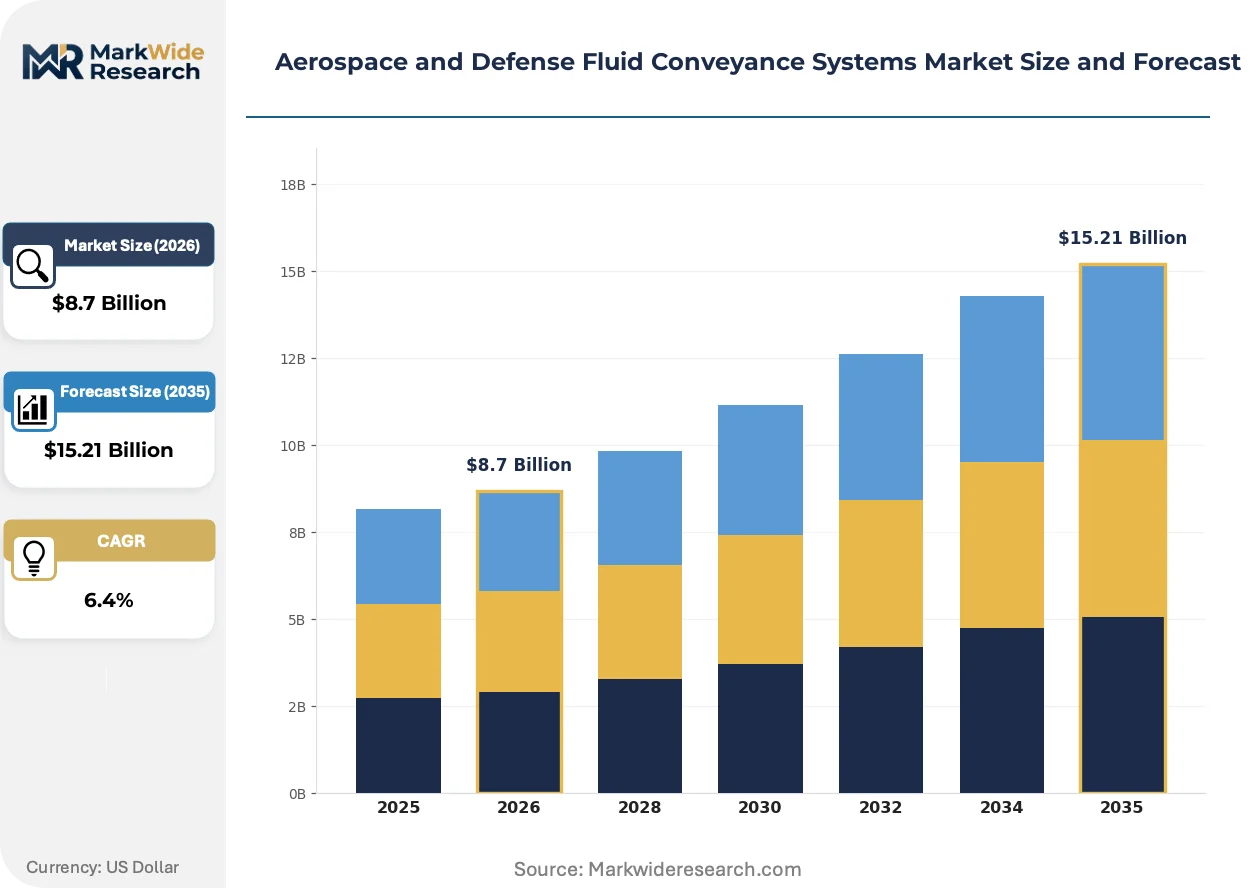
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipes, Hoses, Fittings, Connectors Material: Aluminum, Steel, Polymer, Composite Application: Aircraft, Missiles, Satellites, Drones End User: OEMs, MRO Providers, Government, Contractors |
| Companies Covered | Moog Inc., Senior Aerospace, Parker Hannifin, Flexfab, ITT Aerospace, Eaton Corporation, Smiths Group, Safran, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Fluid Conveyance Systems Market Emerging Trajectories
Material substitution and digital thread integration are compressing development cycles for fluid conveyance hardware. Suppliers must now deliver qualified components with full pedigree documentation in half the historical timeframe.
Carbon-fiber reinforced thermoplastic tubing is collapsing the weight penalty traditionally accepted for pneumatic ducting in commercial aircraft. Boeing's 787 successor studies specify thermoplastic composites for bleed air distribution, cutting system mass by 40 percent versus aluminum predecessors. Airframers in Germany and Japan are accelerating qualification testing to capture fuel efficiency gains on next-generation narrowbody platforms.
EASA's updated Certification Specifications for Large Aeroplanes now mandate predictive maintenance data transmission for critical fluid systems. Airlines operating Airbus A350 and Boeing 777X fleets must install sensor-integrated hoses capable of real-time pressure pulsation monitoring. MRO providers in France and Singapore are retrofitting legacy fleets to avoid operational restrictions in European airspace.
Defense logistics centers are unbundling long-term sustainment contracts into discrete performance-based line items. The U.S. Air Force now awards separate contracts for hose assembly fabrication, kitting, and field installation rather than consolidated prime vendor arrangements. This disaggregation forces mid-tier suppliers to build direct relationships with base-level maintainers at installations across Texas, Arizona, and Florida.
Aerospace and Defense Fluid Conveyance Systems Market Segmentation
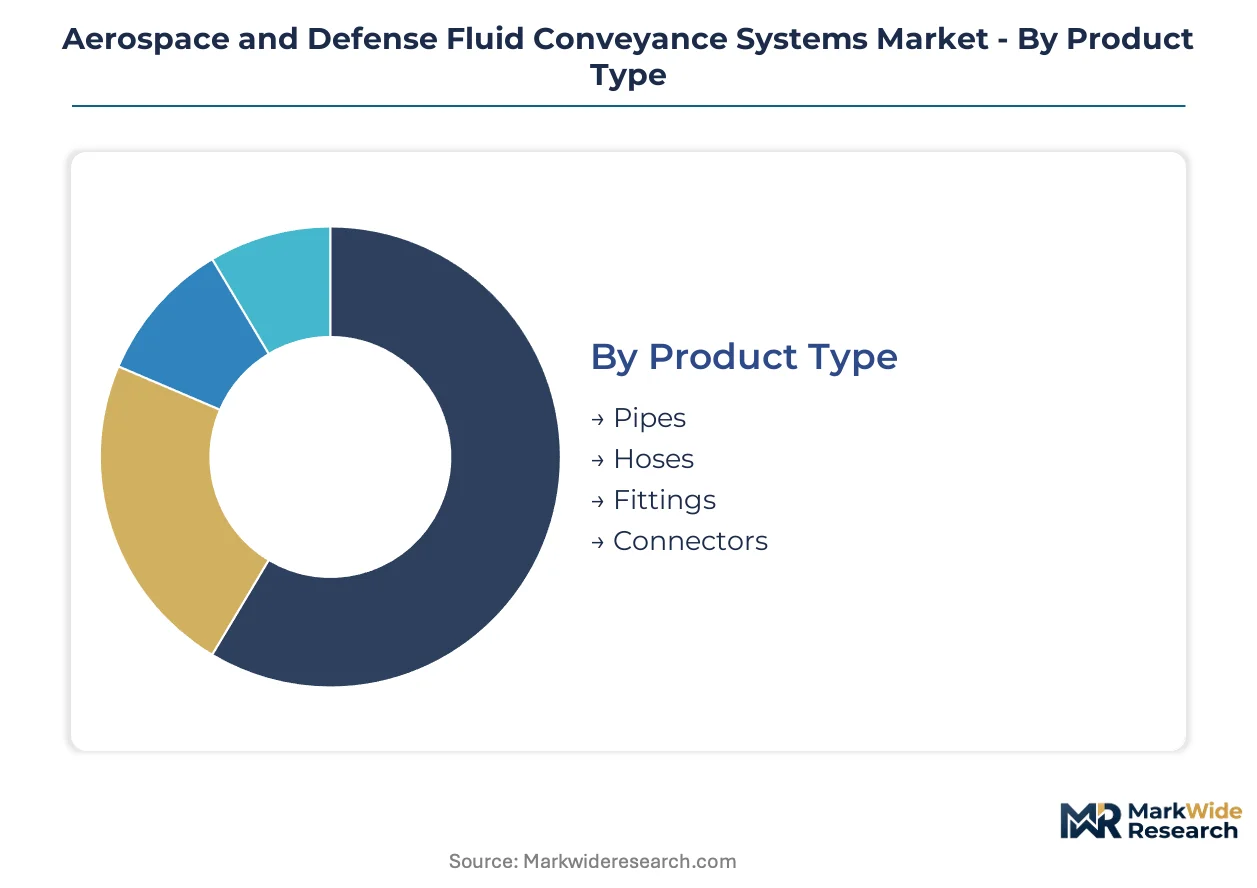
Fluid conveyance procurement splits across divergent technical specifications, material tolerances, and certification pathways. Each segment commands distinct supplier capabilities and margin profiles that reshape competitive positioning across defense and commercial aviation channels.
Product Type:
Use-case spectrum spans permanent structural routing versus replaceable service components, with replacement frequency driving aftermarket economics.
- Hoses:Flexible reinforced assemblies withstand vibration and thermal cycling in engine nacelles and landing gear bays. Commercial fleet utilization above 3,000 annual flight hours concentrates demand in North America and Europe, where quick-turn MRO availability determines airline procurement preferences.
- Fittings:Precision-machined connectors terminate fluid circuits with leak-free sealing under pressure spikes exceeding 5,000 psi. Military aircraft programs in the United States specify titanium alloy variants for corrosion resistance in maritime patrol environments.
- Pipes:Rigid tubing routes hydraulic fluid through wing structures and fuselage compartments with minimal pressure drop.
- Connectors:Quick-disconnect couplings enable rapid line separation during field maintenance operations.
The dominant share belongs to hoses, while fittings is closing the gap fastest.
Material:
Cost tier separation reflects raw material volatility and processing complexity rather than finished component pricing alone.
- Composite:Carbon-fiber reinforced thermoplastic structures deliver 40 percent mass reduction versus metal alternatives for pneumatic ducting. Boeing next-generation narrowbody studies specify thermoplastic composites for bleed air systems, with German and Japanese airframers accelerating parallel qualification programs.
- Steel:Corrosion-resistant alloys retain monopoly in primary flight control hydraulics above 4,000 psi operating pressure. Fatigue resistance requirements for actuation circuits lock this material into long-term military platform specifications.
- Aluminum:Extruded and drawn tubing serves low-pressure fuel vent lines and environmental control systems.
- Polymer:Advanced thermoplastics penetrate secondary fluid circuits where pressure and temperature envelopes permit substitution.
Steel maintains volume leadership in absolute units, though composite is expanding most quickly as weight reduction targets harden.
Application:
Volume concentration tracks platform production rates, with unmanned systems reshaping growth contours.
- Aircraft:Manned platforms consume the majority of hydraulic and fuel system hardware by unit value. F-35 multi-year production ramps across U.S. Air Force, Navy, and Marine Corps sustain demand for titanium tubing and fire-resistant hose assemblies with minimal order variance.
- Drones:Unmanned combat aerial vehicles and tactical reconnaissance systems require compact, lightweight fluid routing for extended endurance missions. Pentagon procurement acceleration for attritable platforms is displacing traditional manned-aircraft share in new contract awards.
- Missiles:Hypersonic glide vehicle programs drive ceramic-matrix composite development for thermal management at Mach 5+ velocities.
- Satellites:On-orbit propellant transfer and thermal control systems demand ultra-lightweight, vacuum-compatible conduit solutions.
Aircraft retains absolute demand dominance, while drones is climbing the fastest as unmanned platform procurement scales.
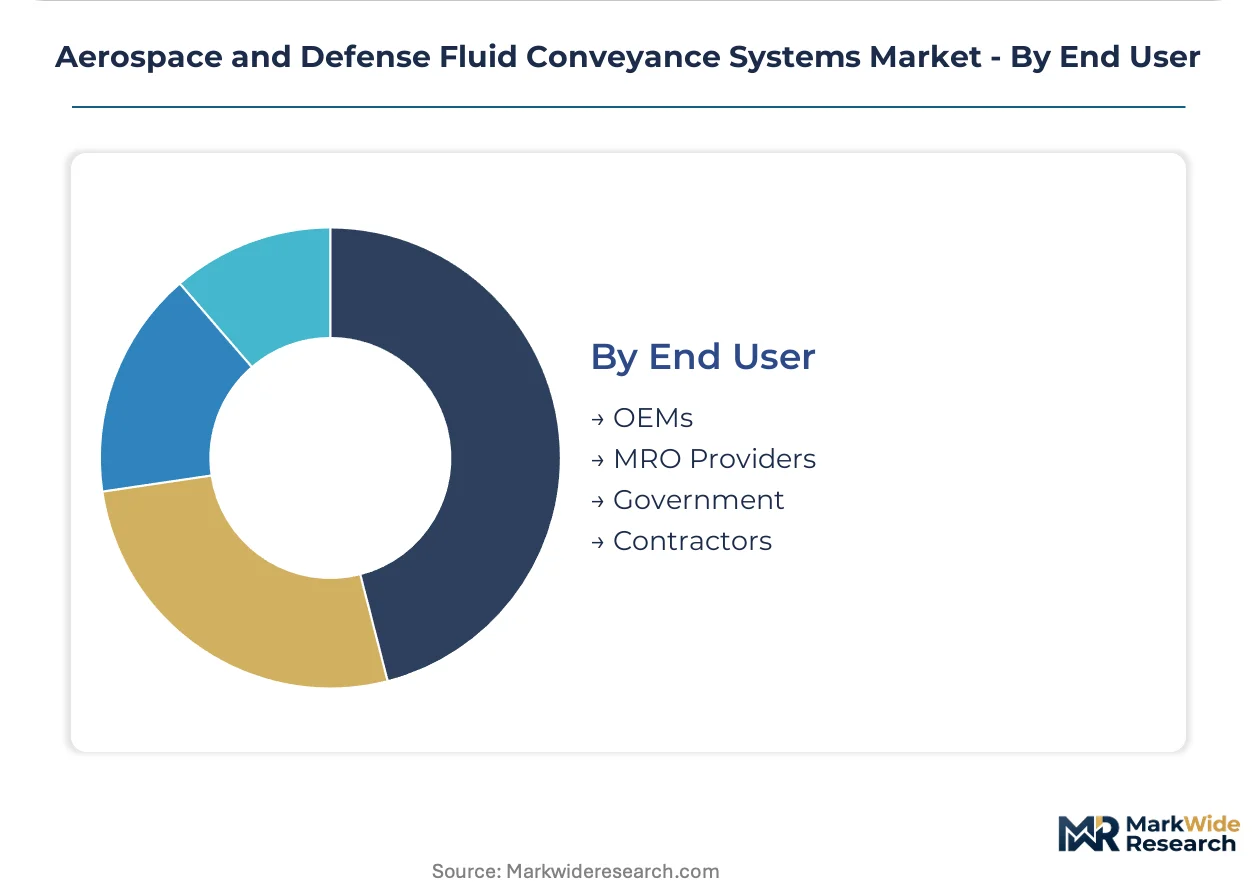
End User:
Customer type determines contract structure, with government buyers imposing traceability requirements that reshape supplier economics.
- OEMs:Original equipment manufacturers integrate fluid systems during final assembly, specifying qualified components with full pedigree documentation. Airbus and Boeing narrowbody programs demand delivery timelines compressed to half historical qualification periods.
- MRO Providers:Maintenance, repair, and overhaul operators capture recurring revenue through fleet sustainment, with hose replacement cycles tied to flight hour accumulation. U.S. Air Force logistics centers in Texas, Arizona, and Florida now contract separately for fabrication, kitting, and field installation rather than consolidated prime vendor arrangements.
- Government:Defense agencies procure directly for depot-level maintenance and foreign military sales programs.
- Contractors:Tier-1 and Tier-2 suppliers fabricate subassemblies for integration into higher-level systems.
OEMs command the largest revenue share, while MRO providers is gaining share fastest as fleet ages extend platform service lives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement incentives across NATO members are redistributing fluid conveyance manufacturing capacity toward politically aligned supply zones. Government production-linked schemes and domestic content mandates now determine supplier qualification timelines more than technical specifications alone.
United States
Multi-year F-35 production ramps across Air Force, Navy, and Marine Corps sustain demand for titanium hydraulic tubing and fire-resistant hose assemblies. The Pentagon's Defense Federal Acquisition Regulations impose traceability and domestic sourcing constraints on military-grade assemblies. Industrial clusters in Texas, Arizona, and Florida host Air Force logistics centers that now contract separately for fabrication, kitting, and field installation.
Germany
Airframers in Germany accelerate qualification testing of carbon-fiber reinforced thermoplastic tubing for next-generation narrowbody platforms. The EU Green Deal's industrial emissions benchmarks pressure aluminum and steel processors toward electric arc furnace and renewable-powered extrusion capacity. Suppliers in Bavaria and Baden-Württemberg secure preferred supplier status with Airbus through decarbonization investments.
France
Safran competes on European fighter and rotorcraft platforms with integrated fuel and pneumatic ducting systems. EASA's updated Certification Specifications for Large Aeroplanes mandate predictive maintenance data transmission for critical fluid systems. MRO providers near Toulouse and Paris retrofit legacy fleets with sensor-integrated hoses to avoid operational restrictions.
United Kingdom
Smiths Group anchors defense fluid systems through precision-machined connectors and quick-disconnect couplings. The country's national aerospace regulator enforces fire-resistant hose testing protocols that diverge from FAA standards, extending dual-certification timelines. Manufacturing concentration in the Midlands and Southwest England supports BAE Systems platform integration.
India
The country's PLI scheme for aerospace components offers 15-year production incentives for foreign suppliers establishing joint ventures with Hindustan Aeronautics. Domestic content requirements for Tejas fighter and Dhruv helicopter retrofit programs redirect procurement toward local fabrication. Industrial corridors in Maharashtra and Karnataka attract fluid conveyance joint ventures seeking defense market access.
Aerospace and Defense Fluid Conveyance Systems Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated system integrators and specialized component fabricators serving distinct certification tiers. Tier-1 primes like Parker Hannifin and Eaton Corporation control captive manufacturing of titanium hydraulic tubing and aftermarket distribution channels. Three strategic archetypes dominate: full-system integrators bundling design-through-sustainment contracts; component specialists commanding premium pricing on AS9100-certified precision fittings; and regional fabricators competing on cost for non-flight-critical assemblies. Competitive moves center on backward integration into specialty alloy processing and strategic partnerships with additive manufacturing equipment suppliers.
Among North American-based system integrators, Parker Hannifin and Eaton Corporation exemplify the full-service archetype through their positions in military hydraulic assembly and Air Force logistics sustainment. Safran occupies a parallel position among European primes, representing the integrated fuel and pneumatic ducting specialist model. Moog Inc. sits within the precision motion control tier, anchoring high-reliability fluid power applications where failure tolerance approaches zero.
| Leading Market Players |
|---|
| Moog Inc. |
| Senior Aerospace |
| Parker Hannifin |
| Flexfab |
| ITT Aerospace |
| Eaton Corporation |
| Smiths Group |
| Safran |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Japanese titanium sponge processing is forcing North American tubing manufacturers toward Kazakh and Saudi feedstock alternatives, compressing margins while elevating spot-price volatility for aerospace-grade material. This utilization squeeze cascades through the supply base, reshaping both procurement strategies and pricing postures across military and commercial channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified titanium assemblies from commercial-grade aluminum alternatives and non-flight-critical polymer routing. Price differentiation hinges on certification grade and volume scale, with multi-year F-35 contracts commanding 15-20 point spreads over spot-market commercial orders. Cost compression in standard-tier steel hydraulic lines is intensifying because prime contractors now force competitive rebidding on legacy platform sustainment. Government buyers exhibit lowest price sensitivity due to traceability mandates, while regional MRO providers face acute margin pressure from disaggregated logistics contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for aluminum extrusion and rare-earth alloy sourcing. Geographic supply concentration centers on Japan, Kazakhstan, and Saudi Arabia for titanium sponge, with Germany and France anchoring European precision fitting fabrication. The chain draws from corrosion-resistant steel billets, carbon-fiber prepreg, and fire-resistant polymer compounds as critical inputs. Single-source vulnerability persists in orbital welding equipment and thin-wall titanium tubing capacity. Distribution runs through prime contractor integration facilities, Air Force logistics centers, and airline MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping this market as sensor-integrated hoses and predictive maintenance data streams create interoperability requirements that favor integrated system providers over component specialists. This ecosystem shift rewards suppliers capable of delivering qualified hardware with full digital pedigree documentation.
For Market Incumbents: Insulate titanium tubing margins through captive supply agreements with Kazakh and Japanese sponge processors, while accelerating additive manufacturing qualification for Inconel fittings to offset specialized welder scarcity. Defense procurement fragmentation poses the central threat, demanding simultaneous cost reduction and enhanced traceability capabilities. For New Entrants and Emerging Players: Urban air mobility thermal management systems in battery-electric vertical take-off aircraft represent the most penetrable entry point, bypassing incumbent qualification barriers facing traditional commercial aviation. India's PLI scheme for aerospace components offers 15-year production incentives for joint ventures with Hindustan Aeronautics. A go-to-market angle anchored on lightweight coolant distribution for electric propulsion systems opens direct relationships with emerging airframers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO-focused component fabricators holding long-term sustainment contracts with U.S. Air Force logistics centers. Long-term viability over the coming decade favors suppliers with demonstrated EASA-FAA dual-certification capability and electric arc furnace capacity for decarbonized aluminum processing. The signal to watch is Pentagon test range validation for ceramic-matrix composite coolant lines, indicating thermal management technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge Processing | Captive supply from Kazakh and Japanese sources insulates against Russian-Ukrainian feedstock disruption. |
| Additive Manufacturing Qualification | Laser powder bed fusion of Inconel fittings eliminates welded joints in high-vibration zones for next-generation engines. |
| Electric Arc Furnace Capacity Expansion | Renewable-powered aluminum extrusion secures preferred supplier status with Airbus under EU Green Deal benchmarks. |
| Sensor-Integrated Hose Development | Real-time pressure pulsation monitoring meets EASA predictive maintenance mandates for A350 and 777X fleets. |
| India Joint Venture Formation | PLI scheme access opens Tejas fighter and Dhruv helicopter retrofit programs through Hindustan Aeronautics partnerships. |
Methodological Framework
A spread of perspectives from procurement officers at prime contractors, Air Force logistics center directors, MRO operations managers, and regulatory affairs specialists at FAA and EASA converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through Defense Federal Acquisition Regulations filings, EU Green Deal industrial emissions benchmarks, and customs data tracking titanium sponge trade flows. Bottom-up segmentation modeling and top-down macroeconomic overlay triangulated volume and value estimates across product types, materials, applications, and end-user categories.
Demand-supply-balance framing anchored the forecast framework, with installed fleet analysis and platform production schedules driving replacement-cycle assumptions across the projection horizon. Segmentation dimensions modeled include product type permanence versus replaceability, material cost tier and processing complexity, application platform class, and end-user contract structure. CAGRs were derived from regression analysis against defense budget appropriations and commercial aircraft delivery schedules, with hypersonic program acceleration and urban air mobility emergence as industry-specific demand inputs.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocations, titanium spot prices, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions regarding F-35 production ramps, FAA-EASA certification convergence timelines, and India defense indigenization pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Global Aircraft Pumps Market