
 Aircraft Fuel Nozzle Market | 2026-2036
Aircraft Fuel Nozzle Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Fuel Nozzle Market Analysis
North American precision machining clusters is repositioning output toward aerospace-qualified fuel system components. Honeywell International Inc. leverages its integrated propulsion electronics portfolio to bundle nozzle control systems. GE Aviation anchors demand through its LEAP engine program and captive aftermarket pull. Safran SA competes on European narrow-body platforms with specialized atomizing geometries.
Aircraft fuel nozzles are precision-engineered fuel metering devices, typically machined from Inconel or titanium alloys to withstand combustion temperatures exceeding 1,700°C, designed to atomize and direct fuel into turbine combustors for optimized burn efficiency and emissions control. Multi-point nozzle configurations lead commercial aviation installations due to staged combustion requirements, while titanium material grades capture expanding margin pools as OEMs prioritize weight reduction. Electrohydraulic technology segments show accelerating replacement cycles as airlines retrofit legacy mechanical systems for improved fuel flow modulation.
FAA airworthiness directives and EASA certification specifications govern nozzle fatigue life and leakage thresholds, while EPA stationary source rules indirectly shape ground-test equipment standards. China's CAAC implements parallel type-certification pathways that extend design validation timelines for imported assemblies. Stakeholders must monitor evolving sustainable aviation fuel compatibility specifications that could necessitate comprehensive nozzle material redesigns without grandfathering provisions.
Market Dynamics
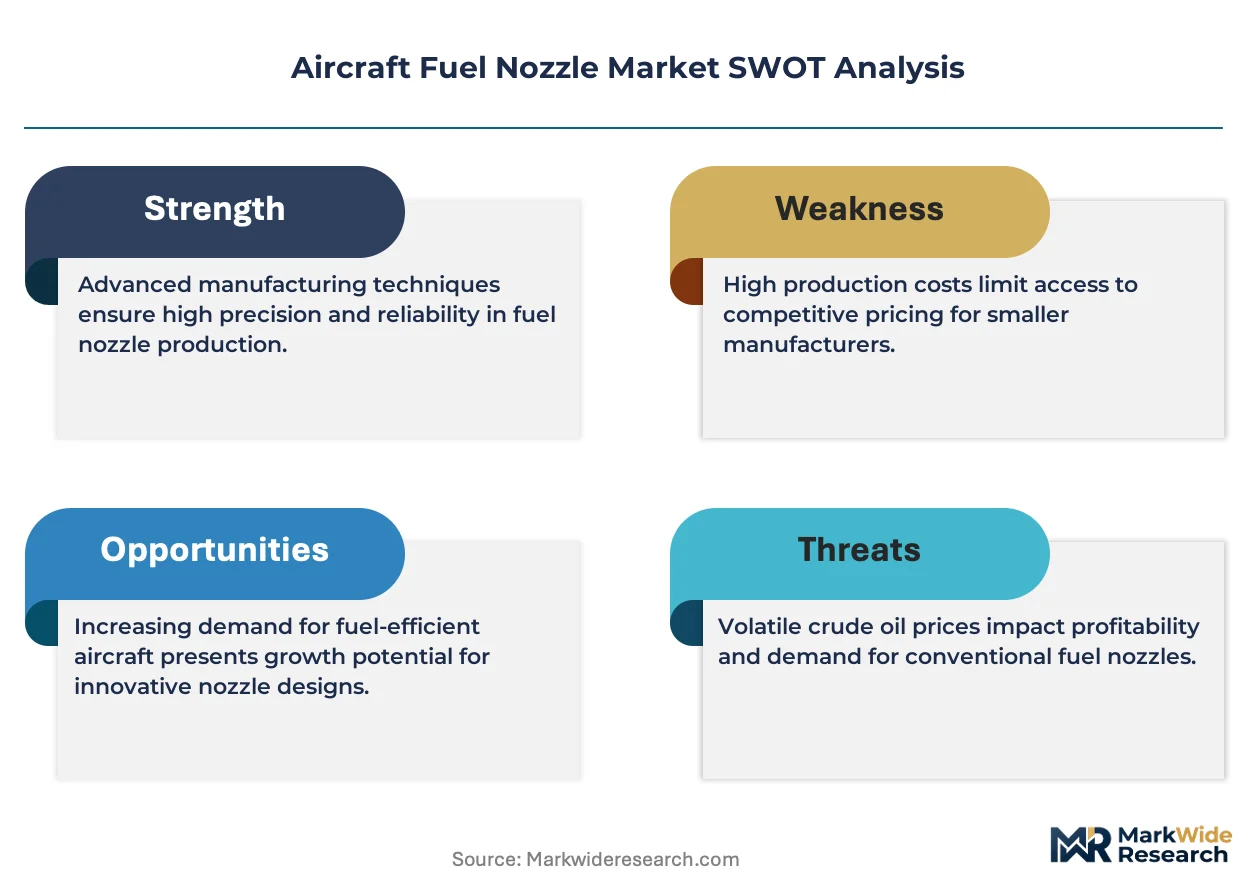
Staged combustion architectures are forcing nozzle suppliers to engineer multi-point fuel delivery systems capable of precise atomization across lean-burn operating envelopes, compressing development cycles and elevating metallurgical specifications.
Growth Catalysts
- FAA Part 33 Emissions Standards:Certification mandates for nitrogen oxide reduction are compelling OEMs to specify advanced atomizing geometries in new engine programs, expanding the addressable hardware market for qualified suppliers.
- Asia-Pacific Narrow-Body Fleet Expansion:Chinese, Indian, and Vietnamese carriers are accelerating delivery schedules for single-aisle aircraft, generating concentrated demand for line-fit nozzle assemblies and associated spare provisioning.
- Additive Manufacturing Qualification:Directed energy deposition processes for Inconel superalloy components are reducing lead times for complex internal flow passages, enabling faster design iteration cycles.
Market Restraints
- Titanium Alloy Price Volatility:Sponge titanium supply concentrates in Russian and Kazakh production facilities, exposing nozzle manufacturers to input cost swings and forced material substitutions.
- Combustor Temperature Ceiling:Current thermal barrier coating systems impose hard limits on peak operating temperatures, constraining the efficiency gains achievable through nozzle geometry optimization alone.
- EASA Certification Timeline Extension:Revised CS-E engine certification specifications have lengthened validation protocols for new fuel system designs, delaying revenue recognition for development programs.
Strategic Opportunities
- Sustainable Aviation Fuel Compatibility:Hydrotreated esters and fatty acids (HEFA) and synthetic paraffinic kerosene (SPK) blends exhibit different viscosity and combustion characteristics, creating retrofit demand for modified nozzle flow coefficients.
- Urban Air Mobility Propulsion:Turboshaft and hybrid-electric distributed propulsion systems for eVTOL platforms require miniature fuel injection hardware, opening adjacent volume pools outside traditional commercial aviation.
- India's PLI Scheme for Aerospace:Production-linked incentive frameworks for precision-engineered components are attracting tier-2 nozzle manufacturers to establish machining capacity in Bangalore and Hyderabad clusters.
Industry Challenges
- Superalloy Machinist Scarcity:Five-axis CNC programming expertise for heat-resistant alloys remains concentrated among aging workforces in Connecticut and southwestern Germany, constraining capacity expansion.
- Legacy System Integration:Electrohydraulic nozzle actuation retrofits onto mechanical fuel control units require bespoke adapter interfaces, complicating fleet-wide upgrade campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Fuel Nozzle Market |
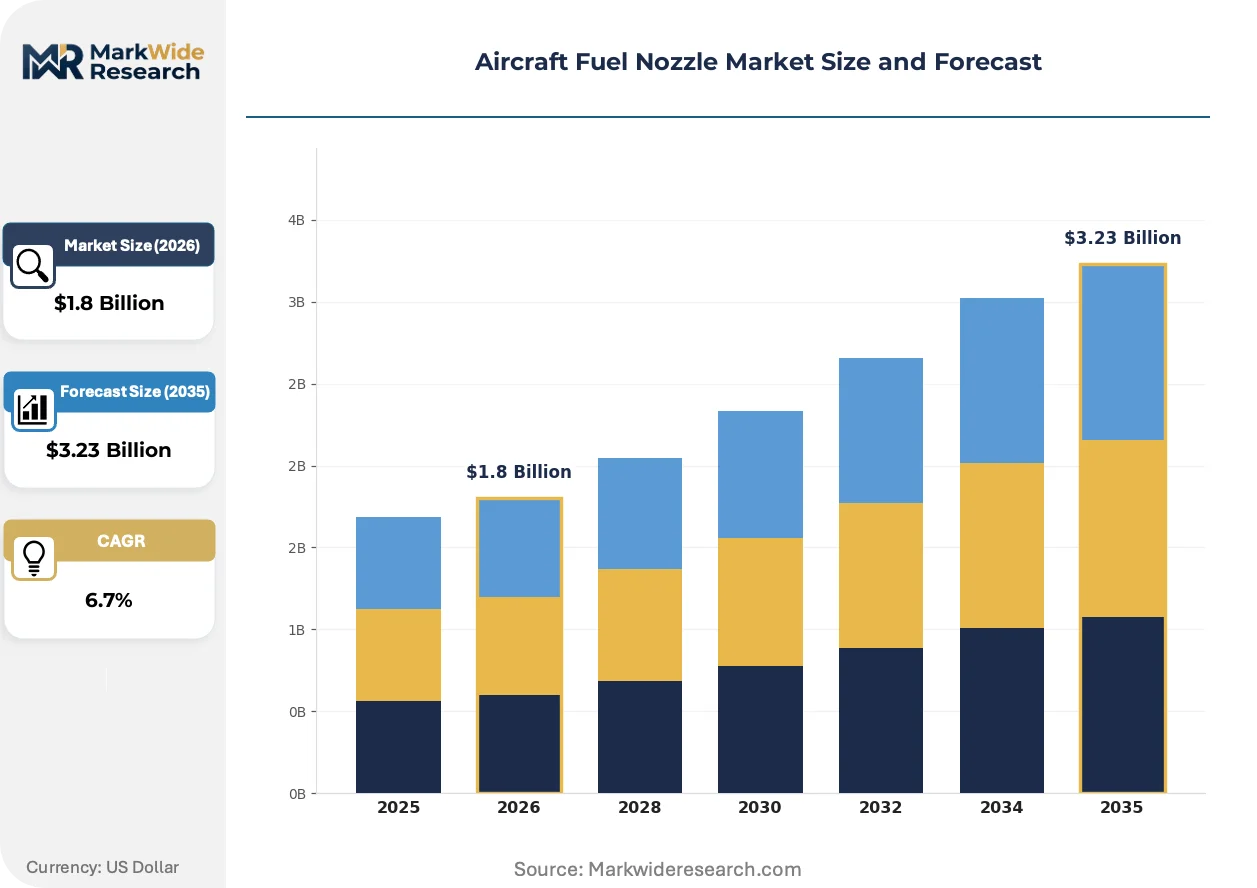
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Point Nozzle, Multi-Point Nozzle, Atomizing Nozzle, Swirl Nozzle Material: Aluminum, Stainless Steel, Composite, Titanium Application: Commercial Aviation, Military Aviation, Business Aviation, General Aviation Technology: Conventional, Advanced, Electrohydraulic, Fuel Efficient |
| Companies Covered | Honeywell International Inc., Eaton Corporation, GE Aviation, Meggitt PLC, Collins Aerospace, Parker Hannifin Corporation, Safran SA, GKN Aerospace, Woodward, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Fuel Nozzle Market Emerging Trajectories
Digital thread integration across design, manufacturing, and in-service monitoring is collapsing the feedback loop between combustor performance data and nozzle geometry optimization, accelerating generational product cycles.
Laser powder bed fusion for titanium aluminide nozzle swirlers is rewriting the trade-off between weight reduction and high-temperature durability. GE Aviation and Pratt & Whitney are qualifying additively manufactured primary components for LEAP and GTF engine variants. The technology is compressing minimum economic order quantities and enabling part consolidation that eliminates braze joints.
EPA stationary source regulations for engine test cell emissions are tightening particulate matter thresholds, forcing ground-test nozzle configurations to mirror flight hardware more precisely. Test equipment suppliers must now source production-equivalent fuel metering devices rather than simplified laboratory substitutes. California and Texas test facilities are absorbing the compliance cost premiums.
Airline technical procurement departments are consolidating vendor panels and demanding long-term aftermarket commitments as a condition of line-fit selection. Maintenance, repair, and overhaul providers are responding with dedicated nozzle repair stations in Miami, Singapore, and Frankfurt. The shift is elevating the strategic value of captive spare parts forecasting capabilities among tier-1 suppliers.
Aircraft Fuel Nozzle Market Segmentation
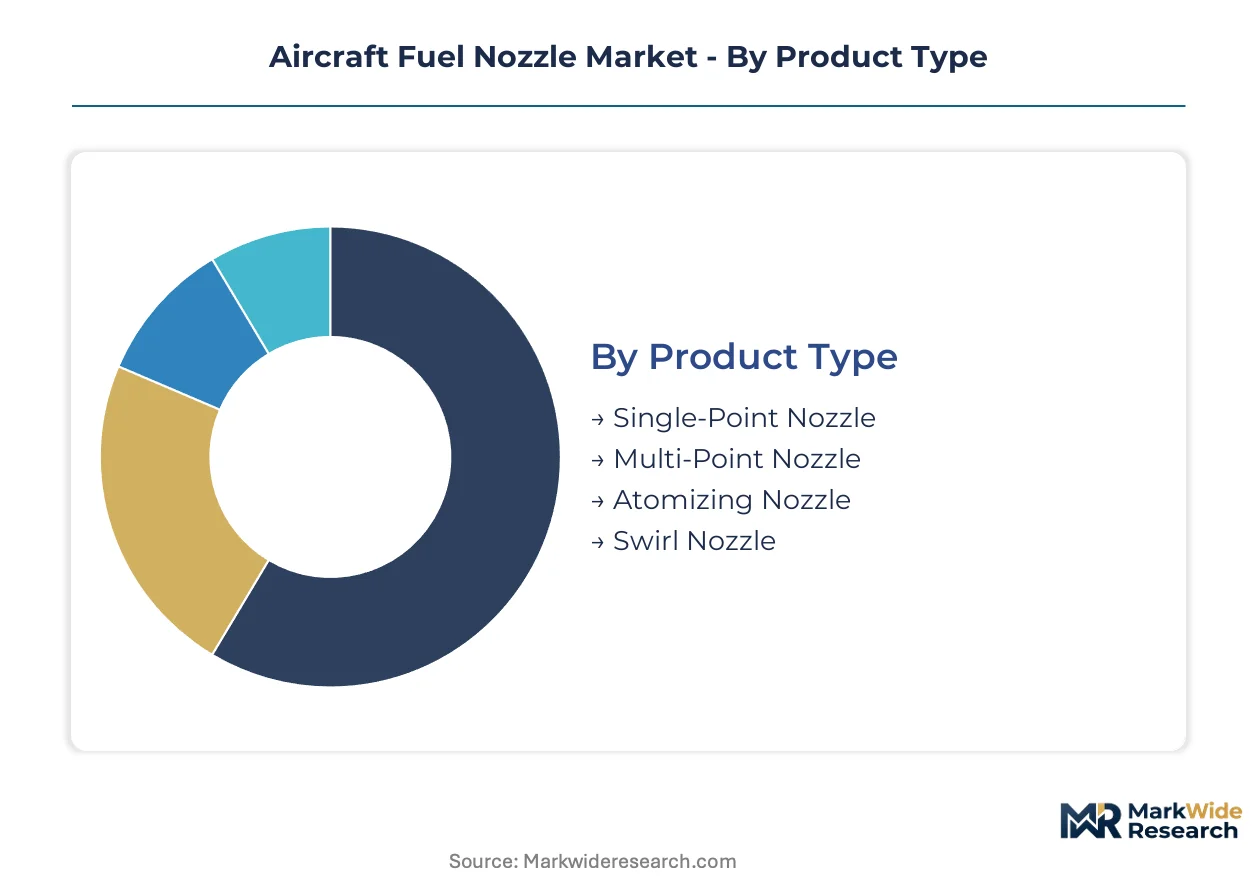
Segmentation in the aircraft fuel nozzle market reveals how engineering specifications and procurement patterns split across distinct performance tiers. Supply chain configuration varies dramatically by material grade and technology generation, with qualified vendors clustering around narrow-body OEM programs and defense procurement channels.
Product Type:
Supply concentration for finished nozzle assemblies tracks engine platform certification status, with LEAP and GTF program approvals creating captive supplier relationships that resist price competition.
- Multi-Point Nozzle:Staged combustion architectures require precisely metered fuel delivery across multiple injection points to achieve lean-burn emission targets. Demand concentrates in China as COMAC C919 production ramps and domestic carriers retrofit existing narrow-body fleets. FAA Part 33 nitrogen oxide mandates compel OEMs to specify these configurations in new engine certifications.
- Single-Point Nozzle:Simpler fuel metering devices serve legacy turbofan designs and auxiliary power units where combustion chamber geometry permits centralized injection. General aviation and business jet refurbishment programs in the United States sustain aftermarket volume for this mature design category.
- Atomizing Nozzle:Specialized geometries optimize droplet size distribution for HEFA and synthetic paraffinic kerosene blends with divergent viscosity profiles.
- Swirl Nozzle:Centrifugal fuel injection patterns enhance flame stability in high-altitude relight scenarios for military turboshaft applications.
Multi-point configurations absorb the bulk of installed capacity; atomizing geometries are expanding most quickly as sustainable aviation fuel compatibility requirements harden.
Material:
Raw material sourcing geography directly shapes cost tier stratification, with sponge titanium supply vulnerability creating premium pricing bands that OEMs absorb through long-term purchase agreements.
- Titanium:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades deliver exceptional strength-to-weight ratios for rotating hardware and hot-section components. Weight reduction priorities at Airbus and Boeing procurement desks are elevating specification share for titanium-intensive nozzle designs. Russian and Kazakh sponge supply concentration exposes programs to forced substitution risks during trade disruption events.
- Stainless Steel:17-4 PH and 15-5 PH precipitation-hardening grades dominate fuel-wetted surfaces requiring corrosion resistance without full superalloy temperature capability. India's PLI scheme for precision-engineered components is attracting machining capacity for stainless nozzle subassemblies in Bangalore clusters.
- Inconel:Nickel-chromium superalloys withstand combustion temperatures exceeding 1,700°C in primary zone applications.
- Composite:Ceramic matrix composite shrouds and external insulation layers reduce conductive heat losses in advanced combustor architectures.
Titanium captures the steepest expansion trajectory as OEMs prioritize fuel burn reduction; stainless steel retains the largest installed base across in-service commercial fleets.
Application:
End-use procurement scale determines supplier qualification investment thresholds, with commercial line-fit programs demanding dedicated manufacturing cells that smaller military and business aviation contracts cannot justify.
- Commercial Aviation:Narrow-body delivery schedules at Chinese, Indian, and Vietnamese carriers concentrate demand for line-fit nozzle assemblies and initial provisioning spares. EASA certification timeline extensions for new fuel system designs are delaying revenue recognition on some next-generation programs.
- Military Aviation:Defense procurement agencies in the United States and France specify hardened fuel systems with enhanced electromagnetic compatibility and battle damage tolerance.
- Business Aviation:Fractional ownership fleets and corporate flight departments drive aftermarket refurbishment cycles for mature turbofan platforms.
- General Aviation:Piston-engine fuel injection hardware serves training and recreational aircraft with simpler mechanical governor systems.
Commercial applications command the dominant share of manufacturing capacity; military programs are gaining share fastest as defense budgets reorient toward tactical airlift modernization.
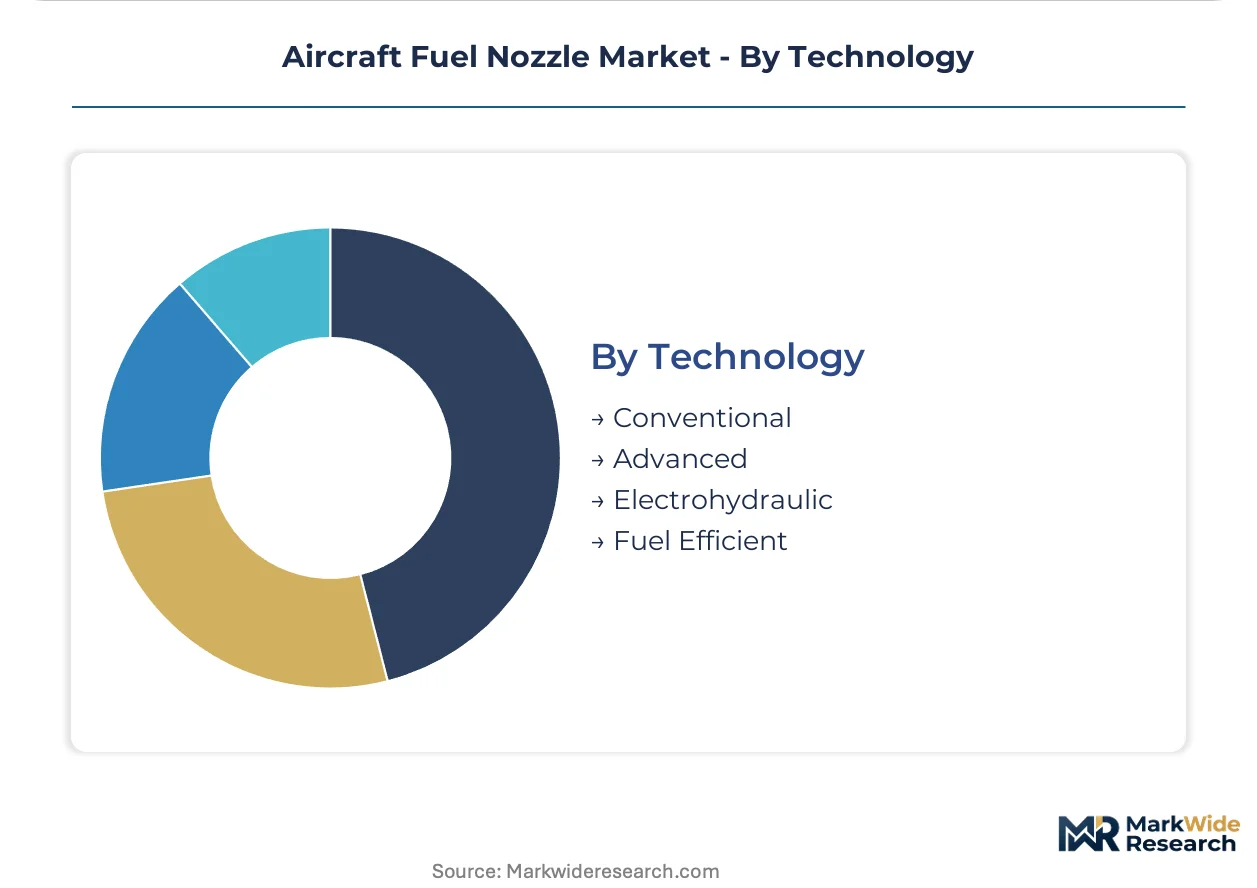
Technology:
Control system architecture separates legacy mechanical installations from retrofit-eligible electrohydraulic upgrades, with technology generation determining maintenance interval economics and fleet-wide deployment feasibility.
- Electrohydraulic:Integrated electronic fuel control enables real-time flow modulation across variable operating envelopes, reducing specific fuel consumption by enabling precise lean-burn scheduling. Retrofit demand is accelerating as airlines seek to extend economic life of mechanical-fleet assets without full engine replacement. Adapter interface complexity for legacy fuel control unit integration complicates upgrade campaign economics.
- Fuel Efficient:Optimized flow coefficients and reduced leakage tolerances support airline sustainability commitments and carbon offset compliance strategies.
- Advanced:Additive manufacturing qualification for titanium aluminide swirlers is collapsing minimum economic order quantities and enabling part consolidation.
- Conventional:Purely mechanical hydro-mechanical units persist in general aviation and certain regional turboprop applications where electronic system weight penalties outweigh efficiency gains.
Conventional technology retains the largest installed population; electrohydraulic systems are climbing the fastest as fleet retrofit programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sponge titanium supply from Russian and Kazakh production facilities anchors cost structures across multiple manufacturing geographies. FAA certification requirements in the United States and EASA specifications in Europe create divergent compliance pathways. China's COMAC production scaling and India's PLI scheme for precision components are redrawing regional demand maps.
United States
Commercial narrow-body fleet modernization at American, Delta, and United Airlines sustains line-fit nozzle demand. FAA Part 33 emissions standards compel OEMs to specify advanced atomizing geometries in new engine certifications. Connecticut's precision machining clusters host concentrated superalloy CNC programming expertise for heat-resistant alloy components.
China
COMAC C919 production ramping and domestic carrier fleet expansion concentrate demand for line-fit nozzle assemblies. CAAC implements parallel type-certification pathways that extend design validation timelines for imported assemblies. Shanghai and Xi'an manufacturing corridors scale ground support infrastructure modernization programs.
Germany
Stuttgart and southwestern Germany host aging workforces with concentrated five-axis CNC programming expertise for Inconel superalloys. EASA revised CS-E engine certification specifications have lengthened validation protocols for new fuel system designs. Munich-area precision engineering clusters supply specialized atomizing geometries for European narrow-body platforms.
India
Production-linked incentive frameworks for precision-engineered components attract tier-2 nozzle manufacturers. Bangalore and Hyderabad machining clusters establish dedicated capacity for stainless nozzle subassemblies. IndiGo and Air India narrow-body delivery schedules generate concentrated spare provisioning requirements.
France
Safran SA anchors domestic demand through specialized atomizing geometries for European narrow-body platforms. French defense procurement agencies specify hardened fuel systems with enhanced electromagnetic compatibility for tactical airlift modernization. Toulouse aerospace corridor maintains captive aftermarket pull through integrated propulsion system bundling.
Aircraft Fuel Nozzle Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing qualification and sustainable aviation fuel compatibility niches. The supplier base concentrates around engine platform certification status, with LEAP and GTF program approvals creating captive relationships that resist price competition. Three archetypes dominate: integrated propulsion system bundlers, specialized atomizing geometry specialists, and precision machining contract manufacturers. Competitive moves center on additive manufacturing process qualification and long-term aftermarket commitment extraction from airline technical procurement departments.
Among diversified industrial conglomerates, Honeywell International Inc. and GE Aviation exemplify integrated system bundlers that leverage captive aftermarket pull. Parker Hannifin Corporation occupies a position within the precision fluid control tier. Safran SA represents European-based specialization in narrow-body platform geometries. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Eaton Corporation |
| GE Aviation |
| Meggitt PLC |
| Collins Aerospace |
| Parker Hannifin Corporation |
| Safran SA |
| GKN Aerospace |
| Woodward, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FAA/EASA-qualified and non-certified nozzle assemblies manifests in pricing spreads exceeding three-to-one, with supply chain configurations clustering around Connecticut and southwestern Germany machining corridors for premium tiers while Indian PLI-subsidized clusters capture commoditized stainless subassemblies.
Pricing Analysis
Warranty and aftermarket service bundling separates line-fit procurement contracts from unbundled spare part transactions, with OEM captive suppliers commanding 15-year maintenance commitments as table stakes. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier, volume scale, and after-sales coverage depth. Cost compression in standard-grade titanium nozzles is intensifying because Russian sponge supply disruption forces material substitutions. Military procurement agencies exhibit lowest price sensitivity due to electromagnetic compatibility hardening requirements, while Indian tier-2 carriers drive hardest bargain on initial provisioning spares.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns, compelling tier-1 suppliers to establish Bangalore machining capacity for stainless nozzle subassemblies. Sponge titanium feeds from Russian and Kazakh production facilities, Inconel superalloy billets from Connecticut rolling mills, and precision forgings from southwestern German clusters. Single-source vulnerability concentrates in sponge titanium supply given geographic concentration of primary extraction. Distribution runs through engine OEM captive logistics networks for line-fit, with independent aftermarket channels serving refurbishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around additive manufacturing qualification capabilities, with EASA timeline extensions and superalloy machinist scarcity forcing sub-scale precision engineering houses toward exit.
For Market Incumbents: Hedge titanium input exposure through long-term offtake agreements with Kazakh alternative suppliers and accelerate backward integration into directed energy deposition process qualification. Lock in airline technical procurement departments with 10-year spare parts forecasting commitments before additive manufacturing collapses minimum order quantities. Threat substitution from laser powder bed fusion entrants demands preemptive certification investment in titanium aluminide swirlers.
For New Entrants and Emerging Players: Urban air mobility propulsion system manufacturers represent an underserved buyer archetype requiring miniature fuel injection hardware outside traditional commercial aviation qualification pathways. Target eVTOL platform developers in California and Texas test facilities with rapid-prototype additive manufacturing capabilities and sustainable aviation fuel compatibility testing. Go-to-market angle centers on collapsing development cycles for distributed propulsion architectures.
For Investors and Strategic Acquirers: Re-rating potential sits with additive manufacturing-qualified precision machining specialists given accelerating replacement cycles for electrohydraulic retrofits. Long-term viability frames around 5-10 year fleet modernization windows as airlines extend mechanical-fleet economic life. Acquisition target archetype: Connecticut or German five-axis CNC programming shops with captive superalloy expertise. Signal to watch: CAAC type-certification timeline compression for COMAC C919 derivative programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Qualification | Directed energy deposition for Inconel components collapses lead times for LEAP and GTF engine variants. |
| Long-term Aftermarket Commitment | Airline technical procurement consolidation elevates spare parts forecasting capabilities to strategic priority. |
| Sustainable Aviation Fuel Compatibility | HEFA and SPK blend viscosity profiles necessitate modified nozzle flow coefficient retrofit programs. |
| India PLI Scheme Manufacturing Footprint | Bangalore and Hyderabad clusters attract tier-2 capacity for stainless nozzle subassemblies. |
| Urban Air Mobility Propulsion Partnership | eVTOL platform developers require miniature injection hardware outside traditional commercial aviation channels. |
Methodological Framework
Document review covered FAA airworthiness directives, EASA CS-E certification specifications, EPA stationary source regulations, and COMAC production disclosures, complemented by interviews with propulsion system procurement directors, five-axis CNC programming specialists, airline technical fleet managers, and additive manufacturing process engineers. Secondary validation drew from engine OEM annual filings, customs trade data for titanium sponge movements, and precision engineering cluster employment statistics. Bottom-up build from individual nozzle program approvals and top-down cross-reference against narrow-body delivery schedules enabled triangulation.
Historical delivery trajectories were cross-referenced against panel input from propulsion system executives to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, material grade, application category, and technology generation. CAGRs were derived from slope analysis of engine program ramp rates and fleet retrofit penetration curves. Forecast inputs incorporated CAAC type-certification timeline assumptions and sustainable aviation fuel mandate implementation schedules.
Revisions become necessary when EASA certification protocol amendments, Russian titanium supply disruptions, or sustainable aviation fuel specification changes materialize beyond current regulatory baselines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Global Aircraft Pumps Market