
 Contactless Ticketing Market | 2026-2036
Contactless Ticketing Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Ticketing Market Outlook
EMVCo certification for contactless payment acceptance is unwinding the competitive landscape for transit system integrators. Cubic Corporation leverages its installed base across North American transit agencies to sustain long-term service contracts. Infineon Technologies anchors semiconductor supply for secure element chips used in NFC-enabled transit cards. Thales Group competes through its dual strength in telecommunications and payment security infrastructure.
Contactless ticketing encompasses fare collection systems that use near-field communication, QR codes, or radio-frequency identification to authenticate and process passenger payments without physical ticket exchange. NFC deployments operate at 13.56 MHz with transaction completion under 500 milliseconds, enabling tap-and-go boarding across buses, metros, and commuter rail. QR code technology leads in emerging markets where smartphone penetration outpaces dedicated transit card issuance, while NFC dominates in mature transit networks where bank-issued contactless cards double as fare media. Mobile wallet integration represents the fastest-growing deployment channel as transit operators bypass proprietary card issuance.
PCI Security Standards Council frameworks govern payment data protection in contactless ticketing architectures, while EMVCo defines terminal-chip interoperability for open-loop transit acceptance. The Federal Transit Administration in the United States and the European Commission's urban mobility directives both incentivize fare system modernization tied to decarbonization targets. Stakeholders must monitor regulatory divergence between closed-loop transit card ecosystems and open-loop bank card acceptance, as this tension determines capital allocation between proprietary infrastructure and interoperable payment rails.
Market Dynamics
The transition from closed-loop transit cards to open-loop bank card acceptance is restructuring capital deployment across fare collection infrastructure, forcing operators to choose between proprietary system upgrades and interoperable payment rail integration.
Growth Catalysts
- EMVCo Certification Mandates:Transit agencies in France, Germany, and Italy now require EMVCo-certified terminals for open-loop payment acceptance, accelerating hardware refresh cycles and vendor consolidation.
- Urban Metro Expansion:Dense metropolitan rail networks in São Paulo, Mexico City, and Jakarta are deploying multimodal fare platforms that unify bus, metro, and micro-mobility payments under single digital wallets.
- NFC Protocol Standardization:ISO/IEC 14443 Type A/B interoperability is eliminating regional fragmentation in contactless card formats, reducing procurement complexity for transit operators.
Market Restraints
- Secure Element Supply Concentration:Production of certified NFC controller chips concentrates among three semiconductor foundries in Taiwan and South Korea, creating vulnerability to geopolitical supply disruptions.
- Legacy Infrastructure Sunk Costs:Transit agencies in Boston, Chicago, and Philadelphia face stranded asset risk from proprietary smart card systems installed during the 2000s that resist open-loop retrofit.
- QR Code Substitution Pressure:Low-cost QR-based ticketing in Indian and Indonesian urban bus networks is displacing NFC investment in markets where smartphone penetration exceeds bank card issuance.
Strategic Opportunities
- Account-Based Ticketing Convergence:The fusion of transit payment credentials with mobile identity frameworks is enabling fare capping and concession automation without physical card issuance.
- EU Green Deal Mobility Credits:The European Commission's carbon-linked transit incentive programs are creating funded deployment windows for integrated multimodal platforms in Poland, Romania, and Portugal.
- Biometric Fare Authentication:Facial recognition payment gates at Shenzhen Metro and Moscow Central Circle are piloting contactless boarding without cards or devices, opening new hardware categories.
Industry Challenges
- EMVCo Certification Timeline Compression:Terminal manufacturers face 18-24 month approval cycles for transit-specific contactless acceptance, delaying revenue recognition on new deployments.
- Interoperable Fare Engine Integration:Transit agencies must reconcile real-time clearing between closed-loop card balances and open-loop bank settlements, requiring complex middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Ticketing Market |
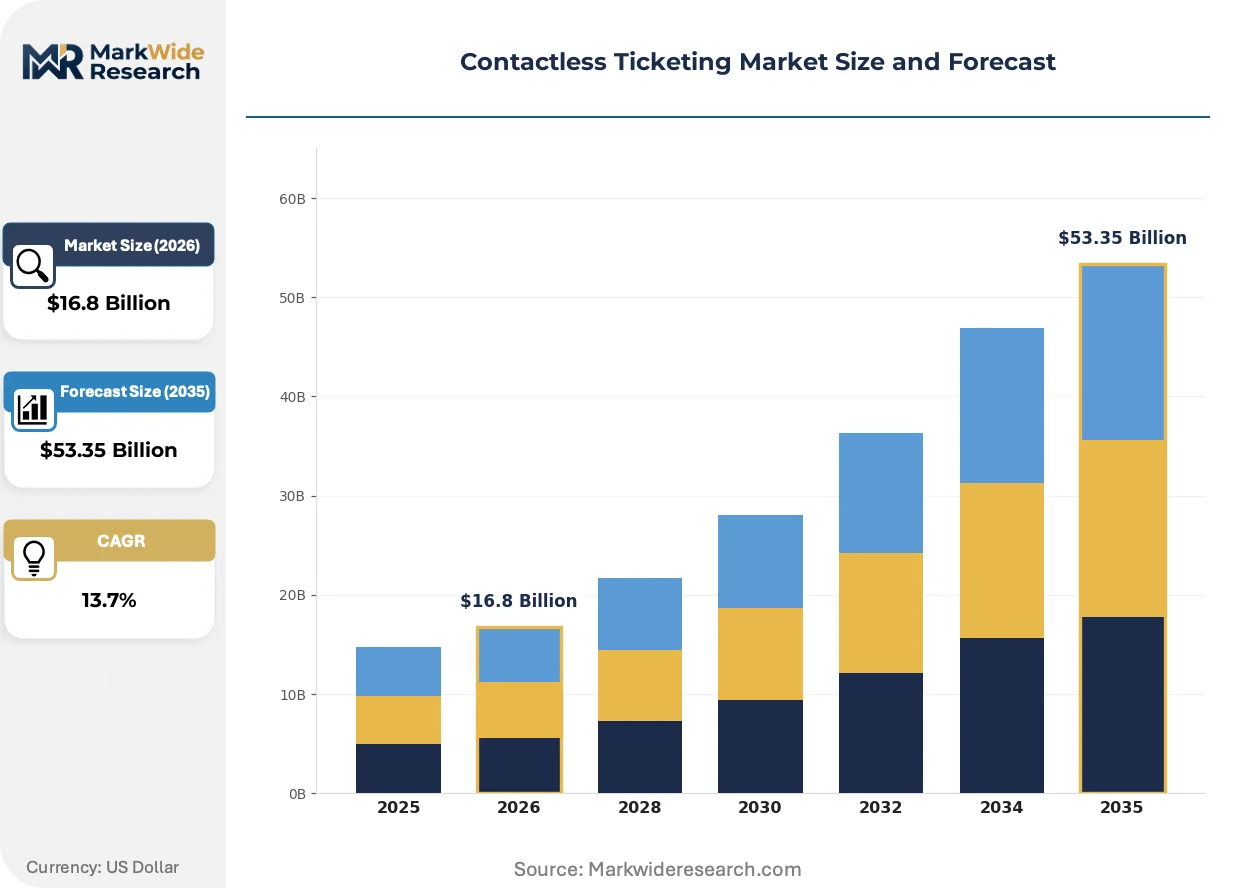
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $53.35 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: NFC, QR Code, Bluetooth, RFID End User: Transportation, Entertainment, Sports, Events Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Payment Method: Credit Card, Mobile Wallet, Bank Transfer, Others |
| Companies Covered | Conduent, Giesecke + Devrient, Cubic Corporation, Vix Technology, IDEMIA, Thales Group, HID Global, Infineon Technologies, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Ticketing Market Strategic Shifts
Contactless ticketing architectures are converging around software-defined fare engines that decouple payment acceptance from proprietary hardware, enabling transit operators to swap terminal vendors without system rebuilds.
Secure element technology is miniaturizing into embedded SIM and integrated UICC form factors, allowing transit credentials to reside directly in smartphones and wearables without separate physical cards. Transit operators in Tokyo, London, and Singapore are migrating to this architecture to eliminate card distribution and replacement costs. The shift is compressing the addressable market for dedicated transit card manufacturers while expanding semiconductor content per user.
The EU's Payment Services Directive 3 is mandating open banking interfaces for transit fare platforms, requiring real-time account-to-account payment rails as alternatives to card network processing. This regulatory pressure is fragmenting payment acceptance architectures across European transit agencies. Operators in Amsterdam, Barcelona, and Vienna are responding with dual-rail systems that maintain card network compatibility while building direct bank connectivity.
Rider preference for subscription-based mobility packages is displacing single-ride ticket purchases in dense urban corridors. Transit agencies in Stockholm, Vienna, and Melbourne are unbundling fare products into daily, weekly, and monthly digital passes sold through app stores rather than ticket vending machines. This channel migration is most visible in Nordic markets where cash acceptance has already been eliminated from surface transit.
Contactless Ticketing Market Segmentation
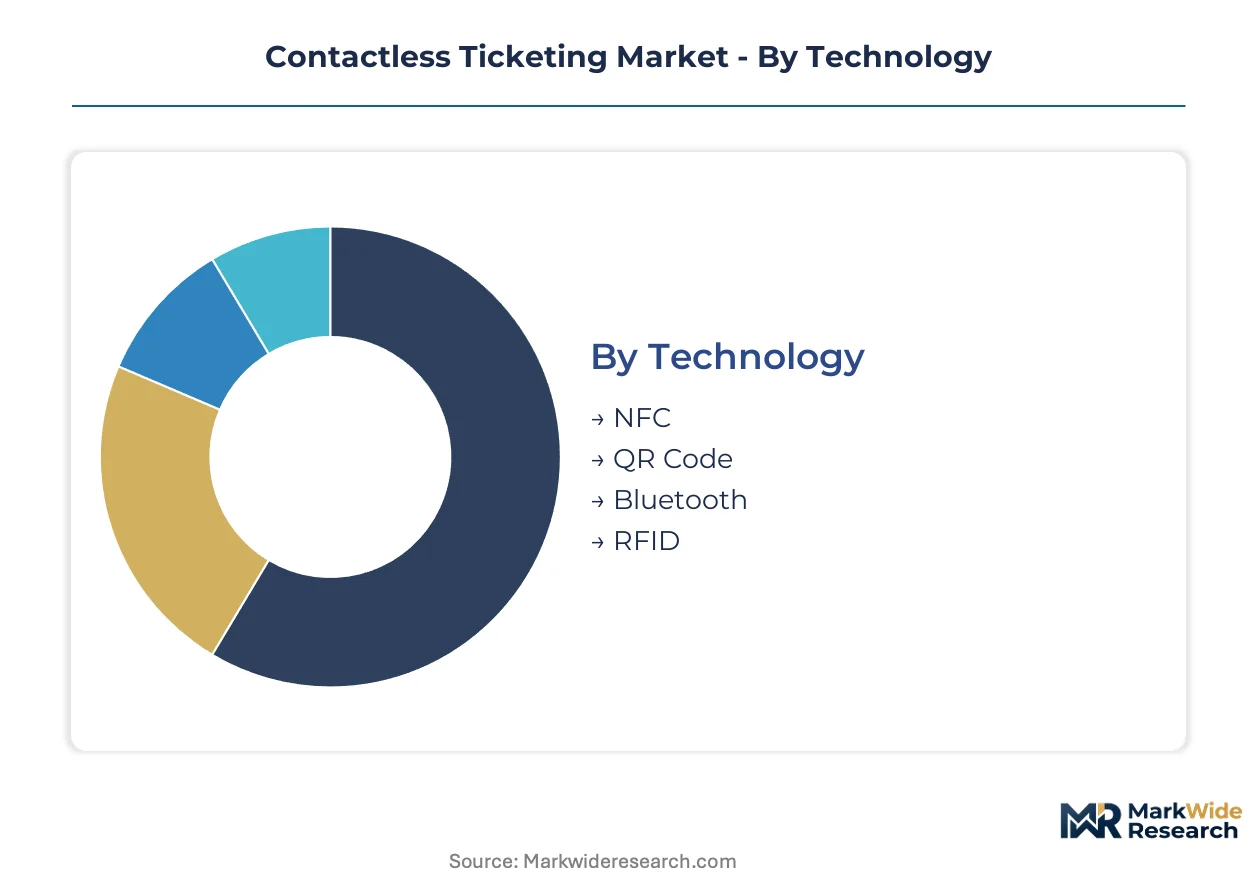
Segmentation in contactless ticketing reveals how technology choices cascade through infrastructure investment, operational complexity, and passenger adoption curves. Deployment architecture decisions lock in vendor relationships for decade-long cycles.
Technology:
NFC dominates domestic transit networks where bank card penetration supports open-loop acceptance, while QR code adoption concentrates in export-led emerging markets with smartphone-first user bases.
- NFC:Operates at 13.56 MHz with sub-500 millisecond transaction completion. Demand concentrates in Tokyo, London, and Singapore metro networks where tap-and-go bank cards displace proprietary transit cards.
- QR Code:Requires only smartphone camera functionality without specialized hardware. Deployment accelerates in Jakarta, São Paulo, and Mexico City bus networks where card issuance infrastructure remains underdeveloped.
- Bluetooth:Enables hands-free gate passage at extended range. Trials proceed at Moscow Central Circle and select Shenzhen Metro corridors.
- RFID:Legacy closed-loop systems persist in Boston, Chicago, and Philadelphia where sunk costs resist retrofit.
NFC holds the largest share; momentum sits with QR code expansion in high-smartphone-penetration corridors.
End User:
Cost tier stratification separates capital-intensive transportation infrastructure from event-based deployments with shorter amortization horizons.
- Transportation:Metro, bus, and rail networks require hardened terminals with 99.99% uptime specifications. Investment concentrates in EU Green Deal-funded corridors across Poland, Romania, and Portugal.
- Entertainment:Cinemas and theme parks prioritize throughput speed over interoperability. Deployment favors mobile wallet integration to eliminate physical ticket stock.
- Sports:Stadium access control demands high-volume burst capacity. Season ticket holders drive account-based credential adoption.
- Events:Temporary installations favor rental terminal fleets with rapid configuration. Music festivals and trade shows represent the primary demand cluster.
Transportation commands the deepest infrastructure commitment; events demonstrate the steepest expansion trajectory in post-pandemic attendance recovery.
Deployment:
Volume concentration in cloud-native architectures reflects transit operator preference for operational expenditure models over capital-intensive on-premise hardware ownership.
- Cloud-Based:Software-defined fare engines enable real-time fare policy updates without terminal reprogramming. Adoption spreads among mid-tier European operators in Amsterdam, Barcelona, and Vienna.
- On-Premise:Air-gapped systems serve security-sensitive military and government transit facilities. Maintenance contracts sustain legacy integrator revenue.
- Hybrid:Edge processing for transaction validation with cloud reconciliation. Balances latency requirements against centralized analytics demand.
- Mobile:Credential storage in embedded SIM and integrated UICC form factors. Tokyo, London, and Singapore lead elimination of physical card distribution.
Cloud-based deployment holds the largest share; mobile credential storage is climbing the fastest as semiconductor miniaturization accelerates.
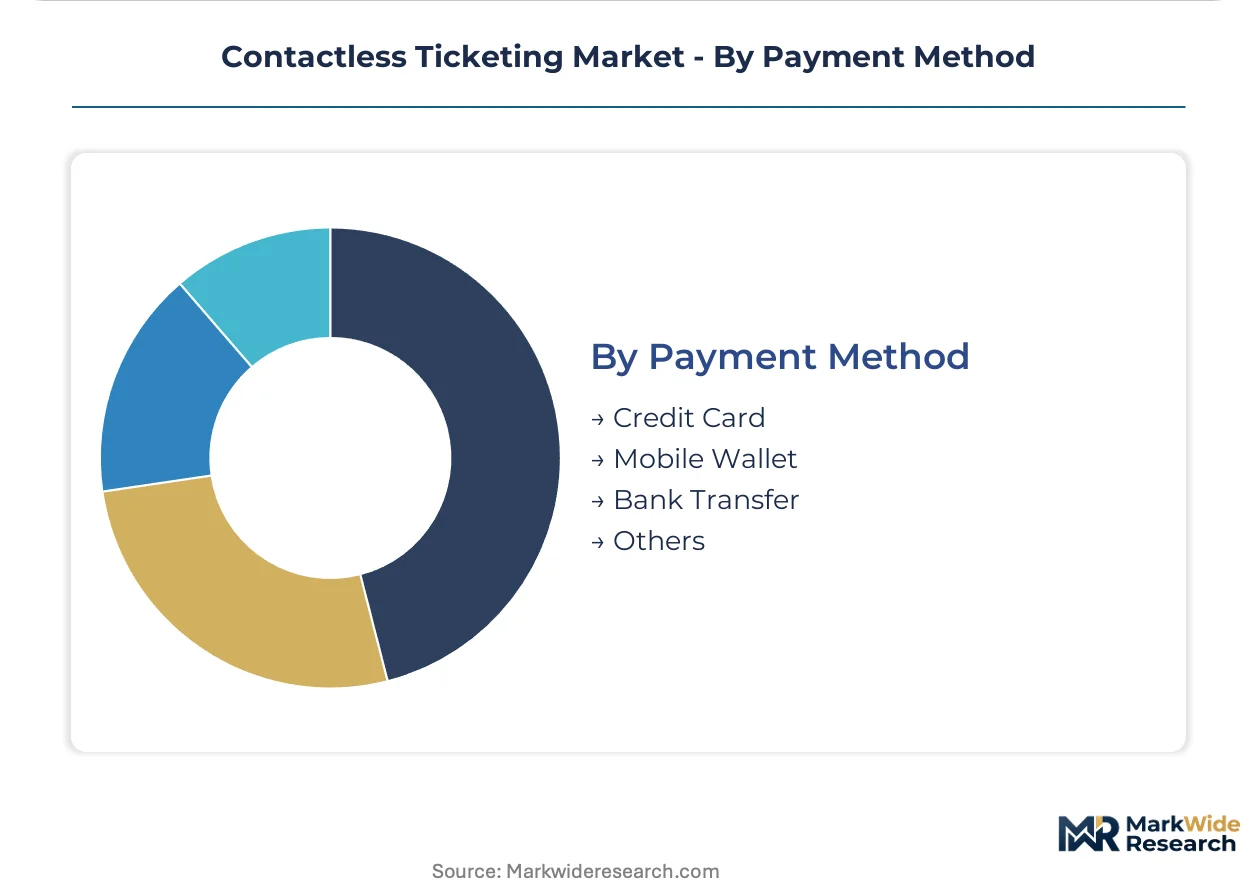
Payment Method:
Customer type divergence splits between banked populations with card network access and unbanked corridors where account-to-account rails gain regulatory support.
- Credit Card:EMVCo-certified open-loop acceptance enables fare payment without transit-specific card issuance. Mandates from French, German, and Italian regulators accelerate terminal refresh.
- Mobile Wallet:Apple Pay, Google Pay, and Samsung Pay integration bypass proprietary transit app development. Stockholm, Vienna, and Melbourne have eliminated cash acceptance from surface transit.
- Bank Transfer:Real-time account-to-account settlement mandated by EU Payment Services Directive 3. Amsterdam, Barcelona, and Vienna deploy dual-rail architectures.
- Others:Prepaid transit cards and cash top-up persist in corridors with partial bank penetration.
Credit card acceptance holds the largest share; bank transfer rails are gaining share fastest under open banking regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London Underground's contactless payment infrastructure underwrites the United Kingdom's role as an open-loop transit pioneer, while Japan's Suica network anchors Asia-Pacific NFC standardization. Transit digitization concentrates in metropolitan corridors where legacy fare collection faces replacement pressure.
United Kingdom
Transport for London's bank card acceptance model drives demand across Transport for Wales and Transport for Greater Manchester networks. The Department for Transport mandates account-based ticketing compatibility in franchised rail services by 2027. Manchester Metrolink and Birmingham West Midlands Metro deploy multimodal fare capping through cloud-native platforms.
Japan
East Japan Railway's Suica and West Japan Railway's ICOCA ecosystems process billions of annual transactions across interoperable transit networks. The Ministry of Land, Infrastructure, Transport and Tourism promotes QR code interoperability standards for inbound tourism corridors. Tokyo Metro and Osaka Metro lead migration to mobile wallet credential storage eliminating physical card distribution.
Germany
Deutsche Bahn's Deutschland-Ticket subscription platform accelerates contactless regional rail adoption across Verkehrsverbünde networks. The Federal Ministry for Digital and Transport funds EMVCo terminal certification through the Digital Rail Germany initiative. Berlin BVG and Munich MVG integrate bike-sharing and car-sharing payments within unified mobility apps.
United States
Metropolitan Transportation Authority's OMNY rollout in New York City pressures Chicago CTA and Boston MBTA to accelerate open-loop retrofits. The Federal Transit Administration's Capital Investment Grants prioritize fare system modernization tied to decarbonization targets. Los Angeles Metro and Seattle Sound Transit deploy cloud-based account-based ticketing with real-time fare capping.
Singapore
Land Transport Authority's SimplyGo platform consolidates bus and rail payments under bank card and mobile wallet acceptance. The Infocomm Media Development Authority mandates NFC interoperability standards for wearable device integration. Downtown Core and Jurong Lake District pilot facial recognition fare gates for hands-free boarding.
Contactless Ticketing Market Competitive Environment
Listed leaders compete with private specialists across fare collection infrastructure, creating a tiered vendor landscape where scale-driven system integrators face agile regional challengers. Cubic Corporation leverages its installed base across North American transit agencies to sustain long-term service contracts, while Infineon Technologies anchors semiconductor supply for secure element chips. Strategic archetypes include full-stack transit system integrators, semiconductor component suppliers, and payment security infrastructure specialists. Competitive moves concentrate on EMVCo certification acceleration and cloud-native fare engine partnerships.
Within the full-stack integrator tier, Cubic Corporation and Thales Group exemplify dual-strength positioning across telecommunications and payment security infrastructure. Infineon Technologies occupies a foundational position in NFC controller supply for transit credential authentication. These three entities represent distinct competitive vectors: installed base leverage, dual-domain expertise, and semiconductor supply concentration.
| Leading Market Players |
|---|
| Conduent |
| Giesecke + Devrient |
| Cubic Corporation |
| Vix Technology |
| IDEMIA |
| Thales Group |
| HID Global |
| Infineon Technologies |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month EMVCo certification timelines compress hardware vendor margins while concentrating pricing power among semiconductor foundries with pre-certified secure element capacity. Transit agencies face procurement trade-offs between premium-certified terminals and lower-tier QR-code alternatives, with supply chain bottlenecks in Taiwan and South Korea amplifying tier separation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hardware procurement, with EMVCo certification grade and after-sales service bundling as the primary differentiation drivers. Pricing pressure stems from QR-code substitution in high-smartphone-penetration corridors, compressing NFC terminal margins. Municipal transit agencies exhibit highest price sensitivity due to budget constraints, while national rail operators demonstrate lowest sensitivity given decarbonization-linked funding access.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Rotterdam and Busan-Los Angeles trade lanes strain terminal manufacturer margins, particularly for EU-funded deployment windows. Semiconductor fabrication concentrates in Taiwan and South Korea, with legacy terminal assembly anchored in China and Mexico. Supply chains draw from silicon wafers, NFC controller chips, and hardened enclosure materials, with single-source vulnerability in certified secure element production. Distribution runs through system integrator partnerships rather than direct agency sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contactless ticketing sits in early-cycle expansion as account-based ticketing architectures displace proprietary card issuance across OECD transit networks. EMVCo certification mandates and EU Green Deal mobility credits accelerate replacement demand beyond traditional infrastructure refresh cycles.
For Market Incumbents: Shield installed base revenue by accelerating cloud-native fare engine partnerships that reduce terminal switching costs for transit agencies. Deepen backward integration into secure element sourcing through foundry relationships in Taiwan and South Korea to offset semiconductor supply concentration risk. Prioritize EMVCo certification pipeline investment to compress approval timelines below competitor benchmarks. For New Entrants and Emerging Players: Mid-tier European operators in Poland, Romania, and Portugal represent underserved white-space as EU funding windows outpace incumbent deployment capacity. Target account-based ticketing middleware development where legacy integrators lack real-time clearing expertise. Pursue partnership-first go-to-market positioning with cloud infrastructure providers to bypass hardware certification barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture infrastructure play because EMVCo certification creates durable moats around terminal supply and service contracts. Acquisition targets should display dual-rail payment competence spanning card network and open banking interfaces. Monitor EU Payment Services Directive 3 implementation velocity as the signal for bank-transfer rail displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Acceleration | Compresses 18-24 month approval cycles to capture EU-funded deployment windows ahead of competitors. |
| Cloud-Native Fare Engine Partnership | Enables transit agencies to swap terminal vendors without system rebuilds, reducing switching friction. |
| Account-Based Ticketing Middleware Development | Addresses real-time clearing complexity between closed-loop balances and open-loop bank settlements. |
| Secure Element Foundry Relationship | Secures captive supply of NFC controller chips from Taiwan and South Korea concentration points. |
| Dual-Rail Payment Architecture Deployment | Maintains card network compatibility while building direct bank connectivity under EU PSD3 pressure. |
Study Parameters
The analysis maps NFC terminal hardware, QR-code platforms, fare engine software, and secure element semiconductors, each validated through transit agency procurement officers, system integrator program managers, semiconductor supply chain directors, and payment security certification leads. Primary fieldwork combined structured interviews with secondary validation against EMVCo certification databases, Federal Transit Administration capital grant disclosures, EU urban mobility directive filings, and customs trade data for NFC component flows. Bottom-up segment sizing triangulated against top-down infrastructure investment tracking.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled technology type, deployment architecture, payment method, and end-use vertical, with regional regulatory cluster as an additional transit-specific dimension. CAGRs derived from infrastructure replacement cycle analysis, EMVCo mandate adoption curves, and EU Green Deal funding disbursement patterns. Fare capping policy diffusion and mobile wallet penetration trajectories served as industry-specific forecast inputs.
Underlying assumptions cover EMVCo certification timeline stability, Taiwan-South Korea semiconductor supply continuity, and EU mobility credit funding persistence, with deviation risk concentrated in geopolitical disruption to secure element production and QR-code substitution acceleration in emerging markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Electric Kick Scooters Market