
 Global Automotive Lubricants Aftermarket Market | 2026-2036
Global Automotive Lubricants Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Lubricants Aftermarket Market Intelligence
The proliferation of franchise-based service models for independent workshops is reshaping competitive positioning in the service channel. This asset-light approach allows smaller players to access branded supply chains and marketing support. Shell plc leverages its extensive global brand recognition to support its network of branded service centers. Valvoline Inc. specializes in the quick-lube service model, directly competing with dealership service bays. TotalEnergies SE similarly extends its reach through partnerships with independent garages and retail chains.
The automotive lubricants aftermarket encompasses fluids sold for servicing vehicles post-initial sale, distinct from factory-fill products. These lubricants are formulated from synthetic or mineral base oils and must meet performance specifications like API SN/SP or ACEA C-series standards to ensure engine protection and efficiency. Engine oil represents the largest product type by volume, driven by regular replacement intervals. While the passenger vehicles segment constitutes the largest application base, the commercial vehicles segment offers higher value-per-vehicle due to larger sump capacities and specialized fluid requirements.
Regulatory frameworks heavily influence lubricant formulation and market access. The US EPA's fuel economy mandates push for lower viscosity oils, while Europe's ECHA, under REACH, governs the chemical constituents used in additives. In parallel, China's Ministry of Ecology and Environment (MEE) sets stringent emission standards that dictate lubricant performance. Suppliers must now decide how to balance investment in advanced ICE lubricants against developing new fluid portfolios for electric vehicles.
Market Dynamics
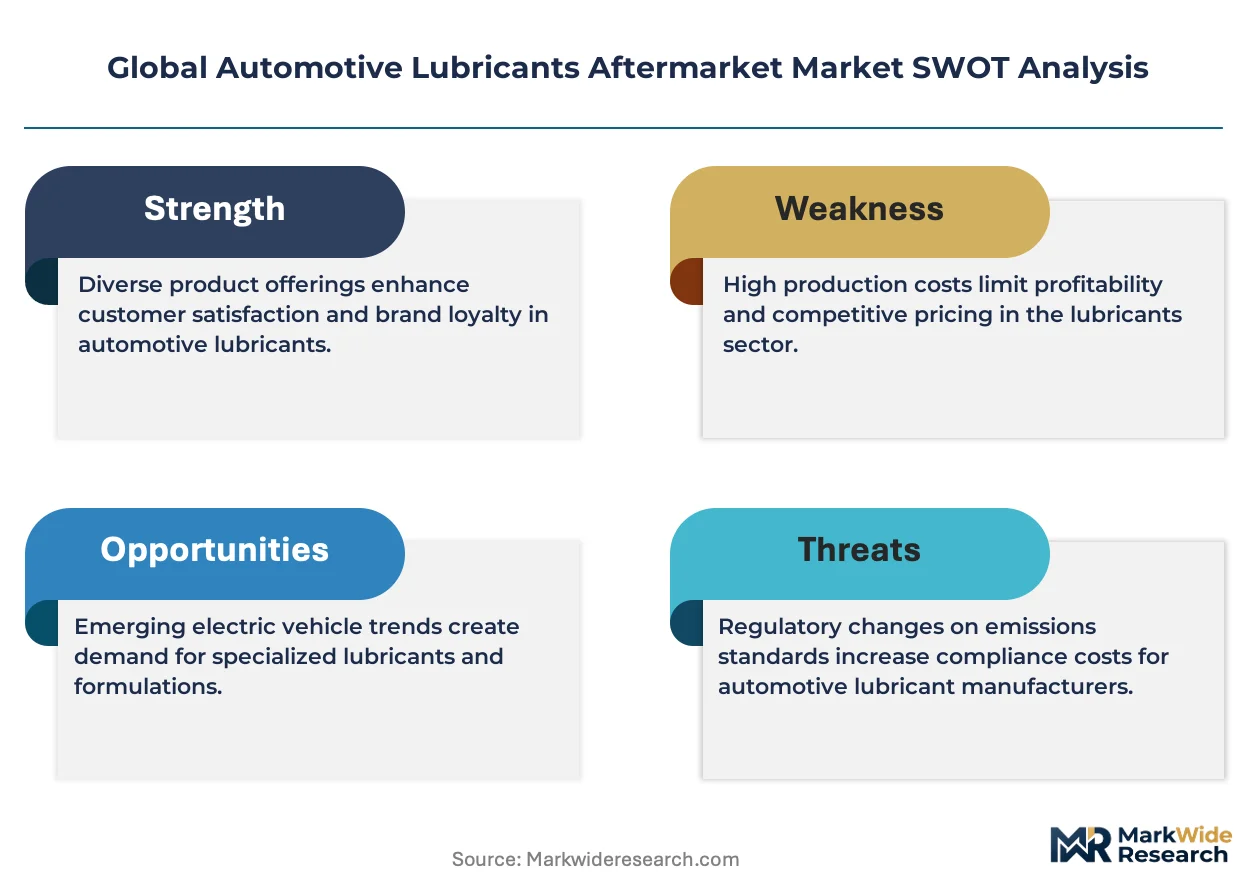
The central dynamic governing the automotive lubricants aftermarket is the bifurcation of research and development. Suppliers must simultaneously innovate advanced, low-viscosity synthetic oils for modern internal combustion engines while also building a portfolio of specialized e-fluids for the emergent electric vehicle parc.
Growth Catalysts
- Aging Vehicle Parc:The expanding and aging population of vehicles, particularly in China, creates a sustained volume of out-of-warranty cars requiring regular service, directly lifting demand for engine oil and other aftermarket fluids.
- Stringent Emission Standards:Regulations like the US EPA's fuel economy mandates and China's MEE emission standards compel the use of higher-performance synthetic lubricants, increasing the value of each oil change.
- Engine Technology Advancement:The proliferation of turbocharged gasoline direct injection (GDI) engines requires specialized lubricants formulated to prevent low-speed pre-ignition (LSPI), creating a new premium product category.
Market Restraints
- Base Oil Price Volatility:The market is sensitive to price fluctuations in Group III and Group IV synthetic base oils, which are tied to crude oil prices and refinery capacity, creating margin pressure for lubricant blenders.
- Electric Vehicle Substitution:The long-term growth of the battery electric vehicle (BEV) market presents a structural threat, as BEVs eliminate the need for engine oil, the largest volume product in the aftermarket.
- Formulation Complexity:Developing a single lubricant that meets diverse and sometimes conflicting OEM specifications alongside global standards like API SP and ACEA C-series is technically challenging and costly.
Strategic Opportunities
- EV Thermal Management Fluids:There is a significant opportunity to develop and market specialized dielectric fluids, coolants, and greases for EV battery packs, e-motors, and power electronics, creating a new high-value revenue stream.
- Service Channel Expansion:Expanding branded quick-lube and independent workshop franchise networks into under-serviced, high-growth markets like Indonesia and Vietnam offers a path to capture new customers.
- Digital Service Platforms:Creating direct-to-workshop digital portals for streamlined ordering, inventory management, and technical support can build loyalty and disintermediate traditional, multi-layered distribution channels.
Industry Challenges
- Regulatory Fragmentation:Managing a global product portfolio requires navigating a complex web of chemical regulations, such as Europe's REACH and specific substance restrictions in countries like South Korea, increasing compliance overhead.
- Combating Counterfeit Products:The persistent issue of counterfeit lubricants, especially prevalent in parts of Africa and Southeast Asia, erodes brand value, poses a risk to consumer vehicles, and requires significant investment in anti-counterfeiting measures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Lubricants Aftermarket Market |
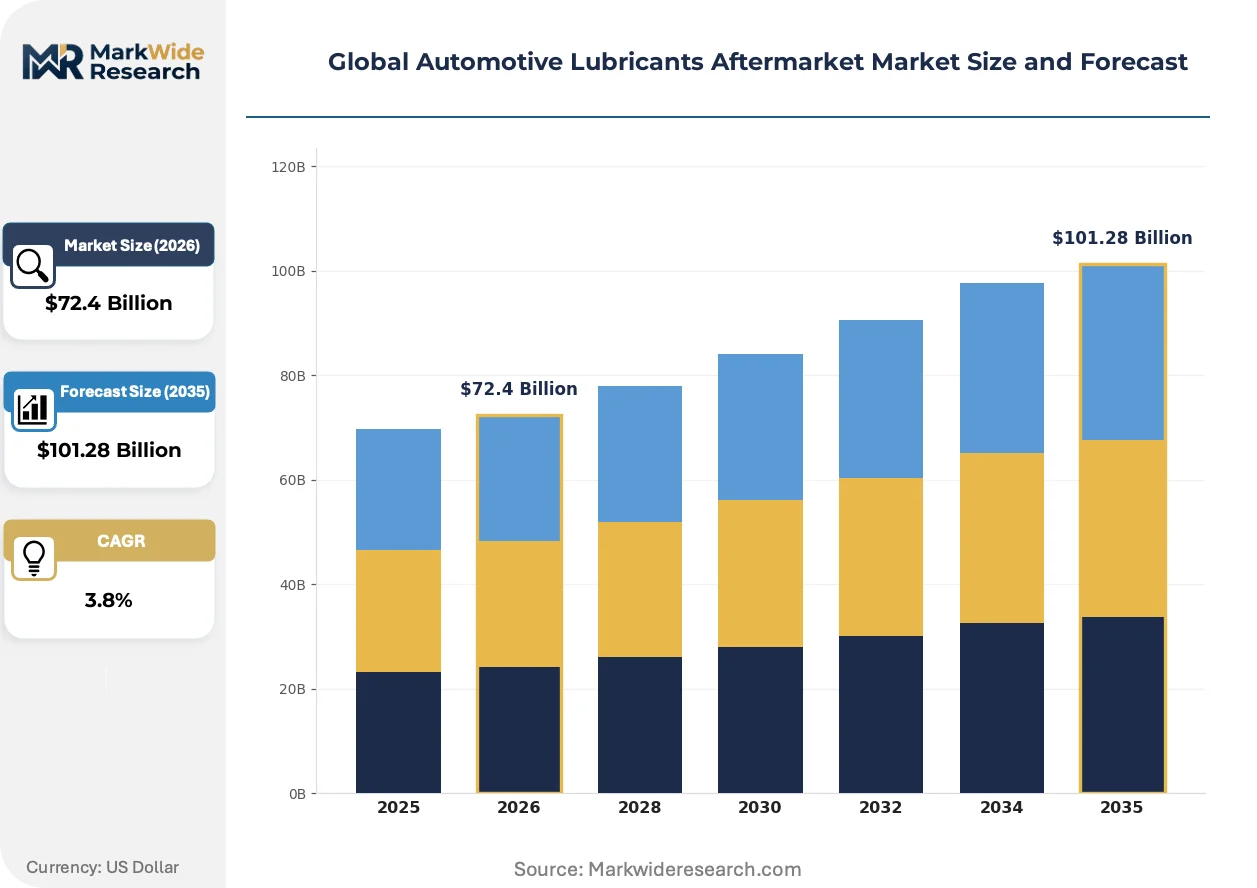
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $101.28 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil, Grease, Brake Fluid Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Highway Vehicles, Industrial Equipment End User: Independent Workshops, Dealerships, Fleet Operators, Vehicle Assemblers, Aftermarket Retailers Distribution Channel: Auto Parts Stores, Online Retailing, Direct Sales, Service Centers, Wholesalers |
| Companies Covered | Chevron Corporation, Sinopec Corporation, Shell plc, Fuchs Petrolub SE, PetroChina Company Limited, ExxonMobil Corporation, TotalEnergies SE, Valvoline Inc., BP p.l.c., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Lubricants Aftermarket Market Strategic Shifts & Innovations
A dual-track evolution defines the market, with product development splitting to serve both increasingly efficient internal combustion engines and the nascent demands of electric vehicle platforms. This divergence forces strategic choices in R&D investment and portfolio management for all suppliers.
Oil condition monitoring systems integrate sensors to analyze lubricant properties in real time. Fleet operators for commercial vehicles are the primary adopters, seeking to optimize drain intervals and prevent catastrophic engine failure. This technology is digitizing the traditional, mileage-based oil change schedule into a predictive, condition-based maintenance model that maximizes asset uptime and reduces total cost of ownership.
Europe's ECHA continues to tighten regulations under its REACH framework, restricting or banning certain chemical compounds historically used in lubricant additive packages. This regulatory pressure forces extensive reformulation efforts, increasing R&D expenditure and lengthening time-to-market for new products. Lubricant suppliers aiming to comply with ACEA performance sequences are most affected, investing heavily in alternative chemistries to maintain engine protection claims.
Consumer behavior is shifting away from do-it-yourself (DIY) oil changes toward do-it-for-me (DIFM) services. This trend disrupts the business model of automotive retail chains, which lose high-margin lubricant sales to quick-lube franchises and independent service workshops. This demand-side evolution is most pronounced in North America, where vehicle complexity and consumer preference for convenience drive the outsourcing of routine maintenance.
Global Automotive Lubricants Aftermarket Market Segmentation
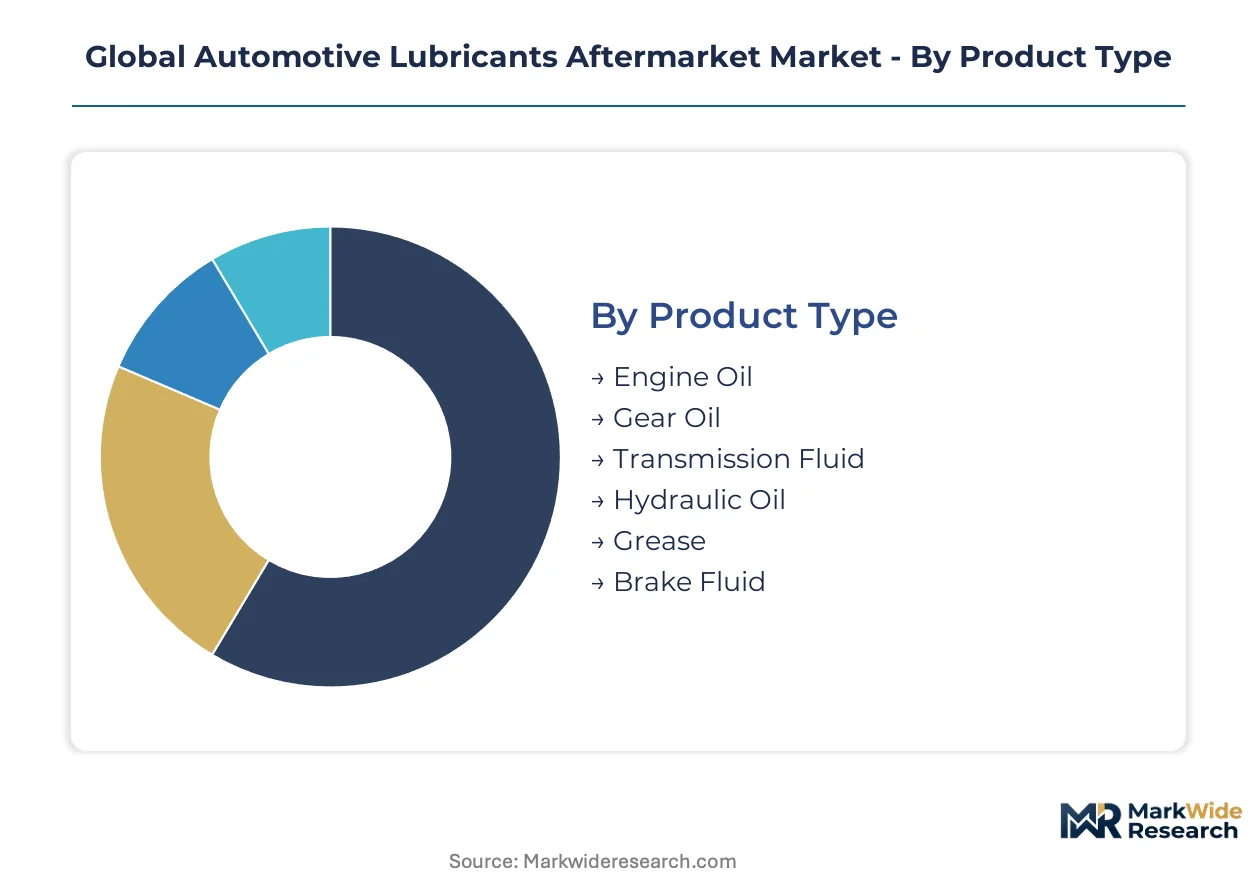
The automotive lubricants aftermarket is strategically segmented to reflect diverse product needs, vehicle applications, and service delivery models. This granular breakdown helps suppliers target specific customer groups and optimize their distribution strategies. Understanding these segments is crucial for navigating market dynamics and identifying growth pockets.
Product Type:
The functional composition of lubricants dictates their performance and application across various vehicle components.
- Engine Oil:Engine oil, primarily formulated from synthetic or mineral base oils, ensures lubrication, cooling, and cleaning of internal combustion engines. Its demand concentrates in China and India due to large vehicle populations and regular replacement intervals.
- Gear Oil:Gear oils protect transmissions and differentials from wear, crucial for heavy-duty commercial vehicles.
- Transmission Fluid:Transmission fluids, including automatic and manual variants, lubricate gears and facilitate power transfer within the drivetrain. The shift towards advanced multi-speed transmissions in North America and Europe drives demand for specialized synthetic formulations.
- Hydraulic Oil:Hydraulic oils transmit power in braking and suspension systems, vital for vehicle control and safety.
- Grease:Greases provide long-lasting lubrication for chassis components and bearings, reducing friction and wear.
- Brake Fluid:Brake fluids transmit hydraulic pressure from the pedal to the calipers, essential for braking efficiency.
Engine Oil holds installed capacity. Transmission Fluid is rotating up the share rankings.
Application:
Customer vehicle types define the specific performance requirements and consumption patterns for aftermarket lubricants.
- Passenger Vehicles:This segment encompasses lubricants for cars and light-duty trucks, representing the largest volume demand due to the sheer number of units. Regular maintenance cycles in Europe and North America drive consistent aftermarket sales.
- Commercial Vehicles:Commercial vehicles, including heavy trucks and buses, require specialized heavy-duty lubricants due to larger sump capacities and demanding operating conditions. Logistics expansion in Southeast Asia fuels significant value-per-vehicle consumption.
- Two-Wheelers:Two-wheelers, prevalent in Asia, require specific engine and gear oils tailored for their smaller engines and air-cooled designs.
- Off-Highway Vehicles:Off-highway vehicles like construction and agricultural machinery demand robust lubricants for extreme operating environments.
- Industrial Equipment:This segment includes lubricants for stationary engines and machinery, distinct from on-road vehicle applications.
Passenger Vehicles maintain the broadest application base. Commercial Vehicles exhibit the steepest expansion trajectory.
End User:
The service model adopted by vehicle owners influences where and how aftermarket lubricants are procured and applied.
- Independent Workshops:These service centers, often franchise-based, cater to out-of-warranty vehicles and represent a large, fragmented customer base. Their expansion in emerging markets like Indonesia captures significant service volume.
- Dealerships:Dealerships primarily service vehicles under warranty, often using OEM-approved lubricants and parts.
- Fleet Operators:Fleet operators for commercial vehicles prioritize total cost of ownership and adopt advanced oil condition monitoring systems. Bulk procurement and specialized fluid requirements characterize this segment in the US and Germany.
- Vehicle Assemblers:Vehicle assemblers primarily use factory-fill lubricants, distinct from the aftermarket segment.
- Aftermarket Retailers:Aftermarket retailers sell lubricants directly to consumers for DIY maintenance or to smaller service shops.
Independent Workshops drive substantial service volume. Fleet Operators are rapidly gaining importance in value-added services.
Distribution Channel:
Market access for aftermarket lubricants is defined by the pathways through which products reach end-users.
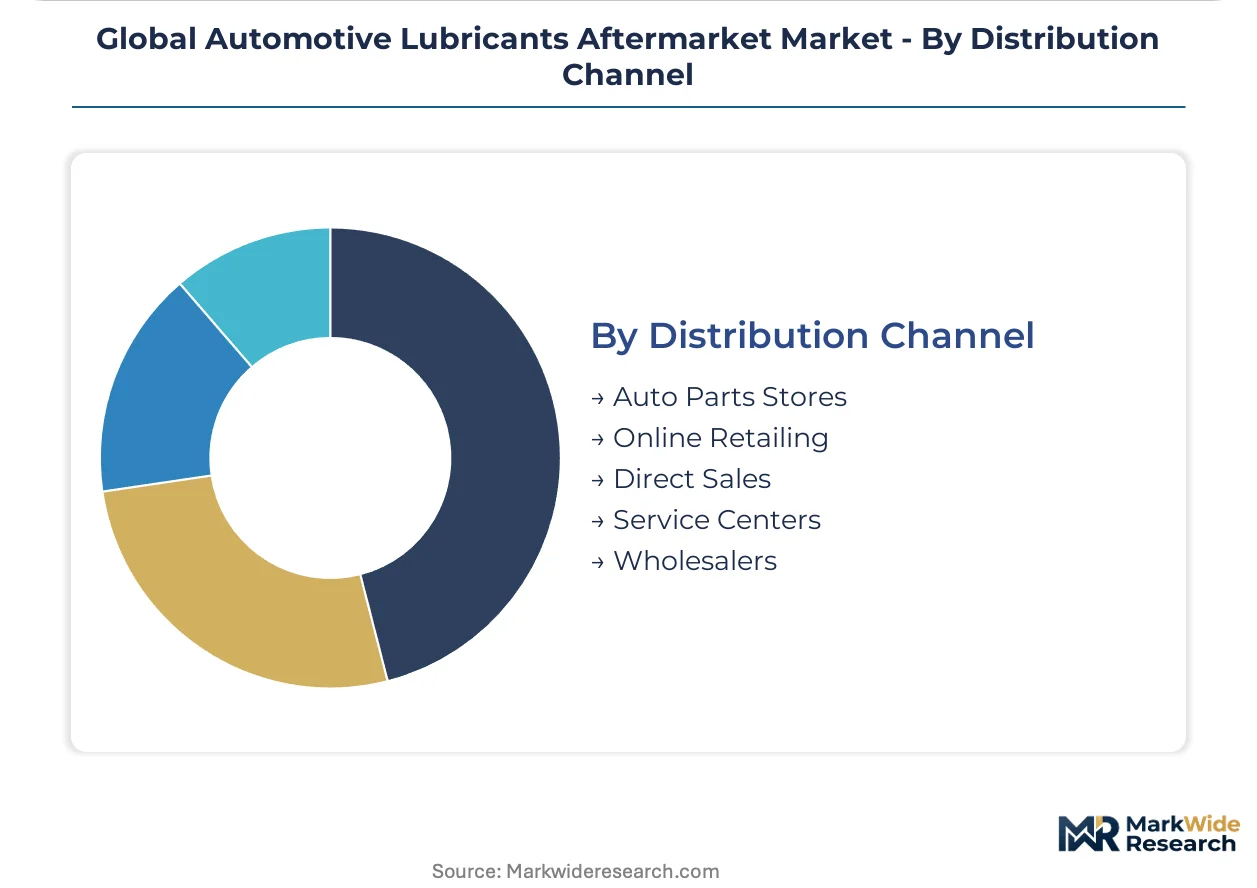
- Auto Parts Stores:Traditional auto parts stores serve both DIY consumers and independent repair shops, offering a wide range of lubricant brands. These stores remain a primary channel in North America for convenient access.
- Online Retailing:E-commerce platforms provide convenience and competitive pricing, increasingly favored by digitally-savvy consumers and smaller workshops. This channel observes accelerated growth in China due to broad digital infrastructure.
- Direct Sales:Direct sales involve manufacturers selling lubricants directly to large fleet customers or industrial accounts.
- Service Centers:Service centers, including quick-lube chains, procure lubricants directly from suppliers or distributors for their service offerings.
- Wholesalers:Wholesalers act as intermediaries, distributing lubricants from manufacturers to various retail and service outlets.
Auto Parts Stores retain a foundational market presence. Online Retailing is quickly expanding its reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive lubricants aftermarket exhibits a complex export-import balance, with raw material supply often originating from distinct regions compared to final product consumption. Lubricant blenders strategically position production facilities near high-demand vehicle markets to optimize logistics and meet localized performance specifications. Regulatory divergence across continents also influences product portfolios and distribution networks, creating distinct regional market characteristics.
China
China's expanding and aging vehicle parc generates substantial demand for engine oil and other aftermarket fluids, particularly in the commercial vehicles segment. The Ministry of Ecology and Environment (MEE) sets stringent emission standards that dictate lubricant performance requirements. The Yangtze River Delta region, a major automotive manufacturing and service hub, demonstrates robust growth in independent workshop networks.
United States
The United States' large passenger vehicle base drives consistent demand for routine maintenance fluids, while fleet operators increasingly adopt advanced oil condition monitoring systems. The US Environmental Protection Agency (EPA) fuel economy mandates push for the widespread adoption of lower viscosity synthetic oils. Automotive research and development in Detroit focuses on advanced lubricant formulations for modern engine technologies.
Germany
Germany's sophisticated commercial vehicle fleet and stringent technical requirements fuel demand for high-performance, specialized lubricants. The European Chemicals Agency (ECHA), under REACH, heavily influences the chemical constituents used in lubricant additive packages. The Stuttgart region, home to major automotive engineering firms, requires advanced fluid solutions for both passenger and heavy-duty applications.
India
India's rapidly expanding vehicle population, including a significant two-wheeler segment, creates a sustained need for engine oils and other essential lubricants. The Bureau of Indian Standards (BIS) ensures quality and performance benchmarks for automotive fluids sold domestically. Chennai, a prominent automotive manufacturing cluster, observes increasing penetration of organized aftermarket service centers.
Indonesia
Indonesia's growing vehicle parc and developing service infrastructure present significant opportunities for service channel expansion, particularly for independent workshops. National environmental regulations are beginning to influence lubricant specifications and product availability. The Jakarta metropolitan area, with its high vehicle density, is a focal point for quick-lube service growth and fluid distribution.
Global Automotive Lubricants Aftermarket Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with a few integrated oil majors dominating base oil production and large-scale blending. These players leverage extensive global distribution networks and brand recognition. Strategic archetypes include integrated energy companies, specialized lubricant manufacturers, and service-focused quick-lube chains. Competitive moves often involve strategic partnerships to expand service channels and portfolio diversification into electric vehicle fluids.
Specialists in service channel expansion, such as Shell plc and Valvoline Inc., exemplify different approaches to market penetration. Shell plc leverages its extensive global brand to support a network of branded service centers, particularly in emerging markets. Valvoline Inc., a US-based company, primarily focuses on the quick-lube service model, directly competing with dealership service bays. TotalEnergies SE similarly extends its reach through partnerships with independent garages and retail chains across various geographies.
| Leading Market Players |
|---|
| Chevron Corporation |
| Sinopec Corporation |
| Shell plc |
| Fuchs Petrolub SE |
| PetroChina Company Limited |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Valvoline Inc. |
| BP p.l.c. |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's expanding refining capacity for Group III base oils directly influences global synthetic lubricant pricing power. This dynamic interplay means localized supply concentration can dictate pricing structures for downstream blenders and end-users.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing for factory-fill lubricants, setting a benchmark for premium aftermarket products. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade (synthetic vs. mineral) and specific certification levels like API SP. Margin pressure stems from volatile Group III base oil prices, impacting blenders. DIY consumers procuring from auto parts stores exhibit the highest price sensitivity, while fleet operators prioritize total cost of ownership over upfront lubricant cost.
Supply Chain Analysis
Export controls on advanced chemical additives for high-performance lubricants could limit flows from key manufacturing hubs. Base oil supply concentrates in the United States, the Middle East, and China, forming critical nodes in the global supply chain. The industry depends on a steady flow of Group III and Group IV synthetic base oils, alongside specialized additive packages. Commodity price volatility for crude oil presents a significant structural risk. Distribution runs through complex, multi-tiered networks involving wholesalers, auto parts stores, and direct sales to large fleet customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat story, primarily due to the high switching costs associated with OEM specifications and the regulatory entrenchment of performance standards.
For Market Incumbents: Insulate core internal combustion engine (ICE) lubricant revenues by investing heavily in advanced formulations that meet stringent MEE emission standards and prevent issues like LSPI. Expand branded quick-lube and independent workshop networks, particularly in high-growth markets like Indonesia, to counter the long-term threat of electric vehicle (EV) substitution. Control distribution channels through strategic partnerships and digital platforms to maintain brand visibility and service quality.
For New Entrants and Emerging Players: Build out specialized portfolios targeting the nascent EV fluids market, including dielectric coolants and greases for battery packs and e-motors. The EV thermal management fluids segment represents the most penetrable white-space opportunity. Leverage digital service platforms to offer streamlined ordering and technical support to independent workshops, providing a compelling go-to-market angle against established players.
For Investors and Strategic Acquirers: Long-term, this sits as an essential consumables play because vehicles require consistent maintenance fluids regardless of propulsion type. Acquisition targets should include specialized lubricant manufacturers with proven EV fluid R&D capabilities or regional quick-lube chains offering strong service channel access. The signal to watch is the accelerated growth rate of the battery electric vehicle market, indicating a shift in long-term product portfolio needs.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand EV Thermal Management Fluids Portfolio | Captures new revenue streams from emergent electric vehicle parc demands. |
| Develop Digital Service Platforms | Streamlines ordering and inventory for independent workshops, building loyalty. |
| Strengthen Independent Workshop Networks | Extends market reach into high-growth markets like Indonesia and Vietnam. |
| Invest in Advanced ICE Lubricant Formulations | Ensures compliance with stringent MEE emission standards for modern engines. |
| Implement Anti-Counterfeiting Technologies | Protects brand value and consumer trust in parts of Africa and Southeast Asia. |
Research Approach
Cross-validation between primary interviews and secondary research anchors the qualitative findings and quantitative projections for this market. The analysis incorporates insights from R&D directors, fleet operators, independent workshop owners, and regulatory affairs specialists. Secondary data sources include OEM technical specifications, API/ACEA performance standards, US EPA fuel economy reports, and ECHA chemical registries, supporting both bottom-up and top-down triangulation.
Volume and value projections are calibrated against historical market performance and macroeconomic indicators across the analysis window. The analytical framework models segmentation dimensions including product type, application, end user, distribution channel, and regional regulatory frameworks. Compound annual growth rates are derived from a comprehensive analysis of demand drivers and market restraints, utilizing industry-specific inputs like vehicle parc growth rates and average drain intervals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated oil majors or specialized lubricant blenders would shift outcomes. This analysis reflects assumptions regarding future regulatory stability and technological adoption rates. Material shifts in base oil supply or vehicle technology adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Global Road Maintenance Market
Vehicle Maintenance & Aftermarket
Car Care Cosmetics Market
Vehicle Maintenance & Aftermarket
Global Integrated Vehicle Health Management Market
Vehicle Maintenance & Aftermarket
Vehicle Wash System Market
Vehicle Maintenance & Aftermarket
Antimicrobial Car Care Products Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
Body Repair Tools Market
Vehicle Maintenance & Aftermarket
Catenary Maintenance Vehicle Market
Vehicle Maintenance & Aftermarket
Automotive Cleaner and Degreaser Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Car Detailing Products Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Vehicle Recycling Market
Vehicle Maintenance & Aftermarket
Car and Truck Wash Market
Vehicle Maintenance & Aftermarket
Motor Winding Repair Service Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market