
 Europe Car Parking Market | 2026-2036
Europe Car Parking Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Car Parking Market Foresight
Steel-reinforced concrete is broadening structural durability thresholds for multi-storey parking facilities across European urban cores. Lödige Industries leverages its vertical parking engineering heritage to anchor premium automated installations in constrained German and Benelux sites. EasyPark Group sustains mobile-first payment penetration through direct municipal partnerships in Nordic cities. Interparking competes on operational scale with consolidated off-street asset control across Southern Europe.
Car parking encompasses the structured provision of vehicle storage spaces through surface lots, multi-level structures, and mechanized vertical systems, typically engineered to support axle loads of 2.5 tonnes per space with integrated drainage, ventilation, and fire suppression subsystems; its commercial purpose centers on monetizing land scarcity in dense urban environments while satisfying municipal planning mandates. Off-street parking commands the dominant revenue pool where land values support structured development, while automated parking represents the fastest-expanding segment as developers seek to maximize vehicle density on footprints below 500 square meters. Smart parking technology concentrates margin capture through recurring software licensing and sensor maintenance contracts layered atop hardware deployments.
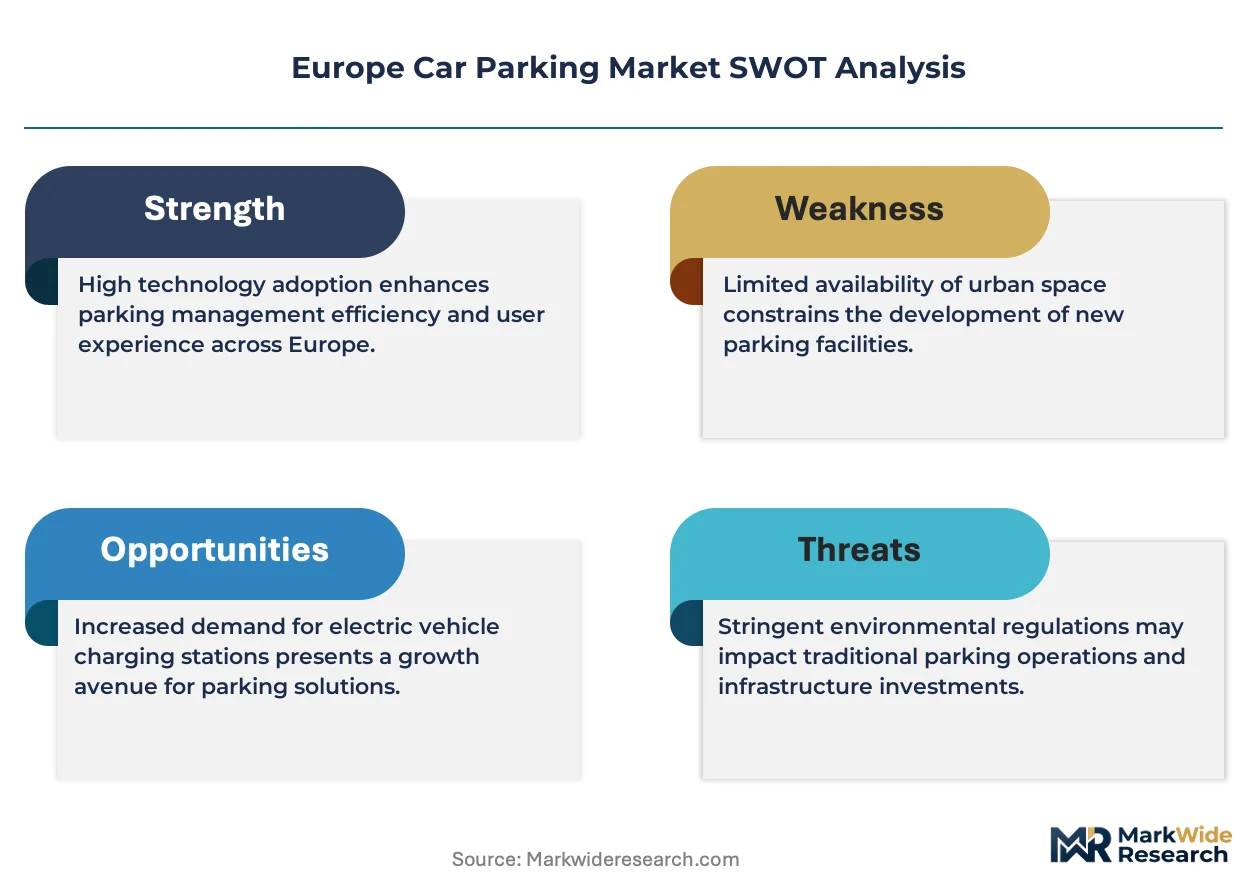
EU Green Deal urban mobility frameworks and national building codes enforced by Germany's KBA and France's ANSM-equivalent regional planning authorities are mandating reduced surface parking ratios and electric vehicle charging readiness in new developments. EMA-adjacent environmental impact assessments for large parking structures are extending approval timelines and elevating compliance costs in sensitive urban zones. Stakeholders must monitor how forthcoming EU AI Act provisions on automated decision systems affect license plate recognition and dynamic pricing algorithms before committing to platform refreshes.
Market Dynamics
EU Green Deal urban mobility directives are compressing surface parking ratios in new developments while mandating electric vehicle charging infrastructure, forcing developers toward vertical and automated systems that maximize vehicle density on constrained footprints.
Growth Catalysts
- EU Green Deal mandates:France's ANSM-equivalent regional planning authorities enforce reduced parking minimums and EV readiness requirements, accelerating structured parking retrofits in dense metropolitan cores.
- Automated vertical systems:Mechanized parking technology enables developers to triple vehicle capacity on footprints below 500 square meters where land scarcity prevents conventional construction.
- German metropolitan density:Berlin, Munich, and Hamburg corridor developments concentrate demand for multi-storey facilities as surface lot expansion becomes physically impossible.
Market Restraints
- Steel-reinforced concrete input volatility:Fluctuating rebar and cement costs compress developer margins on multi-storey structures before operational revenue streams commence.
- EMA-adjacent environmental assessments:Extended approval timelines in sensitive urban zones elevate carrying costs and deter speculative development in premium locations.
- Autonomous vehicle uncertainty:Anticipated reductions in personal car ownership threaten long-term utilization rates for fixed parking assets in forward-looking investment models.
Strategic Opportunities
- Benelux underpenetration:Brussels and Amsterdam central districts lack sufficient automated parking infrastructure relative to German benchmarks, creating first-mover expansion potential.
- Dynamic pricing algorithms:License plate recognition and demand-responsive rate engines enable revenue optimization previously unavailable in static fee structures.
- Building-integrated photovoltaics:Solar canopy installations atop surface and structured facilities generate ancillary revenue streams while satisfying EU Green Deal renewable mandates.
Industry Challenges
- Mechatronics talent scarcity:Automated parking system deployment requires specialized maintenance technicians that European vocational pipelines currently undersupply.
- Legacy municipal payment integration:Fragmented city-level parking management platforms resist standardization, forcing operators to maintain multiple API connections and reconciliation workflows.
- EU AI Act compliance timeline:Forthcoming provisions on automated decision systems create uncertainty for license plate recognition and dynamic pricing algorithm refreshes.
Report Scope
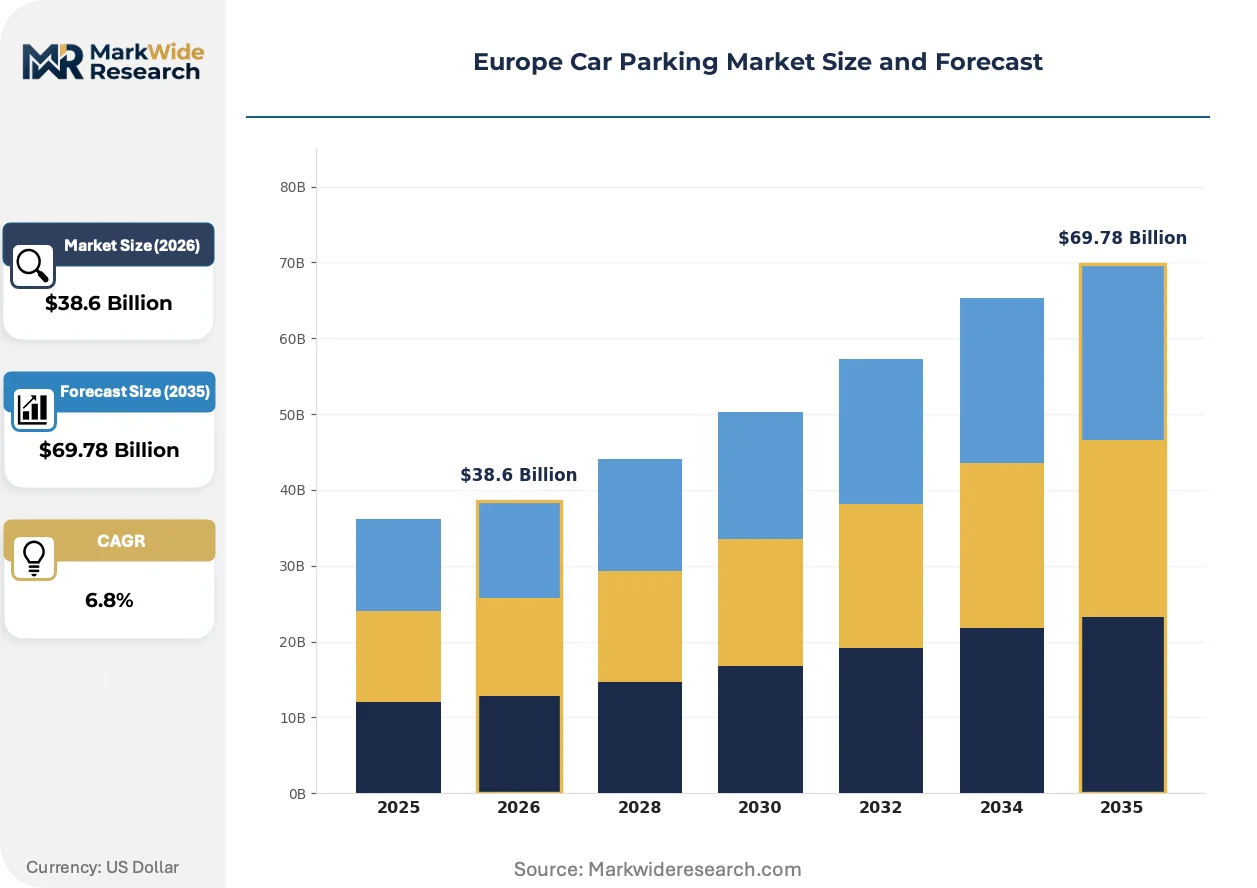
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Car Parking Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Parking Type: On-Street, Off-Street, Multi-Storey, Automated Payment Model: Pay-and-Display, Subscription, Mobile App, Metered End User: Government, Commercial, Residential, Retail Technology: IoT-Enabled, Smart Parking, RFID, License Plate Recognition |
| Companies Covered | EasyPark Group, SpotHero, Lödige Industries, Bmove, VePa Vertical Parking, Interparking, Saba, RAO, Best in Parking AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Car Parking Market Shifts & Advancements
Digital payment convergence and sensor-network densification are transforming parking from static real estate into software-mediated mobility infrastructure with recurring service revenue potential.
Automated mechanical parking systems is expanding into constrained German and Benelux urban sites where conventional multi-storey construction exceeds land area availability. Premium commercial developers in Frankfurt and Rotterdam deploy these systems to satisfy municipal parking mandates while preserving ground-floor retail or residential density. The technology compresses land acquisition requirements by 60-70 percent compared to ramped structures.
EU AI Act provisions on automated decision systems will impose algorithmic transparency requirements on license plate recognition and dynamic pricing engines deployed across European smart parking networks. Operators must document decision logic and enable human oversight interfaces, elevating compliance engineering costs. Germany's KBA and France's regional planning authorities are anticipated to incorporate these standards into facility licensing renewals.
Fleet managers and corporate mobility departments now contract parking access through aggregated platform subscriptions rather than maintaining individual facility relationships. Nordic municipal partnerships with mobile-first payment providers displace single-operator apps as the dominant customer interface. Copenhagen and Stockholm exhibit the most advanced consolidation, with enterprise clients demanding unified billing across multi-city travel patterns.
Europe Car Parking Market Segmentation
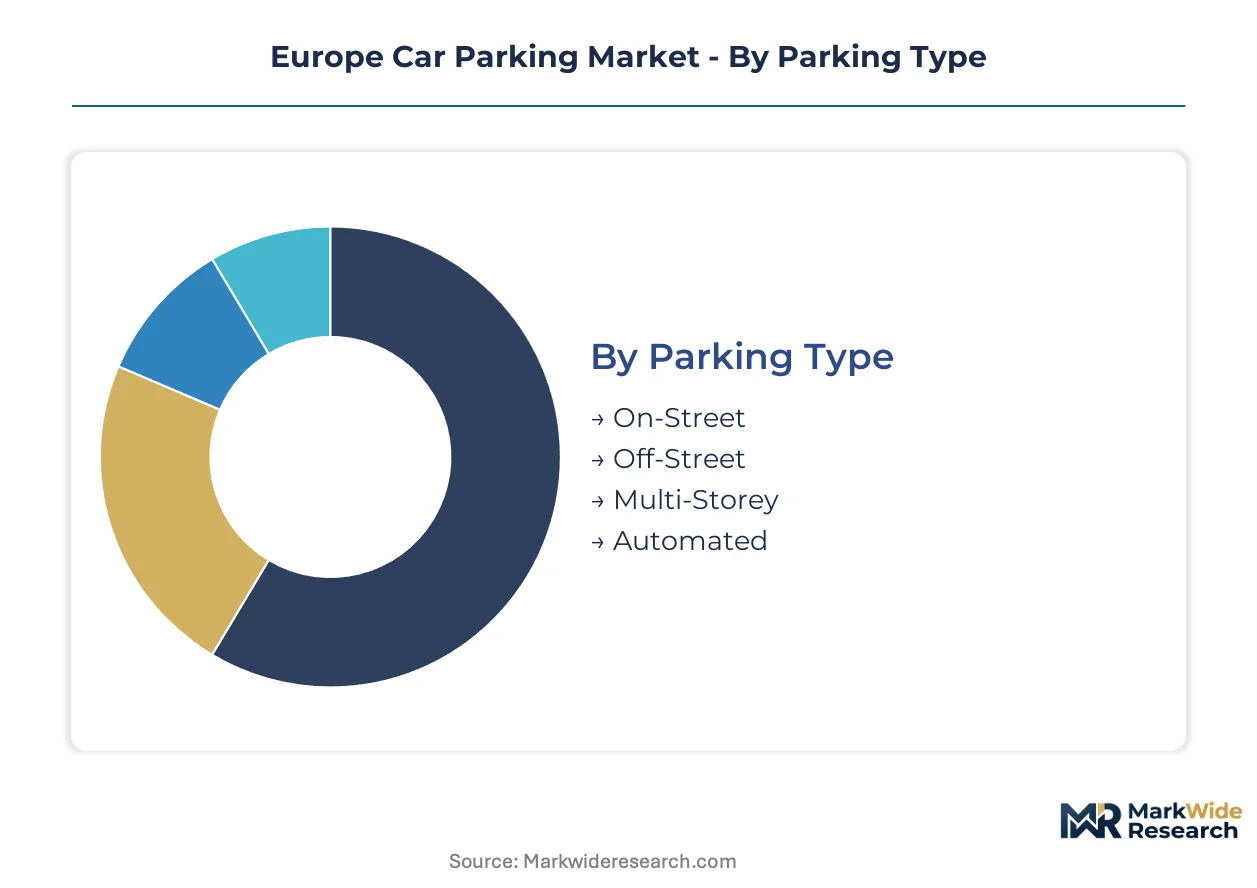
Segmentation reveals how parking infrastructure investment priorities diverge across European regulatory environments and land-constrained urban cores. Upgrade cycles vary dramatically between legacy surface assets and emerging automated systems, reshaping capital allocation patterns for developers and municipal operators.
Parking Type:
Replacement cycles accelerate where EU Green Deal mandates force conversion of surface lots into vertical structures, compressing traditional 30-year asset lifecycles.
- On-Street:Curb-side spaces managed through metered or digital payment systems occupy high-value road corridors. German cities including Munich and Hamburg are reducing on-street ratios to reclaim pedestrian and cycling infrastructure, eroding this segment's share in dense metropolitan cores.
- Off-Street:Surface lots and dedicated parking areas dominate revenue pools where land values support structured development. France's regional planning authorities enforce reduced parking minimums that favor off-street consolidation over dispersed surface provision.
- Multi-Storey:Steel-reinforced concrete structures engineered for 2.5-tonne axle loads with integrated ventilation and fire suppression subsystems. Berlin corridor developments concentrate demand as surface expansion becomes physically impossible.
- Automated:Mechanized vertical systems that triple vehicle capacity on footprints below 500 square meters. Brussels and Amsterdam central districts lack sufficient infrastructure relative to German benchmarks, creating first-mover expansion potential.
Volume placements concentrate in Off-Street; the faster expansion belongs to Automated.
Payment Model:
Customer interface preferences are shifting toward recurring subscription relationships rather than transactional encounters, altering platform architecture requirements.
- Pay-and-Display:Traditional ticket-based systems requiring physical payment at centralized machines. Municipal operators in Southern Europe maintain these installations where digital payment penetration lags Nordic benchmarks.
- Subscription:Monthly or annual access contracts favored by fleet managers and corporate mobility departments. Enterprise clients now demand unified billing across multi-city travel patterns.
- Mobile App:Smartphone-mediated payment and reservation platforms displacing single-operator apps through municipal aggregation. Copenhagen and Stockholm exhibit the most advanced consolidation via direct city partnerships.
- Metered:Time-based charging at individual parking points with variable rate structures. Legacy installations persist where municipal payment platform fragmentation resists standardization.
Revenue concentration sits with Mobile App; Subscription climbs the fastest as enterprise procurement patterns consolidate.
End User:
Procurement authority determines contract scale and technology sophistication requirements across the installation base.
- Government:Municipal and regional authorities managing public parking assets under EU Green Deal urban mobility directives. Procurement prioritizes EV charging readiness and smart sensor integration.
- Commercial:Office and mixed-use developers seeking to maximize vehicle density on constrained footprints. Frankfurt and Rotterdam deployments satisfy parking mandates while preserving ground-floor retail density.
- Residential:Condominium and apartment complex parking provision governed by national building codes. Germany's KBA enforces structural standards for multi-storey residential facilities.
- Retail:Shopping center and high-street parking operations competing on convenience and proximity. Dynamic pricing algorithms enable revenue optimization previously unavailable in static fee structures.
Contract value peaks with Commercial; Residential gains share fastest as urban densification intensifies.
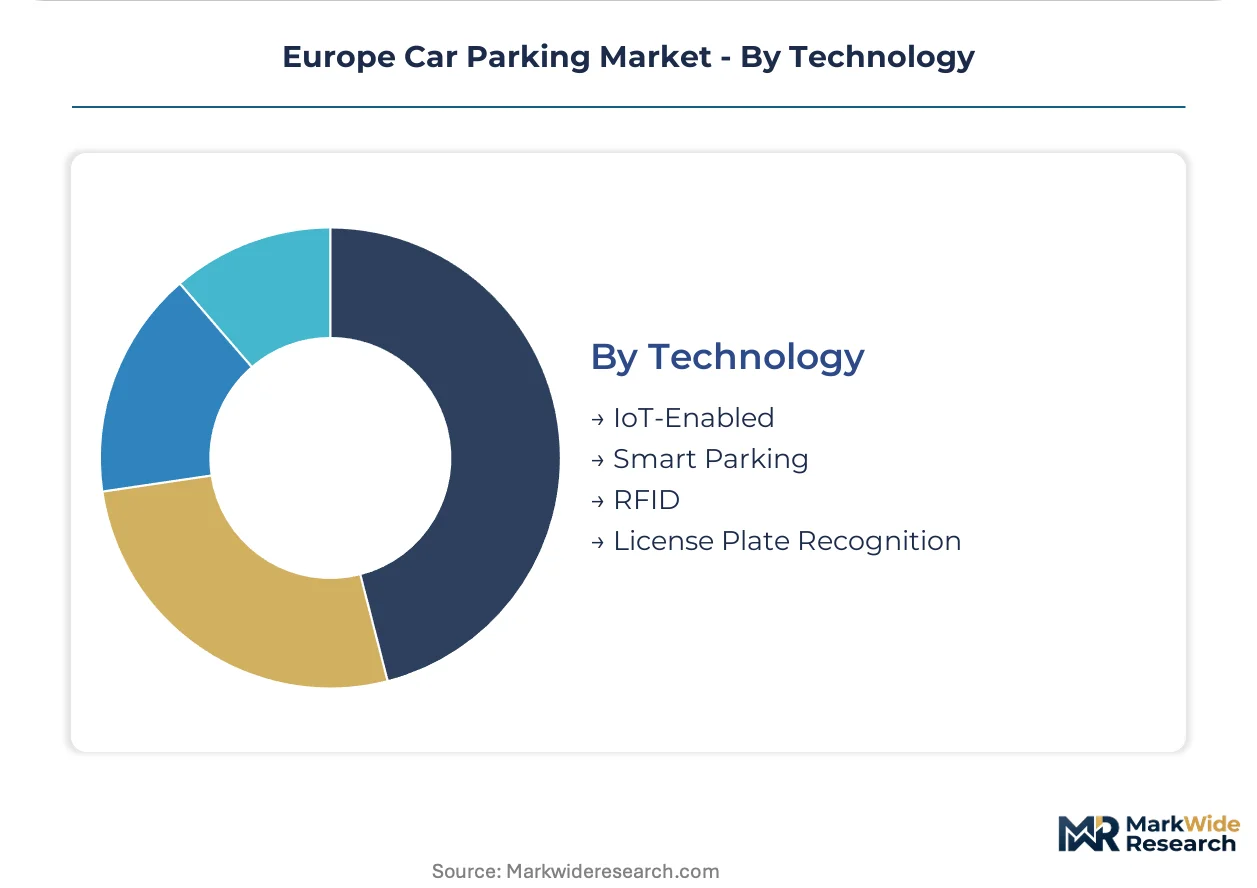
Technology:
Platform refresh cycles compress as EU AI Act provisions impose new compliance requirements on automated decision systems.
- IoT-Enabled:Sensor networks transmitting real-time occupancy and environmental data to centralized management platforms. Hardware deployments layer recurring software licensing and maintenance contracts atop initial installation.
- Smart Parking:Integrated systems combining guidance, payment, and analytics functions. Digital payment convergence transforms static real estate into software-mediated mobility infrastructure.
- RFID:Radio-frequency identification for automated vehicle authentication and access control. Corporate campuses and logistics facilities favor this technology for frictionless entry.
- License Plate Recognition:Optical character recognition systems enabling enforcement and dynamic pricing. Forthcoming EU AI Act provisions impose algorithmic transparency requirements, elevating compliance engineering costs.
Deployment scale favors Smart Parking; License Plate Recognition faces the steepest expansion trajectory pending regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metropolitan corridors concentrate demand for structured parking infrastructure as surface expansion becomes physically impossible in dense urban cores. France and the Benelux region follow with accelerating automated system deployments. Regulatory pressure from EU Green Deal mandates is compressing traditional asset lifecycles across all four markets.
Germany
Berlin, Munich, and Hamburg corridor developments drive multi-storey facility demand as developers maximize vehicle density on constrained footprints. The country's KBA enforces structural standards for steel-reinforced concrete installations with integrated fire suppression subsystems. Frankfurt premium commercial projects deploy automated vertical systems to satisfy municipal parking mandates while preserving ground-floor retail density.
France
Regional planning authorities enforce reduced parking minimums and EV readiness requirements that accelerate structured parking retrofits in dense metropolitan cores. The ANSM-equivalent bodies mandate environmental impact assessments that extend approval timelines in sensitive urban zones. Paris and Lyon central districts exhibit the most advanced consolidation of off-street assets under single operational control.
Netherlands
Amsterdam central districts lack sufficient automated parking infrastructure relative to German benchmarks, creating first-mover expansion potential for mechanized vertical systems. Municipal partnerships with mobile-first payment providers displace single-operator apps as the dominant customer interface. Rotterdam developers deploy building-integrated photovoltaics atop structured facilities to satisfy EU Green Deal renewable mandates.
Belgium
Brussels urban core presents underpenetration in automated parking relative to neighboring German and Dutch markets. The country's national building codes align with EU Green Deal urban mobility directives that compress surface parking ratios in new developments. Antwerp corridor projects concentrate demand for smart sensor integration and license plate recognition systems.
Sweden
Stockholm exhibits the most advanced municipal aggregation of parking access through unified billing platforms across multi-city travel patterns. The country's regional planning authorities prioritize EV charging readiness in all new off-street developments. Gothenburg corporate mobility departments contract parking access through platform subscriptions rather than maintaining individual facility relationships.
Europe Car Parking Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with operational scale operators controlling consolidated off-street assets while engineering heritage firms anchor premium automated installations. The vendor base organizes into three strategic archetypes: municipal partnership platforms, vertical system engineers, and consolidated asset operators. Capacity expansion through automated system deployment and strategic partnerships for payment platform integration represent the dominant competitive moves.
Among Nordic-based mobile-first payment providers, EasyPark Group exemplifies the municipal partnership archetype through direct city relationships. Lödige Industries occupies a position within the vertical engineering tier, representing German heritage in automated parking mechanics. Interparking sits within the scale-driven operational segment, anchoring consolidated asset control across Southern European markets.
| Leading Market Players |
|---|
| EasyPark Group |
| SpotHero |
| Lödige Industries |
| Bmove |
| VePa Vertical Parking |
| Interparking |
| Saba |
| RAO |
| Best in Parking AG |
| Others |
Supply & Pricing Matrix
EU Green Deal mandates for EV-ready structured parking are forcing developers to specify steel-reinforced concrete and mechatronics components that suppliers cannot scale instantly, concentrating pricing power with incumbent material providers and specialized vertical system engineers.
Pricing Analysis
Volume placements favor standardized off-street surface facilities with thin margins, while automated vertical systems capture premium returns through scarcity engineering. Price differentiation hinges on structural certification grade under Germany's KBA standards and after-sales maintenance bundling. Cost compression in multi-storey concrete construction is intensifying because rebar and cement input volatility outpaces operational revenue commencement. Municipal operators exhibit highest price sensitivity due to fragmented procurement budgets, whereas commercial developers absorbing land scarcity premiums show lowest sensitivity.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale commercial projects, while municipal aggregators consolidate fragmented public procurement. Manufacturing concentrates in Germany, the Netherlands, and China for steel-reinforced concrete components and mechatronics subsystems. Production draws from specialized rebar mills, fire suppression system integrators, and sensor network fabricators. Single-source vulnerability sits with European mechatronics talent pipelines that vocational training currently undersupplies. Distribution runs through engineering-procurement-construction contractors for vertical systems and direct municipal contracting for smart sensor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal urban mobility directives have created a supply-constrained environment where automated parking system deployment capacity, not demand, caps market expansion and props developer pricing.
For Market Incumbents: Acquire distressed surface lot portfolios in German metropolitan corridors before EU parking minimum reductions force conversion mandates. Consolidate maintenance technician training pipelines to counter mechatronics talent scarcity threatening service revenue streams. Lock in long-term steel-reinforced concrete supply agreements before rebar volatility compresses multi-storey project margins further. For New Entrants and Emerging Players: EU AI Act algorithmic transparency requirements in Germany open a window for compliance-engineering specialists to capture retrofit demand from legacy license plate recognition installations. Target Brussels and Amsterdam central districts where automated parking infrastructure lags German benchmarks. Lead with municipal partnership aggregation models that displace single-operator apps through unified billing platforms. For Investors and Strategic Acquirers: The window for entry favors vertical system engineers with demonstrated KBA certification track records and established mechatronics maintenance networks. Long-term viability centers on software-mediated recurring revenue rather than hardware installation margins. Watch EU AI Act enforcement timelines as the inflection signal for compliance engineering spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated System Deployment | Triple vehicle density on sub-500 square meter footprints where land scarcity prevents conventional construction. |
| Municipal Payment Platform Integration | Copenhagen and Stockholm aggregation models displace fragmented single-operator apps through unified billing. |
| Mechatronics Talent Pipeline Investment | German vocational training gaps threaten maintenance capacity for vertical system service contracts. |
| Building-Integrated Photovoltaics Installation | Rotterdam developers generate ancillary revenue while satisfying EU Green Deal renewable mandates. |
| License Plate Recognition Compliance Refresh | Algorithmic transparency requirements under EU AI Act elevate engineering costs for dynamic pricing engines. |
Research Methodology
Independent corroboration across municipal planning authority filings, steel-reinforced concrete supplier disclosures, and smart parking platform operator contracts underwrites the qualitative findings. Primary interviews with commercial real estate developers, parking facility operators, mechatronics maintenance technicians, and EU regulatory affairs specialists combined with secondary validation from KBA structural standards documentation, EU Green Deal directive texts, and EMA-adjacent environmental assessment records. Bottom-up project pipeline enumeration triangulates against top-down metropolitan density and vehicle registration forecasts.
Rate-of-change decomposition separates volume growth in off-street surface facilities from value growth in automated vertical systems and smart parking technology licensing across the projection horizon. Segmentation dimensions modeled include parking type, payment model, end user procurement authority, and technology integration tier. CAGRs derive from facility deployment timelines, replacement cycle compression under regulatory mandates, and software licensing renewal patterns. Forecast inputs incorporate EU AI Act compliance cost assumptions and mechatronics technician supply elasticity.
Caveats apply where EU AI Act enforcement timing, autonomous vehicle adoption curves, or steel input volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation consistency and construction cost normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Global Integrated Traffic System Market