
 Fleet Health Monitoring and Diagnostic Analytics Systems Market | 2026-2036
Fleet Health Monitoring and Diagnostic Analytics Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fleet Health Monitoring and Diagnostic Analytics Systems Market Insights
The gap between premium integrated platforms and commodity telematics hardware is shifting from a feature distinction to a data-architecture divide. Geotab leverages its open-platform ecosystem to capture high-margin analytics subscriptions across North American enterprise fleets. Samsara sustains competitive density through vertical software integration that binds sensor hardware to workflow automation. Motive anchors its position in commercial insurance adjacency, where driver safety scoring creates switching costs beyond basic GPS tracking.
Fleet health monitoring and diagnostic analytics systems combine onboard telematics hardware, IoT sensors, and machine learning algorithms to translate vehicle operational data into predictive maintenance intelligence and compliance documentation. These systems process engine fault codes, brake wear indicators, and coolant temperature thresholds through cloud or edge architectures to flag component failures before roadside breakdowns occur. Predictive analytics applications command expanding margin pools as fleets prioritize maintenance scheduling over reactive vehicle tracking, while cloud computing deployment models displace on-premise installations among mid-size logistics providers seeking lower capital burdens. Machine learning technology segments face the steepest capability gradient, separating vendors with trained proprietary models from those reselling third-party inference engines.
The U.S. Federal Motor Carrier Safety Administration's hours-of-service rules and the EPA's greenhouse gas emissions standards for heavy-duty vehicles jointly compel fleet operators to adopt verified diagnostic data streams for compliance reporting. The EU's Green Deal freight transport targets and the F-Gas Regulation on mobile air conditioning systems add parallel compliance layers for European operators, who must document refrigerant leakage through integrated sensor networks. Stakeholders must weigh whether to build captive data infrastructure or accept platform dependency as telematics providers consolidate control over the diagnostic data layer.
Market Dynamics
Machine learning differentiation is compressing margins for telematics resellers while rewarding vendors with proprietary training pipelines and edge-deployment capabilities. The architecture of diagnostic intelligence now separates commodity hardware suppliers from analytics platforms capturing recurring software revenue.
Growth Catalysts
- Predictive maintenance algorithms:Logistics operators deploy machine learning models trained on engine fault code histories to schedule component replacements before roadside failures disrupt delivery contracts.
- F-Gas Regulation:European freight carriers must install refrigerant leakage sensors to document mobile air conditioning compliance, mandating integrated diagnostic hardware upgrades across refrigerated transport fleets.
- German freight corridor density:The concentration of long-haul routes between the Ruhr industrial basin and Hamburg port accelerates real-time diagnostic infrastructure investment to minimize downtime on high-utilization lanes.
Market Restraints
- Semiconductor supply concentration:Telematics control unit production depends on Taiwanese foundry capacity, exposing fleet hardware procurement to geopolitical disruption and extended lead times.
- Cloud subscription cost structures:Mid-size logistics providers face margin pressure from per-vehicle SaaS fees that compound faster than realized fuel savings from predictive maintenance.
- Third-party inference engine dependency:Vendors without proprietary machine learning pipelines pay licensing fees that erode analytics margins and limit customization for specialized fleet configurations.
Strategic Opportunities
- Commercial insurance adjacency:Driver safety scoring derived from diagnostic data streams creates captive relationships with underwriters seeking verified risk telemetry for usage-based policies.
- EU Green Deal freight targets:Emissions documentation requirements for heavy-duty vehicles create demand for integrated sensor networks that combine diagnostic and carbon accounting functions.
- Edge computing convergence:On-vehicle inference chips enable real-time fault analysis without cellular latency, opening subscription tiers for remote-route operators beyond cellular coverage.
Industry Challenges
- Embedded systems engineering scarcity:Fleet technology vendors compete for firmware developers capable of optimizing inference workloads on resource-constrained telematics hardware.
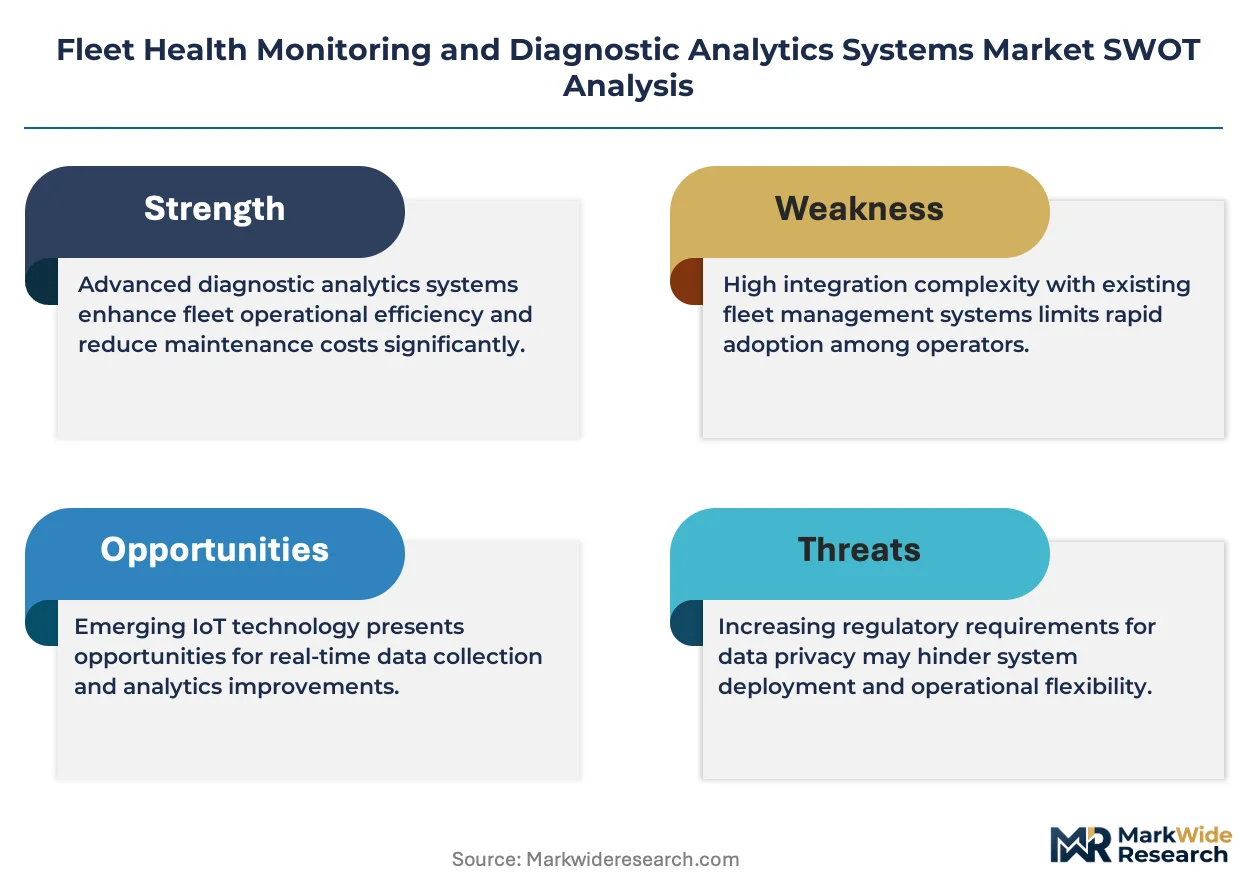
- Legacy fleet integration complexity:Pre-2018 commercial vehicles lack standardized OBD-II data protocols, forcing expensive retrofit kits or exclusion from unified analytics platforms.
- Cross-border data sovereignty:Diagnostic platforms storing driver behavior and location data face fragmented compliance obligations under GDPR, state privacy laws, and emerging sector-specific regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fleet Health Monitoring and Diagnostic Analytics Systems Market |
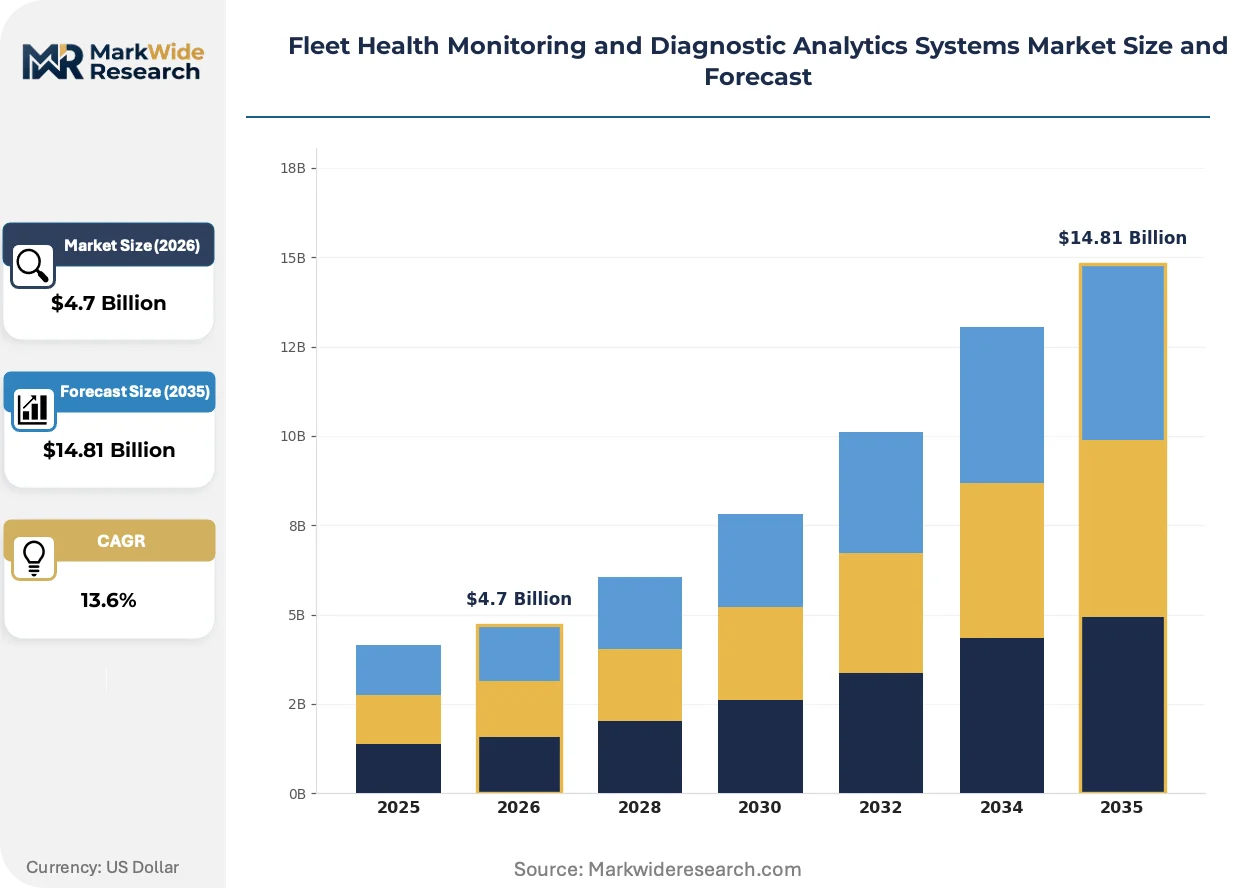
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Telematics, IoT Sensors, Machine Learning, Predictive Analytics, Cloud Computing Application: Vehicle Tracking, Fuel Management, Driver Behavior Analysis, Maintenance Scheduling, Route Optimization End User: Logistics Providers, Public Transportation Agencies, Delivery Services, Construction Firms, Emergency Services Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Geotab, Samsara, Motive, Verizon Connect, Powerfleet, Trimble, Omnitracs, Teletrac Navman, ORBCOMM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fleet Health Monitoring and Diagnostic Analytics Systems Market Trends and Innovations
Diagnostic intelligence is migrating from reactive alert systems toward predictive orchestration of maintenance workflows. The competitive frontier now centers on proprietary data architectures that bind sensor hardware to vertical software applications.
Edge-deployed neural networks are electrifying the latency-performance tradeoff for real-time fault detection. Heavy-duty fleets operating remote mining and timber routes adopt on-vehicle inference chips to process engine telemetry without satellite uplink dependency. This compression of decision loops is enabling predictive maintenance subscriptions for segments previously excluded from cloud-dependent analytics.
EPA greenhouse gas emissions standards for heavy-duty vehicles are mandating verified diagnostic data streams for compliance documentation. Fleet operators must integrate sensor networks that capture fuel consumption, idle time, and auxiliary power unit usage into auditable reporting formats. California-based carriers face the steepest implementation timelines under the state's Advanced Clean Trucks regulation.
Buyers are consolidating vendor relationships around platforms offering workflow automation beyond vehicle tracking. Fleet managers now evaluate diagnostic systems on integration with dispatch software, fuel card programs, and driver payroll systems rather than hardware specifications alone. This bundling preference is most pronounced among North American enterprise logistics providers with centralized procurement functions.
Fleet Health Monitoring and Diagnostic Analytics Systems Market Segmentation
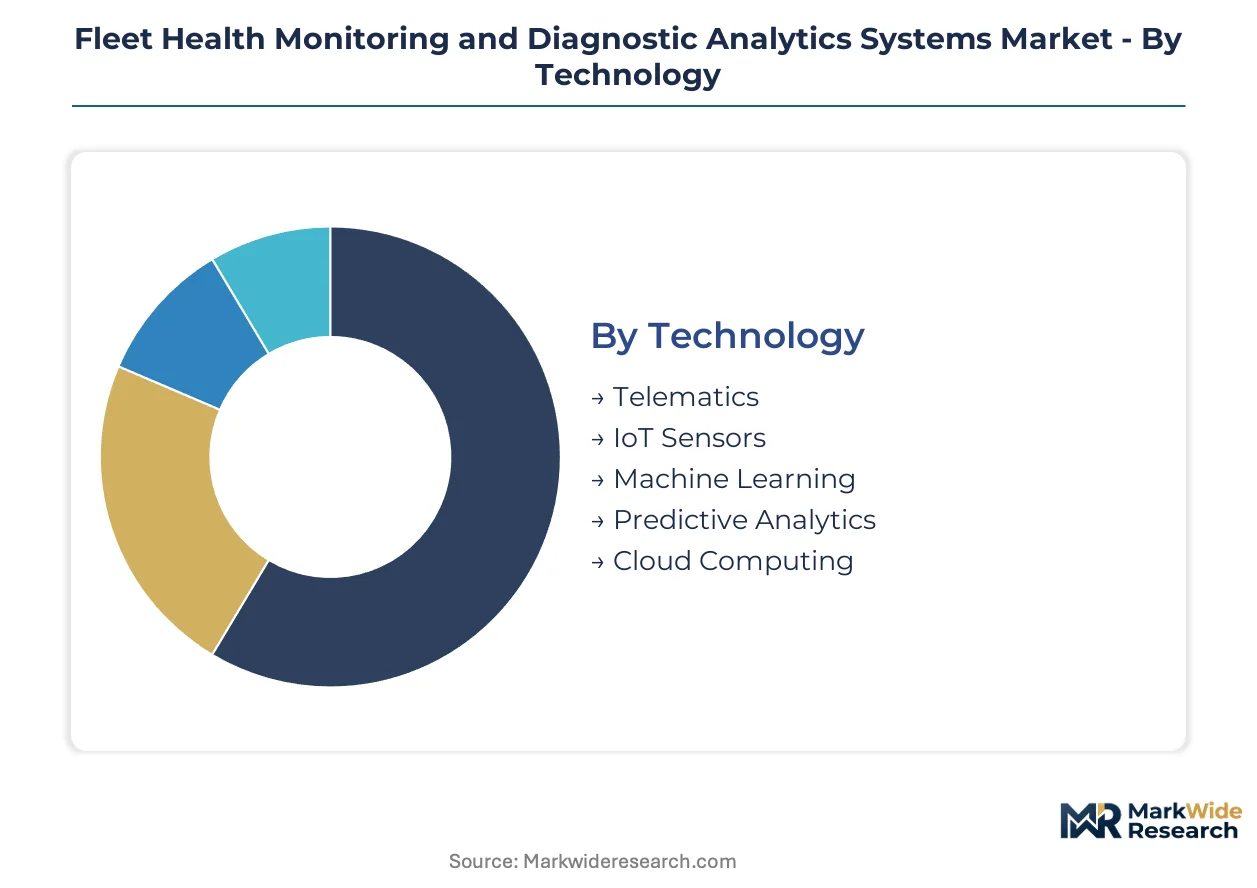
Fleet health monitoring systems fragment across four structural dimensions that determine procurement priorities and margin architecture. Technology choices dictate whether vendors capture hardware revenue or recurring software subscriptions. Application focus separates commodity tracking providers from predictive maintenance platforms commanding premium pricing.
Technology:
Certification burdens concentrate in machine learning and predictive analytics segments, where EPA verification protocols for emissions reporting and EU F-Gas Regulation compliance documentation create regulatory gates. Telematics and IoT sensors face lighter hardware conformity requirements but heavier FCC and CE marking obligations for radio frequency emissions.
- Telematics:Onboard control units transmit vehicle location, engine fault codes, and operational parameters through cellular networks. Demand concentrates among North American logistics providers seeking FMCSA hours-of-service compliance documentation, though semiconductor supply constraints from Taiwanese foundries extend procurement lead times.
- Machine Learning:Proprietary training pipelines process historical fault code patterns to predict component failures before roadside breakdowns. European refrigerated transport fleets drive adoption under F-Gas Regulation mandates requiring refrigerant leakage prediction, separating vendors with captive data infrastructure from those licensing third-party inference engines.
- IoT Sensors:Distributed temperature, pressure, and vibration monitors feed edge or cloud architectures with real-time component health data.
- Predictive Analytics:Maintenance scheduling algorithms translate sensor telemetry into work order automation and parts procurement triggers.
- Cloud Computing:Centralized data architectures displace on-premise installations among mid-size logistics providers seeking lower capital burdens and scalable storage.
Telematics sits at the top of the volume ranking, with machine learning climbing the fastest.
Application:
Cost tier stratification separates basic vehicle tracking from integrated workflow automation platforms. Fuel management and route optimization command mid-tier pricing, while predictive maintenance scheduling captures premium subscriptions.
- Vehicle Tracking:GPS-based location monitoring provides foundational fleet visibility through breadcrumb trails and geofence alerts. German freight corridors between Ruhr and Hamburg anchor demand density, where high-utilization lanes justify real-time position verification for delivery contract compliance.
- Maintenance Scheduling:Predictive algorithms orchestrate component replacement timing, technician dispatch, and parts inventory synchronization. California-based carriers under the state's Advanced Clean Trucks regulation drive adoption, where verified diagnostic data streams document emissions compliance alongside mechanical health.
- Fuel Management:Consumption monitoring identifies idle-time waste and route inefficiencies for cost reduction programs.
- Driver Behavior Analysis:Harsh braking, acceleration, and cornering metrics feed safety scoring systems for insurance adjacency.
- Route Optimization:Real-time traffic and delivery window integration minimizes mileage and maximizes asset utilization.
Vehicle Tracking holds the largest installed base, with maintenance scheduling expanding most quickly.
End User:
Customer type determines deployment complexity and integration requirements. Logistics providers demand API connectivity with dispatch software, while public agencies prioritize compliance documentation for regulatory audit trails.
- Logistics Providers:Enterprise freight operators deploy unified platforms across mixed fleets of owned and contracted vehicles. North American third-party logistics firms concentrate procurement authority in centralized technology functions, evaluating diagnostic systems on fuel card and payroll system integration rather than hardware specifications alone.
- Public Transportation Agencies:Municipal bus and rail operators mandate auditable maintenance records for federal transit administration compliance. European agencies face parallel EU Green Deal freight targets requiring integrated carbon accounting alongside diagnostic functions.
- Delivery Services:Last-mile parcel and food distribution fleets prioritize route density optimization and customer notification automation.
- Construction Firms:Heavy equipment fleets operating remote sites adopt edge computing deployments to process telemetry without cellular dependency.
- Emergency Services:Police, fire, and ambulance fleets require guaranteed uptime with redundant communication paths for critical vehicle availability.
Logistics Providers dominate procurement volume, with emergency services gaining share fastest due to reliability mandates.
Deployment Model:
Supply concentration in cloud infrastructure creates vendor dependency risks, while edge computing investments target latency-sensitive remote operations. Hybrid architectures appeal to fleets with mixed connectivity profiles.
- Cloud-Based:Centralized data processing and storage eliminates on-site server maintenance while enabling fleet-wide analytics dashboards. Mid-size logistics providers across Germany and the United States favor this model for predictable per-vehicle SaaS fees, though subscription cost compounding creates margin pressure when fuel savings materialization lags.
- Edge Computing:On-vehicle inference chips process engine fault codes and sensor telemetry without satellite uplink latency. Mining and timber operators in remote Canadian and Australian territories drive adoption, where cellular coverage gaps previously excluded these segments from predictive maintenance platforms.
- On-Premise:Self-managed data centers retain full control over diagnostic archives for operators with stringent data sovereignty requirements.
- Hybrid:Selective edge processing with cloud aggregation balances real-time responsiveness against centralized analytics depth.
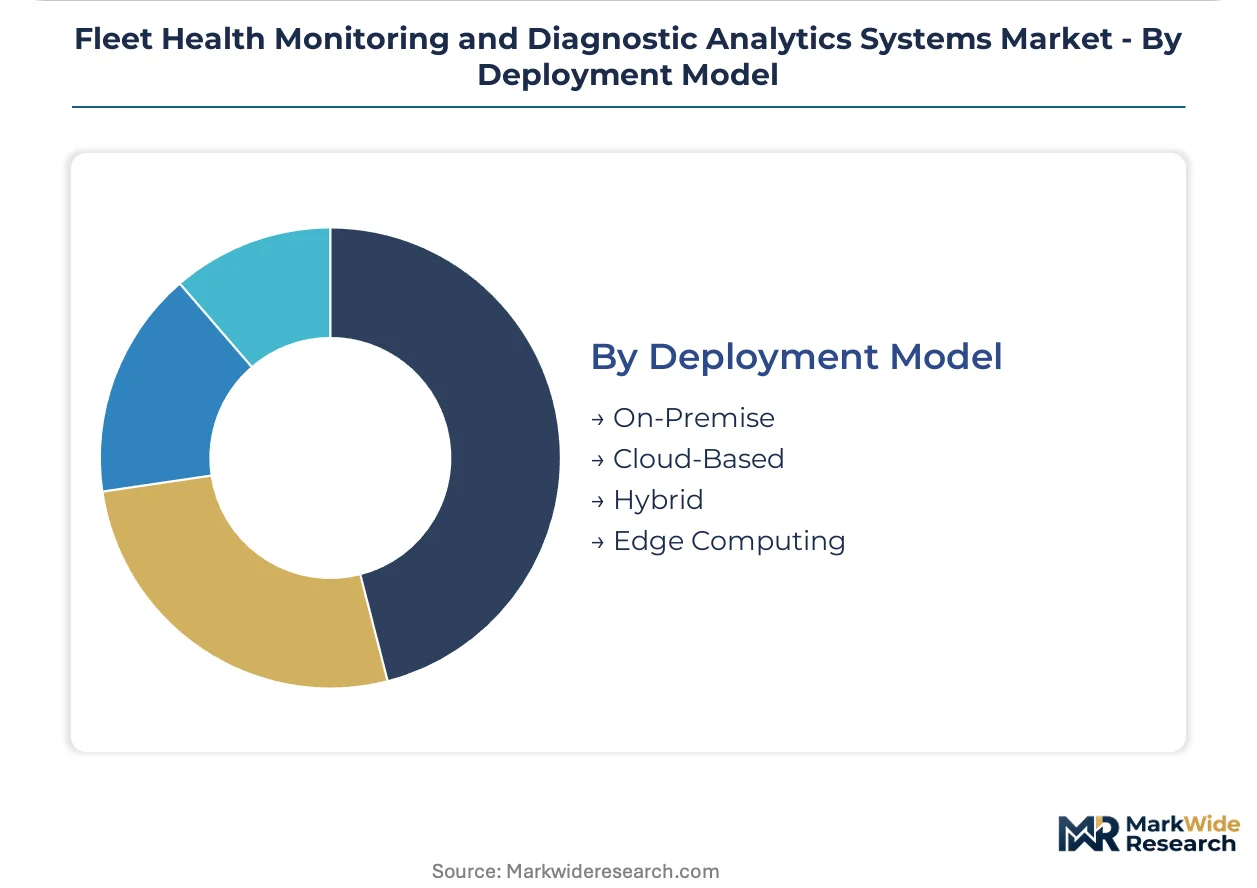
Cloud-Based deployment leads in new installations, with edge computing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Firmware engineers specializing in vehicle telematics cluster around Stuttgart, Detroit, and Shenzhen, anchoring regional capability formation for diagnostic platform development.
United States
Enterprise logistics operators in the Midwest and Southeast drive predictive maintenance platform procurement to minimize downtime across interstate freight corridors. The FMCSA electronic logging device mandate compels hours-of-service compliance documentation through verified diagnostic data streams. California-based carriers under the state's Advanced Clean Trucks regulation face accelerated emissions reporting timelines, forcing diagnostic system upgrades across Los Angeles and Long Beach port servicing fleets.
Germany
Dense freight traffic between the Ruhr industrial basin and Hamburg port creates concentrated demand for real-time diagnostic infrastructure on high-utilization lanes. The EU F-Gas Regulation mandates refrigerant leakage sensors across refrigerated transport fleets, compelling hardware upgrades for compliance documentation. Munich and Stuttgart-based automotive technology clusters host engineering talent pools developing edge-computing inference chips for on-vehicle fault analysis.
China
Domestic logistics providers scale telematics deployments to manage explosive e-commerce delivery volume growth across Yangtze River Delta manufacturing hubs. The Ministry of Industry and Information Technology enforces GB standards for commercial vehicle data transmission protocols. Shenzhen and Shanghai hardware ecosystems supply telematics control units, though semiconductor foundry dependencies create procurement vulnerability for domestic fleet operators.
United Kingdom
London-centered third-party logistics firms prioritize diagnostic platforms integrating with dispatch software and fuel card programs for centralized fleet management. The Driver and Vehicle Standards Agency mandates tachograph compliance documentation that diagnostic systems automate for audit trails. Midlands-based manufacturing logistics operations adopt predictive maintenance scheduling to protect just-in-time delivery contracts with automotive assembly plants.
Japan
Precision manufacturing supply chains demand diagnostic systems ensuring vehicle availability for time-critical component deliveries between Nagoya industrial zones and Tokyo distribution centers. METI promotes connected vehicle standards that fleet operators adopt for interoperability with domestic automotive supplier networks. Osaka-based technology integrators develop hybrid cloud-edge architectures serving construction and mining fleets operating in cellular coverage gaps.
Fleet Health Monitoring and Diagnostic Analytics Systems Market Competitive Landscape
Capital-heavy hardware producers compete with asset-light software designers across the diagnostic analytics value chain. The market structure consolidates around platforms capturing recurring subscription revenue rather than discrete telematics device sales. Three archetypes dominate: integrated platform operators bundling sensor hardware with workflow software, specialized predictive analytics vendors licensing machine learning inference engines, and telecommunications carriers leveraging network infrastructure for fleet data aggregation. Dominant competitive moves include strategic partnerships between automotive OEMs and telematics providers, plus geographic expansion through regional system integrators possessing local compliance expertise.
Within the integrated platform tier, Geotab exemplifies the open-ecosystem archetype, while Samsara occupies a position binding sensor hardware to vertical software applications. Motive anchors the insurance-adjacent specialist segment where driver safety scoring creates platform stickiness beyond basic tracking functionality.
| Leading Market Players |
|---|
| Geotab |
| Samsara |
| Motive |
| Verizon Connect |
| Powerfleet |
| Trimble |
| Omnitracs |
| Teletrac Navman |
| ORBCOMM |
| Others |
Pricing and Supply Chain Analysis
Mid-size logistics providers consolidating vendor relationships around unified workflow platforms are compressing margins for standalone telematics hardware suppliers while rewarding integrated analytics vendors with recurring SaaS pricing power. This procurement consolidation forces component manufacturers to absorb cost pressure or invest in proprietary machine learning pipelines that justify premium subscription tiers.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive positioning across the diagnostic analytics value chain. Hardware-centric vendors compete on per-unit device economics, while integrated platform operators capture three-tier pricing structure across premium, standard, and economy levels based on predictive analytics depth and workflow automation scope. Price differentiation rests on proprietary machine learning certification under EPA verification protocols and EU F-Gas Regulation compliance documentation. Cost compression in the hardware tier is intensifying because semiconductor supply constraints from Taiwanese foundries extend procurement lead times and inflate component costs. Buyer price sensitivity concentrates among mid-size logistics providers facing margin pressure from per-vehicle SaaS fees, while enterprise fleets prioritize predictive maintenance ROI over upfront subscription costs.
Supply Chain Analysis
Firmware engineering scarcity across Stuttgart, Detroit, and Shenzhen manufacturing clusters constrains telematics control unit production capacity and extends development timelines for edge-computing inference chips. Geographic supply concentration centers on Taiwan for semiconductor foundry capacity, China for telematics hardware assembly, and Germany for automotive-grade sensor integration. Raw material and component dependencies draw from rare earth elements for magnet-based sensors, lithium-ion cells for backup power systems, and specialized automotive-grade resins for housing durability. Single-source vulnerability in Taiwanese foundry exposure creates procurement disruption risk for fleet hardware operators. Distribution runs through regional system integrators possessing local compliance expertise, with direct OEM partnerships gaining share among enterprise logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet health monitoring functions as a stable compounder anchored by regulatory mandates for verified diagnostic data streams that perpetuate replacement demand across compliance-driven procurement cycles.
For Market Incumbents: Cement platform stickiness by deepening API integration with dispatch software, fuel card programs, and driver payroll systems that elevate switching costs beyond hardware replacement. Invest captive R&D resources in edge-computing inference chips to capture remote-route operators previously excluded from cloud-dependent analytics, defending against specialized predictive analytics vendors licensing third-party machine learning engines. For New Entrants and Emerging Players: Launch via insurance-adjacent distribution partnerships where driver safety scoring creates verified risk telemetry demand from underwriters seeking usage-based policy data. Target European refrigerated transport fleets under F-Gas Regulation refrigerant leakage mandates as the most penetrable compliance-driven segment, with construction and mining operators in cellular coverage gaps as secondary white-space opportunity. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized predictive analytics vendors possessing proprietary training pipelines and EPA-verified emissions reporting certification. Long-term viability favors platform operators with demonstrated workflow automation integration and recurring revenue concentration above hardware dependency. Watch for inflection signals in edge-computing deployment acceleration among remote-route fleet segments as indicator of subscription tier expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with dispatch software and fuel card programs elevates switching costs beyond hardware replacement cycles. |
| Edge Computing Deployment | On-vehicle inference chips enable predictive maintenance subscriptions for mining and timber fleets beyond cellular coverage. |
| Regulatory Certification Investment | EPA verification protocols and EU F-Gas Regulation compliance documentation create gated margin pools for certified vendors. |
| Insurance Partnership Development | Driver safety scoring creates captive relationships with underwriters seeking verified risk telemetry for usage-based policies. |
| Geographic Expansion via System Integrators | Regional partners possessing local compliance expertise accelerate market entry across fragmented European freight corridors. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged fleet technology procurement directors, telematics platform engineers, commercial insurance underwriters, and automotive OEM connected vehicle strategists. Secondary sources included FMCSA compliance documentation, EPA emissions verification protocols, EU F-Gas Regulation implementation guidance, and SEC filings from publicly traded logistics technology providers. Bottom-up unit economics modeling triangulated against top-down market sizing from fleet operator survey data.
Granularity-level framing applied vehicle class, deployment architecture, and regulatory compliance tier as core segmentation dimensions across the projection horizon. Technology adoption curves modeled separately for telematics hardware, machine learning inference deployment, and predictive analytics software subscription tiers. CAGRs derived from logistic diffusion functions fitted to historical adoption patterns in adjacent fleet management technology categories. Forecast inputs incorporated semiconductor supply lead time assumptions and regulatory mandate implementation timelines without year-specific anchoring.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Taiwanese foundry disruption or accelerated EU Green Deal freight target acceleration. Forecasts reflect documented assumptions regarding fleet operator procurement consolidation behavior and edge-computing cost reduction trajectories. Material deviation in semiconductor supply availability or regulatory enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
GCC Electronic Toll Collection Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Car E-Hailing Market