
 Real-Time Parking System Market | 2026-2036
Real-Time Parking System Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time Parking System Market Analysis
AI-powered occupancy prediction is redrawing competitive benchmarks across the real-time parking system landscape. SpotHero leverages proprietary demand-forecasting algorithms to optimize inventory allocation across fragmented urban supply. Flowbird anchors its position through deep integration with municipal payment ecosystems and transit card interoperability. ParkMobile differentiates via API-first architecture that embeds parking discovery into third-party navigation platforms.
A real-time parking system integrates sensor networks, edge computing nodes, and cloud-native software to detect, communicate, and monetize parking space availability with sub-minute latency. These systems typically process ultrasonic, magnetic, or computer-vision inputs at 95%+ accuracy thresholds to guide drivers via mobile interfaces and dynamic signage. Sensor-based technology leads installed base but IoT solutions represent the fastest-expanding margin pool as hardware-software bundling deepens. Cloud computing deployment is maturing among private operators while hybrid solutions gain traction with municipalities seeking data sovereignty.
The US Department of Transportation's smart city grants and the EU Green Deal's mobility directives are accelerating procurement of emissions-linked parking management platforms. KBA regulations in Germany mandate real-time data interoperability between parking infrastructure and electric vehicle charging networks. Stakeholders must monitor how fragmented municipal procurement standards evolve as federal interoperability mandates crystallize across major economies.
Market Dynamics
Sensor fusion with edge computing architectures is displacing legacy loop-detector infrastructure across metropolitan parking networks, forcing incumbent hardware vendors to reconfigure product roadmaps around software-defined detection layers.
Growth Catalysts
- KBA Emissions Protocols:Germany's Federal Motor Transport Authority mandates real-time data interoperability between parking systems and electric vehicle charging networks, accelerating procurement of dynamic occupancy platforms in urban cores.
- Ultrasonic Sensor Arrays:Municipal operators deploy computer-vision-augmented ultrasonic networks to achieve 95%+ occupancy accuracy thresholds, reducing search traffic and associated emissions in congested districts.
- Smart City Grant Programs:The US Department of Transportation channels federal funding toward integrated mobility platforms that bundle parking discovery with transit payment interoperability.
Market Restraints
- Silicon Supply Concentration:Edge computing node production depends on semiconductor fabrication concentrated in East Asian foundries, exposing deployment timelines to geopolitical supply disruptions.
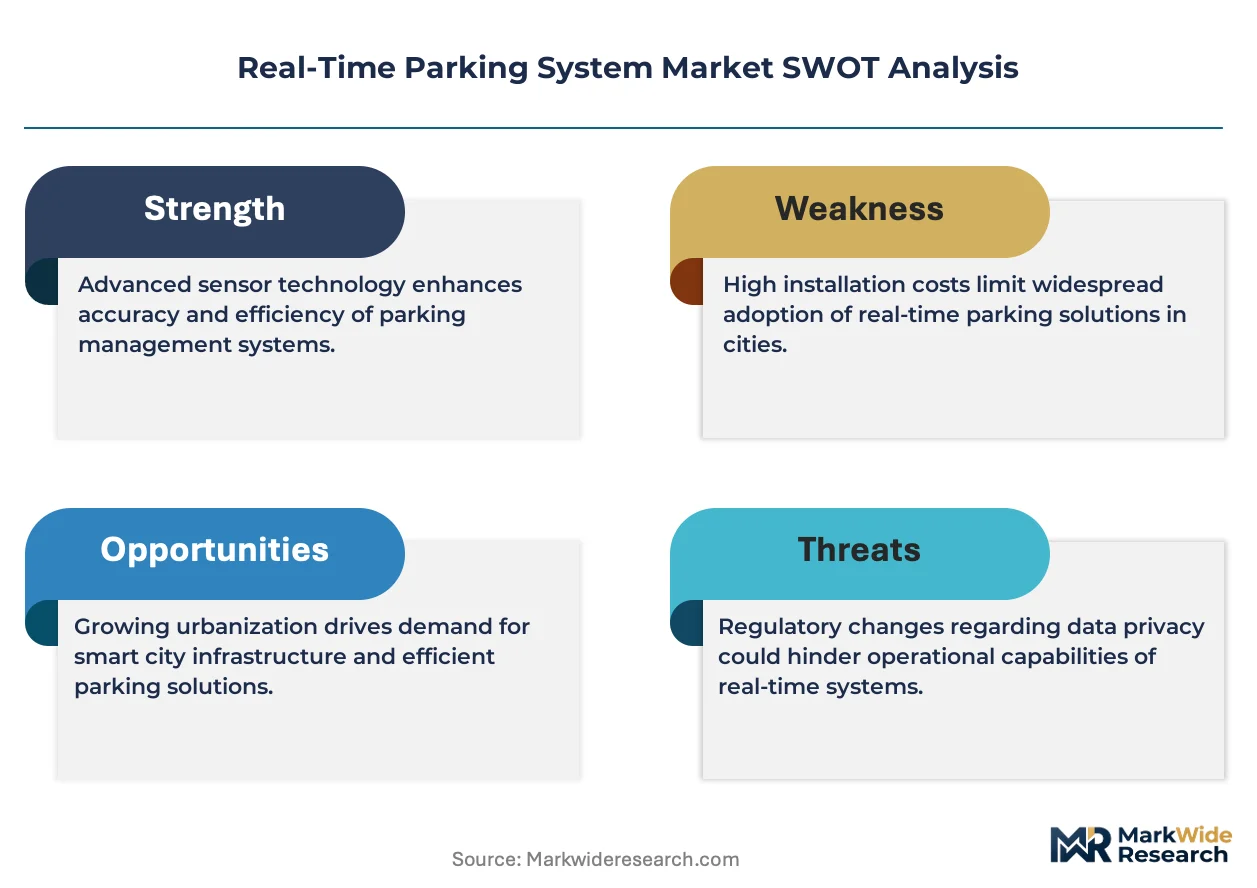
- Legacy Infrastructure Lock-In:Magnetic loop detectors embedded in thousands of municipal roadways create high switching costs for cities with constrained capital renewal cycles.
- Data Sovereignty Requirements:EU GDPR and emerging national cloud localization rules fragment software architecture standards, complicating cross-border platform deployments.
Strategic Opportunities
- Curbside Management Convergence:Parking platforms integrate with delivery logistics and micromobility docking systems, capturing new revenue streams from commercial fleet operators.
- India Urban Mobility Mission:Smart city initiatives in Bangalore, Mumbai, and Delhi create procurement windows for occupancy detection systems linked to congestion pricing pilots.
- API-First Distribution:Embedded parking discovery within navigation applications and automotive infotainment systems bypasses standalone app adoption friction.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for low-power sensor networks requires specialized expertise that municipalities and mid-sized operators struggle to attract.
- Interoperability Certification Delays:Fragmented municipal technical standards extend procurement timelines as vendors pursue jurisdiction-specific compliance validations.
- Cloud-Legacy Integration Complexity:Hybrid deployments bridging on-premise edge nodes with cloud analytics layers demand architectural expertise that stretches internal IT capacities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time Parking System Market |
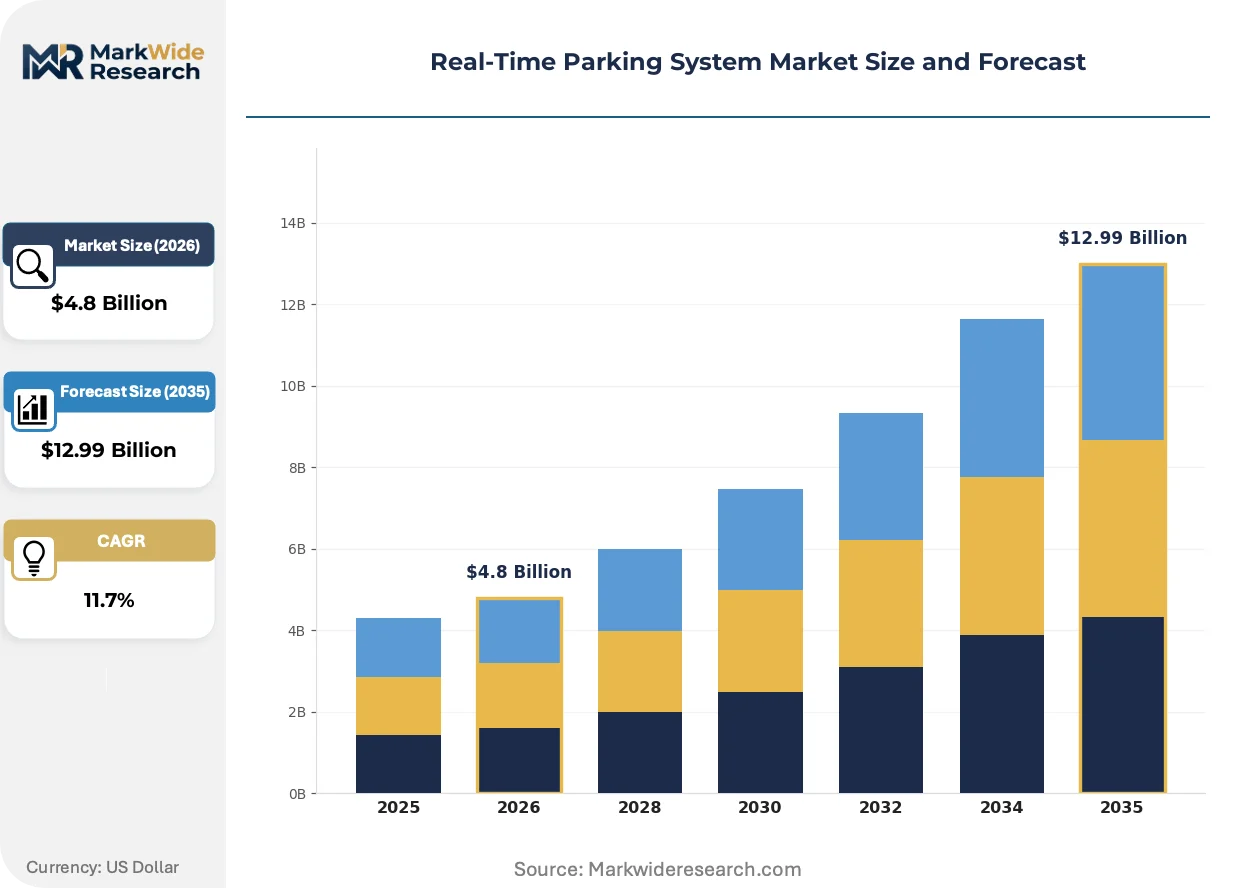
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensor-Based, Cloud Computing, Mobile Applications, IoT Solutions Application: Urban Areas, Airports, Shopping Malls, Events End User: Municipalities, Private Operators, Fleet Services, Retail Chains Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services |
| Companies Covered | JustPark, ParkNow, ParkMobile, Smarking, Flowbird, SpotHero, EasyPark, ParkJockey, ParkMe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time Parking System Market Emerging Trajectories
Artificial intelligence inference at the network edge is redrawing competitive boundaries between hardware-centric and software-centric parking system vendors, compressing latency benchmarks and enabling predictive rather than reactive space allocation.
Computer vision algorithms running on GPU-accelerated edge nodes is bifurcating the installed base between premium deployments achieving sub-second detection latency and cost-constrained ultrasonic alternatives. Large commercial parking operators in Germany and the Netherlands adopt vision-first architectures to support automated payment enforcement. This technology compression is squeezing mid-tier sensor vendors unable to bundle AI software with hardware shipments.
The EU Green Deal's mobility directives mandate emissions-linked parking access protocols in urban cores exceeding 100,000 inhabitants. Municipal procurement specifications now require real-time occupancy data feeds for congestion pricing algorithms and EV charging queue management. German cities lead compliance timelines, with KBA-certified platforms receiving preferential evaluation scoring in federal funding applications.
Fleet operators and logistics platforms now contract directly with parking system vendors for guaranteed space reservations, bypassing traditional municipal intermediaries. Commercial real estate owners respond by installing private occupancy networks that feed into third-party navigation APIs. This channel disintermediation is most advanced in the United States, where SpotHero and ParkMobile aggregate fragmented private supply into corporate fleet dashboards.
Real-Time Parking System Market Segmentation
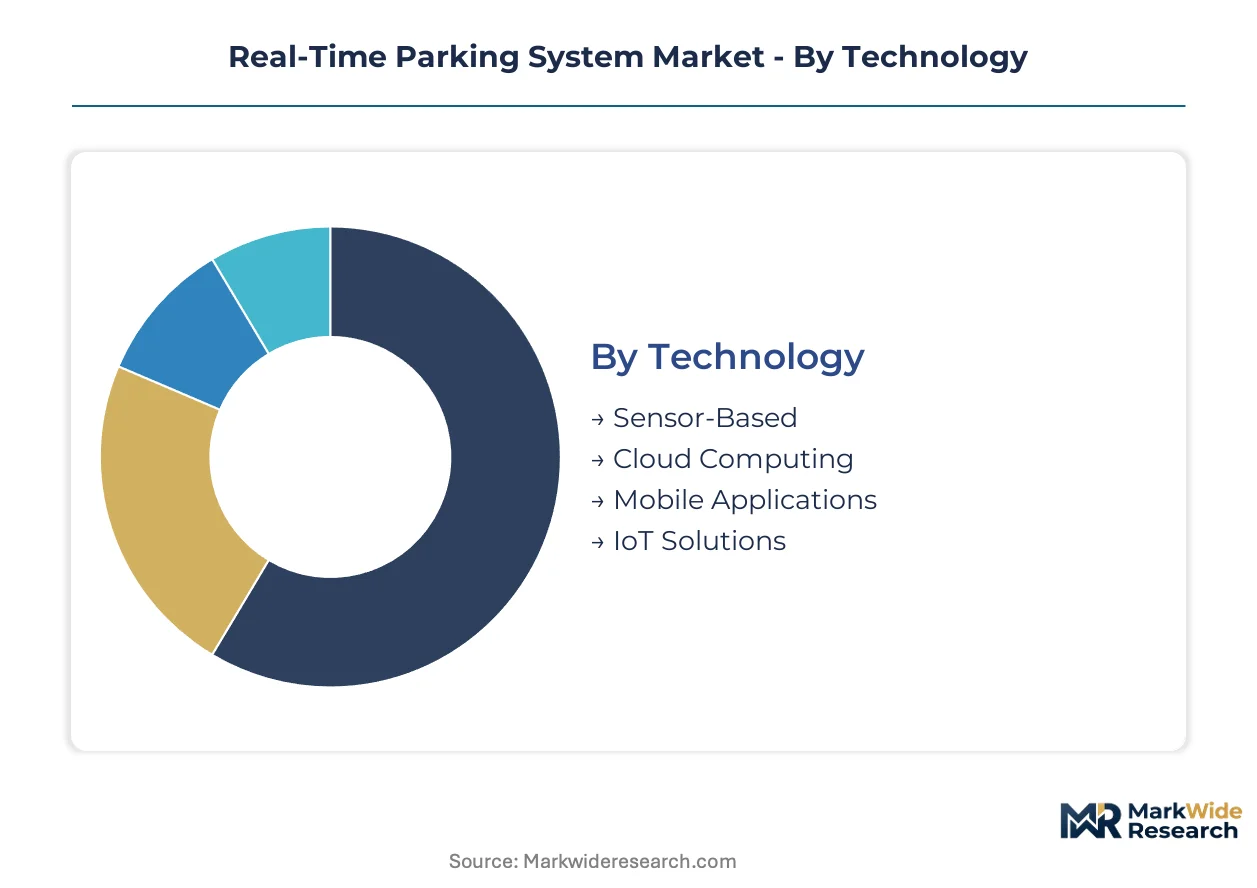
Technology choices in real-time parking systems carry direct compliance implications under emissions-linked access regulations. Procurement specifications increasingly bundle hardware performance thresholds with data interoperability mandates, reshaping how vendors position across segment boundaries.
Technology:
KBA-certified deployments in Germany favor sensor arrays with verified 95% accuracy thresholds, while EU Green Deal procurement guidelines reward edge-computing architectures that minimize cloud data transfer.
- Sensor-Based:Ultrasonic and magnetic detection arrays process occupancy signals at roadside nodes with sub-minute latency. Municipal operators in congested German urban cores specify these systems to meet KBA emissions protocol requirements for real-time space availability.
- IoT Solutions:Low-power wide-area networks connect distributed detection nodes to centralized analytics platforms, enabling predictive occupancy modeling. Demand concentrates among private operators in the Netherlands seeking computer-vision-augmented deployments for automated enforcement integration.
- Cloud Computing:Centralized data processing architectures support multi-facility portfolio management for large commercial parking operators.
- Mobile Applications:Consumer-facing discovery interfaces embed payment functionality and navigation guidance for end-user access.
Established volume favors sensor-based hardware; emerging adoption favors IoT solutions with bundled AI software layers.
Application:
Deployment costs scale with traffic density and enforcement complexity, creating tiered procurement patterns across facility types.
- Urban Areas:Street-level sensor networks feed congestion pricing algorithms and EV charging queue management systems. German cities exceeding 100,000 inhabitants mandate these integrations under EU Green Deal mobility directives, with federal funding preferencing KBA-certified platform vendors.
- Airports:Multi-terminal occupancy platforms coordinate with flight data systems to predict demand surges and adjust pricing dynamically. US hub airports deploy these under Department of Transportation smart city grant programs that bundle parking with transit payment interoperability.
- Shopping Malls:Private commercial real estate operators install occupancy networks to monetize premium spaces and validate loyalty program parking benefits.
- Events:Temporary sensor deployments serve stadium and arena districts with surge pricing capabilities during scheduled gatherings.
Revenue concentration sits with urban municipal contracts; margin expansion concentrates in airport deployments with integrated transit linkages.
End User:
Procurement authority fragmentation shapes vendor engagement models, from centralized federal funding to decentralized facility management.
- Municipalities:Public sector buyers operate under constrained capital renewal cycles and legacy infrastructure lock-in, yet command scale through network-wide standardization. German municipal procurement increasingly requires KBA-certified interoperability with EV charging networks.
- Private Operators:Commercial parking companies prioritize API-first architectures that embed discovery into automotive infotainment systems and third-party navigation platforms. These stakeholders in the United States aggregate fragmented supply into corporate fleet dashboards.
- Fleet Services:Logistics platforms contract directly for guaranteed space reservations, bypassing traditional intermediaries.
- Retail Chains:Big-box and grocery operators deploy private occupancy networks to validate customer parking benefits and manage loading zone logistics.
Contract scale favors municipalities; pricing flexibility favors private operators with dynamic revenue management capabilities.
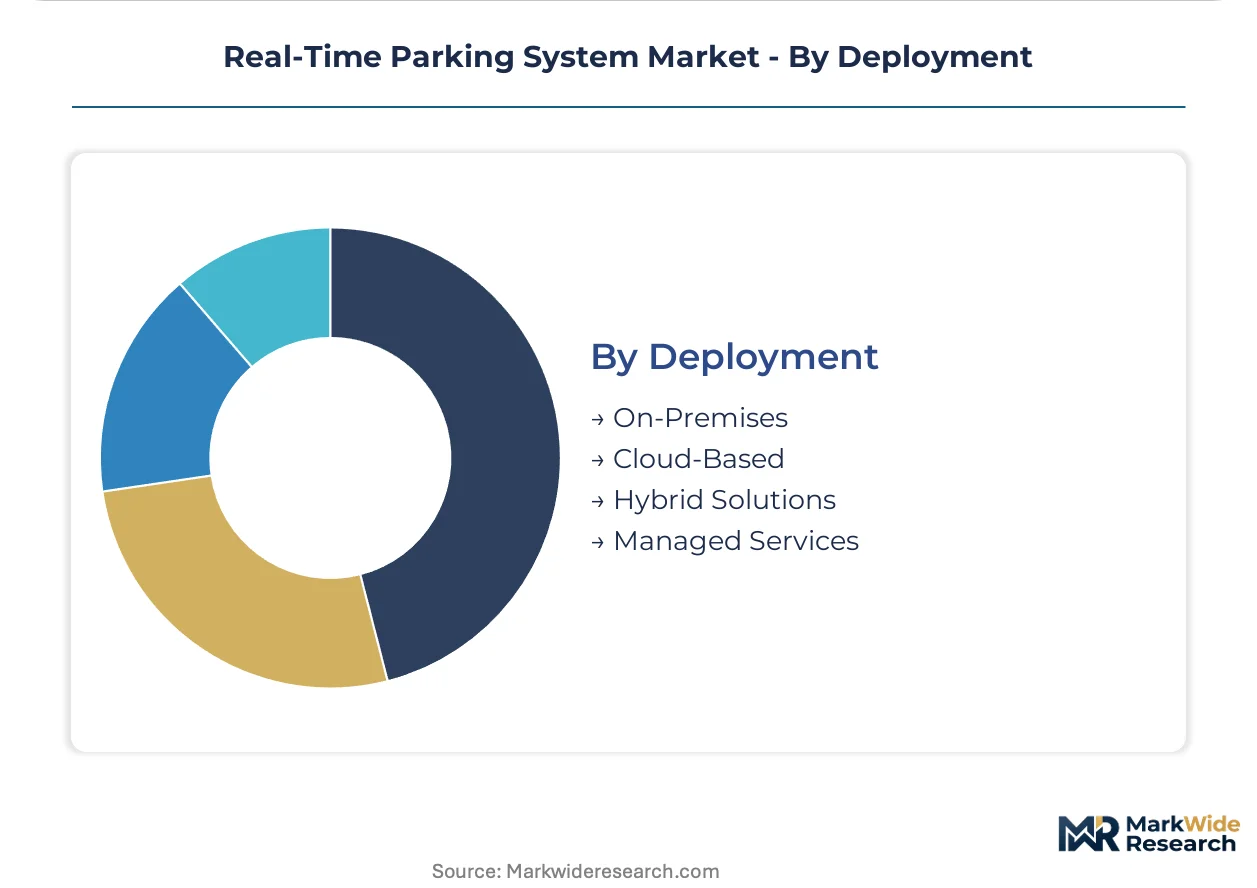
Deployment:
Data sovereignty requirements fragment architecture standards, with EU GDPR and emerging national cloud localization rules complicating cross-border platform designs.
- Hybrid Solutions:Edge nodes process detection signals locally while cloud layers handle analytics and third-party API distribution. German municipalities favor this architecture to satisfy KBA data interoperability mandates while retaining local processing for GDPR compliance.
- Cloud-Based:Fully centralized deployments suit private operators without data sovereignty constraints, enabling rapid feature deployment and multi-tenant scalability. US commercial operators adopt these for portfolio-wide revenue management.
- On-Premises:Air-gapped installations serve facilities with strict cybersecurity requirements or unreliable connectivity infrastructure.
- Managed Services:Outsourced operation and maintenance contracts transfer firmware update and sensor calibration responsibilities to vendor specialists.
Procurement momentum favors hybrid architectures; operational simplicity favors cloud-based deployments for unconstrained private operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Edge computing node fabrication concentrates in East Asian foundries, yet procurement authority for real-time parking systems distributes across municipal governments in congested metropolitan zones. German KBA regulations and US Department of Transportation smart city grants reshape deployment patterns.
United States
Department of Transportation smart city grants channel federal funding toward integrated mobility platforms. Municipal procurement in Los Angeles, San Francisco, and New York prioritizes API-first architectures that embed parking discovery into transit payment systems. Commercial operators aggregate fragmented private supply into corporate fleet dashboards.
Germany
KBA emissions-linked parking access protocols mandate real-time data interoperability with electric vehicle charging networks. Cities exceeding 100,000 inhabitants face compliance deadlines under EU Green Deal mobility directives. Munich and Hamburg lead procurement of computer-vision-augmented sensor networks for automated enforcement.
Netherlands
Private operators in Amsterdam and Rotterdam adopt vision-first architectures for curbside management convergence. National mobility directives reward edge-computing deployments that minimize cloud data transfer. Commercial real estate owners install private occupancy networks feeding third-party navigation APIs.
India
Urban Mobility Mission initiatives in Bangalore, Mumbai, and Delhi create procurement windows for occupancy detection systems. Smart city pilots link parking infrastructure to congestion pricing mechanisms. Municipal corporations struggle with legacy infrastructure lock-in amid constrained capital renewal cycles.
Japan
METI guidelines promote sensor fusion integration with existing urban mobility platforms. Tokyo and Osaka metropolitan governments specify low-power wide-area networks for predictive occupancy modeling. Parking system vendors adapt firmware for earthquake-resilient edge node deployments.
Real-Time Parking System Market Vendor Landscape
Concentration sits with software-centric platforms that bundle AI-powered demand forecasting with municipal payment ecosystem integration. The vendor base spans three tiers: hardware-agnostic SaaS providers, sensor-software bundlers, and legacy equipment retrofitters. Dominant competitive moves include API-first distribution partnerships and strategic acquisitions of computer-vision startups.
Within the software-centric tier, SpotHero and ParkMobile exemplify API-first architectures that embed parking discovery into automotive infotainment systems. Flowbird anchors the municipal payment integration segment through deep transit card interoperability. These three companies represent divergent strategic paths: consumer-facing aggregation, embedded distribution, and public infrastructure lock-in.
| Leading Market Players |
|---|
| JustPark |
| ParkNow |
| ParkMobile |
| Smarking |
| Flowbird |
| SpotHero |
| EasyPark |
| ParkJockey |
| ParkMe |
| Others |
Supply Flow & Price Mechanics
Long-term municipal service contracts lock in supply access and price visibility for edge computing node vendors serving German KBA-certified deployments, insulating procurement from spot-market semiconductor volatility while embedding fixed-margin maintenance obligations.
Pricing Analysis
KBA emissions protocols dictate the pricing tier structure across German municipal deployments, separating KBA-certified premium systems from uncertified standard alternatives and basic sensor-only economy configurations. Pricing pressure stems from silicon supply concentration in East Asian foundries, compressing margins on hardware-centric bundlers. Municipal buyers exhibit highest price sensitivity due to constrained capital renewal cycles, while private operators in the Netherlands accept premium tiers for vision-first architectures with automated enforcement integration.
Supply Chain Analysis
Taiwan Strait transit underwrites semiconductor fabrication for GPU-accelerated edge nodes, creating chokepoint exposure for computer-vision parking system vendors. Production concentrates in Taiwan, South Korea, and China, drawing from specialized silicon wafers, memory modules, and camera sensor arrays. Single-source vulnerability in advanced node fabrication threatens deployment timelines. Distribution runs through municipal procurement channels and direct commercial fleet contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal capital renewal cycles are recovering from pandemic-era deferrals, unlocking procurement for smart city parking infrastructure as federal grant programs replenish.
For Market Incumbents: Secure KBA certification maintenance through firmware update pipelines to defend against API-first SaaS entrants eroding hardware-software bundling margins. Deepen backward integration into edge computing node design to reduce Taiwan foundry dependency. Municipal payment ecosystem lock-in remains the strongest defensive moat. For New Entrants and Emerging Players: Anchor in India's Urban Mobility Mission pilots, where legacy infrastructure lock-in is weakest and congestion pricing creates urgent procurement windows. Target Bangalore and Mumbai municipal corporations with hybrid deployment architectures that bypass cloud data sovereignty concerns. Lead with computer-vision-augmented ultrasonic networks priced below German vision-first premiums. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-first platforms embedding parking discovery into automotive infotainment systems, offering superior cash flow quality against project-based hardware vendors. Acquisition focus should center on computer-vision startups with municipal enforcement integration capabilities. Watch for KBA interoperability mandate expansion beyond Germany as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedding parking discovery into third-party navigation systems bypasses standalone app adoption friction. |
| Computer-Vision Startup Acquisition | Vision-first architectures enable automated enforcement integration that KBA protocols increasingly favor. |
| Hybrid Deployment Architecture | Edge-cloud combinations satisfy GDPR data sovereignty while maintaining KBA interoperability mandates. |
| Municipal Payment Ecosystem Partnership | Transit card interoperability locks in long-term service contracts with constrained-renewal-cycle cities. |
| Curbside Management Convergence | Integration with delivery logistics and micromobility docking captures commercial fleet revenue streams. |
Methodological Framework
A spread of perspectives from municipal procurement officers, edge computing firmware engineers, commercial parking operators, and transit authority IT directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against USDOT smart city grant disclosures, EU Green Deal mobility directive texts, KBA technical specifications, and municipal tender databases. Bottom-up sensor deployment counts triangulated against top-down parking revenue estimates across the analysis window.
Segmentation dimensions modeled include technology type, application facility category, end-user procurement authority, and deployment architecture choice across the projection horizon. CAGRs derive from installed base growth curves adjusted for replacement cycles and regulatory compliance deadlines. Forecast inputs incorporate KBA certification adoption rates and edge computing node production capacity constraints.
Material uncertainties — semiconductor supply disruptions, municipal procurement standard fragmentation, and cloud localization rule evolution — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as federal interoperability mandates crystallize across major economies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Vehicle Parking Meter Market