
 Urban Rail Transit Signaling Market | 2026-2036
Urban Rail Transit Signaling Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Rail Transit Signaling Market Analytics
Aftermarket service revenue is narrowing the margin gap with original equipment sales as operators extend system lifecycles. Siemens sustains technology leadership through its ERTMS platform depth across European corridors. Alstom dominates turnkey project delivery for metro modernization in France and adjacent markets. China Railway Signal & Communication anchors domestic procurement through its grip on Beijing and Shanghai network expansions.
Urban rail transit signaling encompasses the electronic control, interlocking, and train-to-ground communication systems that govern safe headway management, typically operating at update intervals below one second for moving-block configurations. These systems prevent collisions, optimize line capacity, and enable automated train operation in tunnels and elevated guideways. CBTC deployment leads new installations as cities abandon fixed-block legacy infrastructure for granular train tracking. ERTMS gains traction in national rail networks seeking cross-border interoperability, while maintenance services capture expanding recurring revenue as installed bases mature across Europe and East Asia.
China's MIIT enforces GB standards for domestic signaling procurement, effectively restricting non-Chinese vendors from core network awards. The EU's ERTMS deployment mandate under the European Railway Traffic Management System directive compels member states to replace national legacy systems. India's CEA and Ministry of Railways coordinate metro electrification and signaling standards through the Metro Rail Policy. Stakeholders must track how China's dual carbon goals reshape domestic procurement priorities and whether India's PLI scheme extends to rail electronics manufacturing.
Market Dynamics
Communication-based train control (CBTC) is compressing legacy fixed-block infrastructure replacement cycles as Asian metro operators pursue granular headway management in dense corridors. This technological inflection is redistributing vendor influence toward systems integrators with proven tunnel-deployment expertise.
Growth Catalysts
- ERTMS Mandates:The EU's European Railway Traffic Management System directive compels member states to retire national legacy signaling, creating mandatory replacement demand across cross-border corridors.
- China's Tier-1 Metro Expansion:Beijing and Shanghai network extensions under MIIT procurement rules sustain domestic equipment demand despite import restrictions.
- Moving-Block Technology:CBTC adoption enables sub-90-second headways in high-density Asian metros, unlocking capacity without civil infrastructure expansion.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication for safety-critical processors clusters in Taiwan and South Korea, exposing signaling OEMs to single-source vulnerability.
- Domestic Content Requirements:China's GB standards and India's Metro Rail Policy mandate local sourcing percentages that fragment vendor addressable markets.
- Copper and Rare Earth Volatility:Traction power cabling and permanent magnet materials face price swings that compress project margins during extended installation timelines.
Strategic Opportunities
- Indian Network Buildout:Delhi Metro Rail Corporation and emerging Tier-2 cities under CEA coordination present greenfield signaling demand outside saturated Chinese markets.
- AI-Assisted Predictive Maintenance:Machine learning integration with axle counters and track circuits enables condition-based component replacement, shifting revenue toward recurring service contracts.
- Digital Interlocking Convergence:Cloud-based interlocking architectures combined with 5G train-to-ground links reduce wayside hardware density in new-build metros.
Industry Challenges
- SIL-4 Certification Bottlenecks:Safety integrity level validation for software updates extends deployment timelines, compressing vendor cash conversion cycles.
- Legacy System Integration:Hybrid configurations bridging relay-based interlocking with modern CBTC demand specialized engineering talent scarce in emerging metro markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Rail Transit Signaling Market |
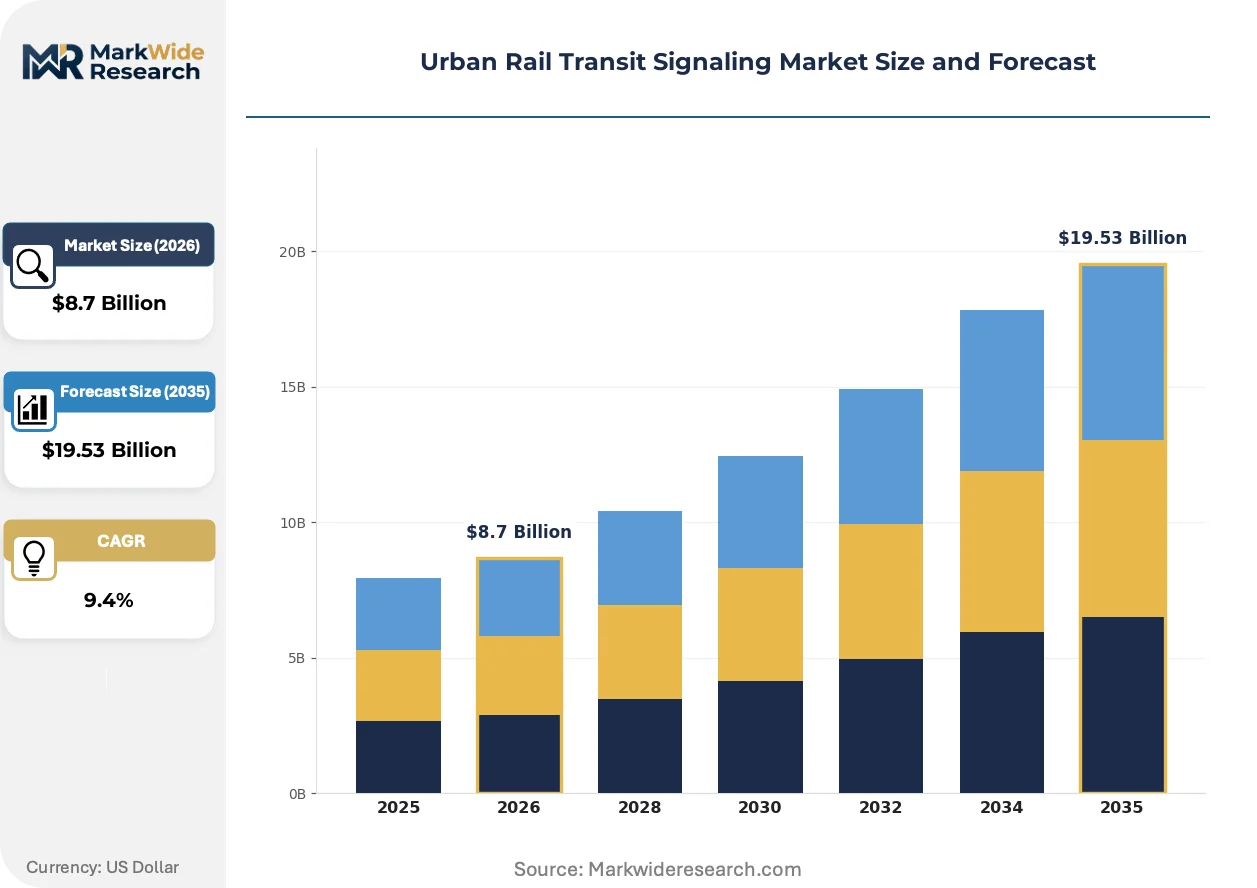
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CBTC, ERTMS, ATC, Traditional Signaling End User: Government, Rail Operators, Infrastructure Managers, Contractors Deployment: On-Premise, Cloud-Based, Hybrid, Remote Service Type: Consulting, Integration, Maintenance, Support |
| Companies Covered | Beijing Urban Transit Technology, Glarun Technology, Casco Signal Ltd., Siemens, China Railway Signal & Communication, Traffic Control Technology, Thales SAIC Transportation System, Alstom, UniTTEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Rail Transit Signaling Market Evolving Landscape
Signaling architecture is decoupling from proprietary hardware stacks as virtualization and open interfaces penetrate safety-critical systems. This shift is compressing vendor lock-in duration and enabling modular upgrade paths.
Moving-block train control is migrating from fixed-block legacy infrastructure in Asian metros seeking granular capacity optimization. Seoul Metro and Singapore's Land Transport Authority have accelerated CBTC retrofit timelines. This migration is compressing incumbent supplier maintenance contract durations as open-architecture alternatives penetrate procurement evaluations.
The EU's F-Gas Regulation is phasing out sulfur hexafluoride in high-voltage switchgear, forcing signaling power supply redesigns. Manufacturers must substitute gas-insulated equipment with vacuum or solid-state alternatives. This transition most affects turnkey project vendors serving German and French national rail networks, where environmental compliance timelines are shortest.
Service unbundling is fragmenting traditional EPC contracts as operators separate signaling hardware from long-term maintenance obligations. Delhi Metro and Hong Kong's MTR Corporation now tender predictive analytics and spare parts logistics as distinct procurement lots. This pattern is most visible in Asia-Pacific markets where public-private partnership structures dominate new line financing.
Urban Rail Transit Signaling Market Segmentation
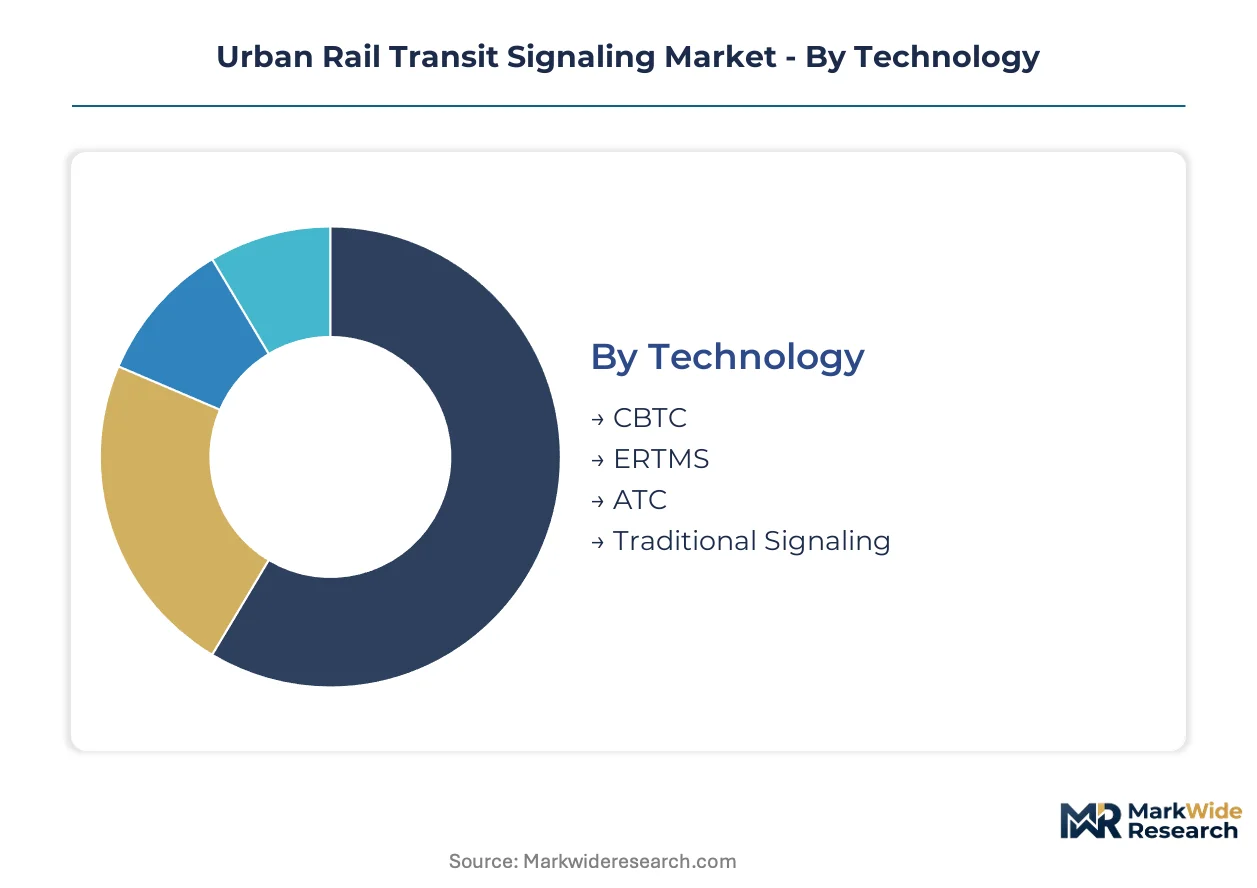
Signaling procurement patterns diverge sharply across technology maturity curves and contracting structures. Vendors must align portfolio depth with replacement-cycle velocity in each segment cluster.
Technology:
Replacement cycles stretch from 15-year ERTMS overhauls to sub-decade CBTC refreshes as Asian metros chase capacity gains.
- CBTC:Communication-based architectures enable moving-block headways below 90 seconds through continuous train-to-ground data exchange. Dense Asian corridors in Beijing, Seoul, and Singapore drive retrofit demand as operators abandon fixed-block constraints for granular capacity optimization.
- ERTMS:The European Rail Traffic Management System standardizes cross-border interoperability through ETCS levels 1-3. EU member states under the ERTMS directive face mandatory legacy replacement timelines, concentrating demand in German, French, and Italian national networks.
- ATC:Automatic train control systems govern speed enforcement and station stopping in legacy metro installations across Japan and North America.
- Traditional Signaling:Relay-based interlocking and track circuits persist in emerging markets with constrained capital budgets.
Traditional signaling dominates installed base. CBTC is where expansion concentrates.
End User:
Procurement authority fragments across public ownership models and concession structures, reshaping vendor sales cycles.
- Government:National transport ministries and municipal authorities control capital allocation for network extensions. China's MIIT procurement rules and India's Metro Rail Policy channel spending through state-directed tendering processes.
- Rail Operators:Delhi Metro Rail Corporation, Hong Kong MTR, and Tokyo Metro wield direct contracting authority for system upgrades. These entities increasingly unbundle hardware from long-term service obligations.
- Infrastructure Managers:Deutsche Bahn Network and SNCF Réseau oversee trackside asset maintenance on national corridors.
- Contractors:Turnkey construction consortia bundle signaling into civil infrastructure packages in greenfield Middle Eastern and Southeast Asian projects.
Government entities control capital deployment. Rail operators are gaining procurement autonomy fastest.
Deployment:
Architecture choices trade off cybersecurity assurance against operational flexibility in safety-critical environments.
- On-Premise:Dedicated server racks and localized interlocking hardware remain mandatory for SIL-4 safety integrity requirements in tunnel environments. European and Japanese regulators enforce air-gapped architectures for core signaling functions.
- Cloud-Based:Virtualized interlocking and centralized traffic management migrate non-safety functions to distributed data centers. Singapore's Land Transport Authority pilots cloud-native signaling for elevated guideways with redundant fiber connectivity.
- Hybrid:Safety-critical logic stays on-premise while diagnostics and passenger information systems leverage cloud connectivity.
- Remote:Satellite-linked monitoring serves rural light-rail extensions with limited wayside infrastructure.
On-premise architectures anchor safety-critical installations. Cloud-based deployment is climbing the fastest in greenfield Asian metros.
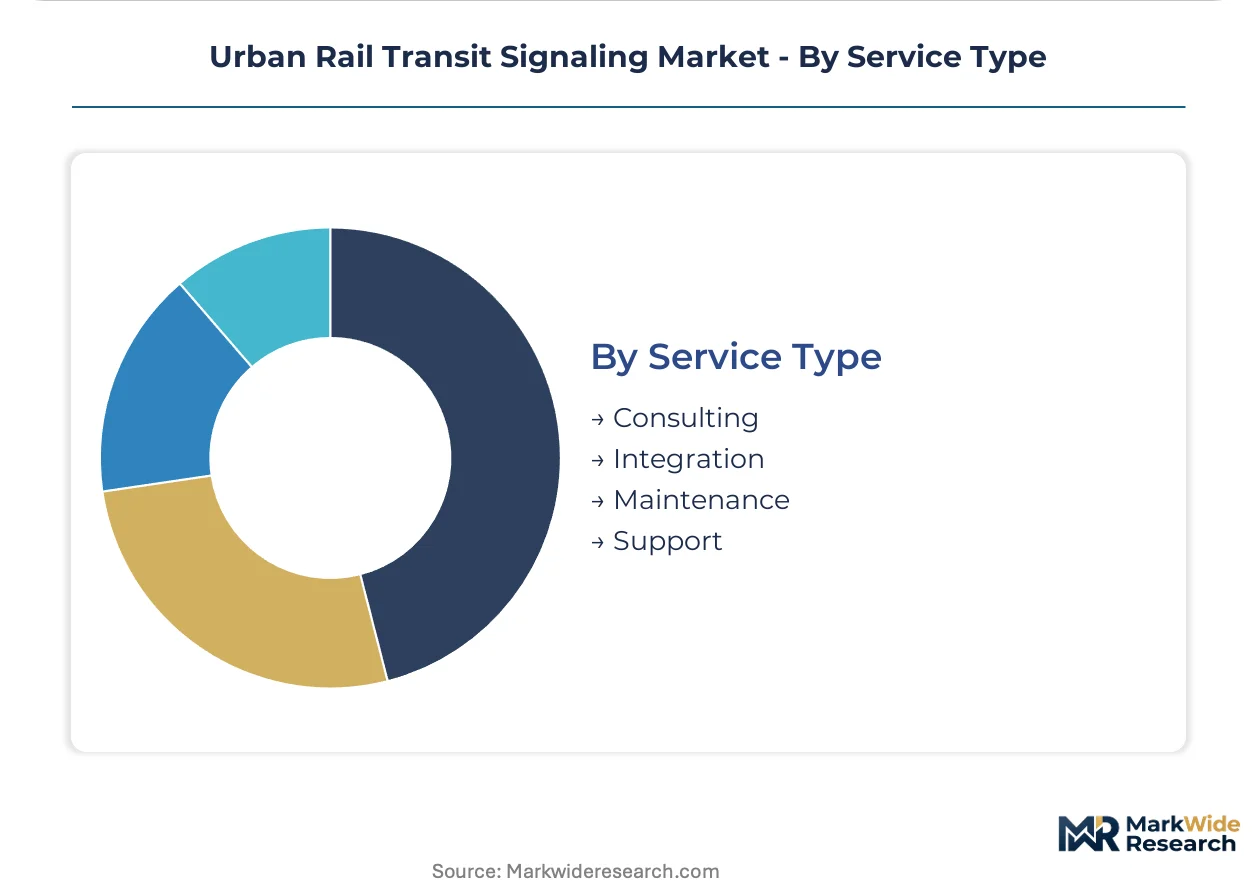
Service Type:
Revenue mix shifts toward recurring obligations as installed bases mature across European and East Asian networks.
- Consulting:System specification and tender documentation support operators navigating technology transitions. European infrastructure managers engage specialized advisors for ERTMS migration planning.
- Integration:Turnkey project delivery encompasses design, installation, and commissioning for new-build metros. Alstom and Siemens dominate this segment through proven tunnel-deployment expertise.
- Maintenance:Preventive and corrective servicing of axle counters, track circuits, and onboard controllers generates recurring revenue. Service contracts now extend 15-20 years on modern CBTC installations.
- Support:24/7 technical assistance and spare parts logistics ensure system availability. Delhi Metro and Hong Kong MTR now tender predictive analytics as distinct procurement lots separate from hardware.
Integration commands upfront project value. Maintenance is where vendor margin stability concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in signaling procurement varies sharply by market maturity. Established European networks prioritize interoperability compliance over unit cost, while emerging Asian metros negotiate aggressively on total project value.
China
Beijing and Shanghai network extensions drive concentrated demand for CBTC modernization under MIIT procurement rules. GB standards enforce domestic content thresholds that channel awards to local systems integrators. The Yangtze River Delta corridor sustains replacement cycles as Tier-1 cities abandon legacy fixed-block infrastructure.
Germany
Deutsche Bahn Network corridors face mandatory ERTMS migration timelines under EU directive obligations. The F-Gas Regulation accelerates power supply redesigns for switchgear compliance. Industrial clusters around Munich and Stuttgart anchor turnkey project delivery for cross-border interoperability upgrades.
India
Delhi Metro Rail Corporation and emerging Tier-2 cities generate greenfield signaling demand outside saturated Chinese markets. CEA coordination with the Ministry of Railways standardizes electrification and signaling specifications through the Metro Rail Policy. Mumbai and Bangalore metro expansions concentrate procurement activity in western and southern corridors.
France
SNCF Réseau manages national trackside asset maintenance with ERTMS deployment concentrated on cross-border corridors to Belgium and Germany. The EU's ERTMS directive compels legacy system retirement on priority routes. Paris metro modernization under RATP authority sustains demand for tunnel-deployment expertise.
Singapore
Land Transport Authority pilots cloud-native signaling architectures for elevated guideways with redundant fiber connectivity. Dense corridor operations prioritize sub-90-second headway optimization through moving-block technology. The city-state's procurement frameworks increasingly unbundle hardware from long-term predictive analytics contracts.
Urban Rail Transit Signaling Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. European systems integrators command premium positioning through ERTMS platform depth and tunnel-deployment expertise. Chinese state-affiliated entities anchor domestic procurement through regulatory alignment with MIIT standards. Turnkey project vendors compete on commissioning velocity, while maintenance specialists capture recurring revenue as installed bases mature. Consolidation pressure intensifies through strategic partnerships linking signaling hardware with civil infrastructure consortia.
Among Chinese state-aligned integrators, Beijing Urban Transit Technology and China Railway Signal & Communication occupy positions shaped by GB standard enforcement and Tier-1 metro network relationships. Siemens and Alstom exemplify the European systems integration tier, with the former anchored in German ERTMS corridor deployment and the latter in French turnkey project delivery. Casco Signal Ltd. sits within the specialized signaling technology segment, representing the joint-venture archetype that bridges domestic regulatory requirements with international technical standards.
| Leading Market Players |
|---|
| Beijing Urban Transit Technology |
| Glarun Technology |
| Casco Signal Ltd. |
| Siemens |
| China Railway Signal & Communication |
| Traffic Control Technology |
| Thales SAIC Transportation System |
| Alstom |
| UniTTEC |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor's containerized electronics logistics costs feed directly into vendor pricing power and buyer segmentation across the signaling value chain. Dense procurement clusters in Shanghai and Beijing compress logistics premiums for domestic integrators while elevating landed costs for European ERTMS specialists serving cross-border mandates.
Pricing Analysis
Extended maintenance contracts and predictive analytics subscriptions now drive lifetime value capture beyond initial system commissioning. Project-based pricing dominates turnkey CBTC installations with differentiation anchored in SIL-4 certification grade and tunnel-deployment expertise. Cost compression in hardware tiers intensifies as Chinese GB standards enforcement deepens local sourcing pools. State-affiliated rail operators exhibit lowest price sensitivity; emerging Tier-2 Indian metros negotiate most aggressively on total project value.
Supply Chain Analysis
Semiconductor foundry capacity concentrates in Taiwan and South Korea with safety-critical processor fabrication tethered to TSMC and Samsung logic nodes. Rare earth permanent magnets for traction systems and copper cabling for power distribution represent critical input dependencies. Single-source vulnerability in advanced node silicon exposes signaling OEMs to geopolitical disruption. Distribution runs through systems integrator-led consortia bundling hardware with civil infrastructure packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maintenance and predictive analytics revenue layers are expanding faster than original equipment sales as Asian operators unbundle long-term service obligations from hardware procurement. This service-attach dynamic restructures vendor economics toward recurring contract structures.
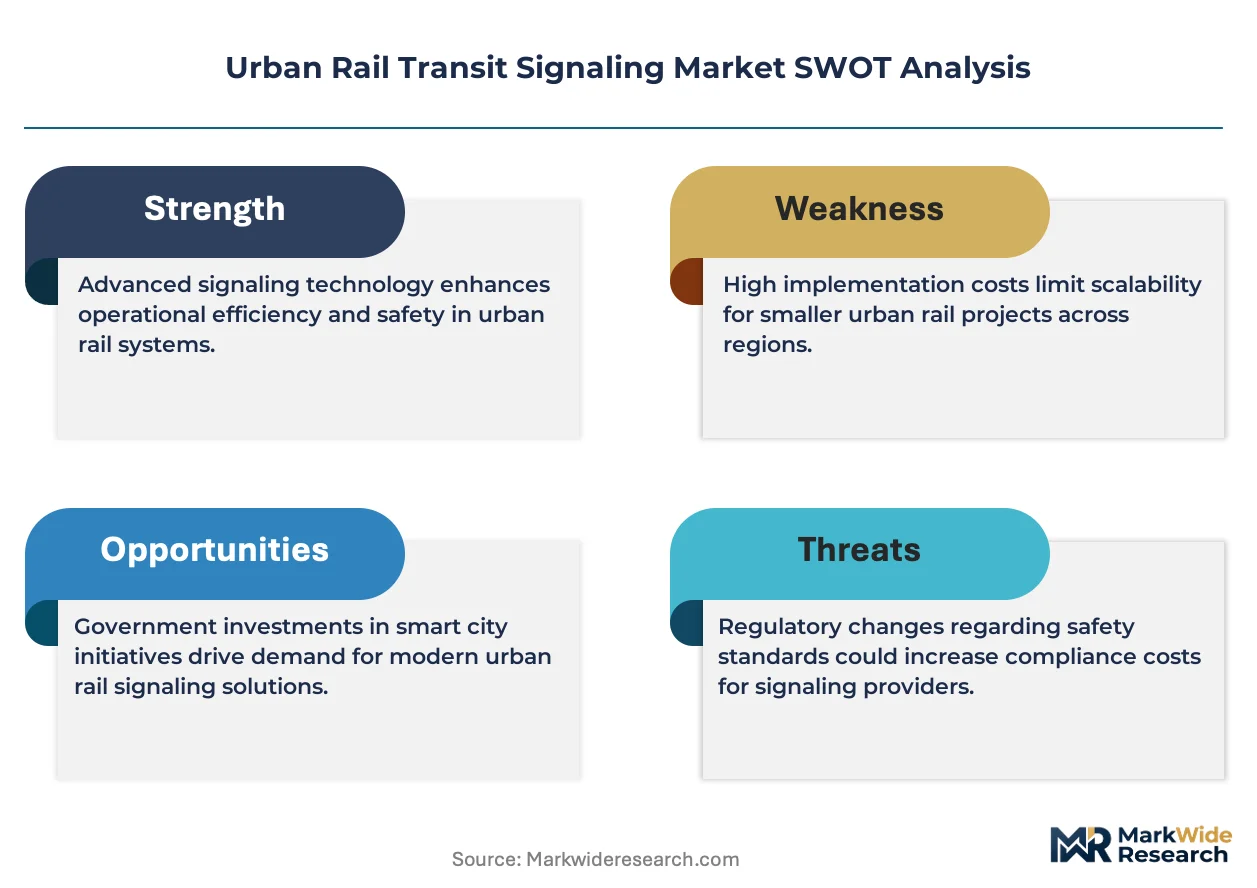
For Market Incumbents: Build switching-cost moats through proprietary diagnostic data lakes accumulated across installed CBTC bases. Deepen backward integration into safety-critical semiconductor sourcing to offset Taiwan foundry concentration risk. Counter emerging cloud-native interlocking entrants by accelerating certification velocity for software updates under ERTMS mandates. For New Entrants and Emerging Players: Build out AI-assisted predictive maintenance capabilities targeting Delhi Metro and Hong Kong MTR's unbundled analytics procurement lots. India's Tier-2 greenfield networks present the most penetrable geography given CEA coordination standardization and absence of incumbent maintenance relationships. Pursue joint-venture structures with domestic Indian systems integrators to satisfy Metro Rail Policy local content thresholds. For Investors and Strategic Acquirers: Specialized signaling software houses with proven SIL-4 validation pipelines represent priority acquisition targets given certification bottleneck scarcity. Long-term viability hinges on recurring revenue mix exceeding hardware dependency across the projection horizon. Monitor ERTMS deployment velocity in German and French cross-border corridors as inflection indicator for European replacement cycle momentum.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Predictive Maintenance Platform Launch | Delhi Metro's unbundled analytics tenders create first-mover advantage in service-attach revenue capture. |
| Backward Integration into Safety-Critical Silicon | TSMC concentration risk mitigation strengthens margin resilience against foundry allocation constraints. |
| Cloud-Native Interlocking Certification Pathway | Singapore LTA pilot programs validate architecture for elevated guideway greenfield deployments. |
| Joint Venture with Indian Domestic Integrator | CEA local content compliance unlocks Mumbai and Bangalore metro expansion procurement access. |
| ERTMS Level 3 Migration Partnership | Deutsche Bahn Network mandatory timelines concentrate demand for ETCS baseline upgrade expertise. |
Research Methodology
Desk research of EU transport directives, MIIT procurement filings, and Indian Metro Rail Policy documentation preceded structured interviews with signaling systems integrators, rail operator procurement directors, and semiconductor supply chain managers. Secondary validation drew from Deutsche Bahn capital expenditure disclosures, Land Transport Authority tender databases, and customs records for signaling equipment trade flows. Bottom-up project pipeline aggregation was cross-checked against top-down market sizing from national rail modernization budgets.
Assumptions held fixed across the modeling period include ERTMS directive enforcement timelines, GB standards procurement continuity, and copper price volatility bands. Segmentation dimensions spanned technology generation, deployment architecture, and service type with regional regulatory clusters as overlay. CAGRs were derived from installed base replacement velocity and greenfield network expansion trajectories. Forecast inputs incorporated CBTC retrofit cycle compression in Seoul and Singapore, plus ERTMS migration pacing in German cross-border corridors.
Stress conditions across semiconductor allocation severity, rare earth export restriction scenarios, and ERTMS deadline extension possibilities were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology transition pacing and regulatory enforcement continuity. Quarterly review of foundry capacity allocation indicators and national rail budget appropriation trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
Railroad Tank Car Market
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Global Rail Freight Transport Market