
 Rail Internet of Things (IoT) Market | 2026-2036
Rail Internet of Things (IoT) Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Internet of Things (IoT) Market Analytics
Multi-source procurement of IoT subsystems is rebalancing toward vertically integrated platform providers as rail operators consolidate vendor relationships. CRRC Corporation Limited anchors large-scale manufacturing capacity across Asia, while ABB Group specializes in electrification-integrated IoT architectures for European corridors. Cisco Systems, Inc. extends its communications backbone dominance into rail-specific edge networks, competing against Fujitsu Limited's embedded signaling expertise.
Rail Internet of Things denotes networked sensor, communication, and computing infrastructure deployed across rolling stock, trackside equipment, and control centers to enable real-time operational visibility and automated decision-making. Systems typically integrate vibration sensors sampling at kilohertz frequencies, GPS positioning modules, and LTE/5G radio links to stream telemetry to centralized or distributed processing nodes for predictive intervention. Fleet Management applications command the largest current revenue pool as freight operators prioritize locomotive availability and fuel optimization, while Edge Computing deployments represent the fastest structural expansion as latency-sensitive safety applications outgrow cloud-only architectures. Predictive Maintenance segments concentrate margin pools in specialized analytics software layered above commoditized sensor hardware.
The EU Agency for Railways enforces ERTMS/ETCS interoperability mandates that shape IoT procurement specifications across member states, while the US Federal Railroad Administration's signal system regulations and positive train control requirements dictate minimum functional performance for domestic deployments. China's MIIT issues GB standards for railway telecommunications that condition market access for foreign platform vendors. Stakeholders must monitor how diverging cybersecurity certification regimes between European EN standards and emerging US TSA rail security directives reshape cross-border product architecture decisions.
Market Dynamics
The convergence of ERTMS/ETCS interoperability mandates with freight operators' fuel optimization imperatives is compressing procurement cycles and forcing vendor consolidation across sensor networks and edge computing infrastructure.
Growth Catalysts
- EU Green Deal rail modal shift targets:The framework's binding emissions reduction thresholds redirect public procurement budgets toward interoperable IoT platforms that enable freight-to-rail conversion on dense industrial corridors.
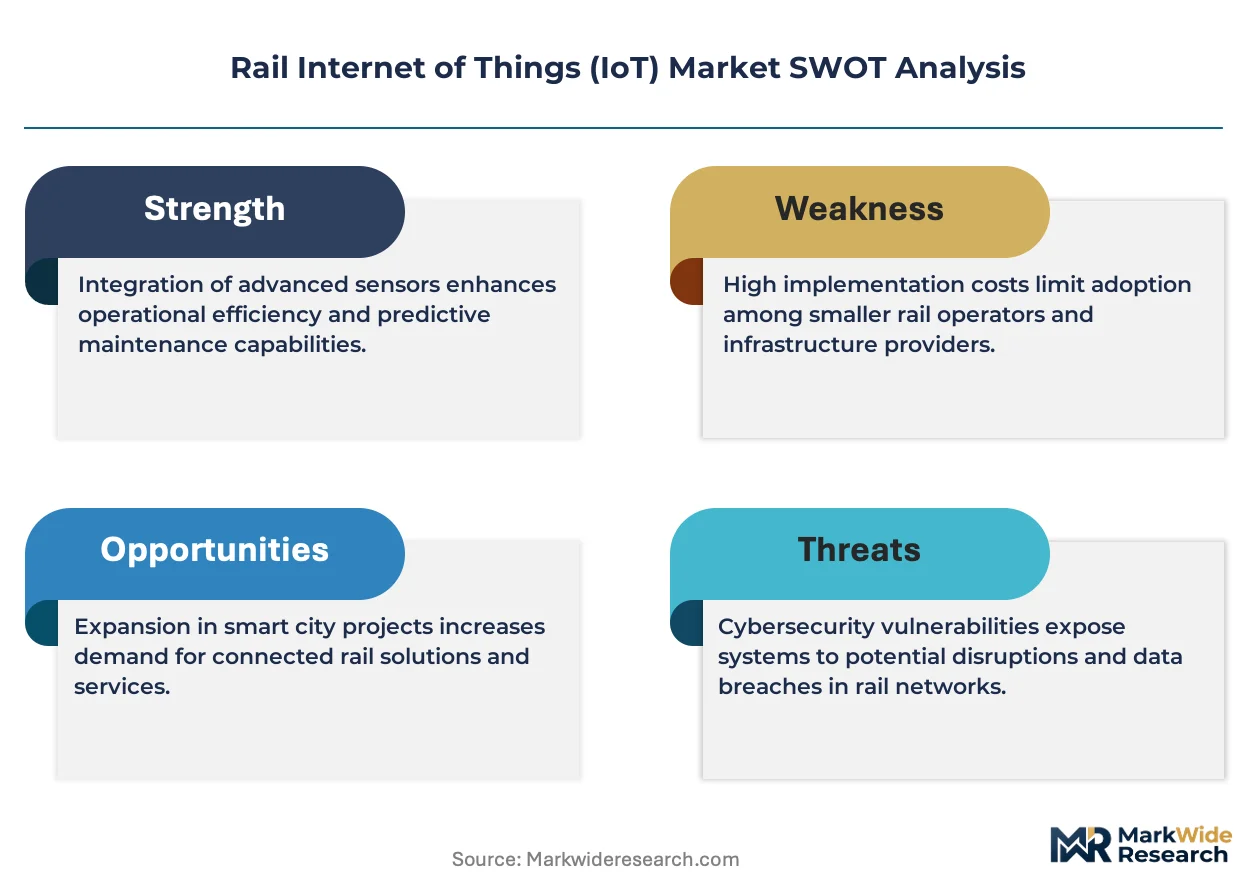
- Predictive maintenance software layering:Specialized analytics suites built atop commoditized vibration and thermal sensor hardware capture margin pools previously absorbed by hardware vendors alone.
- Deutsche Bahn's digital rail program:Germany's concentrated deployment of edge computing nodes along freight-dense corridors creates reference architectures that neighboring operators replicate.
Market Restraints
- Semiconductor supply concentration:GPS positioning modules and kilohertz-frequency vibration sensors depend on foundry capacity concentrated in East Asian manufacturing zones, exposing procurement timelines to geopolitical friction.
- ERTMS certification complexity:The EU Agency for Railways' interoperability testing protocols extend deployment lead times for cross-border rolling stock retrofits beyond standard capital planning horizons.
- LTE/5G spectrum fragmentation:Divergent national frequency allocations for rail-specific radio links force hardware vendors to maintain multiple SKU variants, inflating unit economics for low-volume corridors.
Strategic Opportunities
- Poland's underpenetrated freight corridors:The country's east-west coal and container flows lack sensor density comparable to German networks, creating first-mover deployment potential for integrated platform providers.
- AI-driven acoustic bearing monitoring:Machine learning inference at the edge enables detection of wheel defects before thermal signature emergence, opening subscription revenue streams distinct from hardware sales.
- US TSA rail security directives:Emerging cybersecurity certification requirements for critical infrastructure create compliant-product premiums for vendors with pre-positioned EN-standard security architectures.
Industry Challenges
- Embedded systems cybersecurity talent scarcity:Rail-specific firmware hardening against IEC 62443 threats requires skill sets concentrated in aerospace and automotive sectors, forcing compensation premiums.
- Legacy signaling integration complexity:Analog track circuit systems in Eastern European networks resist seamless digital overlay without intermediate protocol translation layers that introduce latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Internet of Things (IoT) Market |
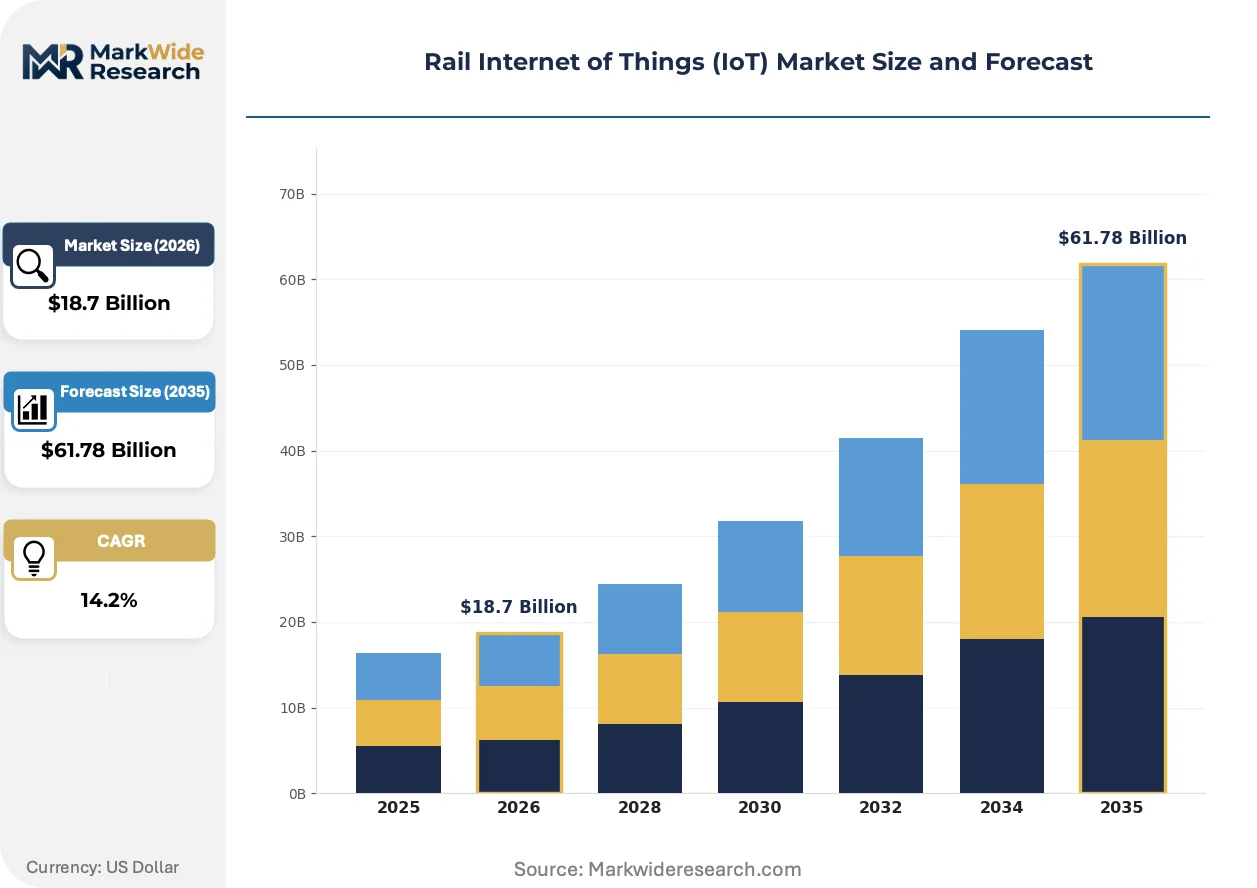
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensor Networks, Cloud Computing, Edge Computing, Data Analytics Application: Predictive Maintenance, Fleet Management, Safety Monitoring, Asset Tracking End User: Rail Operators, Freight Companies, Government Agencies, Maintenance Providers Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Dedicated Infrastructure |
| Companies Covered | CAF, Construcciones y Auxiliar de Ferrocarriles, S.A, CRRC Corporation Limited, ABB Group, HIMA Group, Fujitsu Limited, Alstom Holdings SA, Cisco Systems, Inc., Hitachi, Ltd., AtkinsRéalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Internet of Things (IoT) Market Evolving Landscape
Edge-native inference architectures are displacing cloud-dependent telemetry pipelines as latency-sensitive safety applications outgrow round-trip constraints. This compression is redrawing vendor boundaries between sensor hardware, radio infrastructure, and analytics software layers.
Digital twin implementations for rolling stock fleets are consolidating previously siloed vibration, thermal, and GPS telemetry streams into unified degradation models. European freight operators with dense locomotive deployments are adopting these architectures fastest. The technology is consolidating maintenance vendor relationships by collapsing separate sensor, connectivity, and software procurement contracts into single-platform agreements.
The EU AI Act's risk classification framework for safety-critical infrastructure is forcing explicit documentation of algorithmic decision pathways in predictive maintenance systems. Rail operators deploying automated braking or route optimization must now maintain audit trails that trace inference outputs to training data provenance. German and French corridors with the deepest ERTMS penetration are experiencing the most intensive compliance engineering cycles.
Freight buyers are unbundling long-term maintenance contracts from original equipment procurement, creating discrete competitive arenas for sensor-lifecycle management. Polish and Romanian operators with aging diesel fleets are piloting subscription-based hardware refresh programs that transfer obsolescence risk to platform vendors. This shift is most visible in corridors where state-owned incumbents face new private freight competition with lower capital deployment thresholds.
Rail Internet of Things (IoT) Market Segmentation
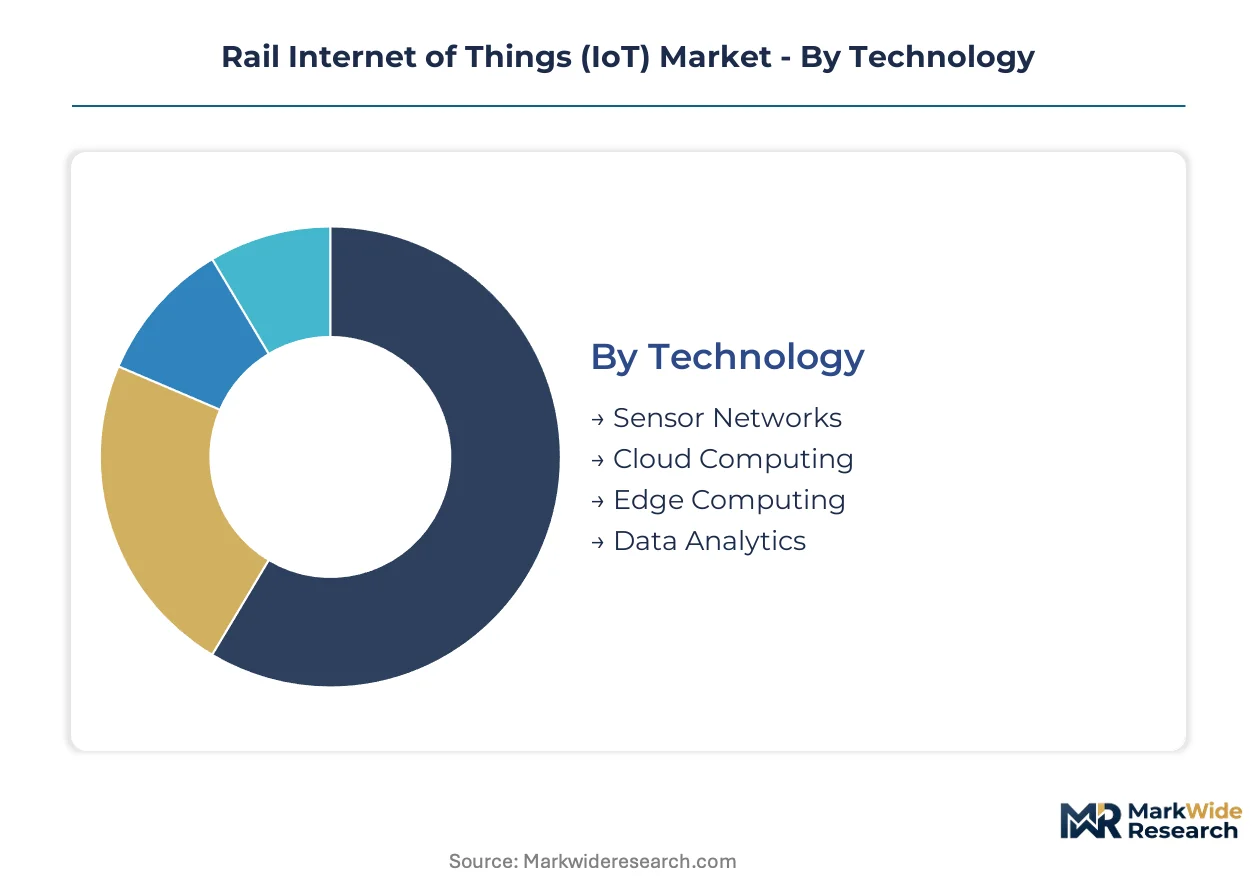
Rail IoT procurement decisions hinge on certification compatibility across ERTMS, IEC 62443, and national telecom standards. Segment boundaries determine which vendor ecosystems operators can access and how integration costs accumulate across rolling stock lifecycles.
Technology:
Certification burdens concentrate in radio transmission and safety-critical processing layers, with EU Agency for Railways interoperability testing extending lead times for Edge Computing and sensor network deployments.
- Sensor Networks:Vibration sensors sampling at kilohertz frequencies, thermal monitors, and GPS positioning modules form the physical data layer. Deutsche Bahn's digital rail program drives concentrated German demand for hardened industrial-grade units that withstand axle-level shock loads. ERTMS certification requirements for trackside sensor gateways extend procurement cycles beyond standard hardware sourcing timelines.
- Edge Computing:Distributed processing nodes enable latency-sensitive safety applications without cloud round-trip delays. Polish and Romanian freight corridors with aging diesel fleets represent underpenetrated deployment opportunities where first-mover platform providers capture reference architecture advantages. IEC 62443 cybersecurity hardening for embedded rail firmware imposes specialized engineering requirements distinct from IT-grade edge deployments.
- Cloud Computing:Centralized telemetry aggregation and long-term fleet analytics reside here, with German operators leading adoption for locomotive availability optimization.
- Data Analytics:Predictive maintenance software suites extract margin pools from commoditized sensor hardware through specialized degradation modeling algorithms.
Sensor Networks sits at the top of the volume ranking, with Edge Computing climbing the fastest.
Application:
Functional priority shifts from reactive fleet visibility toward predictive intervention as fuel optimization imperatives compress maintenance windows across European freight corridors.
- Fleet Management:Real-time locomotive positioning, fuel consumption monitoring, and route optimization command the largest current revenue commitment from freight operators. North American Class I railroads prioritize availability metrics that directly tie to capital utilization rates. The segment demands LTE/5G radio infrastructure that withstands rural coverage gaps and tunnel environments.
- Predictive Maintenance:AI-driven acoustic bearing monitoring and thermal signature analysis enable defect detection before functional failure. German and French corridors with deepest ERTMS penetration pilot these systems fastest, driven by EU Green Deal emissions targets that penalize unplanned downtime. Subscription revenue models are displacing hardware-centric procurement in this segment.
- Safety Monitoring:Automated braking validation and obstacle detection systems interface directly with train control architectures, requiring the most stringent certification protocols.
- Asset Tracking:Container and wagon-level visibility solutions serve intermodal operators managing handoffs between rail, truck, and maritime legs.
Fleet Management holds the dominant revenue position, while Predictive Maintenance gains share fastest through software-subscription conversion.
End User:
Procurement authority fragmentation across state-owned incumbents, private freight challengers, and maintenance outsourcing vendors creates divergent contracting structures for the same underlying sensor hardware.
- Freight Companies:Private operators in Poland and Romania with lower capital deployment thresholds drive subscription-based hardware refresh pilots that transfer obsolescence risk to platform vendors. These buyers unbundle long-term maintenance from original equipment procurement, creating discrete competitive arenas for sensor-lifecycle management. Fuel optimization imperatives dominate their technology prioritization.
- Rail Operators:State-owned incumbents like Deutsche Bahn anchor large-scale edge computing deployments and set reference architectures neighboring operators replicate. Their procurement concentrates in interoperable platforms that satisfy EU Agency for Railways mandates for cross-border rolling stock compatibility.
- Government Agencies:National regulators and infrastructure owners fund trackside sensor networks on priority corridors, with EU Green Deal modal shift targets redirecting public budgets toward freight-to-rail conversion enablers.
- Maintenance Providers:Independent service vendors capture outsourced predictive analytics contracts as operators unbundle software from hardware procurement.
Freight Companies generate the steepest demand expansion, with Rail Operators maintaining the largest installed base commitment.
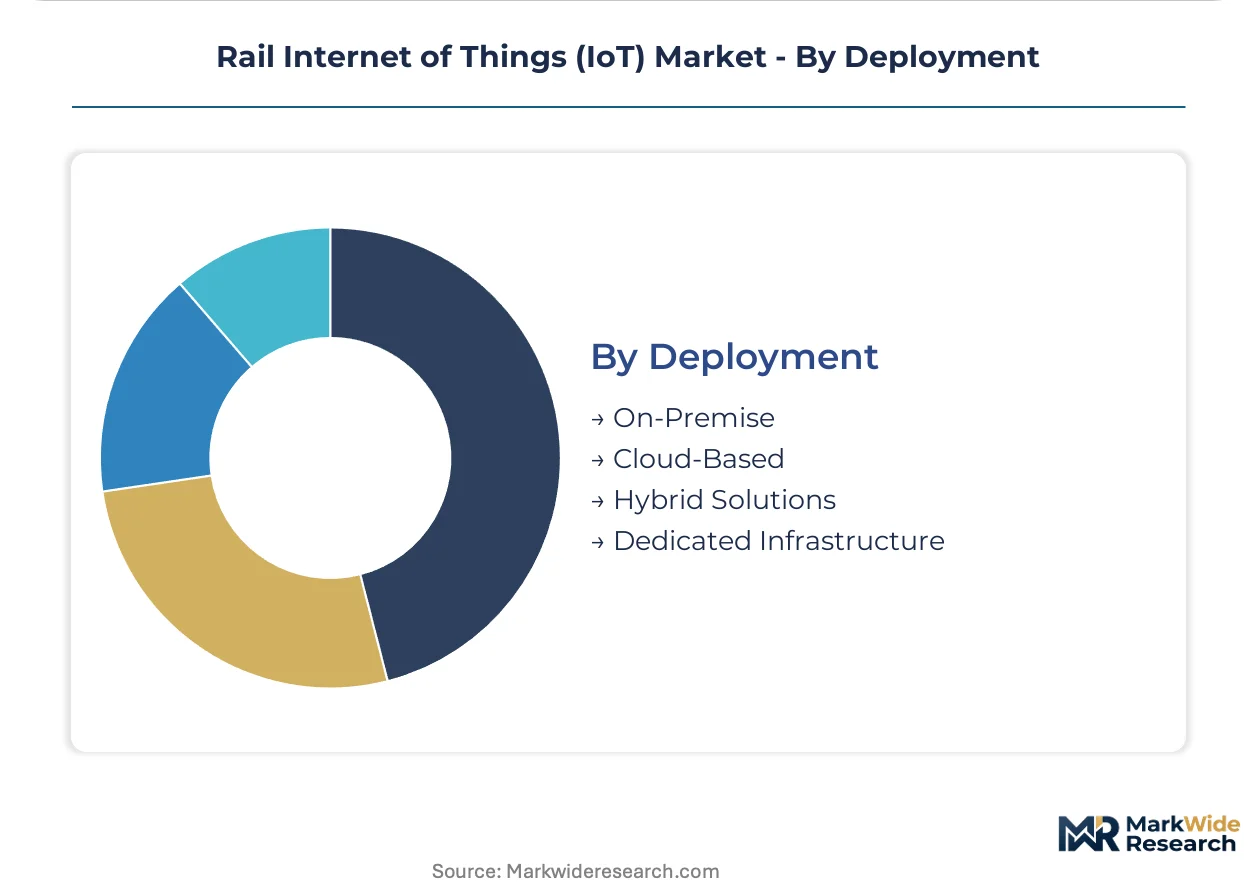
Deployment:
Architecture choices reflect latency requirements, data sovereignty constraints, and legacy system integration complexity across Eastern European analog track circuits.
- Hybrid Solutions:Split processing between edge nodes for real-time safety decisions and cloud aggregation for fleet-level analytics dominates new European deployments. This architecture satisfies EU AI Act documentation requirements for algorithmic audit trails while containing latency for automated braking applications. German corridors with dense ERTMS penetration pilot these configurations most intensively.
- On-Premise:Dedicated control center infrastructure persists where data sovereignty or air-gapped security requirements override cloud economics, particularly in government-funded safety systems.
- Cloud-Based:Pure cloud deployments concentrate in non-safety-critical asset tracking and back-office fleet analytics where round-trip latency tolerances permit.
- Dedicated Infrastructure:Rail-specific LTE/5G networks with hardened trackside base stations serve corridors where commercial telecom coverage proves insufficient for mission-critical telemetry.
Hybrid Solutions command the dominant deployment preference, with Dedicated Infrastructure expanding most quickly in underpenetrated Eastern European corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor anchors concentrated demand for rail IoT infrastructure as freight operators modernize legacy networks. Deutsche Bahn's digital rail program and the EU Green Deal's modal shift targets are redirecting procurement budgets toward interoperable sensor platforms and edge computing nodes across European freight-dense corridors.
United States
Class I freight railroads prioritize locomotive availability metrics that directly tie to capital utilization rates. The Federal Railroad Administration's positive train control requirements dictate minimum functional performance for domestic signal system deployments. Chicago's rail hub concentration drives concentrated demand for LTE/5G radio infrastructure that withstands rural coverage gaps and tunnel environments.
Germany
Deutsche Bahn's digital rail program creates reference architectures that neighboring operators replicate across cross-border corridors. The EU Agency for Railways enforces ERTMS/ETCS interoperability mandates that shape IoT procurement specifications for rolling stock retrofits. The Rhine-Alpine freight corridor pilots edge-native inference architectures for latency-sensitive safety applications.
China
MIIT issues GB standards for railway telecommunications that condition market access for foreign platform vendors. Dual carbon goals accelerate electrification-integrated IoT architectures across high-speed and freight networks. The Beijing-Tianjin-Hebei corridor concentrates manufacturing capacity for GPS positioning modules and vibration sensors.
Poland
East-west coal and container flows lack sensor density comparable to German networks, creating first-mover deployment potential for integrated platform providers. EU Green Deal emissions reduction thresholds redirect public procurement toward freight-to-rail conversion enablers. The Silesian industrial basin pilots subscription-based hardware refresh programs that transfer obsolescence risk to vendors.
France
SNCF's freight division unbundles long-term maintenance contracts from original equipment procurement, creating discrete competitive arenas for sensor-lifecycle management. The EU AI Act's risk classification framework forces explicit documentation of algorithmic decision pathways in predictive maintenance systems. The Lyon-Paris freight corridor experiences intensive compliance engineering cycles for automated braking validation.
Rail Internet of Things (IoT) Market Competitive Landscape
Global majors compete with regional champions across electrification-integrated architectures and communications backbone dominance. The vendor ecosystem organizes around vertically integrated platform providers, specialized signaling fabricators, and communications infrastructure specialists. Three archetypes predominate: state-linked rolling stock conglomerates, European electrification specialists, and North American network equipment providers. Consolidation pressures favor M&A activity among sensor hardware vendors and strategic partnerships between edge computing specialists and rail operators seeking reference architectures.
Within the vertically integrated tier, CRRC Corporation Limited and ABB Group exemplify divergent geographic anchoring strategies, with the former representing state-linked manufacturing scale and the latter occupying a position in European corridor electrification. Cisco Systems, Inc. sits within the communications infrastructure archetype, extending backbone dominance into rail-specific edge networks. These three companies collectively illustrate how certification compatibility across ERTMS, IEC 62443, and national telecom standards determines accessible vendor ecosystems and integration cost accumulation across rolling stock lifecycles.
| Leading Market Players |
|---|
| CAF, Construcciones y Auxiliar de Ferrocarriles, S.A |
| CRRC Corporation Limited |
| ABB Group |
| HIMA Group |
| Fujitsu Limited |
| Alstom Holdings SA |
| Cisco Systems, Inc. |
| Hitachi, Ltd. |
| AtkinsRéalis |
| Others |
Value Network & Pricing Analysis
State-owned rail operators with consolidated procurement authority across European freight corridors drive contract-based long-term offtake agreements that lock in sensor hardware and edge computing infrastructure pricing across multi-year deployment cycles. Their volume concentration enables tiered pricing negotiations that commoditize baseline sensor modules while preserving premiums for ERTMS-certified and IEC 62443-hardened variants.
Pricing Analysis
Input-cost pass-through from GPS positioning modules and kilohertz-frequency vibration sensors flows into hardware procurement contracts, though subscription-based predictive maintenance software layers partially insulate platform vendors from semiconductor volatility. Three-tier pricing structure across ERTMS-certified premium, standard industrial-grade, and uncertified economy sensor tiers separates buyers by interoperability requirements and cybersecurity hardening levels. Pricing pressure stems from freight operators unbundling hardware from maintenance contracts and demanding sensor-lifecycle management subscriptions. Private freight challengers in Poland and Romania exhibit highest price sensitivity due to lower capital deployment thresholds, while Deutsche Bahn's digital rail program maintains lowest sensitivity given reference architecture replication value.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundry capacity for GPS modules and vibration sensor MEMS fabrication, exposing procurement timelines to geopolitical friction. Manufacturing gravity centers on China for railway telecommunications hardware per MIIT GB standards, Germany for ERTMS-compatible signaling components, and South Korea for LTE/5G radio infrastructure. Raw material dependencies span rare earth elements for sensor magnetics, high-purity silicon for semiconductor substrates, and copper for trackside power distribution. Tariff exposure runs through cross-border component flows between Asia and European assembly facilities. Distribution runs through vertically integrated platform providers that bundle sensor procurement with edge computing deployment and predictive analytics software licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail IoT procurement has shifted toward premium-tier ERTMS-certified and EU AI Act-compliant platforms as interoperability mandates and algorithmic audit requirements reshape operator specifications. This quality migration favors vendors with pre-positioned certification investments and penalizes commodity hardware specialists.
For Market Incumbents: Anchor market position through backward integration into ERTMS-certified sensor manufacturing and captive supply of IEC 62443-hardened edge computing firmware. Deutsche Bahn's reference architecture replication creates channel control leverage against emerging platform challengers. Defensive capacity concentration in German freight-dense corridors captures neighboring operator procurement decisions. Cybersecurity talent scarcity in rail-specific embedded systems forces compensation premiums that favor incumbents with established aerospace and automotive recruitment pipelines. For New Entrants and Emerging Players: Capture first-mover advantage in Poland's underpenetrated east-west coal and container corridors where sensor density lags German benchmarks. AI-driven acoustic bearing monitoring at the edge represents the most penetrable application segment, enabling subscription revenue streams distinct from hardware sales. Go-to-market positioning as ERTMS-compliant platform providers with bundled sensor-lifecycle management addresses unbundling trends among private freight operators with lower capital deployment thresholds. For Investors and Strategic Acquirers: European electrification specialists with ERTMS integration capabilities are the most active acquirer in this space, consolidating sensor hardware vendors to deepen platform verticality. Long-term viability hinges on certification moats widening as EU AI Act documentation requirements and US TSA rail security directives compound compliance engineering costs. Acquisition target archetype: mid-cap sensor hardware vendors with ERTMS gateway certification and embedded firmware hardening expertise. Monitor ERTMS certification queue lengths at the EU Agency for Railways as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ERTMS Certification Investment | EU Agency for Railways interoperability mandates condition market access across member state procurement. |
| Edge Computing Infrastructure Deployment | Polish and Romanian freight corridors lack latency-sensitive processing nodes for safety applications. |
| Predictive Maintenance Software Licensing | Subscription revenue models displace hardware-centric procurement among unbundling freight operators. |
| Sensor Hardware Backward Integration | Captive supply of vibration and thermal modules insulates margins from East Asian foundry volatility. |
| Cybersecurity Certification Pre-Positioning | EN-standard architectures command compliant-product premiums under emerging US TSA rail directives. |
Research Methodology
Bottom-up freight operator deployment modeling reconciled against top-down sensor hardware and edge computing production tracking forms the analytical core of this study. Primary interviews with rail procurement directors, ERTMS certification engineers, predictive maintenance software product managers, and EU Agency for Railways technical staff combined with secondary validation against ERTMS deployment databases, EU Green Deal procurement disclosures, SEC filings from listed rail technology vendors, and national telecom regulatory filings. Triangulation between operator capital expenditure plans and vendor order backlogs anchors volume estimates.
Historical trendline analysis of ERTMS rollout velocity, edge computing node deployment density, and predictive maintenance software adoption rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include technology layer, application function, end-user procurement authority, and deployment architecture. CAGRs derived from fitted growth curves adjusted for certification lead time constraints and semiconductor supply cycle phases. Industry-specific forecast inputs encompass EU Green Deal modal shift target compliance timelines and Deutsche Bahn digital rail program expansion milestones.
Semiconductor supply disruption, ERTMS certification queue elongation, and divergent national cybersecurity regime implementation are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding interoperability mandate enforcement consistency and freight operator capital availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Transportation Predictive Analytics Market