
 New Energy Vehicle Sweeper Market | 2026-2036
New Energy Vehicle Sweeper Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Vehicle Sweeper Market Insights
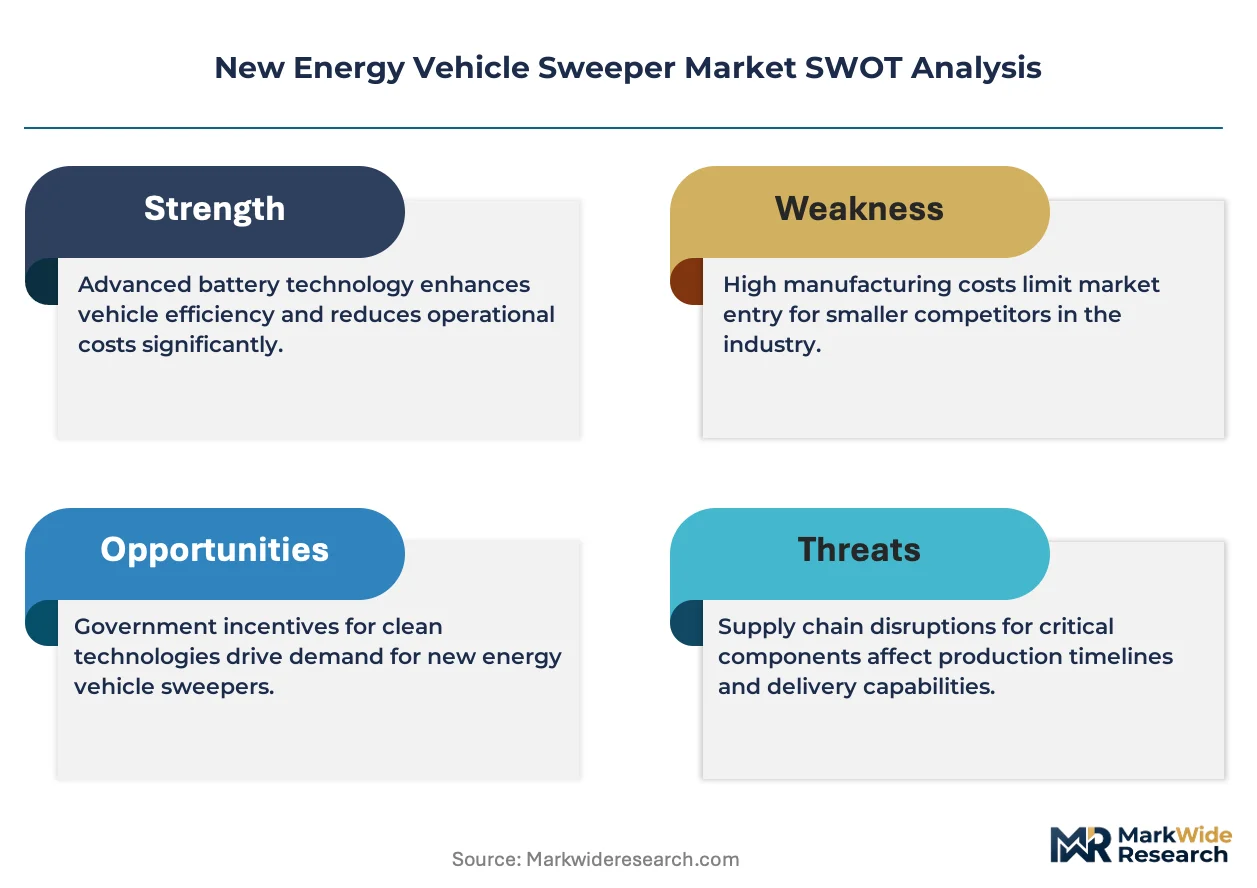
Leasing-based procurement is fragmenting the competitive landscape for new energy vehicle sweepers by lowering capital barriers for municipal contractors and facility management firms. FULONGMA leverages its integrated manufacturing base to control component costs across electric drivetrain production. Boschung differentiates through specialized airport and runway sweeping configurations that demand higher technical certification. Dulevo sustains European market presence with established service networks that reduce downtime for municipal fleets.
A new energy vehicle sweeper is a battery-electric or hybrid-powered municipal cleaning machine equipped with suction systems, brush mechanisms, and debris containment units, typically operating at noise levels below 75 decibels for urban compliance. Its primary purpose is mechanized removal of particulate matter, litter, and road debris from public thoroughfares, industrial zones, and commercial parking facilities while eliminating tailpipe emissions associated with conventional diesel sweepers. Truck-mounted configurations dominate municipal street maintenance contracts due to higher debris capacity and continuous operation requirements, while robotic sweepers represent the fastest-expanding technology segment as autonomous navigation systems mature for controlled environments like parking structures and warehouse complexes. Compact sweepers anchor margin pools in facility management applications where maneuverability in constrained spaces commands pricing premiums over larger formats.
EU Green Deal emission targets and F-Gas Regulation compliance requirements are mandating zero-emission transitions for municipal vehicle fleets across member states, directly conditioning tender specifications and procurement budgets. China's MIIT new energy vehicle catalog and GB standards for special-purpose electric vehicles establish technical baselines for domestic manufacturers exporting to Belt and Road markets. EPA diesel emission regulations in the United States and evolving state-level zero-emission fleet mandates in California are constricting conventional sweeper demand while redirecting capital toward electric alternatives. Stakeholders must monitor battery supply chain localization policies and charging infrastructure deployment timelines to align production capacity with procurement cycles.
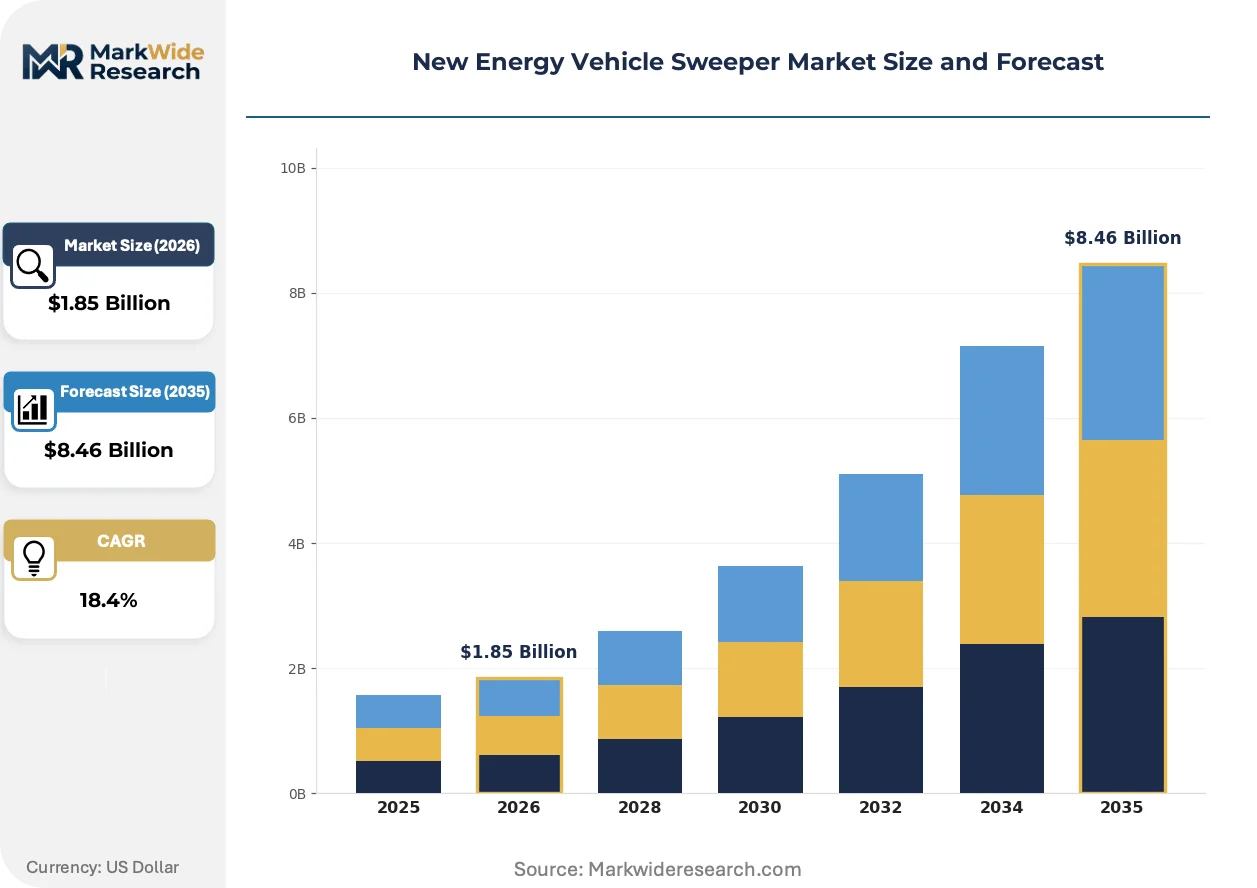
Market Dynamics
Leasing-based procurement models are fragmenting competitive positioning by collapsing capital barriers for municipal contractors and facility management firms, forcing manufacturers to restructure pricing and service bundling. Battery supply chain localization policies across Germany, France, and the Netherlands are compressing delivery timelines and conditioning tender eligibility.
Growth Catalysts
- EU Green Deal mandates:Germany's federal procurement rules now require zero-emission street maintenance equipment in urban contracts, accelerating fleet replacement cycles for diesel sweepers.
- Airport certification demand:Specialized runway sweeping configurations require higher technical standards that electric platforms increasingly satisfy through reduced noise and thermal signatures.
- Solid-state cell development:Battery energy density improvements are extending operational range per charge, enabling continuous-duty municipal applications previously reserved for combustion engines.
Market Restraints
- Lithium supply concentration:Cathode material processing capacity clusters in China, creating geographic vulnerability for European manufacturers dependent on imported cell components.
- Charging infrastructure gaps:Municipal depot electrification timelines lag behind vehicle procurement cycles, constraining deployment in secondary cities and peripheral districts.
- Residual value uncertainty:Battery degradation curves for heavy-duty sweepers remain unproven at scale, elevating total cost of ownership calculations in tender evaluations.
Strategic Opportunities
- Robotic sweeper convergence:Autonomous navigation maturation in controlled environments creates white space in parking structures and warehouse complexes where labor costs dominate.
- Netherlands tender innovation:Dutch municipal procurement rules now prioritize operational service hours over capital expenditure, favoring performance-based contracting models.
- F-Gas Regulation compliance:EU mandates on fluorinated greenhouse gases are eliminating conventional refrigeration-based debris containment systems, opening substitution demand for electric thermal management.
Industry Challenges
- Technician skill gaps:High-voltage drivetrain maintenance requires specialized certification that existing municipal fleet workshops rarely possess, forcing reliance on manufacturer service networks.
- Integration complexity:Legacy fleet management software lacks API compatibility with electric vehicle telematics, complicating route optimization and charge scheduling for mixed-asset operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Vehicle Sweeper Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Sweepers, Truck-Mounted Sweepers, Ride-On Sweepers, Robotic Sweepers Technology: Electric Drive, Hybrid Systems, Autonomous Navigation, IoT Integration Application: Urban Cleaning, Parking Lot Maintenance, Street Maintenance, Industrial Cleaning End User: Municipalities, Facility Managers, Environmental Services, Contractors |
| Companies Covered | FULONGMA, Jinan Baiyi Environmental Protection Technology Co.,Ltd, Shandong Yuedi New Energy Technology Co.,Ltd, Anhui Airuite New Energy Special Purpose Vehicle Co.,Ltd, Shanghai Qixiu Machine Equipments Co.,Ltd, Boschung, Dulevo, Scarab Sweepers, Trombia Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Vehicle Sweeper Market Trends and Innovations
Digital twin technology is virtualizing sweeper design validation and fleet management workflows, compressing development cycles and enabling predictive maintenance models. Three interconnected developments are reshaping how manufacturers and operators extract value from electrified cleaning platforms.
Solid-state battery architectures are virtualizing conventional thermal management systems by eliminating liquid cooling loops and their associated maintenance burden. German municipal fleets are piloting these configurations in compact sweepers where space constraints previously limited energy storage. The structural consequence is a compression of total vehicle weight and a redistribution of engineering resources toward autonomous control systems rather than mechanical subsystems.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in mobile equipment, forcing redesign of debris hopper cooling and dust suppression systems. Industrial consequence includes accelerated adoption of thermoelectric alternatives and electric compressor architectures. Airport sweeping segments face the most compressed compliance timelines, with operators in France and Germany already specifying F-Gas-free equipment in technical tender documents.
Performance-based service contracts are displacing traditional equipment purchase models in Dutch and Belgian municipal markets. Facility management firms and cleaning contractors now procure cleaning capacity by lane-kilometer rather than asset ownership, transferring utilization risk to manufacturers. This pattern concentrates most visibly in urban core contracts where predictable routes favor guaranteed uptime arrangements over capital deployment.
New Energy Vehicle Sweeper Market Segmentation
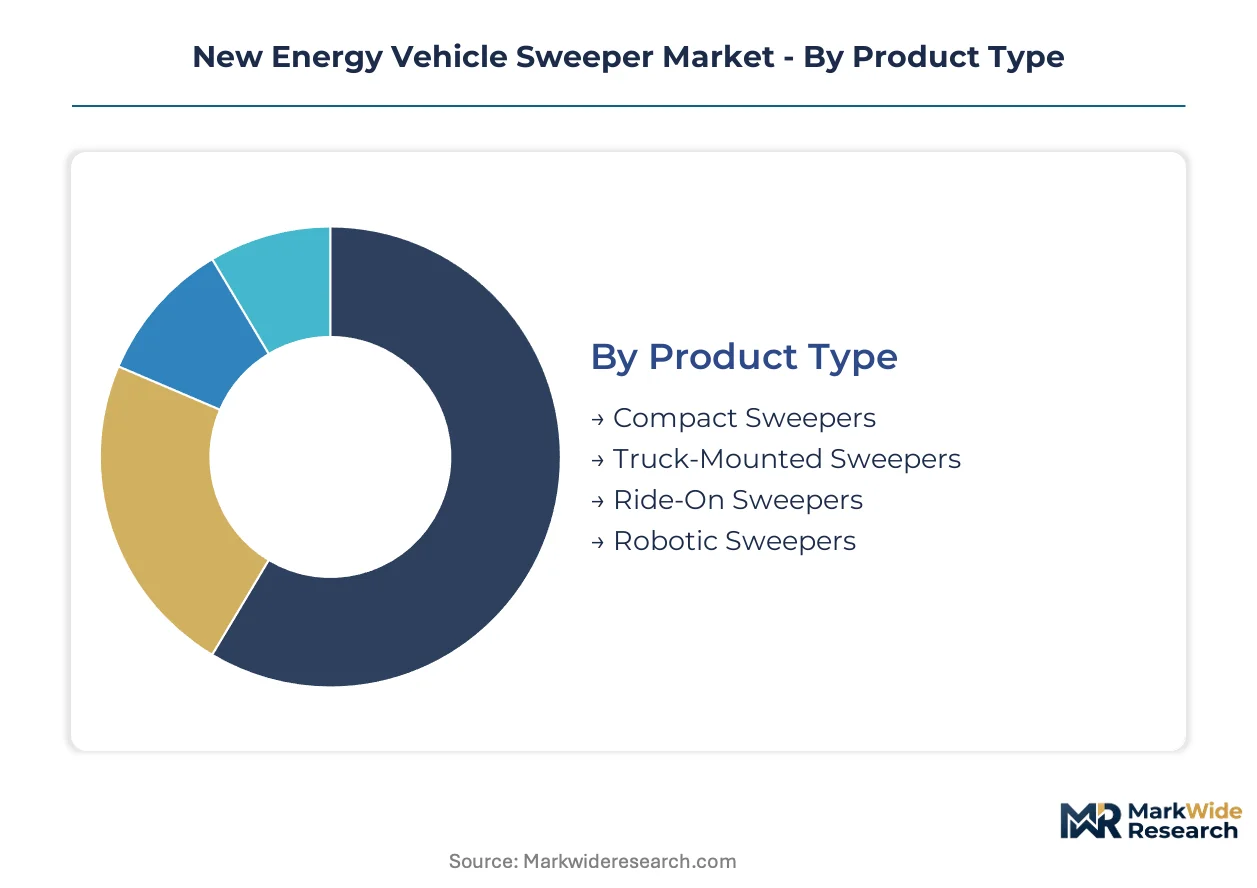
Segmentation in new energy vehicle sweepers determines service network density and spare parts inventory strategies. Municipal procurement patterns diverge sharply from facility management requirements, forcing manufacturers to configure support infrastructure around distinct operational intensity profiles.
Product Type:
After-sales-service intensity varies dramatically across sweeper formats, with compact units requiring frequent brush replacement and truck-mounted platforms demanding specialized high-voltage technician deployment.
- Truck-Mounted Sweepers:Heavy-duty chassis configurations integrate battery packs exceeding 200 kWh capacity alongside hydraulic debris lift systems. Demand concentrates in German and French municipal fleets where continuous-duty street maintenance contracts require 16-hour operational windows. Service intervals center on hydraulic component wear and battery thermal management calibration.
- Robotic Sweepers:Autonomous navigation platforms utilize lidar arrays and edge-computing modules for obstacle detection in structured environments. Facility managers in Dutch logistics parks and Belgian distribution centers are deploying these units to compress labor costs in overnight cleaning operations. Software update cycles and sensor recalibration dominate maintenance schedules.
- Compact Sweepers:Maneuverable units with sub-2-meter width specifications serve constrained urban corridors and pedestrian zones. Battery swapping architectures reduce depot downtime for multi-shift operations.
- Ride-On Sweepers:Operator-steered configurations bridge manual and autonomous cleaning modes for transitional facility environments. Mid-capacity debris hoppers suit commercial parking structures with moderate traffic density.
By volume, truck-mounted configurations lead municipal procurement. By growth pace, robotic sweepers are expanding most quickly in controlled logistics environments.
Technology:
Cost tier stratification separates premium autonomous platforms from standardized electric drivetrains, with hybrid systems occupying a narrowing intermediate position as battery economics improve.
- Electric Drive:Pure battery architectures eliminate tailpipe emissions and thermal signatures for noise-sensitive zones. German airport authorities specify these configurations for apron cleaning where jet fuel vapor management is critical. Cell chemistry selection between NMC and LFP formulations conditions warranty terms and charging infrastructure requirements.
- Autonomous Navigation:Sensor fusion stacks combining camera, radar, and lidar inputs enable unsupervised operation in geofenced environments. Netherlands-based facility contractors are piloting these systems in multi-level parking structures where GPS denial requires SLAM-based positioning. Cybersecurity certification for fleet management APIs adds compliance overhead.
- Hybrid Systems:Range-extender configurations retain small combustion generators for emergency backup duty. Declining relevance in core European markets as charging infrastructure matures.
- IoT Integration:Telematics modules stream operational data to cloud-based fleet management platforms. Predictive brush wear algorithms and charge-optimization scheduling reduce total operating expenditure.
By installed base, electric drive dominates tender specifications. By deployment momentum, autonomous navigation is gaining share fastest in private facility contracts.
Application:
Geography shapes application demand with urban core density favoring compact formats and peripheral industrial zones requiring high-capacity debris handling.
- Urban Cleaning:Municipal street maintenance operations demand sub-75 decibel noise compliance and zero-emission certification for EU Green Deal alignment. French cities including Paris and Lyon mandate these specifications in technical tender documents. Brush wear rates accelerate in abrasive winter conditions requiring salt and grit removal.
- Industrial Cleaning:Manufacturing facilities and logistics hubs prioritize dust suppression and hazardous material containment. German automotive plants specify HEPA filtration and sealed debris hoppers for paint shop proximity operations. Explosion-proof electrical certification opens chemical and pharmaceutical segments.
- Street Maintenance:Highway and arterial road operations require higher travel speeds and larger hopper volumes than urban core sweepers. Seasonal leaf collection drives peak demand cycles.
- Parking Lot Maintenance:Retail and commercial property managers emphasize maneuverability in tight turning radii and low-clearance structures. Overnight operation windows compress service scheduling flexibility.
By contract value, urban cleaning leads procurement spending. By expansion trajectory, industrial cleaning is climbing the fastest as manufacturing reshoring intensifies facility investment.
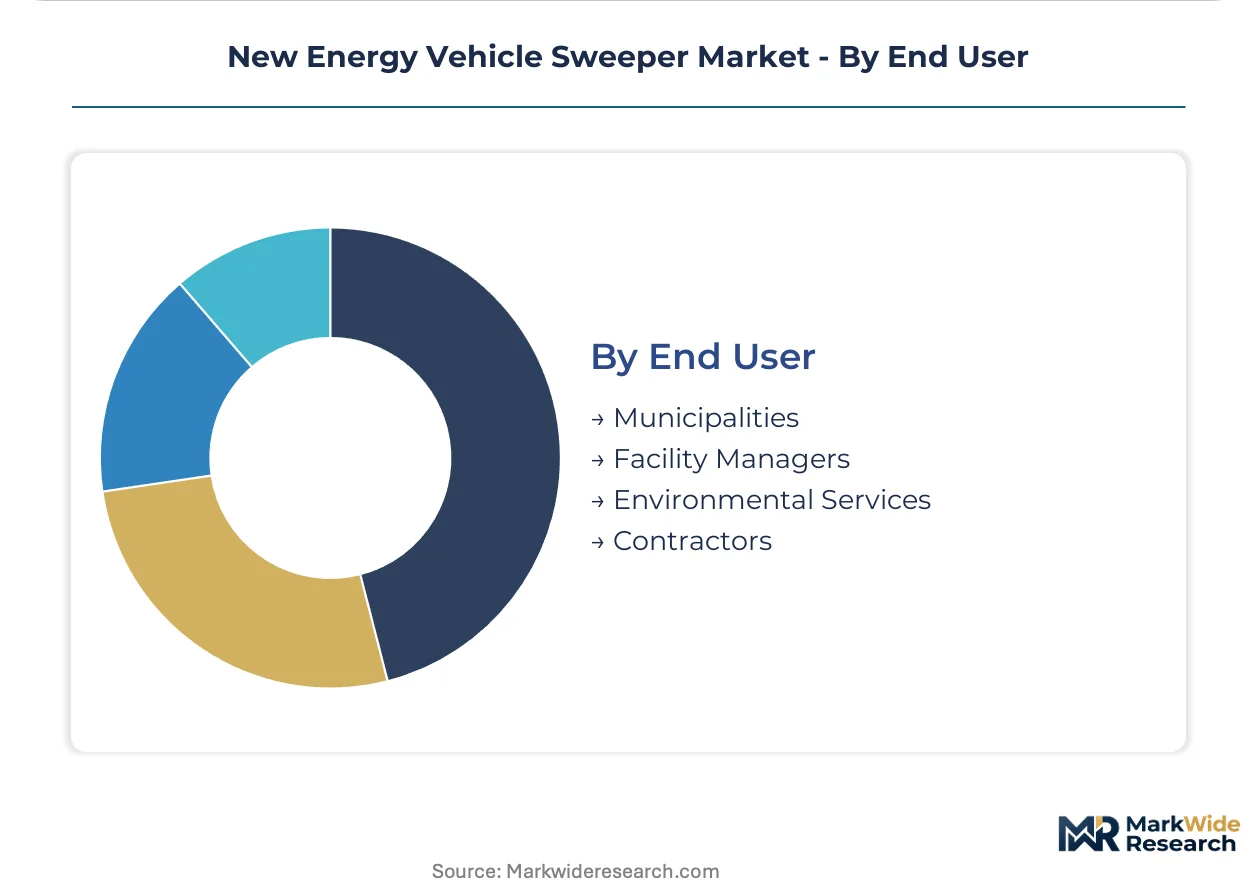
End User:
Customer type determines procurement modality with municipalities favoring capital purchase and facility managers shifting toward performance-based service contracts.
- Municipalities:Public sector fleet operators in Germany, France, and the Netherlands execute multi-year tender processes with total cost of ownership evaluation frameworks. EU Green Deal mandates now embed zero-emission requirements in federal and state-level procurement rules. Depot electrification timelines condition deployment phasing.
- Facility Managers:Commercial property service providers increasingly procure cleaning capacity rather than asset ownership. Dutch and Belgian markets lead this transition with lane-kilometer contracting structures. Uptime guarantees and rapid response service level agreements replace traditional warranty terms.
- Environmental Services:Specialized contractors handle hazardous waste and contaminated site remediation with certified containment systems. Regulatory compliance documentation exceeds standard municipal requirements.
- Contractors:Flexible fleet operators serve seasonal demand spikes and emergency response with rental and short-term lease configurations. Asset utilization optimization drives telematics adoption.
By fleet size, municipalities control the largest installed base. By contract innovation, facility managers are restructuring procurement fastest toward outcome-based models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal mandates zero-emission municipal fleets, accelerating procurement cycles across member states. Germany, France, and the Netherlands anchor European demand through federal tender rules and depot electrification programs. China's MIIT catalog and Belt and Road export frameworks shape Asian supply dynamics.
Germany
Federal procurement rules now require zero-emission street maintenance equipment in urban contracts. KBA certification standards for special-purpose electric vehicles establish technical baselines for domestic manufacturers. Municipal fleets in Berlin and Hamburg are executing phased diesel sweeper replacements through 2030.
France
Paris and Lyon mandate sub-75 decibel noise compliance and zero-emission certification in technical tender documents. ANSM environmental regulations align with EU F-Gas phase-down timelines for debris containment systems. Auvergne-Rhône-Alpes industrial clusters supply thermoelectric cooling components for airport-grade sweepers.
Netherlands
Dutch municipal procurement rules prioritize operational service hours over capital expenditure, favoring performance-based contracting. The Randstad urban corridor leads lane-kilometer service model adoption among facility management firms. Eindhoven Region testing grounds validate autonomous navigation systems for parking structure deployment.
China
MIIT new energy vehicle catalog inclusion determines eligibility for domestic municipal procurement and Belt and Road export financing. GB standards for special-purpose electric vehicles establish technical baselines for battery-electric sweeper architectures. Yangtze River Delta manufacturing bases integrate solid-state cell development into compact sweeper production lines.
United States
EPA diesel emission regulations constrict conventional sweeper demand while California state-level zero-emission fleet mandates redirect capital toward electric alternatives. Municipal depot electrification timelines in Los Angeles and San Francisco condition deployment phasing for truck-mounted configurations. Midwest industrial zones pilot robotic sweepers in warehouse complexes under OSHA-guided safety protocols.
New Energy Vehicle Sweeper Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement modalities. The market structures around three tiers: integrated manufacturers with captive battery supply, specialized airport-grade fabricators with technical certification depth, and regional service-network operators with established municipal relationships. Consolidation pressure concentrates among leasing-platform intermediaries collapsing capital barriers. Dominant competitive moves include backward integration into cell component sourcing and performance-based service contract structuring.
Within the integrated manufacturing tier, FULONGMA exemplifies cost-control architectures spanning electric drivetrain production. Among European specialists, Boschung and Dulevo occupy positions differentiated through technical certification depth and service network density respectively. These three anchors represent divergent strategic postures: scale-driven component integration, premium-tier technical specialization, and relationship-intensive aftermarket presence.
| Leading Market Players |
|---|
| FULONGMA |
| Jinan Baiyi Environmental Protection Technology Co.,Ltd |
| Shandong Yuedi New Energy Technology Co.,Ltd |
| Anhui Airuite New Energy Special Purpose Vehicle Co.,Ltd |
| Shanghai Qixiu Machine Equipments Co.,Ltd |
| Boschung |
| Dulevo |
| Scarab Sweepers |
| Trombia Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Yangtze River Delta battery cell production is compressing module pricing for European OEMs while simultaneously accelerating supplier consolidation toward vertically integrated drivetrain manufacturers. This utilization dynamic forces tier-two sweeper assemblers to absorb margin compression or cede share to captives with in-house lithium processing.
Pricing Analysis
Certification level creates the primary spread between airport-grade and municipal sweeper configurations, with CE marking for F-Gas compliance adding substantial cost premiums over baseline urban equipment. Three-tier pricing structure across premium autonomous, standard electric, and economy hybrid levels stratifies the competitive landscape, with Dutch facility managers showing highest price sensitivity due to lane-kilometer contracting models. Pricing pressure stems from lithium cathode oversupply and aggressive leasing-platform intermediaries collapsing capital barriers. Municipal fleets in Germany demonstrate lowest price sensitivity, prioritizing total cost of ownership and depot electrification compatibility over acquisition cost.
Supply Chain Analysis
CATL and BYD dominate contract manufacturing capacity for heavy-duty vehicle battery packs, with European assembly increasingly dependent on their cell-to-pack architectures. Geographic supply concentration clusters in China for cathode processing, South Korea for separator membranes, and Germany for power electronics integration. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare earth permanent magnets for traction motors. Single-source vulnerability in solid-state electrolyte development creates procurement risk for next-generation compact sweeper programs. Distribution runs through municipal tender platforms and facility management leasing consortia rather than traditional equipment dealerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facility management consolidators in the Netherlands and Belgium, where lane-kilometer contracting aggregates demand across multiple property portfolios. This procurement concentration fragments manufacturer pricing power and elevates service-level guarantees over equipment specifications.
For Market Incumbents: Insulate margin pools by deepening backward integration into battery thermal management systems and securing exclusive service network density in German municipal markets. Autonomous navigation startups threaten technical differentiation advantages, requiring accelerated certification investment in airport-grade configurations. Capacity addition in Eindhoven Region testing facilities reinforces proximity to Dutch performance-based contract innovation.
For New Entrants and Emerging Players: Build out robotic sweeper deployments in Belgian distribution centers and Dutch multi-level parking structures where labor cost compression drives fastest adoption. Autonomous navigation in GPS-denied environments represents the most penetrable technology segment, with SLAM-based positioning systems offering differentiation against established electric drivetrain players. Go-to-market execution should prioritize facility management consortia over municipal tender processes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among leasing-platform intermediaries and performance-based service contractors, positioning these archetypes for superior cash flow quality across the projection horizon. Acquisition targets should display captive battery supply agreements or established municipal service network density. Solid-state cell commercialization timelines signal inflection points for compact sweeper competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL partnerships secure cell allocation priority for German municipal fleet electrification programs. |
| Autonomous Navigation Certification | Eindhoven Region validation enables Dutch parking structure deployment without GPS dependency. |
| Performance-Based Service Contract | Lane-kilometer structures transfer utilization risk from facility managers to manufacturers. |
| F-Gas Compliance Transition | Thermoelectric cooling substitution opens airport-grade sweeper substitution demand in France. |
| Depot Electrification Partnership | Municipal charging infrastructure alignment accelerates truck-mounted configuration deployment timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal fleet managers, facility management procurement directors, airport operations executives, and sweeper manufacturer product strategists; alongside secondary validation through MIIT catalog filings, EU tender documentation databases, KBA type-approval records, and EIA industrial equipment trade data. Bottom-up unit economics triangulated against top-down fleet replacement projections.
Forecast inputs incorporated propulsion architecture transitions, autonomous navigation maturation curves, and municipal electrification spending patterns across the modeling period. Segmentation dimensions modeled include product format, technology tier, application intensity, and end-user procurement modality. CAGRs were derived from logistic diffusion curves fitted to fleet replacement cycles and battery cost decline trajectories, with solid-state commercialization timelines and F-Gas regulation compliance deadlines as industry-specific sensitivity parameters.
Stress conditions across lithium price volatility, charging infrastructure deployment delays, and technician certification bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about battery energy density improvement rates and municipal budget allocation priorities. Cross-checking against IEA clean equipment procurement benchmarks and national fleet electrification commitments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Personal Transporter Market