
 Smart Logistic Market | 2026-2036
Smart Logistic Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Logistic Market Insights
Mid-market retailers is collapsing into enterprise-grade platforms as order volatility and labor costs reshape procurement priorities. SAP SE leverages its embedded ERP footprint to anchor cloud-native warehouse management deployments across European manufacturing networks. Oracle Corporation competes through autonomous database architectures that sustain real-time inventory visibility for multi-node distribution. Körber differentiates via deep specialization in robotics orchestration for high-throughput fulfillment centers.
Smart logistics encompasses the digital integration of transportation, warehousing, and inventory systems through sensor networks, algorithmic decision engines, and distributed cloud architectures to optimize physical goods flow. IoT-enabled asset tracking and AI-driven demand forecasting constitute core functional parameters, with systems typically processing telemetry at sub-second intervals to reroute shipments or rebalance stock positions. Warehouse Management leads service type deployment due to established ROI metrics around picking accuracy and labor reduction, while Blockchain-enabled provenance verification represents the fastest-growing technology segment as pharmaceutical and food-grade cold chains harden traceability requirements. Cloud Computing occupies the broadest margin pool by amortizing infrastructure across mid-tier operators previously excluded from on-premise WMS deployments.
EMA traceability mandates under the EU Medical Device Regulation and FDA 21 CFR Part 11 electronic record requirements are tightening validation protocols for logistics software serving regulated industries. REACH compliance obligations and the EU AI Act's risk classification framework are forcing platform vendors to document algorithmic decision pathways and chemical handling audit trails. Stakeholders must monitor how emerging carbon border adjustment mechanisms reshape route optimization priorities and carrier selection criteria across transatlantic lanes.
Market Dynamics
Order volatility from e-commerce fulfillment networks is compressing procurement cycles for warehouse automation, forcing mid-market operators toward cloud-native platforms previously reserved for enterprise-scale distribution centers.
Growth Catalysts
- EU Green Deal mandates:Emissions transparency requirements across supply chains are accelerating platform deployment for carbon footprint tracking and route optimization in transatlantic freight corridors.
- Pharmaceutical cold chains:EMA traceability requirements under the EU Medical Device Regulation are hardening demand for blockchain-enabled provenance verification systems in temperature-controlled logistics.
- Industrial clustering:Logistics concentration around Hamburg and the Rhine-Ruhr corridor is driving warehouse management system adoption among German automotive and chemical distributors.
Market Restraints
- Sensor hardware costs:IoT-enabled asset tracking requires substantial upfront investment in telemetry infrastructure, excluding smaller 3PL operators from real-time inventory visibility deployments.
- Algorithmic audit burdens:The EU AI Act's risk classification framework forces vendors to document decision pathways, extending validation timelines for AI-driven demand forecasting modules.
- Lithium-ion supply concentration:Dependence on concentrated battery cell production for warehouse robotics creates vulnerability in automated fulfillment center rollouts.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are creating greenfield demand for automated warehousing in Gujarat and Tamil Nadu industrial corridors.
- Autonomous database convergence:Integration of real-time inventory systems with cloud-native architectures enables multi-node distribution visibility previously unavailable to mid-tier retailers.
- Carbon border adjustments:Emerging CBAM mechanisms on transatlantic lanes will reshape carrier selection criteria, rewarding logistics platforms with embedded emissions optimization.
Industry Challenges
- Robotics orchestration expertise:Shortage of engineers capable of programming high-throughput picking systems limits deployment velocity in fulfillment centers.
- Legacy ERP integration:Cloud-native warehouse management platforms face friction connecting with decades-old on-premise inventory systems still prevalent in European manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Logistic Market |
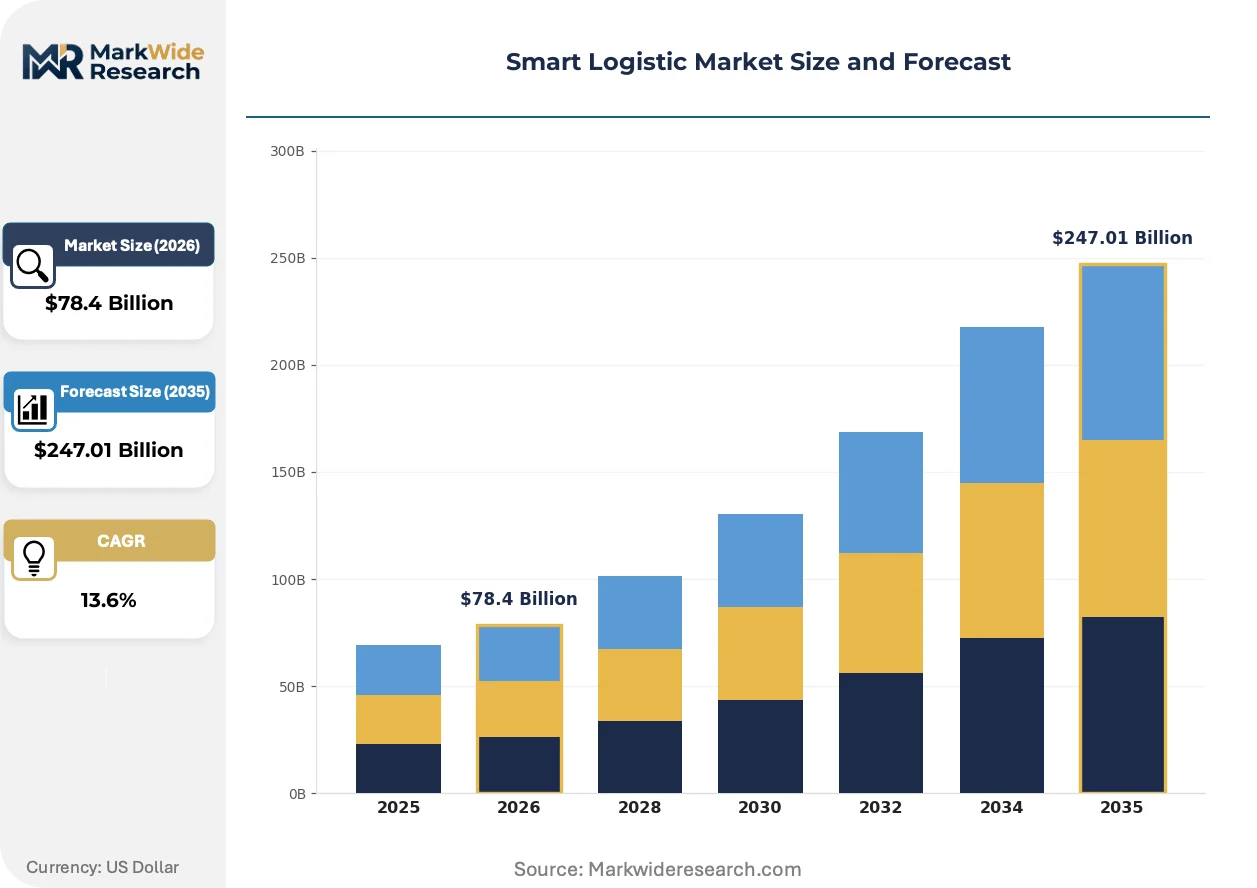
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation Management, Warehouse Management, Inventory Management, Freight Brokerage Technology: IoT, AI, Cloud Computing, Blockchain End User: E-commerce, Retail, Manufacturing, Food & Beverage Delivery Model: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, On-Demand Delivery |
| Companies Covered | Oracle Corporation, IBM Corporation, SAP SE, Dematic, Blue Yonder, Manhattan Associates, Körber, Honeywell International Inc., Cisco Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Logistic Market Trends and Innovations
Algorithmic decision engines are displacing rule-based dispatch systems across transportation networks, while regulatory pressure on emissions documentation and pharmaceutical traceability hardens technical requirements for logistics software architectures.
Digital twin technology for warehouse simulation is fragmenting the traditional WMS vendor landscape. Third-party logistics providers in Germany and the Netherlands are adopting physics-based modeling to optimize picking paths before physical automation deployment. This capability is compressing competitive differentiation between specialized robotics integrators and generalist platform vendors.
The EU AI Act's risk classification framework is tightening validation protocols for algorithmic inventory allocation systems. Logistics software serving pharmaceutical distribution must now document automated decision pathways under EMA guidelines. Cold chain operators in Belgium and Switzerland are restructuring quality assurance teams to maintain compliance documentation for AI-driven temperature excursion responses.
Mid-market retailers are consolidating procurement around subscription-based platform pricing rather than perpetual license models. Cloud computing amortization is displacing on-premise warehouse management deployments among operators previously excluded from enterprise-grade infrastructure. This shift is most visible in French and Italian distribution networks, where capital constraints favor operational expenditure structures over hardware ownership.
Smart Logistic Market Segmentation
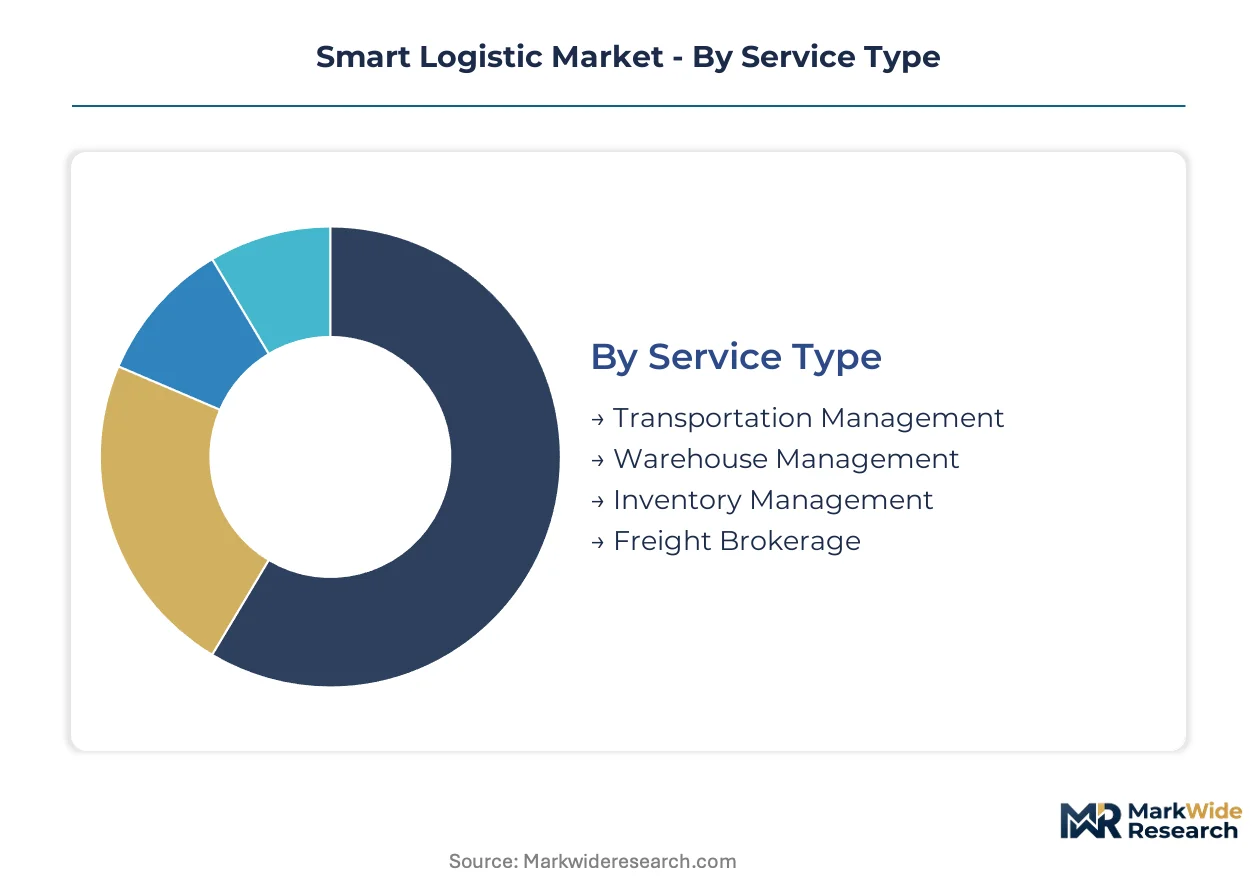
Smart logistics segmentation reveals distinct procurement patterns across service tiers and technology maturity levels. Platform vendors must align pricing architectures with the operational scale and compliance exposure of each buyer category.
Service Type:
Warehouse Management dominates domestic procurement in Germany and the Netherlands, while Transportation Management skews toward export-led demand across transatlantic freight corridors.
- Warehouse Management:Systems orchestrate picking algorithms, robotics integration, and real-time inventory positioning through sensor-dense fulfillment architectures. German automotive distributors around Stuttgart and chemical handlers along the Rhine-Ruhr corridor are consolidating procurement around cloud-native deployments to satisfy CSRD emissions documentation requirements.
- Transportation Management:Platforms optimize carrier selection, route planning, and freight audit through algorithmic dispatch engines. Demand concentrates among Dutch 3PL operators serving Rotterdam-Antwerp port hinterlands, where EU Green Deal mandates on emissions transparency are reshaping procurement priorities for transatlantic lane optimization.
- Inventory Management:Demand forecasting and safety stock optimization modules process telemetry at sub-second intervals for multi-node distribution networks.
- Freight Brokerage:Digital matching platforms connect shippers with contracted carrier capacity, expanding most quickly among mid-market retailers seeking operational expenditure structures over asset ownership.
Warehouse Management commands the established base. The steepest expansion runs through Freight Brokerage.
Technology:
Cost tier stratification separates enterprise-grade full-stack deployments from modular point solutions accessible to capital-constrained operators.
- Cloud Computing:Amortized infrastructure enables mid-tier retailers previously excluded from on-premise WMS deployments to access real-time inventory visibility. French and Italian distribution networks favor subscription pricing over perpetual licenses, compressing competitive differentiation between specialized integrators and generalist platform vendors.
- IoT:Sensor networks for asset tracking and condition monitoring require substantial upfront telemetry infrastructure investment. Belgian pharmaceutical cold chain operators deploy temperature excursion sensors under EMA traceability mandates, while smaller 3PLs face exclusion from real-time visibility deployments due to hardware cost barriers.
- AI:Algorithmic demand forecasting and inventory allocation systems must document decision pathways under EU AI Act risk classification frameworks.
- Blockchain:Provenance verification for pharmaceutical and food-grade supply chains hardens traceability requirements through immutable record architectures.
Cloud Computing anchors the revenue base. Blockchain is climbing the fastest as regulated industries harden audit trail requirements.
End User:
Application intensity varies by sector compliance exposure and order volatility tolerance.
- E-commerce:Fulfillment networks drive automated warehouse system adoption through compressed delivery windows and labor cost pressures. Order volatility is forcing mid-market operators toward enterprise-grade platforms previously reserved for large-scale distribution centers.
- Manufacturing:ERP-integrated logistics platforms synchronize production schedules with inbound material flows and outbound finished goods distribution.
- Retail:Multi-channel inventory positioning requires real-time visibility across store networks, dark stores, and third-party fulfillment nodes.
- Food & Beverage:Temperature-controlled logistics operators in Switzerland restructure quality assurance teams to maintain AI-driven cold chain compliance documentation.
E-commerce holds the volume concentration. Food & Beverage is gaining share fastest through regulatory tailwinds on traceability.
Delivery Model:
Customer type stratification separates premium service tiers with guaranteed windows from economy positioning with flexible scheduling.
- Same-Day Delivery:Urban fulfillment networks in Hamburg and Munich deploy micro-fulfillment centers with automated picking systems to compress last-mile transit times. Labor cost pressures and order volatility are accelerating robotics orchestration investments among grocery and pharmaceutical distributors.
- Next-Day Delivery:Regional distribution nodes optimize sortation capacity and line-haul scheduling to meet committed arrival windows.
- Scheduled Delivery:B2B industrial supply chains coordinate inbound material flows with production line requirements.
- On-Demand Delivery:Crowdsourced driver networks and dynamic routing algorithms serve impulse purchase fulfillment with limited predictability.
Next-Day Delivery represents the operational standard. Same-Day Delivery shows the steepest trajectory as urban density enables micro-fulfillment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics platforms serve transatlantic freight corridors into North American distribution networks, while Indian production-linked incentive schemes attract electronics manufacturing that demands automated warehousing infrastructure.
Germany
Automotive distributors around Stuttgart and chemical handlers along the Rhine-Ruhr corridor drive cloud-native warehouse management procurement. CSRD emissions documentation requirements under the EU Green Deal mandate granular supply chain transparency. Hamburg's port hinterland concentrates transportation management platform deployment for transatlantic lane optimization.
United States
FDA 21 CFR Part 11 electronic record requirements tighten validation protocols for pharmaceutical logistics software serving domestic cold chains. E-commerce fulfillment networks compress delivery windows and accelerate robotics orchestration investments. The Midwest manufacturing belt sustains ERP-integrated logistics platform demand for production schedule synchronization.
India
PLI scheme incentives for electronics manufacturing create greenfield automated warehousing demand in Gujarat and Tamil Nadu industrial corridors. BIS standards for industrial equipment quality intersect with logistics automation procurement specifications. Karnataka's technology clusters incubate domestic logistics software vendors targeting mid-tier manufacturing networks.
Netherlands
Rotterdam-Antwerp port hinterlands concentrate Dutch 3PL operator demand for transportation management systems with embedded emissions tracking. REACH compliance obligations for chemical handling audit trails shape platform selection criteria. Eindhoven's distribution networks exemplify multi-node inventory visibility deployments across European cross-border lanes.
China
Dual carbon goals under MEE oversight reshape route optimization priorities for domestic freight networks. MIIT industrial policy accelerates smart logistics infrastructure investment in Yangtze River Delta manufacturing zones. Shenzhen's electronics export corridors demand real-time inventory systems synchronized with trans-Pacific shipping schedules.
Smart Logistic Market Competitive Landscape
Player mix skews toward enterprise software conglomerates with embedded ERP footprints. Market structure concentrates around three strategic tiers: full-stack platform vendors, specialized robotics orchestrators, and cloud-native point solution providers. Competitive dynamics center on strategic partnerships between automation hardware fabricators and software platform vendors, alongside vertical integration moves into sensor hardware manufacturing.
Within the enterprise software tier, Oracle Corporation and SAP SE anchor platform competition through divergent architectural approaches, while Körber occupies a position exemplifying robotics specialization. These three entities represent distinct competitive vectors: database-centric cloud architectures, ERP-embedded warehouse management, and high-throughput fulfillment automation respectively.
| Leading Market Players |
|---|
| Oracle Corporation |
| IBM Corporation |
| SAP SE |
| Dematic |
| Blue Yonder |
| Manhattan Associates |
| Körber |
| Honeywell International Inc. |
| Cisco Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud-native WMS substitution for on-premise legacy deployments is redrawing supply geography toward hyperscaler data center regions while compressing pricing premiums previously commanded by perpetual-license vendors. This displacement simultaneously fragments hardware supplier power and shifts margin capture toward software layers.
Pricing Analysis
Current-generation cloud-native platforms command subscription premiums against prior-generation on-premise perpetual licenses, while next-generation AI-orchestrated systems are testing value-based pricing. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade ERP-integrated deployments from mid-market SaaS tiers and basic freight-matching utilities. Pricing pressure stems from hyperscaler infrastructure commoditization eroding platform differentiation. Mid-market retailers exhibit highest price sensitivity, while pharmaceutical distributors under EMA traceability mandates show lowest.
Supply Chain Analysis
Strategic stockpiling of lithium-ion cells and sensor hardware is displacing just-in-time procurement as supply volatility reshapes warehouse robotics deployment timelines. Component sourcing draws from China for battery cells, Taiwan for semiconductor telemetry chips, and Germany for precision automation hardware. Concentration risk centers on single-source dependency for high-density energy storage. Distribution runs through systems integrator networks serving regional industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart logistics functions as a defensive-moat market where regulatory entrenchment around EMA and FDA validation protocols creates substantial switching costs for pharmaceutical and food-grade operators.
For Market Incumbents: Consolidate cloud infrastructure partnerships to lock in mid-market subscription bases before hyperscalers develop native logistics modules. Deepen backward integration into sensor hardware manufacturing to offset lithium supply concentration risks. Prioritize CSRD compliance tooling to capture EU Green Deal documentation spend. For New Entrants and Emerging Players: Anchor in India's PLI-funded electronics manufacturing corridors where greenfield warehouse automation lacks incumbent ERP entrenchment. Target Gujarat and Tamil Nadu industrial zones with robotics-orchestration-as-a-service offerings. Lead with rapid-deployment micro-fulfillment configurations bypassing legacy system integration friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed robotics integrators holding EMA-validated cold chain deployments but lacking cloud-native platform scale. Five-to-ten year viability hinges on AI Act compliance documentation capabilities. Watch for carbon border adjustment mechanism implementation triggering route optimization platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Mid-market retailers under CSRD mandates seek subscription economics over capital-intensive on-premise WMS ownership. |
| Robotics Orchestration Specialization | High-throughput fulfillment centers demand engineer-scarce picking algorithm expertise concentrated in German industrial clusters. |
| EMA Validation Investment | Pharmaceutical cold chain operators require documented AI decision pathways under EU Medical Device Regulation traceability rules. |
| Carbon Footprint Integration | EU Green Deal emissions transparency requirements are reshaping carrier selection criteria across Rotterdam-Antwerp port hinterlands. |
| Hyperscaler Partnership Structuring | AWS and Azure infrastructure amortization enables platform vendors to reach capital-constrained French and Italian distribution networks. |
Research Methodology
The analysis maps warehouse management systems, transportation management platforms, and inventory optimization modules, each validated through logistics technology procurement officers, warehouse operations directors, and 3PL contract managers. Primary fieldwork combined with secondary validation from customs trade databases, SEC software vendor filings, EMA regulatory submission logs, and EU emissions disclosure registries. Bottom-up deployment sizing and top-down market aggregation were cross-checked for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, technology tier, end-use vertical, and delivery model commitment windows. CAGRs were derived from algorithmic trend fitting against disclosed platform subscription growth and robotics deployment velocities. Forecast inputs incorporated PLI scheme funding trajectories and EU AI Act implementation timelines.
Decision-makers should treat outputs as directional under sustained e-commerce order volatility and lithium supply concentration assumptions; material deviation would warrant model refresh. Revision becomes warranted when carbon border adjustment mechanism coverage thresholds trigger carrier network restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Traffic Signal Controller Market