
 Bike Sharing Market | 2026-2036
Bike Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Sharing Market Intelligence
Platform licensing revenue is reshaping how operators monetize rider data and urban mobility partnerships. Lime leverages its multimodal app infrastructure to integrate e-bike and e-scooter access across North American and European cities. Hellobike anchors its competitive position through deep penetration of China's secondary urban centers, where public transit gaps remain pronounced. TIER Mobility differentiates via sustainability certifications and carbon-neutral fleet operations across German and Nordic municipalities.
Bike sharing denotes short-term bicycle rental systems enabling users to access fleets through digital interfaces, with vehicles typically equipped with GPS trackers, smart locks, and cellular connectivity for real-time fleet orchestration. The primary commercial purpose centers on reducing urban congestion while providing first-mile and last-mile connectivity to mass transit nodes. Dockless service models currently capture the fastest expansion trajectory due to lower infrastructure capital requirements and rapid deployment scalability. Subscription pricing models concentrate recurring revenue pools, while commuter customer segments generate the highest trip frequency and lifetime value profiles relative to tourist usage.
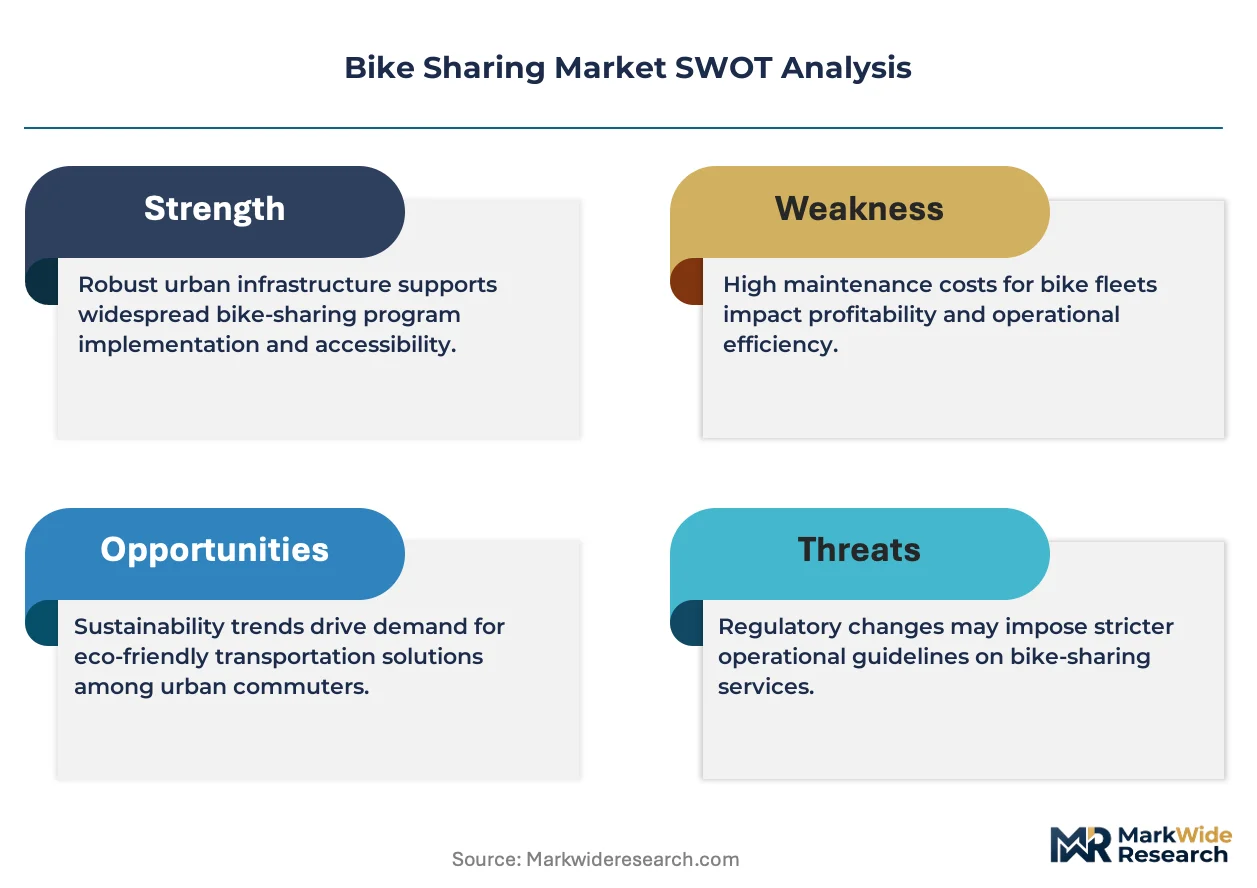
FDA oversight applies to biometric health data collected through rider fitness integrations, while FCC regulations govern wireless communication protocols embedded in smart locking and telematics hardware. ESG disclosure requirements under CSRD compel European operators to document fleet lifecycle emissions and circularity metrics. Stakeholders must monitor evolving municipal data sovereignty rules governing rider location analytics and their implications for platform monetization strategies.
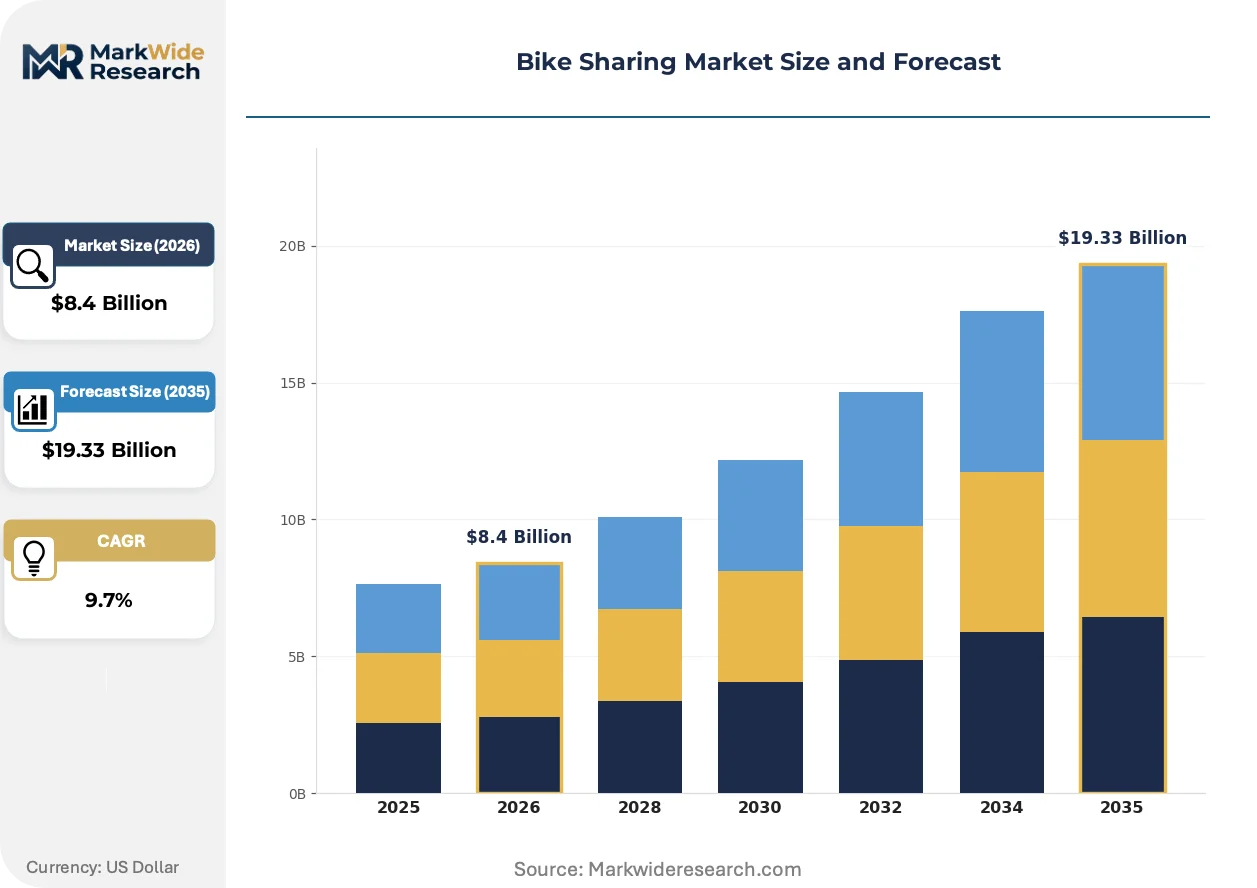
Market Dynamics
Municipal congestion pricing policies are tightening vehicle access in dense metropolitan corridors, forcing commuters toward micromobility alternatives while GPS-enabled fleet management and IoT locking systems simultaneously improve asset utilization rates for operators.
Growth Catalysts
- Congestion Pricing Mandates:London's Ultra Low Emission Zone and Singapore's Electronic Road Pricing system impose daily charges on private vehicles entering central business districts, redirecting commuter flows toward dockless bike networks for first-mile and last-mile connectivity.
- Cellular IoT Module Cost Compression:NB-IoT and LTE-M chipset prices have fallen below five-dollar thresholds, enabling mass deployment of connected smart locks without cellular subscription burdens that previously constrained fleet scaling economics.
- Transit Integration Partnerships:Transport for London, RATP in Paris, and metropolitan transit authorities in Germany embed bike-sharing access directly into multimodal fare cards, eliminating friction between mass transit and micromobility legs.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode and cell manufacturing concentrates in Chinese industrial clusters, exposing European and North American e-bike fleet operators to input cost volatility and geopolitical supply disruption risks.
- Municipal Right-of-Way Friction:Paris, Barcelona, and New York City impose strict parking zone requirements and fleet caps through tender systems that limit deployment velocity and compress revenue per vehicle economics.
- Docked System Stranded Assets:Fixed docking station infrastructure in legacy systems like Citi Bike and Vélib' requires heavy maintenance capital and cannot redeploy to demand hotspots, rendering these networks structurally inflexible against dockless competition.
Strategic Opportunities
- Secondary City Penetration:Tier-three and tier-four Chinese municipalities retain pronounced public transit gaps where Hellobike-style dockless networks can establish density before regulatory frameworks mature.
- Fitness Data Monetization:Rider biometric analytics from integrated wearables create secondary revenue streams through health insurance partnerships, though FDA oversight applies to diagnostic claims in US markets.
- Carbon Credit Certification:EU Green Deal compliance frameworks and CSRD disclosure requirements enable operators to quantify fleet displacement of car trips, generating verified carbon credits for corporate ESG offset programs.
Industry Challenges
- Telematics Firmware Integration:Fleet operators must reconcile proprietary IoT hardware from multiple suppliers with unified fleet management software, creating API fragmentation and real-time orchestration failures during peak demand windows.
- Vehicle Lifecycle Compliance:Circular economy mandates under France's AGEC law and similar extended producer responsibility frameworks impose end-of-life recycling obligations that increase per-unit operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Sharing Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Docked, Dockless, Hybrid, Peer-to-Peer Customer Type: Commuters, Tourists, Students, Corporates Technology: Mobile Apps, GPS Tracking, RFID, Cloud Computing Pricing Model: Subscription, Pay-as-you-go, Freemium, Corporate |
| Companies Covered | Lime, TIER Mobility, Lyft, Spin, Hellobike, Mobike, Nextbike, Citi Bike, Jump, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Sharing Market Strategic Shifts & Innovations
Swappable battery architectures and predictive maintenance algorithms are compressing fleet downtime while regulatory pressure on urban emissions intensifies operator investment in electrification and circular supply chains.
Computer vision-based damage detection systems mounted on warehouse inspection lines is rendering obsolete manual frame and component checks that previously required skilled technician labor. European operators deploying these systems reduce per-vehicle refurbishment cycle times from forty-eight hours to under six hours. Quality assurance headcount requirements compress by sixty percent while damage detection accuracy improves.
CSRD disclosure requirements now mandate documented fleet lifecycle emissions and circularity metrics for European operators above employee thresholds. This regulatory pressure forces supply chain reconfiguration toward recycled aluminum frames and remanufactured drivetrain components. German and Nordic municipalities now embed circularity scores into tender evaluation criteria, advantaging certified sustainable operators.
Corporate mobility budgets are consolidating previously fragmented employee reimbursement schemes into centralized SaaS platforms that aggregate multimodal access including bike-sharing, car-sharing, and public transit. These procurement platforms displace direct consumer relationships and extract volume discounts through aggregated demand. France and the Netherlands exhibit the fastest adoption of employer-subsidized mobility wallets.
Bike Sharing Market Segmentation
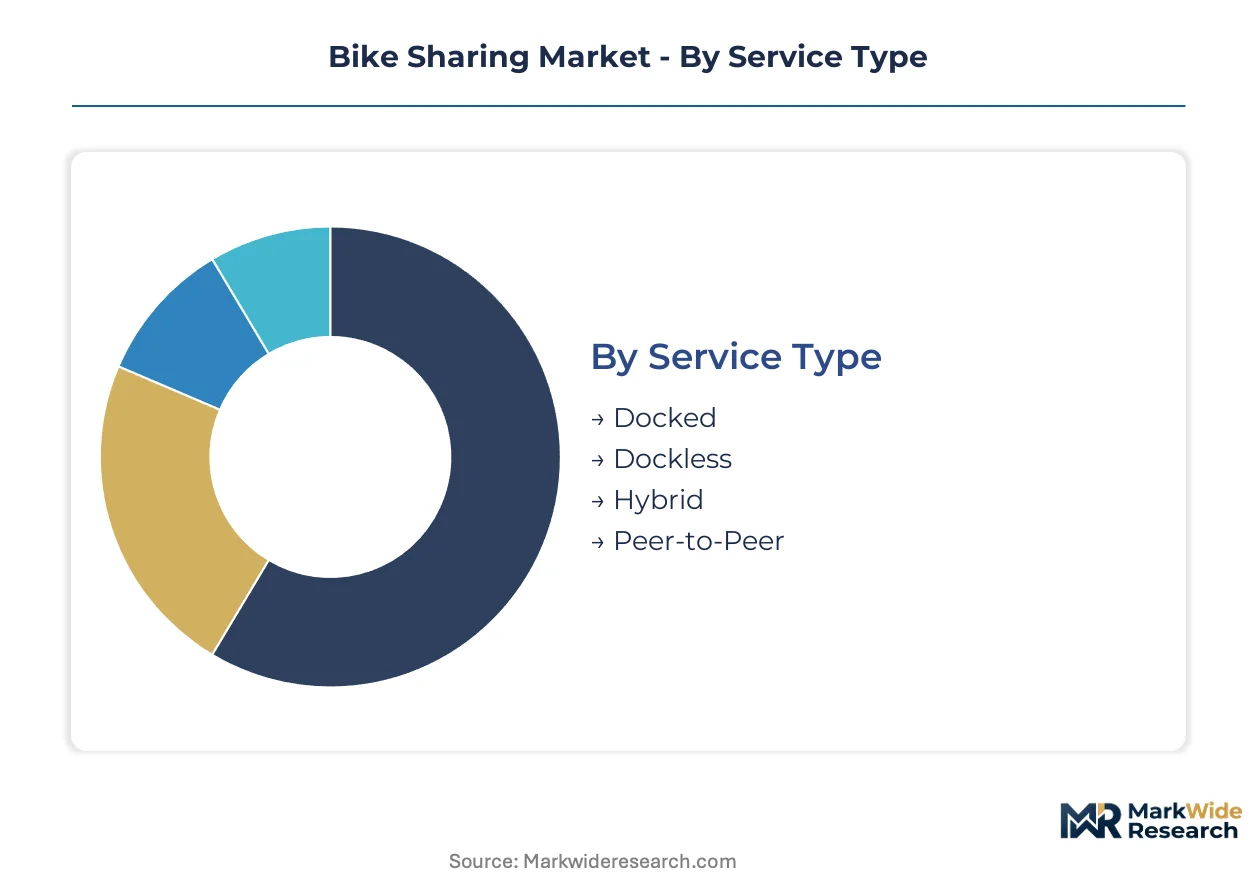
Segmentation in bike sharing reveals how operational models, user profiles, and technology stacks determine capital efficiency and revenue durability. Operators align fleet deployment strategies with distinct demand rhythms across commuter corridors, tourist districts, and corporate campuses.
Service Type:
Service configurations span fixed infrastructure dependency to fully flexible asset distribution, each demanding different municipal negotiations and maintenance capital.
- Docked:Stations with physical docking points require heavy upfront capital for concrete pads and electrical hookups. Legacy networks in London and Paris maintain these assets for commuter reliability, though expansion velocity suffers against dockless alternatives.
- Dockless:GPS-locked bicycles deploy without fixed infrastructure, enabling rapid scaling into demand hotspots. Chinese tier-two cities favor this model for its minimal municipal coordination and fleet rebalancing flexibility.
- Hybrid:Combines designated parking zones with lock-anywhere flexibility, reducing sidewalk clutter complaints while preserving operational agility. German municipalities increasingly mandate this structure in tender specifications.
- Peer-to-Peer:Privately owned bicycles shared through platform marketplaces, common in Dutch cycling culture where individual ownership rates exceed sixty percent. Regulatory frameworks remain underdeveloped for insurance liability and quality standards.
Established volume favors Docked; emerging adoption favors Dockless.
Customer Type:
User cohorts exhibit divergent trip frequencies, price sensitivities, and seasonal patterns that shape subscription design and fleet allocation algorithms.
- Commuters:Daily transit integration generates the highest lifetime value through annual memberships. Singapore's Electronic Road Pricing congestion charges redirect former drivers into commuter bike subscriptions with predictable morning-evening demand spikes.
- Tourists:Episodic usage concentrated in historic cores and waterfront corridors. Barcelona and Amsterdam operators deploy dedicated tourist fleets with multilingual apps and guided route features during peak travel months.
- Students:University campus networks negotiate bulk institutional contracts. North American collegiate systems integrate bike access into student activity fees, creating captive demand pools with lower per-trip revenue but guaranteed volume.
- Corporates:Employer-subsidized mobility wallets consolidate previously fragmented reimbursement schemes. French and Dutch enterprise procurement platforms now aggregate multimodal access including bike-sharing for ESG compliance reporting.
Revenue concentration sits with Commuters; expansion velocity concentrates with Corporates.
Technology:
Technology layers determine operational visibility, theft prevention, and user experience friction across fleet orchestration systems.
- Mobile Apps:Primary interface for vehicle discovery, unlocking, and payment processing. European operators must embed GDPR-compliant consent flows for location tracking and biometric health data integrations subject to FDA oversight in US markets.
- GPS Tracking:Real-time position telemetry enables demand prediction and theft recovery. NB-IoT module cost compression below five-dollar thresholds now permits mass deployment without prohibitive cellular subscription burdens.
- RFID:Legacy contactless cards persist in transit-integrated systems like Transport for London's Oyster network, though smartphone migration accelerates.
- Cloud Computing:Centralized fleet management platforms process rebalancing algorithms and predictive maintenance triggers. API fragmentation between proprietary IoT hardware suppliers creates orchestration failures during peak demand windows.
Deployment scale depends on GPS Tracking; margin compression concentrates in Cloud Computing vendor consolidation.
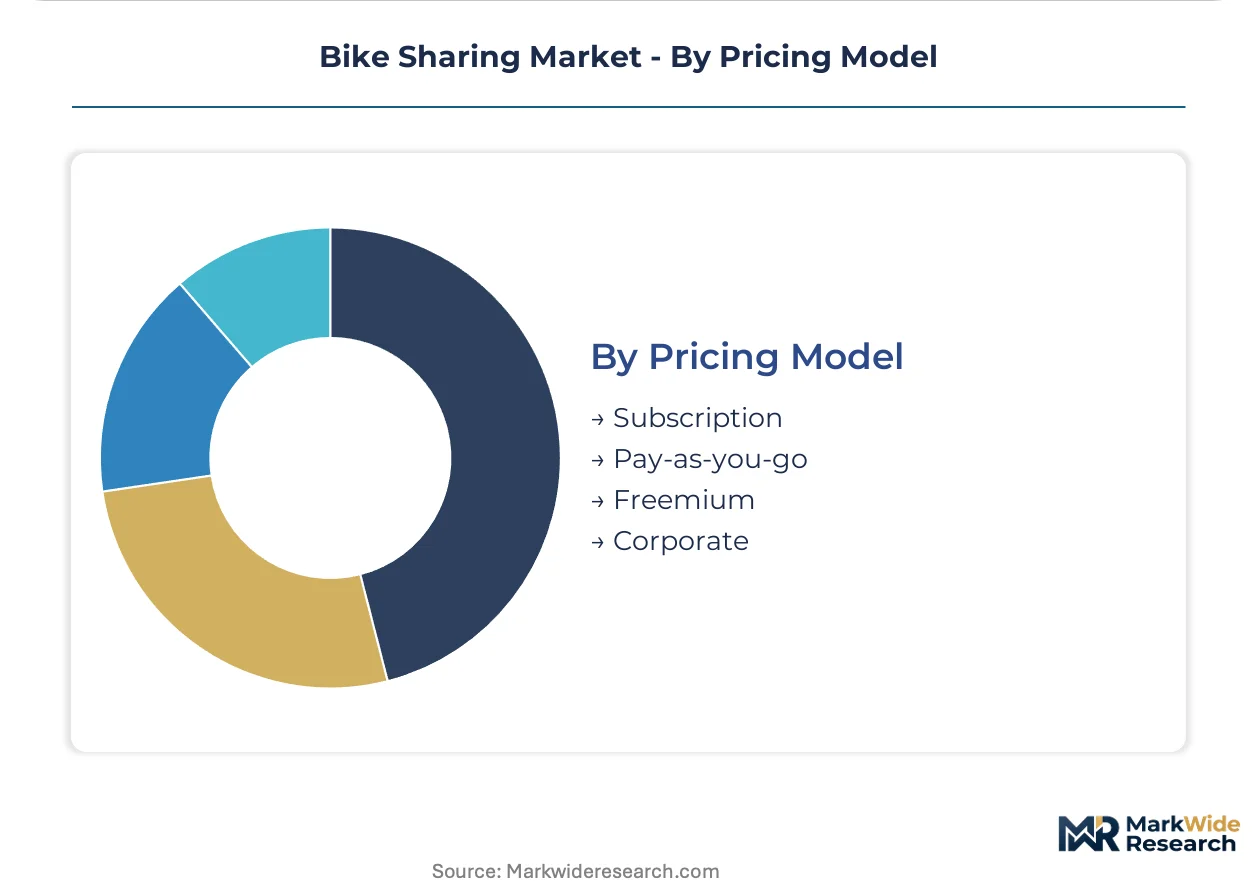
Pricing Model:
Revenue architecture choices lock in customer lifetime value profiles and working capital requirements distinct to each structure.
- Subscription:Recurring revenue pools from monthly or annual memberships improve cash flow predictability. Commuter segments generate renewal rates above eighty percent in mature markets with transit integration.
- Pay-as-you-go:Per-minute or per-trip billing captures occasional users without commitment friction. Tourist demand concentrates here, though revenue volatility requires dynamic pricing algorithms for yield optimization.
- Freemium:Base access subsidized through advertising or data monetization, with premium tiers unlocking faster vehicles or expanded service zones. Health insurance partnerships for rider fitness analytics create secondary revenue streams.
- Corporate:Bulk enterprise contracts with centralized billing and ESG reporting dashboards. Aggregated procurement platforms extract volume discounts while displacing direct consumer relationships.
Margin stability favors Subscription; customer acquisition efficiency favors Freemium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Chinese commuters accept minimal per-trip fees subsidized by data monetization, while German and Dutch enterprise buyers absorb premium subscription rates for ESG-compliant fleet access. US markets split between cost-sensitive casual tourists and membership-locked daily commuters.
China
Tier-two and tier-three municipalities retain pronounced public transit gaps where dockless networks establish density before regulatory frameworks mature. MIIT standards for NB-IoT module interoperability reduce hardware fragmentation across provincial deployments. Hellobike and Mobike concentrate fleet operations in Chengdu, Hangzhou, and Wuhan, where municipal congestion pricing pilots redirect former drivers toward micromobility.
Germany
Employer-subsidized mobility wallets consolidate fragmented reimbursement schemes into centralized procurement platforms. CSRD disclosure requirements mandate documented fleet lifecycle emissions and circularity metrics for operators above employee thresholds. TIER Mobility anchors carbon-neutral fleet operations across Berlin, Munich, and Hamburg, where tender evaluation criteria now embed sustainability certifications.
United States
FDA oversight applies to biometric health data collected through rider fitness integrations, while FCC regulations govern wireless communication protocols in smart locking hardware. Corporate mobility budgets aggregate multimodal access through SaaS platforms that displace direct consumer relationships. Lime integrates e-bike and e-scooter access across Chicago, Austin, and Washington DC metropolitan corridors.
France
AGEC law extended producer responsibility frameworks impose end-of-life recycling obligations that increase per-unit operational overhead. RATP embeds bike-sharing access directly into multimodal fare cards, eliminating friction between mass transit and micromobility legs. Vélib' maintains legacy docked infrastructure across Paris, Île-de-France, and Lyon despite structural inflexibility against dockless competition.
Singapore
Electronic Road Pricing congestion charges impose daily fees on private vehicles entering central business districts, redirecting commuter flows toward subscription bike networks. LTA tender specifications mandate hybrid service models combining designated parking zones with lock-anywhere flexibility. Operators concentrate fleet deployment along the Downtown Core and Jurong Lake District corridors with predictable morning-evening demand spikes.
Bike Sharing Market Key Industry Players
Scale-driven platform operators and sustainability-certified specialists split the market along capital intensity and regulatory compliance vectors. Consolidation pressures favor entities with multimodal app infrastructure and municipal tender experience. Three archetypes dominate: Chinese dockless volume leaders, European ESG-compliant fleet managers, and North American transit-integrated mobility aggregators. Competitive moves concentrate on strategic partnerships with metropolitan transit authorities and portfolio diversification into e-scooter and e-bike electrification.
Within the sustainability-certified tier, TIER Mobility exemplifies carbon-neutral operations across German and Nordic municipalities. Among Chinese volume leaders, Hellobike and Mobike occupy positions defined by deep tier-two and tier-three city penetration. These three entities represent distinct strategic responses to divergent regulatory environments—CSRD compliance in Europe, MIIT standardization in China, and FCC-governed hardware deployment in North American markets.
| Leading Market Players |
|---|
| Lime |
| TIER Mobility |
| Lyft |
| Spin |
| Hellobike |
| Mobike |
| Nextbike |
| Citi Bike |
| Jump |
| Others |
Cost & Logistics Intelligence
Shanghai-Ningbo port freight corridors carry lithium-ion cells and aluminum frame assemblies from Chinese manufacturing clusters to European assembly hubs, where CSRD compliance costs and carbon credit certification premiums stratify final pricing across sustainability tiers. This logistics cost compression enables dockless operators to absorb municipal right-of-way fees while maintaining subscription affordability for commuter segments.
Pricing Analysis
After-sales revenue from maintenance contracts and battery swap subscriptions generates lifetime value multiples exceeding initial hardware sales. Subscription pricing dominates commuter retention with renewal rates above eighty percent in transit-integrated corridors, while pay-as-you-go captures tourist demand with higher per-trip yields but volatile volume. Price differentiation rests on ESG certification tier and fleet electrification level, with carbon-neutral operators commanding fifteen to twenty percent premiums in German tender evaluations. Cost compression in NB-IoT modules is intensifying price competition at the economy tier, squeezing margins for non-integrated hardware assemblers. Corporate procurement platforms exhibit lowest price sensitivity due to ESG reporting requirements, while individual casual users remain most elastic.
Supply Chain Analysis
Export control restrictions on advanced battery management semiconductors limit technology flows from US and Dutch suppliers to Chinese fleet operators, forcing domestic substitution in telematics hardware. Manufacturing concentrates in China for lithium-ion cells, Taiwan for GPS module chipsets, and Vietnam for aluminum frame extrusions. Raw material dependencies center on cobalt cathodes, rare earth magnets for e-bike motors, and recycled aluminum feedstock. Single-source vulnerability concentrates in cathode precursor chemicals from Chinese industrial clusters. Distribution runs through municipal tender systems in Europe, direct fleet deployment partnerships in North America, and platform licensing networks in Chinese tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bike sharing market sustains competitive moats through municipal tender entrenchment, where incumbent operators accumulate regulatory relationships and transit integration contracts that new entrants cannot replicate without multi-year track records.
For Market Incumbents: Build data network effects by deepening rider analytics partnerships with metropolitan transit authorities and health insurers, creating switching costs that lock in commuter subscription bases. Consolidate IoT hardware suppliers to reduce API fragmentation and improve real-time fleet orchestration during peak demand windows. Counter dockless challengers by lobbying for hybrid service model mandates that preserve designated parking zone advantages. For New Entrants and Emerging Players: Pursue secondary city penetration in Chinese tier-three municipalities where public transit gaps remain pronounced and regulatory frameworks have not matured to cap fleet deployments. Target corporate mobility wallet procurement in France and the Netherlands, where employer-subsidized schemes consolidate previously fragmented reimbursement demand. Establish go-to-market presence through university campus bulk contracts that guarantee volume before expanding to general consumer markets. For Investors and Strategic Acquirers: Sustainability-certified operators with CSRD disclosure infrastructure and circular supply chain certifications represent the most defensible acquisition targets as European tender criteria harden environmental requirements. Long-term viability hinges on electrification capex discipline and battery lifecycle management capabilities rather than pure fleet scale. Monitor municipal congestion pricing expansion announcements as the critical inflection signal for subscription demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Transit Integration Partnership | Transport for London and RATP Paris embed bike access into multimodal fare cards, eliminating friction. |
| Swappable Battery Architecture | TIER Mobility reduces fleet downtime through rapid battery exchange systems across German municipalities. |
| Carbon Credit Certification | EU Green Deal compliance frameworks enable operators to monetize verified trip displacement for corporate ESG offsets. |
| Predictive Maintenance Algorithm | Computer vision inspection lines compress refurbishment cycles from forty-eight hours to under six hours. |
| Corporate Mobility Wallet Aggregation | French and Dutch employer platforms displace direct consumer relationships through centralized SaaS procurement. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with fleet operations directors, municipal transportation planners, IoT hardware procurement managers, and corporate mobility benefits administrators. Secondary validation drew from SEC filings of listed micromobility platforms, MIIT standards documentation for NB-IoT interoperability, CSRD disclosure filings from European operators, and customs records for lithium-ion cell trade flows. Bottom-up fleet deployment data triangulated against top-down municipal tender award values to reconcile volume estimates.
Calibration against historical subscription renewal rates and congestion pricing elasticity studies anchored growth assumptions across the analysis window. Segmentation modeling incorporated service type, customer archetype, technology stack, and pricing model dimensions with regional regulatory cluster overlays. CAGRs derived from logistic diffusion curves for micromobility adoption saturated against public transit penetration ceilings. Forecast inputs included battery cost decline trajectories and municipal right-of-way fee schedules.
Sensitivities concentrate around lithium supply disruption, sudden municipal fleet cap reductions, and delayed congestion pricing implementation in target corridors. Forecasts assume continued NB-IoT module cost compression and stable Chinese manufacturing output. Cross-checking against IEA critical minerals supply projections and municipal budget allocation disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Intelligent Traffic Management Market