
 Europe Cross Border Road Freight Transport Market | 2026-2036
Europe Cross Border Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cross Border Road Freight Transport Market Foresight
Polish and Baltic fleet operators is hardening capacity on east-west corridors into Germany and the Netherlands. DB Schenker leverages its integrated rail-road network to secure fixed schedules across the Rhine-Alpine corridor. DSV A/S sustains density advantages through its European hub-and-spoke model, while Girteka anchors long-haul capacity with one of Europe's largest truck fleets.
Europe cross border road freight transport involves the movement of goods by heavy commercial vehicles across national boundaries, typically using tractor-trailers with maximum gross weights of 40-44 tonnes under EU standardization. The sector functions as the backbone of continental supply chains, enabling just-in-time delivery for manufacturing and distribution networks. Full Truck Load services dominate volume flows on major corridors, while Less Than Truck Load offerings capture margin pools through consolidation efficiency in fragmented shipper bases. Refrigerated trucks command premium positioning within the vehicle type mix, driven by temperature-sensitive pharmaceutical and fresh food movements.
The EU Mobility Package, enforced by the European Commission and member state transport ministries, reshapes driver posting rules and cabotage limits, directly altering fleet deployment economics and cross-border hiring practices. REACH and EU Green Deal emissions standards, administered by ECHA and national environment agencies, are accelerating fleet renewal toward alternative powertrains and low-carbon logistics contracts. Stakeholders must weigh compliance investment against route restructuring as regulatory stringency tightens operating models.
Market Dynamics
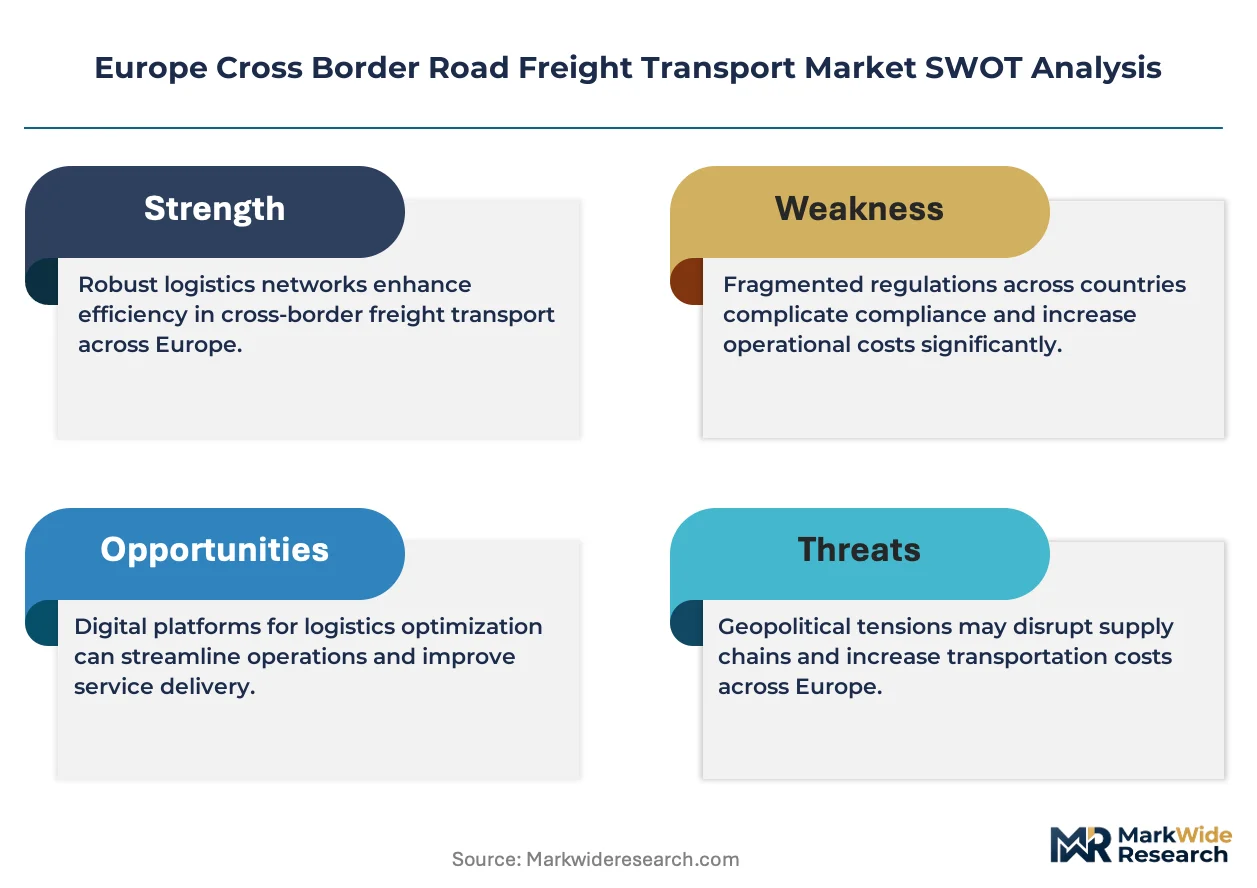
The EU Mobility Package is compressing driver availability and forcing fleet operators toward asset-light subcontracting models across east-west corridors. Compliance costs are restructuring competitive economics between integrated networks and spot-market hauliers.
Growth Catalysts
- E-commerce fulfillment density:Parcel consolidation hubs in Poland and the Netherlands are generating backhaul efficiencies for Full Truck Load operators serving omnichannel distribution networks.
- EU Green Deal incentives:Carbon border adjustments and low-emission zone mandates are accelerating biodiesel and electric tractor adoption on Rhine-Alpine and North Sea-Baltic corridors.
- REACH chemical compliance:Standardized hazardous goods documentation is reducing cross-border inspection delays for pharmaceutical and specialty chemical shippers.
Market Restraints
- Diesel price volatility:Fuel represents 28-35% of operating costs for long-haul operators, with Baltic and Balkan fleets exposed to refining capacity concentration in northwest Europe.
- Driver shortage concentration:Germany and Benelux face acute qualified driver deficits, constraining capacity expansion on the highest-volume corridors regardless of equipment availability.
- Cabotage restriction rigidity:EU Mobility Package return-home requirements limit productive utilization of international fleets on triangular routes through Central Europe.
Strategic Opportunities
- Romania-Bulgaria corridor development:Underpenetrated south-east European routes offer first-mover advantages as manufacturing investment shifts toward lower-cost EU peripheries.
- Pharmaceutical cold chain expansion:Temperature-controlled GDP compliance creates premium service tiers for biologics distribution between Ireland, Belgium, and Germany.
- Digital freight platform convergence:Real-time load matching algorithms combined with predictive ETAs are enabling dynamic pricing models previously restricted to container shipping.
Industry Challenges
- Tachograph compliance complexity:Smart tachograph 2 mandates require telematics retrofitting across aging fleet segments, straining SME operator balance sheets.
- Cross-border enforcement fragmentation:Divergent national interpretations of driver posting rules create operational uncertainty for multi-country dispatch operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cross Border Road Freight Transport Market |
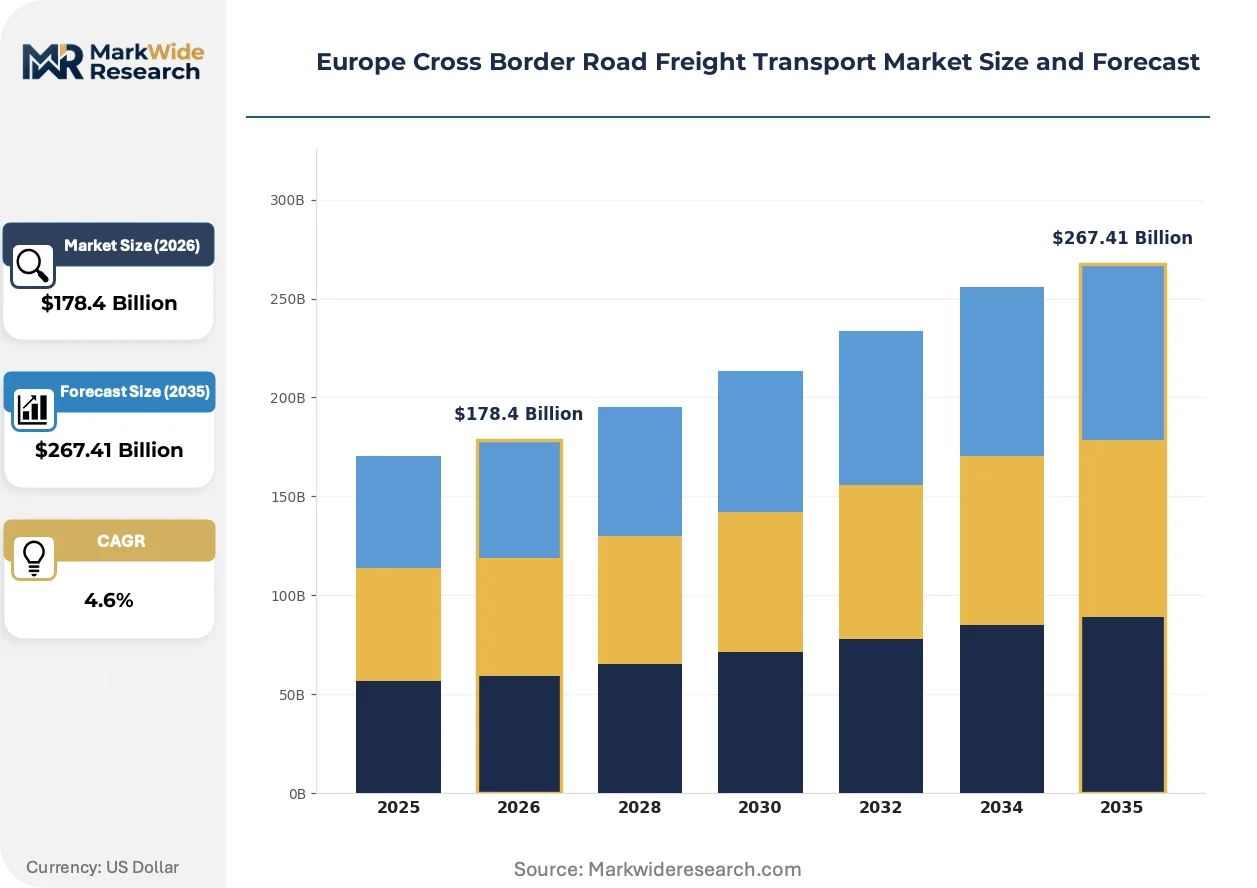
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $267.41 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Expedited Freight, Intermodal Transport End User: Retail, Manufacturing, Automotive, E-Commerce Vehicle Type: Container Trucks, Refrigerated Trucks, Flatbed Trucks, Drones Delivery Model: Direct Delivery, Scheduled Delivery, On-Demand Delivery, Consolidated Delivery |
| Companies Covered | Dachser, XPO Inc, DB Schenker, Girteka, Kuehne + Nagel, DHL Group, Rhenus Group, Nippon Express Holdings, DSV A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cross Border Road Freight Transport Market Shifts & Advancements
Telematics and alternative powertrain development are compressing planning horizons and reshaping asset replacement cycles. Fleet operators face simultaneous pressure to digitize operations and decarbonize equipment without disrupting just-in-time service levels.
Platooning technology is integrating vehicle-to-vehicle communication protocols that enable coordinated braking and acceleration across convoyed tractor-trailers. Major automotive suppliers and logistics operators are piloting systems on Dutch and German motorway segments. This coordination is integrating aerodynamic efficiency gains of 7-10% into fleet operating models previously dependent on single-vehicle optimization.
REACH chemical safety standards are mandating enhanced dangerous goods tracking and emergency response documentation for cross-border movements. The European Chemicals Agency enforcement framework now requires real-time incident reporting capabilities from transport operators. Pharmaceutical and industrial chemical shippers are most affected, with German and Belgian logistics providers accelerating compliance investments ahead of 2025 audit cycles.
Shipper procurement patterns are compressing contract durations from annual to quarterly frameworks with embedded performance metrics. Large retail and automotive manufacturers are unbundling lane-specific awards from network-wide commitments, fragmenting volume concentration among mid-sized regional carriers. This behavioral shift is most visible in the Germany-Poland corridor, where spot market exposure now exceeds contracted coverage for non-refrigerated general cargo.
Europe Cross Border Road Freight Transport Market Segmentation
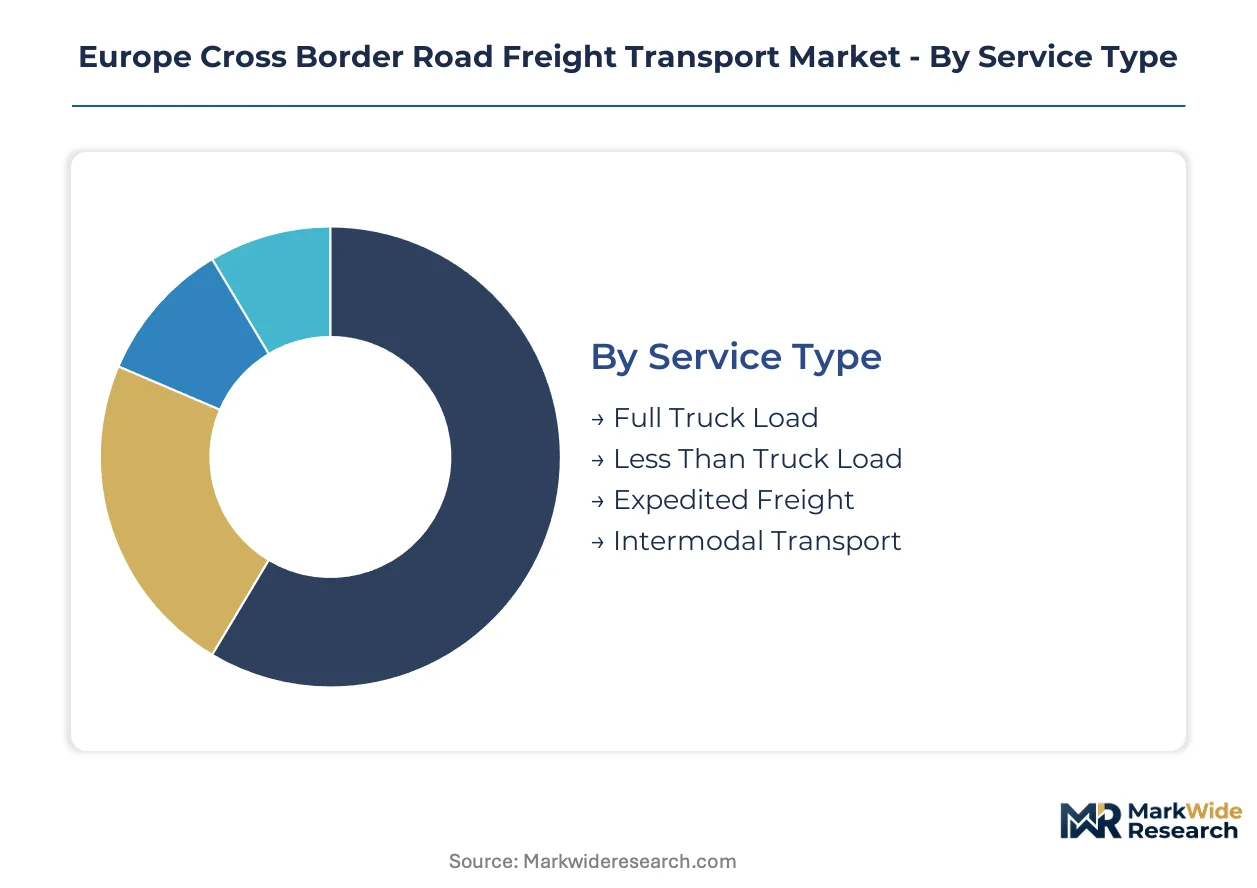
Service differentiation in European cross-border road freight determines equipment utilization rates and margin capture across corridor-specific demand patterns. Segment boundaries reflect capital deployment intensity, regulatory compliance scope, and shipper procurement sophistication rather than simple volume splits.
Service Type:
Capital intensity varies sharply across service tiers, with dedicated fleet commitments and trailer pooling networks demanding the heaviest upfront investment.
- Full Truck Load:Dedicated tractor-trailer pairings move single-shipper cargo from origin to destination without intermediate handling. Manufacturing supply chains between Germany and Poland absorb the majority of contracted FTL capacity, with just-in-time automotive sequences requiring guaranteed transit windows.
- Less Than Truck Load:Consolidation hubs aggregate multiple shipper consignments into optimized trailer loads, capturing margin through density management. Benelux distribution networks generate the densest LTL flows, though EU Mobility Package cabotage limits constrain triangular routing efficiency for international operators.
- Expedited Freight:Time-critical movements bypass standard hub schedules through direct driver relays or air-road interlining. Pharmaceutical and aerospace shippers in the Rhine-Alpine corridor sustain premium rate structures.
- Intermodal Transport:Rail-road combinations shift long-haul mileage onto electrified corridors, with terminal handling equipment representing fixed-cost concentration. North Sea-Baltic routes show strongest adoption as diesel cost volatility persists.
Full Truck Load absorbs the bulk of installed capacity; Intermodal Transport is expanding most quickly as ETS carbon pricing reshapes corridor economics.
End User:
Procurement sophistication divides end-user segments, with consolidated retail buying power pressing rate compression against fragmented manufacturing demand.
- Retail:Omnichannel distribution networks require synchronized inbound replenishment and outbound store delivery, often through shared-user warehouse platforms. German and Dutch retail consolidation hubs generate predictable backhaul opportunities for contracted carriers.
- Manufacturing:Component sequencing for assembly plants demands strict arrival windows and real-time visibility, with penalties for deviation. Polish and Czech automotive supplier parks concentrate manufacturing-linked freight volumes.
- Automotive:Finished vehicle logistics and production parts movements operate under OEM-directed routing guides with embedded compliance requirements. Just-in-sequence deliveries from Spain and Italy to German assembly plants sustain dedicated fleet commitments.
- E-Commerce:Parcel-level final-mile injection into national postal networks requires late-cutoff collection windows and high-frequency linehaul departures. Baltic states and southeastern Europe show steepest volume expansion as fulfillment density builds.
Manufacturing commands the densest lane concentration; E-Commerce is gaining share fastest as fulfillment node placement shifts toward consumption centers.
Vehicle Type:
Asset specialization intensity separates vehicle categories, with temperature-controlled and hazardous-capable equipment carrying the steepest depreciation schedules.
- Container Trucks:Standardized curtain-sided or box trailers dominate general cargo movements, with swap-body interoperability enabling rail terminal efficiency. Intermodal adoption in the Alpine region drives container-compatible fleet renewal.
- Refrigerated Trucks:Engine-powered or cryogenic cooling systems maintain pharmaceutical GDP compliance or fresh food cold chains, with dual-temperature compartments adding flexibility. Belgian and Irish pharmaceutical exports sustain premium positioning.
- Flatbed Trucks:Open-deck configurations accommodate out-of-gauge industrial machinery and construction materials, with specialized securing equipment representing auxiliary capital outlay. German machinery exports to Central Europe anchor demand.
- Drones:Unmanned aerial systems for last-mile delivery remain experimental, with regulatory frameworks under development at EASA and national aviation authorities. Alpine valley communities and island territories represent prospective deployment zones.
Container Trucks carry the majority of fleet book value; Refrigerated Trucks are climbing the fastest as biologics distribution expands.
Delivery Model:
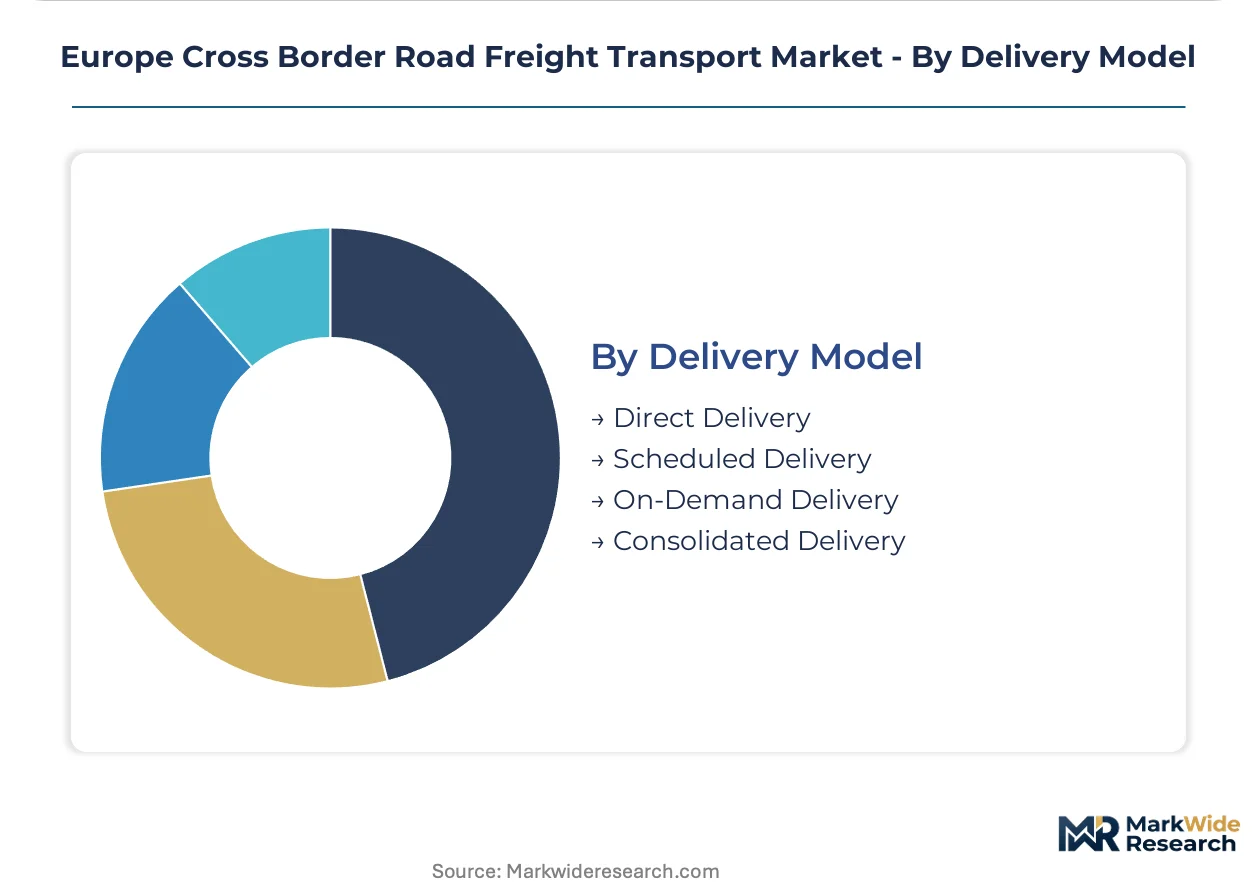
Scheduling predictability versus responsiveness defines delivery model economics, with fixed-route density competing against dynamic dispatch premiums.
- Direct Delivery:Point-to-point movements without intermediate handling minimize transit time and damage risk for high-value or time-critical cargo. Pharmaceutical and aerospace shippers in the Germany-Benelux corridor specify direct routing.
- Scheduled Delivery:Recurring departure windows enable shipper inventory planning and carrier equipment utilization optimization. Manufacturing supply chains with stable demand patterns favor scheduled frameworks.
- On-Demand Delivery:Real-time dispatch responds to unplanned demand spikes, with spot-market pricing reflecting immediate capacity scarcity. Spare parts and maintenance-repair-operations logistics generate on-demand volumes.
- Consolidated Delivery:Multi-shipper aggregation through cross-dock facilities achieves density on lower-volume lanes, extending service reach to fragmented demand bases. Regional distributors in peripheral EU markets rely on consolidation hubs.
Scheduled Delivery accounts for the largest contracted volume base; On-Demand Delivery is expanding most quickly as digital freight platforms compress booking friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diesel refining capacity in Rotterdam and Antwerp anchors northwest Europe's fuel supply chains, while Polish manufacturing clusters and Baltic port infrastructure shape east-west freight corridors across the continent.
Germany
Automotive component sequencing and chemical distribution sustain dense freight volumes on Rhine-Alpine and north-south axes. The KBA enforces EU Mobility Package driver rest mandates through roadside enforcement and digital tachograph audits. The Stuttgart supplier park and Munich logistics corridor concentrate just-in-time manufacturing flows requiring guaranteed transit windows.
Poland
E-commerce fulfillment center expansion and contract manufacturing relocation generate backhaul demand into German and Benelux distribution networks. National transport ministry alignment with EU posting rules affects driver hiring economics for international fleet operators. The Łódź logistics hub and Silesian manufacturing belt anchor capacity concentration for east-west corridor services.
Netherlands
Rotterdam port hinterland distribution and perishables re-export sustain refrigerated and containerized road movements. ECHA REACH compliance documentation requirements shape hazardous goods handling protocols for chemical shippers. The Venlo logistics cluster and Amsterdam-Schiphol cargo zone concentrate pharmaceutical and high-value freight flows.
Belgium
Pharmaceutical GDP-certified distribution and EU institutional supply chains sustain premium temperature-controlled services. Federal mobility authority enforcement of EU cabotage limits constrains triangular routing efficiency for international operators. The Antwerp port periphery and Brussels pharmaceutical corridor anchor biologics and chemical freight specialization.
Spain
Automotive finished vehicle logistics and fresh produce export seasons generate south-north corridor demand into France and Germany. National transport ministry implementation of EU Green Deal low-emission zone mandates accelerates fleet renewal timelines. The Barcelona logistics zone and Madrid distribution hub concentrate manufacturing-linked and perishables freight flows.
Europe Cross Border Road Freight Transport Market Competitive Landscape
Global majors compete with regional champions across network density and corridor specialization. The market structures around integrated multimodal networks, asset-heavy fleet operators, and digital freight platforms. Three archetypes dominate: pan-European integrated logistics providers, corridor-specialized trucking fleets, and technology-enabled freight brokers. Consolidation through acquisition and organic corridor capacity expansion represent the primary competitive vectors reshaping market share distribution.
Within the integrated network tier, DB Schenker, DSV A/S, and Girteka occupy positions exemplifying contrasting scale and specialization strategies. The German-based integrated provider anchors multimodal service architectures across continental corridors. The Danish logistics group represents hub-and-spoke density optimization across Nordic and central European markets. The Lithuanian fleet operator exemplifies asset-heavy long-haul capacity concentration on east-west axes.
| Leading Market Players |
|---|
| Dachser |
| XPO Inc |
| DB Schenker |
| Girteka |
| Kuehne + Nagel |
| DHL Group |
| Rhenus Group |
| Nippon Express Holdings |
| DSV A/S |
| Others |
Supply & Pricing Matrix
Alternative powertrain adoption across German and Dutch motorway networks is compressing total-cost-of-ownership differentials between diesel and electric tractor fleets while redistributing pricing power toward operators with charging infrastructure access. This transition is tightening margin structures for asset-heavy hauliers locked into legacy equipment cycles.
Pricing Analysis
Warranty and maintenance bundling separates premium fleet operators from spot-market hauliers competing on unbundled transactional rates. Three-tier pricing structure across premium, standard, and economy levels reflects GDP certification tiers for pharmaceutical cargo and real-time tracking capabilities. Cost compression in the standard tier is intensifying because digital freight platforms are disintermediating traditional broker margins. E-commerce shippers exhibit the highest price sensitivity due to thin fulfillment economics, while pharmaceutical manufacturers accept premium positioning for temperature-validated services.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale manufacturing demand through dedicated fleet commitments on Germany-Poland corridors, while fragmented retail distribution feeds through consolidation hubs. Manufacturing concentration centers on Germany, Poland, and the Netherlands for automotive components and chemical feedstocks. Fleet operators draw from diesel refining capacity in Rotterdam and Antwerp, electric drivetrain imports from China, and telematics hardware from Taiwan. Single-source vulnerability in battery cell supply creates exposure for electric fleet conversion timelines. Distribution runs through port-centric hinterland networks radiating from Rotterdam, Hamburg, and Gdansk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe cross border road freight transport market sits in a technology-transition phase as battery-electric and hydrogen fuel cell tractors displace diesel-powered legacy fleets across EU Green Deal compliance timelines.
For Market Incumbents: Cement corridor dominance through backward integration into charging infrastructure along Rhine-Alpine routes, insulating against digital freight platform disintermediation. Acquire mid-sized Polish and Baltic fleet operators to consolidate east-west capacity before EU Mobility Package cabotage restrictions harden competitive moats. For New Entrants and Emerging Players: Digital freight broker partnerships offer the fastest path to volume aggregation without asset-heavy fleet commitments. Underpenetrated Romania-Bulgaria manufacturing corridors present white-space expansion opportunities as EU periphery investment accelerates. Target pharmaceutical cold chain compliance as a premium service tier with GDP certification investment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated logistics providers seeking corridor density. Long-term viability favors asset-light technology platforms and specialized temperature-controlled operators over generic dry freight hauliers. Watch EU ETS carbon price trajectories as the inflection signal for electric fleet conversion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Battery-electric tractor deployment aligns with EU Green Deal low-emission zone mandates in German cities. |
| Corridor-Specific Acquisition | Polish and Baltic fleet purchases secure east-west capacity density ahead of regulatory tightening. |
| Digital Platform Integration | Real-time load matching algorithms compress booking friction for fragmented shipper demand bases. |
| Pharmaceutical GDP Certification | Temperature-validated compliance unlocks premium biologics distribution between Belgium and Ireland. |
| Charging Infrastructure Partnership | Motorway charging networks address range anxiety for electric long-haul operations across the Netherlands. |
Research Methodology
Independent corroboration across fleet operator interviews, shipper procurement surveys, and regulatory filing analysis underwrites the qualitative findings. Primary fieldwork engaged dispatch managers at integrated logistics providers, transport ministry officials in Germany and Poland, and pharmaceutical supply chain directors. Secondary validation drew from EU Mobility Package implementation reports, ECHA REACH compliance documentation, KBA enforcement statistics, and customs trade flow databases. Bottom-up corridor volume estimates triangulate against top-down EU freight transport statistics.
Comparable-period anchoring to historical diesel price volatility and EU regulatory implementation phases shaped the forecast window construction. The analytical framework models service type, vehicle powertrain, end-use industry, and corridor-specific demand density across the projection horizon. CAGRs derive from equipment replacement cycle analysis and carbon pricing elasticity assumptions. Forecast inputs include EU ETS price trajectories and battery cost decline curves for electric tractor adoption.
Caveats apply where EU Mobility Package enforcement divergence or diesel refining capacity disruptions could materially shift the outlook. Forecasts reflect assumptions around regulatory implementation timelines and technology cost parity without guarantee of realization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
Italy Road Freight Transport Market
Transportation & Logistics
Hungary Road Freight Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
ASEAN Inland Waterway Freight Transport Market
Transportation & Logistics
Slovakia Road Freight Transport Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Argentina Road Freight Transport Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Traction Equipment Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Road Transport Refrigeration Equipment Market
Transportation & Logistics
Europe Long Haul Transport Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
United States Short Haul Road Freight Transport Market