
 Global V2X Market | 2026-2036
Global V2X Market Size, Share, and Industry Trends Forecast 2026-2036
Global V2X Market Outlook
Fleet operators and transportation network companies is redrawing the V2X demand map as public-sector procurement cycles lengthen. Qualcomm Technologies anchors cellular-V2X chipset supply through its 5G NR-based automotive platform. Robert Bosch GmbH competes with integrated roadside-unit and onboard-unit portfolios spanning DSRC and C-V2X protocols. NXP Semiconductors specializes in secure-element hardware that satisfies automotive-grade encryption requirements.
Vehicle-to-everything (V2X) communication denotes wireless data exchange between vehicles, infrastructure, pedestrians, and networks operating across licensed cellular and dedicated short-range spectrum at 5.9 GHz. The technology enables cooperative awareness messages, intersection movement assistance, and vulnerable road-user protection through sub-100-millisecond latency links. Cellular V2X is gaining share over DSRC where 5G network density permits, while collision avoidance commands the highest application-specific unit economics due to liability-sensitive OEM specifications. Edge computing deployments are expanding fastest among deployment models as latency-sensitive use cases outstrip cloud round-trip constraints.
The Federal Communications Commission in the United States, the European Commission through its C-ITS Delegated Regulation, and China's Ministry of Industry and Information Technology collectively dictate spectrum allocation, message-set standards, and certification pathways that determine vendor market access. ETSI ITS-G5 and 3GPP Release 16 conformance now function as de facto gating criteria for supplier qualification with major automotive manufacturers. Stakeholders must monitor spectrum reallocation proceedings and cross-border harmonization negotiations to anticipate interoperability investment requirements.
Market Dynamics
The V2X market pivots on spectrum reallocation battles between DSRC and C-V2X protocols, with automotive OEMs and infrastructure vendors forced to place dual-technology bets while regulators finalize long-term 5.9 GHz band assignments.
Growth Catalysts
- MIIT Mandates:China's Ministry of Industry and Information Technology requires connected-vehicle standards in all new passenger cars, creating a guaranteed hardware demand floor for onboard units and secure elements.
- Fleet Digitization:Commercial fleet operators deploy V2X for route optimization and incident reduction, with transportation network companies accelerating procurement beyond public-sector procurement cycles.
- C-ITS Framework:The European Union's Delegated Regulation establishes unified message-set standards and certification pathways, reducing vendor fragmentation across member states.
Market Restraints
- Dual-Protocol Inventory Risk:Vendors must maintain parallel DSRC and C-V2X product lines pending FCC spectrum finality, inflating R&D and inventory carrying costs without guaranteed technology winners.
- Silicon Concentration:Cellular-V2X chipset supply concentrates among a handful of 5G NR automotive platform providers, creating single-source vulnerability for Tier-1 automotive suppliers.
- DSRC Stranded Assets:Early roadside unit deployments in the United States face technical obsolescence risk as transportation agencies delay new capital commitments pending C-V2X clarity.
Strategic Opportunities
- Edge Computing Convergence:V2X data processing is migrating from cloud to roadside edge nodes where sub-100-millisecond latency requirements outstrip round-trip cloud constraints, opening server hardware demand.
- Vulnerable Road-User Protection:Pedestrian and cyclist detection applications remain underpenetrated relative to vehicle-to-vehicle use cases, offering white space for specialized sensor fusion and wearable device integration.
- Cross-Border Harmonization:Ongoing ETSI-3GPP alignment negotiations create first-mover advantage for vendors achieving dual ITS-G5 and Release 16 conformance ahead of formal mandate expansion.
Industry Challenges
- Automotive-Grade Certification Timelines:ETSI ITS-G5 and 3GPP Release 16 conformance testing extends supplier qualification cycles with major OEMs, compressing effective revenue windows for each design generation.
- Interoperability Integration Complexity:Legacy traffic management systems in municipal infrastructure require costly retrofitting to support unified C-ITS message protocols, delaying deployment scale.
- Secure Element Talent Scarcity:Hardware security module design expertise for automotive-grade encryption requirements concentrates within specialized semiconductor teams, constraining vendor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global V2X Market |
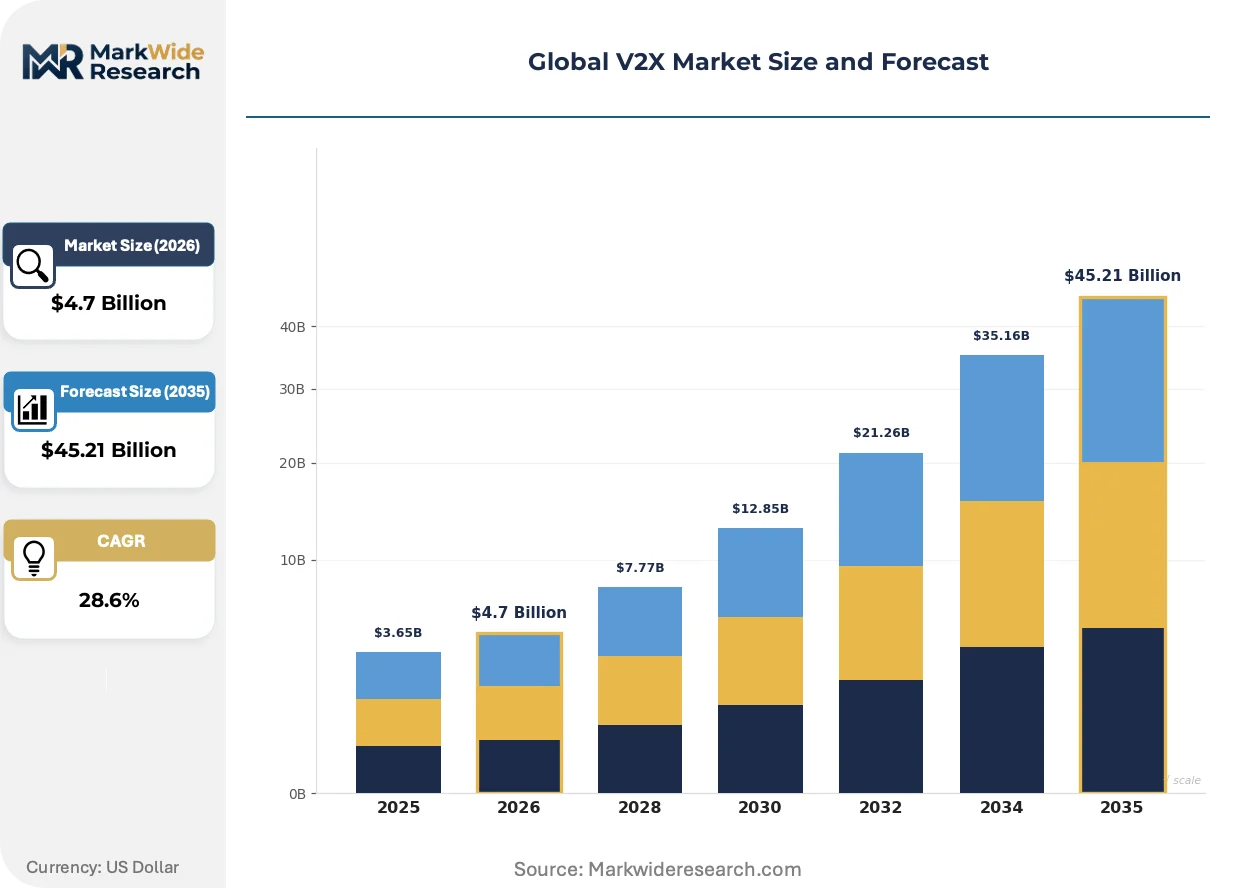
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: DSRC, Cellular V2X, Satellite Communication, Wi-Fi Application: Traffic Management, Emergency Vehicle Notification, Collision Avoidance, Fleet Management End User: Public Sector, Logistics, Automotive Manufacturers, Transportation Network Companies Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Autotalks Ltd., Robert Bosch GmbH, Continental AG, Denso Corporation, Infineon Technologies AG, Qualcomm Technologies, Inc., Cohda Wireless, Harman International, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global V2X Market Strategic Shifts
Cellular-V2X is actively displacing incumbent DSRC installations where 5G network density permits, while edge computing architectures and regulatory harmonization efforts reshape deployment economics across automotive and infrastructure domains.
Cellular-V2X based on 3GPP Release 16 is displacing DSRC roadside units in greenfield deployments across China and select European corridors. Automotive OEMs in these markets are standardizing on 5G NR-based platforms for new vehicle programs, eliminating dual-radio hardware costs. The displacement is compressing the addressable market for dedicated short-range communication chipsets while expanding demand for integrated cellular automotive platforms with V2X sidelink capability.
The FCC's ongoing 5.9 GHz spectrum reallocation proceedings in the United States are forcing transportation agencies to defer new roadside infrastructure commitments. State departments of transportation are responding with pilot-to-production delays, extending payback periods for early C-V2X investors. The uncertainty most acutely affects rural corridor deployments where low traffic density already challenged standalone business cases.
Fleet operators are consolidating V2X procurement decisions at the corporate level rather than delegating to regional maintenance managers. This concentration is displacing fragmented, municipality-driven roadside unit procurement with negotiated enterprise contracts covering vehicle-to-network services. The shift is most visible in North American and European long-haul trucking segments where route optimization platforms bundle V2X data feeds into existing fleet management subscriptions.
Global V2X Market Segmentation
V2X market segmentation reveals how technology choices, deployment architectures, and end-user procurement patterns fragment across regulatory jurisdictions. Understanding these divides helps vendors allocate R&D resources and anticipate standardization timelines.
Technology:
Cellular V2X dominates Chinese domestic installations under MIIT mandates, while DSRC retains residual presence in legacy US roadside deployments awaiting FCC spectrum clarity.
- DSRC:Dedicated short-range communication operates in the 5.9 GHz band with sub-50-millisecond latency for safety-critical messaging. US state transportation agencies face stranded asset risk as the FCC reallocates spectrum, compressing procurement for new roadside units.
- Cellular V2X:3GPP Release 16-based platforms leverage 5G NR sidelink for extended range and network integration. Chinese OEMs and infrastructure vendors have standardized on this protocol, eliminating dual-radio hardware costs in new vehicle programs.
- Satellite Communication:Complements terrestrial coverage in rural corridors and tunnels where cellular density fails.
- Wi-Fi:Serves localized hotspot applications and pedestrian-to-vehicle use cases with minimal infrastructure investment.
Cellular V2X holds the largest share; momentum sits with Satellite Communication as coverage gaps persist in remote logistics corridors.
Application:
Cost tier differentiation separates liability-sensitive collision systems from operational efficiency tools, with premium pricing attaching to safety-critical certifications.
- Traffic Management:Municipal signal prioritization and congestion routing require integration with legacy ITS infrastructure. European C-ITS framework adoption is accelerating cross-border corridor deployments, though retrofit costs delay scale.
- Collision Avoidance:Cooperative awareness messages and intersection movement assistance demand sub-100-millisecond latency. OEM specifications for this application command the highest unit economics due to liability exposure and automotive-grade certification requirements.
- Emergency Vehicle Notification:Preemptive signal clearing and corridor reservation for ambulances and fire services.
- Fleet Management:Route optimization and predictive maintenance integration for commercial vehicle operators.
Collision Avoidance commands premium positioning; Fleet Management is climbing the fastest as transportation network companies consolidate procurement.
End User:
Customer type fragmentation splits between public-sector procurement cycles and enterprise fleet decisions, with diverging contract structures and technology refresh timelines.
- Automotive Manufacturers:New passenger car programs in China integrate V2X as standard equipment per MIIT mandates. Tier-1 suppliers face qualification bottlenecks as ETSI ITS-G5 and 3GPP Release 16 conformance testing extends design windows.
- Transportation Network Companies:Ride-hail and delivery fleets negotiate enterprise V2X subscriptions bundled with existing fleet management platforms. North American and European long-haul operators are consolidating decisions at corporate level, bypassing fragmented municipal procurement.
- Public Sector:State and municipal transportation departments with deferred capital commitments pending regulatory clarity.
- Logistics:Freight operators optimizing intermodal handoffs and warehouse-to-highway transitions.
Automotive Manufacturers anchor volume; Transportation Network Companies are gaining share fastest through subscription-based service models.
Deployment Model:
Supply concentration in edge hardware is reshaping vendor competitive sets as latency requirements outstrip cloud round-trip constraints.
- Edge Computing:Roadside servers process V2X data within sub-100-millisecond thresholds for real-time safety applications. Chinese smart highway deployments and European C-ITS corridors are expanding edge node installations fastest.
- Cloud-Based:Centralized analytics and long-term traffic pattern modeling with relaxed latency tolerances.
- Hybrid:Tiered architectures splitting real-time processing at edge from historical analytics in cloud.
- On-Premises:Captive infrastructure for high-security military or critical infrastructure applications.
Edge Computing leads infrastructure investment; Hybrid deployments are expanding most quickly as operators balance latency against capital efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese V2X component exports flow predominantly to European automotive assembly plants and North American fleet retrofit programs, establishing cross-border supply dependencies that shape regional deployment timelines.
United States
Fleet operators and state transportation departments drive C-V2X procurement ahead of FCC spectrum finality. The FCC's 5.9 GHz reallocation proceedings create planning uncertainty that delays rural roadside unit commitments. Michigan's Ann Arbor corridor hosts active vehicle-to-infrastructure pilot programs testing dual-protocol interoperability.
Germany
Automotive OEMs and Tier-1 suppliers anchor European C-ITS adoption through integrated onboard unit programs. The EU Delegated Regulation mandates unified message-set standards that reduce vendor fragmentation across member states. Bavaria's Munich-Stuttgart corridor serves as the primary testbed for ETSI ITS-G5 and 3GPP Release 16 harmonization.
China
MIIT mandates connected-vehicle standards in all new passenger cars, guaranteeing hardware demand for onboard units and secure elements. The ministry's certification pathways accelerate domestic C-V2X standardization while limiting DSRC market presence. Shanghai's Yangtze River Delta cluster concentrates smart highway edge computing deployments.
Japan
METI coordinates cross-ministry efforts to align V2X spectrum allocation with autonomous vehicle roadmaps. The ministry's 5.9 GHz band assignments favor cellular-based platforms for urban corridor applications. Nagoya's Chubu region hosts concentrated automotive electronics manufacturing for domestic and export programs.
South Korea
Seoul Capital Area municipalities deploy C-V2X infrastructure for autonomous shuttle networks and traffic signal prioritization. The Korea Communications Commission allocates spectrum blocks that prioritize cellular sidelink over dedicated short-range alternatives. Pangyo's technology cluster houses validation centers for automotive-grade chipset certification.
Global V2X Market Competitive Environment
Player mix skews toward semiconductor specialists and diversified automotive Tier-1s with parallel protocol portfolios. The vendor base concentrates among five to seven firms controlling cellular chipset supply and secure-element hardware. Strategic archetypes include integrated platform providers, protocol-agnostic module suppliers, and automotive-grade security specialists. Competitive moves center on dual-technology R&D maintenance and edge computing partnership formations.
Within the integrated platform tier, Qualcomm Technologies and Robert Bosch GmbH exemplify divergent approaches to protocol standardization. Qualcomm Technologies anchors cellular-V2X supply through 5G NR-based automotive platforms. Robert Bosch GmbH occupies a position spanning roadside-unit and onboard-unit portfolios across DSRC and C-V2X protocols. NXP Semiconductors represents the security-specialist archetype with automotive-grade encryption hardware.
| Leading Market Players |
|---|
| Autotalks Ltd. |
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Infineon Technologies AG |
| Qualcomm Technologies, Inc. |
| Cohda Wireless |
| Harman International |
| NXP Semiconductors |
| Others |
Value Chain & Pricing Dynamics
ETSI ITS-G5 and 3GPP Release 16 conformance testing gates both supplier qualification and price differentiation simultaneously, compressing revenue windows for each design generation while stratifying hardware tiers by certification completeness.
Pricing Analysis
DSRC-to-C-V2X migration pricing gaps separate stranded legacy inventory from premium 5G NR-based platforms. Three-tier pricing structure across automotive-grade certified, pre-certified development, and non-certified economy levels reflects liability exposure and OEM qualification status. Pricing pressure stems from dual-protocol inventory maintenance as FCC spectrum finality delays force parallel R&D commitments. Fleet operators exhibit highest price sensitivity through subscription-based procurement, while collision avoidance applications tolerate premium positioning due to liability-sensitive OEM specifications.
Supply Chain Analysis
5G NR automotive platform supply concentrates in Taiwan, South Korea, and the United States as Qualcomm Technologies and NXP Semiconductors anchor chipset fabrication. Secure element hardware draws from specialized semiconductor foundries, while roadside unit assembly feeds from German and Chinese industrial electronics clusters. Single-source vulnerability in cellular-V2X baseband silicon creates supply chain risk as Tier-1 automotive suppliers lack qualified second sources. Distribution runs through Tier-1 supplier integration into OEM vehicle programs and direct enterprise contracting with fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
V2X market expansion is fundamentally a service-attach opportunity as edge computing subscriptions and predictive maintenance layers outpace hardware unit growth in revenue contribution.
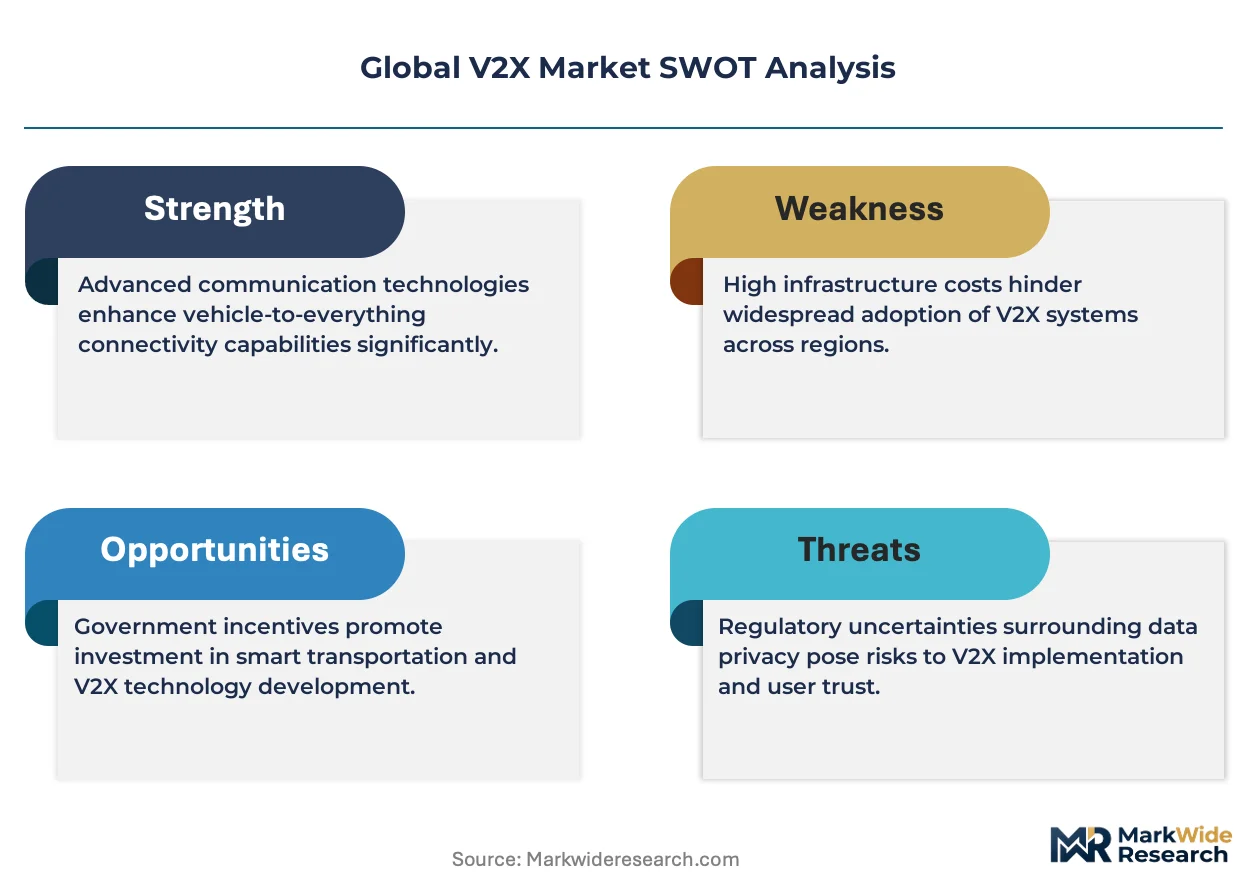
For Market Incumbents: Compound platform stickiness through backward integration into secure element design and captive supply of automotive-grade encryption hardware. Dual-protocol R&D maintenance threatens margin compression until FCC spectrum clarity emerges, demanding selective capacity concentration in C-V2X-qualified facilities. Certification investment in simultaneous ETSI ITS-G5 and 3GPP Release 16 conformance preserves Tier-1 supplier status against emerging Asian competitors. For New Entrants and Emerging Players: Vulnerable road-user protection services represent the most penetrable white space as pedestrian and cyclist detection applications remain underdeveloped relative to vehicle-to-vehicle use cases. Rural corridor satellite-V2X hybrid deployments offer geographic entry points where cellular density fails and incumbent infrastructure investment lags. Go-to-market positioning should anchor on wearable device integration and specialized sensor fusion partnerships with municipal pedestrian safety programs. For Investors and Strategic Acquirers: FCC spectrum reallocation finality reshapes the acquisition landscape by determining stranded asset exposure across DSRC-dependent technology portfolios. Long-term viability centers on cellular-V2X platform providers with demonstrated 5G NR sidelink qualification and edge computing partnership networks. Acquisition target archetypes include automotive-grade security specialists with hardware encryption module expertise and protocol-agnostic roadside unit suppliers with C-ITS corridor deployment experience. The signal to watch is ETSI-3GPP harmonization treaty progress as a leading indicator of cross-border standardization momentum and vendor qualification demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Partnership Formation | Qualcomm Technologies and Bosch are consolidating roadside server deployments with sub-100-millisecond latency guarantees for C-ITS corridors. |
| Dual-Protocol Certification Investment | NXP Semiconductors maintains parallel ETSI ITS-G5 and 3GPP Release 16 conformance programs to preserve OEM qualification status. |
| Secure Element Backward Integration | Automotive-grade encryption hardware specialists are acquiring HSM design teams to reduce silicon dependency. |
| Fleet Management Platform Integration | Transportation network companies bundle V2X data feeds into existing route optimization subscriptions across North American long-haul segments. |
| Cross-Border Harmonization Alignment | Vendors achieving dual ITS-G5 and Release 16 conformance ahead of formal mandate expansion capture first-mover advantage in European C-ITS procurement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with automotive OEM platform engineers, Tier-1 supplier procurement leads, state transportation department planners, and fleet operations directors; and secondary validation through FCC spectrum proceeding dockets, ETSI technical committee releases, MIIT certification bulletins, vehicle production databases, and automotive semiconductor SEC disclosures. Bottom-up unit shipment modeling triangulated against top-down infrastructure investment forecasts across the analysis window.
Across the modeling period, projections incorporate technology segmentation by DSRC, Cellular V2X, satellite communication, and Wi-Fi protocols; application segmentation spanning traffic management, collision avoidance, emergency vehicle notification, and fleet management; and deployment model differentiation across edge computing, cloud-based, hybrid, and on-premises architectures. CAGRs were derived from installed base growth curves and replacement cycle assumptions, with specific inputs including MIIT mandate compliance timelines and FCC spectrum reallocation probability scenarios.
Underlying assumptions cover regulatory mandate adherence rates, technology migration timelines, and infrastructure investment continuity, with deviation risk concentrated in FCC spectrum finality delays and cross-border harmonization treaty negotiations. Practitioners should keep alternative scenarios live as ETSI-3GPP alignment proceedings and national spectrum allocation decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Mobility As a Service Market