
 Automated Robotic Parking System Market | 2026-2036
Automated Robotic Parking System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Robotic Parking System Market Insights
CE marking under the EU Machinery Directive is collapsing the field of qualified installers across Europe, favoring firms with dedicated conformity assessment teams. Westfalia Technologies leverages its integrated steel fabrication and software engineering capabilities to deliver turnkey systems. Klaus Multiparking anchors its position through deep specialization in puzzle-style stacking configurations for mid-rise residential developments. Unitronics differentiates via proprietary PLC-based control architectures that reduce sensor failure rates in high-throughput commercial deployments.
Automated robotic parking systems mechanically transport vehicles into dense storage configurations using shuttles, lifts, and transfer platforms, typically achieving 2-3 times the vehicle density of conventional ramp garages while eliminating human circulation space. Stacking systems dominate current revenue as proven puzzle and tower designs satisfy height-constrained retrofits in established European cities. Shuttle systems represent the fastest-expanding segment as magnetic navigation and laser guidance technologies enable scalable modular expansion without structural overhaul. Computer vision integration across platform systems is concentrating margin pools among vendors with in-house machine learning development.
German KBA type-approval requirements and Japan METI building equipment safety standards shape product design cycles for any vendor seeking access to premium municipal contracts. Dubai's MOHAP civil defense regulations for automated structures mandate redundant fire suppression and emergency manual override protocols that add engineering cost but filter out undercapitalized entrants. Stakeholders must monitor how evolving ISO 3691-4 autonomous mobile robot safety standards will transfer to parking shuttle certification timelines.
Market Dynamics
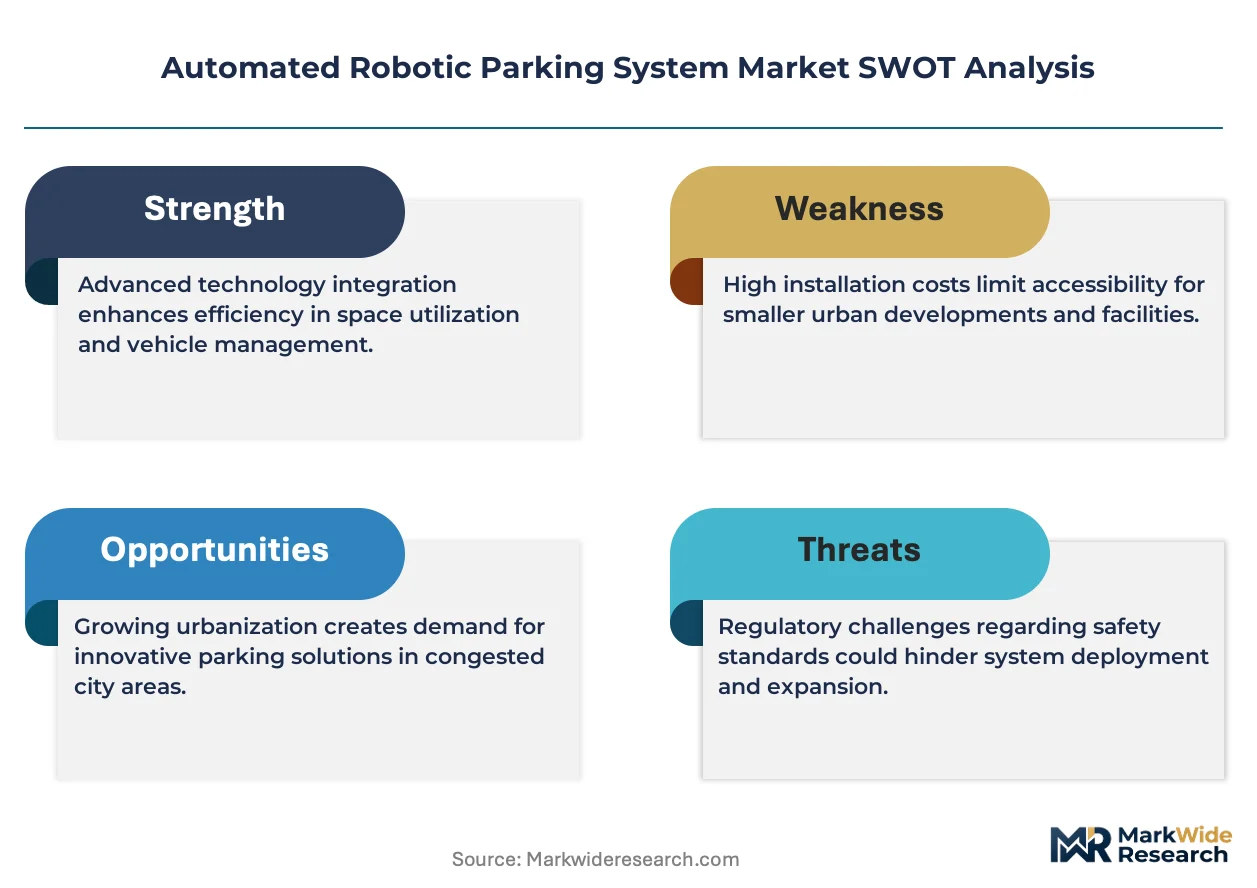
EU machinery safety directives are compressing the qualified installer base across Europe, forcing vendors to internalize conformity assessment capabilities or exit premium municipal contracts entirely. This regulatory consolidation is redistributing margin pools toward vertically integrated system providers with captive certification expertise.
Growth Catalysts
- Land Scarcity Premiums:Dense urban cores in Germany, Japan, and the United Arab Emirates generate returns on capital-intensive parking infrastructure that justify 2-3x vehicle density configurations over conventional ramp garages.
- CE Marking Under Machinery Directive:Harmonized safety standards across EU member states create procurement clarity for commercial building developers seeking turnkey automated installations.
- Magnetic Navigation Advancement:Laser-guided shuttle systems enable modular expansion without structural overhaul, accelerating retrofit adoption in height-constrained European city centers.
Market Restraints
- Steel Input Volatility:Structural fabrication costs for automated parking frames fluctuate with regional steel pricing, compressing project margins for fixed-price contracts.
- Specialized Installer Concentration:Germany and Japan host the majority of qualified system integrators, creating geographic supply bottlenecks for projects in peripheral markets.
- Fire Code Fragmentation:Dubai's MOHAP civil defense regulations for redundant suppression systems add engineering cost layers that filter undercapitalized entrants from premium contracts.
Strategic Opportunities
- Mid-Rise Residential Retrofit:Puzzle-style stacking configurations address parking deficits in aging European housing stock where below-grade expansion is geotechnically constrained.
- ISO 3691-4 Convergence:Emerging autonomous mobile robot safety standards will create certification pathways for parking shuttles, opening municipal tender access for compliant vendors.
- Computer Vision Integration:Machine learning-enabled damage detection and vehicle positioning systems concentrate service revenue among vendors with in-house algorithm development.
Industry Challenges
- Control Systems Expertise Gap:PLC programming and sensor integration skills concentrate among German and Japanese engineering pools, constraining deployment velocity in emerging markets.
- KBA Type-Approval Timelines:German motor vehicle authority certification cycles extend 12-18 months for novel shuttle configurations, delaying revenue recognition on innovative designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Robotic Parking System Market |
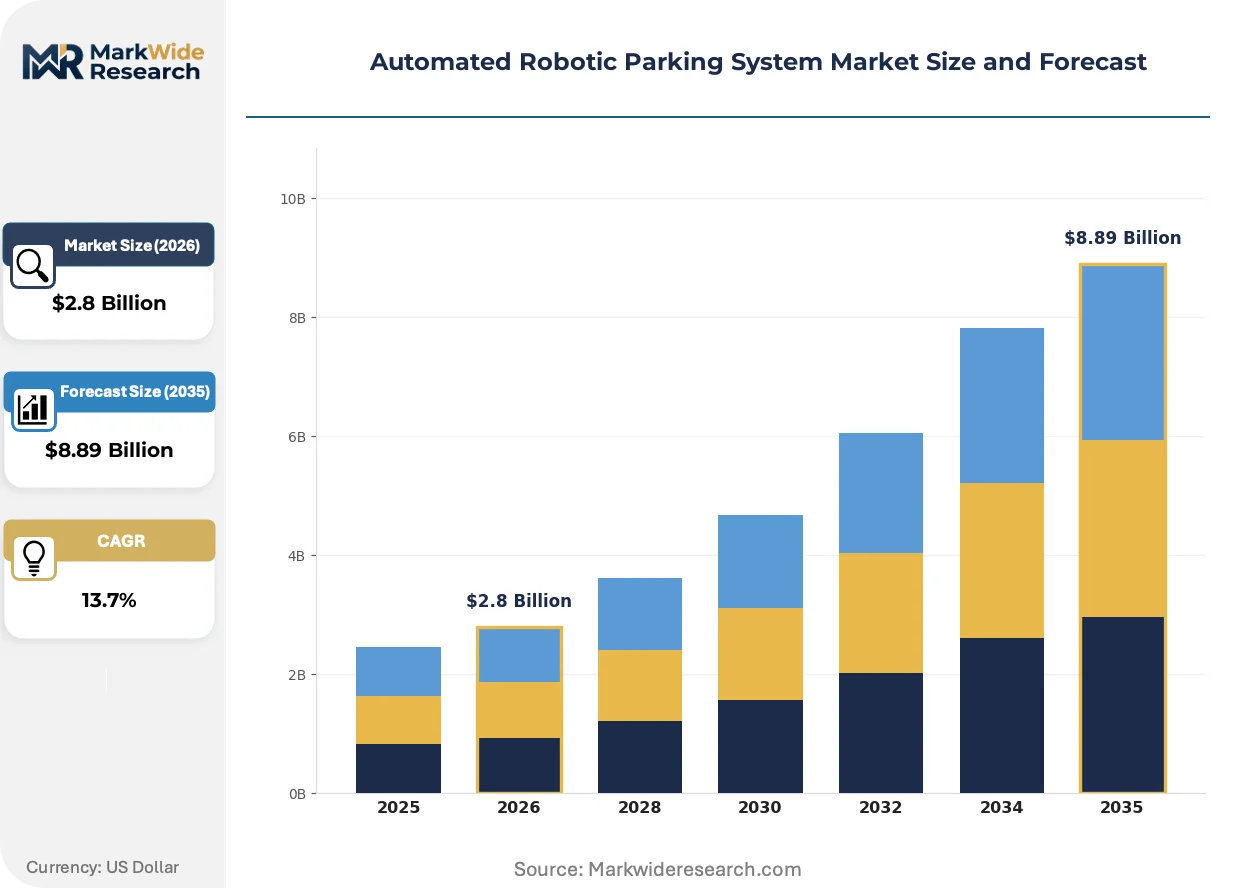
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stacking System, Shuttle System, Platform System, Automated Valet Technology: Magnetic Navigation, Laser Guidance, Computer Vision, RFID End User: Commercial Buildings, Airports, Hospitals, Shopping Malls Deployment Model: On-premise, Cloud-based, Hybrid, Mobile Integrated |
| Companies Covered | Westfalia Technologies, Klaus Multiparking, Wohr Parking Systems, Robotic Parking Systems, Skyline Parking, Unitronics, Parkmatic, Lodige Industries, City Lift Parking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Robotic Parking System Market Trends and Innovations
Automated parking architecture is fragmenting into modular, software-defined subsystems that separate mechanical transport from intelligent control layers. This decomposition is redistributing competitive advantage toward vendors with integrated digital-physical capabilities.
Shuttle-based storage is decomposing the traditional monolithic parking structure into independently scalable transport modules. Commercial developers in the United Arab Emirates are deploying magnetic navigation platforms that expand capacity without crane-dependent construction. This decomposition is compressing the addressable market for conventional tower systems while expanding serviceable obtainable market for phased retrofit projects.
EU machinery safety directives are mandating redundant emergency override protocols and fail-safe positioning systems for all automated vehicle handling equipment. Industrial consequence includes accelerated R&D allocation toward dual-channel sensor architectures and certified safety PLCs. German KBA type-approval requirements are most affected, with vendors pre-certifying shuttle designs to avoid tender disqualification.
Building operators are unbundling parking system procurement from general contractor relationships, establishing direct vendor contracts with performance-based maintenance riders. Facility management firms in Japan are displacing traditional construction-bid models with 15-year service agreements covering uptime guarantees. This pattern is most visible in Tokyo and Osaka commercial developments where METI building equipment standards create certification-driven vendor selection.
Automated Robotic Parking System Market Segmentation
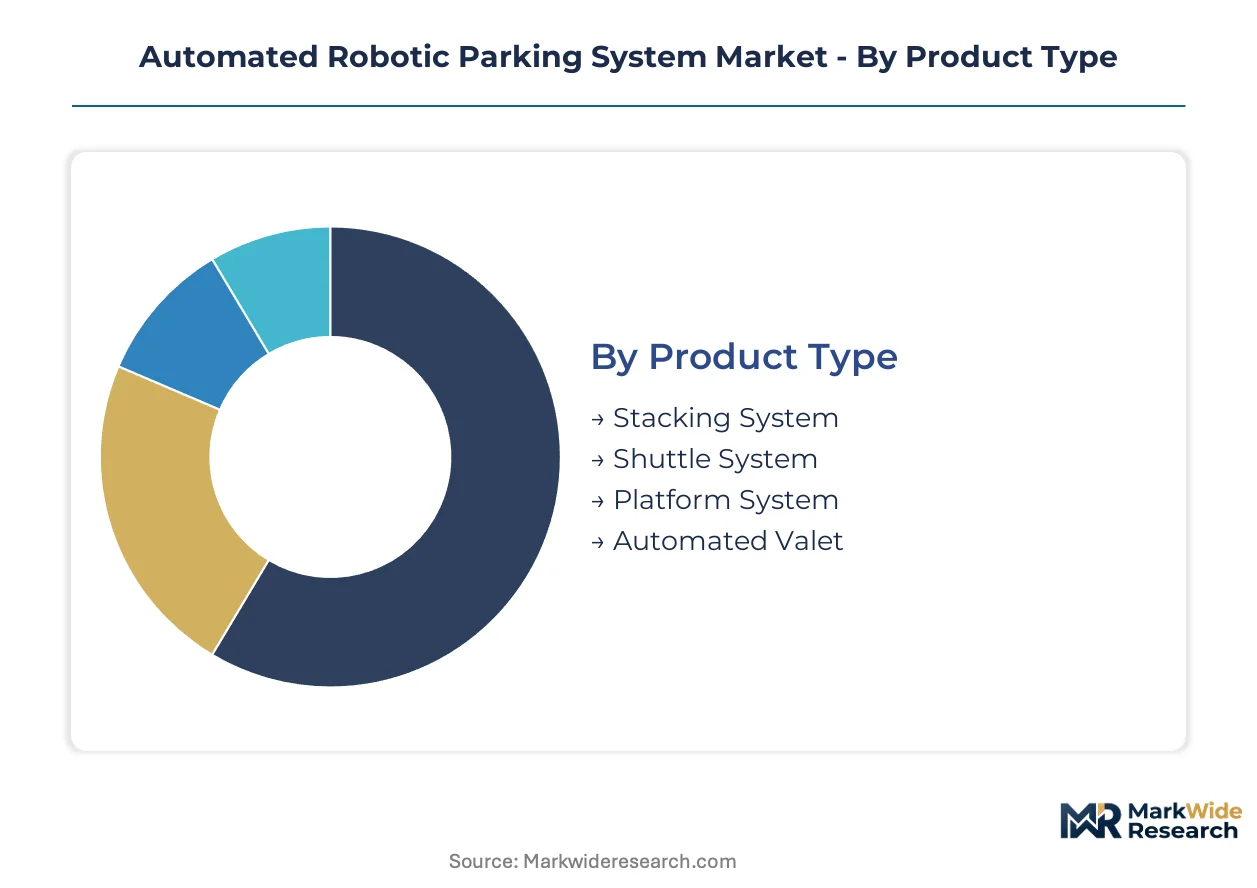
Automated parking architectures diverge sharply across mechanical configuration, navigation modality, and operational integration. Regulatory certification requirements from KBA, METI, and Dubai MOHAP fragment vendor capabilities across these dimensions, creating distinct margin pools.
Product Type:
German KBA type-approval and Japan METI building equipment standards enforce divergent engineering specifications across mechanical configurations, filtering vendor participation by certification capacity.
- Stacking System:Mechanical puzzle and tower designs compress vehicles into vertical columns using lifts and transfer platforms. German commercial developers in Frankfurt and Munich deploy these for height-constrained retrofits where below-grade expansion faces geotechnical barriers.
- Shuttle System:Independently mobile transport modules navigate via embedded magnetic tracks or laser guidance without fixed structural rails. Dubai developers favor these for phased capacity expansion under MOHAP civil defense regulations requiring redundant emergency override protocols.
- Platform System:Fixed horizontal carriers with vertical lift integration serve mid-rise residential stock in Tokyo and Osaka under METI maintenance standards.
- Automated Valet:Robotic vehicle retrieval without fixed infrastructure targets premium hospitality and commercial developments in the United Arab Emirates.
Stacking systems handle the majority of throughput; shuttle systems are climbing the fastest on share.
Technology:
Navigation and sensing modalities concentrate R&D allocation toward vendors with captive software engineering capabilities, separating mechanical fabricators from intelligent control providers.
- Magnetic Navigation:Embedded track systems enable precise shuttle positioning without environmental interference. Japanese integrators in Yokohama and Nagoya deploy these for high-throughput commercial installations under METI safety certification.
- Laser Guidance:LiDAR-based environmental mapping permits flexible path planning without physical infrastructure modification. German KBA approval cycles for laser-configured shuttles extend 12-18 months, delaying revenue recognition for novel designs.
- Computer Vision:Camera-based damage detection and positioning systems.
- RFID:Passive and active tag systems for vehicle identification and access control.
Magnetic navigation dominates current deployment volume; computer vision is gaining share fastest through service revenue concentration.
End User:
Facility type determines fire suppression redundancy, throughput specification, and maintenance contract structure under divergent national building codes.
- Commercial Buildings:Dense urban cores in Germany and Japan generate returns justifying capital-intensive infrastructure. Frankfurt and Tokyo developers specify 15-year performance-based maintenance agreements displacing traditional construction-bid models.
- Airports:24-hour throughput requirements and redundant system architectures. Dubai International Airport deployments face MOHAP civil defense mandates for dual-channel fire suppression.
- Hospitals:Emergency vehicle priority protocols and infection-control surface requirements.
- Shopping Malls:Peak-load variability and consumer-facing retrieval time guarantees.
Commercial buildings absorb the dominant share of installed capacity; airports are expanding most quickly on project value.
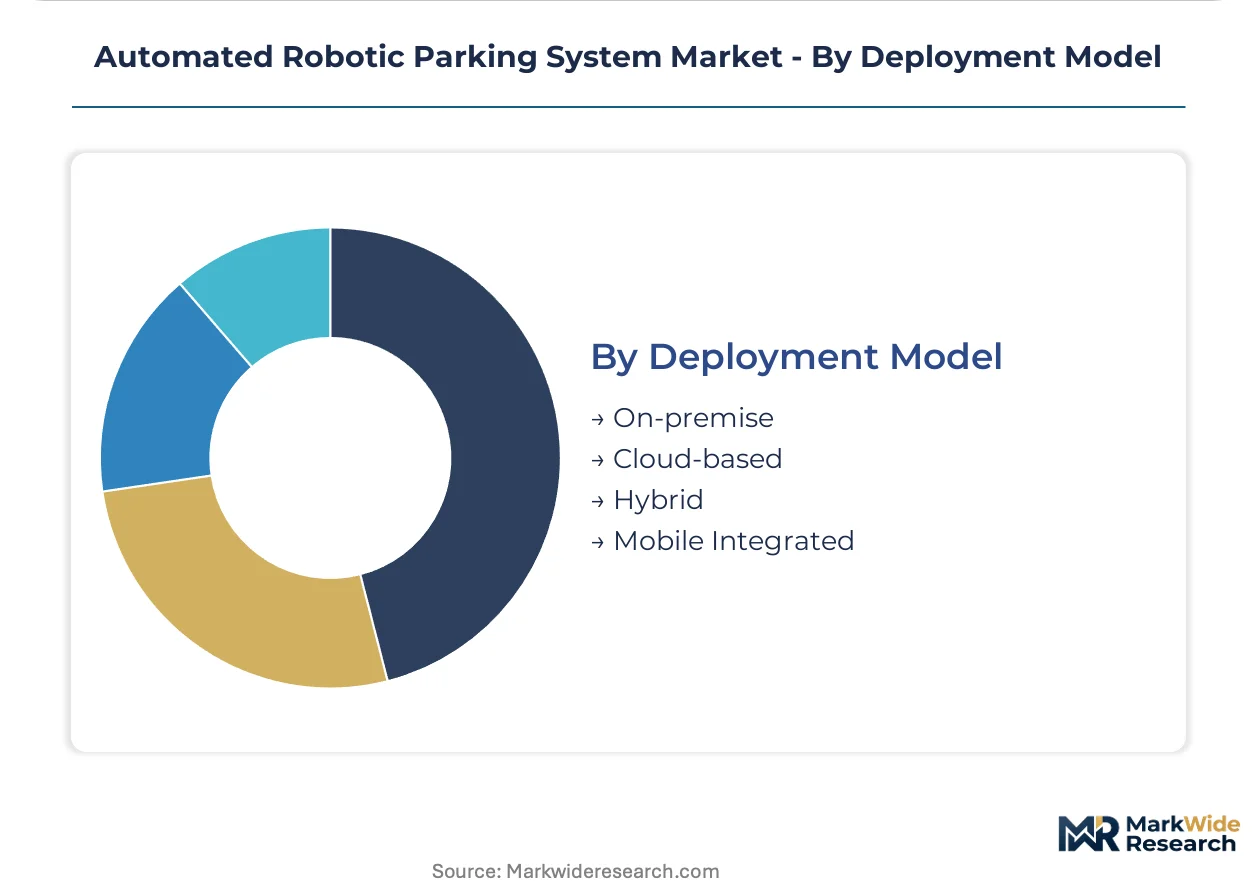
Deployment Model:
Control system architecture separates vendors with integrated digital-physical capabilities from mechanical fabricators, redistributing competitive advantage toward software-defined subsystem providers.
- On-premise:Local PLC control with dedicated safety architectures. German KBA requirements mandate certified safety PLCs with dual-channel sensor redundancy for all on-premise configurations.
- Cloud-based:Centralized monitoring and predictive maintenance via external data centers. Japanese METI building equipment standards create procurement clarity for cloud-integrated facility management contracts in Tokyo commercial developments.
- Hybrid:Local control with remote diagnostics and software update capability.
- Mobile Integrated:Smartphone-based vehicle retrieval and payment systems.
On-premise systems retain the majority of operational base; cloud-based models are scaling fastest through service contract unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German KBA type-approval requirements and Japan METI building equipment standards shape product design cycles for vendors seeking premium municipal contracts. Dubai's MOHAP civil defense regulations mandate redundant fire suppression systems that filter undercapitalized entrants. These regulatory frameworks concentrate installation expertise in specific metropolitan clusters.
Germany
Frankfurt and Munich commercial developers deploy puzzle-style stacking systems for height-constrained retrofits where below-grade expansion faces geotechnical barriers. KBA type-approval cycles extend 12-18 months for novel shuttle configurations, delaying revenue recognition on innovative designs. Stuttgart-based engineering pools supply PLC programming expertise that constrains deployment velocity elsewhere.
Japan
Tokyo and Osaka facility management firms displace traditional construction-bid models with 15-year performance-based maintenance agreements covering uptime guarantees. METI building equipment standards create certification-driven vendor selection for commercial developments. Yokohama and Nagoya integrators deploy magnetic navigation platforms for high-throughput installations.
United Arab Emirates
Dubai developers favor shuttle systems for phased capacity expansion under MOHAP civil defense regulations requiring redundant emergency override protocols. Premium hospitality and commercial developments target robotic valet configurations without fixed infrastructure. Abu Dhabi municipal contracts reward vendors with integrated conformity assessment capabilities.
United States
Dense urban cores in New York and San Francisco generate returns justifying capital-intensive parking infrastructure with 2-3x vehicle density configurations. Local fire codes and ADA compliance requirements fragment installation standards across municipal jurisdictions. Los Angeles developers pilot cloud-based facility management contracts unbundled from general contractor relationships.
China
Shanghai and Beijing commercial building owners seek turnkey automated installations as land scarcity premiums intensify in central business districts. GB standards and local construction safety regulations shape procurement specifications for domestic and foreign vendors. Shenzhen engineering clusters concentrate computer vision integration capabilities for damage detection systems.
Automated Robotic Parking System Market Competitive Landscape
Player mix skews toward vertically integrated system providers with captive certification expertise and specialized mechanical fabricators with regional installation relationships. The vendor base concentrates in Germany and Japan where qualified integrator pools create geographic supply bottlenecks for peripheral markets. Two strategic archetypes dominate: integrated steel-and-software engineering firms delivering turnkey solutions, and puzzle-configuration specialists anchoring mid-rise residential retrofits. Competitive moves center on internalizing conformity assessment capabilities and establishing 15-year performance-based maintenance contracts.
Among Germany-based engineering firms, Westfalia Technologies and Klaus Multiparking occupy positions reflecting divergent specialization vectors. Westfalia exemplifies the integrated archetype through combined steel fabrication and control system capabilities. Klaus Multiparking represents deep specialization in stacking configurations for residential developments. Unitronics anchors the control systems tier with proprietary PLC architectures. These three firms illustrate how certification capacity and software-defined subsystems redistribute competitive advantage.
| Leading Market Players |
|---|
| Westfalia Technologies |
| Klaus Multiparking |
| Wohr Parking Systems |
| Robotic Parking Systems |
| Skyline Parking |
| Unitronics |
| Parkmatic |
| Lodige Industries |
| City Lift Parking |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Machinery Directive gates both supply qualification and price differentiation simultaneously, compressing the installer base while concentrating margin pools among vendors with captive conformity assessment teams. German KBA type-approval and Japan METI certification tiers stratify project pricing across commercial, airport, and residential deployment archetypes.
Pricing Analysis
Certification level creates the primary spread between premium turnkey providers and commodity fabricators. Project-based contracting dominates, with KBA-pre-certified shuttle systems commanding substantial premiums over uncertified alternatives. Price differentiation rests on conformity assessment capacity and after-sales service bundling. Cost compression in mid-tier stacking configurations is intensifying because steel input volatility squeezes fixed-price contracts. Municipal developers in Germany exhibit lowest price sensitivity due to tender disqualification risks, while peripheral European markets show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Strategic stockpiling of certified safety PLCs and dual-channel sensor architectures characterizes vendor inventory strategy given KBA approval timelines. Supply concentrates in Germany, Japan, and South Korea for precision mechanical components and control system engineering. Raw material dependencies include structural steel, magnetic navigation track systems, and laser guidance modules. Single-source vulnerability runs through German engineering pools for PLC programming expertise. Distribution runs through direct vendor contracts with facility management firms displacing traditional general contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 3691-4 autonomous mobile robot safety convergence represents a regulatory inflection that will reshape competitive positioning across shuttle system certification timelines. This standardization wave accelerates market disruption as compliance becomes a gating factor for municipal tender access.
For Market Incumbents: Compound certification advantages by pre-certifying shuttle designs to KBA and METI standards before tender publication, eliminating revenue recognition delays. Deepen backward integration into steel fabrication to buffer margin compression from regional pricing volatility. Anchor position through 15-year performance-based maintenance agreements that displace construction-bid competitors in Tokyo and Frankfurt commercial developments.
For New Entrants and Emerging Players: ISO 3691-4 fast-track certification pathways offer entry into European municipal contracts previously blocked by incumbent approval timelines. Target cloud-based facility management contracts in Los Angeles and emerging Asian markets where METI-equivalent standards are still forming. Lead with computer vision integration capabilities to capture service revenue concentration from damage detection and predictive maintenance applications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed control system specialists possessing captive PLC engineering capabilities but limited mechanical fabrication scale. Five-to-ten year viability hinges on software-defined subsystem decomposition separating intelligent control layers from commodity transport mechanics. Monitor KBA approval cycle compression as signal for which vendors can accelerate revenue recognition on novel shuttle configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | KBA type-approval ahead of tender publication eliminates 12-18 month revenue delays in German municipal contracts. |
| Backward Integration into Steel Fabrication | Captive structural production buffers margin compression from regional steel pricing volatility in fixed-price contracts. |
| 15-Year Performance-Based Maintenance Agreements | Tokyo facility management firms displace construction-bid models with uptime-guaranteed service contracts. |
| Computer Vision Capability Acquisition | Machine learning-enabled damage detection concentrates service revenue among algorithm-capable vendors. |
| Cloud-Based Facility Management Platform Launch | Los Angeles developers pilot remote diagnostics unbundled from general contractor procurement relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and municipal tender databases. Primary interviews engaged system integrators, facility management procurement directors, steel fabrication procurement leads, and conformity assessment specialists. Secondary validation drew from KBA type-approval registers, METI building equipment certification records, Dubai MOHAP civil defense compliance listings, and EU Machinery Directive notified body documentation. Bottom-up project pipeline analysis triangulated against top-down market sizing across mechanical configuration segments.
Segmentation dimensions modeled include mechanical system type, navigation modality, deployment architecture, end-user facility category, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base growth rates and average project value trajectories. Forecast inputs incorporated steel price indexing, certification timeline distributions, and municipal tender award velocity by metropolitan cluster.
Decision-makers should treat outputs as directional under assumptions of sustained land scarcity premiums in dense urban cores and stable regulatory certification timelines; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ISO 3691-4 adoption pace and steel input volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market