
 Rail Freight Digital Transformation Market | 2026-2036
Rail Freight Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Freight Digital Transformation Market Analytics
Multi-source procurement of IoT sensors and AI analytics platforms is restructuring how freight operators build their technology stacks. VTG leverages its European wagon fleet data to anchor predictive maintenance offerings across multiple rail networks. Siemens Mobility competes through in-house development of rail-specific cloud architectures that integrate directly with national signaling systems. IBM extends its position by supplying AI analytics layers that port authorities adopt for cargo tracking across intermodal terminals.
Rail freight digital transformation encompasses the integration of connected sensors, edge computing nodes, and machine learning algorithms into locomotive, wagon, and terminal infrastructure to optimize asset utilization and transit reliability. Systems typically process telemetry at one-second intervals from wheel bearing temperature monitors, GPS units, and brake pressure transducers, then route aggregated data through private cloud instances for pattern recognition and automated dispatching. IoT Solutions and AI Analytics command the primary margin pools as freight operators prioritize real-time condition monitoring over retrospective reporting. Cloud Computing segments are maturing fastest among port authorities that have already completed baseline connectivity projects and now seek API standardization across competing vendor platforms.
The EU Green Deal and F-Gas Regulation impose emissions disclosure requirements that rail networks address through digital fuel monitoring and route optimization systems. The EPA in the United States enforces locomotive exhaust standards that push BNSF Railway and Union Pacific Railroad toward sensor-based compliance verification. ERMES standards and CE marking frameworks govern interoperability of trackside IoT hardware across European corridors. Stakeholders must decide whether to build captive data platforms or accept vendor lock-in from vertically integrated suppliers as regulatory granularity intensifies.
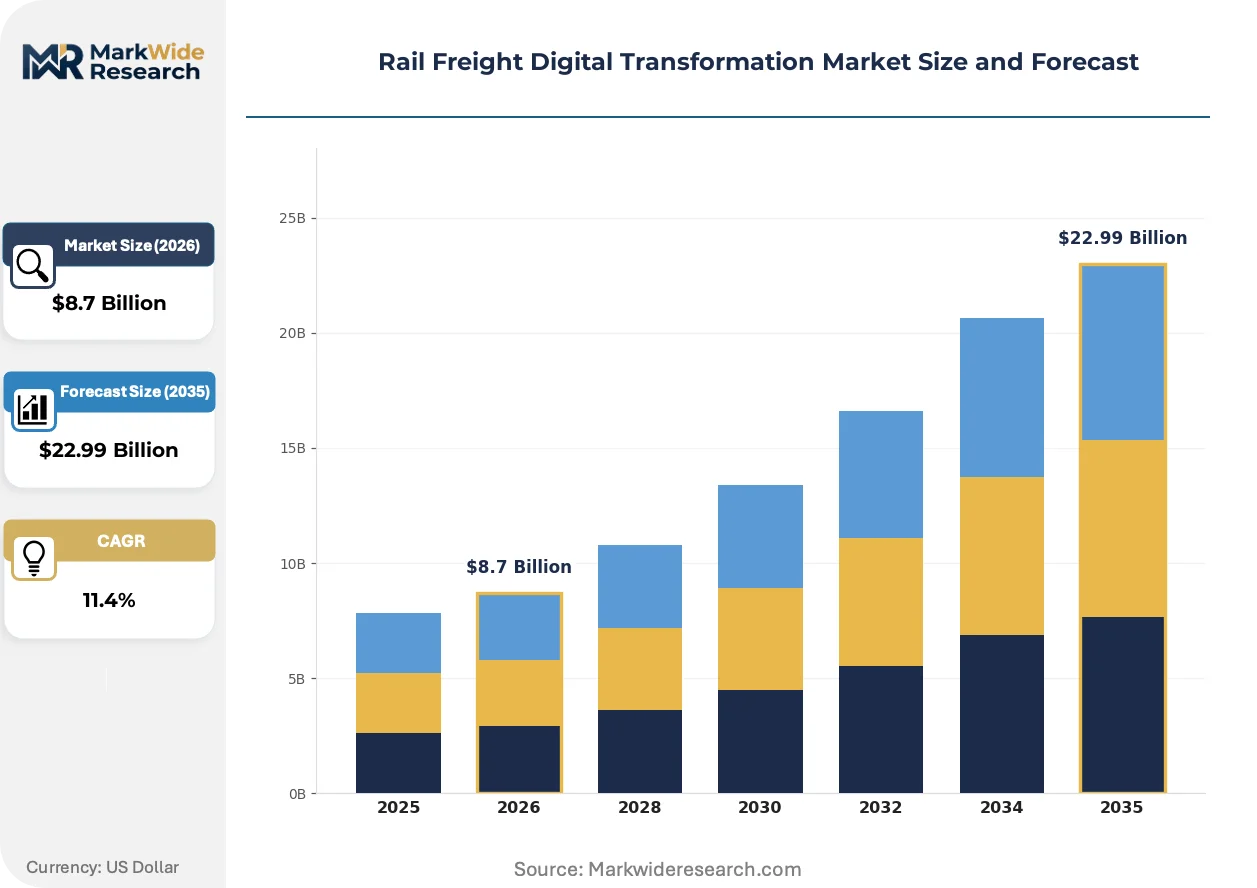
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing rail logistics providers to deploy real-time emissions monitoring and route optimization systems, compressing procurement cycles for digital fuel management platforms across European corridors.
Growth Catalysts
- EU Green Deal:Mandates granular emissions disclosure from freight operators, accelerating demand for sensor-based fuel monitoring and automated carbon reporting across the Rhine-Alpine corridor.
- Mining sector digitization:Bulk commodity shippers in Australia and Brazil are expanding real-time cargo visibility platforms to optimize wagon utilization and reduce dwell times at port terminals.
- Edge computing architectures:One-second telemetry processing from wheel bearing temperature and brake pressure transducers is enabling predictive maintenance contracts that shift revenue models from hardware sales to uptime guarantees.
Market Restraints
- Input cost volatility:Semiconductor shortages and rare earth price swings for GPS and IoT sensor components are extending procurement lead times for trackside hardware deployments.
- Supply concentration risk:Cloud infrastructure for rail networks concentrates among three hyperscale providers, creating single-point-of-failure exposure for mission-critical dispatching systems.
- Interoperability friction:ERMES standards and national signaling system variations force freight operators to maintain multiple hardware configurations across cross-border corridors.
Strategic Opportunities
- Port authority API standardization:Terminal operators in Rotterdam and Hamburg are consolidating vendor platforms into unified data exchange layers, creating openings for middleware specialists.
- AI-driven intermodal matching:Machine learning algorithms that coordinate rail-truck-barge handoffs represent underpenetrated white space outside major European corridors.
- CSRD alignment services:The EU's Corporate Sustainability Reporting Directive is generating demand for automated emissions verification tools that integrate directly with existing fleet management systems.
Industry Challenges
- Embedded systems integration:Retrofitting 30-year-old locomotive control architectures with modern telemetry requires specialized firmware engineering talent that remains scarce in Central and Eastern Europe.
- CE marking timelines:Trackside IoT hardware certification under ERMES and national safety frameworks extends product launch cycles by 14-18 months, compressing vendor R&D returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Freight Digital Transformation Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, AI Analytics, Cloud Computing, Big Data Service Type: Consulting, Integration, Software Development, Maintenance End User: Logistics Providers, Freight Operators, Port Authorities, Rail Networks Application: Asset Management, Cargo Tracking, Predictive Maintenance, Supply Chain Optimization |
| Companies Covered | VTG, Freightliner Group, GATX, Ermewa, BNSF Railway, Union Pacific Railroad, Deutsche Bahn AG, Siemens Mobility, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Freight Digital Transformation Market Evolving Landscape
Digital twin architectures and federated data platforms are restructuring how rail operators orchestrate asset performance across multi-modal networks, shifting competitive advantage toward real-time simulation capabilities.
Digital twin software for locomotive and wagon fleets is modularizing how freight operators prototype maintenance schedules and route configurations before physical deployment. Deutsche Bahn and SNCF are piloting these systems for high-value cargo corridors, compressing the traditional 18-month infrastructure planning cycle into quarterly iteration sprints. This modularizing capability is fragmenting the systems integration market, allowing specialized analytics vendors to displace vertically integrated incumbents in specific functional layers.
The EPA's locomotive exhaust standards are compelling North American Class I railroads to install continuous emissions monitoring systems that transmit real-time NOx and particulate data to regulatory portals. BNSF Railway and Union Pacific Railroad are deploying sensor arrays that integrate with existing positive train control infrastructure, avoiding parallel hardware investments. Bulk commodity terminals in the Powder River Basin face the steepest compliance costs, accelerating their adoption of third-party emissions verification platforms.
Shippers are unbundling predictive maintenance contracts from rolling stock leases, creating standalone service markets for uptime guarantees and condition-based interventions. Mining companies in Western Australia now procure wheel bearing monitoring and brake health analytics separately from wagon provision, forcing fleet owners to open proprietary data interfaces. This disintermediation is most advanced in iron ore corridors where cargo volumes justify dedicated digital infrastructure investments.
Rail Freight Digital Transformation Market Segmentation
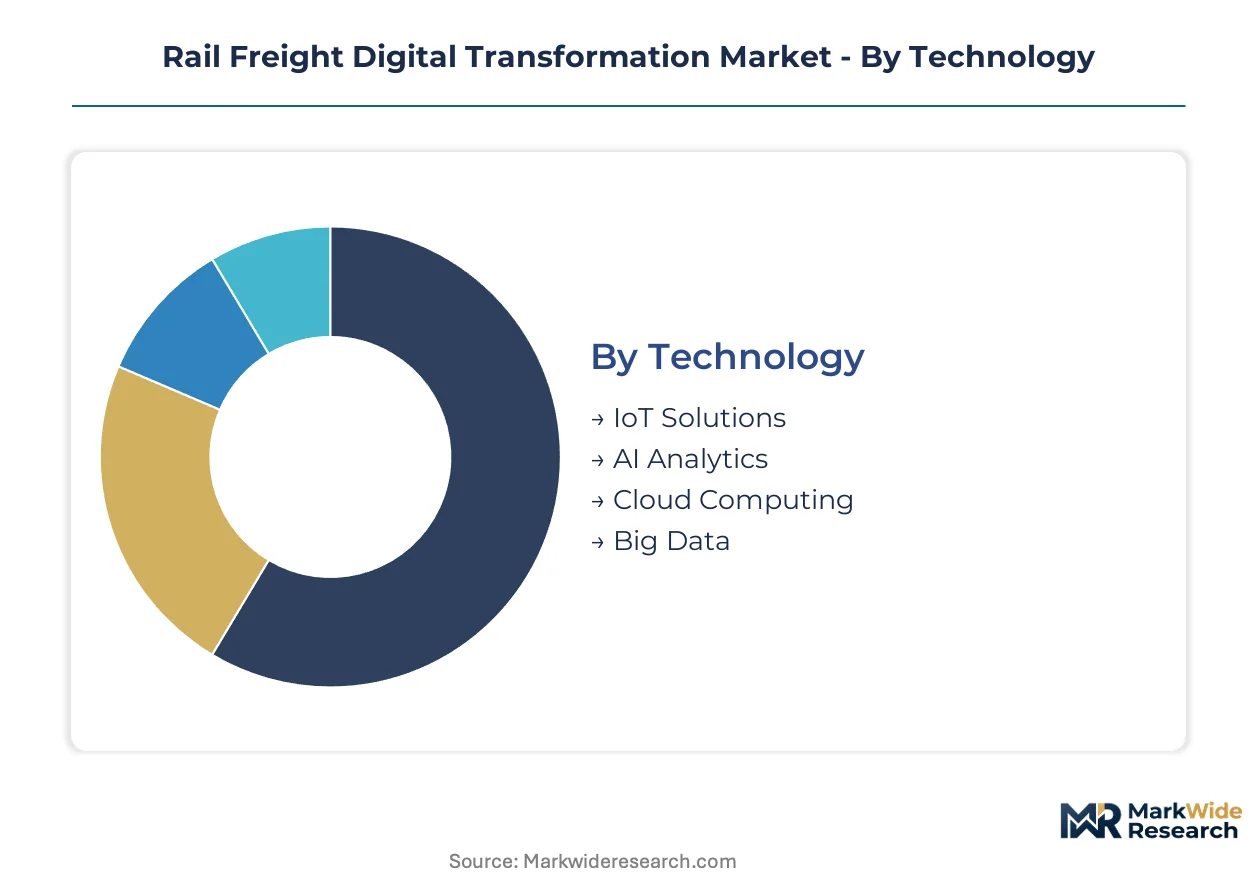
Rail freight digital transformation segments reflect divergent integration depths, from standalone sensor deployments to deeply embedded control systems. Technology choices determine whether operators build modular stacks or accept vendor lock-in through vertically integrated platforms.
Technology:
Standalone telemetry platforms contrast with embedded architectures that fuse directly into locomotive control systems and national signaling networks.
- IoT Solutions:Connected sensor arrays capture wheel bearing temperatures, brake pressures, and GPS coordinates at one-second intervals. Mining corridors in Western Australia and Brazil deploy these most intensively to optimize wagon utilization and reduce port dwell times.
- AI Analytics:Machine learning algorithms process aggregated telemetry to predict component failures and automate dispatch decisions. Port authorities in Rotterdam and Hamburg prioritize these platforms for cargo tracking across intermodal terminals.
- Cloud Computing:Private cloud instances host pattern recognition workloads and regulatory emissions reporting. European corridors lead adoption as Deutsche Bahn and Siemens Mobility anchor Rhine-Alpine infrastructure deployments.
- Big Data:Federated data platforms aggregate multi-source telemetry for network-wide optimization. North American Class I railroads leverage these for EPA compliance verification and route efficiency modeling.
IoT Solutions leads volumes today; AI Analytics is gaining share fastest.
Service Type:
Service procurement patterns split between discrete project engagements and long-term operational partnerships.
- Consulting:Strategic advisory services guide technology stack selection and regulatory alignment. EU Green Deal mandates for emissions disclosure accelerate demand across German and French rail networks.
- Integration:Systems engineering connects legacy locomotive architectures with modern telemetry. Retrofitting 30-year-old control systems requires scarce firmware talent concentrated in Central Europe.
- Software Development:Custom application builds for predictive maintenance and automated dispatching. Mining companies in Australia increasingly unbundle these services from rolling stock leases.
- Maintenance:Uptime guarantees and condition-based intervention contracts replace traditional hardware sales. Iron ore corridors justify dedicated digital infrastructure investments for standalone service procurement.
Integration commands the largest project values; Maintenance shows the steepest expansion trajectory.
End User:
End-user sophistication varies from asset-heavy operators seeking operational control to infrastructure managers prioritizing interoperability.
- Logistics Providers:Third-party operators demand API-standardized platforms to avoid vendor lock-in. Rotterdam and Hamburg terminal operators consolidate competing systems into unified data exchange layers.
- Freight Operators:Asset owners balance captive data platforms against vertically integrated supplier relationships. BNSF Railway and Union Pacific Railroad integrate emissions monitoring with existing positive train control infrastructure.
- Port Authorities:Terminal operators prioritize real-time cargo visibility for intermodal handoff coordination. API standardization initiatives create openings for middleware specialists.
- Rail Networks:Infrastructure managers enforce interoperability standards across cross-border corridors. ERMES certification requirements extend hardware launch cycles by 14-18 months.
Freight Operators dominate current procurement; Port Authorities are climbing the fastest.
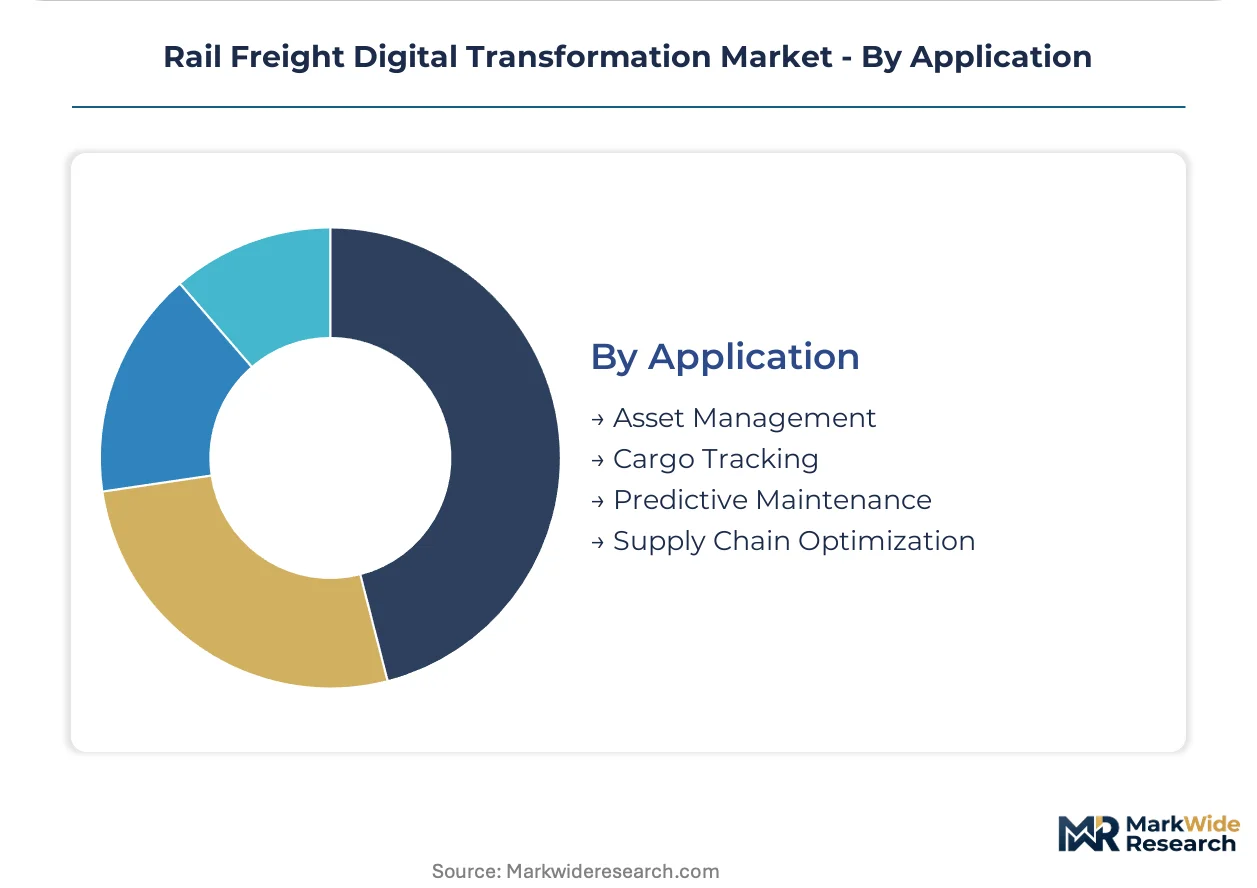
Application:
Application maturity ranges from established asset registries to emerging intermodal coordination algorithms.
- Asset Management:Digital twin architectures simulate maintenance schedules and route configurations before physical deployment. Deutsche Bahn and SNCF compress 18-month planning cycles into quarterly iteration sprints.
- Cargo Tracking:Real-time visibility platforms coordinate rail-truck-barge handoffs. Machine learning algorithms for intermodal matching represent underpenetrated white space outside major European corridors.
- Predictive Maintenance:Condition-based intervention contracts shift revenue models from hardware sales to uptime guarantees. Wheel bearing monitoring and brake health analytics now procure separately from wagon provision.
- Supply Chain Optimization:Route efficiency algorithms reduce fuel consumption and emissions. EU Corporate Sustainability Reporting Directive alignment services integrate directly with fleet management systems.
Asset Management holds the largest installed base; Supply Chain Optimization is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing digital freight investment toward jurisdictions where emissions compliance costs remain manageable relative to operational scale, with Germany, Australia, and the United States capturing disproportionate capital deployment despite divergent enforcement timelines.
Germany
Deutsche Bahn and Siemens Mobility anchor the Rhine-Alpine corridor's digital infrastructure buildout, driven by EU Green Deal mandates for granular emissions disclosure. The KBA enforces ERMES interoperability standards that extend hardware certification cycles. Berlin-Brandenburg and Bavaria concentrate predictive maintenance pilot programs for high-value cargo flows.
United States
BNSF Railway and Union Pacific Railroad deploy continuous emissions monitoring to satisfy EPA locomotive exhaust standards across Powder River Basin bulk corridors. The EPA's real-time NOx reporting requirements accelerate sensor integration with positive train control systems. Chicago and Los Angeles terminals lead API standardization for intermodal handoff coordination.
Australia
Mining operators in Western Australia unbundle predictive maintenance contracts from wagon leases, creating standalone markets for wheel bearing analytics. The country's national transport regulator enforces fatigue management standards that drive automated dispatch adoption. Pilbara iron ore corridors justify dedicated digital infrastructure investments at port terminals.
Netherlands
Rotterdam port authority consolidates competing vendor platforms into unified data exchange layers, opening middleware opportunities for logistics specialists. The EU F-Gas Regulation tightens refrigerant emissions accountability for refrigerated rail cargo. Randstad logistics clusters anchor real-time cargo visibility deployments across North Sea trade lanes.
Brazil
Bulk commodity shippers expand real-time visibility platforms to reduce dwell times at Atlantic port terminals. ANVISA governs pharmaceutical cold-chain rail transport standards that demand sensor-based temperature verification. São Paulo state concentrates domestic freight digitization investments for agricultural export corridors.
Rail Freight Digital Transformation Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-computing specialization and API middleware niches. The vendor base stratifies across three maturity levels: integrated rail operators with captive technology arms, industrial conglomerates with rail-specific divisions, and pure-play analytics specialists. Dominant competitive moves include strategic partnerships for corridor-specific deployments and technology licensing agreements that bypass captive development costs.
Within the integrated operator tier, Deutsche Bahn AG and BNSF Railway exemplify asset owners that internalize digital infrastructure development rather than outsourcing to third-party vendors. Siemens Mobility GmbH occupies a position bridging industrial equipment supply with cloud architecture provision. These three entities represent divergent strategic postures: captive vertical integration, hybrid partnership models, and modular component supply.
| Leading Market Players |
|---|
| VTG |
| Freightliner Group |
| GATX |
| Ermewa |
| BNSF Railway |
| Union Pacific Railroad |
| Deutsche Bahn AG |
| Siemens Mobility |
| IBM |
| Others |
Value Network & Pricing Analysis
EU Green Deal mandates for granular emissions disclosure are compressing procurement cycles for digital fuel management platforms, forcing suppliers to absorb certification costs while freight operators demand API-standardized pricing models that unbundle hardware from analytics subscriptions.
Pricing Analysis
Input-cost pass-through from semiconductor shortages and rare earth price volatility for GPS and IoT sensor components is intensifying pricing pressure across trackside hardware tiers. Pricing stratifies across premium, standard, and economy tiers based on CE marking certification level and after-sales service bundling. Cost compression in the economy tier reflects buyer consolidation among mining operators in Western Australia and Brazil. Freight operators with captive data platforms exhibit the lowest price sensitivity; third-party logistics providers face the highest.
Supply Chain Analysis
Reverse-logistics flows for refurbished IoT sensors and remanufactured edge computing nodes are emerging as cost-containment strategies for European rail networks facing extended hardware certification timelines. Component manufacturing concentrates in Germany, China, and Taiwan for specialized rail-grade semiconductors. Raw material dependencies include rare earth elements for GPS modules, lithium for battery-backed sensors, and high-grade aluminum for trackside enclosures. Single-source vulnerability in cloud infrastructure among three hyperscale providers creates mission-critical dispatching risk. Distribution runs through systems integrators with ERMES certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU emissions compliance costs in Germany and France exceed operational scale advantages in Australia and Brazil, redirecting capital deployment toward jurisdictions with manageable regulatory burdens relative to cargo volumes.
For Market Incumbents: Extend predictive maintenance service portfolios into standalone uptime guarantee contracts that displace vertically integrated hardware vendors. Deutsche Bahn and Siemens Mobility should deepen backward integration into rail-specific cloud architectures to defend against API middleware specialists. Certification investment in ERMES-aligned trackside hardware creates switching costs against emerging entrants.
For New Entrants and Emerging Players: Mid-tier mining operators in Brazil's agricultural export corridors represent an underserved buyer archetype with unmet demand for real-time cargo visibility platforms. AI-driven intermodal matching algorithms for rail-truck-barge coordination outside major European corridors offer the most penetrable white space. A direct sales model targeting port authority API standardization initiatives in Rotterdam and Hamburg provides the clearest go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play analytics specialists possessing federated data platform capabilities and ERMES certification expertise. Long-term viability over the projection horizon favors vendors that modularize around digital twin architectures rather than compete on hardware volume. Acquisition targets should demonstrate established middleware relationships with at least two of Rotterdam, Hamburg, or Chicago port authorities. Monitor EPA enforcement timelines for locomotive exhaust standards as the critical inflection signal for North American sensor deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API Standardization Partnership | Rotterdam port authority's unified data exchange layer creates middleware openings for logistics specialists. |
| Backward Integration into Edge Computing | Siemens Mobility's in-house rail-specific cloud architectures reduce dependency on hyperscale providers. |
| Predictive Maintenance Unbundling | Western Australian mining operators now procure wheel bearing analytics separately from wagon leases. |
| CSRD Alignment Service Launch | EU Corporate Sustainability Reporting Directive generates automated emissions verification demand. |
| Digital Twin Platform Development | Deutsche Bahn and SNCF compress 18-month infrastructure planning into quarterly iteration sprints. |
Research Methodology
Direct dialogue with freight operations directors, IoT platform engineers, port authority procurement managers, and regulatory compliance officers grounded the qualitative foundation. Secondary validation drew from EPA enforcement filings, EU ERMES certification databases, KBA technical directives, and customs data on rail-grade semiconductor imports. Bottom-up demand modeling across operator segments triangulated with top-down market sizing from infrastructure investment disclosures.
Segment-level value outputs across the projection horizon reflect technology-type splits between IoT Solutions, AI Analytics, Cloud Computing, and Big Data, crossed with service-type procurement patterns and end-user sophistication tiers. CAGRs were derived from installed base growth rates adjusted for replacement cycles and regulatory compliance deadlines. Forecast inputs incorporated EU Green Deal implementation timelines and EPA locomotive exhaust standard enforcement phases.
Underlying measurement precision varies by segment; IoT Solutions and AI Analytics carry tighter precision than emerging Big Data platforms where vendor definitions remain fluid. Forecasts reflect documented assumptions on interoperability standard adoption curves and cloud infrastructure concentration risk. Practitioners should monitor EPA rulemaking timelines, EU F-Gas Regulation enforcement intensity, and rare earth supply chain disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market