
 Advanced Therapy Medicinal Products CDMO Market | 2026-2036
Advanced Therapy Medicinal Products CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Therapy Medicinal Products CDMO Market Intelligence
EMA's ATMP classification framework is hardening the cost-of-entry calculus for new CDMO entrants by requiring dedicated containment infrastructure and batch-release expertise. Lonza leverages its global manufacturing footprint to sustain leadership in cell therapy commercial production. Samsung Biologics anchors its competitive position through massive bioreactor capacity and integrated viral vector platforms. Fujifilm Diosynth differentiates via end-to-end gene therapy services spanning process development through commercial fill-finish.
Advanced Therapy Medicinal Products CDMOs are contract organizations that manufacture cell therapies, gene therapies, and tissue-engineered products under GMP conditions using patient-derived or engineered biological starting materials, with critical quality attributes defined by potency assays and vector copy number specifications. Their primary purpose is enabling biopharmaceutical developers to access specialized manufacturing infrastructure without capital-intensive facility construction. Cell therapy manufacturing captures the largest revenue share due to autologous process complexity and patient-specific logistics requirements. Gene therapy services represent the fastest-expanding segment as AAV and lentiviral vector demand outstrips available cleanroom capacity. Viral vector technology dominates R&D allocations while plasmid DNA production emerges as a margin-critical bottleneck across the supply chain.
FDA's CBER division, EMA's Committee for Advanced Therapies, and Japan's PMDA collectively determine market access through divergent potency assay and comparability requirements that shape CDMO capability investments. The FDA's regenerative medicine advanced therapy designation accelerates sponsor timelines but compresses CDMO validation windows, favoring partners with established regulatory track records. Stakeholders must monitor evolving gene therapy durability data requirements and vector immunogenicity thresholds that will determine which manufacturing platforms warrant capacity expansion.
Market Dynamics
Viral vector manufacturing capacity constraints are forcing biopharmaceutical sponsors into multi-year CDMO partnerships before clinical proof-of-concept, locking in capacity years ahead of regulatory filings and reshaping competitive positioning across the contract manufacturing landscape.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy designation:The accelerated approval pathway compresses development timelines and pushes sponsors toward CDMOs with established CBER inspection histories and prior BLA support experience.
- Autologous cell therapy logistics:Patient-specific manufacturing chains require vein-to-vein coordination that biopharmaceutical developers cannot replicate without specialized CDMO partners controlling cold-chain distribution and apheresis center networks.
- Plasmid DNA supply scarcity:Transfection-grade plasmid production capacity concentrates among a limited supplier base, creating pull-through demand for integrated CDMOs controlling this upstream input.
Market Restraints
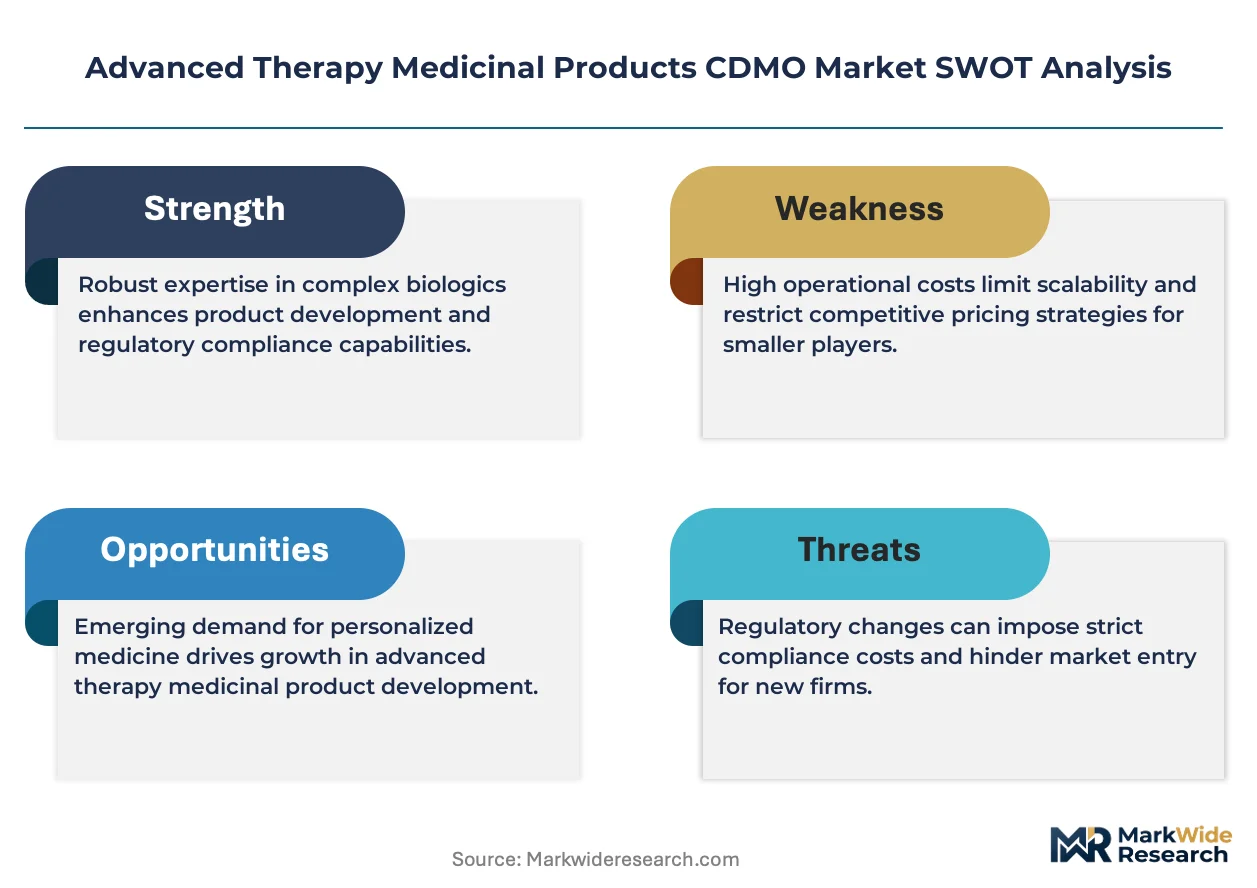
- Containment infrastructure costs:Biosafety Level 2-plus viral vector suites require single-use bioreactor trains and dedicated HVAC segregation that push facility capital intensity beyond $1,500 per square foot.
- European regulatory divergence:EMA's Committee for Advanced Therapies imposes batch-release and comparability requirements that differ from FDA CBER standards, forcing dual-validation investments for global programs.
- Skilled operator scarcity:Aseptic processing technicians with cell culture and gene therapy GMP experience command wage premiums exceeding 40% above traditional biologics manufacturing roles.
Strategic Opportunities
- Japan PMDA harmonization:Japan's accelerated approval framework for regenerative medicines creates demand for CDMOs with Sakigake designation experience and local fill-finish partnerships.
- Allogeneic platform manufacturing:Off-the-shelf cell therapies using donor-derived starting materials enable batch economies that autologous processes cannot achieve, attracting CDMO investment in master cell bank infrastructure.
- Digital supply chain integration:Blockchain-enabled chain-of-identity systems for patient-specific therapies represent a service layer that CDMOs can monetize beyond core manufacturing fees.
Industry Challenges
- Vector copy number assay standardization:Potency measurement variability across qPCR and ddPCR platforms creates regulatory submission risk and delays batch release decisions.
- Legacy ERP integration:Patient scheduling systems must interface with manufacturing execution systems and quality management platforms, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Therapy Medicinal Products CDMO Market |
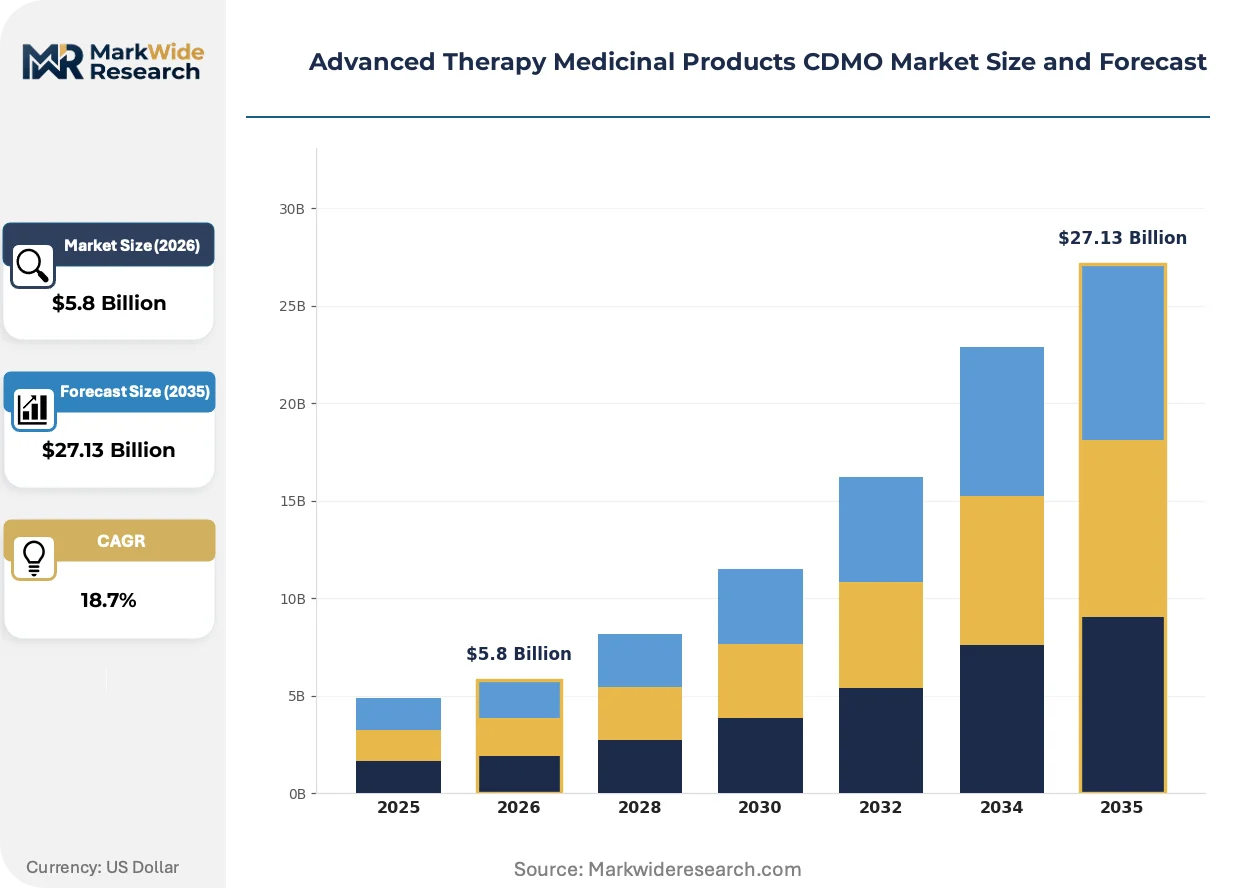
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $27.13 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Therapy, Gene Therapy, Tissue Engineering, Combination Products Service Type: Process Development, Manufacturing, Quality Control, Regulatory Support Technology: Viral Vectors, Plasmid DNA, CRISPR, Stem Cells End User: Biopharmaceutical Companies, Research Institutions, Healthcare Providers, Academic Organizations |
| Companies Covered | WuXi Advanced Therapies, Fujifilm Diosynth, Samsung Biologics, Avid Bioservices, Minaris Advanced Therapies, Lonza, AGC Biologics, Rentschler Biopharma, Catalent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Therapy Medicinal Products CDMO Market Strategic Shifts & Innovations
Suspension-based AAV production platforms are displacing adherent cell culture systems, compressing cost structures and enabling scale that was technically inaccessible five years ago. This platform shift is redrawing which CDMOs can credibly bid on commercial gene therapy programs.
Stable producer cell lines for AAV manufacturing are expanding into programs previously dependent on transient transfection. Large-capacity biopharmaceutical sponsors are adopting these lines for Phase III campaigns to reduce plasmid DNA input costs and improve batch-to-batch consistency. The technology is expanding into mid-scale CDMO facilities that previously lacked the process development depth to support stable line generation.
EMA's updated ATMP classification guidelines are tightening potency assay and comparability demonstration requirements for post-approval changes. Sponsors now face mandatory side-by-side analytical bridging studies that extend regulatory timelines by 12-18 months. European developers are responding by front-loading CDMO selection criteria with prior CAT interaction experience and established quality agreement templates.
Biopharmaceutical procurement teams are consolidating manufacturing contracts with single partners controlling both process development and commercial supply. This behavior displaces the historical model of separate CMOs for clinical and commercial phases. The shift is most visible among US-based gene therapy sponsors seeking to minimize technology transfer risk ahead of BLA submission.
Advanced Therapy Medicinal Products CDMO Market Segmentation
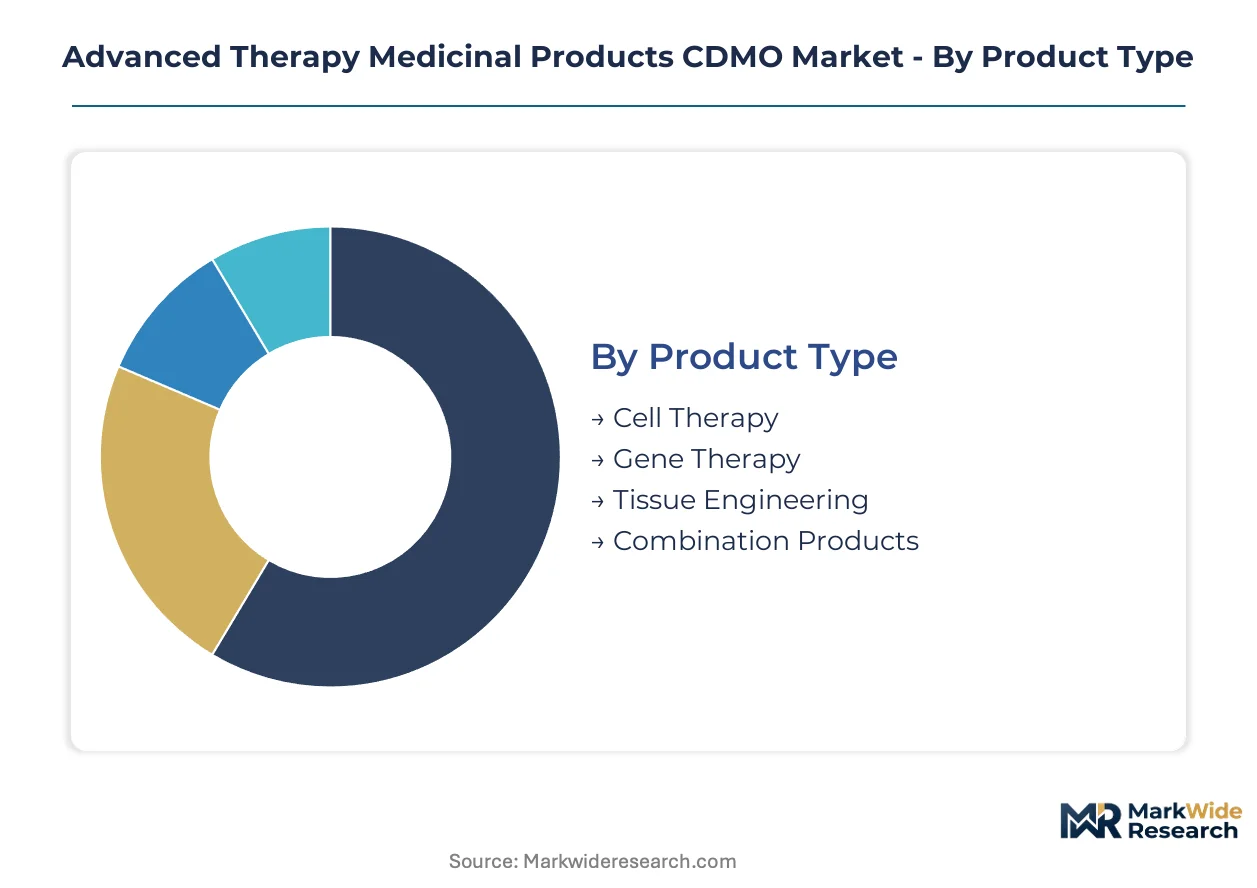
ATMP CDMO segmentation reveals distinct capability requirements across manufacturing modalities. Each category carries different regulatory validation burdens and capital intensity thresholds that shape outsourcing decisions.
Product Type:
Cell therapy manufacturing demands FDA CBER and EMA CAT inspections for autologous processes, while gene therapy suites require Biosafety Level 2-plus containment certification.
- Cell Therapy:Patient-derived starting materials require vein-to-vein logistics coordination and apheresis center networks. Demand concentrates in the United States and Germany where autologous CAR-T approvals have created specialized cleanroom shortages.
- Gene Therapy:Viral vector production using AAV and lentiviral platforms requires dedicated HVAC segregation and single-use bioreactor trains. Sponsors in Japan and the United States are locking in multi-year capacity agreements before clinical proof-of-concept.
- Tissue Engineering:Scaffold-based products combine biological and synthetic materials under combined ATMP-medical device frameworks.
- Combination Products:Integrated delivery systems face dual jurisdiction from biologics and device regulators.
Cell therapy sits at the top of the volume ranking, with gene therapy climbing the fastest.
Service Type:
Service tiers stratify by margin profile, with regulatory support commanding premiums due to specialized expertise scarcity.
- Process Development:Cell line engineering and upstream optimization for suspension-based AAV platforms. Biopharmaceutical sponsors in Germany and Japan are consolidating contracts with partners controlling both development and commercial supply.
- Manufacturing:GMP production spans clinical through commercial scales with batch-release accountability. United States-based gene therapy developers prioritize CDMOs with established BLA submission track records.
- Quality Control:Potency assays and vector copy number specifications require qPCR and ddPCR platform standardization.
- Regulatory Support:CMC documentation and agency interaction management for accelerated approval pathways.
Manufacturing captures the largest revenue share, with regulatory support expanding most quickly as EMA guidelines harden.
Technology:
Technology platforms differentiate by supply chain control points, with plasmid DNA emerging as a margin-critical bottleneck.
- Viral Vectors:AAV and lentiviral production dominates R&D allocations across the United States, Germany, and Japan. Suspension-based platforms are displacing adherent systems, compressing cost structures and enabling commercial scale previously inaccessible.
- Plasmid DNA:Transfection-grade production capacity concentrates among limited suppliers, creating pull-through demand for integrated CDMOs. Japanese and German sponsors face particular constraints in securing GMP-grade inputs for Phase III campaigns.
- CRISPR:Gene editing reagents require specialized containment and off-target validation protocols.
- Stem Cells:Allogeneic master cell bank infrastructure enables batch economies that autologous processes cannot achieve.
Viral vectors lead current capacity deployment, with plasmid DNA gaining share fastest as stable producer cell lines reduce input dependencies.
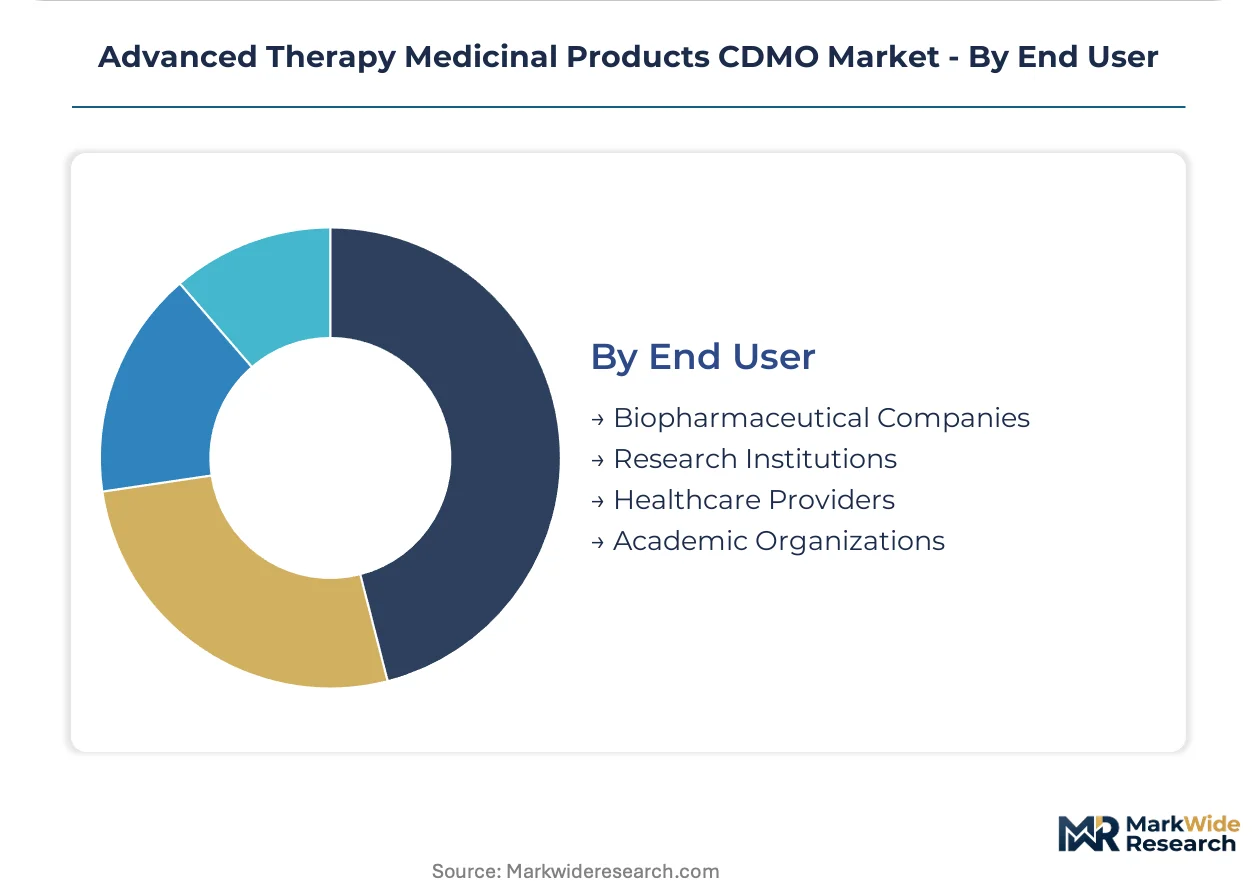
End User:
End user categories separate by internal manufacturing ambition and regulatory sophistication.
- Biopharmaceutical Companies:Large-cap developers are adopting stable AAV producer lines and consolidating manufacturing contracts with single partners. United States sponsors dominate outsourcing volume, with Japanese developers accelerating partnerships following PMDA harmonization.
- Research Institutions:Early-stage programs require flexible clinical-scale capacity with minimal batch size commitments.
- Healthcare Providers:Academic medical centers with in-house GMP facilities serve regional patient access programs.
- Academic Organizations:Investigator-initiated trials need cost-effective access to shared manufacturing platforms.
Biopharmaceutical companies anchor demand volume, with research institutions showing the steepest expansion trajectory as translation funding increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell and gene therapy manufacturing originated in academic medical centers across the United States before commercial CDMO infrastructure consolidated around Boston, San Francisco, and Basel. The current geography reflects this legacy, with capacity clustering near regulatory agencies and venture capital pools that funded first-generation platforms.
United States
FDA CBER's regenerative medicine advanced therapy designation compresses development timelines and pushes sponsors toward partners with established inspection histories. The Boston-Cambridge corridor hosts the densest concentration of viral vector manufacturing capacity, while Maryland's proximity to FDA headquarters attracts regulatory-focused service providers. California's Bay Area anchors gene therapy process development expertise.
Germany
EMA's Committee for Advanced Therapies imposes batch-release requirements that differ from FDA standards, forcing dual-validation investments for global programs. The Rhine-Main region around Frankfurt concentrates plasmid DNA production capacity, while Bavaria's Munich cluster specializes in autologous cell therapy logistics. German sponsors face particular constraints in securing GMP-grade inputs for Phase III campaigns.
Japan
PMDA's Sakigake designation framework for regenerative medicines creates demand for CDMOs with local regulatory experience and fill-finish partnerships. The Kanto region around Tokyo hosts the majority of domestic viral vector capacity, while Osaka's Kansai cluster specializes in induced pluripotent stem cell manufacturing. Japanese developers are accelerating outsourcing partnerships following regulatory harmonization with FDA standards.
Switzerland
Swissmedic's alignment with EMA procedures enables seamless European market access for products manufactured in Basel and Zurich. The country's pharmaceutical heritage supports specialized containment infrastructure for biosafety level 2-plus operations. Geneva's proximity to WHO headquarters facilitates standards-setting participation for emerging gene therapy platforms.
United Kingdom
MHRA's post-Brexit regulatory autonomy has created divergence from EMA batch-release requirements, complicating cross-border supply chains for London-based developers. The Golden Triangle between London, Oxford, and Cambridge retains concentration in early-stage process development. Cell and gene therapy manufacturing investment has shifted toward dedicated facilities in Stevenage and Braintree.
Advanced Therapy Medicinal Products CDMO Market Key Industry Players
The competitive structure tilts toward integrated platform providers with regulatory track records. Three tiers have emerged: global diversified CDMOs with viral vector and cell therapy capabilities, regional specialists concentrating on single modalities, and emerging entrants backed by private equity capacity buildouts. Consolidation pressure intensifies as sponsors demand end-to-end accountability from process development through commercial supply. Capacity expansion and strategic partnerships represent the dominant competitive moves, with multi-year capacity lock-ins reshaping competitive positioning before clinical proof-of-concept.
Within the integrated platform tier, Lonza, Samsung Biologics, and Fujifilm Diosynth occupy positions that exemplify divergent strategic archetypes. Lonza represents the established European model with regulatory depth across FDA and EMA jurisdictions. Samsung Biologics anchors the scale-driven Asian competitive position through massive bioreactor infrastructure. Fujifilm Diosynth exemplifies Japanese-backed diversification into end-to-end gene therapy services spanning process development through commercial fill-finish.
| Leading Market Players |
|---|
| WuXi Advanced Therapies |
| Fujifilm Diosynth |
| Samsung Biologics |
| Avid Bioservices |
| Minaris Advanced Therapies |
| Lonza |
| AGC Biologics |
| Rentschler Biopharma |
| Catalent |
| Others |
Cost & Logistics Intelligence
Regulatory certification tiers split CDMO service pricing into sharply divergent bands, with FDA CBER-inspected facilities commanding premiums that reflect both compliance infrastructure costs and sponsor risk mitigation. This bifurcation concentrates supply chain investments in the United States, Germany, and Japan where containment infrastructure and batch-release expertise justify higher service fees.
Pricing Analysis
Bundled end-to-end contracts versus unbundled discrete services define the dominant pricing split in ATMP manufacturing. Premium tiers attach to partners with established BLA submission track records and dual FDA-EMA inspection histories, while standard tiers serve clinical-phase programs with lighter regulatory burdens. Price differentiation rests on vector platform sophistication and cold-chain logistics integration. Cost compression in standard-tier viral vector production is intensifying as suspension-based platforms displace adherent systems. Emerging biopharmaceutical sponsors exhibit highest price sensitivity, prioritizing capacity access over regulatory depth.
Supply Chain Analysis
Freight costs for patient-derived autologous materials dominate logistics expenditure, with vein-to-vein cold-chain requirements constraining site selection to apheresis center proximity. Supply concentrates in the United States, Germany, and Japan where GMP-grade plasmid DNA production faces acute scarcity. Raw material dependencies center on transfection-grade plasmids, single-use bioreactor consumables, and specialized cell culture media. Single-source vulnerability runs through plasmid DNA suppliers, exposing Phase III campaigns to input bottlenecks. Distribution runs through integrated CDMO networks controlling both manufacturing execution and quality release.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ATMP CDMO market functions as a regulatory compounder where FDA's regenerative medicine advanced therapy designation compresses timelines and multiplies capacity scarcity premiums. This dynamic rewards early-mover investments in containment infrastructure and agency inspection histories.
For Market Incumbents: Cement regulatory moats through backward integration into plasmid DNA production and expansion of dual-jurisdiction batch-release capabilities. Emerging entrants backed by private equity capacity buildouts threaten regional specialists lacking end-to-end service depth. Priority leverage sits in master cell bank infrastructure for allogeneic platforms, creating switching costs that lock sponsors through commercial scale-up.
For New Entrants and Emerging Players: Begin with tissue engineering and combination product segments where combined ATMP-medical device frameworks have deterred larger CDMO investment. Japan's PMDA harmonization creates penetrable white space for partners with Sakigake designation experience and local fill-finish alliances. Go-to-market positioning should emphasize digital supply chain integration and blockchain-enabled chain-of-identity systems as differentiated service layers.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists controlling viral vector platforms in supply-constrained geographies. Long-term viability favors targets with demonstrated CBER inspection histories and stable AAV producer cell line capabilities. Watch vector immunogenicity threshold revisions as the inflection signal determining which manufacturing platforms warrant capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA CBER inspection history accelerates sponsor BLA submissions and locks multi-year contracts. |
| Manufacturing Scale-Up | Suspension-based AAV platforms enable commercial batch sizes previously inaccessible to mid-scale facilities. |
| Backward Integration | In-house plasmid DNA production secures margin-critical inputs and reduces Phase III campaign risk. |
| Strategic Partnership | Apheresis center networks create vein-to-vein logistics capabilities that sponsors cannot replicate internally. |
| Geographic Expansion | PMDA Sakigake experience opens Japan's accelerated approval framework for regenerative medicines. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell therapy process development leads, regulatory affairs directors at gene therapy sponsors, viral vector manufacturing heads, and CBER compliance officers with secondary validation against FDA BLA submissions, EMA CAT meeting minutes, ClinicalTrials.gov records, and GMP inspection databases. Bottom-up capacity utilization models and top-down sponsor outsourcing spend estimates were triangulated to anchor market sizing.
Historical reference periods spanning commercial ATMP approvals through accelerated designation expansions anchored the forecast window. Segmentation modeling incorporated product type, service tier, vector platform technology, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from sponsor pipeline progression rates and CDMO capacity expansion announcements. Forecast inputs included vector copy number assay standardization timelines and stable producer cell line adoption curves.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on durability data requirements and disruptive gene editing platform shifts that could obsolete existing viral vector infrastructure. Forecasts reflect documented assumptions about sponsor consolidation behavior and capacity lock-in timing. Stakeholders should weight assumptions against their own operating context and monitor EMA guideline revisions for comparability demonstration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
APAC Pharmaceutical Warehousing Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Global Viral Vaccines Market