
 Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market | 2026-2036
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market Foresight
Project finance for late-stage oncology supportive-care assets is tilting competitive dynamics toward developers with access to specialized healthcare credit facilities. Pfizer Inc. leverages its established hospital formulary relationships to secure preferential placement for combination antiemetic therapies. Heron Therapeutics Inc. sustains differentiation through extended-release delivery platforms that reduce administration frequency in outpatient settings.
Chemotherapy-induced nausea and vomiting encompasses the acute and delayed emetic responses triggered by cytotoxic agents, managed through prophylactic regimens combining serotonin receptor blockade, substance P inhibition, and corticosteroid modulation to protect nutritional status and treatment adherence. NK1 receptor antagonists command premium positioning in delayed CINV prophylaxis where standard 5-HT3 monotherapy proves insufficient. Oncology clinics represent the fastest-growing end-user channel as same-day chemotherapy administration shifts volume away from inpatient wards.
The FDA maintains stringent efficacy thresholds for breakthrough CINV indications, while the EMA's MDR framework imposes enhanced pharmacovigilance on combination antiemetic devices. Japan's PMDA evaluates novel antiemetics against region-specific chemotherapy regimens that differ from Western protocols. Stakeholders must monitor evolving payer criteria for prophylactic versus rescue therapy reimbursement as value-based oncology contracts expand.
Market Dynamics
The transition from inpatient to outpatient chemotherapy administration is restructuring antiemetic demand toward extended-release formulations and single-dose prophylactic regimens that reduce nursing burden and same-day return visits.
Growth Catalysts
- Outpatient oncology expansion:Same-day chemotherapy protocols in United States cancer centers are driving demand for long-acting antiemetic injections that eliminate multi-day oral compliance requirements.
- REACH MDR framework:Enhanced pharmacovigilance mandates for combination drug-device products in Europe are accelerating adoption of pre-validated antiemetic delivery systems with integrated safety monitoring.
- Substance P receptor science:Improved understanding of neurokinin-1 pathway modulation is expanding prophylactic use of NK1 antagonists beyond high-emetic-risk regimens into moderate-risk protocols.
Market Restraints
- API supply concentration:Manufacturing of granisetron and palonosetron active pharmaceutical ingredients concentrates in Chinese and Indian chemical clusters, exposing formulators to geopolitical trade friction and import inspection delays.
- Reimbursement compression:United States Medicare Part B payment limits for supportive oncology drugs are squeezing margin on combination antiemetic regimens relative to standalone 5-HT3 monotherapy.
- Generic 5-HT3 saturation:Patent expiration of first-generation serotonin antagonists has flooded oncology formularies with low-cost ondansetron alternatives that anchor price expectations for premium delayed-emesis prophylaxis.
Strategic Opportunities
- Japan PMDA pathway:Region-specific chemotherapy protocols including S-1 and oral fluoropyrimidine regimens create demand for antiemetic efficacy data packages distinct from Western IV-centric trials.
- Home infusion nursing:Expansion of ambulatory infusion suites and home-based chemotherapy administration is opening channel access for patient-administered transdermal or subcutaneous antiemetic platforms.
- ISO 13485 device convergence:Integration of antiemetic reservoirs with smart infusion pumps enables closed-loop nausea detection and automated rescue dosing in outpatient settings.
Industry Challenges
- Clinical trial design complexity:Demonstrating superiority over guideline-recommended triple-therapy prophylaxis requires large patient populations and standardized emesis assessment protocols that extend development timelines.
- Formulary access negotiation:Pharmacy and therapeutics committees in United States hospital systems demand real-world adherence data and total-cost-of-care analyses before granting preferred status to novel antiemetic mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market |
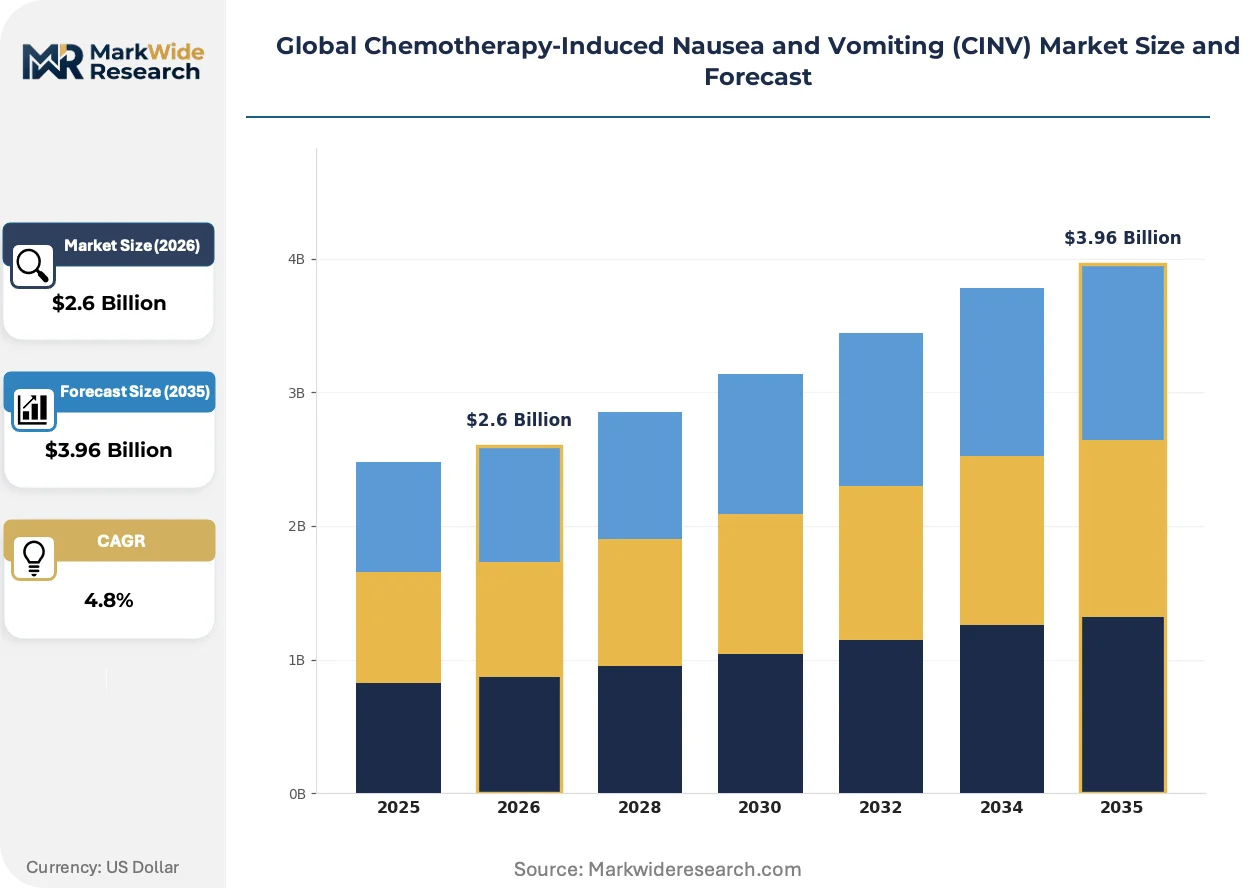
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $3.96 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5-HT3 Receptor Antagonists, NK1 Receptor Antagonists, Corticosteroids, Dopamine Antagonists, Others Therapy Area: Acute CINV, Delayed CINV, Anticipatory CINV, Breakthrough CINV End User: Hospitals, Oncology Clinics, Cancer Research Centers, Outpatient Facilities Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Hospital Procurement |
| Companies Covered | Pfizer Inc., Roche Holding AG, Merck & Co. Inc., GlaxoSmithKline plc, Novartis AG, AbbVie Inc., Helsinn Holding S.A., Heron Therapeutics Inc., Teva Pharmaceuticals Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market Shifts & Advancements
Antiemetic development is pivoting from receptor pharmacology toward delivery system innovation that compresses dosing frequency and integrates with existing chemotherapy infusion workflows.
Extended-release polymer depot formulations of 5-HT3 and NK1 antagonists are collapsing the distinction between acute and delayed emesis prophylaxis by maintaining therapeutic plasma concentrations across the full 120-hour post-chemotherapy window. Oncology clinics in the United States are adopting these platforms to eliminate the need for patient self-administration of oral rescue medications during weekends. The structural consequence is a reduction in breakthrough CINV episodes that previously drove emergency department utilization and treatment delays.
EMA's Medical Device Regulation is reclassifying combination antiemetic injector systems as Class III devices, requiring clinical evidence of delivery reliability equivalent to drug efficacy data. Manufacturers with existing drug-device submissions under the prior directive face supplemental validation studies for needle safety mechanisms and dose accuracy. German and French notified bodies are prioritizing review capacity for oncology supportive care devices, compressing approval timelines for European market entry relative to other therapeutic categories.
Oncology group purchasing organizations are consolidating antiemetic procurement across health system networks, replacing individual hospital formulary decisions with standardized protocols negotiated at the enterprise level. This concentration is displacing local pharmacy-driven preference for familiar generic compounds in favor of performance-guaranteed contracts with outcomes-based rebate structures. The shift is most visible in United States integrated delivery networks where pharmacy spend accountability now resides with chief financial officers rather than clinical pharmacy directors.
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market Segmentation
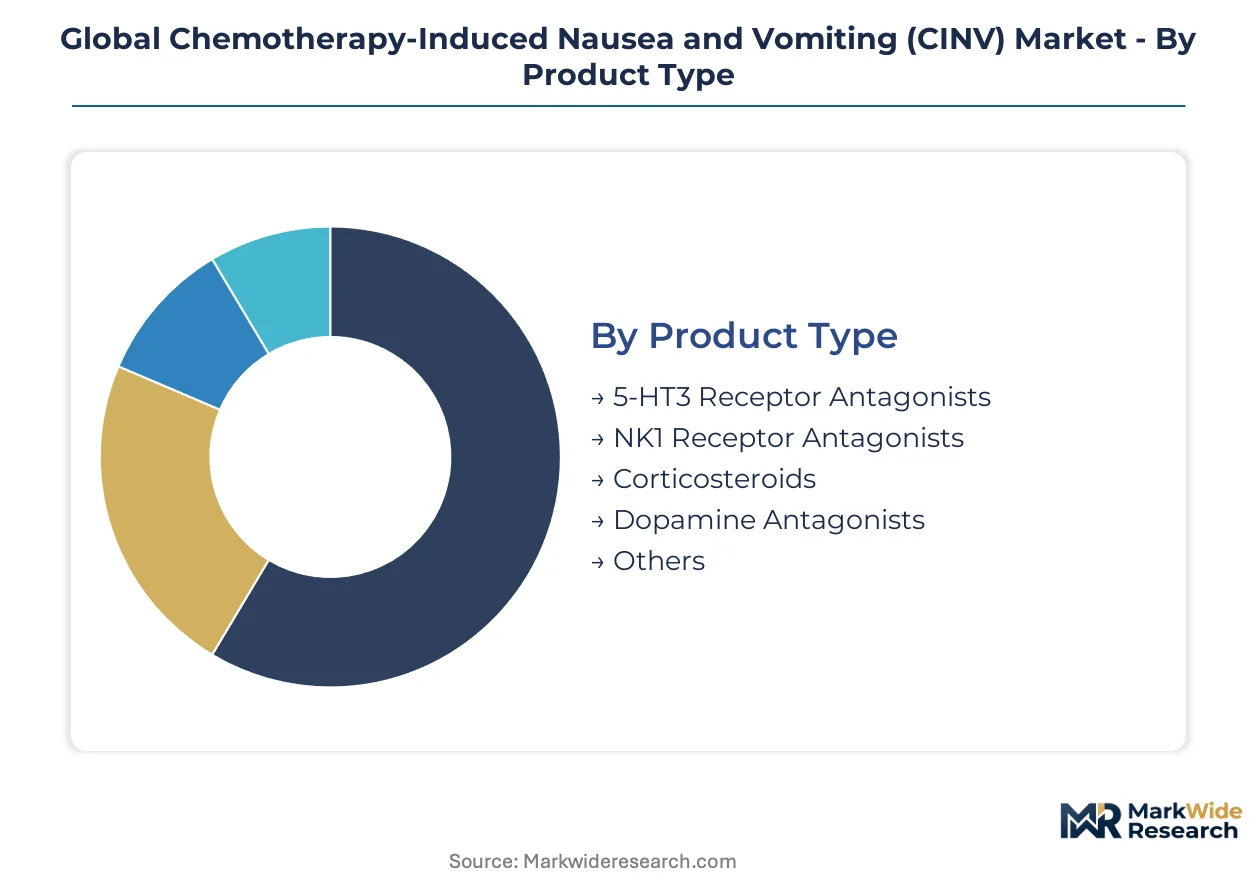
Segmentation in the CINV market reveals distinct procurement cycles across product categories and care settings. Oncology clinics turn over antiemetic inventory faster than hospital wards due to same-day chemotherapy protocols. Understanding velocity differences helps manufacturers align supply contracts with actual consumption patterns.
Product Type:
Serotonin receptor antagonists rotate through formularies most rapidly as generic ondansetron pressures pricing, while NK1 antagonists maintain longer replacement cycles due to patent protection and premium positioning.
- 5-HT3 Receptor Antagonists:First-line prophylactic agents blocking serotonin at peripheral and central receptors. Demand concentrates in United States outpatient infusion centers where palonosetron's extended half-life reduces nursing administration burden compared to first-generation alternatives.
- NK1 Receptor Antagonists:Substance P pathway inhibitors administered alongside 5-HT3 blockers for delayed emesis control. Oncology clinics in Germany and France prioritize oral aprepitant formulations that eliminate weekend return visits for IV rescue therapy.
- Corticosteroids:Dexamethasone-based protocols modulating inflammatory mediators in acute-phase response.
- Dopamine Antagonists:Metoclopramide and prochlorperazine compounds reserved for breakthrough rescue scenarios.
- Others:Olanzapine and cannabinoid derivatives addressing refractory cases.
5-HT3 antagonists dominate installed base across oncology formularies. NK1 receptor blockers represent where expansion concentrates as delayed CINV protocols standardize.
Therapy Area:
Cost tier stratification separates acute-phase prophylaxis—commoditized by generic saturation—from anticipatory and breakthrough categories commanding premium pricing for unmet need.
- Acute CINV:Emesis occurring within 24 hours of chemotherapy administration, typically managed with 5-HT3 monotherapy. United States cancer centers in Texas and Florida favor single-dose IV granisetron for same-day discharge protocols.
- Delayed CINV:Nausea and vomiting manifesting 24-120 hours post-treatment, driven by substance P release. Japanese oncology practices treating S-1 regimens require distinct efficacy data packages from Western IV-centric trials.
- Anticipatory CINV:Conditioned response before chemotherapy exposure, addressed through behavioral intervention and anxiolytic adjuncts.
- Breakthrough CINV:Emesis despite prophylaxis, triggering rescue medication protocols.
Acute CINV commands the largest prescription volume. Delayed CINV is climbing the fastest as combination prophylaxis protocols expand into moderate-emetic-risk regimens.
End User:
Customer type determines formulary decision-making structure—hospital pharmacy committees versus clinic medical directors with direct procurement authority.
- Oncology Clinics:Ambulatory infusion centers administering same-day chemotherapy with extended-release antiemetic platforms. United States networks in California and New York are consolidating procurement through group purchasing organizations that standardize protocols across enterprise systems.
- Hospitals:Inpatient wards managing high-emetic-risk regimens with multi-day admission protocols. German university hospitals maintain dedicated oncology pharmacy units with compound preparation capabilities.
- Cancer Research Centers:Academic institutions conducting investigator-initiated trials of novel antiemetic mechanisms.
- Outpatient Facilities:Community-based infusion suites and home nursing services.
Hospitals retain the deepest formulary penetration. Oncology clinics are gaining share fastest as chemotherapy administration shifts away from inpatient wards.
Distribution Channel:
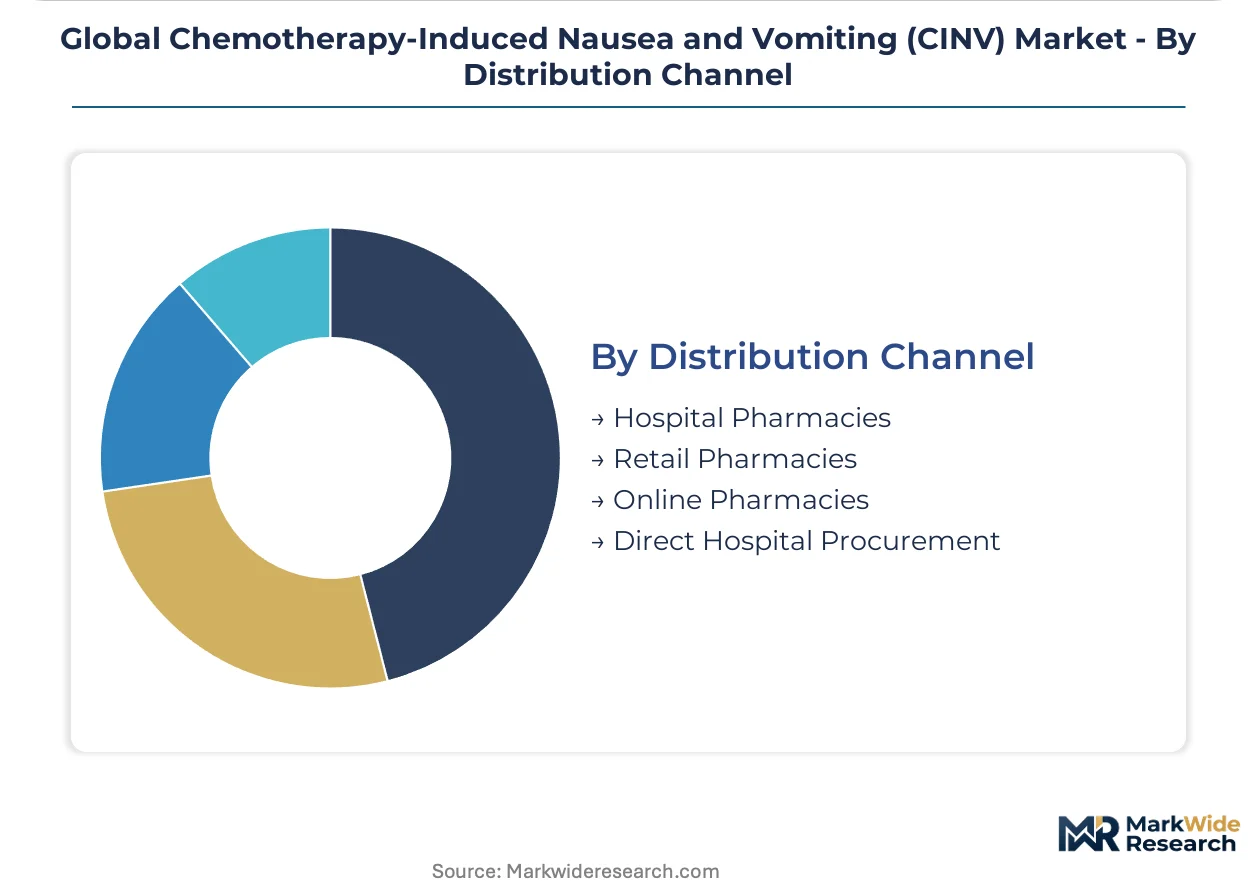
Supply concentration differs by channel—hospital procurement leverages volume contracting while retail and online channels fragment demand across individual prescriptions.
- Direct Hospital Procurement:Enterprise-level contracting between health systems and antiemetic manufacturers. United States integrated delivery networks in Pennsylvania and Ohio negotiate performance-guaranteed agreements with outcomes-based rebate structures.
- Hospital Pharmacies:Captive dispensing within oncology wards and infusion centers. French public hospital systems operate centralized pharmacy units with robotic compounding for sterile antiemetic preparations.
- Retail Pharmacies:Community dispensing of oral rescue medications for delayed-phase self-administration.
- Online Pharmacies:Mail-order distribution for maintenance antiemetic supplies.
Direct hospital procurement captures the highest-value contracts. Hospital pharmacies represent where volume expansion concentrates as outpatient protocols extend into home-based administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in antiemetic APIs concentrate manufacturing capacity in Asian chemical clusters while formulation and commercialization gravitate toward Western oncology markets. The United States maintains the deepest negative trade balance in finished dosage forms, importing extended-release injectable platforms from European contract manufacturers. Germany and Switzerland anchor European export capacity for high-potency NK1 antagonist synthesis.
United States
Outpatient chemotherapy administration in Texas and Florida cancer centers drives demand for single-dose IV granisetron protocols that eliminate weekend return visits. FDA guidance on supportive oncology care tightens efficacy benchmarks for new antiemetic approvals, extending clinical development timelines for novel mechanisms. The Philadelphia-Wilmington corridor hosts specialized healthcare credit facilities that project finance late-stage oncology supportive-care assets.
Germany
German university hospitals maintain dedicated oncology pharmacy units with robotic compounding capabilities for sterile antiemetic preparations. EMA's MDR framework reclassifies combination antiemetic injector systems as Class III devices, requiring supplemental validation studies for needle safety mechanisms. The Rhine-Main cluster around Frankfurt concentrates notified body review capacity, compressing approval timelines for oncology supportive care devices relative to other therapeutic categories.
Japan
Japanese oncology practices treating S-1 and oral fluoropyrimidine regimens require antiemetic efficacy data packages distinct from Western IV-centric trials. PMDA evaluates novel antiemetics against region-specific chemotherapy protocols that differ from North American and European standards. The Kanto region around Tokyo anchors domestic formulation manufacturing for extended-release platforms adapted to ambulatory care expansion.
India
Indian chemical clusters concentrate active pharmaceutical ingredient production for granisetron and palonosetron, exposing global formulators to geopolitical trade friction and import inspection delays. CDSCO maintains alignment with ICH guidelines for antiemetic clinical trial design while imposing additional stability testing requirements for tropical climate zones. The Hyderabad-Bengaluru pharmaceutical corridor supplies generic 5-HT3 antagonists that anchor price expectations in emerging markets.
Switzerland
Swissmedic oversees pharmacovigilance for combination antiemetic therapies distributed through European hospital networks. The Basel-Zurich corridor hosts contract manufacturing organizations specializing in high-potency NK1 antagonist synthesis for global supply. Swiss private equity participation in oncology supportive care assets has accelerated since 2023, targeting extended-release delivery platforms with integrated safety monitoring capabilities.
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market Competitive Landscape
On the supply side, the industry is consolidating around developers with integrated drug-device capabilities and established hospital formulary relationships. Large-cap pharmaceutical companies leverage global manufacturing scale and existing oncology portfolios to secure preferential placement for combination antiemetic therapies. Mid-cap specialists differentiate through extended-release delivery platforms and region-specific regulatory expertise. Competitive dynamics center on formulary access negotiation and outcomes-based contracting with integrated delivery networks.
Among large-cap developers, Pfizer Inc. and Roche Holding AG occupy positions anchored by established hospital procurement relationships and broad oncology portfolios. Heron Therapeutics Inc. exemplifies the mid-cap specialist archetype, sustaining differentiation through platform technologies that reduce administration frequency. Merck & Co. Inc. and Novartis AG sit within the diversified pharmaceutical tier, leveraging cross-portfolio synergies in supportive oncology care. These groupings reflect strategic positioning around delivery innovation, regulatory navigation, and channel access rather than molecule differentiation alone.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Roche Holding AG |
| Merck & Co. Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| AbbVie Inc. |
| Helsinn Holding S.A. |
| Heron Therapeutics Inc. |
| Teva Pharmaceuticals Industries Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Indian and Chinese API manufacturing clusters is compressing supplier margins while amplifying price competition for generic 5-HT3 antagonists, forcing formulators to consolidate procurement volumes or pivot toward patent-protected NK1 combination therapies to defend pricing power.
Pricing Analysis
Oncology group purchasing organizations anchor three-tier pricing structure across premium, standard, and economy levels in United States hospital systems, with extended-release injectable platforms commanding premium positioning against commoditized ondansetron tablets. Price differentiation hinges on FDA approval tier and volume commitment scale, with integrated delivery networks extracting steepest discounts through outcomes-based rebate structures. Pricing pressure stems from Medicare Part B reimbursement compression, squeezing margin on combination regimens relative to standalone serotonin antagonist monotherapy. Community oncology clinics exhibit highest price sensitivity due to thin operating margins, while academic medical centers with captive pharmacy compounding capabilities demonstrate lowest sensitivity.
Supply Chain Analysis
Export control restrictions on high-potency pharmaceutical manufacturing equipment limit capacity expansion in emerging markets, concentrating active pharmaceutical ingredient production for granisetron and palonosetron in Hyderabad-Bengaluru and Zhejiang chemical corridors. Formulation draws from Chinese chemical intermediates, Indian API synthesis, and European contract manufacturing for sterile injectable finishing. Single-source vulnerability runs through concentrated granisetron precursor supply. Distribution runs through oncology group purchasing organizations consolidating enterprise-level procurement across United States health system networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CINV market is approaching a platform-economics inflection as smart infusion pump integration and closed-loop dosing algorithms transform antiemetics from discrete pharmaceuticals into embedded care system components.
For Market Incumbents: Entrench formulary position through backward integration into extended-release polymer depot manufacturing, capturing margin that currently leaks to contract development partners. Lock in multi-year performance-guaranteed contracts with United States integrated delivery networks before pharmacy spend accountability fully shifts to chief financial officers. Prioritize ISO 13485 certification investment for combination drug-device platforms as EMA MDR reclassification accelerates. For New Entrants and Emerging Players: Build out region-specific efficacy data packages for Japan PMDA submissions targeting S-1 and oral fluoropyrimidine regimens, where Western IV-centric trial data holds limited relevance. Penetrate home infusion nursing channels with patient-administered transdermal or subcutaneous platforms as ambulatory chemotherapy administration expands beyond clinic walls. Pursue licensing partnerships with established oncology supportive care portfolios to bypass hospital formulary access barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with extended-release delivery platforms locked into multi-cycle chemotherapy protocols, generating predictable refill demand across 4-6 month treatment courses. Target acquisition archetypes combine drug-device integration capabilities with established GPO contracting relationships. Watch for inflection signals in United States outpatient chemotherapy volume share crossing threshold levels that trigger enterprise formulary standardization mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Platform Development | Collapses acute and delayed prophylaxis into single-dose regimens reducing nursing burden in outpatient settings. |
| Drug-Device Combination Submission | EMA MDR Class III reclassification requires clinical evidence of delivery reliability equivalent to drug efficacy. |
| Japan-Specific Efficacy Package | PMDA evaluation against S-1 regimens opens access to distinct chemotherapy protocol market. |
| Home Infusion Channel Partnership | Ambulatory expansion beyond clinic walls creates patient-administered platform opportunity. |
| Outcomes-Based GPO Contracting | Performance guarantees with integrated delivery networks displace local pharmacy-driven generic preference. |
Research Methodology
Cross-validation between primary interviews with hospital formulary directors, oncology pharmacy managers, and payer access specialists and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement database extracts anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing across product type, therapy area, end user, and distribution channel dimensions.
Calibration against historical approval timelines and reimbursement decision patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include receptor antagonist class, emesis phase indication, administration route, and regional regulatory cluster. CAGRs derive from patient volume projections tied to chemotherapy protocol expansion and antiemetic prophylaxis penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mid-cap specialists with platform technology acquisitions would shift outcomes. Material shifts in United States Medicare Part B reimbursement methodology or API import inspection protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Injectable Ketamine Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Anthelmintic Drugs Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market