
 Advanced Therapy Medicinal Products (Atmps) Market | 2026-2036
Advanced Therapy Medicinal Products (Atmps) Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Therapy Medicinal Products (Atmps) Market Outlook
Oncology centers are bifurcating the ATMP demand base away from traditional hospital infusion suites. Novartis AG dominates CAR-T manufacturing scale through in-house vector production capabilities. Gilead Sciences anchors its position via Kite Pharma's established autologous cell therapy infrastructure. Bristol-Myers Squibb differentiates through diversified modalities spanning both cell and gene therapy platforms.
Advanced Therapy Medicinal Products comprise gene therapies, cell therapies, tissue-engineered products, and regenerative medicines manufactured using viral vectors, patient-derived cellular material, or scaffold-based constructs, with specifications requiring cryopreservation protocols and chain-of-identity tracking throughout the supply chain. Cell therapy leads commercial value generation due to the concentration of approved autologous CAR-T products, while gene therapy represents the fastest-expanding segment driven by adeno-associated vector platforms for monogenic disorders. Oncology commands the dominant application share, though rare diseases attract premium reimbursement structures.
The FDA's regenerative medicine advanced therapy designation compresses development timelines, while EMA's ATMP classification framework harmonizes market access pathways across EU member states. The EU AI Act introduces algorithmic scrutiny for computational tools used in cell manufacturing quality control. Stakeholders must monitor how evolving payer evidence requirements for single-administration curative therapies reshape commercialization strategies.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation compresses clinical development timelines, reshaping how manufacturers allocate capital between process development and commercial infrastructure. This regulatory acceleration concentrates investment in viral vector capacity and cryogenic logistics networks.
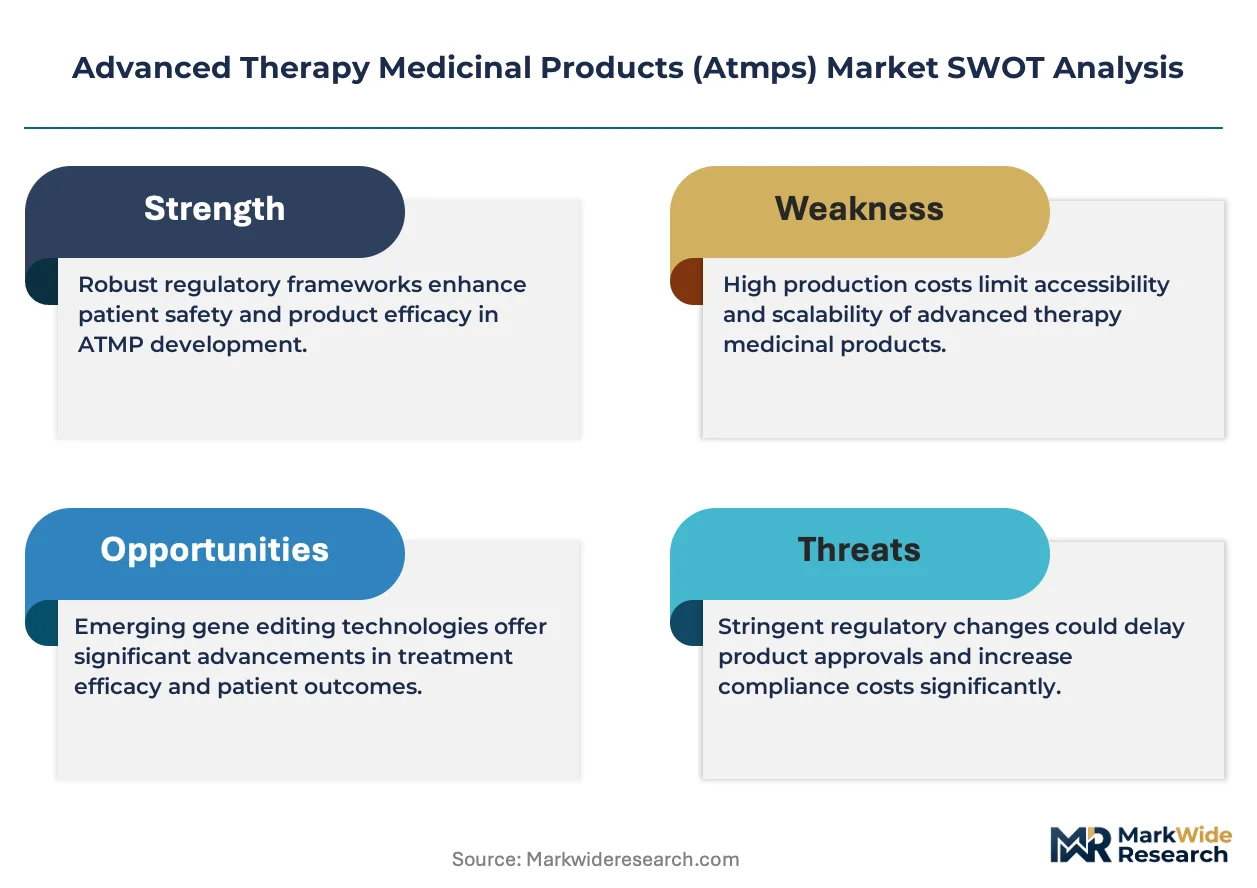
Growth Catalysts
- EMA's ATMP Classification Framework:Harmonized market access pathways across EU member states reduce regulatory duplication costs for cross-border therapy distribution. Manufacturers leverage this structure to centralize manufacturing in Belgium and the Netherlands.
- Oncology Center Expansion:Specialty clinics in the United States deploy dedicated CAR-T infusion suites, decoupling advanced therapy administration from general hospital infrastructure. This channel expansion broadens patient access beyond academic medical centers.
- Allogeneic Cell Platforms:Off-the-shelf cell therapy manufacturing is displacing autologous collection logistics, compressing vein-to-vein timelines from weeks to days. Platform standardization enables economies of scale previously unattainable in personalized medicine.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector production depends on a concentrated supplier base in the United States and Europe, creating single-source vulnerability for GMP-grade starting material. Price volatility in this input directly impacts COGS for gene therapy programs.
- Cryogenic Cold Chain Infrastructure:Liquid nitrogen storage and transport capacity constraints limit therapy distribution to urban corridors with established cell therapy logistics hubs. Rural and mid-market hospital systems face exclusion from curative therapy access.
- Small Molecule Oncology Substitution:Oral targeted therapies and antibody-drug conjugates compete for the same oncology reimbursement budgets, particularly in indications where cell therapy offers incremental rather than transformative benefit.
Strategic Opportunities
- Japan's Sakigake Designation System:Priority review pathways for regenerative medicines accelerate market entry timelines, creating first-mover advantages in the Asia-Pacific's second-largest pharmaceutical market. Domestic partnerships with PMDA-preferred CMOs reduce regulatory friction.
- In Vivo Gene Editing Delivery:Lipid nanoparticle and engineered viral vector convergence enables direct administration of editing machinery without ex vivo cell manipulation. This modality eliminates apheresis infrastructure requirements and expands addressable patient populations.
- Pharmacy Benefit Manager Integration:Novel reimbursement structures through specialty pharmacy networks separate therapy acquisition from administration site-of-care. This channel innovation aligns financial flows with clinical outcomes data capture.
Industry Challenges
- Vector Manufacturing Talent Scarcity:GMP-grade viral vector production requires hybrid skill sets spanning molecular biology, bioprocess engineering, and regulatory quality assurance. The limited pipeline of professionals with cross-functional ATMP experience constrains capacity expansion.
- Chain-of-Identity System Integration:Patient-specific tracking from leukapheresis through infusion demands real-time data architecture that legacy hospital IT infrastructure cannot support. Middleware development and validation timelines extend commercial readiness.
- Reimbursement Evidence Generation:Single-administration curative therapies require long-term follow-up data to justify premium pricing, yet payers demand immediate budget impact certainty. This temporal mismatch strains manufacturer cash flow during launch phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Therapy Medicinal Products (Atmps) Market |
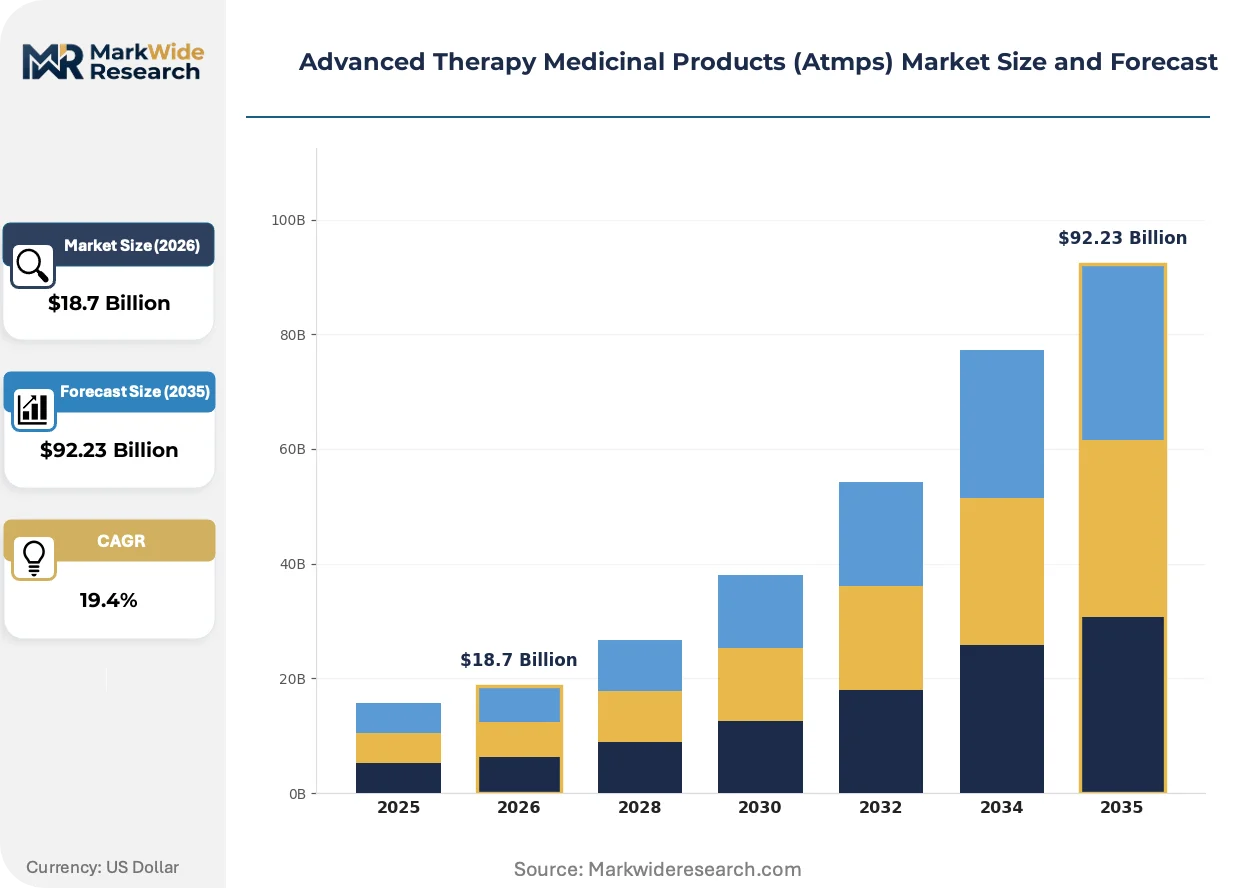
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Cell Therapy, Tissue Engineering, Regenerative Medicine Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Local Administration End User: Hospitals, Research Institutions, Specialty Clinics, Pharmaceutical Companies Application: Oncology, Cardiovascular, Neurology, Rare Diseases |
| Companies Covered | Novartis AG, Gilead Sciences, Inc., Bristol-Myers Squibb Company, Bluebird Bio, Inc., Spark Therapeutics, Inc., Vericel Corporation, UniQure N.V., Kolon TissueGene, Inc., Organogenesis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Therapy Medicinal Products (Atmps) Market Strategic Shifts
Closed-system manufacturing technologies are displacing open cleanroom operations, reducing contamination risk while enabling distributed production models that challenge centralized biologics infrastructure assumptions.
Automated cell processing platforms is miniaturizing footprint requirements for GMP-compliant manufacturing. Contract development organizations in Singapore and Switzerland deploy these systems in multi-product facilities, reducing per-batch facility overhead by enabling rapid changeover between therapy programs. This compression of physical infrastructure requirements lowers the capital barrier for regional manufacturing presence.
The EU AI Act introduces mandatory algorithmic impact assessments for machine learning tools deployed in cell therapy quality control. Manufacturers utilizing computational phenotyping or automated release testing must document training data provenance and model drift monitoring protocols. European facilities with existing digital quality systems face accelerated compliance timelines compared to greenfield implementations.
Hospital procurement committees now require real-world evidence packages alongside clinical trial data for ATMP formulary inclusion. United States oncology centers increasingly contract outcomes-based arrangements that tie reimbursement thresholds to durability of response metrics. This behavioral shift privileges manufacturers with established patient registry infrastructure and long-term follow-up capabilities.
Advanced Therapy Medicinal Products (Atmps) Market Segmentation
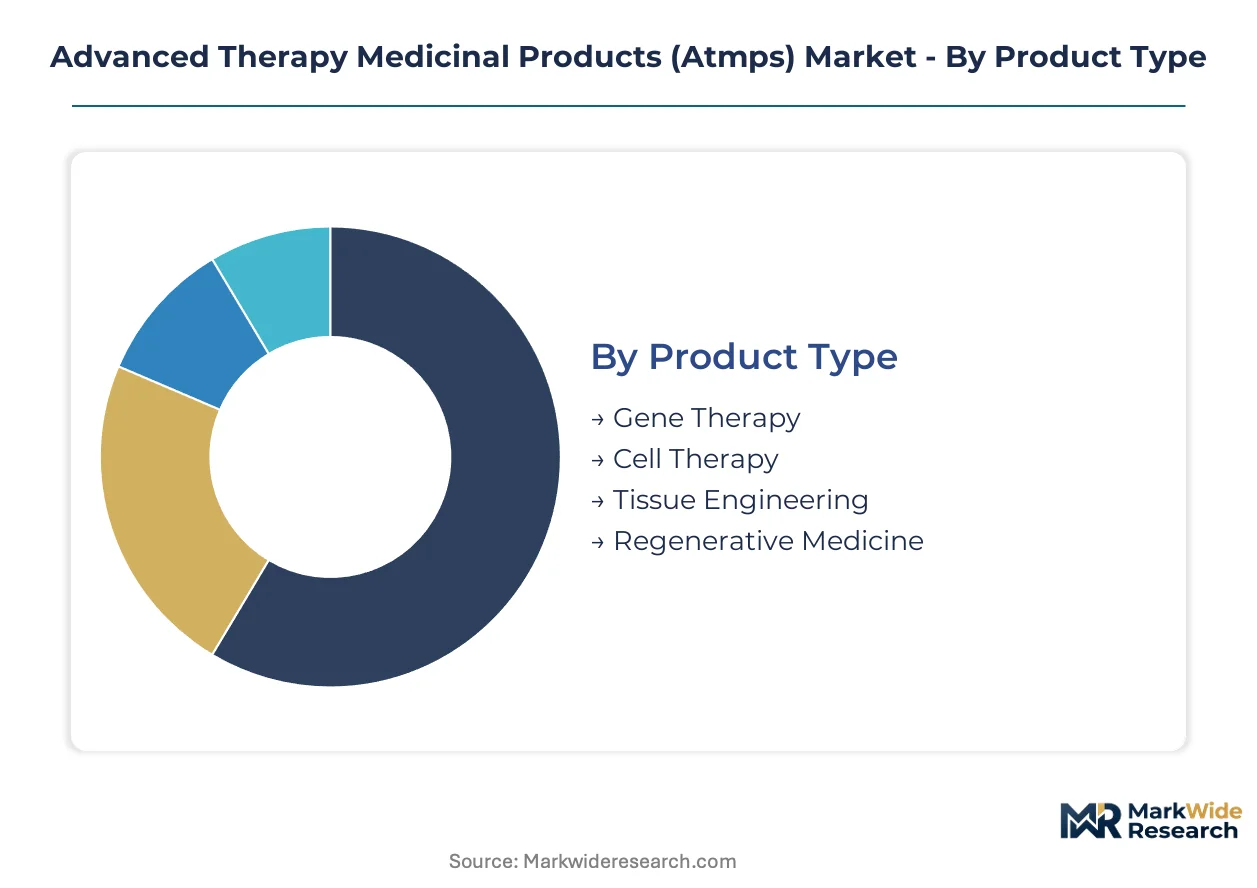
ATMP manufacturers allocate R&D capital across divergent technical platforms, each carrying distinct regulatory pathways and manufacturing infrastructure requirements. Segmentation reveals where commercial scale currently concentrates versus where pipeline innovation is redirecting investment priorities.
Product Type:
Margin pools concentrate in modalities with approved commercial products and established reimbursement codes, while pre-revenue platforms absorb development-stage capital.
- Gene Therapy:Adeno-associated viral vectors deliver functional genetic material to target tissues, with intravenous administration for monogenic disorders driving clinical trial volume. United States-based programs dominate the late-stage pipeline, though EMA's centralized approval pathway accelerates EU market entry for cross-border patient access.
- Cell Therapy:Autologous chimeric antigen receptor T-cell products require patient-specific leukapheresis, cryopreservation, and lymphodepletion protocols. Oncology centers in the United States deploy dedicated infusion suites, decoupling administration from general hospital infrastructure and expanding addressable patient populations beyond academic medical centers.
- Tissue Engineering:Scaffold-based constructs combine synthetic or biological matrices with cellular components for structural repair applications.
- Regenerative Medicine:Stem cell-derived products and tissue regeneration platforms target organ dysfunction without permanent genetic modification.
Cell therapy holds installed capacity. Gene therapy is rotating up the share rankings.
Delivery Mode:
Route selection determines manufacturing scale, cold chain requirements, and site-of-care infrastructure investment.
- Intravenous:Systemic administration via infusion enables broad biodistribution for hematologic malignancies and systemic genetic disorders. United States oncology centers standardize CAR-T infusion protocols, while hospital outpatient departments build dedicated apheresis-to-infusion workflows.
- Subcutaneous:Depot formulations and sustained-release platforms reduce administration frequency for chronic genetic conditions. Patient self-administration potential shifts cost structure from clinical site fees toward device and formulation development.
- Intramuscular:Regional delivery concentrates therapeutic effect in skeletal muscle tissue for localized genetic disorders.
- Local Administration:Direct injection into target organs or lesions minimizes systemic exposure and off-target effects.
Intravenous dominates current procedure volume. Subcutaneous is climbing the fastest as outpatient delivery models mature.
End User:
Procurement authority and reimbursement capture vary sharply across institutional categories with divergent capital allocation flexibility.
- Hospitals:Academic medical centers anchor early adoption through integrated apheresis, processing, and infusion capabilities. Medicare reimbursement for CAR-T products under the new technology add-on payment preserves margin for high-cost inpatient procedures.
- Specialty Clinics:Dedicated oncology and gene therapy centers decouple administration from general hospital infrastructure. United States-based networks expand regional footprint to reduce patient travel burden for multi-week treatment protocols.
- Research Institutions:University-affiliated medical centers conduct investigator-initiated trials and registry studies generating real-world evidence.
- Pharmaceutical Companies:Sponsor-sponsored treatment centers and compassionate use programs bridge clinical trial access and commercial launch.
Hospitals retain the majority of infused volume. Specialty clinics are gaining share fastest through focused operational models.
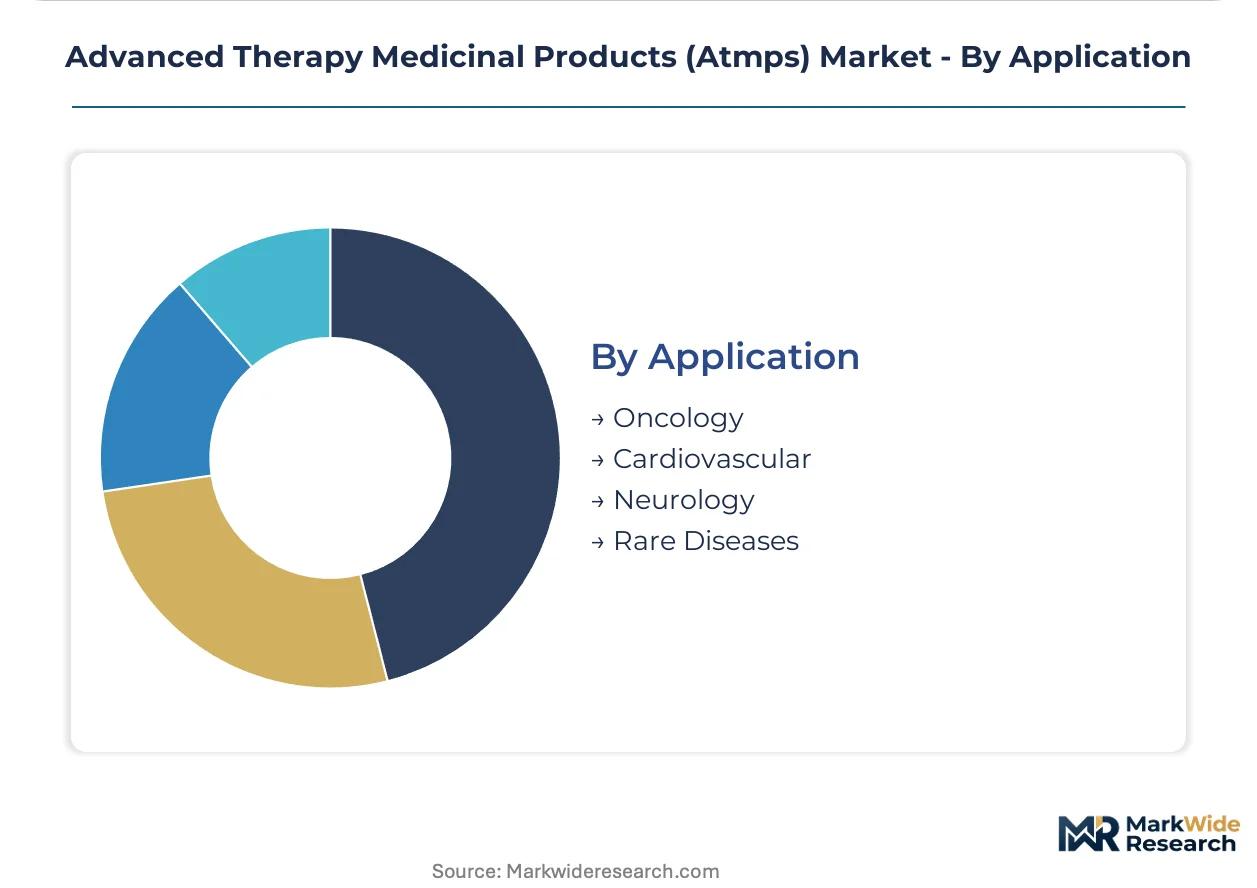
Application:
Addressable patient populations and pricing power diverge across therapeutic areas based on unmet need severity and competitive alternatives.
- Oncology:Hematologic malignancies command the dominant commercial position through approved CD19 and BCMA-directed CAR-T therapies. United States treatment centers standardize axicabtagene ciloleucel and lisocabtagene maraleucel administration protocols, while pipeline expansion targets solid tumor indications with novel antigen targets.
- Rare Diseases:Monogenic disorders with no existing therapeutic alternatives justify premium pricing and accelerated regulatory pathways. EMA's priority medicines designation and FDA's regenerative medicine advanced therapy designation compress development timelines for ultra-rare indications.
- Cardiovascular:Ischemic heart failure and peripheral vascular disease programs leverage autologous cell delivery for tissue regeneration.
- Neurology:Central nervous system delivery challenges, including blood-brain barrier penetration, constrain current commercial scale.
Oncology holds established reimbursement infrastructure. Rare diseases are expanding most quickly as gene therapy platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold chain logistics networks at Memphis International Airport and the Port of Rotterdam anchor transatlantic ATMP distribution, connecting manufacturing clusters in Belgium and the Netherlands to United States treatment centers.
United States
FDA's regenerative medicine advanced therapy designation compresses clinical trial timelines for hematologic malignancy programs. The Medicare new technology add-on payment preserves hospital margins for CAR-T administration. Boston's Longwood Medical Area and Houston's Texas Medical Center host the highest concentration of approved therapy infusion sites.
Germany
EMA's centralized marketing authorization enables cross-border patient access from neighboring EU member states. The Paul-Ehrlich-Institut maintains stringent batch release protocols for viral vector products. Heidelberg and Munich anchor the country's gene therapy manufacturing corridor with integrated academic-industry translation centers.
Switzerland
Swissmedic's parallel scientific advice procedures align with EMA timelines for simultaneous EU-Swiss market entry. The country's bilateral agreements with the EU preserve customs-free movement of temperature-sensitive biological materials. Basel's pharmaceutical cluster concentrates vector production capacity and specialized cryogenic logistics providers.
Japan
PMDA's Sakigake designation system grants priority review for regenerative medicines addressing unmet needs. Domestic partnerships with PMDA-preferred contract manufacturers reduce regulatory friction for foreign sponsors. The Kanto region around Tokyo hosts the majority of cell therapy clinical trial infrastructure and specialized hospital networks.
United Kingdom
The Medicines and Healthcare products Regulatory Agency's innovative licensing pathway accelerates access to promising ATMPs post-Brexit. London's cell and gene therapy catapult facility bridges academic research and commercial manufacturing scale-up. The Golden Triangle between London, Oxford, and Cambridge concentrates early-stage biotechnology company formation.
Advanced Therapy Medicinal Products (Atmps) Market Competitive Environment
Concentration sits with integrated pharmaceutical conglomerates that control viral vector manufacturing and autologous cell therapy infrastructure. The competitive structure reflects tiered capabilities across vector production, cryogenic logistics, and patient access programs. Three archetypes dominate: diversified biopharmaceutical majors with captive manufacturing, specialized cell therapy pure-plays, and emerging allogeneic platform developers. Capacity expansion into GMP-grade plasmid DNA and automated cell processing equipment represents the primary competitive moves reshaping supply-side positioning.
Among the diversified majors, Novartis AG, Gilead Sciences, Inc., and Bristol-Myers Squibb Company occupy positions defined by manufacturing scale and established reimbursement relationships. Novartis exemplifies the integrated archetype through in-house vector production capabilities. Gilead represents the acquisition-driven consolidation pattern via Kite Pharma's autologous infrastructure. Bristol-Myers Squibb sits within the modality-diversified tier spanning both cell and gene therapy platforms.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences, Inc. |
| Bristol-Myers Squibb Company |
| Bluebird Bio, Inc. |
| Spark Therapeutics, Inc. |
| Vericel Corporation |
| UniQure N.V. |
| Kolon TissueGene, Inc. |
| Organogenesis Inc. |
| Others |
Value Chain & Pricing Dynamics
Vein-to-vein timelines stretching 3-4 weeks for autologous therapies concentrate pricing power with manufacturers controlling cryogenic logistics networks and GMP-grade viral vector capacity. This lead-time band couples supply chain bottlenecks to reimbursement negotiations, as payers weigh premium pricing against curative durability claims.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortia from standalone community hospitals, with the former capturing 15-25% acquisition discounts through multi-year commitment pools. Price differentiation hinges on chain-of-identity system sophistication and FDA regenerative medicine advanced therapy designation status. Cost compression in the autologous segment intensifies as allogeneic platforms promise manufacturing economies, while specialty clinics prove least price-sensitive due to outcomes-based reimbursement carve-outs.
Supply Chain Analysis
Inventory buffers for GMP-grade plasmid DNA rarely exceed 45-60 days, exposing manufacturers to supply interruptions from the concentrated United States and European supplier base. Raw material dependencies center on HEK293 cell lines, suspension culture media, and cryopreservation-grade dimethyl sulfoxide. Single-source vulnerability in viral vector production creates structural risk, with distribution running through Memphis International Airport and the Port of Rotterdam to connect Belgian manufacturing clusters to United States treatment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ATMP market functions as a defensive-moat arena where regulatory entrenchment through FDA's regenerative medicine advanced therapy designation and EMA's ATMP classification framework creates durable competitive barriers against replication.
For Market Incumbents: Secure captive plasmid DNA supply through backward integration or long-term offtake agreements with United States-based GMP suppliers. Expand cryogenic logistics infrastructure into mid-market United States geographies before allogeneic platforms democratize patient access and erode site-of-care exclusivity. For New Entrants and Emerging Players: Real-world evidence infrastructure gaps present white-space opportunities where incumbents under-serve payer data requirements. Target rare disease gene therapy programs in Japan's Sakigake designation pathway, deploying domestic PMDA-preferred CMO partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents with stranded ATMP assets lacking integrated vector manufacturing. Five-to-ten year viability hinges on allogeneic platform conversion timelines; monitor FDA approval velocity for off-the-shelf cell therapies as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Viral Vector Manufacturing Scale-Up | In-house AAV capacity insulates Novartis and Gilead from plasmid supply volatility and price shocks. |
| Allogeneic Platform Development | Off-the-shelf cell banks displace patient-specific logistics, compressing COGS and expanding addressable populations. |
| Real-World Evidence Infrastructure | Patient registry capabilities satisfy United States payer durability requirements and secure formulary placement. |
| PMDA Sakigake Partnership Structure | Domestic Japanese CMO relationships accelerate priority review timelines and reduce regulatory friction. |
| Specialty Clinic Network Expansion | Dedicated CAR-T infusion suites in United States regional markets decouple access from academic medical center capacity constraints. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cell therapy manufacturing executives, regulatory affairs specialists at FDA and EMA, hospital formulary directors, and payer access strategists. Secondary validation drew from FDA BLA submissions, EMA centralized approval records, ClinicalTrials.gov registry data, and Medicare new technology add-on payment determinations. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Across the analysis window, forecasts integrated treatment-line segmentation, administration route differentiation, and regional regulatory cluster dynamics. CAGRs derived from log-linear trend fitting to approved therapy revenue trajectories, adjusted for pipeline probability-weighted launch timing and reimbursement code adoption curves. Vector manufacturing capacity expansion schedules and cryogenic logistics network build-outs fed supply-side constraints into demand projections.
Forecasts assume regulatory continuity in FDA's regenerative medicine advanced therapy designation and EMA's ATMP classification framework; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Granulocyte Macrophage Colony Stimulating Factor Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Pharmacovigilance (PV) Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Tuberculosis Vaccine Treatment Market