
 Immunoglobulin Products Market | 2026-2036
Immunoglobulin Products Market Size, Share, and Industry Trends Forecast 2026-2036
Immunoglobulin Products Market Foresight
Subcutaneous-grade immunoglobulin formulations is reorganizing competitive priorities across the industry. CSL Behring leverages its plasma fractionation scale to dominate hospital contracts in North America. Grifols anchors European supply security through vertically integrated plasma collection networks. Octapharma AG competes on specialty immunoglobulin portfolios targeting neurological indications.
Immunoglobulin products are sterile protein preparations derived from pooled human plasma, containing standardized IgG concentrations typically exceeding 95% of total protein, manufactured through cold ethanol fractionation and viral inactivation protocols to treat antibody deficiency and autoimmune modulation. Intravenous immunoglobulin retains the largest revenue pool due to established hospital reimbursement, while subcutaneous immunoglobulin represents the fastest-growing delivery modality as homecare penetration deepens. Specialty immunoglobulin segments command premium positioning through hyperimmune titers against specific pathogens such as hepatitis B and rabies.
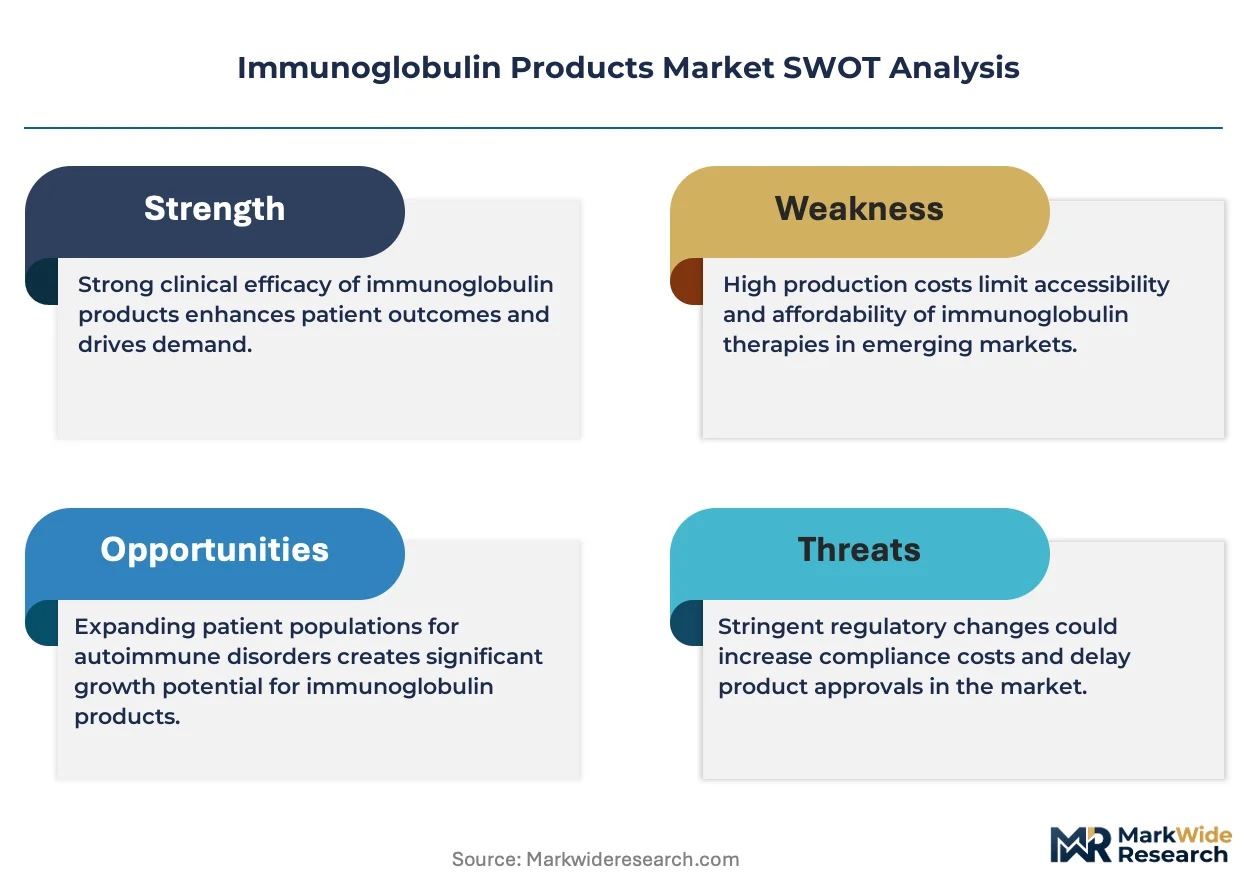
FDA plasma donor deferral criteria and EU MDR traceability mandates are elevating compliance costs while restricting qualified plasma supply, directly constraining batch release volumes. WHO plasma quality guidelines and national blood service regulations in Germany and Japan further fragment market access pathways. Stakeholders must monitor plasma collection economics against evolving homecare reimbursement to calibrate capacity investments.
Market Dynamics
Plasma supply scarcity is compressing manufacturing economics across the immunoglobulin value chain, forcing fractionators to renegotiate hospital contracts and accelerate subcutaneous formulation development to preserve margin structures amid rising collection costs.
Growth Catalysts
- Primary Immunodeficiency Prevalence:Rising diagnosis rates in the United States and Germany are expanding chronic replacement therapy patient pools. Hospital-based infusion protocols now anchor reimbursement frameworks in both markets.
- FDA Plasma Collection Modernization:Revised donor deferral criteria and automated collection technologies are expanding qualified donor bases. This regulatory recalibration directly increases plasma throughput for fractionation facilities.
- Subcutaneous Delivery Technology:Homecare administration systems are reducing hospital dependency for immunoglobulin patients. Patients in Japan and the United States increasingly prefer self-administration over intravenous infusion centers.
Market Restraints
- EU MDR Batch-Testing Burden:Extended release timelines and enhanced viral marker testing protocols are constraining qualified plasma supply. European fractionators face 15-20% longer certification cycles.
- Plasma Collection Concentration:United States-based collection networks control over 70% of global source plasma. Geographic supply concentration creates vulnerability to donor recruitment disruptions.
- Recombinant Alternative Threat:Engineered monoclonal antibody platforms for specific autoimmune indications are capturing niche segments previously served by polyclonal immunoglobulin.
Strategic Opportunities
- Neurological Application Expansion:CIDP and myasthenia gravis represent underpenetrated therapeutic areas with premium pricing potential. Specialty immunoglobulin portfolios targeting these indications command hospital formulary preference.
- Japanese Homecare Reimbursement:METI-aligned policy reforms are expanding subcutaneous immunoglobulin coverage for outpatient administration. This regulatory tailwind accelerates patient migration from hospital to home settings.
- Digital Adherence Platforms:Integration of injection devices with remote monitoring systems is creating new service revenue streams. Technology convergence between drug delivery and patient data capture opens subscription-based commercial models.
Industry Challenges
- Plasma Fractionation Talent Scarcity:Specialized biochemists and viral inactivation engineers command premium compensation. CSL Behring and Grifols compete aggressively for experienced personnel across European and North American facilities.
- Legacy Hospital Contract Reconfiguration:Intravenous immunoglobulin purchasing agreements require complex renegotiation to accommodate subcutaneous product substitution. Procurement teams resist volume commitment shifts that disrupt established infusion center economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunoglobulin Products Market |
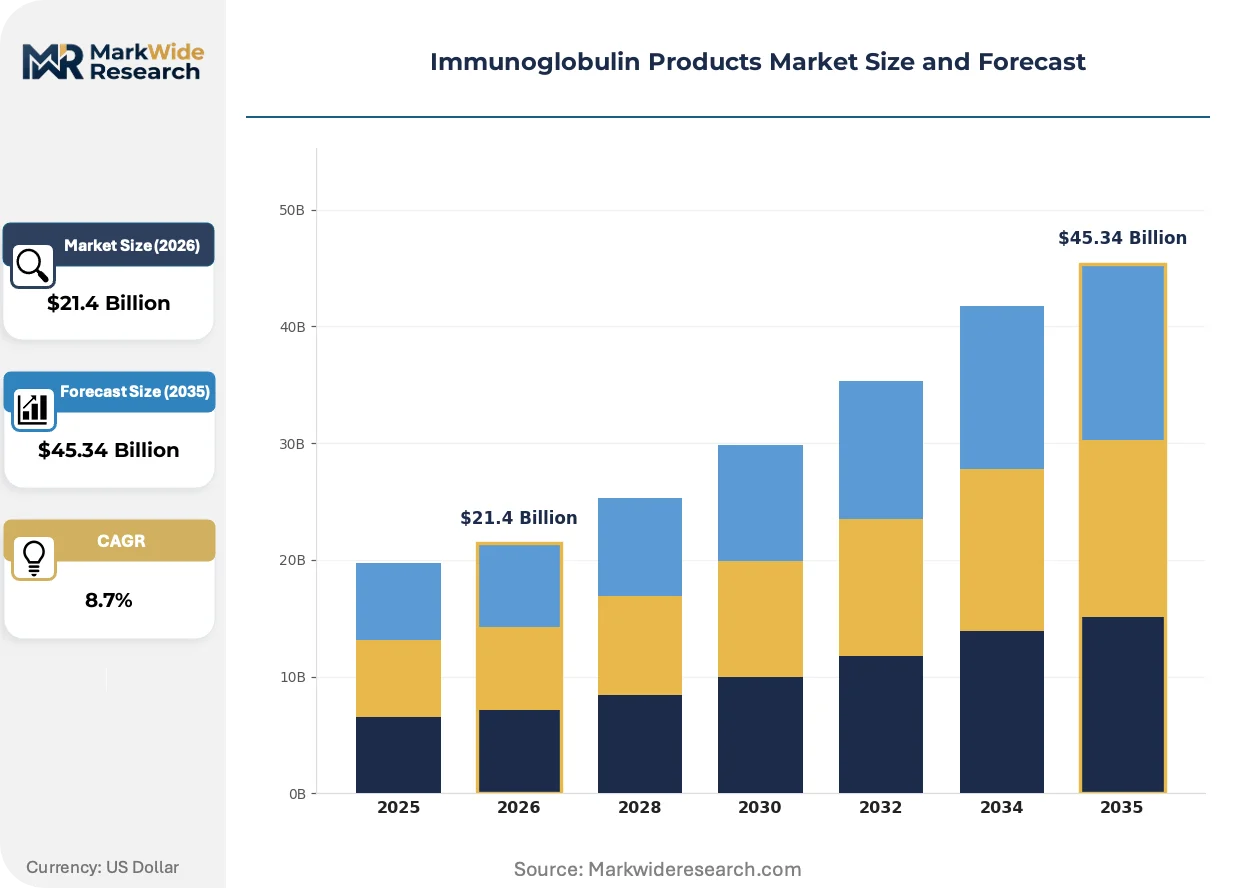
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $45.34 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Immunoglobulin, Subcutaneous Immunoglobulin, Hyperimmune Globulin, Specialty Immunoglobulin End User: Hospitals, Homecare Settings, Specialty Clinics, Blood Banks Application: Immunodeficiency Disorders, Autoimmune Diseases, Infectious Diseases, Neurological Disorders Distribution Channel: Online Pharmacies, Retail Pharmacies, Direct Sales, Distributors |
| Companies Covered | CSL Behring, Grifols, Octapharma AG, Takeda Pharmaceutical Company Limited, Kedrion Biopharma, Biotest AG, LFB Group, China Biologic Products Holdings, Baxter International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunoglobulin Products Market Shifts & Advancements
Bioprocessing automation and patient-centric delivery formats are restructuring competitive advantage in immunoglobulin manufacturing, with regulatory harmonization efforts creating divergent compliance pathways across major markets.
Chromatography-based purification methods are decomposing the traditional cold ethanol fractionation paradigm that has dominated plasma processing since the 1940s. Fractionators in Germany and Switzerland are adopting protein A and ion-exchange chromatography to achieve higher IgG yield and purity. This technology shift is decomposing capital efficiency assumptions across the industry, as chromatography systems demand 40-60% higher upfront investment but reduce batch-to-batch variability and viral clearance validation burdens.
The EU MDR traceability mandate is forcing systematic overhaul of plasma provenance documentation across European supply chains. Manufacturers must now maintain electronic records linking each finished vial to individual donor collection events, extending batch release timelines by 8-12 weeks. Specialty immunoglobulin segments face the steepest compliance costs, as hyperimmune products require additional serological testing against specific pathogen titers that complicate donor pool qualification.
Hospital purchasing consortia are consolidating immunoglobulin procurement decisions into centralized pharmacy and therapeutics committees. Individual physician preference for specific brands is yielding to formulary compliance requirements and outcome-based contracting terms. This behavioral shift is most pronounced in the United States, where integrated delivery networks now control 60% of hospital-based immunoglobulin volume and leverage scale to extract price concessions from fractionators.
Immunoglobulin Products Market Segmentation
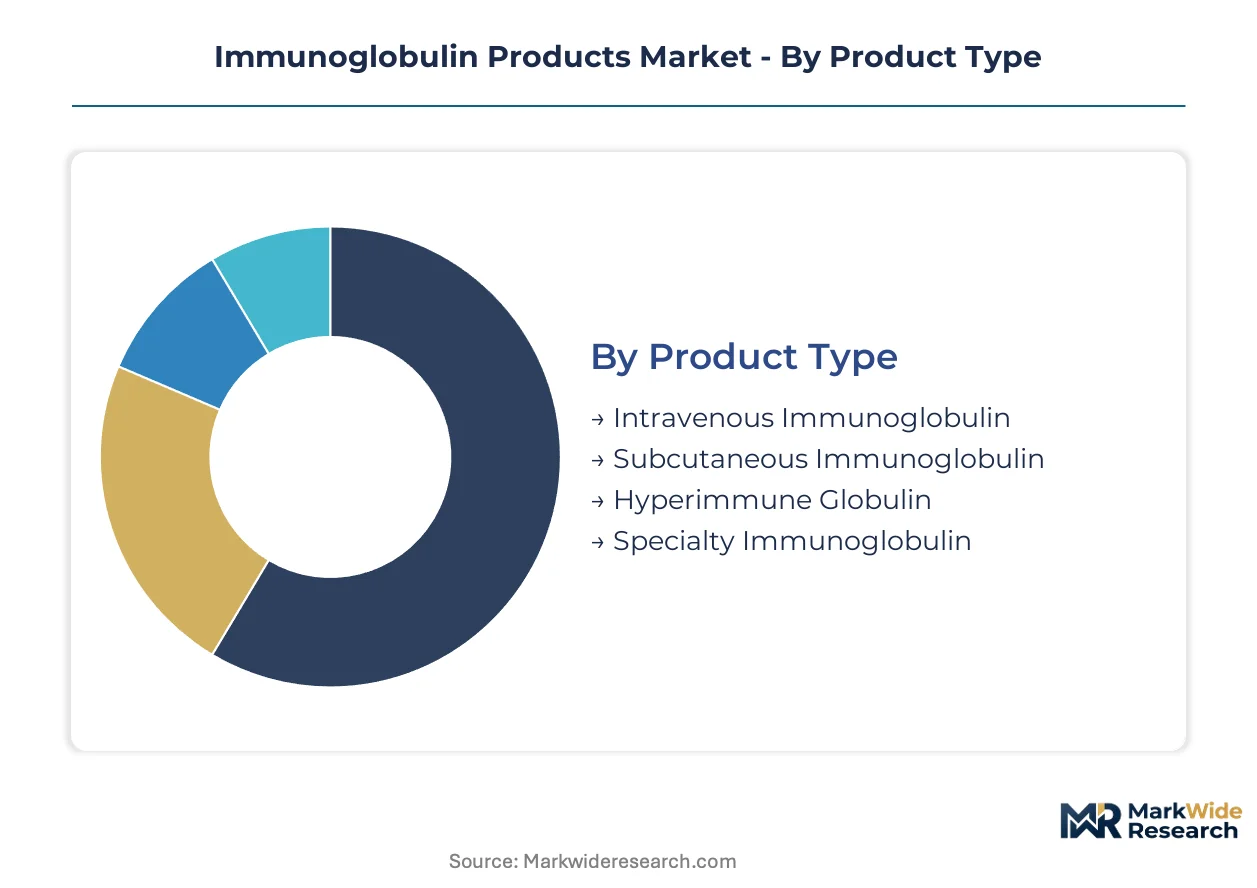
Segmentation in the immunoglobulin products market reveals how plasma fractionation economics, reimbursement pathways, and patient administration preferences reshape competitive positioning across distinct product formats and delivery settings.
Product Type:
Hospital infusion centers and homecare channels pull different formulations through their procurement systems based on reimbursement codes and patient training infrastructure.
- Intravenous Immunoglobulin:Sterile liquid preparations containing 10% protein concentration deliver high-dose IgG through central or peripheral venous access. United States hospital purchasing consortia anchor demand through established J-code reimbursement mechanisms that favor inpatient administration protocols.
- Subcutaneous Immunoglobulin:Concentrated 20% protein solutions enable weekly self-administration via subcutaneous tissue deposition. German and Japanese patients increasingly migrate toward home-based delivery systems as outpatient reimbursement frameworks expand coverage for self-infusion training programs.
- Hyperimmune Globulin:Pathogen-specific antibody preparations derived from vaccinated donor pools target hepatitis B, rabies, and tetanus post-exposure prophylaxis.
- Specialty Immunoglobulin:Purified IgG fractions with enhanced neutralizing titers against cytomegalovirus or respiratory syncytial virus serve transplant and neonatal intensive care units.
Intravenous formulations dominate hospital formulary placement. Subcutaneous delivery systems are where expansion concentrates.
End User:
Procurement authority and reimbursement complexity stratify across settings, with integrated delivery networks consolidating purchasing power while homecare operators compete on patient adherence metrics.
- Hospitals:Academic medical centers and community hospital systems maintain captive infusion centers with pharmacy oversight of immunoglobulin stewardship programs. United States integrated delivery networks now control the majority of intravenous immunoglobulin volume through centralized therapeutics committees.
- Homecare Settings:Specialized nursing agencies and durable medical equipment suppliers coordinate subcutaneous immunoglobulin distribution with remote patient monitoring. Japanese METI-aligned reimbursement reforms accelerate patient migration from hospital to home administration.
- Specialty Clinics:Outpatient infusion centers operated by hematology and immunology practices compete on appointment availability and nursing ratios.
- Blood Banks:Hospital-based transfusion services and regional blood centers maintain emergency hyperimmune globulin inventories for rabies and tetanus exposure protocols.
Hospitals retain the largest procurement scale. Homecare settings are climbing the fastest.
Application:
Clinical evidence thresholds and FDA label expansions determine which therapeutic areas command premium pricing and hospital formulary preference.
- Immunodeficiency Disorders:Chronic replacement therapy for primary humoral deficiencies including common variable immunodeficiency and X-linked agammaglobulinemia constitutes the foundational indication. United States diagnosis rates for primary immunodeficiency continue expanding the addressable patient pool through newborn screening programs.
- Autoimmune Diseases:Immunomodulatory applications in immune thrombocytopenic purpura, Kawasaki disease, and dermatomyositis leverage high-dose intravenous protocols. German and Austrian treatment centers favor immunoglobulin over corticosteroid escalation for refractory cases.
- Infectious Diseases:Adjunctive therapy for severe bacterial and viral infections in immunocompromised hosts targets transplant and oncology patient populations.
- Neurological Disorders:Chronic inflammatory demyelinating polyneuropathy and multifocal motor neuropathy represent premium-priced indications with expanding FDA label coverage.
Immunodeficiency disorders anchor chronic replacement volume. Neurological applications are gaining share fastest.
Distribution Channel:
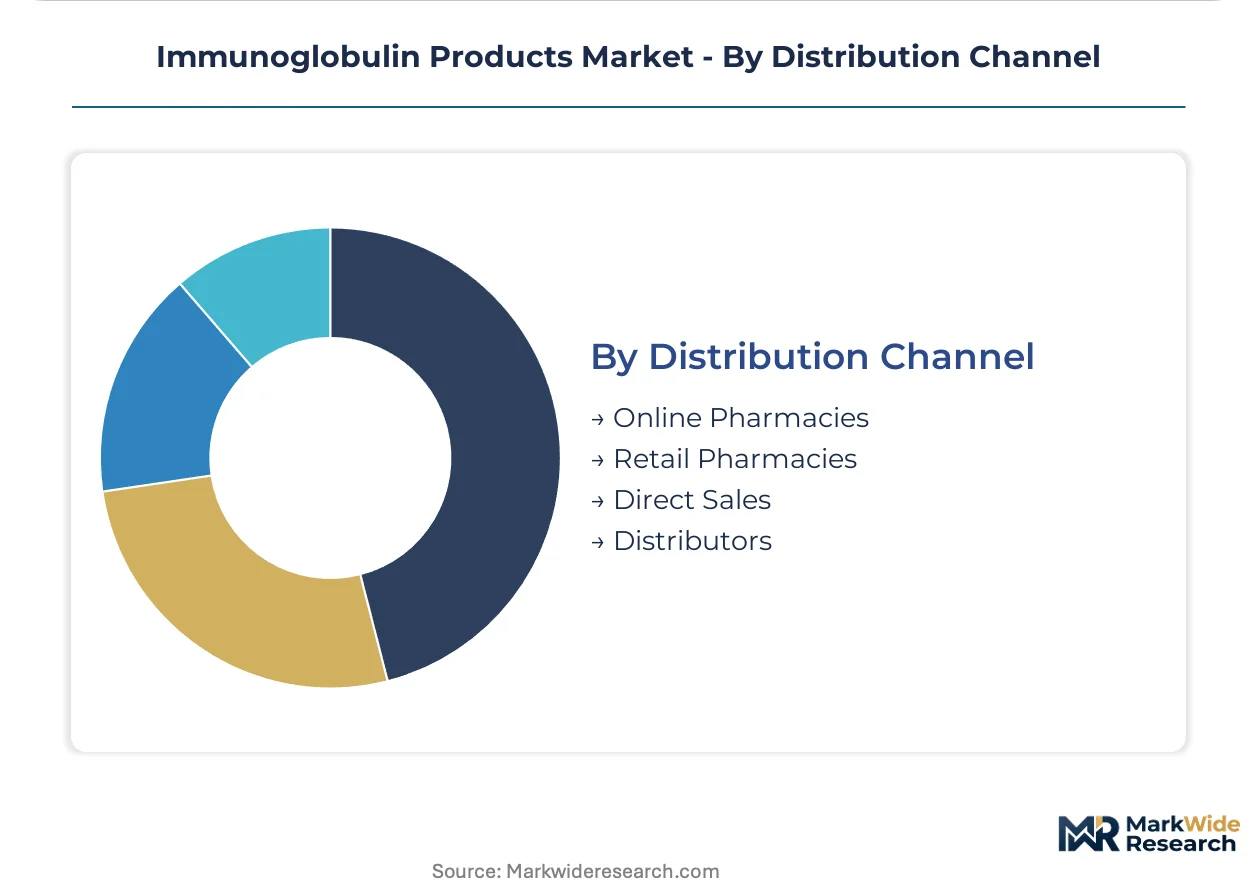
Channel economics reflect cold chain requirements, patient training obligations, and payer prior authorization workflows that favor direct manufacturer relationships over wholesale intermediaries.
- Direct Sales:Plasma fractionators maintain dedicated hospital account teams negotiating multi-year contracts with integrated delivery networks. CSL Behring and Grifols deploy specialized field forces to manage United States hospital consortia relationships.
- Distributors:Regional and national wholesale distributors handle inventory logistics for smaller hospital systems and specialty clinics. German pharmaceutical wholesalers navigate EU MDR traceability mandates through electronic batch documentation systems.
- Retail Pharmacies:Community pharmacy channels serve subcutaneous immunoglobulin patients with prescription fulfillment and injection training support.
- Online Pharmacies:Digital platforms facilitate specialty pharmacy services for homecare patients with recurring immunoglobulin orders.
Direct sales relationships dominate institutional procurement. Distributor partnerships are where margin pressure concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports finished immunoglobulin formulations while importing specialized hyperimmune plasma fractions from European collection networks. Germany and Japan maintain near-autarkic supply chains through national blood service regulations. China and India remain net importers of fractionation technology and quality-certified plasma derivatives.
United States
Hospital purchasing consortia and integrated delivery networks drive demand concentration across academic medical centers in Boston and Houston. FDA plasma donor deferral criteria revisions expand qualified collection bases through automated apheresis technologies. The Research Triangle Park corridor in North Carolina anchors plasma fractionation R&D clusters where viral inactivation engineering talent concentrates.
Germany
Chronic replacement therapy for primary immunodeficiency and CIDP neurological applications sustains hospital formulary demand in Munich and Berlin treatment centers. Paul-Ehrlich-Institut batch-testing protocols and EU MDR traceability mandates extend certification timelines for fractionators operating in Frankfurt-Rhine-Main industrial zones. Bavarian plasma collection networks maintain vertical integration into finished immunoglobulin production.
Japan
METI-aligned reimbursement reforms accelerate patient migration from hospital infusion to subcutaneous homecare administration in Tokyo and Osaka metropolitan areas. PMDA quality guidelines enforce stringent viral marker testing that constrains imported plasma qualification. The Kansai region hosts specialty immunoglobulin distribution hubs serving transplant and neonatal intensive care units.
Switzerland
Chromatography-based purification technology adoption concentrates in Basel and Zurich bioprocessing clusters where protein A yield optimization research advances. Swissmedic traceability requirements exceed baseline EU MDR standards for donor-to-vial documentation. Geneva-based hyperimmune globulin specialists serve WHO emergency stockpile procurement for rabies and tetanus post-exposure protocols.
Australia
TGA immunoglobulin product registration pathways prioritize subcutaneous formulation approvals to reduce hospital infusion center dependency in Sydney and Melbourne. National Blood Authority contracts secure plasma supply through domestic collection networks and New Zealand bilateral agreements. The Parkville biomedical precinct in Victoria anchors viral inactivation research partnerships with fractionators.
Immunoglobulin Products Market Competitive Landscape
Listed leaders compete with private specialists across plasma collection scale and fractionation technology portfolios. The market consolidates around three to four dominant fractionators controlling hospital contract channels while mid-tier specialists occupy neurological and hyperimmune niches. Strategic archetypes separate plasma supply integrators, chromatography technology adopters, and specialty indication developers. Capacity expansion in automated collection centers and backward integration into donor recruitment networks constitute the dominant competitive moves.
Among plasma fractionation specialists, CSL Behring, Grifols, and Octapharma AG occupy positions reflecting distinct geographic and technological anchoring. CSL Behring represents the scale-driven archetype with North American hospital contract concentration. Grifols exemplifies European supply security through captive collection network architecture. Octapharma AG sits within the specialty portfolio tier targeting neurological indication premium pricing.
| Leading Market Players |
|---|
| CSL Behring |
| Grifols |
| Octapharma AG |
| Takeda Pharmaceutical Company Limited |
| Kedrion Biopharma |
| Biotest AG |
| LFB Group |
| China Biologic Products Holdings |
| Baxter International |
| Others |
Supply & Pricing Matrix
Plasma fractionation scale economics in the United States compress unit costs for immunoglobulin manufacturers operating above 4 million liter annual throughput, simultaneously elevating price floors for smaller European fractionators facing EU MDR compliance burdens. This capacity asymmetry concentrates pricing power among three dominant suppliers while forcing mid-tier competitors toward specialty hyperimmune segments where FDA orphan-drug designations sustain premium positioning.
Pricing Analysis
Hospital purchasing consortia anchor immunoglobulin pricing through multi-year J-code contracts that favor intravenous formulations with established reimbursement pathways. Pricing stratifies across premium, standard, and economy tiers based on IgG concentration purity and viral inactivation certification grade. Cost compression in standard-grade intravenous immunoglobulin is intensifying because automated plasma collection technologies expand qualified donor bases and depress collection premiums. Specialty clinics and homecare nursing agencies exhibit highest price sensitivity, while academic medical centers with captive infusion centers tolerate premium positioning for neurological indication portfolios.
Supply Chain Analysis
Strategic stockpiling of plasma-derived intermediates dominates inventory strategy among fractionators confronting 8-12 week EU MDR batch-release timelines. Plasma supply concentrates in the United States, Germany, and Austria, with United States-based collection networks controlling over 70% of global source plasma. Manufacturing rests on three critical inputs: qualified donor plasma pools, protein A chromatography resins, and viral inactivation chemical reagents. Single-source vulnerability in Chinese-produced chromatography media creates supply chain risk. Distribution runs through direct manufacturer-to-hospital contracts for institutional volume, with specialty pharmacy intermediaries handling homecare subcutaneous fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immunoglobulin product manufacturers increasingly attach digital adherence platforms and remote patient monitoring services to core drug offerings, with subscription-based service revenue expanding faster than per-vial product sales across Japanese and German homecare markets.
For Market Incumbents: Consolidate plasma collection network control through automated apheresis center expansion in Texas and North Carolina corridors where FDA donor deferral recalibration expands qualified bases. Secure hospital formulary position against recombinant monoclonal antibody substitutes by accelerating neurological indication label expansions for CIDP and myasthenia gravis. Capacity addition in Bavarian fractionation facilities addresses EU MDR traceability compliance while reducing cross-border plasma dependency. For New Entrants and Emerging Players: Differentiate on subcutaneous delivery device integration with Bluetooth-enabled injection logging systems that capture patient adherence data for payer outcomes contracts. Target Japanese homecare reimbursement expansion as the most penetrable geography, where METI-aligned policy reforms accelerate patient migration from hospital infusion centers. Pursue specialty hyperimmune globulin segments—hepatitis B and rabies post-exposure prophylaxis—where vaccinated donor pool scarcity limits incumbent scale advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chromatography-purification adopters over legacy cold-ethanol fractionators, as protein A yield optimization research concentrates in Basel and Zurich bioprocessing clusters. Long-term viability over the projection horizon hinges on backward integration into plasma collection networks rather than toll-manufacturing dependence. Acquisition targets should demonstrate captive donor recruitment infrastructure and FDA pre-approval inspection history. The signal to watch is Japanese PMDA subcutaneous formulation approval velocity as inflection indicator for homecare penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Automated apheresis center buildout in FDA-favored corridors secures qualified donor supply against EU MDR constraints. |
| Chromatography Purification Adoption | Protein A yield optimization reduces batch-to-batch variability and viral clearance validation burdens for fractionators. |
| Neurological Indication Label Expansion | CIDP and myasthenia gravis FDA submissions command hospital formulary preference and premium pricing positioning. |
| Digital Adherence Platform Integration | Bluetooth-enabled injection devices with remote monitoring create subscription revenue streams beyond per-vial sales. |
| Japanese Homecare Reimbursement Strategy | METI-aligned policy navigation accelerates patient migration from hospital infusion to subcutaneous self-administration. |
Research Methodology
A spread of perspectives from plasma collection network operators, hospital pharmacy directors, regulatory affairs specialists at fractionators, and homecare nursing agency coordinators converged on the working assumptions underlying demand forecasts. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA marketing authorization databases, Paul-Ehrlich-Institut batch-release records, and Japanese PMDA approval summaries. Bottom-up patient population modeling and top-down plasma throughput analysis triangulated volume estimates across the analysis window.
Segmentation dimensions modeled include product type, end-user setting, therapeutic application, and distribution channel, with additional cross-cutting by regional regulatory cluster. CAGRs were derived from plasma collection economics trajectories, reimbursement code expansion timelines, and patient diagnosis rate projections. Forecast inputs incorporated EU MDR traceability implementation pace, FDA donor deferral criteria modernization effects, and Japanese METI homecare policy alignment.
The analysis sits within stated boundaries; outcomes outside sustained plasma donor recruitment efficiency and stable fractionation capacity utilization would require recalibration. Forecasts reflect assumptions regarding regulatory harmonization progress and chronic immunodeficiency diagnosis expansion through newborn screening programs. Revision becomes warranted when recombinant monoclonal antibody platform efficacy crosses thresholds that displace polyclonal immunoglobulin in neurological indications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market