
 Gastrointestinal Diseases Drug Development Market | 2026-2036
Gastrointestinal Diseases Drug Development Market Size, Share, and Industry Trends Forecast 2026-2036
Gastrointestinal Diseases Drug Development Market Foresight
A shortage of gastroenterology-specialized clinical investigators is reorganizing trial site selection across the industry. Takeda Pharmaceutical anchors its development footprint in Japan and North America through deep relationships with academic medical centers. AbbVie Inc. leverages its immunology infrastructure to sustain one of the largest biologics pipelines in inflammatory bowel disease. Pfizer Inc. competes through broad geographic coverage of Phase II networks across multiple continents.
Gastrointestinal diseases drug development encompasses the discovery, preclinical validation, clinical testing, and regulatory filing of therapeutics targeting disorders of the esophagus, stomach, intestines, liver, and pancreas, with biologics requiring cold-chain distribution at two to eight degrees Celsius to preserve protein stability. The primary purpose is to advance molecules from target identification through post-marketing surveillance to secure regulatory approval and commercial access. Biologics command the deepest investment pools due to validated mechanisms in tumor necrosis factor and interleukin pathway modulation. Anti-inflammatory agents retain volume leadership in gastroesophageal reflux and peptic ulcer indications where generic penetration has compressed margins. Phase III trials absorb the greatest share of development capital as registrational endpoints demand large, multi-year cohort studies.
FDA accelerated approval and breakthrough therapy designations compress development timelines for severe GI conditions with unmet need, while EMA adaptive licensing frameworks enable iterative evidence generation in parallel with controlled commercial access. These regulatory pathways reshape how pharmaceutical companies and biotechnology firms allocate capital across preclinical and clinical portfolios. Stakeholders must monitor how evolving evidentiary standards for biosimilar interchangeability influence pipeline prioritization and partnership structures.
Market Dynamics
Biologics pipelines are compressing traditional small-molecule timelines as FDA accelerated approval pathways reward tumor necrosis factor and interleukin pathway innovations with earlier market access. Cold-chain distribution requirements at two to eight degrees Celsius are restructuring site selection toward academic medical centers with validated infrastructure.
Growth Catalysts
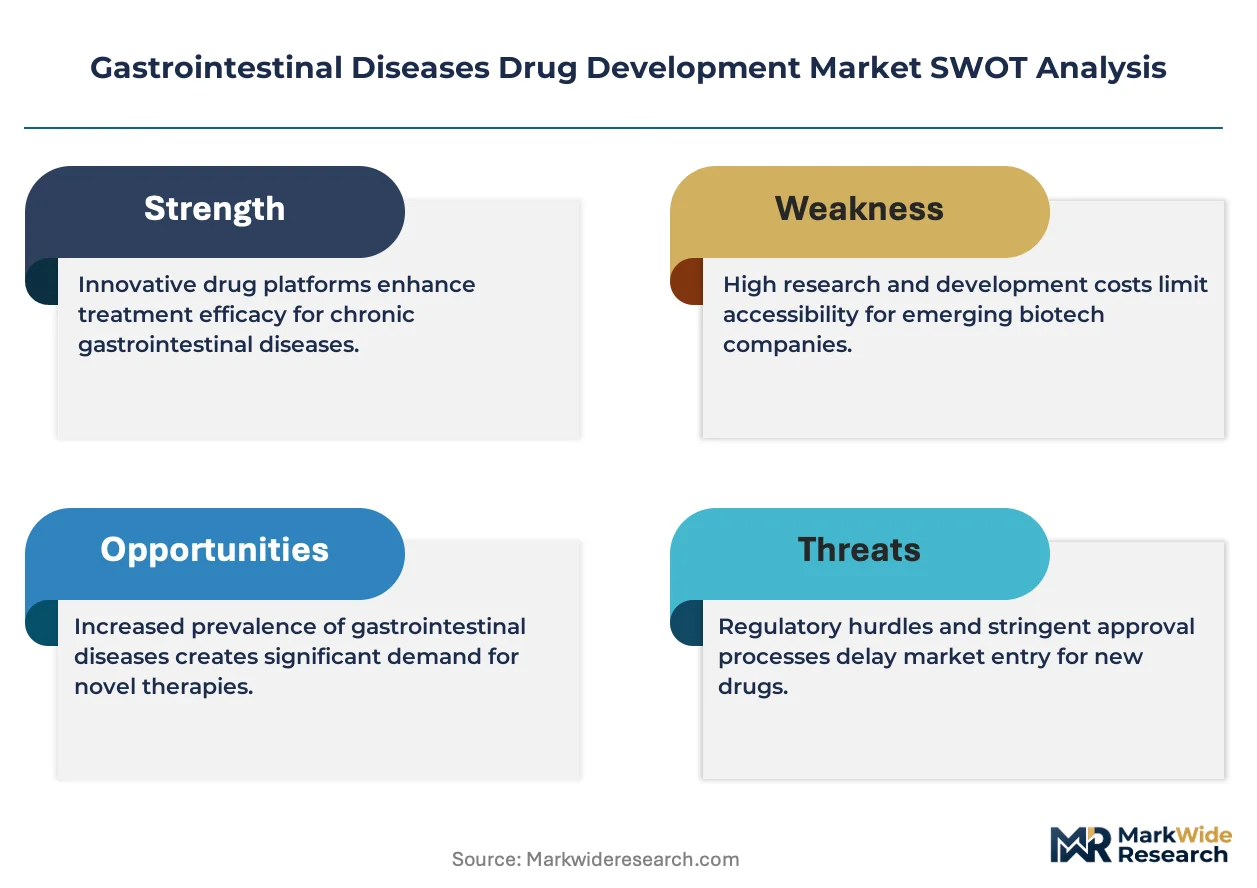
- FDA Accelerated Approval:The pathway compresses registrational timelines for severe GI conditions with unmet need, enabling iterative evidence generation during commercial rollout.
- Academic Medical Center Concentration:Hospital systems in the United States anchor Phase II and III recruitment through deep investigator relationships and patient access.
- Interleukin Pathway Modulation:Validated immunology mechanisms are drawing capital allocation away from generic-saturated anti-inflammatory segments.
Market Restraints
- Cold-Chain Infrastructure Cost:Protein stability requirements demand validated two-to-eight-degree distribution networks that smaller developers cannot self-fund.
- Investigator Scarcity:A shortage of gastroenterology-specialized clinical researchers is constraining trial site expansion and extending recruitment windows.
- Biosimilar Erosion:Generic penetration in gastroesophageal reflux and peptic ulcer indications has compressed margins below sustainable development thresholds.
Strategic Opportunities
- EMA Adaptive Licensing:Controlled commercial access with parallel evidence generation offers European market entry before full registrational completion.
- Specialty Clinic Networks:Outpatient infusion centers are emerging as lower-cost alternatives to hospital-based administration for maintenance biologic therapy.
- Japan PMDA Pathways:Sakigake designation provides priority review for GI biologics addressing unmet needs in inflammatory bowel disease.
Industry Challenges
- Multi-Year Cohort Requirements:Phase III registrational endpoints demand large, longitudinal studies that absorb disproportionate capital shares and extend cash runway needs.
- Evidentiary Standard Uncertainty:Shifting FDA and EMA criteria for biosimilar interchangeability are complicating pipeline prioritization and partnership valuation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gastrointestinal Diseases Drug Development Market |
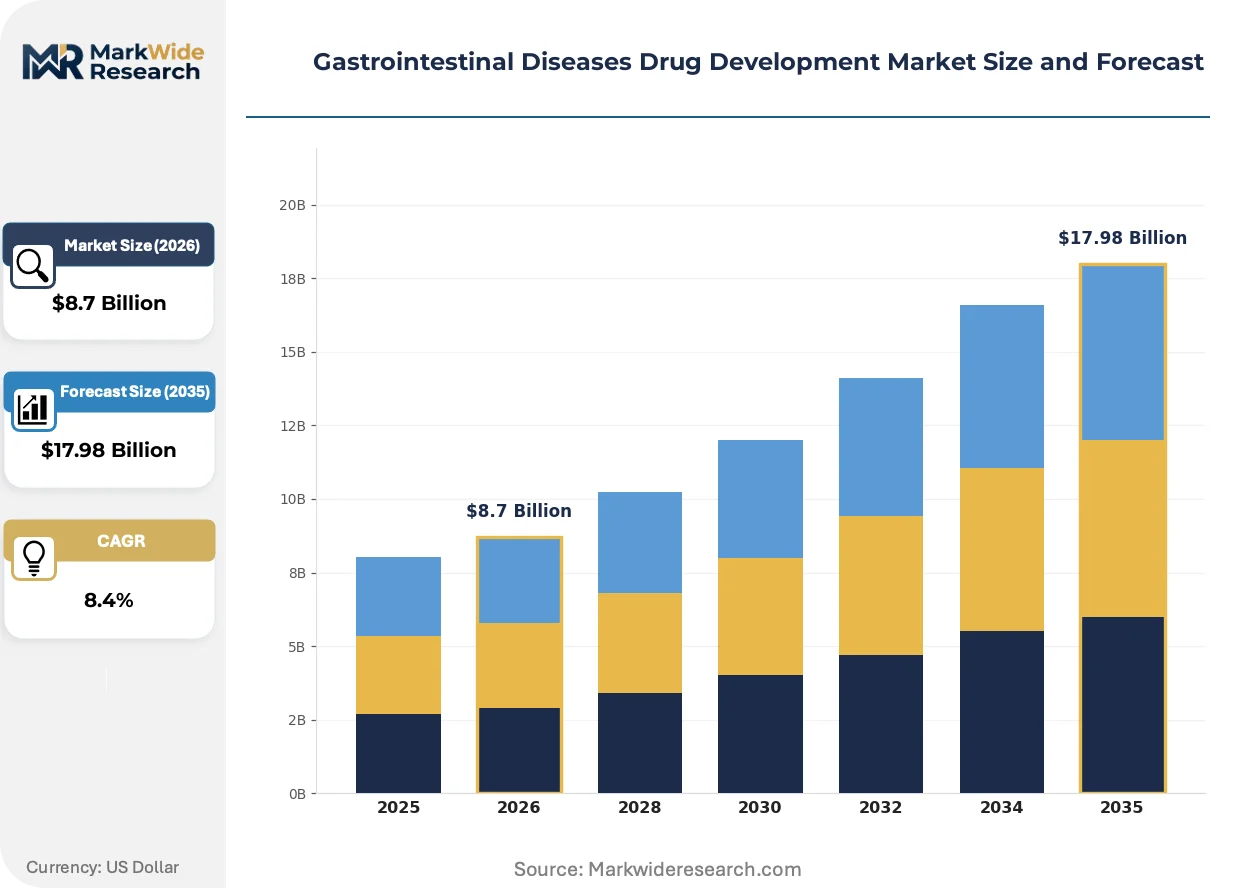
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Proton Pump Inhibitors, Antacids, Antibiotics, Anti-inflammatory Agents, Biologics, Immunosuppressants Therapy Area: Inflammatory Bowel Disease, Gastroesophageal Reflux, Irritable Bowel Syndrome, Peptic Ulcer, Celiac Disease, Hepatitis Clinical Trial Phase: Preclinical, Phase I, Phase II, Phase III, Regulatory Review, Post-Marketing Surveillance End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions |
| Companies Covered | AbbVie Inc., Takeda Pharmaceutical, Johnson & Johnson, Pfizer Inc., AstraZeneca, Bristol Myers Squibb, Bausch Health Companies, Nestlé Health Science, Recordati Rare Diseases, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gastrointestinal Diseases Drug Development Market Shifts & Advancements
Modular trial design and decentralized data capture are collapsing traditional site-centric development models. Regulatory frameworks on both sides of the Atlantic are rewarding adaptive protocols with compressed review timelines.
Artificial intelligence-driven patient stratification is decomposing the homogeneous enrollment pools that have historically masked responder heterogeneity in inflammatory bowel disease trials. Biopharma developers are adopting machine learning models to identify biomarker-defined subpopulations before Phase II initiation. This capability is decomposing the blockbuster model that relied on broad-label indications for commercial viability.
EMA adaptive licensing frameworks enable iterative evidence generation in parallel with controlled commercial access for novel GI therapies. The industrial consequence is a reallocation of capital toward earlier-phase assets with conditional approval potential. European biotech firms are responding by front-loading health technology assessment dialogue to secure reimbursement alignment before registrational submission.
Hospital procurement departments are consolidating biologic purchasing through centralized specialty pharmacy contracts that disaggregate drug acquisition from administration reimbursement. Academic medical centers are negotiating outcomes-based arrangements that tie formulary placement to real-world effectiveness data. This shift is most visible in the United States, where integrated delivery networks are capturing specialty drug distribution from traditional wholesale channels.
Gastrointestinal Diseases Drug Development Market Segmentation
Segmentation in gastrointestinal drug development reveals how capital allocation diverges across molecular modalities, therapeutic targets, and development stages. Each dimension exposes distinct risk-return profiles that reshape portfolio construction for biopharma developers.
Drug Class:
Substitution pressure from biosimilars and generic entrants varies sharply across molecular categories, with small-molecule segments facing margin compression while biologics defend pricing power through formulation complexity.
- Proton Pump Inhibitors:Small-molecule agents suppressing gastric acid secretion through irreversible H+/K+ ATPase inhibition. Generic saturation in the United States has collapsed reimbursement rates below sustainable development thresholds for novel entrants.
- Antacids:Rapid-onset neutralizing compounds containing aluminum, magnesium, or calcium salts. Over-the-counter distribution dominance limits prescription-channel investment despite persistent symptomatic demand in emerging markets.
- Antibiotics:Antimicrobial therapies targeting Helicobacter pylori and gut flora modulation. Resistance surveillance requirements from FDA and EMA extend post-approval commitment timelines.
- Anti-inflammatory Agents:Corticosteroid and aminosalicylate compounds addressing mucosal inflammation. Volume leadership persists in gastroesophageal reflux and peptic ulcer indications where generic penetration has stabilized.
- Biologics:Monoclonal antibodies and fusion proteins modulating tumor necrosis factor, interleukin-12/23, and integrin pathways. Cold-chain requirements at two to eight degrees Celsius restrict manufacturing to validated contract development organizations with GMP biologics capability.
- Immunosuppressants:Small-molecule and biologic agents suppressing T-cell activation and cytokine signaling. Transplant-derived infrastructure supports repurposing into inflammatory bowel disease maintenance therapy.
Anti-inflammatory agents retain volume leadership; biologics hold the steepest expansion curve.
Therapy Area:
Development cost tiers separate chronic maintenance indications from acute infectious targets, with autoimmune segments commanding premium pricing and extended exclusivity horizons.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis pathologies requiring lifelong immunomodulation. Academic medical centers in the United States anchor Phase III recruitment through established patient registries.
- Gastroesophageal Reflux:Chronic acid exposure disorders managed through proton pump inhibition and surgical intervention. Generic substitution rates exceed ninety percent in developed markets, eliminating novel small-molecule investment.
- Irritable Bowel Syndrome:Functional motility and sensitivity disorders with heterogeneous responder populations. FDA guidance on patient-reported outcome measures complicates endpoint validation.
- Peptic Ulcer:Mucosal erosion pathologies linked to H. pylori infection and NSAID exposure. Antibiotic combination therapy dominates first-line management with limited biologic penetration.
- Celiac Disease:Gluten-triggered autoimmune enteropathy with no approved pharmacotherapy. Pipeline assets target zonulin pathway inhibition and transglutaminase-2 modulation.
- Hepatitis:Viral and autoimmune liver inflammation spanning hepatitis B, C, and non-viral etiologies. Direct-acting antiviral success in hepatitis C has redirected investment toward hepatitis B functional cure.
Inflammatory bowel disease commands the deepest development budgets; celiac disease represents the most underserved clinical space.
Clinical Trial Phase:
Capital absorption rates accelerate through development stages, with late-phase trials consuming disproportionate shares of corporate R&D expenditure.
- Preclinical:In vitro and in vivo validation of pharmacokinetics, toxicology, and proof-of-concept efficacy. Biologics require extended immunogenicity assessment in non-human primates.
- Phase I:First-in-human safety and tolerability evaluation in healthy volunteers or targeted patients. Adaptive dose-escalation designs compress traditional timelines.
- Phase II:Efficacy signal detection and biomarker validation in disease-specific populations. Patient stratification using machine learning models is decomposing homogeneous enrollment pools.
- Phase III:Registrational studies establishing statistically significant benefit-risk profiles. Multi-year cohort requirements absorb the greatest share of development capital.
- Regulatory Review:Formal assessment by FDA, EMA, or national agencies of manufacturing quality and clinical evidence. Accelerated approval pathways compress review windows for unmet need indications.
- Post-Marketing Surveillance:Real-world effectiveness monitoring and rare adverse event detection. Outcomes-based contracts with hospital systems tie formulary placement to registry data.
Phase III trials absorb the greatest capital share; adaptive licensing frameworks are accelerating regulatory review velocity.
End User:
Customer concentration patterns vary by development stage, with early-phase demand fragmenting across biotechnology firms and late-phase consolidating toward multinational pharmaceutical companies.
- Pharmaceutical Companies:Integrated developers with commercial infrastructure spanning discovery through post-marketing surveillance. Portfolio prioritization favors biologics with blockbuster revenue potential.
- Biotechnology Firms:Specialized developers lacking manufacturing scale or commercial reach. Partnership structures with large pharma dominate Phase II-to-III transitions.
- Contract Research Organizations:Outsourced service providers managing site selection, patient recruitment, and data management. Investigator scarcity is extending recruitment timelines and inflating service pricing.
- Academic Institutions:University-affiliated medical centers conducting investigator-initiated trials and early-phase translational research. Deep relationships with Takeda and AbbVie anchor site selection in Japan and North America.
Pharmaceutical companies retain the largest development budgets; biotechnology firms are expanding most quickly through venture-backed pipeline formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor development velocity in the United States, while EMA adaptive licensing and Japan's PMDA Sakigake designation reshape competitive access across the Atlantic and Pacific. National regulator frameworks are compressing timelines for biologics targeting inflammatory bowel disease.
United States
Academic medical centers in Boston, New York, and San Francisco anchor Phase II and III recruitment through established patient registries and deep investigator relationships. FDA breakthrough therapy designation compresses review windows for tumor necrosis factor and interleukin pathway innovations. The Research Triangle Park corridor in North Carolina concentrates contract manufacturing organizations with validated cold-chain biologics capability.
Germany
EMA headquarters in Amsterdam drives adaptive licensing adoption among Frankfurt and Munich-based developers seeking controlled commercial access. German hospital procurement consolidation through centralized specialty pharmacy contracts is restructuring biologic distribution away from wholesale channels. The Heidelberg-Mannheim medical cluster anchors real-world evidence generation for post-marketing surveillance requirements.
Japan
PMDA Sakigake designation provides priority review for inflammatory bowel disease biologics addressing unmet clinical need. Takeda Pharmaceutical's deep relationships with Tokyo and Osaka academic centers sustain site selection for global registrational trials. The Kobe biomedical innovation cluster houses contract development organizations with GMP biologics manufacturing validated for two-to-eight-degree distribution.
Switzerland
Swissmedic's streamlined review processes attract Basel and Zurich-based developers seeking European market entry for novel GI therapies. The country's concentrated pharmaceutical infrastructure supports iterative evidence generation frameworks aligned with EMA adaptive pathways. Geneva's health technology assessment dialogue capabilities front-load reimbursement alignment before registrational submission.
India
CDSCO's evolving biosimilar guidelines are attracting Hyderabad and Bangalore-based contract research organizations to global Phase II networks. Indian academic medical centers in Delhi and Mumbai are expanding investigator capacity for gastroenterology-specialized trials. The country's central drug standard control organization is harmonizing inspection protocols with FDA and EMA standards to accelerate multinational study participation.
Gastrointestinal Diseases Drug Development Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the gastrointestinal drug development landscape. Large integrated pharmaceutical companies with immunology infrastructure dominate biologics pipelines, while biotechnology firms lacking manufacturing scale pursue partnership structures at Phase II-to-III transitions. The market structure separates into three strategic archetypes: global immunology majors with validated cold-chain distribution, mid-cap biotech specialists with machine learning-enabled patient stratification, and regional contract research organizations managing site selection and recruitment. Competitive moves concentrate on academic medical center relationship deepening and adaptive licensing pathway exploitation.
Within the global immunology tier, AbbVie Inc. and Takeda Pharmaceutical exemplify archetypes anchored in North American and Japanese academic center networks respectively. Pfizer Inc. occupies a position representing broad geographic Phase II coverage across multiple continents. These named entities sit within a competitive structure where partnership valuation depends on biosimilar interchangeability evidentiary standards and cold-chain infrastructure access rather than manufacturing scale alone.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Takeda Pharmaceutical |
| Johnson & Johnson |
| Pfizer Inc. |
| AstraZeneca |
| Bristol Myers Squibb |
| Bausch Health Companies |
| Nestlé Health Science |
| Recordati Rare Diseases |
| Others |
Supply & Pricing Matrix
Ninety-day stability validation cycles for cold-chain biologics anchor pricing power to GMP-certified manufacturing clusters in the United States, Switzerland, and Japan. This lead-time concentration lets academic medical centers extract volume discounts while smaller developers absorb premium slotting fees at contract development organizations.
Pricing Analysis
Geographic price spreads of forty to sixty percent separate United States list prices from European reimbursement rates for identical TNF-alpha inhibitors. Three-tier pricing structure across originator biologics, biosimilars, and emerging small-molecule alternatives captures differential risk-return profiles. Cost compression in the anti-inflammatory segment stems from generic substitution rates exceeding ninety percent in gastroesophageal reflux indications. Hospital procurement departments demonstrate highest price sensitivity through centralized specialty pharmacy tenders, while specialty clinics accept premium positioning for cold-chain convenience.
Supply Chain Analysis
Inventory buffers of fourteen to twenty-one days at two-to-eight-degree distribution hubs constrain site selection to validated academic medical centers. Active pharmaceutical ingredient synthesis concentrates in India and China, with fill-finish operations anchored in Switzerland and the United States. Cold-chain logistics hinge on single-source relationships with specialized couriers certified for biologics transport. Tariff exposure on temperature-controlled containers threatens margin structures for European developers sourcing from Asian API manufacturers. Distribution runs through hospital-based specialty pharmacies and emerging outpatient infusion networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning-enabled patient stratification is collapsing the homogeneous enrollment pools that once sustained blockbuster economics, creating platform-level interoperability demands between biomarker diagnostics and therapeutic development pipelines.
For Market Incumbents: Fortify academic medical center relationships through exclusive site selection agreements that lock out biosimilar competitors from Phase III recruitment networks. Deepen vertical integration into cold-chain distribution infrastructure to defend margin structures against investigator scarcity and premium CRO pricing. The priority threat is mid-cap biotech specialists with AI-enabled responder identification capabilities that decompose broad-label indications into niche subpopulations. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-track offers compressed regulatory timelines for inflammatory bowel disease assets with biomarker-defined responder populations. Target celiac disease as the most penetrable therapeutic area, where zero approved pharmacotherapies eliminate incumbent defensive positioning. Pursue partnership structures with established immunology majors at Phase II-to-III transition points rather than building captive commercial infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical parents seeking to divest non-core GI assets amid portfolio prioritization shifts toward oncology and rare disease platforms. Long-term viability in this market rests on adaptive licensing pathway expertise and EMA reimbursement dialogue capabilities rather than manufacturing scale alone. Watch for inflection signals in health technology assessment front-loading activity among European biotechnology firms.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Licensing Pathway Exploitation | EMA frameworks enable European revenue before full registrational completion for IBD biologics. |
| Biomarker-Driven Patient Stratification | Machine learning models decompose homogeneous enrollment pools before Phase II initiation. |
| Academic Medical Center Partnership Deepening | Exclusive site agreements with Boston and Tokyo centers lock out competitor trial recruitment. |
| Cold-Chain Infrastructure Investment | Validated two-to-eight-degree distribution networks defend against investigator scarcity premiums. |
| Health Technology Assessment Front-Loading | Early payer dialogue in Geneva and Frankfurt secures reimbursement alignment before submission. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up and top-down triangulation cross-checked pipeline asset counts against disclosed R&D expenditure patterns.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning drug class, therapy area, clinical trial phase, and end-user archetype. CAGRs were derived from asset-level progression probabilities weighted by regulatory pathway acceleration factors and reimbursement landscape evolution. Forecast inputs incorporated investigator scarcity indices and cold-chain infrastructure capacity constraints.
Underlying assumptions cover stable regulatory evidentiary standards for biosimilar interchangeability, with deviation risk concentrated in FDA and EMA guidance shifts that could compress or extend development timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Injectable Cytotoxic Drugs Market
Pharmaceuticals
Global Chick Embryo Cell Rabies Vaccine Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Ceftriaxone Sodium (API) Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Galculus Bovis and Metronidazole Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market