
 Global Healthcare Middleware Market | 2026-2036
Global Healthcare Middleware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Middleware Market Intelligence
The consolidation of large hospital networks is decoupling middleware procurement decisions from individual departmental budgets. Major technology providers like Oracle Corporation leverage their extensive enterprise resource planning footprint to secure large contracts. InterSystems Corporation differentiates through its specialized data platforms for complex clinical environments. IBM Corporation competes by offering integrated solutions combining middleware with AI and analytics capabilities.
Healthcare middleware comprises a software layer that enables interoperability between otherwise incompatible healthcare applications, databases, and medical devices. Its core function relies on translating data formats and communication protocols, often adhering to standards like HL7 and FHIR for seamless information exchange. Among product types, integration engines form the foundational layer for most deployments. The shift toward cloud-based and hybrid deployment models is accelerating, driven by the need for scalability and reduced capital expenditure for hospitals and diagnostic centers.
Market access and product design are heavily influenced by data privacy and security regulations. The US Health Insurance Portability and Accountability Act (HIPAA) and the EU's General Data Protection Regulation (GDPR) set stringent requirements for handling patient information. Similar data governance rules from bodies like China's NMPA shape local implementation. Vendor selection will increasingly hinge on a platform's proven ability to manage cross-border data flows while maintaining compliance with these disparate regulatory regimes.
Market Dynamics
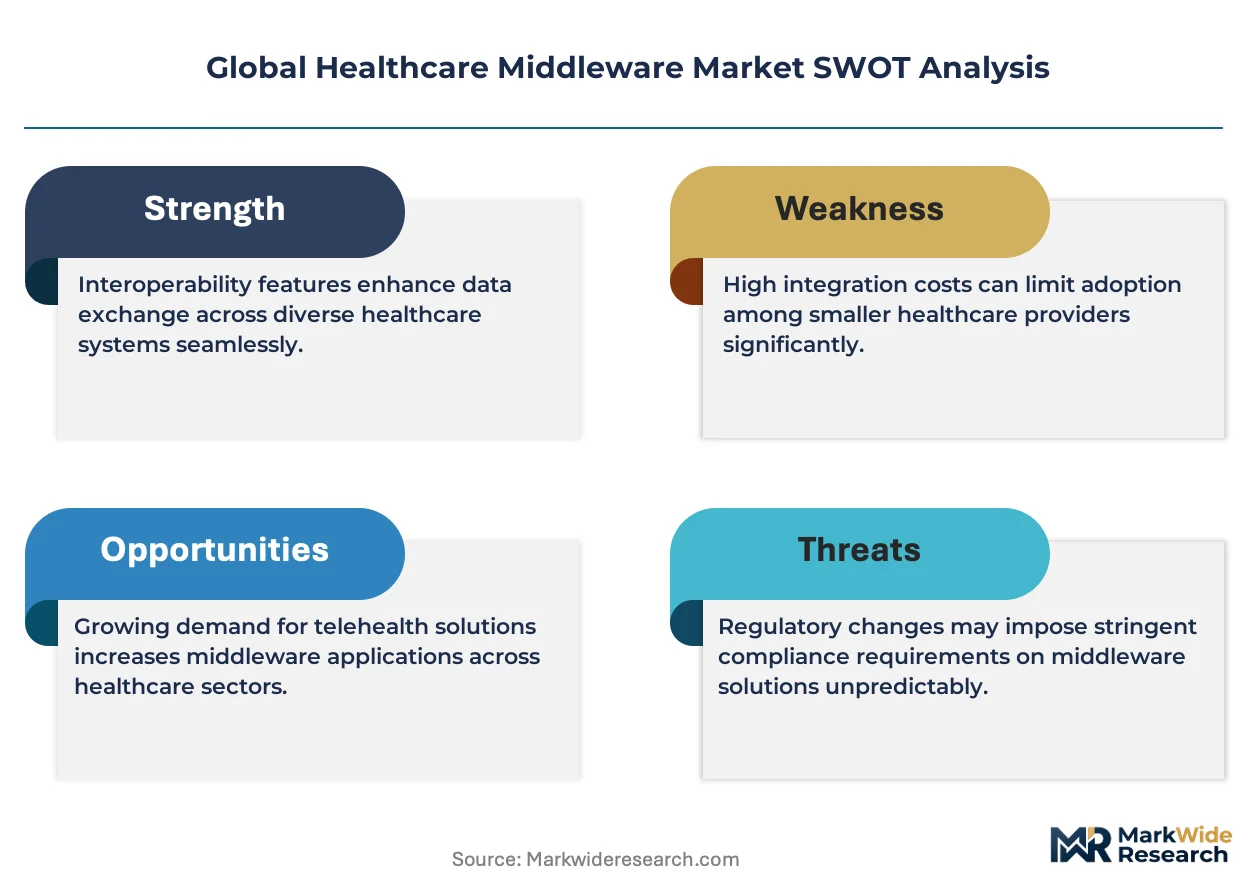
The market's structure is defined by the tension between the need for seamless data exchange across consolidated hospital networks and the increasing complexity of disparate data privacy regulations like HIPAA and GDPR. This forces a focus on compliant interoperability.
Growth Catalysts
- Regulatory Mandates:Europe's GDPR and China's NMPA rules require secure patient data exchange, compelling healthcare providers to adopt compliant middleware platforms.
- FHIR Standard Adoption:The implementation of the FHIR standard creates a common API-based language for health data, fueling demand for modern middleware.
- Provider Consolidation:Large hospital networks centralize IT procurement, favoring scalable, enterprise-wide middleware to ensure data consistency across multiple facilities.
Market Restraints
- High Implementation Costs:Significant capital expenditure and specialized IT labor for initial deployment are a major barrier for smaller hospitals and clinics.
- Legacy System Complexity:Integrating with proprietary, outdated electronic health record systems creates technical hurdles and extends deployment timelines for middleware.
- Data Sovereignty Rules:Conflicting data localization laws, particularly between China and the EU, complicate architectures for compliant cross-border data exchange.
Strategic Opportunities
- Emerging Market Entry:Healthcare IT modernization in Southeast Asia and Latin America creates greenfield opportunities for cloud-based middleware platforms.
- Remote Patient Monitoring:The expansion of telehealth creates demand for middleware that integrates data from home-based medical devices into core clinical systems.
- Embedded AI Capabilities:A significant opportunity lies in embedding AI within middleware to provide real-time clinical decision support directly in existing workflows.
Industry Challenges
- Specialized Talent Scarcity:A shortage of IT professionals with expertise in healthcare standards like HL7 and FHIR, combined with cybersecurity skills, constrains implementation and support.
- Device Interoperability Gaps:A lack of standardization among medical device manufacturers creates persistent challenges for middleware in reliably connecting and translating data from diverse endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Middleware Market |
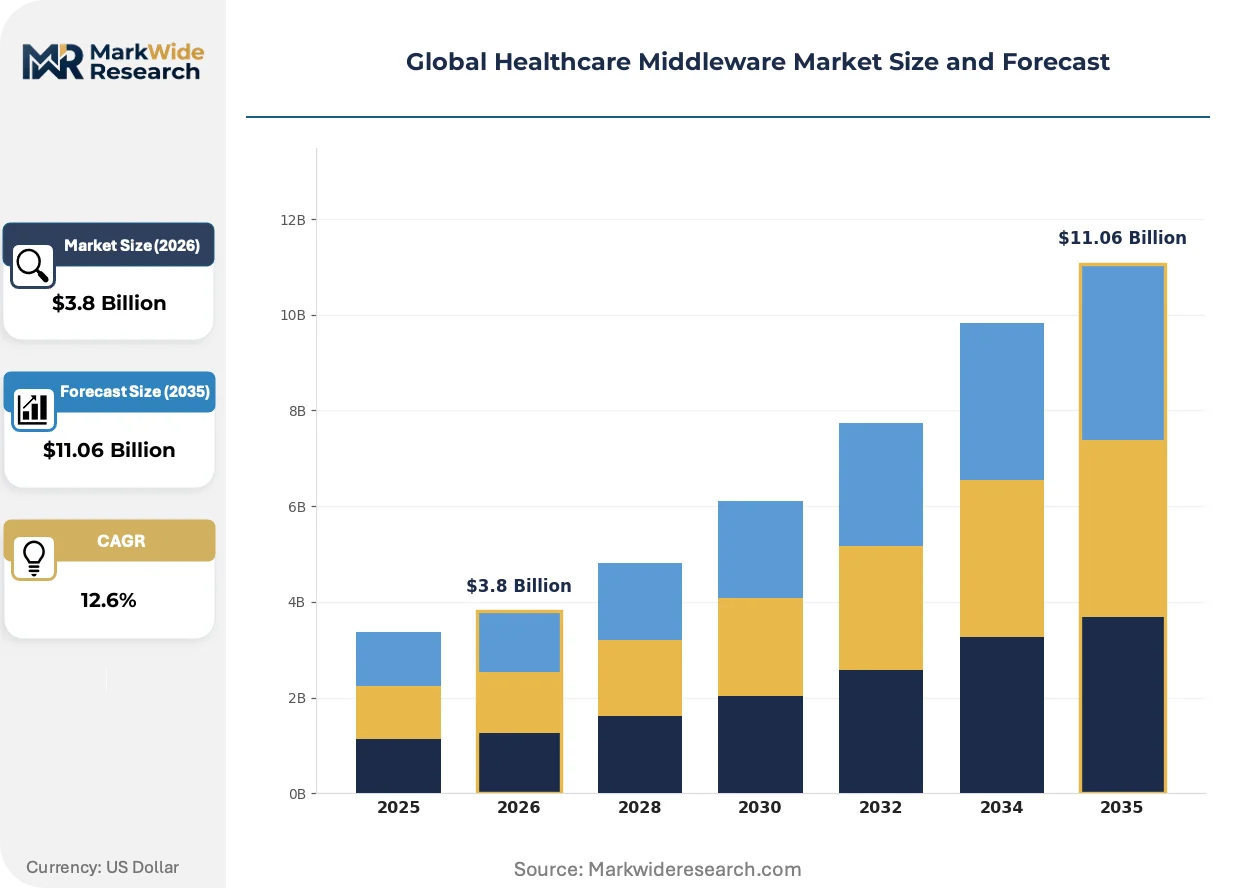
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integration Engines, Clinical Data Repository, Interface Engines, Data Analytics Platforms, Communication Server Application: Patient Data Management, Clinical Workflow Automation, Telehealth Support, Health Information Exchange, Remote Monitoring End User: Hospitals, Diagnostic Centers, Ambulatory Care, Research Institutions, Pharmaceutical Firms Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | InterSystems Corporation, IBM Corporation, Informatica, Orion Health Group, Fujitsu Ltd., Epic Systems Corporation, Oracle Corporation, Redox Inc., Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Middleware Market Strategic Shifts & Innovations
This market is shifting from basic data translation to intelligent interoperability. The evolution reflects the convergence of cloud computing, advanced data standards, and new healthcare delivery models demanding more dynamic and scalable data exchange.
Cloud-native integration platforms, or iPaaS, provide scalable, API-centric tools for connecting disparate applications and data sources. Large hospital systems and diagnostic centers are increasingly adopting these solutions to reduce on-premise infrastructure. This cloud-native architecture is absorbing the core functions of traditional on-premise integration engines, compressing the need for dedicated server hardware.
The European Union's proposed European Health Data Space (EHDS) regulation aims to create a unified framework for health data access. This policy mandates standardized formats for cross-border data exchange to support patient care and secondary research uses. Middleware vendors targeting the EU are proactively embedding EHDS-compliant features, especially for customers in the large German and French hospital sectors.
A definitive shift from perpetual software licenses to subscription-based, as-a-service consumption models is underway. This model disrupts the traditional large upfront capital expenditure, replacing it with predictable operational expenses that align with hospital budgeting cycles. This transition is most visible in the US and UK healthcare markets where financial pressures on providers are acute.
Global Healthcare Middleware Market Segmentation
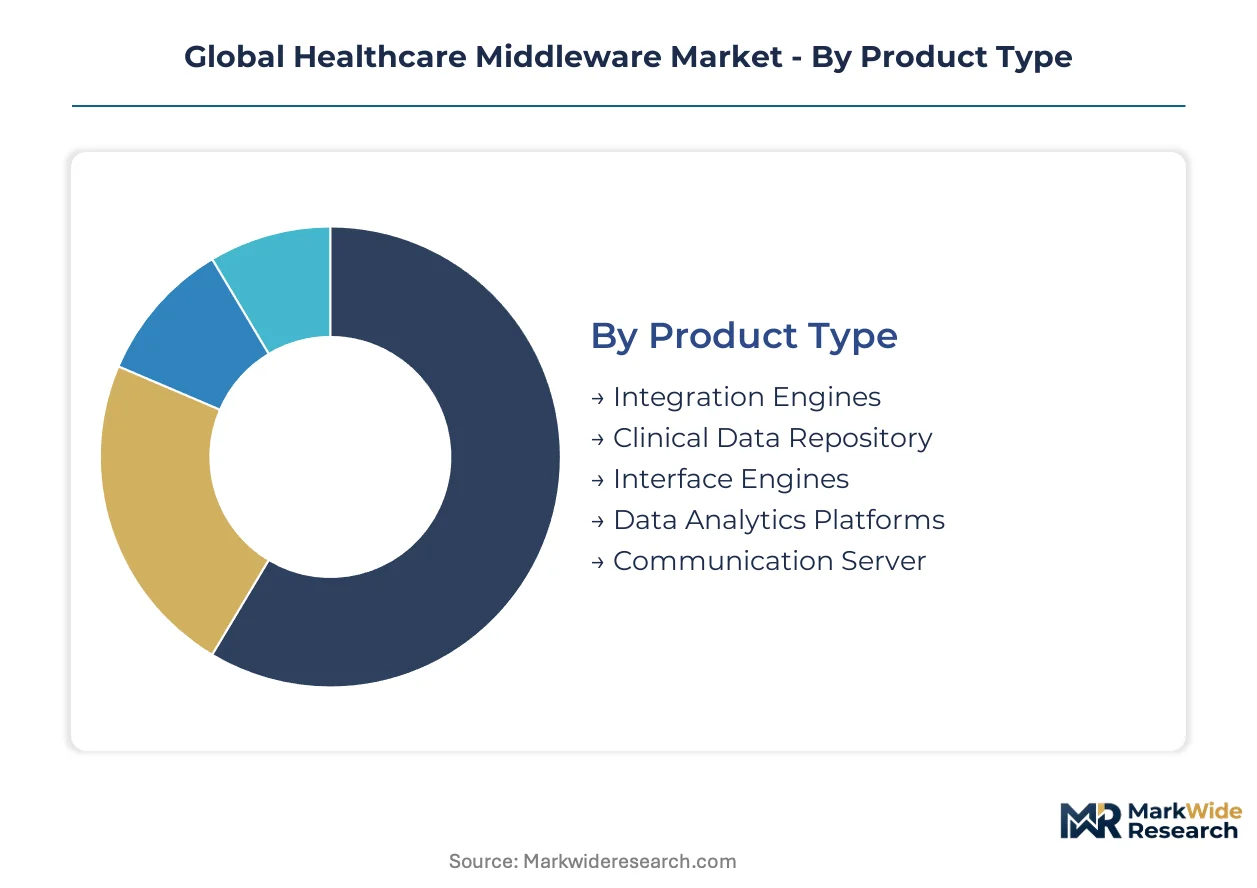
Segmentation of the global healthcare middleware market illuminates how diverse technological requirements and operational models shape platform adoption. Understanding these distinct segments allows technology providers to tailor solutions for specific clinical and administrative challenges. This breakdown highlights areas of concentrated demand and emerging growth trajectories.
Product Type:
The market for healthcare middleware products differentiates by the depth of integration offered, from foundational data translation layers to advanced analytical tools.
- Integration Engines:Foundational software facilitating data flow between disparate healthcare systems by translating various formats and protocols. Robust demand exists in large hospital networks across the US and Germany, driven by consolidating patient records from multiple facilities.
- Clinical Data Repository:A centralized database storing and managing patient clinical information from diverse sources, providing a unified view for professionals. Hospitals in Japan and the UK increasingly adopt these systems to improve data accessibility for clinical decision support.
- Interface Engines:Specialized software enabling communication between two specific applications, often for point-to-point connections within a department.
- Data Analytics Platforms:Integrated tools processing and interpreting large volumes of healthcare data, supporting predictive modeling and operational insights.
- Communication Server:Facilitates secure, standardized message exchange between healthcare applications, critical for real-time information sharing.
Integration Engines leads volumes today; Clinical Data Repository is gaining share fastest.
Application:
Application segments reflect the primary clinical or administrative functions that middleware platforms are designed to enhance within healthcare organizations.
- Patient Data Management:Focuses on organizing, securing, and providing access to comprehensive patient information across care settings, ensuring data consistency and regulatory compliance. US healthcare systems prioritize this middleware to comply with HIPAA and support value-based care.
- Telehealth Support:Middleware enabling secure, efficient data exchange between remote patient monitoring devices, virtual consultation platforms, and electronic health records. Demand in Canada and Australia expands rapidly, driven by digital health infrastructure investments.
- Clinical Workflow Automation:Middleware streamlines clinical processes, reducing manual tasks and improving efficiency in order entry and results reporting.
- Health Information Exchange:Facilitates secure sharing of patient health information among different providers, promoting coordinated care.
- Remote Monitoring:Connects home-based medical devices with clinical systems, allowing continuous oversight of patient health metrics.
Patient Data Management applications hold significant market share, while Telehealth Support applications are expanding most quickly.
End User:
The end-user segmentation highlights the diverse institutional environments that deploy healthcare middleware, each with unique scale and integration requirements.
- Hospitals:Large, complex healthcare institutions requiring comprehensive middleware to integrate numerous departmental systems, EHRs, and medical devices. Hospitals in Germany and France are major adopters, driven by national digital health strategies.
- Diagnostic Centers:Facilities specializing in medical imaging and laboratory testing, needing middleware to connect diagnostic equipment with patient management systems and facilitate rapid report delivery. Growth is notable in India and Brazil, where service expansion requires efficient data flow.
- Ambulatory Care:Outpatient clinics and physician offices utilize middleware to manage patient records, appointments, and billing across smaller networks.
- Research Institutions:Leverage middleware for secure data aggregation and exchange, supporting clinical trials and health studies, maintaining GDPR compliance.
- Pharmaceutical Firms:Employ middleware to integrate clinical trial data, R&D systems, and regulatory submission platforms, enhancing drug development.
Hospitals remain the dominant end-user segment, with Diagnostic Centers showing a steep expansion trajectory.
Deployment:
Deployment models for healthcare middleware reflect varying preferences for infrastructure ownership, scalability, and operational expenditure among healthcare providers.
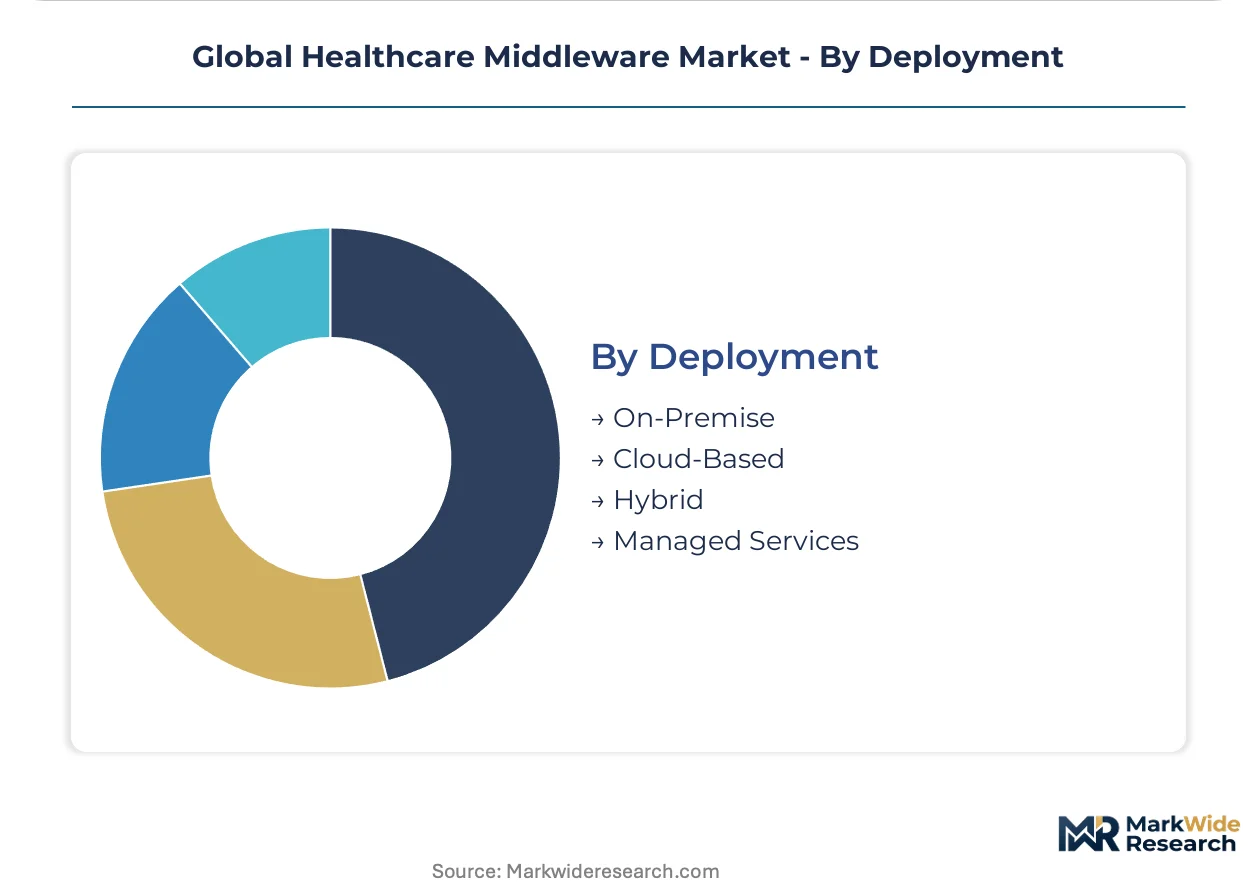
- Cloud-Based:Middleware hosted and managed by a third-party provider, accessed via the internet, offering scalability, reduced upfront costs, and easier maintenance. Rapid adoption in the US and UK, as providers seek operational efficiencies without large capital investments.
- Hybrid:Combines on-premise infrastructure with cloud-based services, allowing organizations to maintain sensitive data locally while leveraging cloud benefits for less critical functions. Large hospital systems in Canada and Australia favor hybrid approaches for data sovereignty and disaster recovery.
- On-Premise:Middleware installed and managed directly within an organization's own data centers, providing maximum control over data and security.
- Managed Services:Outsourced management of middleware operations by a third-party vendor, covering deployment, maintenance, and support for healthcare IT departments.
On-Premise deployment still holds a substantial base, but Cloud-Based and Hybrid models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany exhibit distinct yet powerful drivers for healthcare middleware adoption. US demand centers on HIPAA-compliant patient data management, while Germany focuses on national digital health strategies. Both nations prioritize robust interoperability for their complex healthcare ecosystems.
United States
Strong demand for patient data management and telehealth support drives middleware growth in the United States. HIPAA mandates secure patient information exchange, compelling widespread platform adoption across providers. Technology hubs like Boston and Silicon Valley see active development of cloud-based integration solutions for large hospital networks.
Germany
Germany's large hospital systems require comprehensive middleware to integrate numerous departmental systems and EHRs. National digital health strategies and the proposed European Health Data Space push for standardized data formats. The Berlin-Brandenburg region actively develops interoperability solutions for its extensive hospital sector and research institutions.
Japan
Hospitals in Japan increasingly adopt clinical data repositories to improve data accessibility for clinical decision support. METI initiatives promote digital transformation in healthcare, encouraging secure data exchange platforms. The Tokyo metropolitan area hosts major technology firms innovating in healthcare data integration for complex clinical environments.
China
China's NMPA rules necessitate secure patient data exchange, compelling healthcare providers to adopt compliant middleware platforms. The government's push for healthcare IT modernization creates greenfield opportunities for cloud-based solutions. The Yangtze River Delta region, with its dense hospital networks, is a focal point for integrating diagnostic centers and patient management systems.
Canada
Canada sees rapid expansion in telehealth support applications, driven by digital health infrastructure investments. Health Canada guidelines emphasize secure and efficient data exchange for remote patient monitoring devices. The Toronto-Waterloo corridor is a significant hub for developing hybrid deployment models favored by large hospital systems.
Global Healthcare Middleware Market Key Industry Players
United States-based software producers anchor one tier of the healthcare middleware market, often leveraging extensive domestic healthcare infrastructure; European specialists hold another, focusing on GDPR compliance and cross-border data exchange. The market exhibits a tiered structure, with large enterprise solution providers coexisting with niche clinical interoperability firms. Strategic archetypes include established IT conglomerates, specialized healthcare data platform vendors, and agile cloud-native integration engine providers. Companies primarily engage in strategic partnerships, portfolio diversification, and targeted acquisitions to enhance their offerings and expand market reach.
Among technology giants, Oracle Corporation exemplifies a broad enterprise resource planning footprint, leveraging its extensive ecosystem. IBM Corporation represents integrated solutions combining middleware with AI and analytics capabilities, targeting complex clinical environments. Microsoft Corporation also occupies a position as a major cloud services provider, offering scalable, API-centric tools for connecting disparate healthcare applications and data sources. These firms leverage extensive existing client bases and cloud infrastructure to secure large contracts within consolidated hospital networks and diagnostic centers.
| Leading Market Players |
|---|
| InterSystems Corporation |
| IBM Corporation |
| Informatica |
| Orion Health Group |
| Fujitsu Ltd. |
| Epic Systems Corporation |
| Oracle Corporation |
| Redox Inc. |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
The clear performance gap between cloud-native integration platforms and legacy on-premise engines manifests in distinct pricing models and supply chain dependencies. This divergence shapes how healthcare providers procure and implement middleware solutions.
Pricing Analysis
Capacity additions in cloud infrastructure are reshaping price floors for middleware solutions, particularly for scalable, API-centric tools. Subscription-based, as-a-service models dominate, replacing perpetual licenses. Price differentiation stems from compliance with stringent regulations like HIPAA and GDPR, alongside the level of specialized integration services required. Cost compression in the US and UK healthcare markets intensifies due to provider financial pressures. Smaller hospitals and clinics exhibit higher price sensitivity compared to large, consolidated hospital networks.
Supply Chain Analysis
Workforce availability in technology hubs like the United States and Germany directly impacts the supply of specialized healthcare middleware talent. The supply chain concentrates around major technology providers in the US and European specialists, drawing heavily on cloud infrastructure and expertise in standards like HL7 and FHIR. Specialized talent scarcity represents a significant structural risk, constraining implementation and support. Data sovereignty rules, particularly between China and the EU, further complicate compliant cross-border data exchange architectures. Distribution runs through direct enterprise sales teams and cloud marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The healthcare middleware market is entering a late-cycle quality story, driven by a demand-shift toward intelligent interoperability with embedded AI capabilities.
For Market Incumbents: Anticipate continued pressure from legacy system complexity and the scarcity of specialized IT talent. Incumbents like Oracle Corporation must leverage their extensive enterprise resource planning footprint to secure large contracts. Investing in FHIR standard adoption and EHDS-compliant features will defend market share, especially in Germany and France. Consolidating offerings to provide integrated solutions with AI and analytics, as IBM Corporation does, addresses complex clinical environments.
For New Entrants and Emerging Players: Capture greenfield opportunities in emerging markets like Southeast Asia and Latin America with cloud-based middleware platforms. The Telehealth Support application segment in Canada and Australia represents a highly penetrable area for specialized solutions. Focus on providing cloud-native iPaaS tools that offer scalability and reduced capital expenditure. Integrating data from home-based medical devices into core clinical systems provides a unique go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory complexity demands specialized compliance and integration capabilities. The market demonstrates long-term viability, driven by persistent data interoperability requirements across healthcare systems. Investors should target agile cloud-native integration engine providers or specialized healthcare data platform vendors. A key signal to watch is the proactive embedding of EHDS-compliant features, indicating readiness for future European market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Development | Reduces capital expenditure for hospitals and enhances scalability for data exchange. |
| FHIR Standard Integration | Creates a common API-based language for health data, facilitating seamless information exchange. |
| AI/Analytics Embedding | Provides real-time clinical decision support directly within existing healthcare workflows. |
| Data Sovereignty Compliance Tools | Ensures adherence to disparate regulatory regimes like GDPR and China's NMPA for cross-border data flows. |
| Telehealth Data Connector Partnerships | Expands middleware's reach to integrate home-based medical devices into core clinical systems. |
Research Approach
Multiple input streams — primary interviews, regulatory documentation, and financial disclosures — were reconciled through a rigorous data collection process. Conversations with IT procurement officers, clinicians, and hospital purchasing committees provided qualitative insights. Secondary validation involved analysis of SEC filings, HIPAA and GDPR guidelines, and industry association reports. This approach ensured robust bottom-up and top-down triangulation of market data.
The analytical framework integrated reconciled data streams to project market trajectories across the analysis window. Segmentation dimensions modeled included product type, application, end user, and deployment model. Compound annual growth rates were derived from historical data analysis and projected demand shifts. Key forecast inputs included healthcare IT spending trends and regulatory compliance investment patterns.
New regulatory mandates, unforeseen technological disruptions, and shifts in healthcare funding models are the dominant revision risks for market forecasts. These projections reflect assumptions regarding market evolution and stakeholder behavior. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Laboratory Informatics Market
Health Informatics
Global E-Health Market
Health Informatics
Allergy Care Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
Global Ambulatory EHR Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
AI in Healthcare Market
Health Informatics
IHE XDS.B Market
Health Informatics
Global Healthcare Integration Market