
 Secondary Myelofibrosis Therapeutics Market | 2026-2036
Secondary Myelofibrosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Secondary Myelofibrosis Therapeutics Market Analytics
Hospital procurement for myelofibrosis regimens is consolidating around large academic medical centers with dedicated myeloproliferative neoplasm programs. Incyte Corporation dominates the JAK inhibitor landscape through deep clinical infrastructure. Bristol-Myers Squibb Company competes via its established hematology franchise and investigator networks. Pfizer Inc. anchors its position through manufacturing scale and broad oncology distribution channels.
Secondary myelofibrosis therapeutics comprise pharmaceutical agents targeting dysregulated JAK-STAT signaling, marrow fibrosis, and associated constitutional symptoms in patients who develop myelofibrosis following prior myeloproliferative disorders. JAK Inhibitors command the largest revenue share due to established efficacy in spleen volume reduction and symptom burden improvement. Oral administration routes lead in patient preference metrics, though intravenous formulations retain share in hospitalized acute cases. Targeted Therapy represents the fastest-expanding category as novel mechanisms beyond JAK inhibition advance through clinical pipelines.
The FDA and EMA govern pivotal trial design and post-marketing surveillance requirements for this therapeutic class, with FDA accelerated approval pathways compressing time-to-market for agents demonstrating surrogate endpoint benefits. The EU AI Act and GDPR impose emerging compliance burdens on real-world evidence generation and patient data utilization for post-approval studies. Stakeholders must monitor regulatory divergence between US and European evidentiary standards for progression-free survival endpoints.
Market Dynamics
FDA accelerated approval pathways for oncology therapies are compressing commercialization timelines, forcing incumbents to accelerate real-world evidence generation while defending established JAK inhibitor positions against mechanistically novel entrants.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's oncology surrogate endpoint framework enables earlier market entry for agents demonstrating spleen volume reduction benefits, shortening development cycles for targeted therapies.
- Academic Medical Center Consolidation:Hospital procurement is concentrating around tertiary centers with dedicated myeloproliferative neoplasm programs, creating centralized high-volume sites for protocol adoption.
- JAK-STAT Biology Elucidation:Deeper understanding of signaling dysregulation in secondary transformation is expanding addressable patient populations beyond primary myelofibrosis indications.
Market Restraints
- Specialized Manufacturing Concentration:Active pharmaceutical ingredient production for kinase inhibitors clusters in limited contract manufacturing organizations, creating single-source vulnerability for commercial supply.
- EMA-FDA Evidentiary Divergence:European regulators demand more mature progression-free survival data than FDA surrogate endpoints require, forcing dual-track clinical investment and delayed EU launches.
- Biosimilar Substitution Threat:Patent cliffs on first-generation JAK inhibitors expose revenue streams to forthcoming biosimilar competition in hematology-oncology formularies.
Strategic Opportunities
- Combination Regimen White Space:Pairing JAK inhibitors with agents targeting marrow fibrosis directly offers mechanistic synergy in patients with accelerated phase disease.
- Real-World Evidence Monetization:The EU AI Act and GDPR create compliance moats for sponsors with established patient data infrastructure, rewarding early investment in federated analytics platforms.
- Community Oncology Penetration:Outpatient administration protocols enable expansion beyond academic centers into regional hematology practices managing stable patients.
Industry Challenges
- Specialized Investigator Recruitment:Principal investigators with myeloproliferative neoplasm expertise concentrate at top-50 academic sites, creating trial startup bottlenecks and site activation delays.
- Biomarker Assay Standardization:Lack of harmonized molecular diagnostic criteria for secondary transformation complicates patient stratification and eligibility determination across protocols.
- Post-Marketing Surveillance Burden:FDA-mandated cardiovascular event monitoring for JAK inhibitors requires costly long-term follow-up infrastructure that strains mid-cap sponsor resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Secondary Myelofibrosis Therapeutics Market |
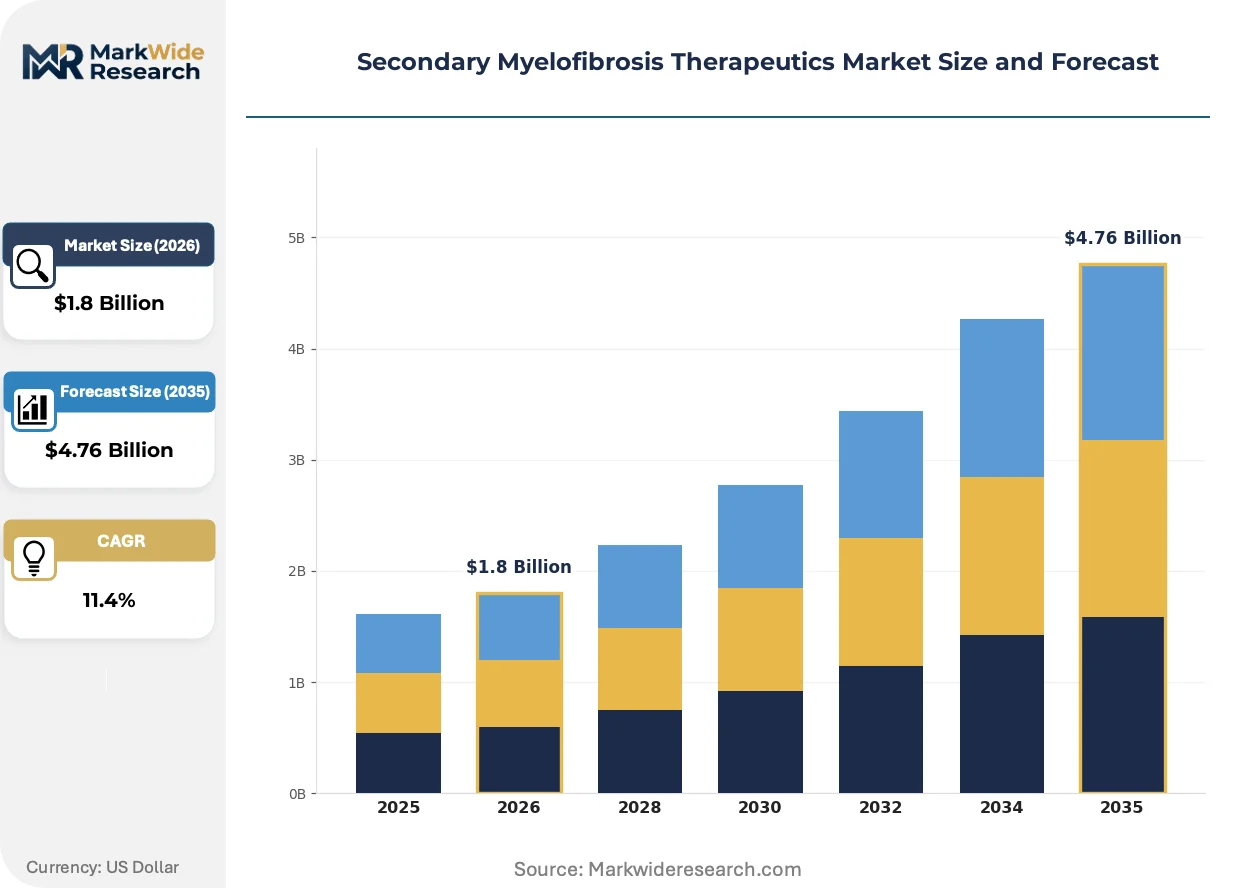
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: JAK Inhibitors, Chemotherapy, Immunotherapy, Targeted Therapy End User: Hospitals, Ambulatory Surgical Centers, Homecare Settings, Specialty Clinics Administration Route: Oral, Intravenous, Subcutaneous, Transdermal Therapeutic Stage: Clinical Trials, Post-Marketing, Preclinical Development, Market Approval |
| Companies Covered | AbbVie Inc., Pfizer Inc., Incyte Corporation, Imago BioSciences, Actuate Therapeutics Inc., Bristol-Myers Squibb Company, GlaxoSmithKline plc, Galecto, Inc., CTI BioPharma Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Secondary Myelofibrosis Therapeutics Market Evolving Landscape
Novel mechanisms beyond JAK inhibition are advancing through clinical pipelines, threatening to fragment the therapeutic landscape as sponsors bet on differentiated biology in a market long dominated by single-class dominance.
Targeted therapies directed at marrow fibrosis pathogenesis itself, rather than symptomatic JAK-STAT blockade, are overtaking traditional development priorities in sponsor portfolios. Academic medical centers with dedicated myeloproliferative neoplasm programs are prioritizing these agents in early-phase trial participation, compressing enrollment timelines for mechanism-first studies while lengthening control arm recruitment for JAK inhibitor comparators.
The EU AI Act's risk classification framework for clinical decision support tools is reshaping how sponsors deploy machine learning for patient identification in post-approval studies. European sites now require explicit governance documentation for algorithm-assisted eligibility screening, adding procedural friction that US sites under FDA guidance do not yet face. This regulatory asymmetry is diverting real-world evidence generation investment toward American tertiary care networks.
Hospital formulary committees are unbundling spleen response metrics from quality-of-life endpoints in value assessment frameworks, forcing manufacturers to generate discrete evidence packages for each outcome category. This behavioral shift concentrates contracting leverage at integrated delivery networks with sufficient patient volume to demand indication-specific pricing. The phenomenon is most visible in United States multi-hospital systems where pharmacy benefit managers negotiate indication-level rebates rather than class-level contracts.
Secondary Myelofibrosis Therapeutics Market Segmentation
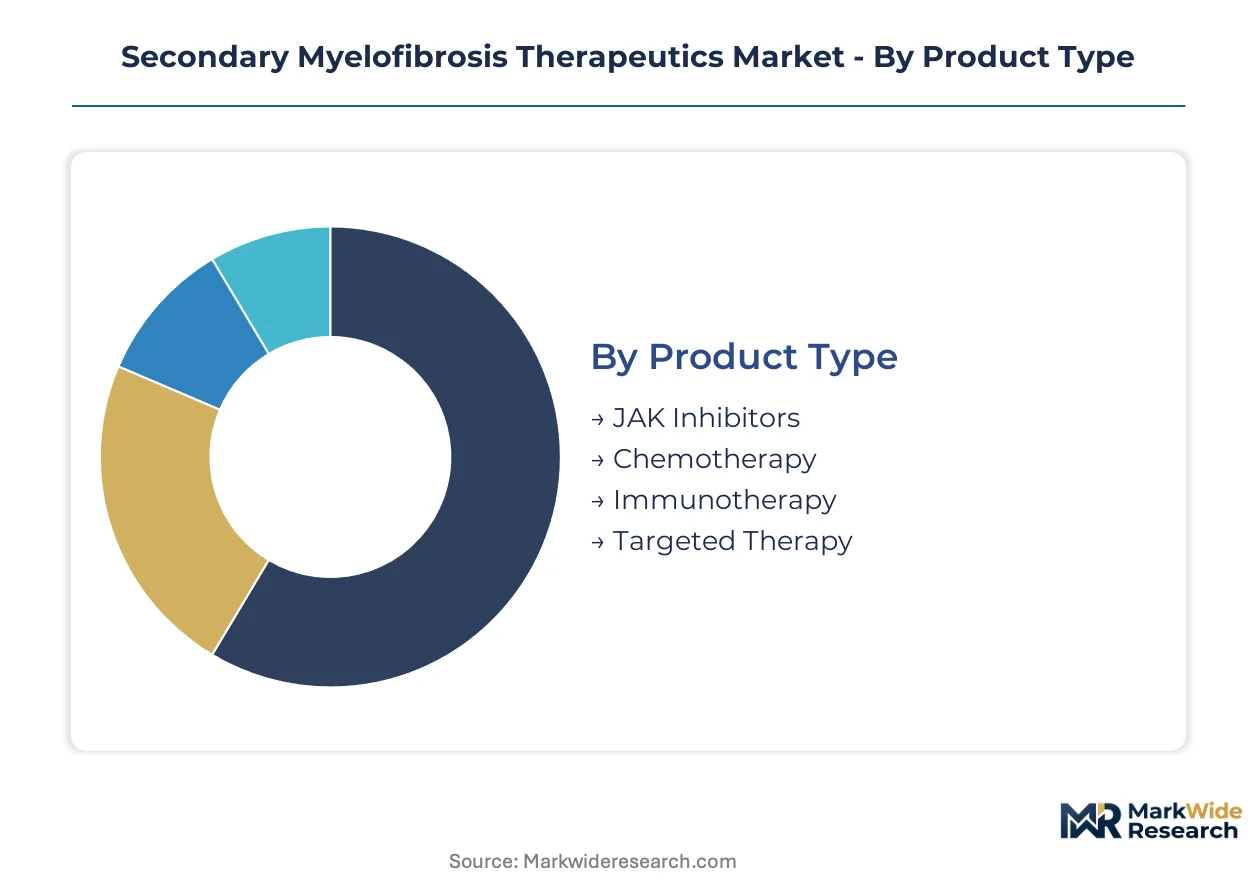
Secondary myelofibrosis therapeutics segment along four critical dimensions that determine prescribing patterns, reimbursement pathways, and commercial access. Product type dictates mechanism of action and formulary positioning. End user location shapes administration protocols and patient monitoring intensity. Route of administration drives compliance rates and care setting economics. Therapeutic stage governs regulatory investment and pipeline risk exposure.
Product Type:
JAK Inhibitors anchor volume share while Targeted Therapy commands premium pricing in academic centers.
- JAK Inhibitors:Small-molecule agents blocking JAK1/JAK2 kinase activity to interrupt constitutive STAT signaling in myeloproliferative neoplasms. Hospital-based hematology-oncology departments in the United States concentrate procurement around ruxolitinib protocols for spleen volume reduction. FDA accelerated approval pathways compress time-to-market for next-generation entrants in this class.
- Targeted Therapy:Novel mechanisms directed at marrow fibrosis pathogenesis itself rather than symptomatic JAK-STAT blockade, including BET inhibitors and antifibrotic biologics. Academic medical centers with dedicated myeloproliferative neoplasm programs prioritize these agents in early-phase trial participation. The EU AI Act's risk classification framework diverts real-world evidence generation investment toward American tertiary care networks for this emerging category.
- Chemotherapy:Cytotoxic regimens reserved for accelerated-phase or blast-crisis transformation requiring rapid cytoreduction.
- Immunotherapy:Immune checkpoint and cellular approaches exploring modulation of the tumor microenvironment in fibrotic marrow.
Today's leader: JAK Inhibitors. Tomorrow's challenger: Targeted Therapy.
End User:
Care setting fragmentation reflects disease severity stratification and reimbursement mechanics across the treatment continuum.
- Hospitals:Tertiary and quaternary centers manage acute complications, stem cell transplant evaluation, and protocol-driven JAK inhibitor initiation. Integrated delivery networks with pharmacy benefit managers negotiate indication-specific rebates that concentrate contracting leverage at high-volume academic sites.
- Specialty Clinics:Dedicated hematology-oncology practices handle stable patient monitoring and oral therapy management. Community oncology penetration strategies target regional practices managing patients post-stabilization.
- Ambulatory Surgical Centers:Limited role confined to diagnostic bone marrow biopsy procedures and port placement.
- Homecare Settings:Emerging site for oral JAK inhibitor administration with remote monitoring protocols reducing hospital burden.
Hospitals capture the highest acuity cases. Specialty clinics represent the expansion frontier for oral therapy maintenance.
Administration Route:
Patient preference and clinical indication jointly determine route selection across the therapeutic lifecycle.
- Oral:Dominant preference metric for chronic JAK inhibitor therapy enabling outpatient disease management. Oral bioavailability and established efficacy in spleen response anchor commercial strategy for stable secondary myelofibrosis patients.
- Intravenous:Retains critical share in hospitalized acute cases requiring rapid symptom control or combination regimens. EMA-FDA evidentiary divergence forces dual-track clinical investment that delays EU launches for IV formulations.
- Subcutaneous:Investigational delivery for biologic agents targeting marrow fibrosis directly.
- Transdermal:Preclinical exploration for continuous low-dose JAK inhibitor delivery.
Oral administration leads patient preference. Intravenous formulations defend position in acute care settings.
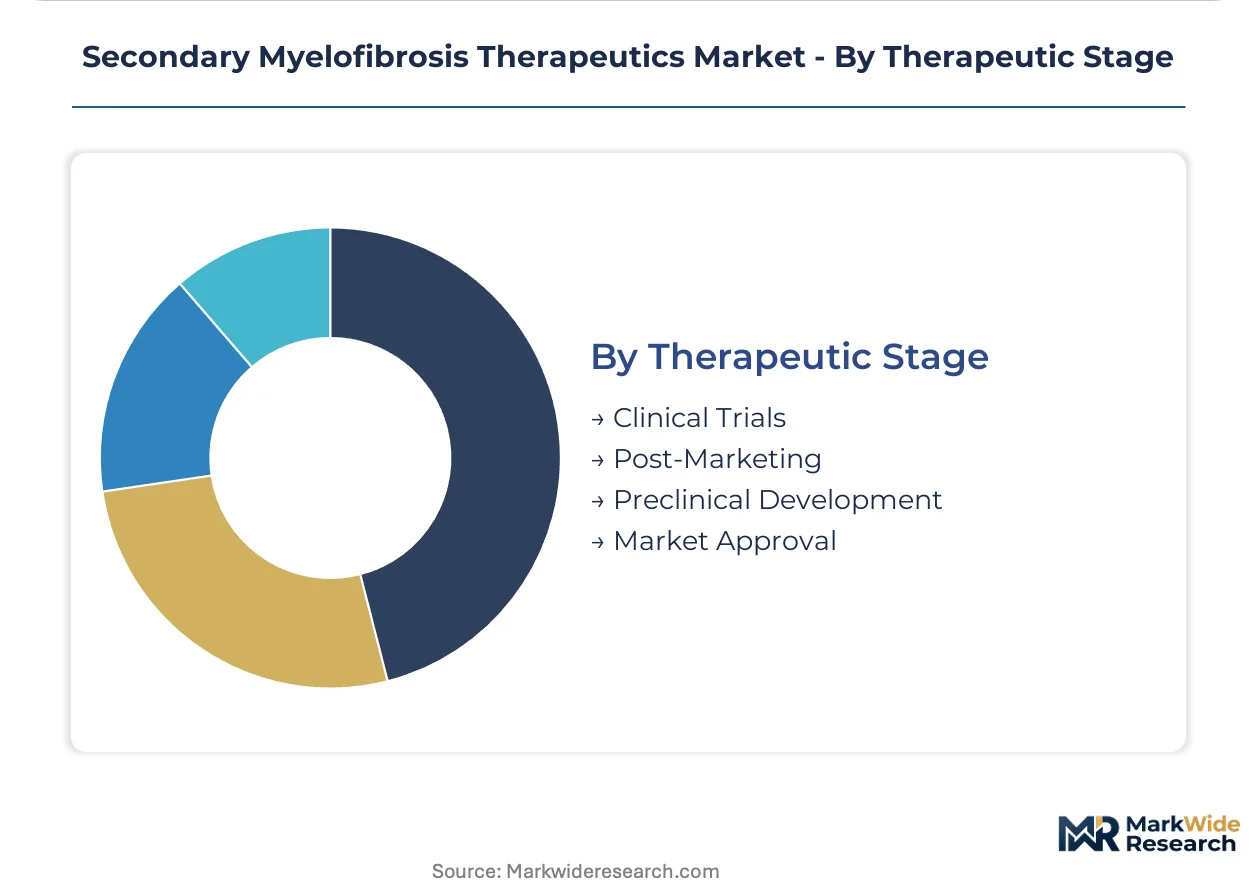
Therapeutic Stage:
Development phase determines capital intensity, regulatory risk, and commercialization timeline exposure.
- Market Approval:Established agents with FDA or EMA authorization generating commercial revenue through hospital formulary placement. Post-marketing surveillance requirements for cardiovascular event monitoring strain mid-cap sponsor resources.
- Clinical Trials:Active enrollment in Phase II and III studies for mechanism-first agents beyond JAK inhibition. Specialized investigator recruitment concentrates at top-50 academic sites creating enrollment bottlenecks.
- Preclinical Development:Early-stage programs exploring combination regimens pairing JAK inhibitors with antifibrotic agents.
- Post-Marketing:Real-world evidence generation and label expansion studies mandated by accelerated approval conditions.
Market Approval segments command current revenue. Clinical Trials segments carry the steepest expansion trajectory for novel mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hematologist-oncologists concentrate in tertiary academic centers across five countries, anchoring protocol adoption and clinical trial enrollment for JAK inhibitor therapies.
United States
Hospital-based hematology-oncology departments at Mayo Clinic, MD Anderson, and Memorial Sloan Kettering manage the highest secondary myelofibrosis patient volumes. FDA accelerated approval pathways compress commercialization timelines for surrogate endpoint demonstrations. The Boston-Cambridge corridor anchors biotech R&D clustering for novel mechanism agents.
Germany
University hospitals in Heidelberg, Munich, and Hamburg concentrate myeloproliferative neoplasm expertise and early-phase trial participation. EMA evidentiary standards for progression-free survival endpoints exceed FDA requirements, delaying launches for mechanism-first therapies. The Rhine-Main biotech cluster houses contract research organizations supporting real-world evidence generation.
United Kingdom
NHS England's specialized commissioning frameworks centralize high-cost JAK inhibitor prescribing at designated hematology centers. NICE technology appraisals demand mature quality-of-life data beyond spleen response metrics. The London-Oxford-Cambridge golden triangle anchors academic investigator networks for clinical trial activation.
Japan
PMDA's Sakigake designation system accelerates review for agents addressing unmet needs in myelofibrosis transformation. Tokyo and Osaka academic medical centers concentrate patient access for approved JAK inhibitors. Kansai region pharmaceutical manufacturing clusters supply active pharmaceutical ingredients for kinase inhibitor production.
Switzerland
Swissmedic's reliance on EMA centralized procedures streamlines market access for approved therapeutics. Basel and Zurich university hospitals participate in multinational Phase III protocols for novel antifibrotic mechanisms. The country's contract manufacturing organizations produce specialized kinase inhibitor intermediates for global supply.
Secondary Myelofibrosis Therapeutics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the therapeutic landscape, creating a tiered structure where scale-driven pharmaceutical companies defend established positions against mechanism-first biotechnology entrants. Large-cap incumbents leverage manufacturing infrastructure and oncology distribution networks while mid-cap innovators pursue accelerated approval pathways for differentiated biology. Strategic moves concentrate on real-world evidence generation infrastructure and academic medical center contracting relationships.
Within the diversified pharmaceutical tier, Pfizer Inc. and Bristol-Myers Squibb Company occupy positions anchored by broad hematology franchises and established investigator networks. Incyte Corporation exemplifies the focused specialist archetype, representing deep clinical infrastructure concentration in JAK-STAT pathway therapeutics. AbbVie Inc. sits within the emerging competitor tier, leveraging immunology and oncology cross-functional capabilities.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Incyte Corporation |
| Imago BioSciences |
| Actuate Therapeutics Inc. |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline plc |
| Galecto, Inc. |
| CTI BioPharma Corp |
| Others |
Value Network & Pricing Analysis
Biotech-specialist sponsors rolled up through private-equity platforms anchor pricing discipline through concentrated manufacturing partnerships, while their reliance on single-source active pharmaceutical ingredient producers creates vulnerability that contract manufacturers exploit in long-term offtake negotiations.
Pricing Analysis
Bundled spleen response and quality-of-life endpoints are unbundling into discrete evidence packages demanded by integrated delivery networks with pharmacy benefit managers. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center protocols from community oncology access tiers, with price differentiation driven by indication-specific contracting and cardiovascular monitoring service inclusion. Pricing pressure stems from forthcoming biosimilar substitution on first-generation JAK inhibitors. Community hematology practices exhibit highest price sensitivity; tertiary transplant centers demonstrate lowest.
Supply Chain Analysis
Active pharmaceutical ingredient production for kinase inhibitors rests on contract manufacturing organizations concentrated in Switzerland, India, and Japan, with Kansai region clusters supplying specialized intermediates for global JAK inhibitor programs. Raw material dependencies include high-purity starting reagents, specialized chromatography resins, and single-use bioreactor components. Single-source vulnerability for commercial supply creates structural risk following recent regulatory inspections. Distribution runs through cold-chain logistics networks serving hospital-based hematology-oncology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary myelofibrosis therapeutics represent a late-cycle quality story as demand concentrates toward premium mechanism-first agents with direct antifibrotic activity beyond symptomatic JAK-STAT blockade.
For Market Incumbents: Extend real-world evidence generation infrastructure into American tertiary care networks before EU AI Act compliance burdens mature, while accelerating cardiovascular outcome study completion to defend against biosimilar substitution threats in community oncology formularies. Deepen backward integration into specialized kinase inhibitor intermediate production to reduce single-source contract manufacturing exposure.
For New Entrants and Emerging Players: Enter via combination regimen white space pairing JAK inhibitors with marrow fibrosis-directed biologics, targeting accelerated-phase patients at academic medical centers with dedicated myeloproliferative neoplasm programs. Prioritize FDA accelerated approval pathway positioning over EMA dual-track investment to compress time-to-revenue. Deploy federated analytics platforms as compliance moat for post-approval studies.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap mechanism-first specialists with Phase II antifibrotic assets and established principal investigator relationships at top-50 academic sites. Long-term viability hinges on successful progression-free survival differentiation in a market transitioning beyond JAK inhibitor dominance. Watch for FDA confirmatory trial readouts as inflection indicators for portfolio rebalancing toward novel biology.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates enrollment for mechanism-first agents at academic sites with myeloproliferative neoplasm expertise. |
| Regulatory Approval Pathway | FDA accelerated approval compresses commercialization timelines for surrogate endpoint demonstrations. |
| Manufacturing Scale-Up | Expands captive production of kinase inhibitor intermediates to reduce single-source vulnerability. |
| Pipeline Diversification | Adds antifibrotic biologics beyond JAK-STAT blockade to address marrow fibrosis pathogenesis directly. |
| Strategic Partnership | Secures integrated delivery network contracts with indication-specific rebate structures for oral therapy maintenance. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, Japan, and Switzerland, with primary inputs from each market gathered through structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-volume modeling triangulates against top-down pharmaceutical revenue estimates across the therapeutic landscape.
Granularity-level framing applies treatment line, administration route, and patient population dimensions at the country-regulatory cluster level throughout the forecast period. CAGRs derive from epidemiological progression models, protocol adoption curves at academic medical centers, and pricing trajectory assumptions for mechanism-first entrants. Forecast inputs include myelofibrosis transformation incidence rates, JAK inhibitor persistence data, and real-world evidence generation investment flows.
The model holds under stable FDA-EMA regulatory convergence and continued academic medical center consolidation; deviation in evidentiary standard divergence or biosimilar entry timing would shift commercialization trajectory assumptions. A small set of named triggers warrants ongoing watch: cardiovascular outcome study readouts, EU AI Act enforcement patterns, and principal investigator recruitment bottlenecks at top-50 sites.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Cervical Cancer Drugs Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Europe Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Tetanus Toxoid Vaccine Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Viscosupplementation Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Global Pharmaceutical Gelatin Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
United Kingdom OTC Drugs Market