
 Aesthetics Combination Therapy Market | 2026-2036
Aesthetics Combination Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Aesthetics Combination Therapy Market Analysis
Medical-grade combination protocols is redrawing competitive boundaries across aesthetics. Galderma leverages its injectables portfolio to anchor combination therapy bundles with toxin-plus-filler regimens. Alma Lasers competes through integrated platform designs that merge laser delivery with radiofrequency energy in single devices.
Aesthetics combination therapy deploys synergistic modalities—typically pairing botulinum toxin with dermal fillers or coupling laser resurfacing with radiofrequency tightening—to achieve layered tissue remodeling beyond single-treatment outcomes. Non-surgical technology platforms command expanding share as patients prioritize downtime reduction alongside measurable results. Skin rejuvenation applications lead volume while acne treatment segments attract faster growth due to rising demand for scar revision protocols in younger demographics.
FDA device clearance requirements and HIPAA privacy mandates shape product development timelines and clinic marketing practices across the United States. CE marking under the EU MDR extends compliance obligations for manufacturers serving European dermatology centers. Stakeholders must monitor evolving reimbursement classifications for multi-modal procedures as payors recalibrate coverage policies for cosmetic-indication treatments.
Market Dynamics
Multi-modal treatment protocols are compressing the traditional separation between injectable and energy-based device categories, forcing manufacturers to bundle hardware with consumable ecosystems to capture recurring revenue streams.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's abbreviated pathway for laser-injectable combination systems accelerates commercialization timelines for device manufacturers targeting US dermatology practices.
- Medical spa channel expansion:Medspa operators in South Korea deploy ultrasound-microneedling protocols, creating demonstration effects that drive protocol adoption in neighboring markets.
- Scar revision demand surge:Younger patient demographics seek acne scar combination treatments, expanding addressable volume beyond traditional anti-aging applications.
Market Restraints
- Capital equipment intensity:Multi-modal platform acquisition costs strain independent dermatology clinics, favoring consolidated practice groups with balance sheet capacity.
- EU MDR compliance burden:CE marking renewal under the Medical Device Regulation extends European product launch timelines and elevates clinical evidence requirements.
- Single-modality substitution:Standalone fractional laser systems retain cost advantage for price-sensitive patient segments in emerging markets.
Strategic Opportunities
- India private clinic expansion:Underpenetrated metro dermatology centers present white space for toxin-plus-filler protocol training and device placement programs.
- Home-use device convergence:Radiofrequency-microneedling handheld systems create channel expansion beyond clinical settings into physician-supervised retail.
- Japan PMDA combination approvals:Regulatory precedent for multi-energy platform clearances enables faster Asian market entry for integrated system manufacturers.
Industry Challenges
- Cross-training workforce gaps:Clinicians require dual certification in injectable administration and laser operation, lengthening staff onboarding cycles.
- HIPAA-compliant marketing constraints:Before-and-after photography protocols for combination treatments demand enhanced patient consent workflows and data storage infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aesthetics Combination Therapy Market |
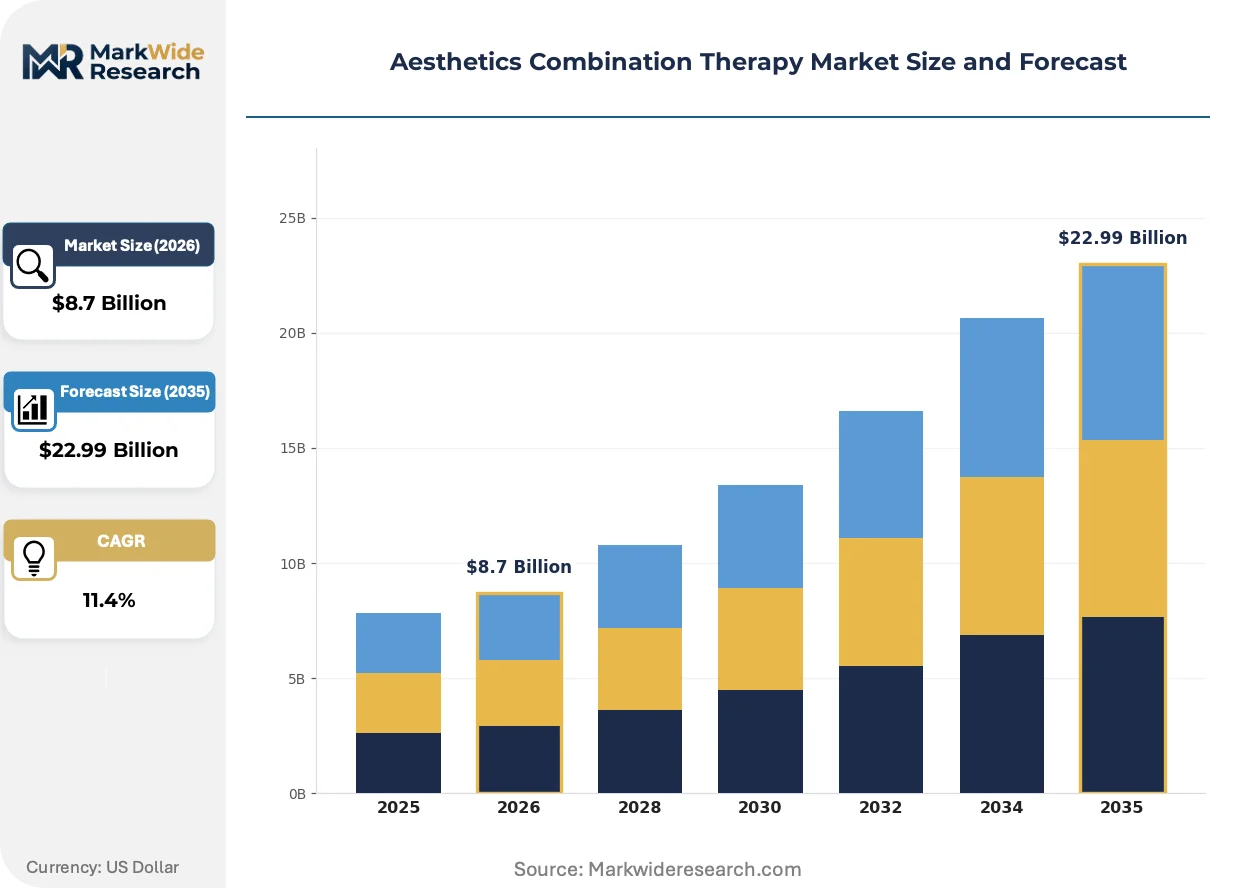
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Dermal Fillers, Lasers, Chemical Peels End User: Clinics, Dermatology Centers, Medical Spas, Hospitals Application: Skin Rejuvenation, Anti-Aging, Acne Treatment, Scarring Technology: Non-Surgical, Radiofrequency, Ultrasound, Microneedling |
| Companies Covered | Lutronic, Galderma, Alma Lasers, Merz Aesthetics, AbbVie/Allergan Aesthetics, Lumenis Be Ltd., Bausch & Lomb Incorporated, Sisram Medical Ltd., Cynosure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aesthetics Combination Therapy Market Emerging Trajectories
Device architecture is converging toward modular platforms that swap energy delivery heads and consumable cartridges, reducing capital redundancy across treatment rooms.
Radiofrequency microneedling technology is miniaturizing from cart-based systems to handheld pen devices. Medical spas in Seoul and Tokyo deploy these portable units for express facial protocols. The form factor reduction is compressing per-treatment pricing power and expanding technician-administered service menus.
EU MDR Article 10 clinical evaluation requirements now mandate post-market surveillance for combination energy devices. Manufacturers serving German and French dermatology centers must maintain active implant registries. The compliance burden is favoring larger device firms with dedicated regulatory affairs infrastructure over mid-tier competitors.
Patient acquisition is migrating from physician referral networks to direct-to-consumer social platforms. Instagram and TikTok content drives consultation bookings for toxin-plus-filler bundles in Los Angeles and Miami aesthetic practices. The channel shift is forcing clinics to unbundle consultation fees from procedure pricing and invest in in-house content production capabilities.
Aesthetics Combination Therapy Market Segmentation
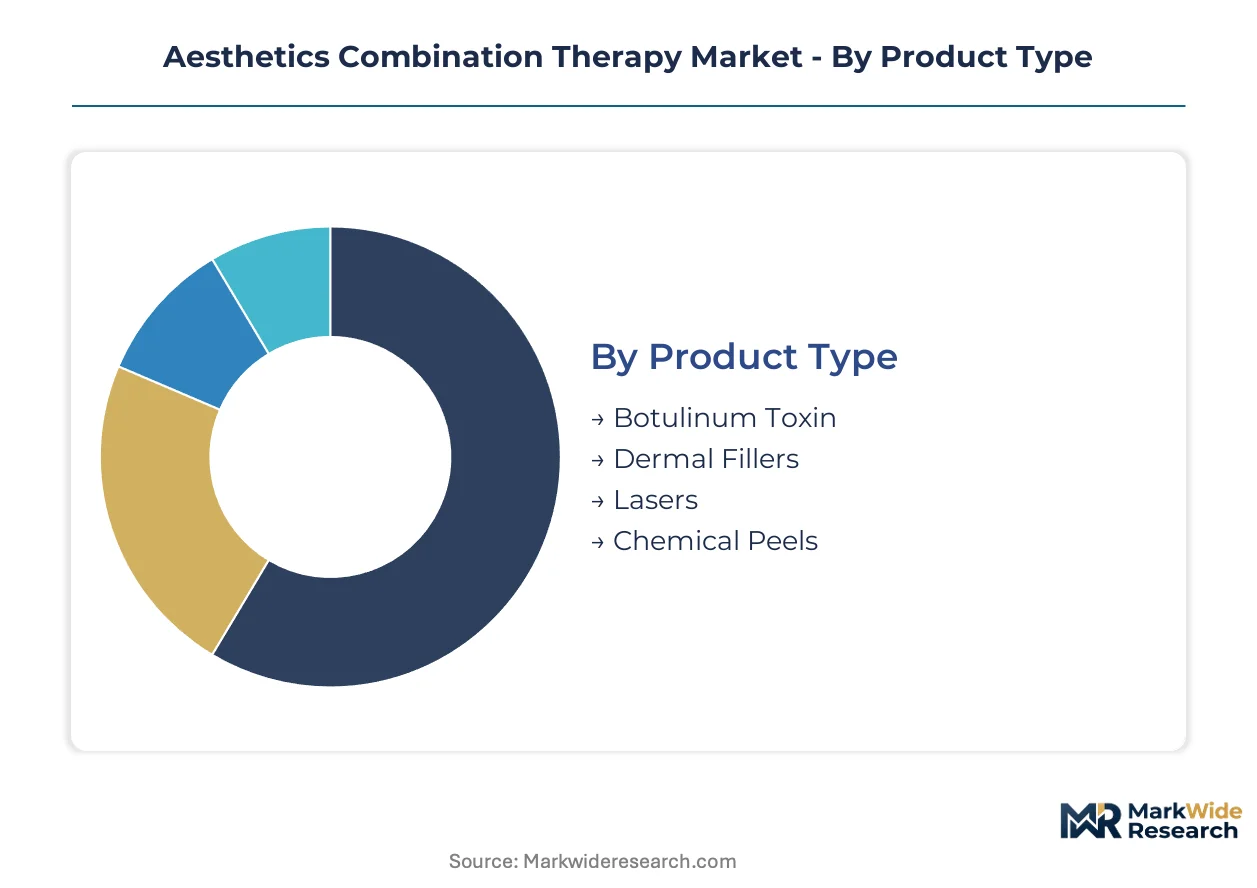
Segmentation in aesthetics combination therapy reveals how modality bundling concentrates purchasing power and technical capability requirements. Product mix and technology choices determine capital intensity and consumable attach rates for clinic operators.
Product Type:
Margin pools concentrate in injectable categories where repeat purchase cycles generate recurring revenue streams.
- Botulinum Toxin:Neurotoxin formulations require precise reconstitution protocols and cold chain logistics. Dermatology centers in Seoul and Los Angeles anchor volume for toxin-plus-filler combination regimens, driven by FDA 510(k) clearance precedents that streamlined US commercialization timelines.
- Dermal Fillers:Cross-linked hyaluronic acid gels and calcium hydroxylapatite microspheres enable volumetric facial contouring. Medical spas in Miami and Dubai deploy filler bundles as entry-level combination protocols, constrained by EU MDR clinical evidence requirements that extend European launch cycles.
- Lasers:Ablative and non-ablative fractional systems deliver controlled thermal injury for collagen remodeling.
- Chemical Peels:Acid-based exfoliation protocols complement energy-based modalities in multi-session treatment plans.
Botulinum toxin holds installed capacity. Dermal fillers are rotating up the share rankings.
End User:
Channel selection determines pricing power and patient throughput economics.
- Clinics:Independent aesthetic practices balance capital equipment costs against procedure volume. Clinics in Mumbai and São Paulo are expanding toxin-plus-filler service menus, driven by physician-supervised retail models that compress per-treatment pricing.
- Dermatology Centers:Specialist-led facilities combine diagnostic capability with multi-modal treatment protocols. German and French dermatology centers maintain active implant registries under EU MDR Article 10 surveillance mandates, elevating compliance infrastructure requirements.
- Medical Spas:Technician-administered services in Seoul and Tokyo deploy portable radiofrequency-microneedling pens for express facial protocols.
- Hospitals:Academic medical centers integrate combination therapy into reconstructive and dermatology service lines.
Dermatology centers hold installed capacity. Medical spas are rotating up the share rankings.
Application:
Demand concentration shifts with demographic targeting and scar revision protocols.
- Skin Rejuvenation:Photodamage correction and texture improvement dominate procedure volume. Practices in Sydney and Toronto prioritize laser-resurfacing-plus-radiofrequency bundles, constrained by HIPAA-compliant marketing workflows that demand enhanced patient consent infrastructure.
- Anti-Aging:Preventive and corrective protocols target collagen depletion and dynamic rhytides. Clinics in London and Singapore deploy toxin-plus-filler combinations for periorbital and perioral rejuvenation, driven by social platform patient acquisition channels that unbundle consultation fees.
- Acne Treatment:Active lesion management and sebaceous gland modulation attract younger patient cohorts.
- Scarring:Hypertrophic and atrophic scar revision protocols combine microneedling with energy-based remodeling.
Skin rejuvenation holds installed capacity. Acne treatment is rotating up the share rankings.
Technology:
Platform architecture determines capital redundancy and consumable ecosystem lock-in.
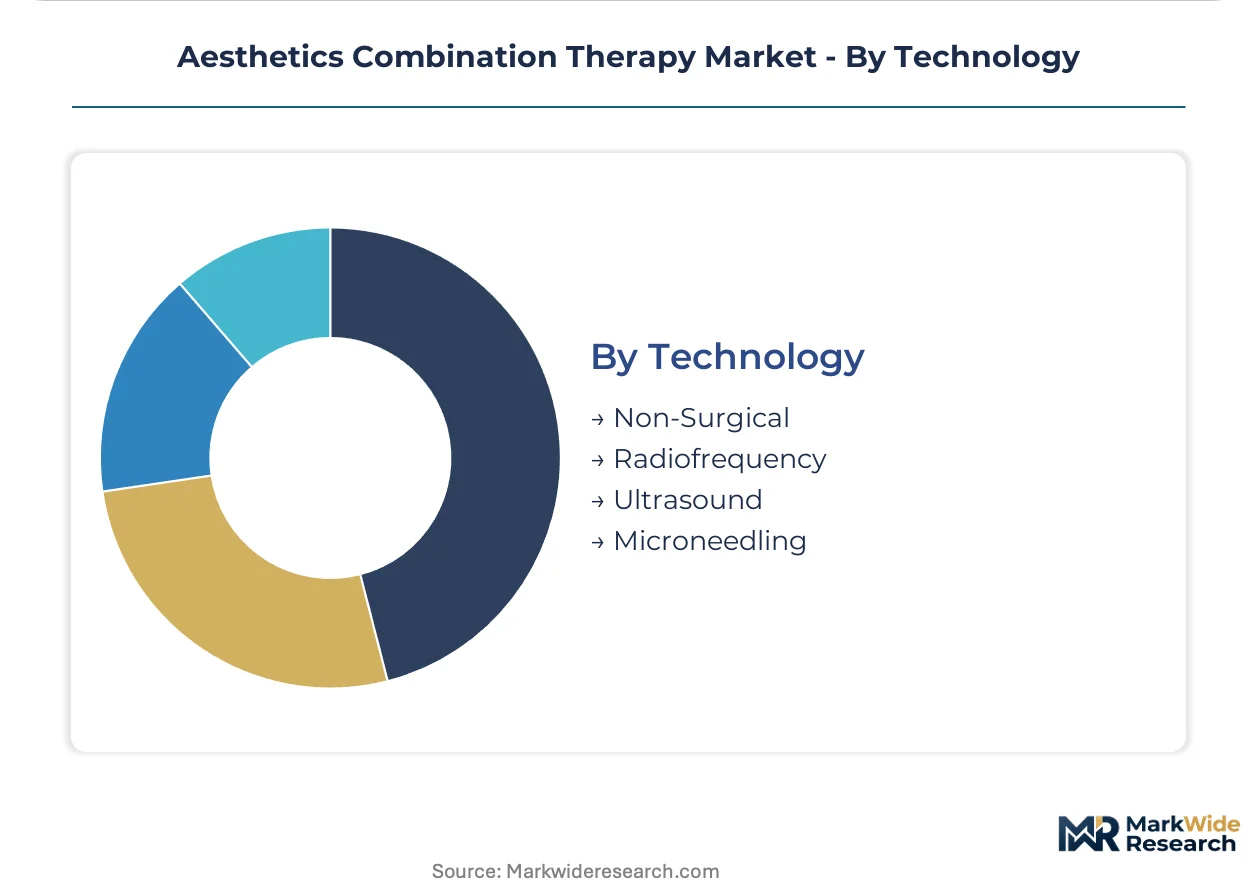
- Non-Surgical:Injectable-only protocols minimize equipment requirements and facility overhead. Medspa operators in Mexico City and Jakarta prioritize toxin-plus-filler training programs, driven by underpenetrated metro markets with expanding addressable patient bases.
- Radiofrequency:Thermal energy delivery systems tighten dermal collagen through controlled heating. Device manufacturers in Tokyo pursue PMDA combination approvals for multi-energy platforms, enabling faster Asian market entry.
- Ultrasound:Micro-focused and high-intensity focused ultrasound systems target deeper tissue planes.
- Microneedling:Percutaneous collagen induction combines with energy delivery for enhanced penetration.
Non-surgical holds installed capacity. Radiofrequency is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of multi-modal laser platforms and neurotoxin formulations concentrate in markets with advanced dermatology infrastructure. Export dynamics favor manufacturers with streamlined regulatory clearances in their home jurisdictions.
United States
FDA 510(k) clearance precedents for laser-injectable combination systems have compressed commercialization timelines for device manufacturers. HIPAA privacy mandates shape clinic marketing practices and patient data workflows across aesthetic practices. Los Angeles and Miami aesthetic clusters drive toxin-plus-filler bundle adoption through social platform patient acquisition channels.
South Korea
Dermatology centers in Seoul pioneer ultrasound-microneedling protocols that create demonstration effects for neighboring Asian markets. MFDS combination device approvals establish regulatory benchmarks for multi-energy platform clearances. The Seoul Capital Area concentrates technician-administered express facial services using portable radiofrequency-microneedling pen devices.
Germany
EU MDR Article 10 clinical evaluation requirements mandate post-market surveillance for combination energy devices serving German dermatology centers. CE marking renewal obligations extend product launch timelines and elevate clinical evidence standards. Frankfurt and Munich medical aesthetics clusters maintain active implant registries under heightened compliance infrastructure.
Japan
PMDA combination approvals for multi-energy platforms enable faster Asian market entry for integrated system manufacturers. METI industrial policy supports domestic device innovation in aesthetic energy delivery systems. Tokyo medical spas deploy miniaturized radiofrequency-microneedling handheld units for express protocol menus.
India
Underpenetrated metro dermatology centers present expansion white space for toxin-plus-filler protocol training and device placement programs. CDSCO medical device registration requirements shape import timelines for combination laser platforms. Mumbai and Delhi-NCR private clinics balance capital equipment costs against expanding addressable patient bases for multi-modal services.
Aesthetics Combination Therapy Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and consumable ecosystem dimensions. The vendor base spans multinational device manufacturers, pharmaceutical injectables producers, and regional platform specialists. Three archetypes dominate: integrated platform designers bundling hardware with recurring consumables, pure-play toxin or filler suppliers anchoring combination regimens, and modular device architects enabling treatment room flexibility. M&A activity concentrates on acquiring complementary energy modalities, while portfolio diversification moves target cross-selling opportunities between injectable and device categories.
Within the integrated platform tier, Alma Lasers and Lumenis Be Ltd. exemplify device manufacturers pursuing multi-energy convergence. Galderma occupies a position anchoring the injectables-centric archetype through toxin-plus-filler combination bundles. Among Asia-based specialists, Sisram Medical Ltd. represents the regional modular platform segment serving technician-administered service channels.
| Leading Market Players |
|---|
| Lutronic |
| Galderma |
| Alma Lasers |
| Merz Aesthetics |
| AbbVie/Allergan Aesthetics |
| Lumenis Be Ltd. |
| Bausch & Lomb Incorporated |
| Sisram Medical Ltd. |
| Cynosure |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance pathways gate both supply qualification and price differentiation simultaneously, as manufacturers bearing this certification command premium positioning in US dermatology practices while uncertified competitors face market exclusion. The interplay between regulatory compliance costs and consumable ecosystem lock-in shapes margin capture across toxin-plus-filler bundles and multi-modal energy platforms.
Pricing Analysis
Medical spa operators anchor pricing stratification across premium, standard, and economy tiers, with FDA-cleared toxin-plus-filler protocols commanding brand premiums against technician-administered alternatives. Price differentiation hinges on certification grade and vertical integration depth, as Galderma and AbbVie bundle consumables with training support. Cost compression in economy tiers intensifies due to portable radiofrequency-microneedling pen proliferation. Independent clinics exhibit highest price sensitivity; consolidated dermatology groups absorb premium positioning.
Supply Chain Analysis
South Korea and Germany anchor injectable formulation and precision laser manufacturing respectively, with the United States serving as the dominant consumption hub. Raw material dependencies center on cross-linked hyaluronic acid precursors, botulinum toxin master seeds, and rare-earth doped laser crystals. Single-source vulnerability concentrates in toxin strain production, where limited fermentation facilities create chokepoints. Distribution runs through authorized medical device distributors with cold chain logistics capabilities, feeding into clinic direct purchasing and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through medical spa chain consolidation, as regional operators aggregate procurement volume and demand standardized training protocols from device manufacturers.
For Market Incumbents: Consolidate consumable ecosystem control through exclusive cartridge-locking mechanisms on modular platforms, defending against modular device architects like Sisram Medical. Deepen backward integration into laser crystal and RF component manufacturing to compress COGS. Prioritize EU MDR Article 10 compliance infrastructure as a competitive moat against mid-tier competitors lacking surveillance registry capabilities. For New Entrants and Emerging Players: Japan PMDA combination approval fast-tracks offer regulatory arbitrage for multi-energy platform entrants seeking Asian market entry before US FDA timelines. White space concentrates in India's underpenetrated metro dermatology centers, where CDSCO registration pathways remain less burdensome than EU MDR. Target technician-administered service channels with portable pen-form-factor devices, leveraging express facial protocol demand in Seoul and Tokyo medical spas. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated platform manufacturing, as modular architecture R&D and dual-certification training infrastructure elevate fixed cost bases. Long-term viability favors manufacturers with recurring consumable attach rates exceeding hardware depreciation cycles. Acquisition targets should demonstrate active implant registry compliance and PMDA/FDA dual-track regulatory capabilities. Monitor FDA 510(k) clearance velocity as an inflection indicator for commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Abbreviated pathway accelerates US commercialization for laser-injectable combination systems. |
| CE Marking Pathway | EU MDR Article 10 compliance enables German and French dermatology center market access. |
| Medical Spa Partnership | Seoul and Tokyo technician-administered channels drive portable device volume expansion. |
| Consumable Ecosystem Lock-in | Cartridge-based revenue models defend margin capture against standalone device competitors. |
| Reimbursement Strategy | Cosmetic-indication classification monitoring shapes payor coverage policy for multi-modal procedures. |
Methodological Framework
The analysis maps injectable categories, energy-based device platforms, and end-user channels, each validated through dermatology center procurement managers, medical spa operators, device manufacturer regulatory affairs leads, and aesthetic clinician practitioners. Primary interviews combined with secondary validation from FDA 510(k) filings, MFDS approval databases, EU MDR Article 10 surveillance registries, and PMDA combination device clearances. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Consistency checks validated outputs against external benchmarks across the projection horizon, with segmentation modeling spanning product type, end user, application, and technology architecture dimensions. CAGRs derived from fitted growth curves incorporating regulatory approval timelines, channel expansion rates, and demographic procedure demand elasticity. Forecast inputs included medical spa establishment growth, toxin-plus-filler protocol adoption curves, and portable device miniaturization trends.
Decision-makers should treat outputs as directional under stable regulatory clearance velocity assumptions; material deviation in FDA, PMDA, or EU MDR processing timelines would warrant model refresh. Specific risk factors include reimbursement reclassification for cosmetic indications, supply disruption in toxin fermentation capacity, and HIPAA enforcement actions affecting direct-to-consumer marketing channels. Recalibration cycles align with material shifts in regulatory approval precedents and medical spa channel consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Energy-Based Aesthetic Devices Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Aesthetic Surgery Procedures Market
Aesthetic Medicine
Aesthetic Medicine and Cosmetic Surgery Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Australia Facial Injectable Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Platysmaplasty Treatment Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Global Aesthetic Dermatology Market
Aesthetic Medicine
Italy Aesthetic Market
Aesthetic Medicine
Colombia Facial Aesthetics Market
Aesthetic Medicine
North America Aesthetic Dermatology Market