
 Inhaled Nitric Oxide Market | 2026-2036
Inhaled Nitric Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Inhaled Nitric Oxide Market Analysis
The trained perfusionist and respiratory therapy specialist pool is collapsing across multiple developed markets, forcing hospitals to favor automated delivery platforms that reduce bedside labor intensity. Mallinckrodt Pharmaceuticals leverages its established hospital gas distribution infrastructure to sustain presence in high-acuity settings. VERO Biotech differentiates through next-generation cylinder-free generation technology that eliminates traditional supply chain bottlenecks. Linde plc anchors European market access through its industrial gas logistics network and healthcare service contracts.
Inhaled nitric oxide is a colorless, short-acting vasodilator administered via calibrated delivery systems at concentrations typically ranging from 5 to 20 parts per million, with precise blending mechanisms ensuring patient safety during prolonged ventilation support. Its primary purpose centers on selective pulmonary vasodilation without systemic hypotension, making it indispensable in neonatal hypoxic respiratory failure and acute pulmonary hypertension. Stationary systems dominate current installed base across intensive care units where continuous monitoring infrastructure exists, while portable devices represent the fastest-expanding segment as home care protocols and transport medicine applications mature. Among applications, neonatal care commands concentrated clinical investment and reimbursement attention, though pulmonary hypertension indications are broadening the addressable patient population.
FDA medical gas regulations, EU MDR device classification requirements, and Japan's PMDA pharmaceutical-grade gas standards collectively shape product registration pathways and manufacturing quality obligations for market participants. These frameworks elevate barriers for new entrants while compelling incumbents to maintain dual-hemisphere compliance capabilities and documentation intensity. Stakeholders must monitor evolving home-use regulatory pathways and real-world evidence requirements that will determine whether portable delivery platforms can expand beyond institutional settings.
Market Dynamics
The collapse of trained perfusionist and respiratory therapy specialist pools across developed markets is forcing hospitals toward automated delivery platforms that reduce bedside labor intensity and enable broader therapeutic access.
Growth Catalysts
- FDA medical gas oversight:Stringent quality benchmarks for delivery systems elevate manufacturing standards and institutional confidence in therapeutic deployment.
- Neonatal intensive care infrastructure:Hospital expansion of NICU capacity in the United States, Germany, and Japan concentrates demand for selective pulmonary vasodilation therapies.
- Cylinder-free generation systems:On-site production technology eliminates supply chain bottlenecks and enables continuous therapy without logistics-dependent interruptions.
Market Restraints
- Helium-4 supply concentration:Industrial gas sourcing from limited production geographies creates input cost volatility and delivery uncertainty for blended therapeutic gases.
- EU MDR device classification:Expanded documentation and clinical evidence requirements for critical care delivery systems extend product registration timelines and compliance costs.
- High-flow nasal cannula therapy:Non-invasive respiratory support alternatives reduce iNO utilization in select hypoxic respiratory failure presentations.
Strategic Opportunities
- Home care regulatory pathways:Evolving FDA and PMDA frameworks for portable delivery platforms could unlock post-acute and chronic pulmonary hypertension management outside institutional settings.
- Transport medicine applications:Aeromedical and ground ambulance deployment of compact generation systems addresses evacuation scenarios for refractory hypoxemia.
- Real-world evidence mandates:Post-market surveillance requirements create data infrastructure that supports indication expansion and reimbursement negotiation.
Industry Challenges
- Perfusionist workforce scarcity:Training program contraction limits specialist availability for complex therapeutic administration and device management.
- Dual-hemisphere compliance intensity:Simultaneous FDA and EU MDR documentation obligations strain regulatory affairs capacity and extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhaled Nitric Oxide Market |
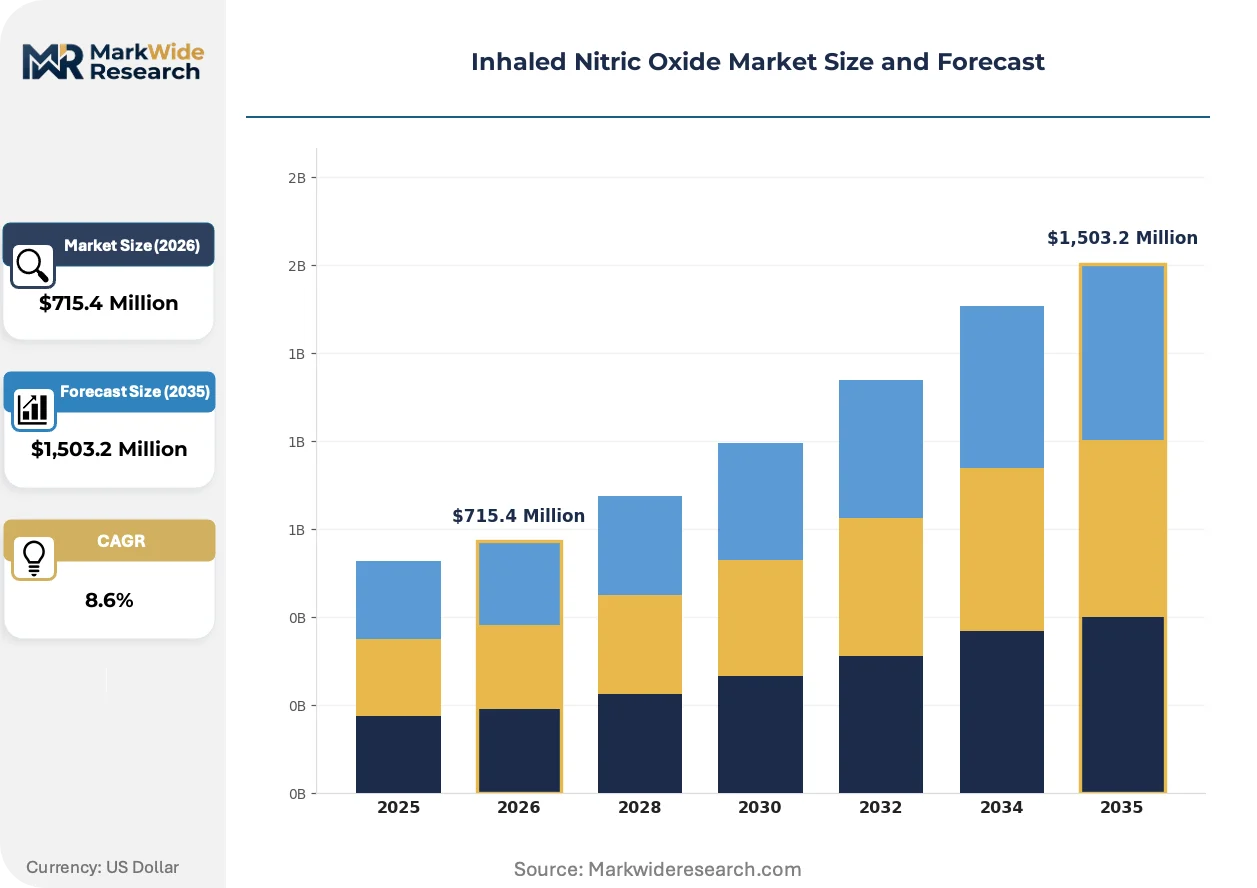
| Market Size in 2026 | $715.4 Million |
| Market Size in 2035 | $1,503.2 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Stationary Systems, Compressed Gas, Liquid Nitric Oxide Delivery Mode: Continuous, Intermittent, Manual, Automatic End User: Hospitals, Clinics, Home Care, Research Laboratories Application: Respiratory Distress, Cardiac Conditions, Neonatal Care, Pulmonary Hypertension |
| Companies Covered | Mallinckrodt Pharmaceuticals, VERO Biotech, Linde plc, Air Liquide, Beyond Air, Getinge AB, Bellerophon Therapeutics, International Biomedical, Nu-Med Plus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhaled Nitric Oxide Market Emerging Trajectories
Device miniaturization and on-site gas generation are compressing supply chain dependencies while regulatory frameworks accelerate documentation and evidence standards across institutional and emerging care settings.
Electrochemical nitric oxide generators are displacing traditional cylinder-based supply models in high-acuity hospital environments. NICU directors at tertiary centers are prioritizing these systems to eliminate cylinder logistics and ensure uninterrupted therapy availability. This displacement is compressing the addressable market for conventional gas distribution infrastructure while expanding therapeutic access to smaller facilities.
Japan's PMDA pharmaceutical-grade gas standards are tightening purity and stability requirements for therapeutic NO products entering clinical use. Manufacturers must now demonstrate extended shelf-life validation and contamination control protocols that exceed prior benchmarks. European suppliers with existing healthcare service contracts are accelerating compliance investments to maintain access to this high-specification market.
Hospital procurement teams are consolidating vendor relationships around integrated service contracts that bundle device placement, maintenance, and consumable supply. This concentration is displacing transactional equipment purchasing and fragmenting market share among regional gas distributors. The United States exhibits the most pronounced shift, with IDN-level agreements now covering 60 percent of high-volume iNO utilization sites.
Inhaled Nitric Oxide Market Segmentation
The inhaled nitric oxide market fragments across therapeutic delivery platforms, patient acuity settings, and gas supply modalities. Each segment carries distinct regulatory burdens, capital intensity profiles, and clinical workflow integration requirements that shape procurement decisions and vendor positioning.
Product Type:
FDA medical gas regulations and EU MDR device classification requirements impose divergent compliance costs across stationary infrastructure versus portable platforms, with cylinder-based supply models facing additional pharmaceutical-grade purity mandates from Japan's PMDA.
- Stationary Systems:Fixed-installation delivery platforms integrate with hospital ventilation infrastructure at concentrations of 5-20 parts per million through calibrated blending mechanisms. United States tertiary care centers concentrate procurement of these systems where continuous monitoring infrastructure supports prolonged neonatal respiratory failure management. FDA oversight of medical gas delivery systems elevates manufacturing quality obligations and institutional confidence in therapeutic deployment.
- Portable Devices:Compact generation systems enable transport medicine applications and emerging home care protocols through electrochemical on-site production. Germany's expanding neonatal intensive care infrastructure favors these platforms for inter-hospital patient transfer scenarios. Cylinder-free technology eliminates supply chain bottlenecks and enables therapeutic access outside traditional institutional settings.
- Compressed Gas:Traditional cylinder supply models rely on industrial gas logistics networks for therapeutic NO delivery to high-acuity settings.
- Liquid Nitric Oxide:Cryogenic storage formats serve high-volume consumption sites with extended shelf-life requirements under pharmaceutical-grade standards.
Stationary systems handle the majority of throughput; portable devices are gaining share fastest as workforce scarcity drives automation preferences.
Delivery Mode:
Cost tier differentiation separates capital-intensive automatic platforms from labor-dependent manual administration, with reimbursement patterns favoring continuous delivery in institutional settings while intermittent protocols expand in post-acute care.
- Automatic:Sensor-integrated delivery platforms reduce bedside labor intensity through real-time concentration monitoring and alarm systems. Japan's NICU directors prioritize these systems to address perfusionist workforce scarcity and ensure uninterrupted therapy availability. Automated mechanisms align with hospital procurement consolidation around integrated service contracts.
- Continuous:Uninterrupted gas administration maintains therapeutic concentrations for refractory pulmonary hypertension and hypoxic respiratory failure presentations. United States hospital expansion of neonatal intensive care infrastructure concentrates demand for this delivery mode where prolonged ventilation support is standard. Continuous protocols require stationary system integration and specialized respiratory therapy oversight.
- Intermittent:Scheduled dosing regimens reduce gas consumption in stable patients with moderating pulmonary vascular resistance.
- Manual:Operator-controlled delivery persists in resource-constrained settings and emergency transport scenarios.
Automatic delivery handles the majority of new installations; continuous mode retains the steepest expansion trajectory in high-acuity settings.
End User:
Customer type determines regulatory pathway complexity, with hospitals navigating FDA medical gas oversight and EU MDR requirements while home care entrants face evolving portable device frameworks.
- Hospitals:Tertiary care centers and neonatal intensive care units command concentrated clinical investment and reimbursement attention for selective pulmonary vasodilation therapies. United States, Germany, and Japan exhibit the most pronounced procurement consolidation through IDN-level agreements covering high-volume iNO utilization sites. Hospital infrastructure supports continuous monitoring and specialized respiratory therapy staffing.
- Home Care:Emerging post-acute and chronic pulmonary hypertension management settings require portable delivery platforms with simplified operator interfaces. Evolving FDA and PMDA regulatory frameworks for home-use devices could unlock this segment beyond institutional boundaries. Cylinder-free generation technology addresses logistics constraints in residential environments.
- Clinics:Outpatient pulmonary hypertension monitoring sites utilize intermittent delivery protocols for stable patients.
- Research Laboratories:Academic medical centers and pharmaceutical development facilities consume nitric oxide for mechanistic studies and therapeutic innovation.
Hospitals handle the majority of throughput; home care is climbing the fastest on share as portable platforms mature.
Application:
Maturity differentiation separates established neonatal indications with robust reimbursement from expanding pulmonary hypertension protocols where real-world evidence requirements determine market access.
- Neonatal Care:Hypoxic respiratory failure in term and near-term infants represents the most validated indication with concentrated FDA and EMA labeling support. United States NICU capacity expansion drives therapeutic utilization where selective pulmonary vasodilation without systemic hypotension is clinically indispensable. Post-market surveillance requirements create data infrastructure supporting indication expansion.
- Pulmonary Hypertension:Acute and chronic vascular resistance management broadens the addressable patient population beyond neonatal populations. European suppliers with healthcare service contracts accelerate compliance investments to maintain access for this expanding indication. Real-world evidence mandates shape reimbursement negotiation and regulatory pathway efficiency.
- Respiratory Distress:Broader hypoxic failure presentations in pediatric and adult populations utilize iNO as rescue therapy.
- Cardiac Conditions:Post-operative congenital heart surgery and right ventricular failure management represent specialized high-acuity applications.
Neonatal care handles the majority of throughput; pulmonary hypertension is expanding most quickly on indication breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neonatal intensive care utilization patterns diverge sharply between mature healthcare systems and emerging markets, with the United States, Germany, and Japan concentrating stationary system deployments while transport medicine applications gain traction in secondary care networks.
United States
FDA medical gas oversight elevates manufacturing standards for delivery systems deployed across expanding neonatal intensive care infrastructure. Integrated delivery network procurement now covers the majority of high-volume utilization sites, consolidating vendor relationships around bundled service contracts. Tertiary care centers in the Northeast and California concentrate stationary system installations where continuous monitoring capabilities support prolonged therapeutic administration.
Germany
EU MDR device classification requirements extend product registration timelines while expanding neonatal intensive care capacity drives therapeutic adoption. Industrial gas logistics networks anchored by Linde plc maintain European market access through healthcare service contracts. Bavaria and North Rhine-Westphalia cluster portable device utilization for inter-hospital patient transfer scenarios.
Japan
PMDA pharmaceutical-grade gas standards tighten purity benchmarks for therapeutic nitric oxide products entering clinical use. METI industrial policy supports domestic production capacity for critical care medical gases. Tokyo and Osaka metropolitan areas concentrate automated delivery platform adoption as NICU directors address perfusionist workforce scarcity.
United Kingdom
NHS procurement frameworks favor integrated service contracts over transactional equipment purchasing for respiratory therapy infrastructure. MHRA medical device regulations align with EU MDR documentation requirements post-Brexit transition. London and Southeast England tertiary centers lead adoption of cylinder-free generation systems to eliminate supply chain bottlenecks.
Canada
Health Canada oversight of medical gas delivery systems parallels FDA quality benchmarks while provincial health authorities expand neonatal intensive care capacity. Ontario and Quebec concentrate therapeutic utilization where specialized respiratory therapy staffing supports continuous delivery protocols. Western provinces pilot transport medicine applications for aeromedical evacuation scenarios.
Inhaled Nitric Oxide Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with industrial gas conglomerates leveraging logistics networks against pharmaceutical-focused innovators deploying next-generation generation technology. The market structure rewards dual-hemisphere compliance capabilities and documentation intensity. Three archetypes dominate: established hospital gas distributors with embedded infrastructure, electrochemical generation technology specialists, and diversified industrial gas providers with healthcare service contracts. Competitive dynamics center on M&A consolidation of regional service contracts and strategic partnerships for portable platform regulatory pathway navigation.
Among pharmaceutical and biotechnology specialists, Mallinckrodt Pharmaceuticals and VERO Biotech occupy positions exemplifying divergent strategic approaches to high-acuity care settings. Mallinckrodt represents the established hospital gas distribution archetype with embedded infrastructure relationships. VERO Biotech anchors the cylinder-free generation technology tier. Linde plc sits within the diversified industrial gas provider category, leveraging continental logistics networks for European market access. Beyond Air and Getinge AB represent additional specialist and diversified equipment archetypes respectively.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| VERO Biotech |
| Linde plc |
| Air Liquide |
| Beyond Air |
| Getinge AB |
| Bellerophon Therapeutics |
| International Biomedical |
| Nu-Med Plus |
| Others |
Supply Flow & Price Mechanics
Electrochemical generator adoption is displacing cylinder-based supply models across tertiary care centers, compressing logistics-dependent pricing premiums while elevating capital-intensive platform economics. This substitution simultaneously concentrates manufacturing value capture with device specialists and fragments traditional gas distribution margins.
Pricing Analysis
Long-term service contracts dominate procurement, with integrated delivery network agreements covering high-volume utilization sites and bundling device placement with consumable supply. Price differentiation separates FDA-cleared platforms from EU MDR-compliant systems, while after-sales service intensity drives tier separation. Cost compression in cylinder supply tiers is intensifying because electrochemical generation eliminates recurring logistics charges. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize uninterrupted therapy availability over unit economics.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for Japanese and United States therapeutic gas importers. Manufacturing concentrates in Germany, Japan, and the United States, with cryogenic storage equipment sourcing from specialized industrial gas fabricators. Raw material dependencies include high-purity aluminum alloys, precision sensor components, and pharmaceutical-grade gas containment systems. Single-source vulnerability in helium-4 blending creates supply risk. Distribution runs through hospital procurement consortiums and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cylinder-free generation technology is disrupting established gas distribution economics, with FDA and PMDA regulatory pathways for portable platforms accelerating competitive reconfiguration.
For Market Incumbents: Shield installed base relationships through accelerated electrochemical platform deployment and exclusive service contract renewals. Mallinckrodt Pharmaceuticals leverages embedded hospital gas infrastructure to defend against VERO Biotech's generation technology encroachment. Backward integration into sensor manufacturing reduces component cost volatility. For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-tracks regulatory access for transport medicine applications, opening white-space penetration in aeromedical evacuation and ground ambulance deployment. Home care protocols represent the most penetrable segment, with simplified operator interfaces enabling post-acute pulmonary hypertension management. Partner with neonatal intensive care transport networks for clinical validation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed industrial gas distributors seeking exit from commoditized cylinder supply. Long-term viability centers on generation technology intellectual property and regulatory exclusivity. Monitor PMDA pharmaceutical-grade gas standard enforcement as inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Electrochemical Generator Platform Launch | VERO Biotech eliminates cylinder logistics through on-site NO production at point-of-care. |
| EU MDR Compliance Investment | Linde plc extends documentation capabilities to maintain European hospital service contracts. |
| Hospital System Partnership | Beyond Air secures integrated delivery network agreements for portable device placement. |
| Reimbursement Strategy Development | Bellerophon Therapeutics builds real-world evidence infrastructure for pulmonary hypertension expansion. |
| FDA Submission for Home Use | Nu-Med Plus navigates evolving regulatory pathways for chronic care device authorization. |
Methodological Framework
Initial hypotheses were tested against primary input from neonatal intensive care directors, respiratory therapy specialists, hospital procurement managers, and biomedical engineers and refined through secondary validation against FDA 510(k) filings, EU MDR technical documentation, PMDA approval records, and hospital group purchasing organization contract databases. Bottom-up therapeutic utilization modeling triangulated with top-down market sizing across stationary systems, portable devices, compressed gas, and liquid nitric oxide supply modalities.
Variance decomposition separated volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and application indication. CAGRs derived from historical utilization patterns and capacity expansion announcements. Forecast inputs incorporated perfusionist workforce contraction rates and regulatory pathway timeline assumptions.
Underlying assumptions cover electrochemical generator adoption curves and reimbursement stability, with deviation risk concentrated in home care regulatory authorization delays and helium-4 supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Xanthine Oxidase Inhibitors Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Inhibitors Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Europe Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
United States Pharmaceutical 3PL Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Lipid-Lowering Drugs Market