
 Global Hemostasis and Tissue Sealing Agents Market | 2026-2036
Global Hemostasis and Tissue Sealing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemostasis and Tissue Sealing Agents Market Foresight
The hemostasis and tissue sealing landscape is consolidating around a widening gap between premium biologics and commodity synthetics. Johnson & Johnson leverages its broad surgical portfolio to dominate high-margin fibrin sealant categories. Baxter International anchors North American hospital contracts through integrated blood management platforms. Becton Dickinson & Company differentiates in active hemostat technology with proprietary flowable gel matrices.
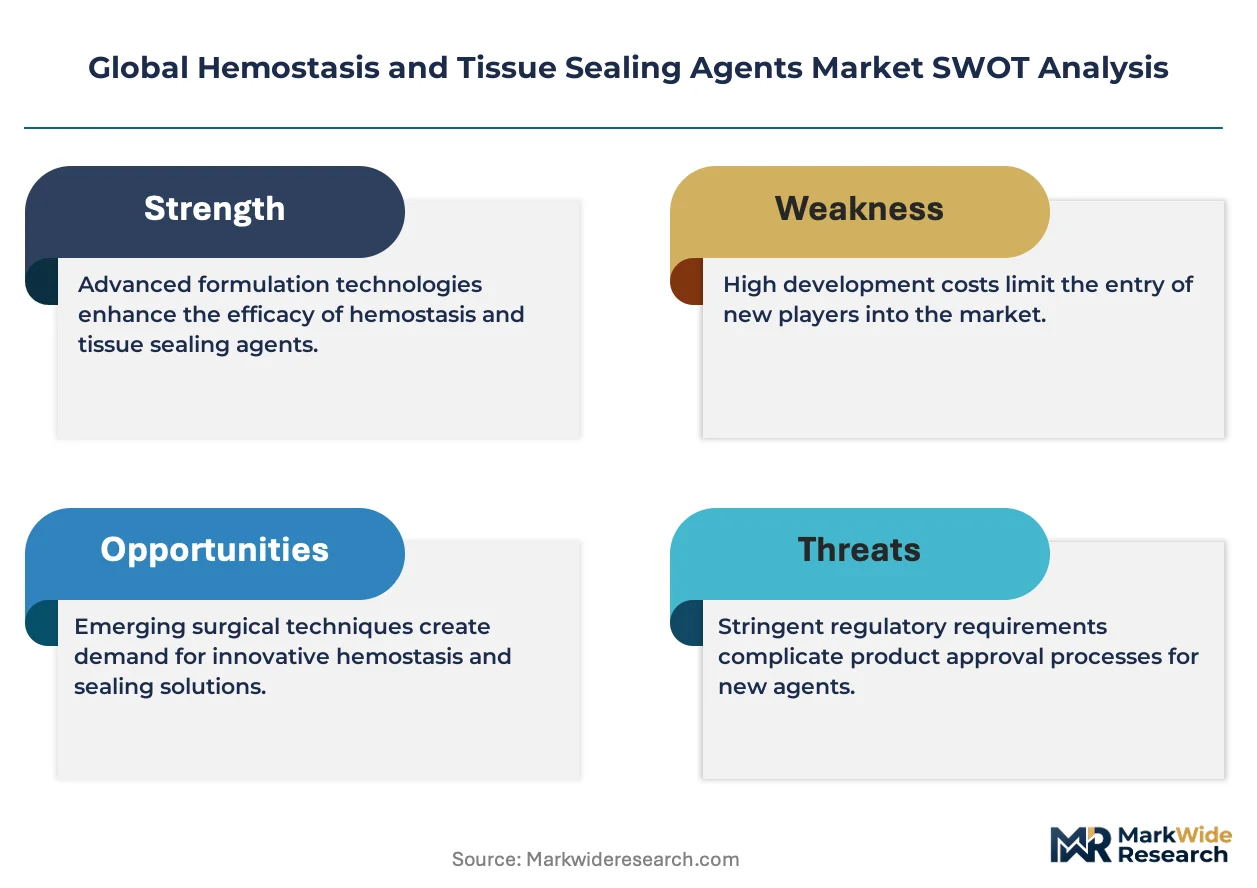
Hemostasis and tissue sealing agents comprise biologically active or synthetic formulations designed to arrest bleeding and bond tissue planes during operative procedures, typically incorporating thrombin, fibrinogen, collagen, or oxidized cellulose in concentrations calibrated to clotting cascade activation. These products serve the fundamental surgical purpose of reducing operative blood loss, shortening time to hemostasis, and eliminating the need for mechanical ligation in inaccessible anatomical sites. Fibrin sealants command the largest revenue pool due to their physiological mechanism and premium pricing, while synthetic sealants represent the fastest-expanding segment as polymer chemistry advances enable comparable efficacy at lower production cost. Mechanical hemostasis retains substantial volume in emerging markets where reimbursement constraints limit access to advanced biologics.
FDA premarket approval pathways, EMA Medical Device Regulation conformity assessments, and Japan's PMDA quality management standards collectively elevate barriers for new entrants while mandating post-market surveillance that extends product development timelines. The EU Green Deal's chemical sustainability targets are beginning to influence raw material sourcing for synthetic sealant polymers. Stakeholders must monitor evolving reimbursement thresholds for combination hemostat systems versus standalone agents as health technology assessment bodies tighten evidence requirements.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines while elevating clinical evidence requirements, forcing manufacturers to restructure trial designs and regulatory submission strategies around post-market surveillance obligations.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding ASCs in the United States are accelerating same-day discharge protocols that demand rapid hemostasis without transfusion support, expanding addressable procedure volume beyond traditional hospital settings.
- FDA Breakthrough Device designation pathway:Expedited review for novel hemostat formulations targeting unmet surgical needs is shortening time-to-revenue for biologically active sealants with differentiated mechanisms.
- Dual carbon targets in China:NMPA incentives for domestically manufactured biologics are redirecting procurement toward local fibrin sealant production, stimulating capacity investment across Jiangsu and Zhejiang manufacturing clusters.
Market Restraints
- Plasma-derived raw material concentration:Fibrinogen and thrombin sourcing depends on contracted blood collection networks concentrated in the United States and Germany, exposing supply continuity to donor availability fluctuations.
- EMA MDR conformity assessment backlog:Notified body capacity constraints are extending CE marking timelines for Class III surgical sealants, delaying commercial launch across EU member states.
- Synthetic polymer performance ceiling:Oxidized cellulose and gelatin-based hemostats exhibit inferior adhesion under wet field conditions compared to biologics, limiting penetration in cardiovascular and spinal procedures.
Strategic Opportunities
- Underpenetrated Brazilian market:ANVISA regulatory harmonization with IMDRF standards is reducing import barriers for advanced sealants, creating first-mover advantage as private hospital chains modernize surgical infrastructure.
- Combination hemostat-drug delivery systems:Convergence of flowable matrices with localized antibiotic or chemotherapy agents opens premium positioning in oncology and trauma reconstruction segments.
- Direct-to-hospital distribution platforms:Digital procurement portals are disintermediating traditional medical device distributors, enabling manufacturers to capture margin and build real-time consumption data relationships with surgical suites.
Industry Challenges
- Biologics manufacturing talent scarcity:Specialized expertise in aseptic fibrin sealant production and viral inactivation validation remains concentrated among legacy plasma fractionation facilities, constraining new entrant scale-up.
- ISO 13485:2016 transition complexity:Updated quality management system requirements for risk-based device classification are forcing documentation overhauls and supplier requalification across contract manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemostasis and Tissue Sealing Agents Market |
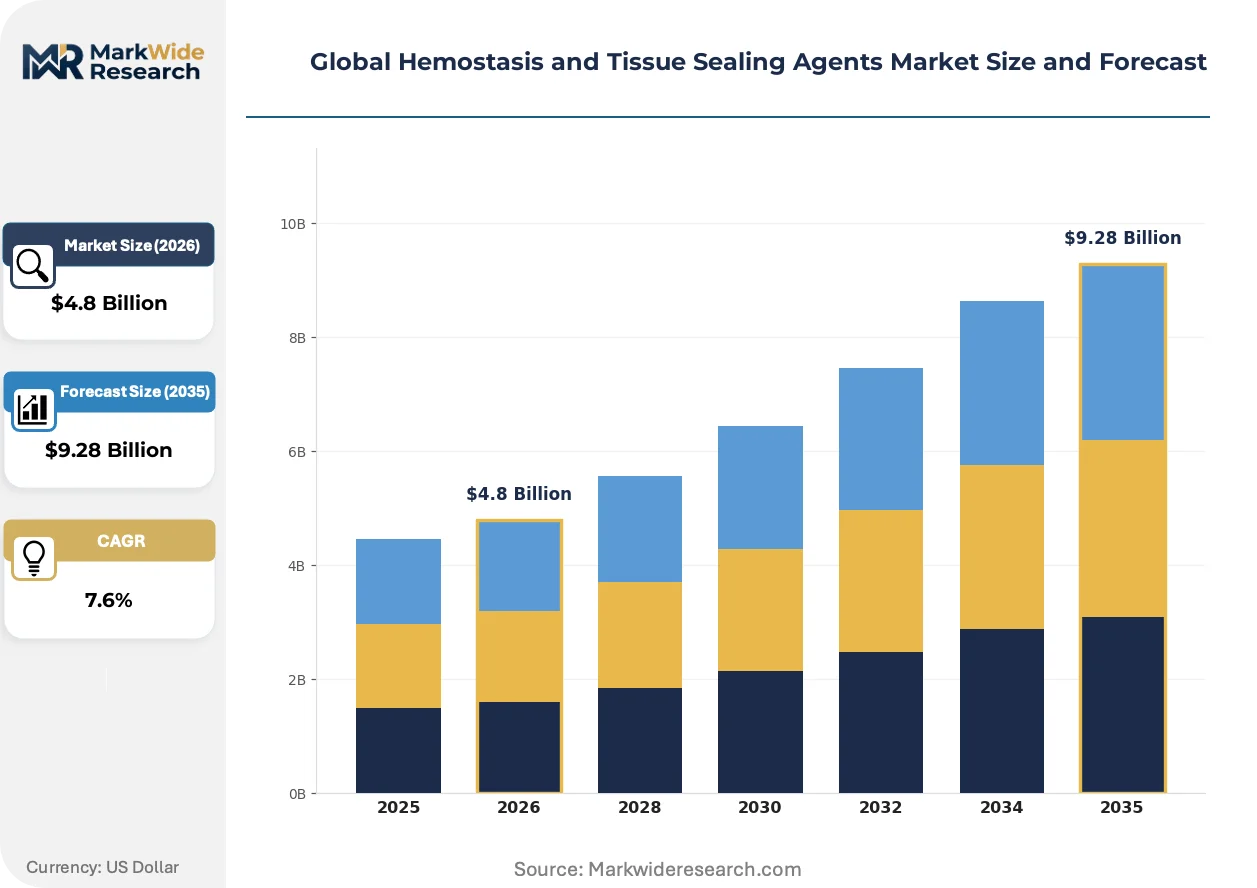
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrin Sealants, Synthetic Sealants, Collagen-Based Agents, Gelatin-Based Agents, Polysaccharide-Based Agents Application: Cardiovascular Procedures, Neurosurgery, Orthopedic Surgery, Plastic Surgery, General Surgery End Use: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Technology: Mechanical Hemostasis, Active Hemostats, Passive Hemostats, Combination Systems |
| Companies Covered | Johnson & Johnson, Baxter International, Becton Dickinson & Company, Medtronic, Pfizer, B. Braun, Integra LifeSciences Corporation, CryoLife, Advanced Medical Solutions Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemostasis and Tissue Sealing Agents Market Shifts & Advancements
Polymer chemistry advances and regulatory data requirements are simultaneously compressing development economics and expanding functional possibilities for next-generation surgical sealants.
Recombinant thrombin formulations are modularizing hemostat supply chains by eliminating plasma dependency and enabling consistent lot-to-lot activity profiles. Academic medical centers in Germany and Switzerland are piloting these synthetic alternatives in cardiac surgery protocols. The technology is modularizing manufacturer raw material strategies, allowing dual-source flexibility that biologic-dependent competitors cannot replicate.
REACH chemical sustainability mandates are forcing reformulation of synthetic sealant polymers to exclude persistent organic pollutants and halogenated compounds. ECHA substance restriction proposals targeting specific cross-linking agents are accelerating R&D investment in bioabsorbable polyester alternatives. Sealant manufacturers with European manufacturing footprints are responding by qualifying plant-derived polymer feedstocks ahead of 2027 registration deadlines.
Hospital value analysis committees are consolidating hemostat purchasing decisions at system level, displacing surgeon-driven preference contracting. Integrated delivery networks in the United States are bundling sealant procurement with blood management platform agreements, favoring suppliers with comprehensive product portfolios. This concentration is most visible in Texas and Florida health systems where surgical volume justifies dedicated supply chain analytics teams.
Global Hemostasis and Tissue Sealing Agents Market Segmentation
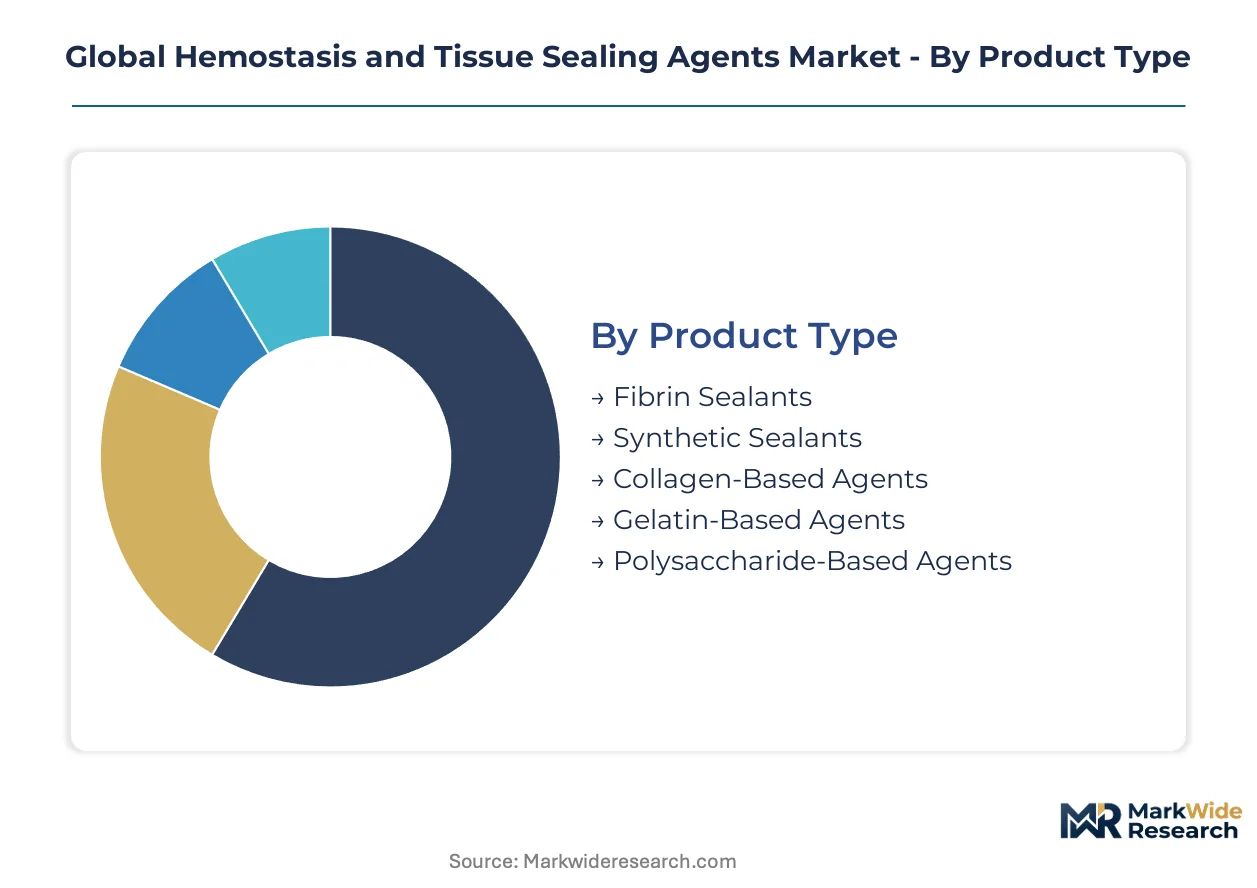
Segmentation in hemostasis and tissue sealing agents reveals distinct technology-performance tradeoffs that govern procurement decisions across surgical settings. Product chemistry, procedure type, and care delivery site each impose unique constraints on formulation selection and pricing acceptance.
Product Type:
Material composition determines hemostatic mechanism, absorption profile, and reimbursement tier across surgical applications.
- Fibrin Sealants:Plasma-derived formulations combining fibrinogen and thrombin replicate final coagulation cascade stages for physiological clot formation. Demand concentrates in cardiovascular and spinal procedures at German university hospitals where blood management protocols prioritize biologic mechanisms despite premium procurement cost.
- Synthetic Sealants:Polymer-based systems employing polyethylene glycol or cyanoacrylate chemistry achieve tissue adhesion through synthetic cross-linking independent of patient clotting function. Ambulatory surgical centers in the United States are expanding procurement of these alternatives as same-day discharge protocols demand reliable hemostasis without transfusion infrastructure.
- Collagen-Based Agents:Bovine or porcine-derived matrices provide passive hemostasis through platelet activation at bleeding surfaces; widely stocked in emergency departments.
- Gelatin-Based Agents:Cross-linked gelatin sponges deliver absorbable mechanical support for capillary oozing in general surgery suites.
- Polysaccharide-Based Agents:Oxidized cellulose and starch derivatives offer low-cost options for surface bleeding control in resource-constrained settings.
Fibrin sealants lead on scale; synthetic sealants lead on momentum.
Application:
Procedure complexity and bleeding risk profile dictate hemostat performance requirements and acceptable cost thresholds.
- Cardiovascular Procedures:Sternotomy closure, valve replacement, and bypass grafting demand rapid, reliable hemostasis under full anticoagulation. German cardiac surgery centers specify fibrin sealants with recombinant thrombin for predictable clot formation when patient hemostasis is pharmacologically suppressed.
- Neurosurgery:Cranial and spinal interventions require hemostats that achieve control without tissue retraction or thermal damage. Flowable gel matrices from Becton Dickinson penetrate irregular dural surfaces where mechanical tamponade is anatomically impractical.
- Orthopedic Surgery:Joint replacement and trauma fixation generate substantial cancellous bone bleeding addressable through collagen-based and gelatin-based agents.
- Plastic Surgery:Aesthetic and reconstructive procedures favor synthetic sealants with minimal inflammatory response and clear visualization.
- General Surgery:Hepatic resection and splenic trauma employ combination systems integrating mechanical and active hemostatic components.
Cardiovascular applications command premium pricing; neurosurgery applications drive formulation innovation fastest.
End Use:
Site of care determines inventory breadth, reimbursement mechanics, and clinical decision-making authority over hemostat selection.
- Hospitals:Integrated surgical departments maintain diversified formularies spanning biologics and synthetics for complex multi-specialty caseloads.
- Ambulatory Surgical Centers:Freestanding facilities in Texas and Florida health systems prioritize synthetic sealants and combination systems that eliminate transfusion dependency for outpatient arthroscopy and spine procedures.
- Specialty Clinics:Dermatology and ophthalmology practices stock narrow hemostat portfolios calibrated to low-bleeding-risk interventions.
- Research Institutes:Academic medical centers in Switzerland and Germany pilot recombinant thrombin formulations and novel polymer platforms under clinical trial protocols.
Hospitals anchor volume; ambulatory surgical centers are expanding most quickly.
Technology:
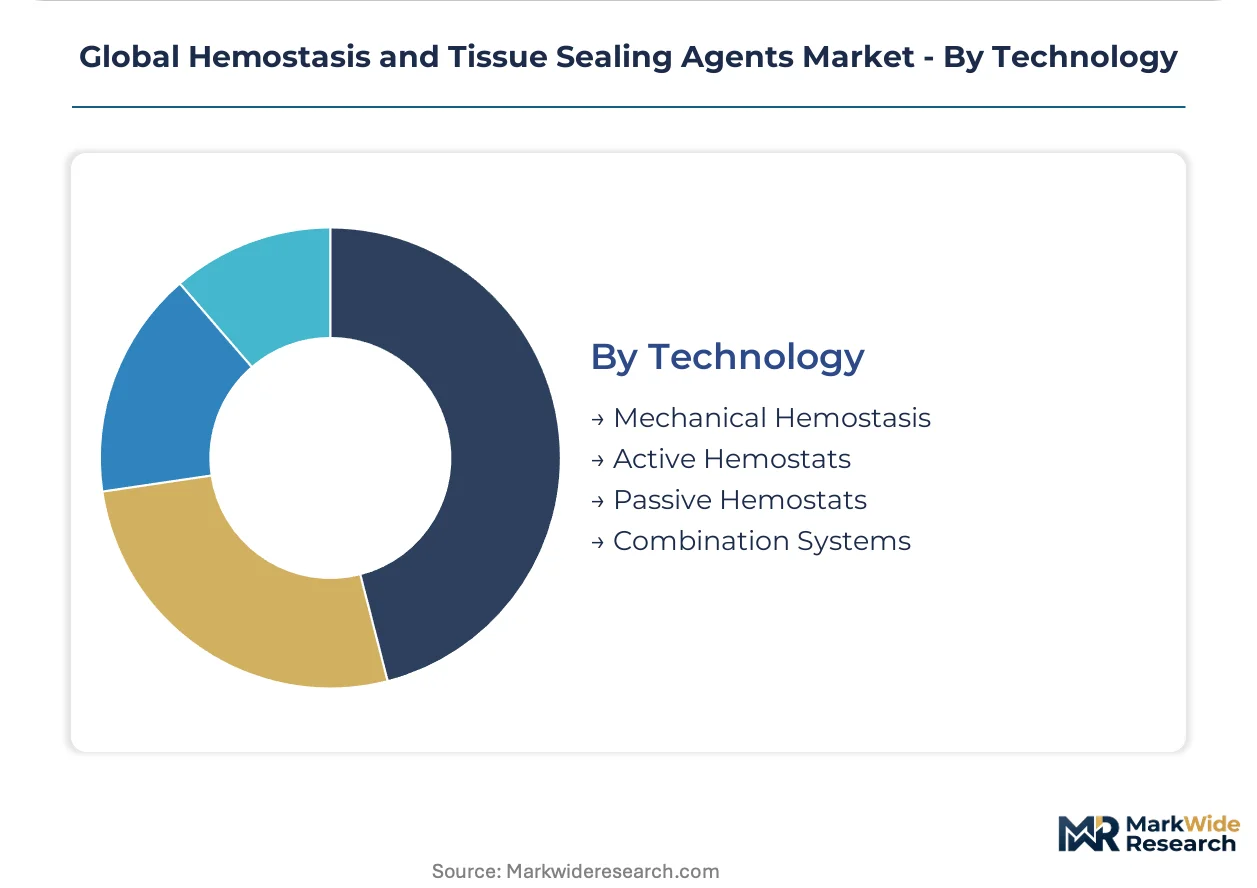
Mechanism of action classifies hemostats by their interaction with patient physiology and surgical workflow requirements.
- Mechanical Hemostasis:Pressure application, suture ligation, and metallic clips remain foundational in emerging markets where reimbursement constraints limit advanced biologic access.
- Active Hemostats:Thrombin-containing preparations directly accelerate clot formation; Johnson & Johnson dominates this category through concentrated thrombin sprays.
- Passive Hemostats:Collagen, gelatin, and cellulose matrices provide scaffolding for native coagulation without biologic activity; Baxter International anchors hospital contracts through oxidized cellulose product lines.
- Combination Systems:Integrated platforms merging active agents with flowable matrices command premium positioning in trauma and oncology reconstruction.
Passive hemostats lead on procedure volume; combination systems lead on revenue per application.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German university hospitals specify fibrin sealants with recombinant thrombin for cardiac surgery protocols, while Chinese manufacturing clusters in Jiangsu and Zhejiang redirect procurement toward domestically produced biologics under NMPA incentives.
United States
Freestanding ambulatory surgical centers in Texas and Florida accelerate same-day discharge protocols demanding rapid hemostasis without transfusion support. FDA Breakthrough Device designation pathways expedite review for novel hemostat formulations targeting unmet surgical needs. Integrated delivery networks in the Southeast bundle sealant procurement with blood management platform agreements.
Germany
Cardiac surgery centers at Charité Berlin and Heidelberg University Hospital specify fibrin sealants with recombinant thrombin for predictable clot formation under anticoagulation. EMA Medical Device Regulation conformity assessments elevate clinical evidence requirements for Class III surgical sealants. The Mannheim-Heidelberg medical technology corridor anchors plasma fractionation expertise for aseptic fibrin sealant production.
China
NMPA dual carbon targets redirect procurement toward domestically manufactured fibrin sealants, stimulating capacity investment across Jiangsu and Zhejiang manufacturing clusters. The country's national pharmaceutical regulator incentivizes local biologics production through streamlined registration pathways. Shanghai-based research institutes pilot recombinant thrombin formulations under clinical trial protocols.
Switzerland
Academic medical centers in Zurich and Geneva pilot recombinant thrombin formulations and novel polymer platforms under Swissmedic-supervised clinical trial protocols. REACH chemical sustainability mandates force reformulation of synthetic sealant polymers to exclude persistent organic pollutants. The Basel biotech cluster advances bioabsorbable polyester alternatives ahead of 2027 ECHA registration deadlines.
Brazil
ANVISA regulatory harmonization with IMDRF standards reduces import barriers for advanced sealants as private hospital chains modernize surgical infrastructure. The country's national health surveillance agency aligns conformity assessment procedures with international medical device reference frameworks. São Paulo-based hospital systems expand procurement of combination hemostat systems for trauma reconstruction segments.
Global Hemostasis and Tissue Sealing Agents Market Competitive Landscape
Top-tier vendors anchor hospital contracts through integrated blood management platforms, while mid-scale specialists occupy niche formulation segments. The competitive structure stratifies across three tiers: diversified medical device conglomerates with broad surgical portfolios, dedicated hemostasis manufacturers with concentrated biologics expertise, and emerging polymer chemistry firms advancing synthetic alternatives. Dominant competitive moves include portfolio diversification into combination hemostat-drug delivery systems and strategic partnerships with plasma fractionation networks to secure raw material supply.
Within the diversified conglomerate tier, Johnson & Johnson and Baxter International exemplify positioning through comprehensive surgical product ecosystems. Becton Dickinson & Company occupies a distinct position among active hemostat technology specialists. These three entities represent the primary competitive anchors shaping procurement dynamics across United States and German hospital systems.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Baxter International |
| Becton Dickinson & Company |
| Medtronic |
| Pfizer |
| B. Braun |
| Integra LifeSciences Corporation |
| CryoLife |
| Advanced Medical Solutions Group |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up plasma fractionation specialists anchor supply concentration across fibrin sealant production, translating contracted blood collection network access into pricing power over hospital GPO negotiations while synthetic polymer entrants compress margins through lower-cost manufacturing alternatives.
Pricing Analysis
Bundled blood management platform agreements dominate hospital procurement, while unbundled standalone hemostat purchases persist in ambulatory surgical centers lacking transfusion infrastructure. Three-tier pricing structure across premium fibrin sealants, standard synthetic alternatives, and economy polysaccharide agents reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from integrated delivery network consolidation favoring comprehensive suppliers over single-product vendors. ASC procurement teams exhibit highest price sensitivity; cardiac surgery centers at German university hospitals demonstrate lowest sensitivity due to protocol-driven biologic requirements.
Supply Chain Analysis
ISO 13485:2016 certification and viral inactivation validation protocols gate entry to contract manufacturing networks for aseptic fibrin sealant production. Plasma fractionation capacity concentrates in the United States and Germany, while synthetic polymer feedstock manufacturing clusters in China and Switzerland. Raw material dependencies include fibrinogen and thrombin from contracted blood collection networks, polyethylene glycol precursors, and cross-linked gelatin matrices. Single-source vulnerability runs through plasma-derived input concentration. Distribution runs through GPO-mediated hospital contracts and direct-to-hospital digital procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as surgical procedure volumes recover across aging populations and health systems institutionalize blood management protocols as standard of care.
For Market Incumbents: Cement hospital contract renewal rates through integrated blood management platform bundling that displaces standalone hemostat competitors. Deepen backward integration into plasma fractionation capacity across Mannheim-Heidelberg and Jiangsu manufacturing corridors to secure fibrinogen supply continuity against donor availability fluctuations. Prioritize CE marking pathway acceleration for Class III surgical sealants ahead of notified body capacity constraints.
For New Entrants and Emerging Players: The price-point gap between premium fibrin sealants and economy polysaccharide agents creates white-space opportunity for mid-tier synthetic alternatives with comparable wet-field adhesion. Target Brazilian private hospital chains modernizing surgical infrastructure under ANVISA harmonization as the most penetrable geography. Pursue combination hemostat-drug delivery convergence in oncology reconstruction segments as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale synthetic polymer specialists lacking hospital GPO access but possessing REACH-compliant bioabsorbable polyester R&D pipelines. Long-term viability frames around 5-10 year regulatory data exclusivity windows for recombinant thrombin formulations. Watch FDA Breakthrough Device designation grants to novel hemostat mechanisms as inflection signal for platform acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EMA MDR conformity assessment backlog compresses commercial launch timelines for Class III surgical sealants across EU member states. |
| Hospital System Partnership | Integrated delivery networks in Texas and Florida bundle sealant procurement with blood management platform agreements favoring comprehensive portfolios. |
| Backward Integration into Plasma Fractionation | Captive fibrinogen and thrombin supply from Mannheim-Heidelberg and Jiangsu clusters insulates against donor availability volatility. |
| Reimbursement Strategy | Health technology assessment bodies tighten evidence requirements for combination hemostat systems versus standalone agents. |
| Software Companion Development | Digital procurement portals disintermediate traditional medical device distributors and build real-time consumption data relationships with surgical suites. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cardiac surgeons, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and plasma fractionation facility operators with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down market sizing triangulated segment-level estimates.
Historical reference periods anchored the forecast window to pre-pandemic surgical volume baselines and post-recovery trajectory normalization. Segmentation dimensions modeled include product chemistry, procedure type, care delivery site, and technology mechanism across the projection horizon. CAGRs derived from weighted average of procedure volume growth, pricing trajectory assumptions, and mix shift toward synthetic alternatives. Industry-specific inputs incorporated NMPA dual carbon incentive impact on domestic biologics procurement and REACH chemical sustainability mandate compliance costs.
Caveats apply where EMA notified body capacity constraints, plasma donor availability fluctuations, or synthetic polymer wet-field performance breakthroughs could materially shift the outlook. Deviation in regulatory approval timelines or reimbursement threshold adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Steroid-Free Nasal Sprays Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Global Lidocaine Market