
 APAC Pharmaceutical Warehousing Market | 2026-2036
APAC Pharmaceutical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Pharmaceutical Warehousing Market Insights
Insulated panel composites are hardening as the preferred enclosure material for pharmaceutical cold rooms across APAC, displacing conventional polyurethane foam in facilities requiring sub-zero integrity. Nippon Express leverages its Japan-centric temperature-controlled network to anchor premium vaccine distribution contracts. DHL Supply Chain competes through multi-country GDP-compliant certifications that sustain cross-border pharmaceutical flows between Singapore, Australia, and South Korea.
APAC pharmaceutical warehousing encompasses the receipt, climate-controlled storage, inventory management, and order fulfillment of medicinal products within facilities maintaining temperature bands from ambient through cryogenic, typically monitored by validated warehouse management systems with continuous data logging. Prescription drugs and biopharmaceuticals occupy the dominant volume positions, though vaccines within the cryogenic temperature band represent the fastest-growing margin pool as mRNA platforms expand regional manufacturing. Automated storage and retrieval systems concentrate investment among pharmaceutical manufacturers seeking to minimize human contact contamination risks, while cold storage solutions capture disproportionate capital allocation relative to their facility footprint.
India's CDSCO mandates Good Distribution Practice compliance for all pharmaceutical warehouses handling scheduled formulations, elevating infrastructure standards and disqualifying uncertified operators. Australia's TGA and South Korea's MFDS enforce parallel temperature validation protocols that shape cross-border facility design requirements. Japan's PMDA inspects foreign warehouses supplying its market, creating regulatory barriers that favor established operators with multi-jurisdiction quality systems. Stakeholders must monitor evolving pharmacopeial harmonization between ASEAN national regulators, as divergence in stability testing requirements will determine which warehouse networks qualify for regional consolidation.
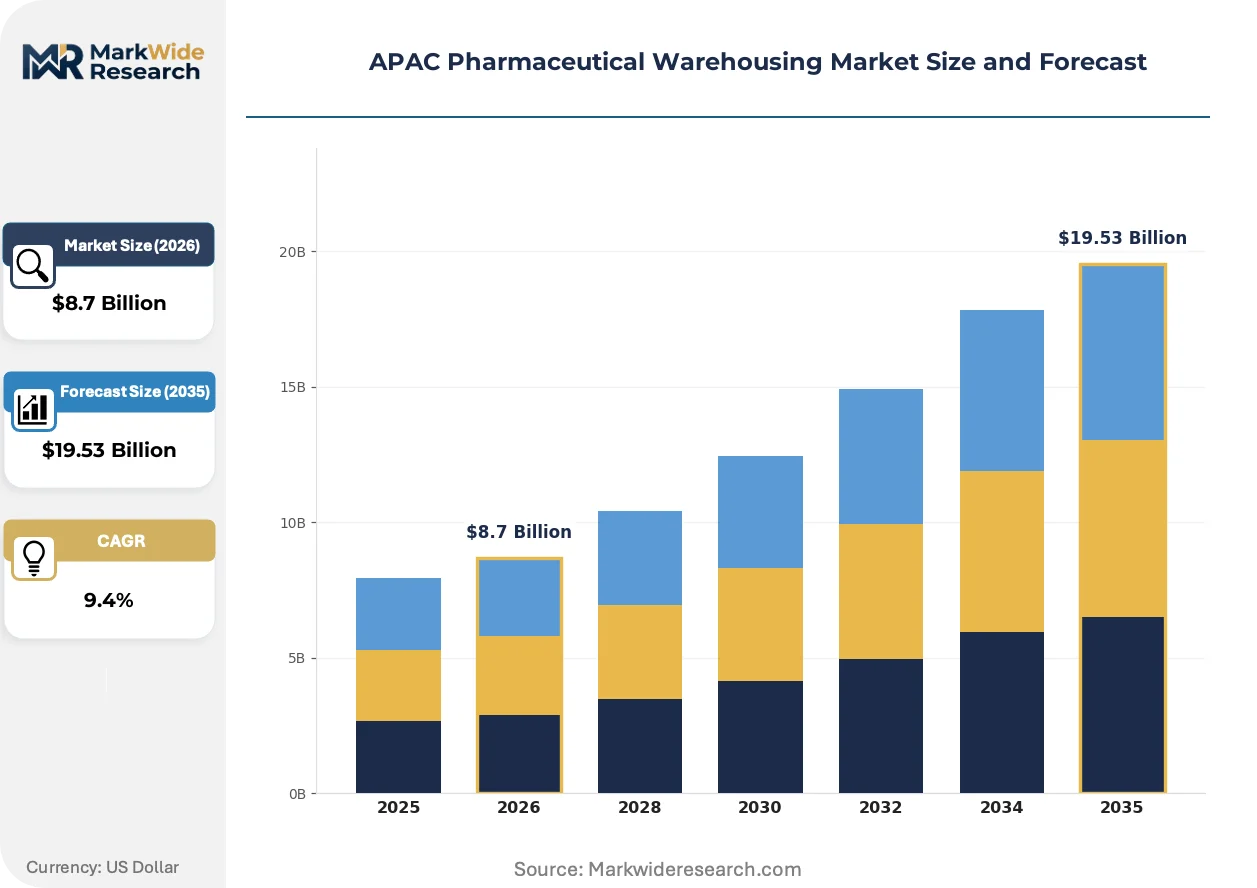
Market Dynamics
Biopharmaceutical cold chain requirements are compressing warehouse design cycles across APAC, forcing operators to retrofit ambient facilities with validated cryogenic infrastructure before regional mRNA manufacturing capacity comes online. This temperature-band expansion is reshaping capital allocation, staffing models, and regulatory compliance timelines simultaneously.
Growth Catalysts
- India's PLI Scheme:Production-linked incentives for active pharmaceutical ingredients and drug formulations are triggering warehouse construction clusters around Hyderabad, Ahmedabad, and Mumbai to support domestic manufacturing scale-up.
- Automated Storage and Retrieval Systems:Pharmaceutical manufacturers are deploying AS/RS technology to eliminate human contact contamination risks in high-value biologics handling, compressing inventory cycle times by removing manual picking errors.
- CDSCO Good Distribution Practice Mandate:India's national pharmaceutical regulator now requires GDP compliance for all scheduled formulation warehouses, disqualifying uncertified operators and consolidating volume toward qualified third-party logistics providers.
Market Restraints
- Insulated Panel Composite Input Costs:Specialized cold room enclosure materials face price volatility tied to aluminum and mineral wool supply chains, squeezing margins on sub-zero facility construction.
- Japan PMDA Foreign Warehouse Inspections:Japan's pharmaceutical regulator inspects overseas facilities supplying its market, creating regulatory barriers that favor established multi-jurisdiction operators and block new entrants.
- Cryogenic Infrastructure Capital Intensity:Liquid nitrogen and mechanical cascade systems for mRNA vaccine storage require three to four times the capital per pallet position versus conventional cold storage, limiting facility expansion rates.
Strategic Opportunities
- ASEAN Regulatory Harmonization:Divergent pharmacopeial stability testing requirements across Southeast Asian national regulators will eventually consolidate, enabling qualified warehouse networks to capture regional distribution consolidation.
- Biopharmaceutical Contract Manufacturing:CDMOs across South Korea and Singapore are outsourcing temperature-controlled warehousing to specialized operators, creating captive demand for GDP-certified facilities with cryogenic capabilities.
- Sensor-Blockchain Convergence:Continuous temperature monitoring systems are integrating with distributed ledger technology to create immutable chain-of-custody records, enabling premium pricing for compliance-verified distribution services.
Industry Challenges
- Qualified Personnel Scarcity:Validated warehouse management system operation and GDP compliance auditing require specialized skill sets that outpace regional training program output, particularly in Vietnam and Indonesia.
- Multi-Temperature Zone Integration:Facilities must simultaneously manage ambient, cold chain, frozen, and cryogenic bands with discrete validation protocols, complicating facility design and increasing commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Pharmaceutical Warehousing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Medications, Biopharmaceuticals, Vaccines Temperature Control: Ambient, Refrigerated, Frozen, Cryogenic Storage Solution: Automated Systems, Racking Systems, Cold Storage, Bulk Storage End User: Pharmaceutical Manufacturers, Distributors, Wholesalers, Hospital Pharmacies |
| Companies Covered | Nippon Express, Sankyu, DHL Supply Chain, DSV, Goke Hengtai, Kuehne + Nagel, DB Schenker, CJ Logistics, Yusen Logistics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Pharmaceutical Warehousing Market Trends and Innovations
Digital validation protocols and modular cold room construction are compressing facility deployment timelines across APAC pharmaceutical warehousing, enabling operators to match infrastructure expansion to biopharmaceutical manufacturing ramp rates without overbuilding capacity.
Insulated panel composites incorporating vacuum insulation panels and phase-change materials are converging with conventional polyurethane foam systems in pharmaceutical cold room construction. Biologics manufacturers in South Korea and Australia are specifying these hybrid enclosures for new facilities requiring sub-zero integrity with reduced energy consumption. This material convergence is enabling smaller footprint facilities to achieve equivalent thermal performance, reducing real estate requirements in high-cost urban distribution hubs.
Australia's TGA and South Korea's MFDS are enforcing parallel temperature validation protocols that shape cross-border facility design requirements. Pharmaceutical warehouses serving both markets must maintain dual-compliant documentation systems and redundant monitoring infrastructure. This regulatory alignment is compressing design variation across the region, pushing operators toward standardized GDP-compliant templates that satisfy multiple jurisdictions simultaneously.
Pharmaceutical manufacturers are consolidating warehousing contracts toward operators offering integrated ambient-through-cryogenic capabilities with single-point accountability. Large molecule biologics producers in China's eastern seaboard cities are displacing fragmented multi-provider arrangements in favor of comprehensive temperature-band coverage from specialized third-party logistics operators. This procurement consolidation is most visible in Shanghai and Suzhou, where vaccine export volumes require seamless cold chain handoffs from manufacturing through international air freight.
APAC Pharmaceutical Warehousing Market Segmentation
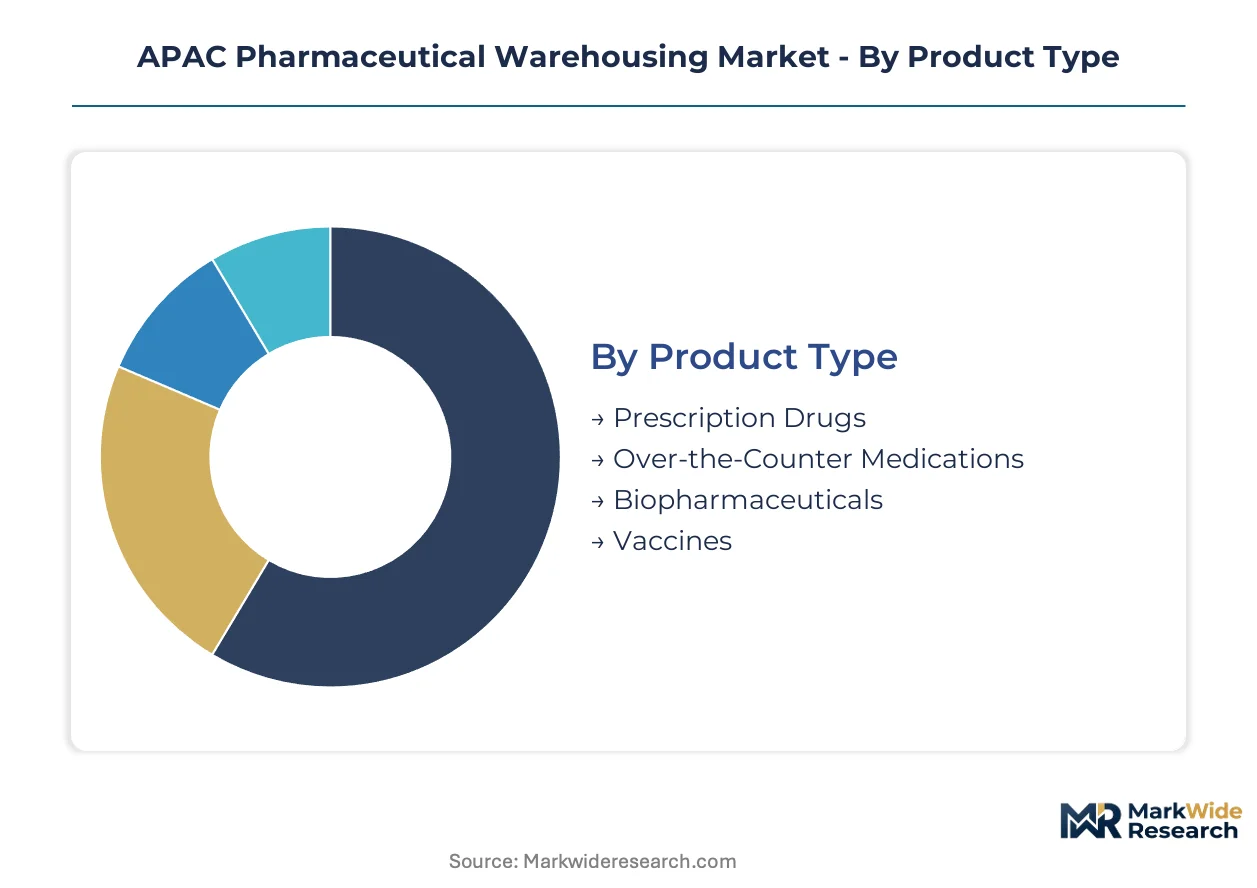
Segmentation in APAC pharmaceutical warehousing reveals how regulatory complexity concentrates investment toward certified infrastructure. Temperature-band requirements and end-use compliance obligations determine which operators capture premium contract flows across the region.
Product Type:
CDSCO GDP certification applies differentially across product categories, with biologics and vaccines triggering the most stringent validation protocols while ambient prescription drugs face lighter documentation burdens.
- Prescription Drugs:Scheduled formulations under India's CDSCO mandate require full GDP-compliant warehousing with continuous temperature monitoring and batch traceability systems. Demand clusters around Hyderabad and Mumbai where domestic manufacturing scale-up under the PLI scheme is accelerating.
- Biopharmaceuticals:Monoclonal antibodies and recombinant proteins demand validated cold chain infrastructure with redundant backup systems. South Korean CDMOs are driving facility investment in the Seoul-Incheon corridor where MFDS inspection standards shape design specifications.
- Over-the-Counter Medications:Ambient storage dominates, with distributors in Southeast Asia consolidating volume toward regional hubs in Singapore and Bangkok.
- Vaccines:mRNA platforms require cryogenic liquid nitrogen infrastructure that multiplies capital requirements per pallet position.
Leading the category by volume: Prescription Drugs. Growing fastest: Biopharmaceuticals.
Temperature Control:
Capital allocation across temperature bands correlates directly with margin capture, as sub-zero infrastructure commands pricing premiums that ambient facilities cannot match.
- Cryogenic:Liquid nitrogen and mechanical cascade systems maintain minus 150 to minus 196 degrees Celsius for mRNA vaccine stability. Australia's TGA and South Korea's MFDS enforce parallel validation protocols that compress design variation across facilities serving both markets.
- Refrigerated:Two to eight degrees Celsius bands handle insulin, biologics, and certain vaccines. China's eastern seaboard cities concentrate demand where temperature-controlled distribution networks serve export manufacturing clusters.
- Ambient:Fifteen to twenty-five degrees Celsius storage dominates tablet and capsule volumes across India and Southeast Asia.
- Frozen:Minus twenty to minus forty degrees Celsius bands support plasma derivatives and certain oncology products.
Refrigerated infrastructure commands the largest capital deployment. Cryogenic systems are climbing the fastest as regional mRNA manufacturing capacity ramps.
Storage Solution:
Automation intensity separates premium-tier operators from commodity competitors, with AS/RS investment concentrating among facilities handling high-value biologics where contamination risk carries catastrophic financial exposure.
- Automated Systems:Storage and retrieval systems eliminate human contact in high-value biologics handling. Japanese pharmaceutical manufacturers specify AS/RS for facilities supplying PMDA-regulated markets where inspection failure risks contract termination.
- Cold Storage:Insulated panel composites with vacuum insulation layers achieve sub-zero integrity in reduced footprints. Australian biologics manufacturers are specifying these hybrid enclosures for new facilities in Sydney and Melbourne.
- Racking Systems:Conventional selective and drive-in racking dominates ambient pharmaceutical storage across India.
- Bulk Storage:High-bay warehouses handle active pharmaceutical ingredients in Hyderabad and Ahmedabad production clusters.
Cold Storage leads facility investment by square meterage. Automated Systems are expanding most quickly as labor costs and contamination risks reshape procurement criteria.
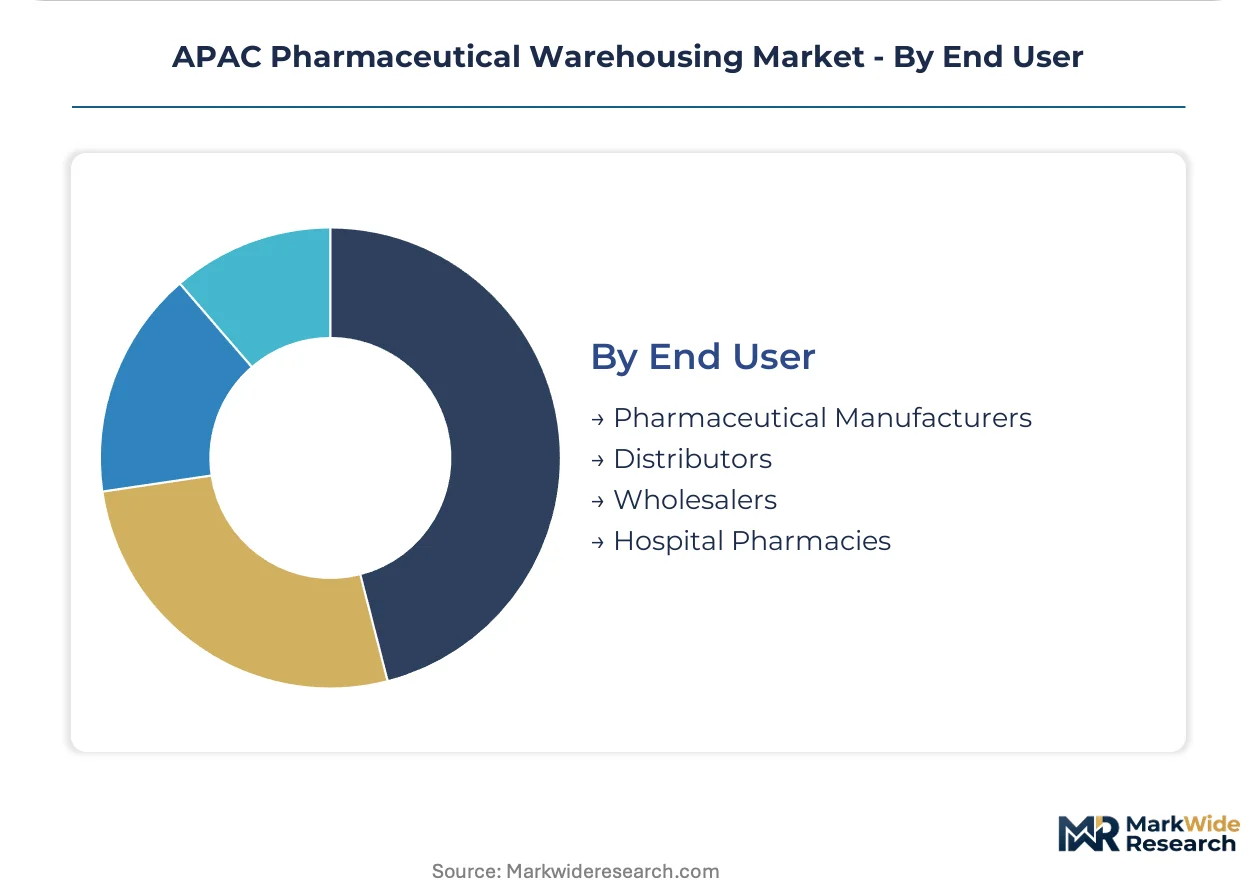
End User:
Customer type determines contract structure, with pharmaceutical manufacturers demanding integrated ambient-through-cryogenic capabilities while distributors prioritize flexibility across temperature bands.
- Pharmaceutical Manufacturers:Large molecule biologics producers in Shanghai and Suzhou are consolidating warehousing contracts toward single-point accountability operators. This procurement shift displaces fragmented multi-provider arrangements in favor of comprehensive temperature-band coverage.
- Distributors:Third-party logistics providers with GDP certification capture volume as India's CDSCO mandate disqualifies uncertified warehouse operators. Mumbai and Ahmedabad clusters show the fastest contract consolidation.
- Wholesalers:Regional distributors in Southeast Asia rely on shared-user facilities with multi-temperature zone capabilities.
- Hospital Pharmacies:Direct-to-institution delivery requires last-mile cold chain integrity that favors urban hub-and-spoke networks.
Pharmaceutical Manufacturers represent the largest contract value concentration. Distributors are gaining share fastest as regulatory compliance barriers reshape competitive dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical warehousing demand concentrates in eastern seaboard cities where temperature-controlled distribution networks serve both domestic manufacturing and export markets. India's PLI scheme is accelerating warehouse construction clusters around production hubs. Regulatory divergence across national pharmacopeial standards shapes cross-border facility qualification requirements.
China
Shanghai and Suzhou anchor biopharmaceutical manufacturing scale-up requiring seamless cold chain handoffs from production through international air freight. The NMPA enforces Good Supply Practice standards that mandate continuous temperature monitoring and batch traceability. Large molecule producers in the Yangtze River Delta are consolidating warehousing contracts toward single-point accountability operators with comprehensive ambient-through-cryogenic capabilities.
India
Hyderabad, Ahmedabad, and Mumbai form the dominant warehouse construction triangle supporting domestic API and formulation manufacturing expansion. CDSCO mandates GDP compliance for all scheduled formulation warehouses, disqualifying uncertified operators and consolidating volume toward qualified third-party logistics providers. The PLI scheme's production incentives are triggering capital allocation into validated cold storage infrastructure around these clusters.
Japan
Tokyo-Osaka corridor demand centers on premium vaccine distribution requiring sub-zero integrity throughout validated networks. PMDA inspects foreign warehouses supplying the Japanese market, creating regulatory barriers that favor established multi-jurisdiction operators. Nippon Express leverages its domestic temperature-controlled network to anchor high-value pharmaceutical contracts requiring inspection-ready quality systems.
South Korea
Seoul-Incheon corridor CDMOs are outsourcing temperature-controlled warehousing to specialized operators with cryogenic capabilities. MFDS enforces parallel temperature validation protocols with Australia's TGA, compressing facility design variation across facilities serving both markets. Biologics manufacturers specify automated storage and retrieval systems to eliminate human contact contamination risks in high-value handling operations.
Australia
Sydney and Melbourne biologics manufacturers are specifying hybrid insulated panel enclosures with vacuum insulation layers for new facilities requiring reduced energy consumption. TGA temperature validation protocols align with South Korean MFDS standards, pushing operators toward standardized GDP-compliant templates. Sensor-blockchain convergence in continuous temperature monitoring is enabling premium pricing for compliance-verified distribution services.
APAC Pharmaceutical Warehousing Market Competitive Landscape
Capacity expansion dominates the current landscape as operators retrofit ambient facilities with validated cryogenic infrastructure before regional mRNA manufacturing capacity comes online. The market structure shows tiered consolidation around established multi-jurisdiction operators with GDP certifications and specialized cold chain specialists with deep temperature-band expertise. Three archetypes define competitive positioning: integrated global logistics networks, regional pharmaceutical specialists, and automated technology-forward operators. M&A activity concentrates on acquiring GDP-certified facilities in high-demand clusters, while strategic partnerships between warehouse operators and biopharmaceutical manufacturers secure captive demand for cryogenic-capable infrastructure.
Among Japan-based logistics networks, Nippon Express and Yusen Logistics exemplify the integrated global archetype with domestic temperature-controlled networks anchoring premium pharmaceutical contracts. DHL Supply Chain represents the multi-country certification model competing through GDP-compliant cross-border flows between Singapore, Australia, and South Korea. CJ Logistics occupies a position within the Korean specialist tier, while Kuehne + Nagel and DB Schenker sit within the European-origin global network segment competing for APAC biopharmaceutical warehousing contracts.
| Leading Market Players |
|---|
| Nippon Express |
| Sankyu |
| DHL Supply Chain |
| DSV |
| Goke Hengtai |
| Kuehne + Nagel |
| DB Schenker |
| CJ Logistics |
| Yusen Logistics |
| Others |
Pricing and Supply Chain Analysis
Qualified GDP compliance auditors and validated warehouse management system operators in Vietnam and Indonesia command wage premiums that compress pricing-tier spreads between premium-certified and standard-tier pharmaceutical warehousing services across APAC.
Pricing Analysis
High-volume ambient prescription drug storage generates thin margins that subsidize cryogenic infrastructure investment, while cryogenic mRNA vaccine handling captures pricing premiums three to four times conventional cold storage rates. Price differentiation hinges on GDP certification tier and automation intensity, with AS/RS-equipped facilities commanding substantial premiums over manual operations. Cost compression in standard-tier ambient storage is intensifying because India's PLI scheme is flooding Hyderabad and Mumbai with new warehouse capacity. Generic drug distributors show acute price sensitivity, whereas biologics manufacturers prioritize temperature-band integrity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese mineral wool and aluminum suppliers feeding insulated panel composite production for pharmaceutical cold room construction across the region. Raw material dependencies center on aluminum framing, mineral wool cores, and vacuum insulation panels sourced primarily from China, South Korea, and Japan. Supply chain risk manifests as tariff exposure on aluminum imports disrupting facility construction timelines in Australia and India. Distribution runs through hub-and-spoke networks anchored in Shanghai, Singapore, and Mumbai, with last-mile cold chain integrity commanding premium pricing for direct-to-hospital pharmacy delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
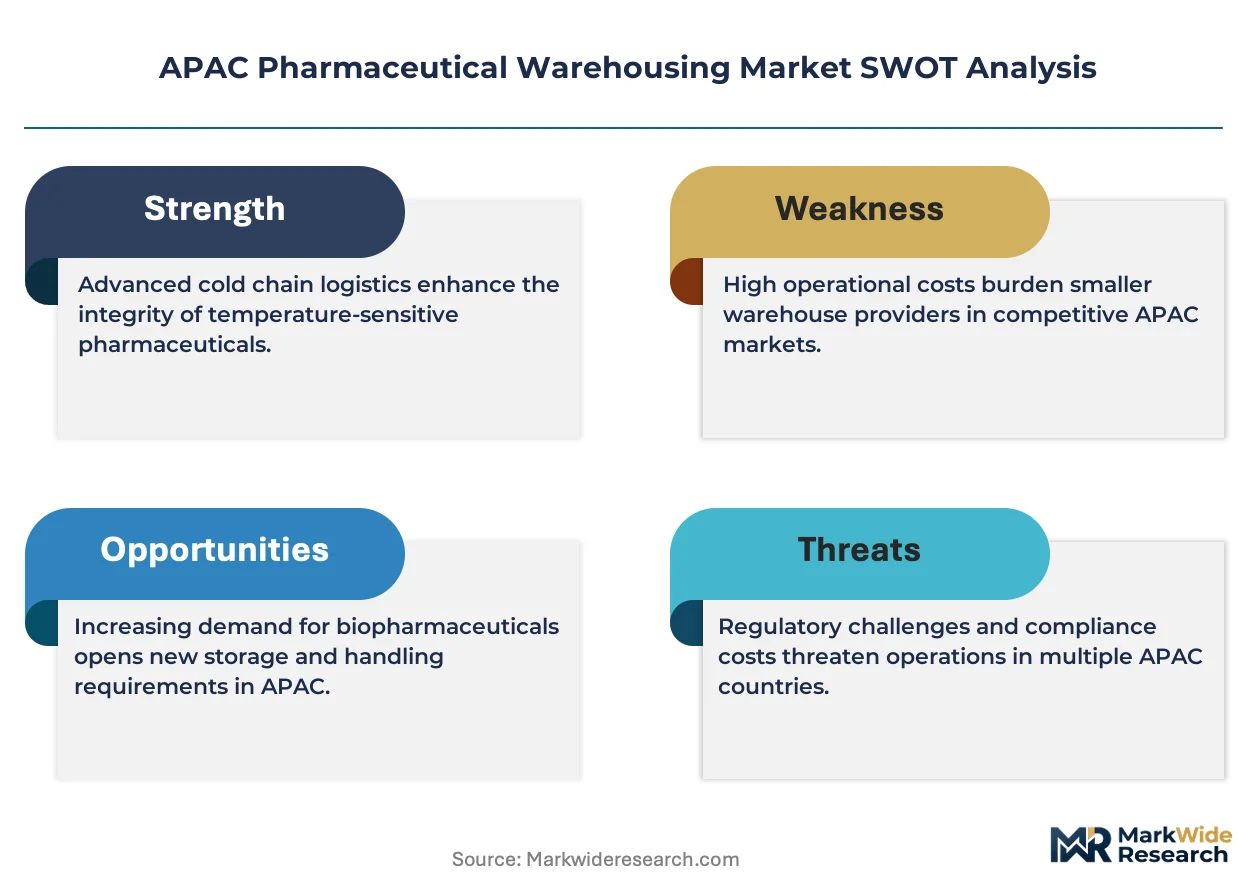
APAC pharmaceutical warehousing is transitioning from conventional polyurethane foam enclosures to insulated panel composites with vacuum insulation layers, a materials shift that is compressing facility deployment timelines and reshaping competitive positioning.
For Market Incumbents: Deepen vertical integration into insulated panel composite manufacturing to secure input cost stability and accelerate facility deployment timelines. Expand cryogenic-capable capacity in the Seoul-Incheon corridor before regional mRNA manufacturing capacity saturates qualified warehouse supply. Lock in long-term contracts with South Korean and Australian biologics manufacturers seeking single-point accountability operators. For New Entrants and Emerging Players: Capture white-space demand in Vietnam and Indonesia where qualified personnel scarcity has delayed GDP-compliant facility commissioning. Target third-party logistics contracts from India's CDSCO-mandate consolidation, where uncertified operator disqualification is displacing volume toward new qualified entrants. Lead with sensor-blockchain temperature monitoring as a differentiated compliance-verification service. For Investors and Strategic Acquirers: The window for entry favors automated technology-forward operators with existing cryogenic infrastructure in high-demand clusters. Long-term viability rests on facilities capable of spanning ambient-through-cryogenic temperature bands under multi-jurisdiction GDP compliance. Watch ASEAN regulatory harmonization progress as the signal for regional distribution consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Retrofit | Enables mRNA vaccine storage contracts as regional manufacturing capacity ramps. |
| GDP Certification Investment | Qualifies operators for India's CDSCO-mandated scheduled formulation warehousing. |
| AS/RS Technology Deployment | Eliminates contamination risks in high-value biologics handling for PMDA-regulated markets. |
| Sensor-Blockchain Integration | Creates immutable temperature records enabling premium pricing for compliance-verified services. |
| Regional Hub Consolidation | Captures economies of scale in Singapore and Bangkok for Southeast Asian distribution. |
Research Methodology
Document review covered regulatory filings with CDSCO, TGA, MFDS, and PMDA, complemented by interviews with pharmaceutical logistics directors, cold chain engineering specialists, GDP compliance auditors, and biopharmaceutical supply chain managers. Secondary sources included customs trade data on insulated panel composite imports, warehouse construction permits in Hyderabad and Ahmedabad, and air freight pharmaceutical volume statistics from Shanghai and Singapore. Bottom-up facility capacity estimates were triangulated against top-down pharmaceutical production value projections.
Historical capacity expansion patterns were cross-referenced against panel input from logistics operators and biopharmaceutical manufacturers to inform deployment assumptions across the analysis window. Segmentation modeling incorporated temperature band, storage solution automation level, end-user contract structure, and regional regulatory cluster dimensions. CAGRs were derived from fitted trend analysis applied to validated facility investment announcements and pharmaceutical manufacturing capacity expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASEAN regulatory harmonization timelines and mRNA manufacturing capacity realization rates. Forecasts reflect documented assumptions about PLI scheme continuation, aluminum tariff stability, and qualified personnel training program expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Urinary Retention Drugs Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
US Intravenous Immunoglobulin Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Obsessive Compulsive Disorder (OCD) Drug Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Hepatitis - B Therapeutics Market