
 Isoflurane Market | 2026-2036
Isoflurane Market Size, Share, and Industry Trends Forecast 2026-2036
Isoflurane Market Analytics
Indian API manufacturers are repositioning isoflurane bulk supply toward regulated Western markets. Piramal Critical Care leverages backward integration into active pharmaceutical ingredient production to secure cost advantages. Baxter International sustains brand strength across North American hospital formulary contracts. Fresenius Kabi anchors European distribution through direct sales channels to surgical centers.
Isoflurane is a halogenated methyl ethyl ether administered via calibrated vaporizer to induce and maintain general anesthesia, with a blood-gas partition coefficient of 1.4 enabling rapid induction and emergence. The liquid formulation dominates hospital procurement due to compatibility with precision vaporizer systems and established safety profiles in human surgical protocols. The veterinary care application segment represents the fastest-expanding demand pool as companion animal surgery volumes climb across Latin America and Southeast Asia. Research institutions occupy a specialized niche where isoflurane serves as the preferred anesthetic in preclinical rodent models, sustaining premium pricing despite smaller volumes.
The FDA oversees isoflurane as a prescription drug under New Drug Application pathways, while the EMA enforces Good Manufacturing Practice standards through centralized marketing authorization procedures. India's CDSCO mandates batch testing for imported inhalation anesthetics, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving volatile anesthetic waste scavenging regulations and the competitive displacement risk from sevoflurane adoption in pediatric and outpatient settings.
Market Dynamics
Sevoflurane's encroachment into pediatric and ambulatory surgical protocols is compressing isoflurane's addressable patient population, forcing suppliers to defend position through veterinary diversification and emerging market penetration.
Growth Catalysts
- Veterinary protocol expansion:Companion animal surgery volumes across Brazil and Thailand are accelerating inhalation anesthesia adoption in small-animal practices.
- EMA GMP harmonization:Centralized marketing authorization procedures are streamlining cross-border supply for compliant European manufacturers.
- Tier-one hospital concentration:Surgical volume growth in Shanghai and Beijing hospital systems is sustaining bulk procurement of precision vaporizer-compatible formulations.
Market Restraints
- Sevoflurane substitution:Lower blood-gas partition coefficients in alternative agents are capturing pediatric and outpatient settings.
- API supply concentration:Indian bulk manufacturers control upstream active pharmaceutical ingredient output, creating single-source vulnerability.
- Waste scavenging mandates:OSHA and EPA volatile anesthetic discharge regulations are elevating operating room infrastructure costs.
Strategic Opportunities
- Latin American veterinary penetration:Brazil's expanding small-animal clinic networks present untapped demand for cost-effective inhalation protocols.
- Research institution specialization:Preclinical rodent model standardization is creating premium niche pricing power.
- CDSCO pathway optimization:India's batch testing requirements for imports favor domestic manufacturers with established compliance infrastructure.
Industry Challenges
- Vaporizer calibration expertise:Precision equipment maintenance requires specialized biomedical engineering talent scarce in secondary hospital markets.
- Legacy system integration:Anesthesia delivery workstation upgrades demand capital coordination between procurement and clinical engineering departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoflurane Market |
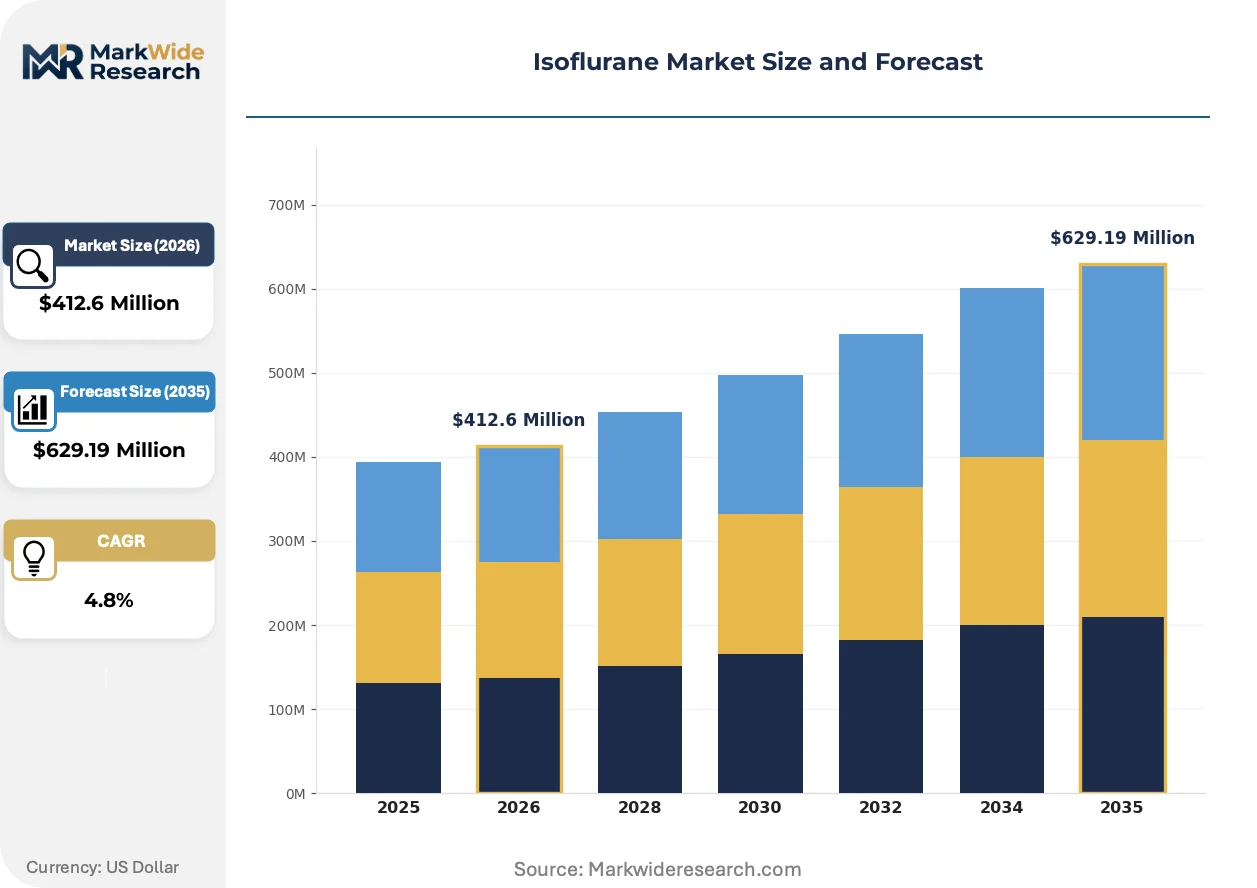
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Vapor, Injectable, Gas Application: Anesthesia, Veterinary Care, Hospital Use, Outpatient Procedures End User: Hospitals, Surgical Centers, Veterinary Clinics, Research Institutions Distribution Channel: Online Retail, Wholesalers, Direct Sales, Pharmacy |
| Companies Covered | Baxter International Inc., AbbVie Inc., Piramal Critical Care, Fresenius Kabi, Neon Laboratories Ltd, Lunan Pharmaceutical Group, Hikma Pharmaceuticals, Halocarbon Life Sciences LLC, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoflurane Market Evolving Landscape
Closed-circuit anesthesia delivery systems are reshaping consumption patterns by reducing agent waste and enabling real-time monitoring integration. These advances are compressing per-procedure cost structures while elevating equipment sophistication requirements.
Closed-circuit low-flow anesthesia technology is electrifying surgical suite efficiency by recirculating exhaled gases after carbon dioxide absorption. German and Japanese university hospital networks are adopting these systems at accelerated replacement cycles. The technology is electrifying competitive differentiation around total cost-of-ownership metrics rather than unit price alone.
EPA volatile organic compound emission thresholds are tightening scavenging system mandates for hospital outpatient departments. The regulatory friction is elevating capital expenditure requirements for waste gas capture infrastructure. North American ambulatory surgical centers are responding through group purchasing organization consolidation to amortize compliance costs.
Research laboratory procurement is consolidating around sole-source contracts with integrated chemical and equipment suppliers. Academic medical centers and contract research organizations are displacing fragmented purchasing through multi-year vendor partnerships. This pattern is most visible in US and European preclinical research hubs where protocol standardization reduces experimental variability.
Isoflurane Market Segmentation
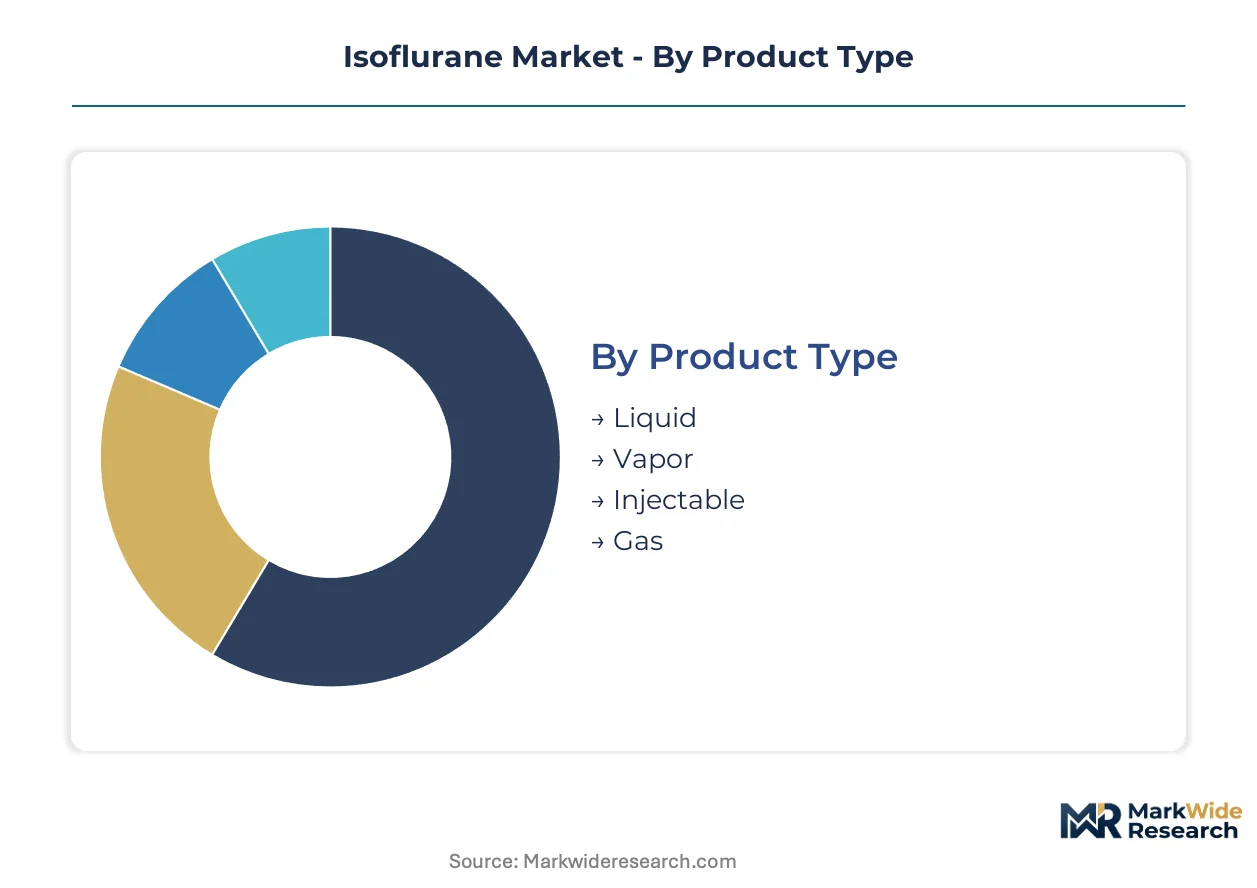
Isoflurane procurement patterns diverge sharply across clinical settings, with human surgical protocols demanding precision vaporizer compatibility while veterinary and research applications prioritize cost efficiency and bulk availability. Understanding these segment boundaries clarifies where formulation investments yield margin protection versus where price competition dominates supplier selection.
Product Type:
Liquid formulations command hospital procurement budgets through vaporizer system integration, while alternative delivery formats carve out defensive positions in specialized settings where equipment constraints or regulatory flexibility apply.
- Liquid:Halogenated methyl ethyl ether in calibrated bottle presentations compatible with precision vaporizer systems. Demand concentrates in Shanghai and Beijing tier-one hospital systems as surgical volumes climb and anesthesia workstations require standardized agent reservoirs.
- Vapor:Pre-mixed gas presentations for direct delivery without vaporization infrastructure. Veterinary clinics across Brazil are adopting vapor formats to bypass capital equipment requirements in expanding small-animal surgery networks.
- Injectable:Parenteral formulations for specialized induction protocols in research environments. Academic medical centers in Germany specify injectable isoflurane for rodent model standardization where inhalation delivery proves impractical.
- Gas:Bulk cylinder presentations for high-volume institutional consumption. Research institutions in the United States consolidate procurement around sole-source gas supply contracts to reduce experimental variability.
Today's leader: Liquid. Tomorrow's challenger: Vapor.
Application:
Human anesthesia protocols anchor revenue stability through regulatory compliance requirements, while adjacent applications expand addressable volume through lowered barriers to entry and geographic diversification.
- Anesthesia:General surgical induction and maintenance in operating room environments requiring calibrated vaporizer delivery and scavenging infrastructure. FDA prescription drug oversight under NDA pathways sustains premium positioning against sevoflurane substitution threats.
- Veterinary Care:Companion animal and livestock surgical protocols across Latin America and Southeast Asia. Thailand's small-animal clinic expansion is accelerating inhalation anesthesia adoption where intravenous alternatives previously dominated.
- Hospital Use:Inpatient surgical suites with integrated anesthesia delivery workstations and biomedical engineering support. EMA GMP harmonization is streamlining cross-border supply for compliant European manufacturers serving hospital formularies.
- Outpatient Procedures:Ambulatory surgical center applications where rapid emergence profiles reduce recovery room occupancy. EPA volatile organic compound emission thresholds are elevating capital requirements for waste gas capture infrastructure in North American ASCs.
Anesthesia defends margin. Veterinary care is climbing the fastest.
End User:
Capital intensity and regulatory sophistication create tiered customer structures, with integrated health systems extracting volume discounts while fragmented veterinary practices remain price-sensitive and brand-agnostic.
- Hospitals:Tier-one medical centers with anesthesia departments, vaporizer calibration expertise, and scavenging infrastructure. China's hospital systems in Shanghai and Beijing sustain bulk procurement of precision-compatible formulations.
- Surgical Centers:Ambulatory facilities with compressed procedure schedules and equipment standardization imperatives. Group purchasing organization consolidation in North America is amortizing compliance costs across multi-facility networks.
- Veterinary Clinics:Small-animal and mixed practices with variable anesthesia equipment sophistication. Brazil's clinic network expansion is outpacing biomedical engineering talent availability, favoring simpler delivery formats.
- Research Institutions:Academic medical centers and contract research organizations with protocol standardization requirements. Preclinical rodent model standardization in US and European hubs sustains premium pricing despite smaller absolute volumes.
Today's anchor: Hospitals. Tomorrow's expansion engine: Veterinary clinics.
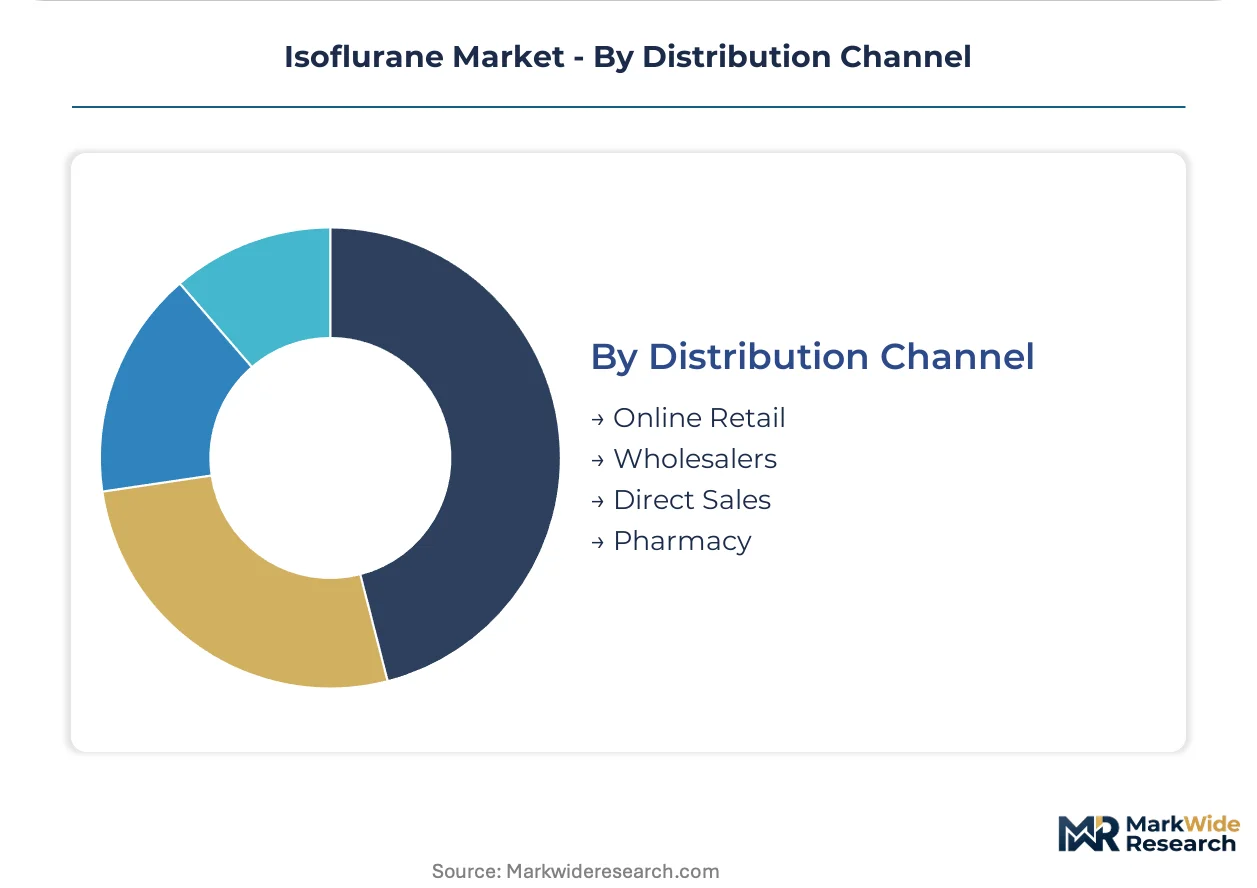
Distribution Channel:
Channel selection reflects customer scale and regulatory complexity, with direct relationships dominating institutional procurement while intermediaries serve fragmented demand pools where compliance burden and credit risk concentrate.
- Online Retail:E-commerce platforms serving veterinary practices and research laboratories with smaller order quantities. India's CDSCO batch testing requirements for imports create compliance barriers that domestic online distributors navigate more efficiently.
- Wholesalers:Regional distributors with cold chain capabilities and pharmaceutical licensing. Fresenius Kabi anchors European distribution through direct sales channels to surgical centers, bypassing wholesaler markups where volume justifies relationship investment.
- Direct Sales:Manufacturer-employed representatives serving tier-one hospital systems with formulary contracting and equipment integration support. Baxter International sustains brand strength across North American hospital formulary contracts through dedicated account management.
- Pharmacy:Hospital and retail pharmacy procurement with inventory management and just-in-time delivery protocols. Piramal Critical Care leverages backward integration into active pharmaceutical ingredient production to secure cost advantages in pharmacy channel pricing.
Direct sales commands premium positioning. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one hospital systems consume isoflurane volumes that rival North American procurement, while India's API manufacturers redirect bulk supply toward regulated Western markets. Brazil's veterinary clinic networks are expanding faster than biomedical engineering talent pools can support.
United States
FDA prescription drug oversight under NDA pathways sustains premium positioning for hospital formulary contracts. EPA volatile organic compound emission thresholds are elevating capital requirements for waste gas capture infrastructure in ambulatory surgical centers. Research institutions in Boston and San Diego consolidate procurement around sole-source contracts for preclinical rodent model standardization.
Germany
EMA GMP harmonization through centralized marketing authorization procedures streamlines cross-border supply for compliant manufacturers. German university hospital networks are adopting closed-circuit low-flow anesthesia systems at accelerated replacement cycles. Industrial clusters in Bavaria and Baden-Württemberg anchor European distribution infrastructure for precision vaporizer-compatible formulations.
China
NMPA oversight of halogenated anesthetic imports creates compliance barriers that domestic manufacturers navigate more efficiently. Shanghai and Beijing hospital systems sustain bulk procurement as surgical volumes climb in tier-one medical centers. The Yangtze River Delta concentration of pharmaceutical production supports backward integration into active pharmaceutical ingredient manufacturing.
Brazil
ANVISA pharmaceutical licensing requirements shape import pathways for inhalation anesthetics entering Latin America's largest market. Small-animal clinic networks in São Paulo and Rio de Janeiro are outpacing vaporizer calibration expertise availability. Veterinary protocol expansion across the Southeast region favors simpler vapor delivery formats that bypass capital equipment requirements.
India
CDSCO batch testing mandates for imported inhalation anesthetics create compliance barriers favoring domestic manufacturers with established infrastructure. Piramal Critical Care leverages captive supply of active pharmaceutical ingredients to secure cost advantages in regulated Western markets. Maharashtra and Gujarat pharmaceutical clusters reposition bulk isoflurane output toward export markets as domestic surgical demand matures.
Isoflurane Market Competitive Landscape
North American producers anchor one tier; Indian specialists hold upstream control over active pharmaceutical ingredient supply. The vendor base stratifies across three structural tiers: integrated pharmaceutical conglomerates with formulary contracting power, regional manufacturers with backward integration advantages, and niche specialists serving research or veterinary segments. Dominant competitive moves include geographic expansion into Latin American veterinary markets and portfolio diversification toward sevoflurane alternatives.
Among integrated pharmaceutical conglomerates, Baxter International Inc. and AbbVie Inc. exemplify the formulary-contracting archetype through dedicated account management structures. Piramal Critical Care and Fresenius Kabi occupy positions defined by upstream manufacturing control and European distribution anchoring respectively. Neon Laboratories Ltd and Lunan Pharmaceutical Group represent the regional manufacturer tier with API-to-finished-dose integration. Within the niche specialist segment, Halocarbon Life Sciences LLC exemplifies research-focused positioning.
| Leading Market Players |
|---|
| Baxter International Inc. |
| AbbVie Inc. |
| Piramal Critical Care |
| Fresenius Kabi |
| Neon Laboratories Ltd |
| Lunan Pharmaceutical Group |
| Hikma Pharmaceuticals |
| Halocarbon Life Sciences LLC |
| Viatris Inc. |
| Others |
Value Network & Pricing Analysis
Hospital formulary tiering against veterinary clinic price sensitivity splits the market into parallel pricing universes, with FDA-regulated hospital procurement commanding premium positioning while Brazilian small-animal practices drive commodity-grade demand through simpler vapor delivery formats. This bifurcation concentrates API supply control among Indian manufacturers while finished-dose pricing power accumulates with North American formulary contract holders.
Pricing Analysis
Distributor margin stacking elevates hospital channel pricing substantially above direct-to-clinic veterinary procurement, with wholesaler markups in European markets adding 15-25% over manufacturer net. Price differentiation hinges on FDA NDA pathway certification and EMA GMP compliance tier, separating regulated Western hospital supply from emerging market veterinary tiers. Pricing pressure stems from sevoflurane substitution in pediatric settings, compressing isoflurane's addressable premium segment. Veterinary clinics exhibit highest price sensitivity, while research institutions show lowest sensitivity due to protocol standardization imperatives.
Supply Chain Analysis
India's CDSCO domestic-content preferences for batch-tested inhalation anesthetics are redirecting API sourcing toward Maharashtra and Gujarat pharmaceutical clusters. Active pharmaceutical ingredient production concentrates in India and China, with finished-dose formulation in Germany and the United States. Raw material dependencies include halogenated ether precursors, specialized pharmaceutical-grade solvents, and precision vaporizer-compatible packaging materials. Single-source vulnerability pervades Indian API output concentration. Distribution runs through direct sales channels for tier-one hospitals and regional wholesalers for fragmented veterinary demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isoflurane's late-cycle quality story centers on research institution premiumization, where preclinical rodent model standardization is displacing price-sensitive procurement with specification-driven sole-source contracting.
For Market Incumbents: Deploy backward integration into halogenated ether precursor production to secure margin defense against Indian API supply volatility. Baxter International and Piramal Critical Care should consolidate formulary contracting power through multi-year anesthesia workstation bundling, neutralizing sevoflurane substitution threats in hospital systems while capturing veterinary clinic expansion through simplified vapor format distribution partnerships. For New Entrants and Emerging Players: Capture Brazil's Southeast region small-animal clinic networks where ANVISA licensing barriers filter out multinational competition and biomedical engineering scarcity favors equipment-bypass delivery formats. Thailand's accelerating companion animal surgery volume presents secondary white-space, with direct online retail penetration offering lowest customer acquisition cost against established wholesaler relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with research-focused niche specialists possessing captive rodent model protocol relationships and integrated chemical-equipment supply contracts. Long-term viability over a multi-year horizon favors acquisition targets with FDA-established 505(b)(2) pathways or EMA centralized marketing authorization infrastructure. Monitor sevoflurane pediatric adoption curves as the critical inflection signal for isoflurane hospital pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Piramal Critical Care's captive halogenated ether supply secures cost advantage against import-dependent competitors. |
| Veterinary Distribution Partnership | Fresenius Kabi's direct sales channel expansion into Brazilian clinic networks bypasses fragmented wholesaler infrastructure. |
| Research Institution Sole-Source Contracting | Halocarbon Life Sciences' multi-year academic medical center agreements lock in premium pricing through protocol standardization. |
| EMA GMP Harmonization Investment | Centralized marketing authorization procedures streamline cross-border European supply for compliant manufacturers. |
| Closed-Circuit Anesthesia System Integration | German university hospital adoption of low-flow technology shifts competitive differentiation toward total cost-of-ownership metrics. |
Research Methodology
Bottom-up hospital and veterinary clinic procurement modeling reconciled against top-down API production and finished-dose shipment tracking forms the analytical core of this study. Primary interviews with anesthesia department directors, veterinary clinic owners, biomedical engineering managers, pharmaceutical regulatory affairs leads, and group purchasing organization contract specialists were validated against secondary sources including FDA NDA filings, EMA centralized marketing authorization procedures, CDSCO import batch testing records, and ANVISA pharmaceutical licensing databases. Triangulation between demand-side consumption patterns and supply-side manufacturing output ensures statistical integrity.
Input-output matrix framing connects halogenated ether precursor availability through vaporizer-compatible finished-dose formulation to end-use consumption across human anesthesia, veterinary care, and research applications. Segmentation dimensions modeled include product type, application, end user, and distribution channel across the analysis window. CAGRs were derived from surgical volume projections, companion animal procedure growth curves, and research institution funding trajectories. Forecast inputs incorporate EPA waste scavenging mandate compliance cost escalation and sevoflurane substitution elasticity estimates.
Sevoflurane technology displacement, API supply concentration shocks, and evolving volatile anesthetic emission regulations are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Leukotriene Modifiers Market
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market