
 Optical Profilometer Market | 2026-2036
Optical Profilometer Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Profilometer Market Insights
Buyer concentration among semiconductor foundries is broadening as mature-node fabs and specialty substrate makers enter the metrology procurement pool. KLA-Tencor Corporation dominates front-end wafer inspection with captive optics expertise. Zygo Corporation leverages interferometric heritage to anchor high-precision aerospace contracts. Sensofar Metrology differentiates through modular platform architectures that span research and production environments.
An optical profilometer is a non-contact surface measurement instrument that captures topographical data through interferometric or confocal optical techniques, typically resolving vertical features below one nanometer for quality-critical components. White light interferometry variants deliver sub-nanometer z-resolution across millimeter fields, serving semiconductor, precision optics, and medical device manufacturing where tactile methods risk damage. Non-contact profilometers lead installed base value due to throughput advantages on delicate substrates, while 3D profilometers capture the fastest growth as manufacturers replace legacy 2D line scans with areal surface texture analysis per ISO 25178. Semiconductor end users concentrate the largest procurement volumes, though medical device makers generate premium pricing for validated systems under FDA 21 CFR Part 820.
ISO 25178 areal surface texture standards and FDA quality system regulations shape instrument specifications and software validation requirements across target industries. The EPA and OSHA frameworks in the United States additionally constrain manufacturing facility deployments through laser safety and cleanroom ventilation mandates. METI's industrial standards in Japan and China's GB calibration protocols further fragment certification pathways for vendors seeking multi-regional placements. Stakeholders must monitor evolving semiconductor node roadmaps and corresponding metrology sensitivity thresholds to align R&D pipelines with next-generation substrate inspection requirements.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are scaling non-contact surface metrology for advanced node inspection, creating a demand pull that concentrates procurement among foundries with sub-7nm process requirements.
Growth Catalysts
- ISO 25178 Areal Standards:Tighter surface texture specifications are forcing manufacturers to replace legacy 2D stylus systems with 3D optical profilometers capable of measuring surface parameters across full areas rather than single line scans.
- FDA 21 CFR Part 820:Medical device manufacturers face intensified quality system mandates that validate non-contact measurement for implantable components where tactile methods risk surface damage or contamination.
- White Light Interferometry:Advances in vertical resolution below one nanometer across millimeter fields are opening inspection applications for precision optics and photonic substrates previously beyond optical reach.
Market Restraints
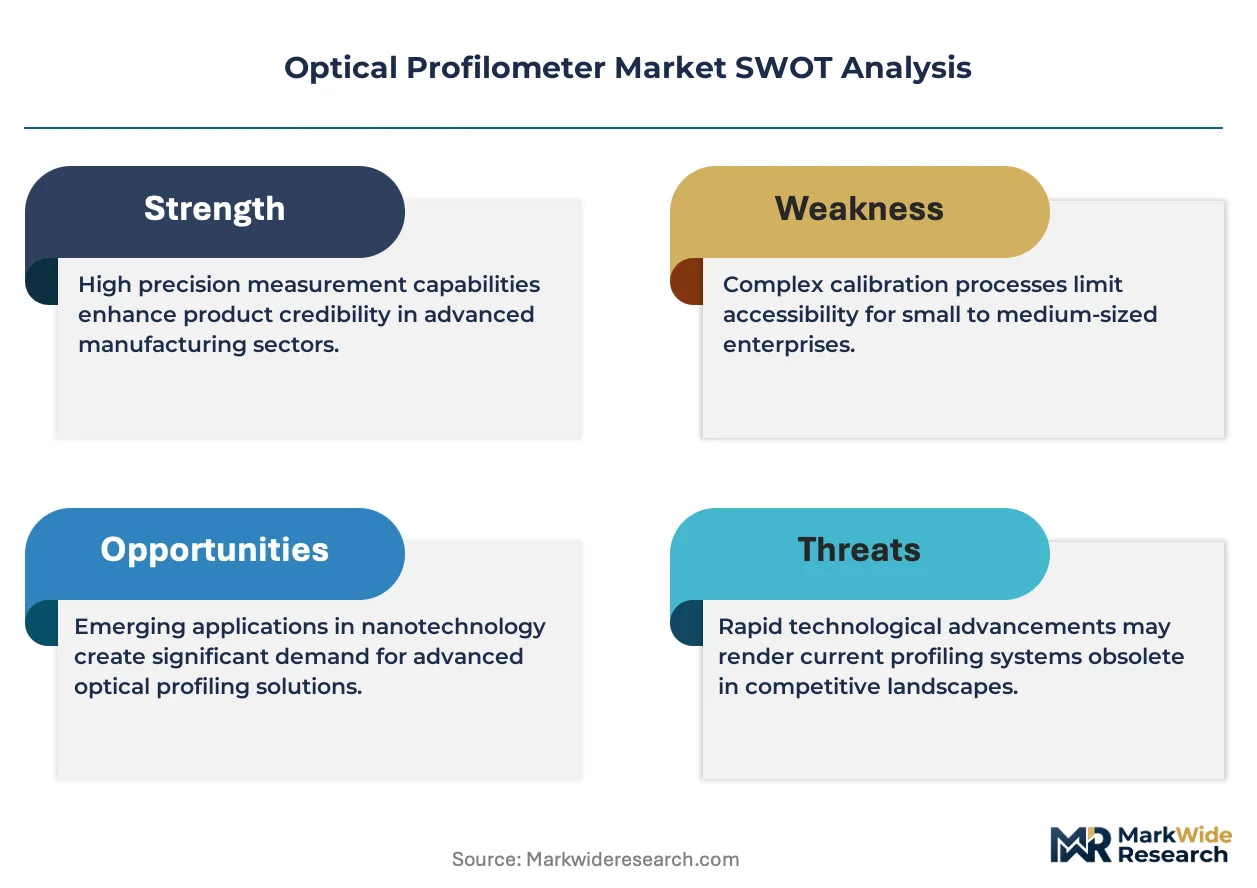
- High-Precision Optics Supply Concentration:Specialized objective lenses and reference mirrors concentrate among Japanese and German optical houses, creating single-source vulnerability for instrument builders.
- Cleanroom Infrastructure Requirements:EPA and OSHA laser safety mandates plus ventilation specifications add facility costs that exclude smaller contract manufacturers from deploying interferometric systems.
- Atomic Force Microscope Substitution:AFM systems capture sub-nanometer lateral resolution for research applications, constraining optical profilometer penetration in materials science laboratories.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating first-time demand for surface metrology among domestic EMS providers establishing captive testing labs.
- Automotive Lidar Optics:Precision aspheric lens production for autonomous vehicle sensors requires areal roughness verification that white light interferometry delivers at production throughput rates.
- AI-Enabled Defect Classification:Machine vision integration with profilometry software is expanding into automated pass-fail decisions that reduce operator dependency in high-volume environments.
Industry Challenges
- Interferometry Specialist Shortage:Instrument calibration and optical alignment require physics-trained technicians that fabs and service organizations struggle to recruit against semiconductor equipment competitors.
- Multi-Regional Certification Burden:Japan's METI industrial standards, China's GB calibration protocols, and FDA software validation requirements create redundant documentation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Profilometer Market |
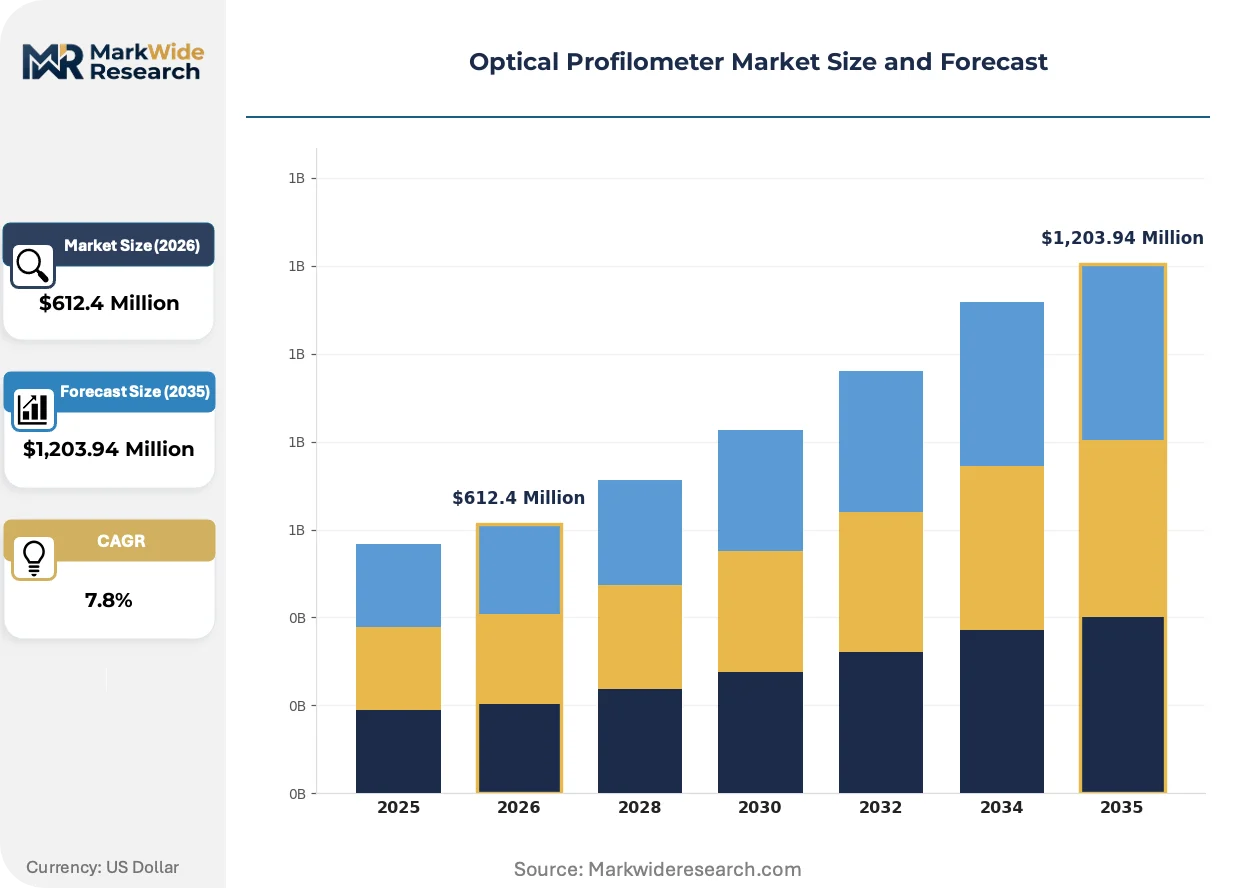
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,203.94 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Profilometers, Non-Contact Profilometers, 2D Profilometers, 3D Profilometers End User: Semiconductor, Aerospace, Automotive, Medical Devices Technology: Interferometry, Laser Scanning, White Light Interferometry, Confocal Microscopy Application: Surface Analysis, Thickness Measurement, Quality Control, Research & Development |
| Companies Covered | Sensofar Metrology, Taylor Hobson Ltd., Zygo Corporation, 4D Technology Corporation, Alicona Imaging GmbH, KLA-Tencor Corporation, Keyence Corporation, Cyber Technologies GmbH, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Profilometer Market Trends and Innovations
Three distinct vectors are reshaping optical profilometer development: optical hardware miniaturization, regulatory harmonization pressures, and buyer procurement model evolution toward integrated metrology platforms.
Confocal chromatic sensor technology is expanding into high-aspect-ratio feature measurement for through-silicon vias and microfluidic channels. MEMS manufacturers in Germany and Switzerland are adopting these sensors for wafer-level packaging inspection. The technology is expanding into geometries previously requiring destructive cross-sectioning, compressing development cycles for advanced substrate designs.
REACH substance restrictions and EU F-Gas Regulation are constraining laser source materials and cooling chemistries in interferometer construction. Instrument vendors are reformulating optical coatings and sealed gas laser tubes to maintain stability without restricted compounds. German precision optics manufacturers are most affected, accelerating transitions to solid-state and fiber-based illumination architectures.
Buyers are consolidating metrology vendors to reduce qualification overhead and service fragmentation. Semiconductor foundries in Taiwan now specify platform architectures spanning research through production rather than maintaining separate instrument pools. This vendor consolidation trend is most visible among tier-one foundries with multi-fab footprints seeking standardized data formats and interoperable software environments.
Optical Profilometer Market Segmentation
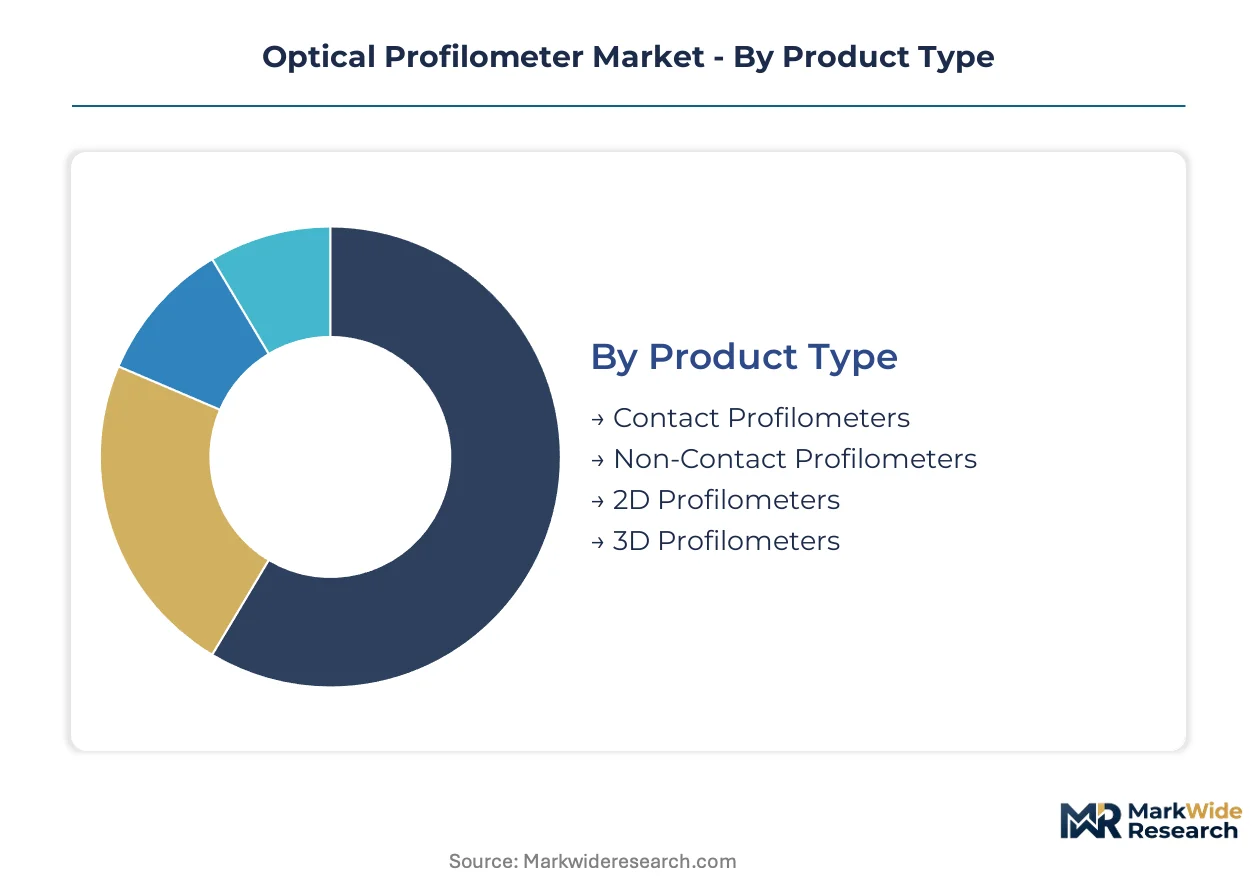
Optical profilometer procurement splits across four structural dimensions, each carrying distinct certification burdens and technical validation requirements. Semiconductor fabs demand ISO 25178 traceability, while medical device manufacturers require FDA 21 CFR Part 820 software validation. Understanding these segment boundaries clarifies why vendor consolidation and platform standardization dominate buyer strategy.
Product Type:
Certification pathways diverge sharply: non-contact and 3D systems face extended FDA and METI validation cycles for areal surface texture compliance, while contact profilometers navigate simpler mechanical calibration protocols.
- Non-Contact Profilometers:Interferometric and confocal optical systems eliminate stylus damage risk on delicate substrates. Taiwan and South Korea foundries concentrate procurement for sub-7nm node wafer inspection where tactile methods destroy yield.
- 3D Profilometers:Areal surface measurement systems capture full-field topography per ISO 25178 standards. Medical device manufacturers in Germany and Switzerland drive premium pricing for validated implantable component inspection.
- Contact Profilometers:Stylus-based mechanical tracing systems retain cost advantages for coarse surface roughness measurement in automotive supply chains.
- 2D Profilometers:Legacy line-scan instruments face replacement pressure from areal measurement mandates in precision optics manufacturing.
Leading the category by volume: Non-Contact Profilometers. Expanding most quickly: 3D Profilometers.
End User:
Cost tier stratification separates capital-intensive semiconductor fabs from price-sensitive automotive suppliers, with aerospace and medical device makers occupying premium validation tiers.
- Semiconductor:Foundries in Taiwan, South Korea, and the United States concentrate the largest procurement volumes for advanced node metrology. Sub-7nm process requirements demand sub-nanometer vertical resolution that white light interferometry delivers.
- Medical Devices:Implantable component manufacturers face FDA 21 CFR Part 820 quality system mandates that validate non-contact measurement methods. Swiss and German precision instrument clusters generate premium pricing for certified systems.
- Aerospace:Precision optics and turbine blade inspection requires interferometric heritage for aspheric surface verification. North American and European defense contractors anchor long-term service contracts.
- Automotive:Lidar lens production for autonomous vehicle sensors creates emerging demand for production-throughput areal roughness measurement. German and Japanese tier-one suppliers lead pilot deployments.
Dominating procurement value: Semiconductor. Climbing the fastest: Medical Devices.
Technology:
Application specificity determines technology selection, with high-aspect-ratio geometries favoring confocal approaches and nanometer-scale planar inspection demanding interferometric methods.
- White Light Interferometry:Vertical resolution below one nanometer across millimeter fields serves semiconductor front-end inspection and precision optics manufacturing. South Korean display panel fabs scale deployment for OLED substrate characterization.
- Confocal Microscopy:Chromatic sensor technology measures high-aspect-ratio features in through-silicon vias and microfluidic channels. German MEMS manufacturers adopt these systems for wafer-level packaging inspection.
- Interferometry:Coherent laser interferometry retains dominance in flatness measurement for optical reference surfaces and semiconductor wafer geometry.
- Laser Scanning:Triangulation-based systems offer cost-efficient alternatives for coarse surface mapping in automotive and consumer electronics quality control.
Holding largest installed base: Interferometry. Gaining share fastest: White Light Interferometry.
Application:
Customer type fragmentation separates high-volume production environments from research laboratories, with quality control representing the volume anchor and R&D commanding premium pricing.
- Quality Control:Production-line surface verification dominates instrument utilization hours across semiconductor and automotive manufacturing. Taiwan foundries specify automated pass-fail integration to reduce operator dependency.
- Surface Analysis:Areal texture characterization per ISO 25178 parameters drives replacement demand from legacy 2D stylus systems. Japanese precision component manufacturers lead standard adoption.
- Thickness Measurement:Transparent film and coating thickness applications favor interferometric methods in display and photovoltaic manufacturing.
- Research & Development:Materials science laboratories require flexible platform architectures spanning multiple measurement modalities. Academic and government research institutes in Europe and North America anchor this segment.
Capturing highest unit volume: Quality Control. Steepest expansion trajectory: Surface Analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical profilometer procurement concentrates in East Asian electronics manufacturing corridors, with Taiwan and South Korea foundries driving sub-7nm metrology requirements. FDA-regulated medical device clusters in Germany and Switzerland generate premium pricing for validated systems. India's PLI scheme is catalyzing first-time demand among domestic EMS providers.
Taiwan
Semiconductor foundries in Hsinchu and Tainan Science Parks scale white light interferometry for advanced node wafer inspection. The island's Industrial Development Bureau enforces precision equipment localization targets. TSMC and United Microelectronics anchor procurement volumes for non-contact surface metrology systems.
South Korea
Display panel fabs in Gyeonggi Province deploy optical profilometers for OLED substrate characterization. MFDS medical device regulations drive validation requirements for implantable component manufacturers. Samsung and SK Hynix facilities in Suwon and Icheon concentrate metrology investment.
Germany
MEMS manufacturers in Baden-Württemberg adopt confocal chromatic sensors for wafer-level packaging inspection. REACH substance restrictions constrain laser source materials in interferometer construction. Precision optics clusters in Stuttgart and Oberkochen reformulate optical coatings to maintain stability.
United States
Precision optics and turbine blade inspection in Connecticut and Arizona requires interferometric heritage for aspheric surface verification. FDA 21 CFR Part 820 mandates quality system validation for medical device metrology. Northrop Grumman and Raytheon defense contractors anchor long-term service contracts.
India
PLI scheme incentives for semiconductor and display fabrication create first-time demand among domestic EMS providers. BIS calibration protocols establish metrology standards for emerging testing labs. Gujarat and Karnataka electronics manufacturing clusters establish captive surface measurement capabilities.
Optical Profilometer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular platform architectures that span research and production environments. The vendor base stratifies across three tiers: front-end semiconductor specialists with captive optics expertise, precision interferometry heritage players serving aerospace and defense, and modular platform builders addressing multi-industry applications. Consolidation pressures intensify as tier-one foundries seek standardized data formats and interoperable software environments across multi-fab footprints. Competitive moves center on strategic partnerships for AI-enabled defect classification and geographic expansion into India electronics manufacturing corridors.
Within the precision interferometry tier, Zygo Corporation and 4D Technology Corporation exemplify heritage players leveraging optical expertise for high-precision aerospace and defense contracts. Among modular platform specialists, Sensofar Metrology occupies a position representing flexible architectures that bridge research laboratories and production environments. At the semiconductor front-end vector, KLA-Tencor Corporation anchors the inspection-intensive segment where sub-nanometer resolution requirements concentrate procurement decisions. These three archetypes—heritage interferometry, modular platforms, and front-end semiconductor specialists—capture distinct buyer segments with limited overlap in technical specifications and validation requirements.
| Leading Market Players |
|---|
| Sensofar Metrology |
| Taylor Hobson Ltd. |
| Zygo Corporation |
| 4D Technology Corporation |
| Alicona Imaging GmbH |
| KLA-Tencor Corporation |
| Keyence Corporation |
| Cyber Technologies GmbH |
| Bruker Corporation |
| Others |
Pricing and Supply Chain Analysis
Optical metrology physicists concentrate in German and Japanese precision optics clusters, and their scarcity widens pricing spreads between validated premium-tier systems and standard production instruments. Labor-cost differentials between Stuttgart-area interferometer specialists and Taiwan-based service technicians feed directly into tiered service-contract pricing that semiconductor foundries negotiate.
Pricing Analysis
Volume concentrates in non-contact profilometers for semiconductor fabs, while margins accrue to 3D systems with FDA validation for medical device manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates certified metrology platforms from modular research systems and legacy 2D stylus instruments. Price differentiation hinges on ISO 25178 traceability grade and after-sales service bundling. Pricing pressure stems from foundry consolidation demanding standardized data formats across multi-fab footprints. Automotive lidar lens suppliers exhibit highest price sensitivity; Swiss implantable device makers show least.
Supply Chain Analysis
Specialized objective lenses and reference mirrors rest on Japanese and German optical houses, creating single-source vulnerability for instrument builders. High-precision optics concentrate in Japan, Germany, and Switzerland; electronic controllers source from Taiwan and South Korea. Raw material dependencies include fused silica substrates, laser gas mixtures, and chromatic sensor coatings. Supply chain risk centers on REACH substance restrictions constraining laser source materials. Distribution runs through direct sales for semiconductor fabs and specialized distributors for research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White light interferometry is displacing legacy 2D stylus profilometers as ISO 25178 areal standards tighten, creating a technology-transition window where platform architecture decisions determine competitive position.
For Market Incumbents: Deploy AI-enabled defect classification to reduce operator dependency in Taiwan foundries facing interferometry specialist shortages. Consolidate software environments across research and production platforms to defend against modular entrants. Deepen captive optics expertise through backward integration into reference mirror production, mitigating Japanese supplier concentration risk.
For New Entrants and Emerging Players: Begin with India's PLI-scheme electronics manufacturing corridors where first-time demand for surface metrology lacks established vendor relationships. Target domestic EMS providers establishing captive testing labs in Gujarat and Karnataka. Pursue confocal chromatic sensor architectures for high-aspect-ratio MEMS inspection as the most penetrable technology gap.
For Investors and Strategic Acquirers: Re-rating potential sits with modular platform specialists given foundry procurement consolidation toward standardized architectures. Long-term viability favors vendors spanning semiconductor front-end and medical device validation tiers. Watch semiconductor node roadmap acceleration as the inflection signal for metrology sensitivity threshold shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Defect Classification | Machine vision integration reduces operator dependency in TSMC and Samsung high-volume environments. |
| Modular Platform Architecture | Flexible systems bridge research laboratories and production lines for Sensofar-style multi-industry positioning. |
| Backward Integration into Optics | In-house reference mirror production mitigates Japanese supplier concentration for Zygo heritage players. |
| India Geographic Expansion | PLI scheme incentives create first-mover advantage among domestic EMS providers in Gujarat clusters. |
| Regulatory Harmonization Investment | Unified FDA-METI-GB validation documentation accelerates multi-regional product launches for tier-one vendors. |
Research Methodology
Multi-period observation of semiconductor node roadmaps and metrology procurement patterns anchored the trend analysis, supplemented by interviews with instrument calibration technicians, foundry metrology engineers, precision optics procurement leads, and FDA quality system auditors. Secondary validation drew from SEMI equipment market data, ISO standard revision documentation, SEC filings of listed metrology vendors, and Taiwan Industrial Development Bureau localization reports. Bottom-up vendor shipment tracking and top-down electronics manufacturing investment flows were triangulated.
Input-output matrices mapped white light interferometry and confocal chromatic sensor adoption against end-user segmentation across semiconductor, medical device, aerospace, and automotive verticals. Modeled dimensions spanned product type, technology modality, application environment, and regional regulatory cluster. CAGRs were derived from instrument replacement cycles tied to ISO standard revision timelines and foundry capacity expansion announcements. Forecast inputs included sub-7nm node metrology sensitivity thresholds and OLED substrate inspection throughput requirements.
Semiconductor capital expenditure volatility, REACH substance restriction scope expansion, and interferometry specialist labor market tightness are the dominant revision risks. Forecasts reflect documented assumptions on node transition pacing and regulatory harmonization progress. A small set of named triggers—node acceleration announcements, PLI scheme disbursement timing, and METI standard revision schedules—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Anti Glare Film Market
Optics
Single-Mode Optical Fiber Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Smart Glass Market
Optics
Photostimulation Lasers Market
Optics
Optical Fiber Raw Material Market
Optics
Laser Transmitter Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Europe Laser Interferometer Market
Optics
MEMS Mirrors Market
Optics
Polymeric Optical Fiber Market
Optics
Lasers Market
Optics
Global Fiber Optic Components Market
Optics
Global Enhanced Vision System Market
Optics
North America Optical Imaging Market
Optics
Sports Optics Market