

Optical Telephoto Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Telephoto Lens Market Insights
The EU Green Deal's material sustainability mandates is consolidating procurement criteria across European broadcasting agencies and scientific research institutions. Canon leverages in-house fluorite crystal cultivation to sustain premium lens lines with reduced rare-earth dependency. Nikon anchors its professional sports imaging dominance through proprietary vibration reduction systems integrated across its telephoto range. Sigma competes aggressively in the third-party zoom segment with Art-series optics that undercut first-party pricing while matching resolving power.
An optical telephoto lens employs an elongated focal length—typically exceeding 85mm in full-frame equivalent—to magnify distant subjects through converging lens groups arranged in telephoto configuration, often incorporating extra-low dispersion glass and aspherical surfaces to suppress chromatic aberration and field curvature across extended optical paths. Prime telephoto lenses occupy the margin-rich professional tier where wildlife photographers and cinematographers prioritize maximum aperture and rendering character over versatility. Zoom telephoto variants lead unit volumes among broadcasting agencies requiring rapid focal-length adjustment during live sports coverage. Image stabilization technology represents the fastest-growing technical segment as drone imaging and handheld wildlife applications demand effective compensation for platform motion and operator shake.
EMA chemical safety assessments, EU RoHS substance restrictions, and ISO 10110 optical surface quality standards collectively govern material selection, coating chemistry, and manufacturing tolerances for lenses distributed across European professional markets. The US FDA does not directly regulate camera optics, yet FCC electromagnetic emissions certification affects telephoto lenses with integrated autofocus motors and electronic aperture control. Stakeholders must monitor evolving rare-earth export policies and fluorite supply concentration in select mining jurisdictions to secure long-term material access and cost predictability.
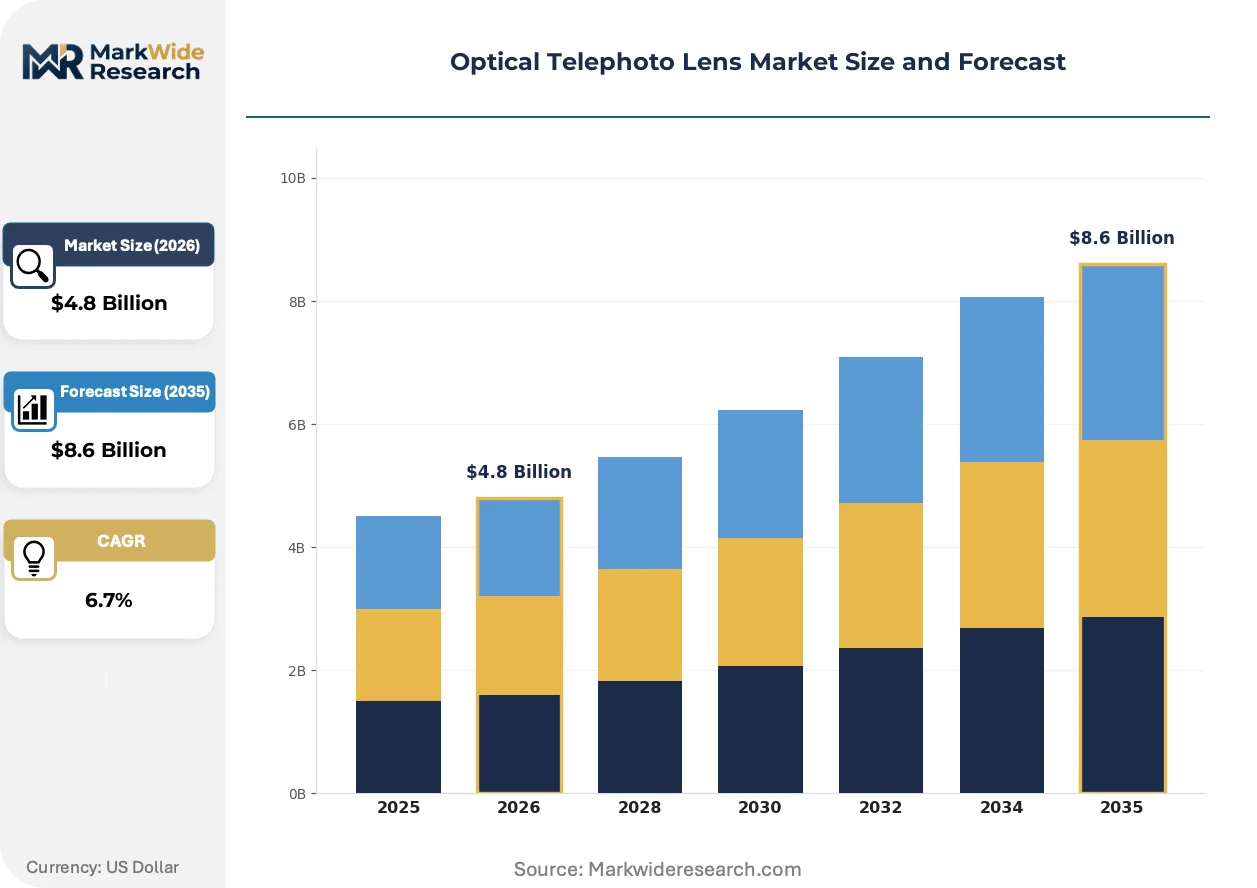
Market Dynamics
Fluorite crystal supply concentration and REACH-mandated lead-glass phaseouts are restructuring European procurement networks and accelerating alternative material qualification programs across premium lens manufacturers.
Growth Catalysts
- Wildlife cinematography expansion:Streaming platforms commission natural history documentaries requiring super-telephoto optics with minimal focus breathing. Production houses in Kenya, Botswana, and Costa Rica expand rental fleets.
- EU Green Deal material mandates:Broadcasting agencies in Germany, France, and the Netherlands consolidate sustainable procurement criteria favoring fluorite-based lenses with verified supply chain documentation.
- Image stabilization maturation:Gyroscopic and electromagnetic actuator technologies now deliver five-stop compensation, enabling handheld 600mm equivalent capture for drone-mounted and vehicle-based cinematography.
Market Restraints
- Fluorite supply geography:High-purity synthetic fluorite cultivation concentrates in Japanese and Chinese facilities, creating single-source vulnerability for European and North American lens assemblers.
- Rare-earth magnet dependency:Autofocus linear motors require neodymium-iron-boron magnets subject to export licensing fluctuations from Chinese customs authorities.
- Optical glass energy intensity:Lead-free extra-low dispersion glass requires 40% higher kiln temperatures than legacy formulations, compressing margins at mid-tier manufacturers without captive energy contracts.
Strategic Opportunities
- Indian content production infrastructure:Reliance and Disney+ Hotstar commissioning drive demand for broadcast telephoto zooms in Mumbai, Hyderabad, and Chennai production clusters.
- Computational-optical convergence:Multi-frame computational sharpening reduces absolute resolving power requirements, opening market space for lighter, polymer-asphere designs in travel photography segments.
- EU CSRD disclosure requirements:Scope 3 emissions reporting mandates push rental houses toward certified refurbishment programs and circular lens economy platforms.
Industry Challenges
- Optical design talent scarcity:Zemax and Code V proficiency concentrates among engineers with 15+ years experience, constraining expansion at emerging Asian lens houses.
- ISO 10110 surface quality certification:Scratch-dig specification testing requires six-month qualification cycles for new coating vendors, delaying cost-reduction initiatives.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Telephoto Lens Market Trends and Innovations
Telephoto lens architecture is bifurcating between computational-augmented lightweight designs for content creators and uncompromising optical purity systems for professional wildlife and sports documentation.
Diffraction-limited aspherical molding is electrifying mid-market zoom construction. Precision glass-molding presses now shape complex convex-concave surfaces to λ/20 wavefront accuracy at volumes impossible with traditional grinding. Chinese optical houses in Changchun and Shenzhen deploy these presses for f/2.8 constant-aperture 70-200mm equivalents. The technology is electrifying price-performance ratios in the $800-1,500 segment, compressing first-party premium positioning.
REACH Annex XVII lead restrictions are forcing coating chemistry reformulation across European distribution channels. ECHA substance evaluations now classify certain high-refractive index glass components as substances of very high concern, requiring substitution with lanthanum-doped alternatives. German and Italian lens importers accelerate supplier audits to maintain CE marking compliance, favoring Japanese and Taiwanese coating facilities with pre-certified environmental management systems.
Rental-to-own financing structures are displacing outright purchase in independent cinematographer segments. ShareGrid and KitSplit platforms enable $200-400 daily access to $10,000+ super-telephoto primes previously restricted to studio inventory. Los Angeles and Atlanta production communities demonstrate highest platform penetration, with wildlife specialists in Bozeman and Anchorage adopting similar models for seasonal shooting windows.
Optical Telephoto Lens Market Segmentation
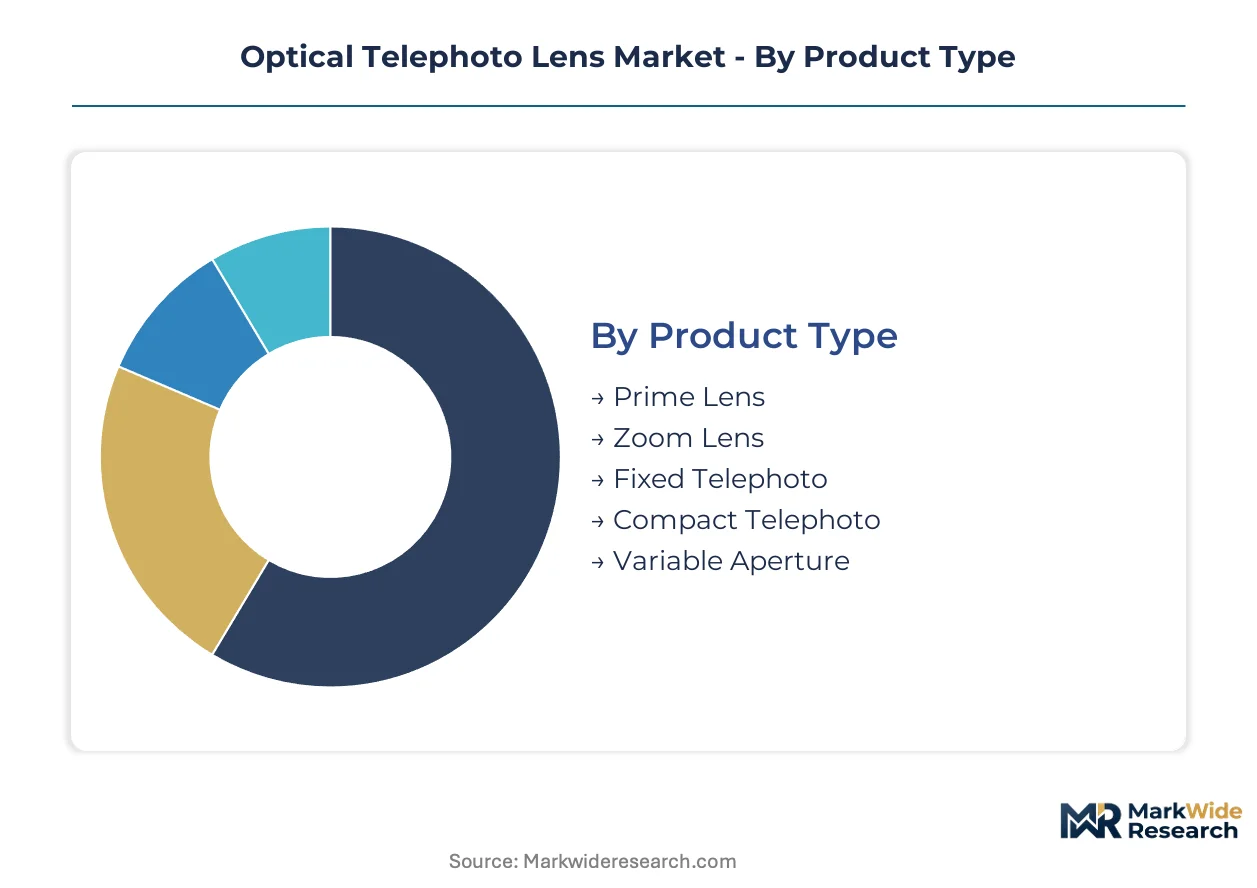
Telephoto lens purchasing patterns diverge sharply across technical specifications, deployment contexts, and operator sophistication. Manufacturers configure product lines, coating investments, and distribution channels around these fault lines to capture margin concentration where optical performance commands premium pricing.
Product Type:
Customization intensity spans from bespoke cinema primes to mass-produced consumer zooms, with each tier demanding distinct glass sourcing, assembly precision, and channel economics.
- Prime Lens:Fixed focal-length designs maximize aperture diameter and minimize optical aberrations through simplified group structures. Wildlife photographers in Kenya and Botswana prioritize 400mm and 600mm equivalents for dawn-dusk light capture where speed outweighs flexibility.
- Zoom Lens:Variable focal-length systems integrate multiple moving groups with complex cam mechanisms to maintain optical alignment across magnification ranges. Broadcasting agencies in Germany and the Netherlands dominate procurement for live sports coverage requiring rapid reframing without lens changes.
- Fixed Telephoto:Non-collapsible barrel designs optimize thermal stability and alignment precision for laboratory and observatory applications. Scientific researchers at European astronomy institutes specify these for spectroscopic instrumentation.
- Compact Telephoto:Shortened optical paths through folded mirror or diffractive element integration reduce mass for travel and drone mounting. Content creators in Los Angeles rental markets favor these for location shoots with weight restrictions.
- Variable Aperture:Mechanically or electronically controlled iris systems adapt exposure across zoom ranges where constant aperture would require prohibitive element diameters. Budget-conscious wedding videographers in Indian production clusters adopt these for cost-controlled kit building.
Leading the category by volume: Zoom Lens. Growing fastest: Compact Telephoto.
Technology:
Material science investments separate premium positioning from commodity competition, with patented element formulations creating defendable margin architecture.
- Aspherical Lens:Precision-molded or ground surfaces correct spherical aberration without additional elements, reducing weight and transmission losses. Chinese optical houses in Changchun deploy glass-molding presses achieving λ/20 wavefront accuracy at volumes that compress mid-market pricing.
- Low Dispersion Glass:Modified refractive index formulations minimize chromatic aberration through controlled dispersion curves. REACH-mandated lead-glass phaseouts are accelerating lanthanum-doped alternative qualification across European supply chains.
- Fluorite Elements:Synthetic calcium fluoride crystals deliver ultra-low dispersion with anomalous partial dispersion characteristics impossible in optical glass. Canon's in-house cultivation capabilities insulate premium lines from rare-earth supply volatility.
- Image Stabilization:Gyroscopic sensors and electromagnetic actuators compensate for platform motion and operator shake. Five-stop compensation systems now enable handheld 600mm equivalent capture for vehicle-based cinematography.
- Multi-Coating:Vapor-deposited interference layers suppress surface reflections and ghosting across extended element counts. ISO 10110 surface quality certification requirements impose six-month qualification cycles that delay cost-reduction initiatives at new coating vendors.
Dominating manufacturer R&D allocation: Image Stabilization. Expanding most quickly: Fluorite Elements.
Application:
End-use environments dictate durability specifications, optical performance thresholds, and service infrastructure requirements across divergent deployment contexts.
- Wildlife Photography:Extended focal lengths with weather-sealed construction operate in humidity, dust, and temperature extremes. Production houses in Costa Rica expand rental fleets for streaming platform natural history commissions.
- Sports Imaging:Rapid autofocus acquisition and high frame-rate compatibility capture decisive moments in stadium lighting. Nikon's proprietary vibration reduction systems anchor professional dominance in this segment.
- Surveillance Systems:Continuous operation reliability and integrated analytics interfaces prioritize mean-time-between-failure metrics over absolute resolving power. China's expanding infrastructure modernization programs concentrate demand volume.
- Astrophotography:Flat-field correction and minimal coma across wide image circles support long-exposure deep-sky capture. Amateur astronomers in Arizona and New Mexico dark-sky regions drive enthusiast-tier purchasing.
- Drone Imaging:Mass minimization and gimbal compatibility enable aerial cinematography with stabilized telephoto perspectives. FAA operational waivers for beyond-visual-line-of-sight flights are expanding commercial deployment scope.
Highest revenue concentration: Wildlife Photography. Steepest expansion trajectory: Drone Imaging.
End User:
Procurement sophistication varies from individual operator research to institutional tender processes with sustainability documentation requirements.
- Professional Photographers:Individual practitioners prioritize rendering character and build longevity with direct retail or authorized dealer relationships. EU Green Deal procurement criteria are consolidating sustainable supply chain documentation requirements.
- Broadcasting Agencies:National and regional networks operate centralized equipment pools with standardized mount systems and service contracts. German public broadcasters now mandate fluorite-based lens verification for new acquisitions.
- Security Firms:Corporate and government operators integrate telephoto optics with video management software and thermal fusion systems. Indian smart city initiatives in Mumbai and Hyderabad are expanding installation volumes.
- Scientific Researchers:Institutional laboratories specify diffraction-limited performance with calibration traceability for measurement applications. EMA chemical safety assessments govern coating chemistry selection for European research distribution.
- Cinematographers:Feature and documentary productions rent or lease premium cine-modified telephoto primes for specific project durations. ShareGrid and KitSplit platforms displace outright purchase in Los Angeles and Atlanta production communities.
Largest absolute spending: Broadcasting Agencies. Gaining share fastest: Cinematographers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changchun's precision glass-molding corridor shapes Chinese optical output for mid-market telephoto zooms, while Japanese fluorite cultivation facilities in Utsunomiya and Chinese synthetic crystal plants concentrate premium element supply. Demand clusters in Germany's broadcasting procurement networks, India's content production hubs, and Kenya's wildlife cinematography rental markets.
China
Surveillance infrastructure modernization and broadcasting equipment upgrades drive procurement volumes through state-directed procurement programs. MIIT's industrial standards for optical instrument quality govern domestic manufacturing certification. Changchun and Shenzhen optical houses deploy precision glass-molding presses for 70-200mm equivalent lenses, compressing price-performance ratios in the mid-market segment.
Germany
Public broadcasting agencies consolidate sustainable procurement criteria favoring fluorite-based lenses with verified supply chain documentation. EU Green Deal material mandates and REACH Annex XVII restrictions accelerate lead-glass phaseouts across distribution channels. Munich and Cologne production communities anchor rental-to-own platform adoption for independent cinematographers.
United States
Streaming platform documentary commissions expand rental fleet investment in super-telephoto optics for natural history production. FAA operational waivers for beyond-visual-line-of-sight drone flights enable commercial telephoto deployment in aerial cinematography. Los Angeles and Atlanta production communities demonstrate highest ShareGrid and KitSplit platform penetration for premium lens access.
India
Reliance and Disney+ Hotstar commissioning drives demand for broadcast telephoto zooms across Mumbai, Hyderabad, and Chennai production clusters. BIS optical equipment standards and PLI scheme incentives shape domestic assembly investments. Smart city surveillance initiatives in Mumbai and Hyderabad expand installation volumes for integrated telephoto optics.
Kenya
Wildlife cinematography production houses expand rental fleets for streaming platform natural history documentaries requiring dawn-dusk light capture capabilities. Kenya Bureau of Standards import regulations govern optical equipment quality certification. Maasai Mara and Amboseli production corridors concentrate super-telephoto prime deployment for seasonal shooting windows.
Optical Telephoto Lens Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material science capabilities and proprietary element cultivation. The vendor base stratifies between first-party manufacturers with captive fluorite supply, third-party optical houses with precision molding scale, and specialty coating facilities with ISO 10110 certification. Two dominant competitive moves are reshaping positioning: backward integration into synthetic crystal cultivation and geographic diversification of coating supply to satisfy EU chemical safety mandates.
Within the premium-tier vector, Canon exemplifies in-house fluorite crystal cultivation capabilities that insulate product lines from rare-earth supply volatility. Nikon occupies a position anchored by proprietary vibration reduction system integration across professional sports imaging applications. Sigma represents aggressive third-party competition through Art-series optics that match resolving power at reduced price points. These three manufacturers collectively illustrate the archetype segmentation between vertically integrated material control, differentiated stabilization technology, and value-engineered optical performance.
| Leading Market Players |
|---|
| Canon |
| Nikon |
| Sony |
| Fujifilm |
| Panasonic |
| Olympus |
| Tamron |
| Sigma |
| Tokina |
| Others |
Pricing and Supply Chain Analysis
Backward integration into synthetic fluorite cultivation anchors premium-tier pricing power for Japanese manufacturers while mid-tier competitors face margin compression from precision glass-molding scale in Changchun and Shenzhen. REACH-mandated lead-glass phaseouts and EU Green Deal procurement criteria are restructuring European buyer-seller negotiations around verified supply chain documentation rather than unit cost alone.
Pricing Analysis
Resolution-per-kilogram value anchors pricing stratification across professional wildlife, broadcast, and enthusiast segments. Premium-mid-economy pricing differentiation separates fluorite-element primes with Canon and Nikon branding from molded-asphere zooms by third-party optical houses. Cost compression in the mid-market intensifies because Chinese glass-molding presses achieve λ/20 wavefront accuracy at volumes impossible with traditional grinding. Rental houses and independent cinematographers demonstrate highest price sensitivity, while scientific research institutions prioritize optical performance over procurement cost.
Supply Chain Analysis
Dual-sourcing requirements for REACH-compliant coating chemistry are forcing German and Italian lens importers to qualify secondary Japanese and Taiwanese facilities with pre-certified environmental management systems. High-purity synthetic fluorite concentrates in Japanese and Chinese cultivation plants, while precision glass-molding equipment clusters in Changchun and Shenzhen. Single-source vulnerability for European and North American assemblers stems from concentrated fluorite geography. Distribution runs through authorized dealer networks for professional tiers and direct e-commerce for enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision glass-molding technology is displacing traditional grinding across mid-market zoom construction, compressing first-party premium positioning and opening white-space for computational-optical convergence in travel photography segments.
For Market Incumbents: Anchor professional-tier dominance through captive fluorite supply expansion and proprietary image stabilization R&D roadmaps. Defend against molded-asphere price erosion by accelerating lanthanum-doped glass qualification ahead of REACH Annex XVII enforcement timelines. Deepen rental house partnerships in Los Angeles and Atlanta to lock in seasonal demand visibility.
For New Entrants and Emerging Players: Content creators operating under drone weight restrictions represent the most penetrable buyer archetype for compact telephoto designs with diffractive element integration. Target Indian production clusters in Mumbai and Hyderabad with broadcast zoom offerings priced below first-party equivalents. Pursue ShareGrid and KitSplit platform listing agreements as primary go-to-market channel.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty coating facilities with ISO 10110 certification and six-month qualification track records. Long-term viability hinges on material science capabilities rather than assembly scale. Watch for ECHA substance evaluations classifying additional high-refractive index components as substances of very high concern as the inflection indicator for coating chemistry restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorite Supply Security Program | Canon and Nikon in-house cultivation insulates premium lines from rare-earth export licensing fluctuations. |
| Precision Glass-Molding Scale-Up | Changchun optical houses compress mid-market pricing through λ/20 wavefront accuracy at volume production. |
| REACH-Compliant Coating Qualification | Japanese and Taiwanese facilities with pre-certified EMS capture European import demand from lead-glass phaseouts. |
| Rental Platform Partnership Expansion | ShareGrid and KitSplit penetration in Los Angeles and Atlanta displaces outright purchase for independent cinematographers. |
| Computational-Optical Convergence R&D | Multi-frame sharpening algorithms reduce absolute resolving power requirements for travel photography segments. |
Research Methodology
Trade publications, customs databases, and equipment rental platform disclosures formed the secondary backbone, supplemented by primary interviews with optical design engineers, procurement leads at European broadcasting agencies, coating facility technical directors, and wildlife cinematography rental house operators. Bottom-up triangulation across product-level bill-of-materials and top-down validation through end-user spending pattern analysis ensured cross-verification of volume and value estimates.
Historical trendline analysis across shipment volumes, average selling prices, and technology adoption curves informed the projection framework. Segmentation modeling incorporated product type, element technology, application environment, and end-user procurement sophistication across the analysis window. CAGRs derived from curve-fitting across technology diffusion patterns and replacement cycle dynamics, with specific inputs from fluorite supply concentration metrics and REACH regulatory implementation timelines.
Revisions become necessary when rare-earth export licensing regimes tighten, ECHA substance evaluations expand SVHC classifications, or precision glass-molding technology diffusion accelerates beyond modeled adoption curves. Deviation in fluorite supply geography or coating chemistry qualification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.