
 Magnetic Absorption Data Line Market | 2026-2036
Magnetic Absorption Data Line Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Absorption Data Line Market Insights
Aftermarket service revenue for magnetic absorption data line calibration and shielding performance verification is fragmenting across regional service networks. Samsung Electronics leverages its semiconductor fabrication ecosystem to sustain captive demand for precision shielding components. Huawei anchors domestic procurement through in-house production of magnetoresistive transmission modules for telecom infrastructure.
Magnetic absorption data lines are engineered transmission media that integrate ferromagnetic or ferrite-composite layers—typically operating at permeability values exceeding 1,000 µH/m—to attenuate electromagnetic interference while preserving signal integrity in high-frequency applications. These lines serve critical shielding and filtering functions in environments where crosstalk suppression determines system reliability. Digital lines dominate current procurement volumes across data center buildouts, while fiber optic lines represent the fastest-growing category as hyperscale operators deploy magnetically shielded optical backbones. Magnetoresistive technology occupies the premium tier in sensing-integrated applications, whereas Hall Effect variants compete on cost in standard industrial deployments.
FCC Part 15 emissions standards in the United States and the EU's RoHS and REACH frameworks constrain material composition and shielding effectiveness thresholds, directly shaping supplier qualification requirements and product redesign cycles. China's SAMR enforces GB standards for electromagnetic compatibility that domestic and foreign manufacturers must satisfy for market access. Stakeholders must monitor evolving regulatory divergence between jurisdictions to determine whether centralized or regionalized certification strategies minimize compliance drag.
Market Dynamics
Data center electromagnetic shielding requirements are intensifying as server rack densities climb past 50kW per cabinet, forcing procurement teams to specify ferrite-composite data lines with permeability ratings exceeding 1,000 µH/m to maintain signal integrity under extreme interference loads.
Growth Catalysts
- Dual carbon compliance mandates:China's GB standards and SAMR enforcement are compelling domestic manufacturers to reformulate ferrite composites with reduced rare-earth content while maintaining shielding thresholds, opening procurement channels for certified suppliers.
- Hyperscale data center buildouts:Cloud infrastructure operators in East Asian manufacturing clusters are specifying magnetically shielded optical backbones for AI training clusters, creating sustained volume demand for fiber optic absorption lines.
- Magnetoresistive sensing integration:Telecom infrastructure deployments are embedding magnetoresistive transmission modules for real-time interference monitoring, expanding the addressable market beyond passive shielding into active signal conditioning.
Market Restraints
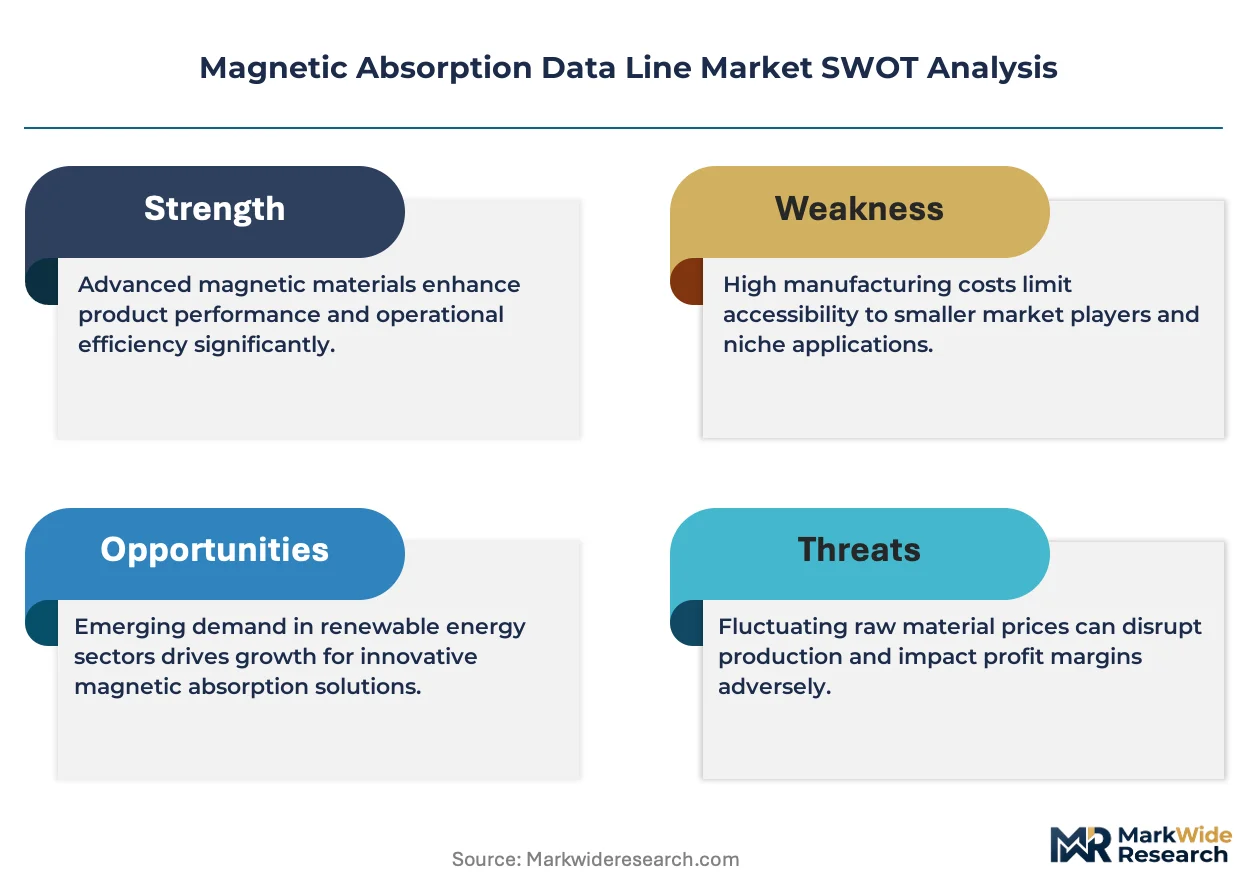
- Rare-earth price volatility:Neodymium and ferrite powder inputs face supply concentration risk from Chinese mining and processing operations, compressing margins for non-vertically integrated cable assemblers.
- REACH material restrictions:EU ECHA substance screening is disqualifying legacy ferrite binders containing restricted phthalates, forcing costly reformulation cycles for European market access.
- Copper substitution pressure:Unshielded twisted-pair Category 8 cabling is capturing low-sensitivity enterprise networking applications where electromagnetic environments remain controlled.
Strategic Opportunities
- South Korean semiconductor ecosystem:Memory and logic foundry expansions near Pyeongtaek and Yongin are generating captive demand for precision shielding components in probe card and test socket applications.
- Automotive ethernet penetration:In-vehicle networking standards are mandating magnetic absorption for 10Gbps+ links in electric powertrain control modules, opening a greenfield application vertical.
- Japan METI green procurement:Public infrastructure projects are prioritizing low-carbon ferrite formulations, creating preferential purchasing pathways for suppliers with verified lifecycle assessments.
Industry Challenges
- Permeability testing talent scarcity:Qualified technicians capable of operating vector network analyzers for shielding effectiveness validation are concentrated in legacy RF engineering hubs, constraining quality assurance scaling.
- Multi-jurisdiction certification lag:Simultaneous FCC Part 15, EU CE marking, and China GB compliance testing extends product launch timelines by 8-14 months for unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Absorption Data Line Market |
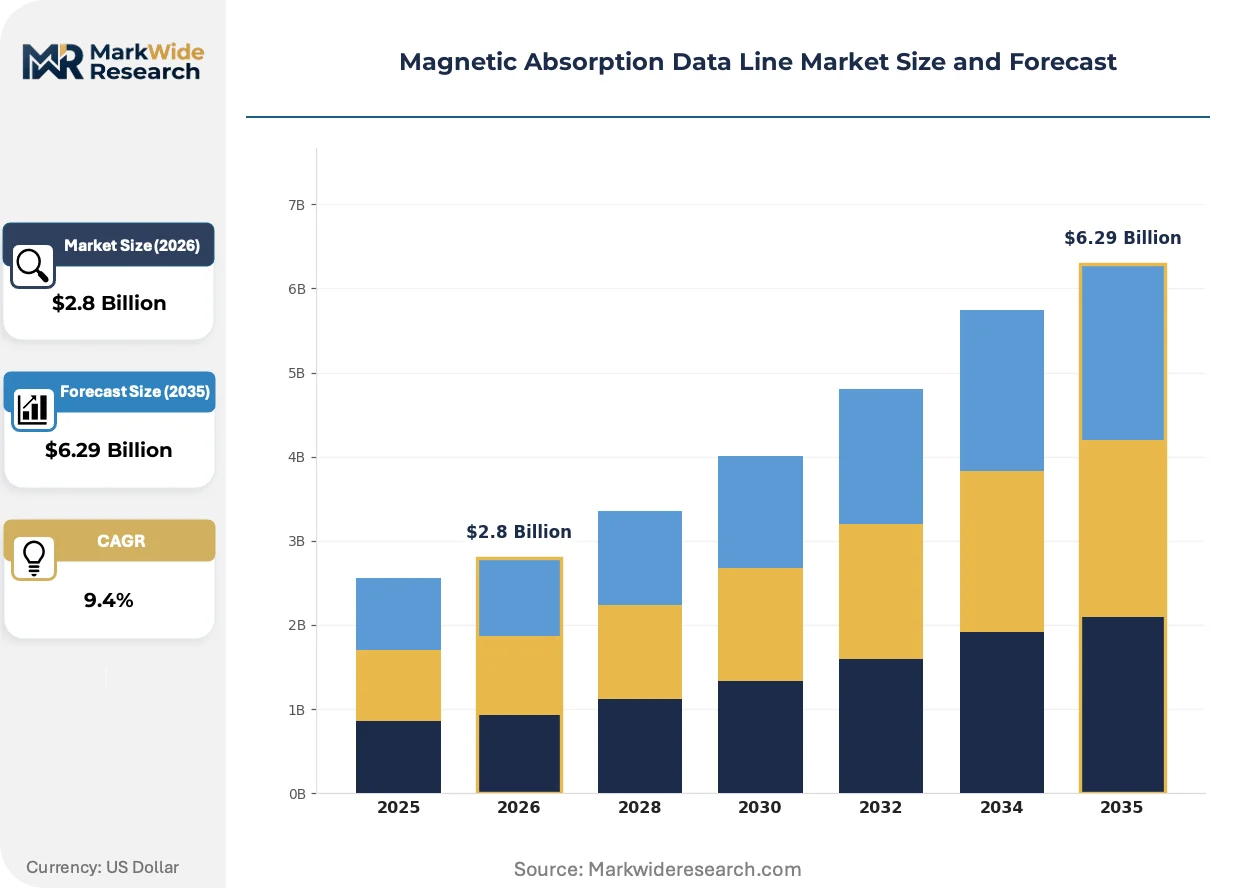
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Lines, Digital Lines, Fiber Optic Lines, Coaxial Lines, Twisted Pair Cables Technology: Magnetoresistive, Hall Effect, Fluxgate, Magnetoimpedance, Anisotropic Magnetoresistance Application: Data Transmission, Signal Filtering, Electromagnetic Shielding, Magnetic Sensing, Noise Reduction End User: Telecommunication Providers, Network Infrastructure Firms, Electronic Manufacturers, Data Centers |
| Companies Covered | OPPO, Xiaomi, ifanr, Dudado, Huawei, Samsung Electronics, Anker Innovations, UGREEN, Baseus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Absorption Data Line Market Trends and Innovations
Material science advances and procurement model evolution are compressing product lifecycles while elevating performance thresholds. Shielding effectiveness verification is migrating from batch sampling to 100% automated testing, and supplier qualification criteria are tightening around carbon footprint transparency.
Nano-crystalline ferrite composites are migrating from aerospace and defense procurement into commercial data center specifications. Hyperscale operators in Singapore and Frankfurt are piloting these materials for 400Gbps optical backbones where conventional ferrite layers exhibit saturation at elevated temperatures. The technology is migrating from premium-tier magnetoresistive applications into standard digital line deployments, compressing the historical performance gap between sensing-integrated and passive shielding categories.
China's SAMR is accelerating GB standard revisions for electromagnetic compatibility in telecommunications infrastructure, with draft specifications requiring enhanced shielding effectiveness above 3GHz for 5G-Advanced deployments. Domestic manufacturers are pre-qualifying reformulated ferrite composites to secure State Grid and China Mobile procurement contracts. Foreign suppliers face compressed certification windows as mandatory compliance dates advance, forcing accelerated in-country testing partnerships.
Buying patterns among data center operators are fragmenting from consolidated national tenders toward direct engagement with specialized shielding component vendors. Procurement teams in Northern Virginia and Amsterdam are unbundling cable assembly from system integration contracts, creating direct sales channels for ferrite-core suppliers with validated test data. This disintermediation is most pronounced in AI cluster deployments where thermal and electromagnetic specifications exceed standard product catalogs, forcing custom engineering relationships.
Magnetic Absorption Data Line Market Segmentation
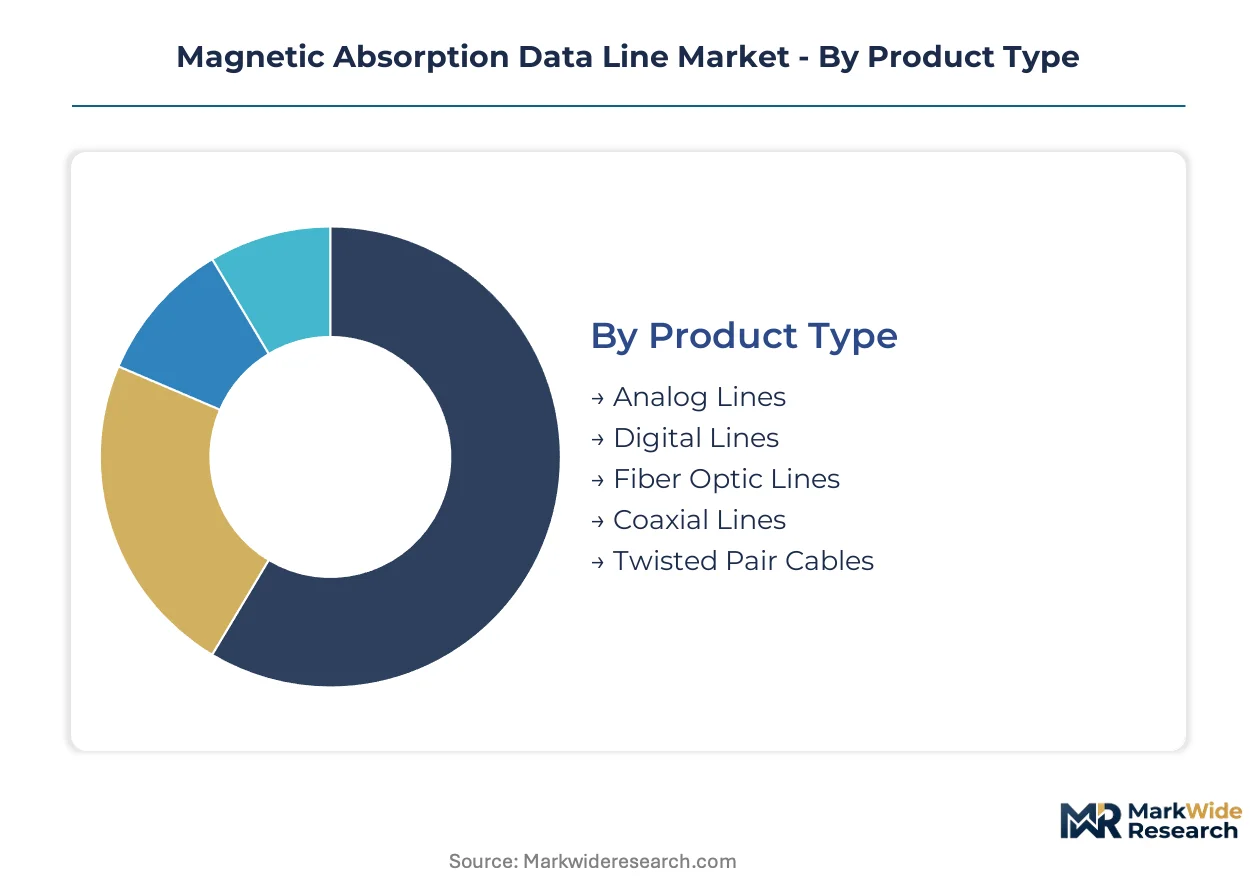
Segmentation in the magnetic absorption data line market reveals how procurement teams prioritize shielding performance against cost constraints across divergent deployment environments. Understanding these category boundaries enables suppliers to align ferrite composite formulations with specific electromagnetic interference thresholds and signal integrity requirements.
Product Type:
Use-case spectrum spans legacy analog infrastructure through hyperscale optical backbones, with each format demanding distinct permeability specifications and thermal tolerances.
- Digital Lines:Ferrite-composite shielding layers rated above 1,000 µH/m dominate data center rack-to-rack connections where server densities exceed 50kW per cabinet. Procurement volumes concentrate in East Asian manufacturing clusters serving cloud infrastructure operators.
- Fiber Optic Lines:Magnetically shielded optical backbones integrate nano-crystalline ferrite composites for 400Gbps+ AI training clusters. Singapore and Frankfurt hyperscale pilots are validating these materials against temperature saturation limits.
- Analog Lines:Legacy instrumentation and industrial control systems in mature manufacturing bases sustain residual demand for standard ferrite shielding.
- Coaxial Lines:RF transmission applications in broadcast and defense infrastructure specify precision impedance-matched ferrite layers.
- Twisted Pair Cables:Enterprise networking deployments balance cost against controlled electromagnetic environments where unshielded alternatives compete aggressively.
The dominant share belongs to Digital Lines, while Fiber Optic Lines are closing the gap fastest.
Technology:
Cost tier stratification separates premium sensing-integrated modules from commodity passive shielding, with magnetoresistive variants commanding substantial price premiums for real-time interference monitoring capabilities.
- Magnetoresistive:Telecom infrastructure embeds these transmission modules for active signal conditioning and real-time electromagnetic interference detection. Huawei produces these in-house for domestic 5G-Advanced deployments, while Samsung Electronics sustains captive demand through semiconductor fabrication ecosystems.
- Hall Effect:Standard industrial deployments favor this cost-optimized technology where basic shielding suffices without integrated sensing. Manufacturing automation and automotive ethernet penetration in electric powertrain modules drive volume procurement.
- Fluxgate:Precision measurement applications in aerospace and geophysical instrumentation specify these high-sensitivity variants.
- Magnetoimpedance:Emerging thin-film implementations target miniaturized consumer electronics with severe space constraints.
- Anisotropic Magnetoresistance:Niche positioning in angular position sensing and rotational encoders for industrial robotics.
Magnetoresistive technology captures the premium tier by margin, though Hall Effect variants ship the highest unit volumes.
Application:
Volume concentration tracks data center buildout intensity, with electromagnetic shielding and signal filtering absorbing the majority of ferrite composite output as AI cluster deployments accelerate.
- Electromagnetic Shielding:Server rack densities past 50kW per cabinet force specification of high-permeability ferrite composites. China's State Grid and China Mobile procurement contracts are pre-qualifying reformulated materials for 5G-Advanced infrastructure.
- Data Transmission:Optical backbone deployments for AI training clusters in Northern Virginia and Amsterdam data centers are unbundling cable assembly from system integration contracts, creating direct sales channels for component vendors.
- Signal Filtering:Base station and telecom infrastructure deployments specify these applications for harmonic suppression in dense RF environments.
- Magnetic Sensing:Industrial automation and automotive powertrain control modules integrate these functions for position and current monitoring.
- Noise Reduction:Audio-visual and medical imaging equipment manufacturers specify these for sensitive analog signal paths.
Electromagnetic Shielding commands procurement priority, while Data Transmission applications are expanding most quickly.
End User:
Customer type determines certification burden and contract structure, with data center operators fragmenting buying patterns toward direct component engagement while telecom providers sustain consolidated national tenders.
- Data Centers:Hyperscale operators in Singapore, Frankfurt, and Northern Virginia specify custom thermal and electromagnetic performance exceeding standard catalogs. These buyers validate suppliers through 100% automated shielding effectiveness testing rather than batch sampling.
- Telecommunication Providers:China Mobile and comparable carriers enforce GB standard compliance through SAMR-mandated electromagnetic compatibility thresholds. Procurement consolidates through state-directed tenders with compressed certification windows for foreign suppliers.
- Network Infrastructure Firms:System integrators serving enterprise and mid-market deployments balance performance against total installed cost.
- Electronic Manufacturers:Consumer and industrial OEMs specify magnetic absorption for internal subsystem integration with varying shielding stringency.
Data Centers drive the steepest specification escalation, while Telecommunication Providers anchor baseline volume commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and South Korea exhibit the least price sensitivity for high-permeability ferrite composites, while procurement teams in Germany and the United States negotiate aggressively on total installed cost for standard shielding specifications. This demand-elasticity divide separates premium-tier magnetoresistive applications from commodity Hall Effect deployments.
China
State Grid and China Mobile procurement contracts are pre-qualifying reformulated ferrite composites with reduced rare-earth content for 5G-Advanced infrastructure. SAMR enforces GB standard revisions requiring enhanced shielding effectiveness above 3GHz, compressing certification windows for foreign suppliers. Manufacturing clusters in Shenzhen and Dongguan are scaling nano-crystalline ferrite output for hyperscale data center specifications.
South Korea
Memory and logic foundry expansions near Pyeongtaek and Yongin are generating captive demand for precision shielding components in probe card applications. The country's national telecommunications regulator enforces electromagnetic compatibility thresholds that align with global hyperscale operator specifications. Samsung Electronics anchors domestic procurement through in-house production of magnetoresistive transmission modules for semiconductor fabrication ecosystems.
Japan
METI green procurement guidelines for public infrastructure projects are prioritizing low-carbon ferrite formulations with verified lifecycle assessments. Industrial automation and automotive ethernet penetration in electric powertrain modules drive volume procurement for Hall Effect shielding. Manufacturing concentration in the Nagoya and Osaka corridors sustains demand for precision impedance-matched ferrite layers in RF transmission applications.
United States
FCC Part 15 emissions standards constrain material composition and shielding effectiveness thresholds for data center buildouts in Northern Virginia. Hyperscale operators are unbundling cable assembly from system integration contracts, creating direct sales channels for ferrite-core suppliers with validated test data. The country's environmental protection framework shapes supplier qualification requirements through substance screening protocols.
Germany
ECHA REACH material restrictions are disqualifying legacy ferrite binders containing restricted phthalates, forcing costly reformulation cycles for European market access. Industrial machinery and automotive OEMs in Bavaria and Baden-Württemberg specify magnetic absorption for 10Gbps+ in-vehicle networking links. Frankfurt hyperscale pilots are validating nano-crystalline ferrite composites for 400Gbps optical backbones against temperature saturation limits.
Magnetic Absorption Data Line Market Competitive Landscape
Capability concentration sits with integrated electronics conglomerates; scale advantage sits with specialized cable assembly houses. The market structure reflects a bifurcated competitive field where captive production ecosystems coexist with independent component vendors serving fragmented procurement channels. Three archetypes dominate: vertically integrated technology conglomerates, specialized connectivity accessory manufacturers, and contract fabrication specialists serving unbranded OEM demand. Competitive moves center on backward integration into ferrite composite formulation and accelerated in-country testing partnerships to compress multi-jurisdiction certification timelines.
Among Chinese technology conglomerates, Huawei and Xiaomi occupy positions representing the captive production archetype, with in-house magnetoresistive module fabrication insulating procurement from external supply volatility. Samsung Electronics exemplifies the vertically integrated Korean model, leveraging semiconductor fabrication ecosystems to sustain internal demand for precision shielding components. Anker Innovations sits within the specialized connectivity tier, representing independent vendors that compete on validated test data and direct engagement with hyperscale procurement teams unbundling cable assembly from system integration contracts.
| Leading Market Players |
|---|
| OPPO |
| Xiaomi |
| ifanr |
| Dudado |
| Huawei |
| Samsung Electronics |
| Anker Innovations |
| UGREEN |
| Baseus |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into ferrite composite pricing power, concentrating margin leverage with Chinese manufacturers who control rare-earth processing while forcing European assemblers to absorb logistics premiums or cede share to domestic competitors.
Pricing Analysis
Aftermarket calibration and shielding verification services generate disproportionate lifetime value relative to initial hardware sales. Three-tier pricing structure across premium magnetoresistive, standard Hall Effect, and economy-grade passive shielding reflects certification grade differentiation against volume scale. Cost compression in the Hall Effect tier is intensifying because copper substitution pressure from Category 8 cabling squeezes contract manufacturers serving price-sensitive enterprise networking buyers. Data center operators exhibit the least price sensitivity for nano-crystalline ferrite specifications exceeding 1,000 µH/m permeability, while mid-market network infrastructure firms negotiate aggressively on total installed cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for ferrite composite assemblers. Raw material concentration in China, South Korea, and Japan for neodymium, ferrite powder, and nano-crystalline substrates draws from mining and processing operations with limited geographic diversification. Single-source vulnerability around Chinese rare-earth separation facilities rests on state-controlled export licensing frameworks. Distribution runs through specialized cable assembly houses in East Asian manufacturing clusters serving hyperscale operators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic absorption data lines sit in early-cycle expansion as AI training cluster deployments accelerate specification escalation beyond legacy ferrite capabilities. Hyperscale operator procurement fragmentation creates direct vendor engagement opportunities previously locked behind system integrator contracts.
For Market Incumbents: Build certification moats through accelerated in-country testing partnerships that compress multi-jurisdiction compliance timelines. Deepen upstream control over nano-crystalline ferrite formulation to insulate margins from rare-earth price volatility. Samsung Electronics and Huawei demonstrate how captive magnetoresistive module production neutralizes supply concentration risk.
For New Entrants and Emerging Players: Establish a beachhead in automotive ethernet shielding for 10Gbps+ electric powertrain links where specification standards are still crystallizing. Japan METI green procurement pathways offer preferential access for suppliers with verified lifecycle assessments. Target direct engagement with Northern Virginia and Amsterdam data center operators who have unbundled cable assembly from system integration contracts.
For Investors and Strategic Acquirers: Specialized ferrite-core suppliers with validated vector network analyzer test data represent compelling acquisition targets as hyperscale procurement shifts toward component-level qualification. Long-term viability hinges on backward integration into ferrite composite formulation or exclusive partnerships with nano-crystalline material innovators. Watch for SAMR GB standard compliance deadlines as inflection indicators for foreign supplier displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Formulation | Captive supply of nano-crystalline composites insulates margins from Chinese rare-earth export licensing volatility. |
| In-Country Testing Partnership Expansion | Accelerated SAMR GB certification compresses 8-14 month multi-jurisdiction timelines for unified product platforms. |
| Automotive Ethernet Shielding Development | 10Gbps+ powertrain control specifications open greenfield vertical beyond saturated data center procurement. |
| 100% Automated Shielding Verification Deployment | Hyperscale operator qualification requirements displace batch sampling for AI cluster cable specifications. |
| Low-Carbon Ferrite Lifecycle Assessment Certification | Japan METI green procurement creates preferential purchasing pathways for verified carbon footprint transparency. |
Research Methodology
Cross-validation between primary interviews with data center procurement directors, ferrite composite plant managers, telecom infrastructure engineers, and aftermarket calibration technicians anchors the qualitative findings against secondary validation from FCC Part 15 filings, ECHA REACH substance registrations, SAMR GB standard drafts, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulates against top-down market sizing through trade flow analysis of ferrite powder and rare-earth concentrate shipments.
Calibration against historical permeability specification adoption curves and data center rack density trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, technology tier, application intensity, and end-user procurement structure. CAGRs derive from elasticity-adjusted volume projections against price evolution in nano-crystalline versus conventional ferrite composite tiers. Shielding effectiveness testing capacity constraints and multi-jurisdiction certification lag function as industry-specific forecast inputs.
Stress conditions across rare-earth price volatility bands, SAMR compliance timeline acceleration, and copper substitution penetration thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hyperscale buildout intensity and automotive ethernet standardization velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
MEMS Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
APAC Chemical Sensors Market