
 Fiber Optical Receivers Market | 2026-2036
Fiber Optical Receivers Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optical Receivers Market Foresight
Market Context with Strategic Players
Data center interconnect is rebalancing the Fiber Optical Receivers Market away from traditional telecom capex cycles. Broadcom Inc. leverages its merchant silicon position to dominate high-volume coherent DSP supply. Coherent Corporation anchors North American manufacturing through vertical integration of indium phosphide foundry operations. Sumitomo Electric Industries competes via captive supply of high-reliability components for submarine cable systems.
Technical Definition and Structural Segments
Fiber optical receivers convert modulated light signals into electrical signals using photodetectors such as InGaAs PIN diodes or avalanche photodiodes, with typical sensitivity thresholds measured in dBm for bit-error-rate performance. These devices enable high-speed data transmission across single-mode and multimode fiber infrastructure spanning metro, long-haul, and hyperscale data center networks. Coherent receivers command premium positioning due to DSP-enabled phase recovery, while silicon photonics technology is displacing discrete assemblies in volume 400G and 800G pluggable modules. Direct detection receivers retain cost advantages in short-reach data center links where power consumption and latency constraints favor simpler architectures.
Regulatory Frame and Forward-Looking Close
China's MIIT enforces GB standards for optical module energy efficiency, while the EU F-Gas Regulation restricts fluorinated greenhouse gases used in semiconductor etching processes for photonic chip fabrication. The US FCC and Japan's METI both mandate interoperability testing frameworks that shape product certification timelines and market access requirements. Stakeholders must monitor divergence between Chinese domestic standards and IEC frameworks to avoid redundant certification burdens.
Market Dynamics
Data center interconnect demand is compressing traditional telecom capex cycles into continuous refresh patterns, forcing coherent receiver architectures into volume production scales previously reserved for direct detection modules.
Growth Catalysts
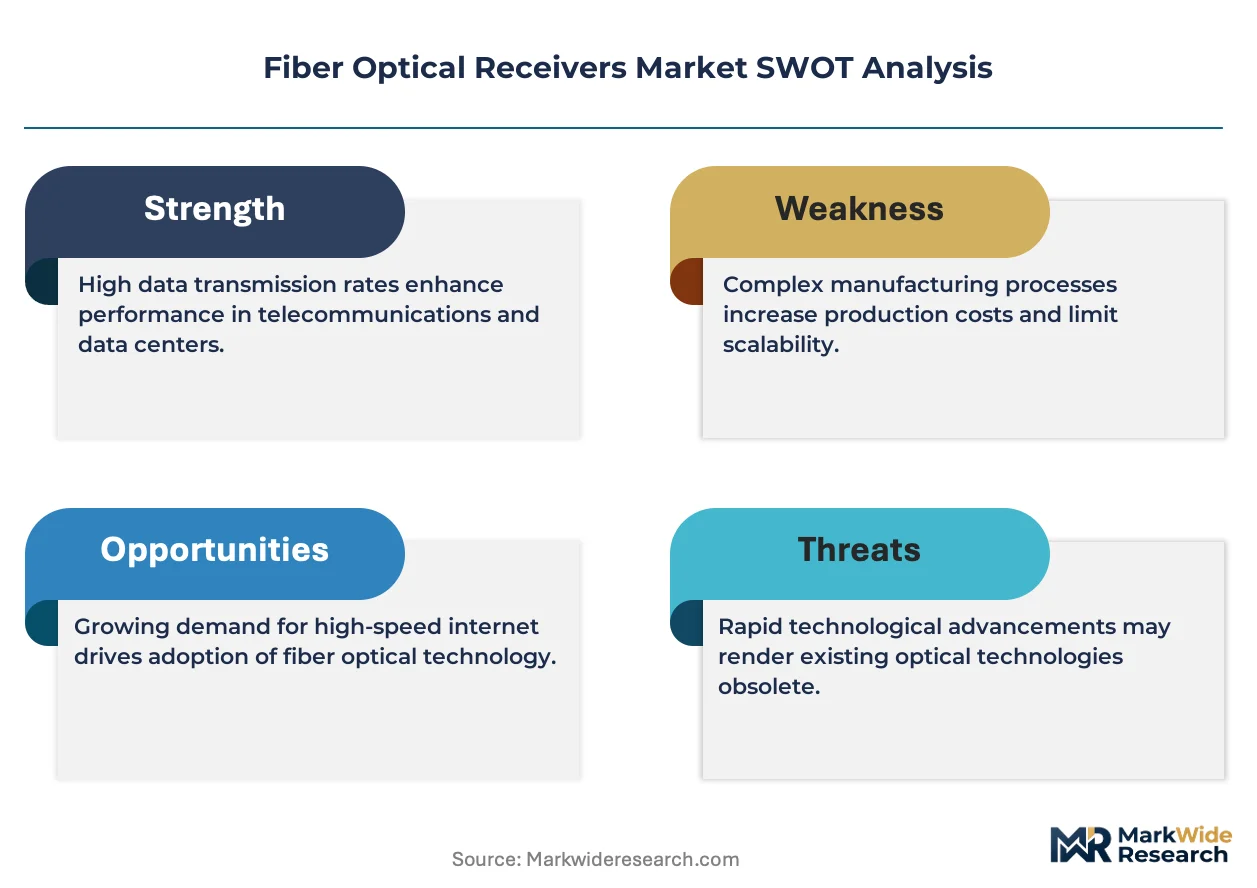
- Dual carbon mandates:China's MIIT efficiency standards for optical modules are accelerating replacement of legacy 100G infrastructure with lower-power coherent designs in state-owned carrier networks.
- Indium phosphide foundry concentration:East Asian manufacturing clusters around Shenzhen and Wuhan are achieving yield breakthroughs that reduce coherent DSP module costs for hyperscale buyers.
- Submarine cable renewal:Transoceanic system upgrades are pulling high-reliability avalanche photodiode receivers into multi-year procurement windows with dedicated qualification tracks.
Market Restraints
- Compound semiconductor supply:InP wafer availability remains concentrated among three merchant foundries, creating input cost volatility for coherent receiver IC fabrication.
- F-Gas regulatory friction:The EU F-Gas Regulation restricts fluorinated etching gases used in photonic chip manufacturing, extending fab qualification timelines for European-sourced components.
- Silicon photonics substitution:Integrated silicon photonics platforms are capturing short-reach data center links below 10km, compressing addressable market for discrete InGaAs PIN receiver assemblies.
Strategic Opportunities
- Coherent-lite architectures:Simplified DSP implementations for metro distances below 500km are opening mid-tier carrier segments previously priced out of coherent technology.
- India's BharatNet expansion:Rural fiberization mandates under the Department of Telecommunications are creating volume demand for cost-optimized direct detection receivers in temperature-hardened form factors.
- Open optical line systems:Disaggregation of transponder and line card procurement is enabling merchant receiver module suppliers to bypass traditional system vendor captive supply arrangements.
Industry Challenges
- Packaging engineering scarcity:Co-packaged optics design requires rare cross-functional expertise spanning high-speed electrical, thermal, and optical simulation, constraining module development velocity.
- Interoperability certification backlog:Japan's METI interoperability frameworks and the US FCC equipment authorization queues are extending product launch timelines by 6-12 months for multi-market introductions.
- Legacy SONET/SDH integration:Carrier networks with embedded TDM infrastructure require costly adaptation layers to interface with packet-optimized coherent receivers, complicating brownfield deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optical Receivers Market |
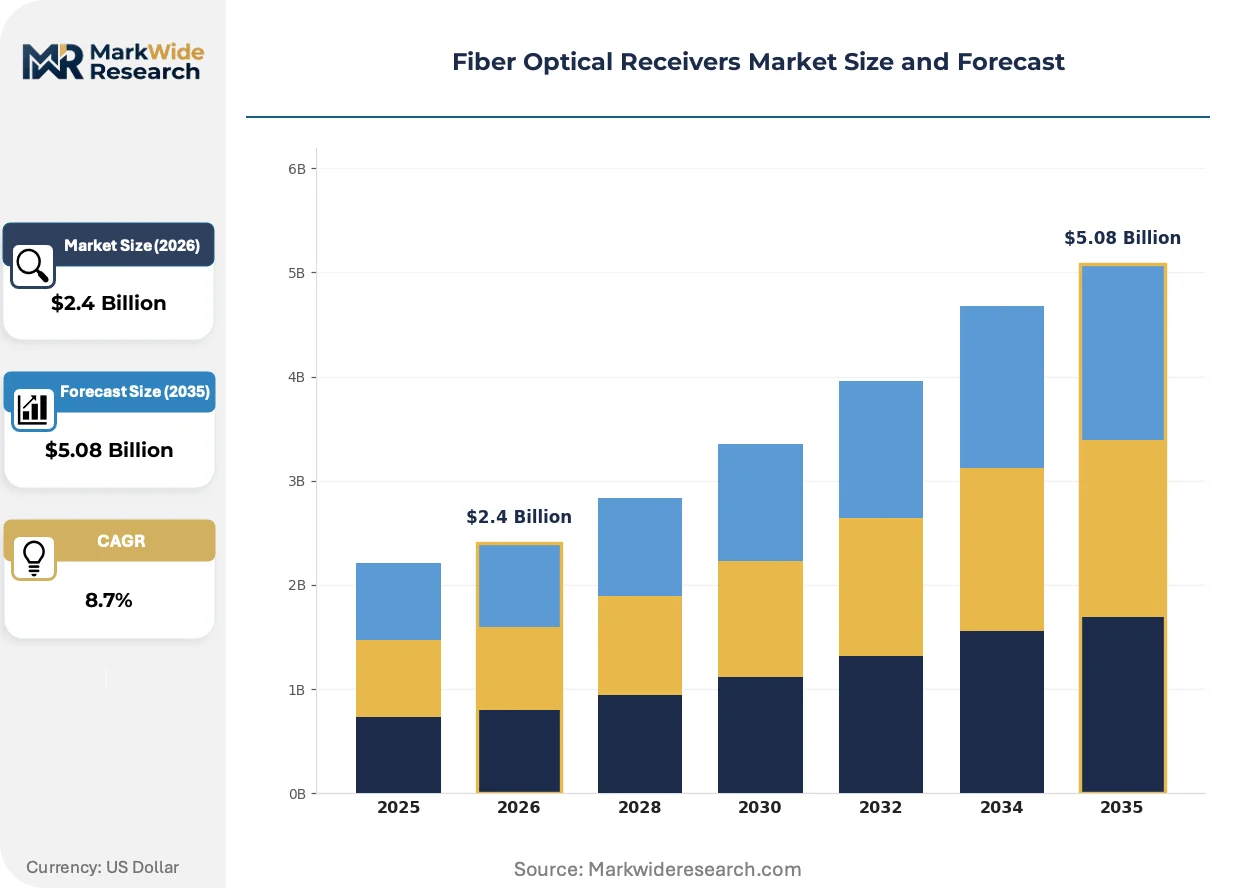
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Detection Receivers, Coherent Receivers, Analog Receivers, Digital Receivers Technology: Silicon Photonics, InGaAs, APD, CMOS End User: Telecommunications, Data Centers, Government, Aerospace Deployment: On-Premises, Cloud-Based, Hybrid, Distributed |
| Companies Covered | Broadcom Inc., Coherent Corporation, Lumentum Holdings Inc., Sumitomo Electric Industries, Accelink Technologies, Amphenol Corporation, EMCORE Corporation, Fujitsu Optical Components, Furukawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optical Receivers Market Shifts & Advancements
Silicon photonics integration is collapsing the traditional boundary between optical component and semiconductor manufacturing, while regulatory pressure on energy efficiency and fluorinated gas emissions is reshaping fabrication geography and process chemistry simultaneously.
Coherent digital signal processors with embedded machine learning-based impairment compensation are automating real-time link optimization previously requiring manual engineering intervention. Hyperscale cloud operators are deploying these DSPs across 400G and 800G pluggable modules at annual refresh cadences. This automation is compressing the performance gap between merchant silicon and custom ASIC implementations, eroding traditional vendor lock-in advantages.
The EU F-Gas Regulation is restricting perfluorinated compound use in semiconductor etching processes for InP and silicon photonics wafer fabrication. European-based foundries are retrofitting alternative chemistries with throughput penalties of 15-20 percent. North American and Asian fabs with grandfathered equipment or alternative process flows are capturing displaced European photonic component demand.
Hyperscale buyers are consolidating optical module procurement through direct contracts with merchant DSP and photonics suppliers, bypassing traditional system integrator channels. This channel disintermediation is most visible in the United States, where Amazon Web Services, Microsoft Azure, and Google Cloud now specify receiver performance requirements directly in multi-source agreements. Component suppliers are reconfiguring sales organizations around named account teams rather than distributor networks.
Fiber Optical Receivers Market Segmentation
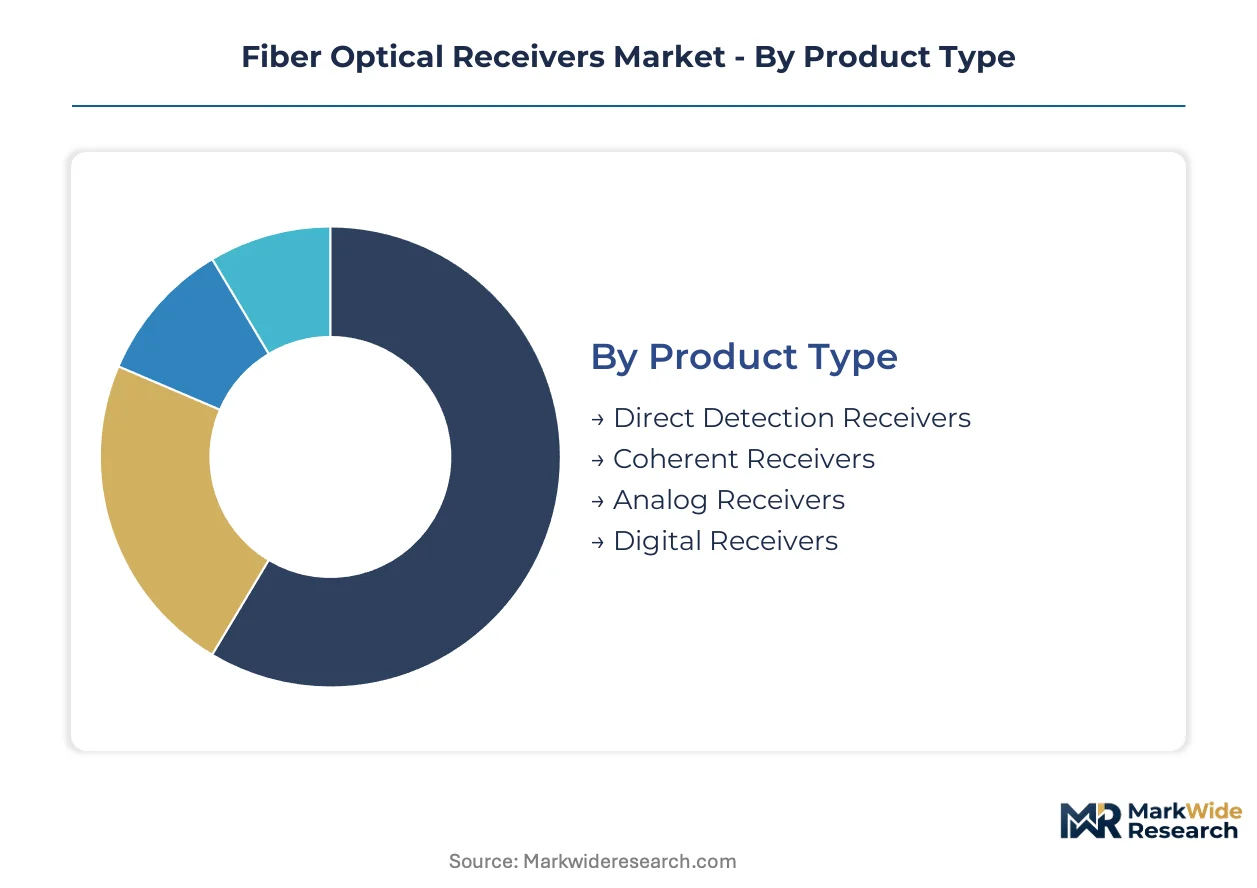
Segmentation in the Fiber Optical Receivers Market reflects divergent buyer priorities across power budgets, reach requirements, and procurement channels. Hyperscale operators prioritize silicon photonics integration and pluggable form factors, while submarine cable deployers demand hermetically sealed avalanche photodiode assemblies with decades-long reliability guarantees.
Product Type:
Buyers select receiver architectures based on link distance, power constraints, and DSP integration requirements, with cost-per-bit and thermal envelope driving final specification.
- Direct Detection Receivers:PIN photodiode-based designs convert optical intensity directly to electrical current without phase recovery, dominating intra-data center links below 10km. Amazon Web Services and Microsoft Azure specify these for spine-leaf architectures where latency budgets under 100 nanoseconds preclude coherent processing overhead. Direct detection leads on scale; coherent receivers lead on momentum.
- Coherent Receivers:DSP-enabled modules recover both phase and amplitude information through dual-polarization quadrature detection, enabling 800G transmission over 1000km+ spans. China's state-owned carriers under MIIT efficiency mandates are replacing legacy 100G direct detection with coherent designs in metro rings. Coherent modules command 4-6x unit premiums over direct detection equivalents.
- Analog Receivers:Linear response photodetectors without digitization stages serve radio-over-fiber and distributed antenna systems in 5G fronthaul.
- Digital Receivers:Integrated ADC and clock recovery circuits support PAM4 modulation in 400G/800G short-reach pluggables.
Direct detection dominates port volume; coherent designs capture value concentration in long-haul and submarine applications.
Technology:
Foundry process selection determines yield curves, thermal performance, and regulatory compliance across fluorinated gas restrictions.
- Silicon Photonics:CMOS-compatible waveguide integration collapses transmitter and receiver functions onto single dies, with Intel and Broadcom driving 800G DR8 volume production. Shenzhen-based packaging houses are achieving 50% cost reductions versus discrete assemblies through automated wafer-scale testing. Silicon photonics leads on manufacturing scale; InGaAs PIN retains wavelength flexibility advantages.
- InGaAs:Indium gallium arsenide PIN diodes deliver 900-1700nm spectral coverage with quantum efficiency exceeding 80%, essential for C-band and L-band dense wavelength division multiplexing. Wuhan manufacturing clusters supply these detectors for coherent receiver front-ends. InGaAs maintains process maturity; silicon photonics shows steepest expansion trajectory.
- APD:Avalanche photodiodes provide internal gain for weak signal detection in submarine cable repeaters and free-space optical links.
- CMOS:Standard CMOS photodetectors serve cost-optimized consumer and automotive LiDAR applications with relaxed sensitivity requirements.
Silicon photonics wins on integration density; InGaAs preserves performance margins in high-sensitivity applications.
End User:
Procurement patterns diverge between capex-driven infrastructure owners and opex-optimized cloud operators with continuous refresh cycles.
- Telecommunications:Incumbent carriers including Verizon and NTT operate multi-decade asset bases where coherent receiver upgrades must interoperate with legacy ROADM nodes and amplifier chains. India's BharatNet rural fiberization under the Department of Telecommunications is pulling volume demand for temperature-hardened direct detection modules. Telecom leads on installed base; data centers lead on refresh velocity.
- Data Centers:Hyperscale operators deploy 800G pluggable modules with 2-3 year depreciation schedules, bypassing traditional system vendor channels through direct DSP procurement. Google's custom optical switching fabrics specify receiver sensitivity thresholds in multi-source agreements. Data center procurement concentrates in the United States and China.
- Government:Defense and intelligence networks require ITAR-compliant supply chains with domestic wafer fabrication for classified transmission infrastructure.
- Aerospace:Satellite optical inter-satellite links demand radiation-hardened receivers with extreme thermal cycling tolerance.
Telecom dominates cumulative deployed volume; data centers dictate next-generation interface roadmaps.
Deployment:
Infrastructure ownership models shape receiver lifecycle management, sparing strategies, and interoperability testing burdens.
- On-Premises:Enterprise and carrier-owned facilities maintain captive sparing pools with 10-15 year receiver replacement timelines, favoring discrete component architectures with field-replaceable photodetector assemblies. Japan's METI interoperability frameworks extend qualification timelines for brownfield integrations.
- Cloud-Based:Hyperscale operators treat optical modules as consumables with automated failure detection and hot-swappable replacement, accepting higher failure rates for density gains. Cloud deployment concentrates receiver demand in Ashburn, Frankfurt, and Singapore metro areas.
- Hybrid:Split architectures with on-premises switching and cloud-managed control planes require dual qualification tracks for receiver hardware.
- Distributed:Edge computing nodes and 5G fronthaul deploy receivers in uncontrolled environments with extended temperature ranges.
Cloud-based deployment leads on module velocity; on-premises retains longest replacement cycles and qualification rigor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors global manufacturing for fiber optical receivers, with Wuhan and East Asian clusters supplying coherent DSP modules and InGaAs photodetectors to hyperscale buyers. China's dual carbon mandates and state-owned carrier procurement are compressing legacy infrastructure replacement cycles. India's rural fiberization and Japan's interoperability frameworks are reshaping regional demand patterns.
China
State-owned carriers under MIIT efficiency mandates are replacing legacy 100G direct detection with coherent receivers in metro rings. GB standards for optical module energy efficiency enforce strict power consumption ceilings on procurement. Shenzhen packaging houses achieve 50% cost reductions through automated wafer-scale testing of 800G pluggables.
United States
Hyperscale cloud operators deploy 800G modules with 2-3 year depreciation schedules, bypassing traditional system vendor channels. The FCC mandates interoperability testing frameworks that extend equipment authorization timelines. Ashburn and Silicon Valley data centers concentrate demand for merchant DSP and photonics supply.
Japan
NTT operates multi-decade asset bases where coherent upgrades must interoperate with legacy ROADM infrastructure. METI interoperability frameworks extend product qualification timelines by 6-12 months for multi-market introductions. Nagoya and Osaka manufacturing clusters supply high-reliability components for submarine cable systems.
India
The Department of Telecommunications' BharatNet rural fiberization mandates create volume demand for temperature-hardened direct detection receivers. TRAI spectrum allocation policies shape backhaul infrastructure investment cycles. Tamil Nadu and Karnataka manufacturing corridors are emerging as assembly hubs for cost-optimized optical modules.
Germany
Incumbent carriers operate brownfield networks requiring costly adaptation layers for packet-optimized coherent receiver integration. The EU F-Gas Regulation restricts fluorinated etching gases used in photonic chip fabrication, extending fab qualification timelines. Bavaria-based foundries are retrofitting alternative chemistries with throughput penalties.
Fiber Optical Receivers Market Competitive Landscape
Capacity expansion dominates the current landscape as East Asian foundries scale indium phosphide wafer output to meet hyperscale demand. The market structure consolidates around three tiers: merchant silicon suppliers with DSP dominance, vertically integrated photonics manufacturers with captive foundry operations, and specialized component vendors serving submarine and defense applications. Strategic archetypes include scale-driven DSP merchants, integration-focused photonics houses, and reliability-specialized niche suppliers. M&A activity and strategic partnerships are the dominant competitive moves as players secure compound semiconductor supply and packaging expertise.
Among merchant silicon suppliers, Broadcom Inc. and Coherent Corporation exemplify the DSP-centric archetype with upstream control over coherent receiver IC fabrication. Sumitomo Electric Industries occupies a position within the reliability-specialized tier, anchoring high-sensitivity component supply for transoceanic cable systems. These three entities represent the competitive spectrum from volume-driven hyperscale supply to mission-critical infrastructure deployment.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Coherent Corporation |
| Lumentum Holdings Inc. |
| Sumitomo Electric Industries |
| Accelink Technologies |
| Amphenol Corporation |
| EMCORE Corporation |
| Fujitsu Optical Components |
| Furukawa Electric |
| Others |
Supply & Pricing Matrix
Silicon photonics wafer-scale integration is collapsing assembly costs while concentrating photodetector supply among Shenzhen and Wuhan packaging houses. This manufacturing transition simultaneously compresses module pricing tiers and reinforces geographic supply dominance across East Asian foundry clusters.
Pricing Analysis
Input-cost pass-through from indium phosphide wafer pricing dominates coherent receiver module economics, with InP foundry concentration among three merchant suppliers amplifying cost volatility. Three-tier pricing structure across premium coherent DSP, standard direct detection, and economy analog receivers reflects certification grade and volume scale differentiation. Pricing pressure stems from hyperscale buyer consolidation through direct DSP procurement contracts. Data center operators exhibit highest price sensitivity through annual refresh cadences, while submarine cable deployers accept premium positioning for multi-decade reliability guarantees.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale cloud operators mandate multi-supplier qualification for 800G pluggable modules, forcing component vendors to maintain redundant DSP and photonics relationships. Manufacturing concentrates in China, Japan, and the United States, with InP wafer fabrication drawing from compound semiconductor foundries in Taiwan and Singapore. Critical dependencies include indium phosphide substrates, fluorinated etching gases, and hermetic packaging ceramics. Single-source vulnerability runs through concentrated InP foundry capacity. Distribution runs through direct multi-source agreements with named hyperscale accounts rather than traditional system vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by continuous data center interconnect refresh cycles that transcend traditional telecom capex volatility.
For Market Incumbents: Hedge against silicon photonics substitution by securing captive InP foundry capacity or multi-year wafer supply agreements with Taiwan-based compound semiconductor houses. Reinforce position through vertical integration into automated wafer-scale packaging operations in Shenzhen manufacturing corridors. Prioritize METI and FCC interoperability certification investment to defend against qualification timeline compression from merchant DSP suppliers. For New Entrants and Emerging Players: Merchant DSP distributors represent the most viable channel partner type for bypassing traditional system vendor lock-in. Target India's BharatNet rural fiberization for cost-optimized direct detection receiver supply, where temperature-hardened specifications and domestic assembly requirements favor specialized component vendors. Pursue open optical line system disaggregation as the primary go-to-market angle, positioning receiver modules for direct procurement by cloud-managed network operators. For Investors and Strategic Acquirers: Valuations sit cheapest among packaging-engineering-constrained module assemblers lacking coherent DSP silicon capabilities. The five-to-ten year viability window favors acquiring photonics packaging specialists with proven high-speed electrical-thermal-optical co-simulation expertise. Target acquisition archetype: East Asian packaging houses with automated wafer-scale testing infrastructure. Watch hyperscale cloud capex disclosure inflections as the primary demand signal.| Strategic Initiative | Industry Significance |
|---|---|
| Coherent DSP Merchant Supply Agreement | Secures volume allocation from Broadcom or Coherent Corporation for hyperscale 800G module production. |
| InP Foundry Capacity Expansion | Adds compound semiconductor wafer output to reduce input cost volatility for coherent receiver IC fabrication. |
| Silicon Photonics Packaging Scale-Up | Automates wafer-scale testing to capture 50% cost reductions in 800G pluggable module assembly. |
| Interoperability Certification Investment | Accelerates METI and FCC qualification timelines to compress multi-market product launch cycles. |
| Open Optical Line System Partnership | Disaggregates transponder procurement to bypass traditional system vendor captive supply arrangements. |
Research Methodology
Bottom-up data center and telecommunications operator modeling reconciled against top-down photonics component supply tracking forms the analytical core of this study. Primary interviews with optical module procurement executives, DSP platform engineers, carrier network planning officers, and packaging house operations directors combined with secondary validation from SEC filings, hyperscaler capex disclosures, and customs trade data. Triangulation between demand-side deployment tracking and supply-side foundry output monitoring ensures cross-verified volume and value estimates.
Historical trendline analysis across coherent and direct detection receiver shipments established baseline growth patterns, with projection modeling incorporating technology transition curves for silicon photonics adoption. Segmentation dimensions include receiver architecture type, foundry process technology, end-user procurement pattern, and geographic deployment concentration. CAGRs derive from fitted growth curves adjusted for regulatory mandate impacts and hyperscale refresh cycle acceleration. Industry-specific forecast inputs encompass MIIT efficiency standard compliance timelines and submarine cable renewal procurement windows.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to indium phosphide foundry capacity expansion and EU F-Gas Regulation process chemistry adaptation. Projections reflect assumptions regarding continuous data center interconnect demand and state-owned carrier replacement cycles under carbon efficiency mandates. Deviation in hyperscale cloud capex allocation or compound semiconductor supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Glass Scintillator Market
Optics
Photostimulation Lasers Market
Optics
Optical Liquid Level Sensor Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Global Fiber Optic Components Market
Optics
Global High Purity Quartz Glass Market
Optics
Anti Glare Film Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Picosecond Lasers Market
Optics
Optical Telescope Market
Optics
Global Enhanced Vision System Market
Optics
Collimating Lens Market
Optics
Global Optical Lens Market
Optics
Beam Combining Optics Market
Optics
Fiber Optic Development Tools Market
Optics
Polymeric Optical Fiber Market