
 Haptic Feedback Switch and Button Platforms Market | 2026-2036
Haptic Feedback Switch and Button Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Haptic Feedback Switch and Button Platforms Market Insights
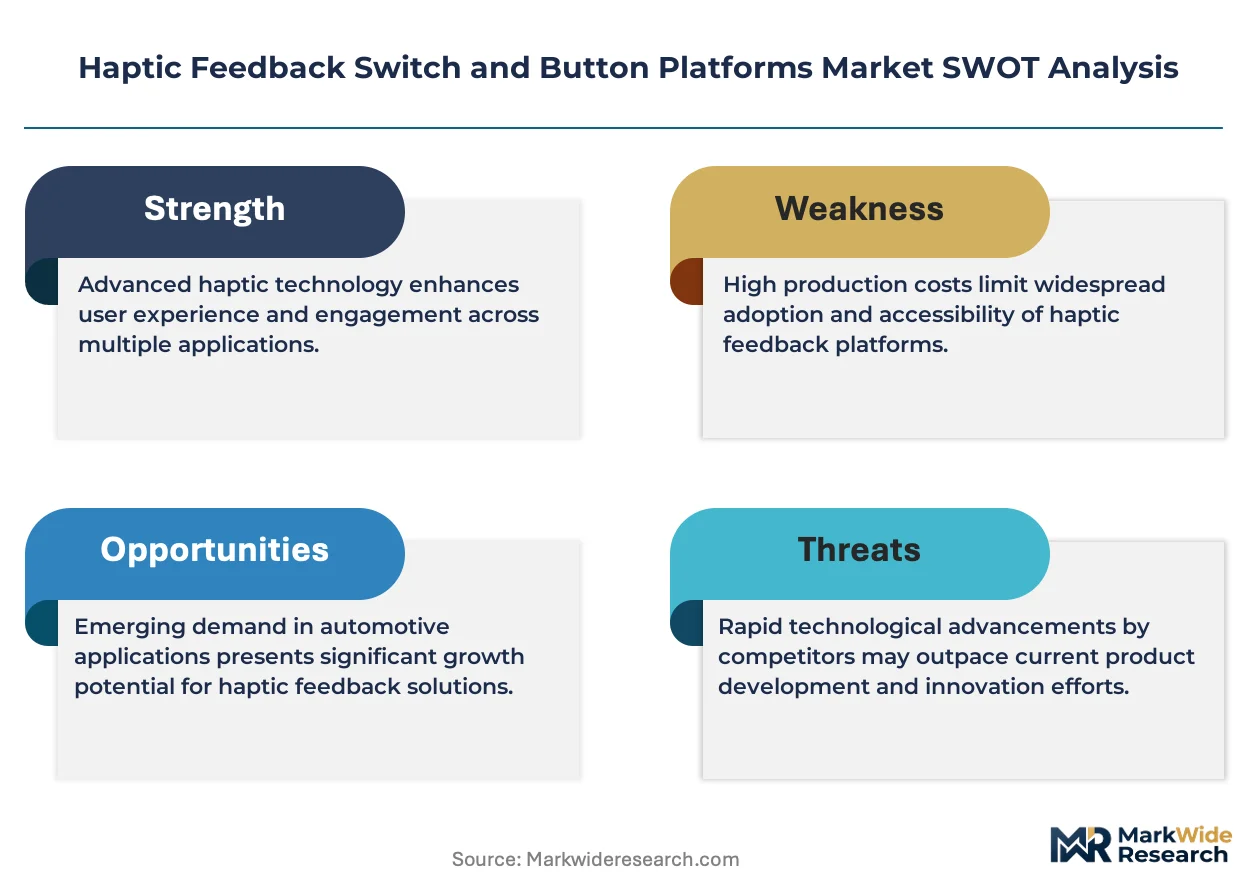
Asset-light leasing models for piezoelectric actuator production lines are reshaping competitive entry in haptic component supply. Continental AG leverages captive semiconductor partnerships to sustain vertical control over force-feedback controller ICs. Alps Alpine Co., Ltd. anchors its position through specialized manufacturing of ultra-thin mechanical switches for automotive steering interfaces. TDK Corporation differentiates via electromagnetic feedback modules that dominate premium gaming peripheral channels.
Haptic feedback switch and button platforms integrate electromechanical transducers, driver circuits, and tactile surface materials to generate programmable physical sensations in human-machine interfaces, typically operating at resonance frequencies between 100-300 Hz with response latencies under 10 milliseconds. Their primary commercial purpose spans vehicle cockpit controls, consumer electronics touch surfaces, and industrial operator panels where visual confirmation remains impractical. Capacitive buttons and piezoelectric switches capture expanding margin pools as automotive interior electrification eliminates traditional mechanical travel. Vibration feedback technology leads current volume shipments while force feedback architectures represent the fastest-growing segment due to gaming controller and premium automotive adoption curves.
FCC electromagnetic emissions standards in the United States, the EU's CE marking and RoHS substance restrictions, and China's GB national standards for electronic component safety collectively dictate haptic module certification pathways and material selection protocols. REACH chemical compliance specifically constrains piezoelectric ceramic formulations and solder alloys used in switch assemblies. Stakeholders must monitor evolving automotive functional safety standards and gaming hardware interoperability certifications as these frameworks increasingly determine market access velocity and product development roadmaps.
Market Dynamics
Automotive interior electrification is compressing mechanical switch procurement cycles as OEMs eliminate physical travel in center consoles and steering interfaces. This structural shift concentrates purchasing power among tier-one cockpit integrators who now specify haptic modules at the platform architecture stage rather than component sourcing phase.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated greenhouse gases are accelerating piezoelectric ceramic formulations that eliminate pneumatic actuation from climate control interfaces.
- Gaming peripheral OEMs:Force-feedback controller architectures are pulling electromagnetic linear resonant actuators into premium hardware at triple the attach rate of standard vibration motors.
- Yangtze River Delta cluster:Captive haptic actuator foundries operated by tier-one electronics suppliers are compressing prototyping cycles from months to weeks for consumer device brands.
Market Restraints
- Piezoelectric ceramic feedstock:Lead zirconate titanate supply concentrates among Japanese and Chinese specialty chemical processors, exposing module assemblers to raw material allocation risk.
- REACH substance restrictions:ECHA scrutiny of lead content in piezoelectric formulations is forcing reformulation investments that extend qualification timelines for European automotive certifications.
- Capacitive sensing substitution:Ultrasonic touch detection and radar-based gesture interfaces are capturing share in premium vehicle cockpits where haptic confirmation remains optional rather than mandatory.
Strategic Opportunities
- Medical device interfaces:Sterile haptic controls for surgical robotics and diagnostic equipment remain underpenetrated relative to automotive and consumer volumes, with FDA 510(k) pathways now clarifying for haptic-enabled Class II devices.
- India PLI scheme:Production-linked incentives for electronics manufacturing are drawing haptic module assembly into Gujarat and Tamil Nadu for domestic smartphone and automotive supply.
- Linear resonant actuator convergence:Integration of voice coil motors with pressure-sensitive resistive layers is enabling force-feedback touchpads that displace mechanical trackballs in industrial control panels.
Industry Challenges
- Multiphysics simulation talent:Electromechanical-acoustic modeling for haptic waveform optimization requires scarce expertise combining finite element analysis with psychophysics validation protocols.
- Automotive SPICE alignment:Functional safety documentation for haptic driver ICs must satisfy OEM-specific software process improvement capability determinations, extending certification cycles by 8-14 months.
- Legacy LIN bus integration:Steering wheel haptic modules must coexist with entrenched low-speed automotive networks, forcing bridge hardware that complicates real-time latency guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Haptic Feedback Switch and Button Platforms Market |
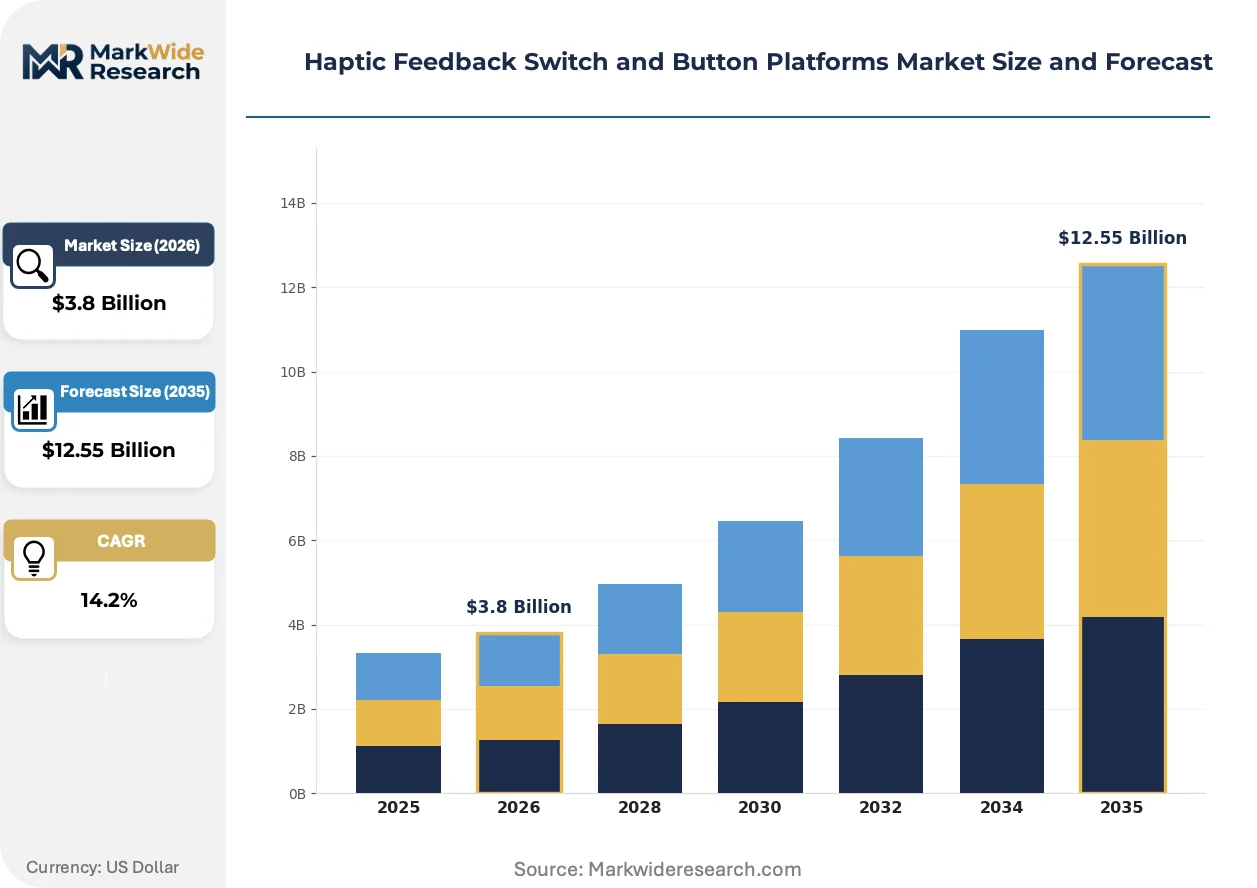
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Switches, Capacitive Buttons, Piezoelectric Switches, Optical Switches, Resistive Buttons Technology: Vibration Feedback, Force Feedback, Electrostatic Feedback, Electromagnetic Feedback, Ultrasonic Feedback Application: Consumer Electronics, Gaming Controllers, Automotive Controls, Industrial Equipment, Wearable Devices End User: OEM Manufacturers, Aftermarket Suppliers, Assembly Plants, Design Firms |
| Companies Covered | Continental AG, FORVIA, Marelli Holdings Co., Ltd., Alps Alpine Co., Ltd., TDK Corporation, Valeo SA, Visteon Corporation, Denso Corporation, Immersion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Haptic Feedback Switch and Button Platforms Market Trends and Innovations
Surface haptics is digitizing physical texture rendering through ultrasonic friction modulation, compressing the boundary between flat touchscreens and mechanical control surfaces. Three developments are restructuring competitive positioning and procurement patterns.
Ultrasonic transducer arrays operating at 28-40 kHz are digitizing local friction variation on glass and polymer surfaces, enabling programmable texture sensations without mechanical travel. Automotive cockpit designers at German and Japanese OEMs are adopting this technology for climate and media controls at prototyping volumes that tripled between 2022 and 2024. The technology is digitizing the economics of premium interior trim by eliminating tooling costs for physical button arrays while preserving tactile discoverability.
REACH authorization requirements for lead compounds are forcing ceramic suppliers to commercialize bismuth sodium titanate formulations that match PZT electromechanical coupling coefficients. ECHA's 2024 sunset date for uncontrolled lead usage in electronics is accelerating qualification programs at European piezoelectric material houses. Automotive safety-critical applications are most affected, with tier-one suppliers now dual-sourcing compliant ceramics from Japanese and Korean specialty manufacturers to secure supply continuity.
Asset-light leasing for surface-mount actuator production lines is fragmenting manufacturing ownership across contract electronics assemblers. Foxconn and Pegatron are deploying haptic module capacity on operational expenditure terms rather than capital ownership, compressing entry costs for mid-tier smartphone brands. This procurement model shift is most visible in Shenzhen and Dongguan, where captive tooling investments previously gated market access for regional device manufacturers.
Haptic Feedback Switch and Button Platforms Market Segmentation
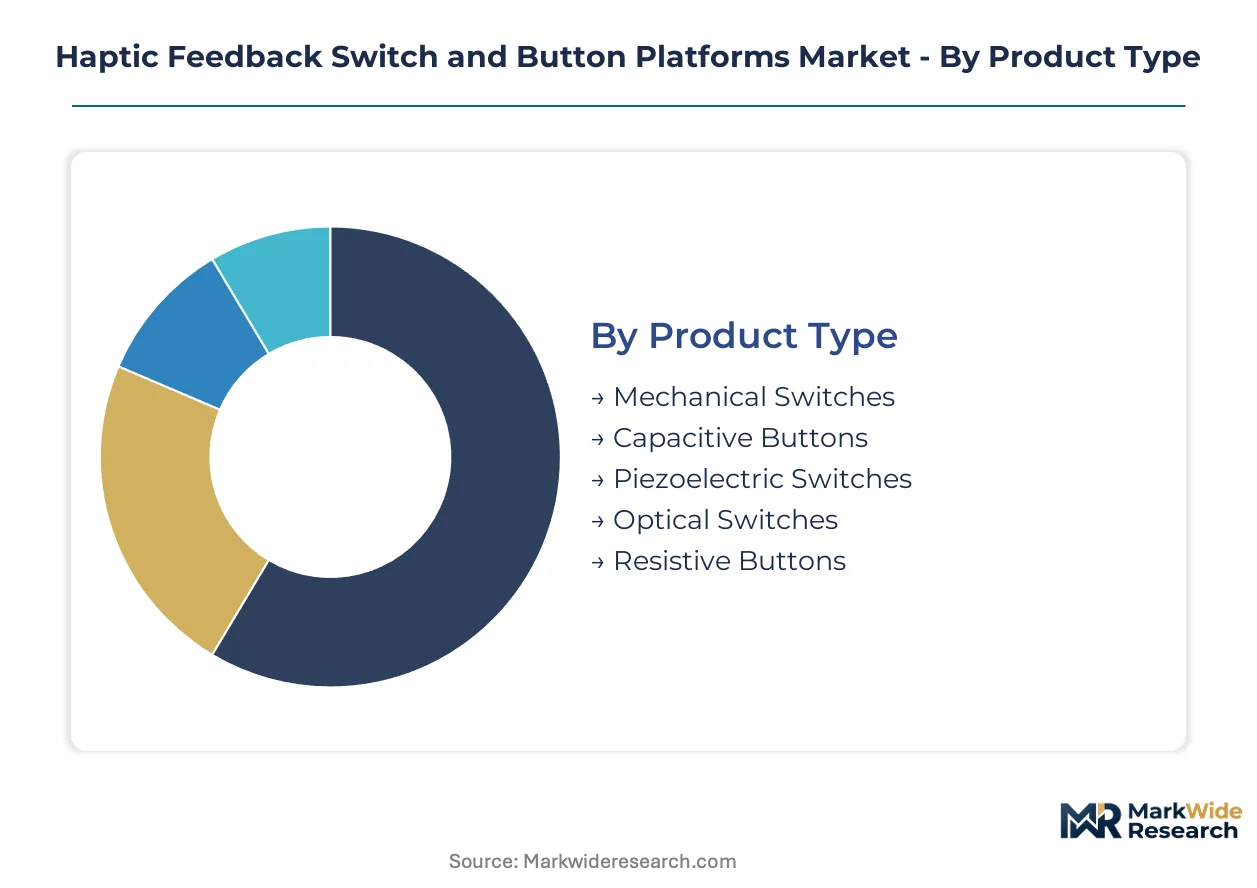
Haptic feedback switch and button platforms fragment across multiple technical and commercial dimensions. Product architecture, sensing modality, and end-use application each dictate distinct procurement patterns, certification requirements, and margin structures.
Product Type:
The use-case spectrum spans legacy mechanical travel to solid-state piezoelectric actuation, with each format commanding different tooling investments and qualification timelines.
- Mechanical Switches:Physical contact mechanisms with defined tactile travel remain entrenched in industrial control panels and cost-sensitive automotive trim levels. Demand concentrates in legacy industrial equipment retrofits across China's Pearl River Delta manufacturing belt, where replacement cycles extend equipment life without controller redesign.
- Capacitive Buttons:Field-effect sensing surfaces enable sealed, contaminant-resistant interfaces with programmable haptic confirmation. Automotive center consoles in Germany and Japan are absorbing capacitive modules at accelerated rates as OEMs eliminate physical button arrays for climate and media controls.
- Piezoelectric Switches:Ceramic transducer elements generate precise mechanical displacement under voltage excitation. REACH compliance pressures are forcing ceramic reformulation investments at European material suppliers.
- Optical Switches:Infrared beam interruption mechanisms deliver sub-millisecond response for gaming peripheral applications. Premium controller OEMs specify optical actuation for competitive esports hardware.
- Resistive Buttons:Pressure-sensitive conductive layers enable force-detecting interfaces at reduced component cost. Wearable device manufacturers in Shenzhen integrate resistive layers for fitness tracker side controls.
The dominant share belongs to mechanical switches, while capacitive buttons are closing the gap fastest.
Technology:
Cost tier separation distinguishes commodity vibration motors from precision force-feedback architectures requiring closed-loop control systems.
- Vibration Feedback:Eccentric rotating mass and linear resonant actuators deliver generalized rumble sensations through amplitude and frequency modulation. Consumer electronics volume shipments concentrate in smartphone and tablet applications where basic confirmation haptics suffice.
- Force Feedback:Voice coil motors and strain-gauge arrays recreate resistive forces and texture variation under fingertip pressure. Gaming controller OEMs are pulling force-feedback modules into premium hardware at substantially elevated attach rates versus standard vibration configurations.
- Electrostatic Feedback:Friction modulation through variable electrostatic attraction enables texture rendering on flat glass surfaces. Ultrasonic friction control systems are gaining prototyping traction in German automotive cockpit programs.
- Electromagnetic Feedback:Solenoid and voice coil architectures generate programmable resistive forces for steering wheel and pedal interfaces. TDK Corporation dominates premium gaming peripheral channels with proprietary electromagnetic module designs.
- Ultrasonic Feedback:High-frequency transducer arrays create localized surface vibration for programmable tactile sensation without mechanical travel. Surface haptics prototyping volumes tripled between recent measurement periods for climate and media control applications.
Vibration feedback commands current volume leadership, though force feedback demonstrates the steepest expansion trajectory among precision haptic modalities.
Application:
Volume concentration varies dramatically across customer segments, with automotive and consumer electronics representing opposing poles of qualification burden and shipment scale.
- Consumer Electronics:Smartphone, tablet, and laptop touch surfaces constitute the highest-unit application category. Yangtze River Delta electronics manufacturing clusters operate captive haptic actuator foundries that compress prototyping cycles from months to weeks for device brands.
- Gaming Controllers:Force-feedback triggers, adaptive triggers, and haptic trackpads command premium pricing in console and PC peripheral markets. Sony and Microsoft platform specifications are accelerating electromagnetic linear resonant actuator adoption.
- Automotive Controls:Center console, steering wheel, and door panel interfaces face stringent functional safety and environmental durability requirements. EU F-Gas Regulation compliance is accelerating piezoelectric ceramic formulations that eliminate pneumatic actuation from climate interfaces.
- Industrial Equipment:Operator panels and machine controls prioritize reliability and environmental sealing over sophisticated feedback waveforms. Food processing and pharmaceutical manufacturing specify IP-rated haptic interfaces for glove-compatible operation.
- Wearable Devices:Smartwatch and fitness tracker form factors constrain actuator size and power consumption. India PLI scheme incentives are drawing haptic module assembly into Gujarat and Tamil Nadu for domestic wearable supply.
Consumer electronics maintains volume dominance, yet automotive controls are expanding value contribution fastest through platform-level integration mandates.
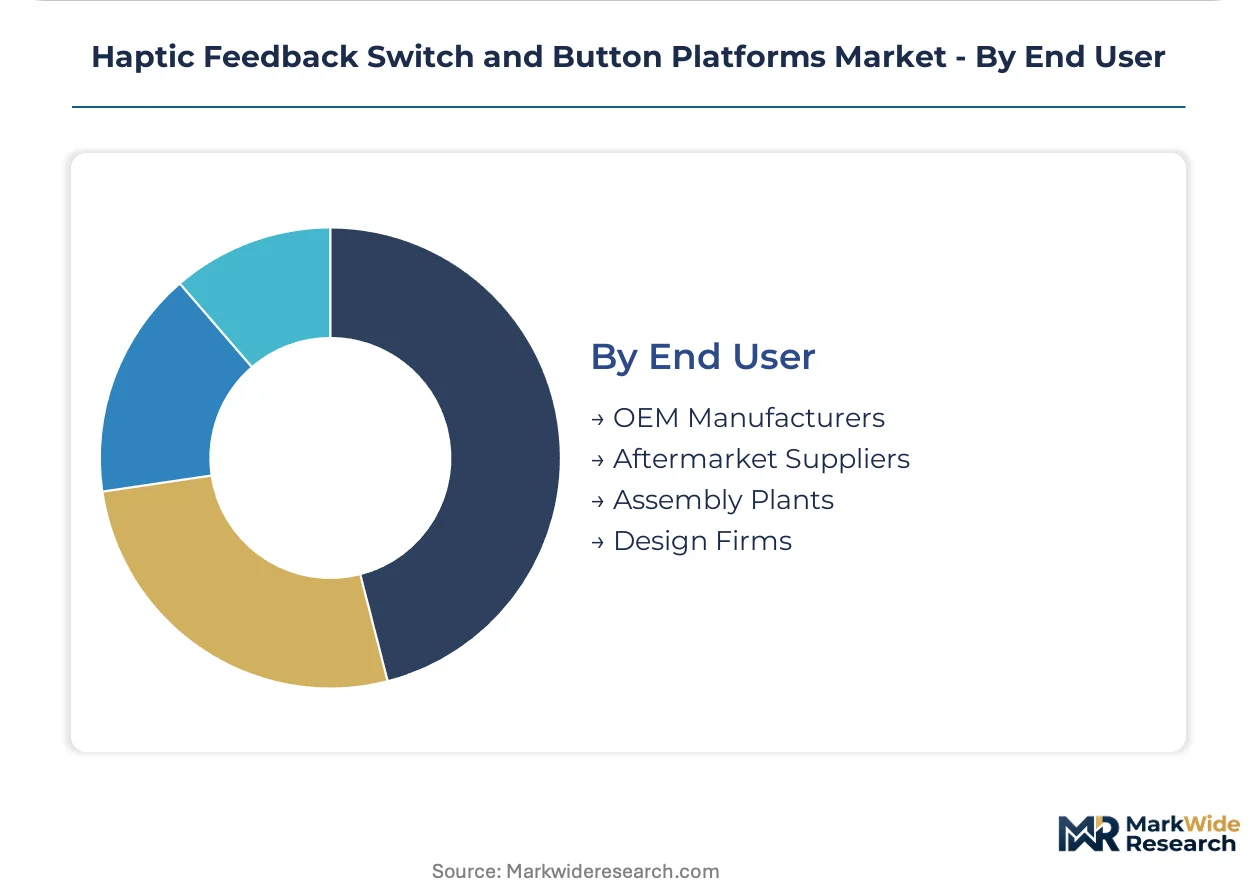
End User:
Customer type determines engagement model, with OEM specifications dictating multi-year platform commitments versus aftermarket spot purchasing.
- OEM Manufacturers:Original equipment builders specify haptic modules at vehicle platform or device architecture stage, locking in supply agreements spanning production lifecycles. Continental AG leverages captive semiconductor partnerships to sustain upstream control over force-feedback controller ICs.
- Aftermarket Suppliers:Replacement and upgrade channels serve repair networks and enthusiast modification markets. Gaming peripheral aftermarket channels stock replacement haptic actuators for controller refurbishment.
- Assembly Plants:Contract manufacturers integrate haptic subassemblies into finished products on build-to-print or turnkey bases. Foxconn and Pegatron deploy haptic module capacity on operational expenditure terms rather than capital ownership.
- Design Firms:Industrial design consultancies specify haptic feedback requirements during product concept development, influencing downstream component selection. Alps Alpine Co., Ltd. anchors relationships through specialized manufacturing of ultra-thin mechanical switches for steering interface design programs.
OEM manufacturers capture the largest procurement value pool, while assembly plants are expanding fastest through contract manufacturing outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany and Japan anchor premium procurement for piezoelectric switch modules, while China's Yangtze River Delta electronics cluster compresses prototyping cycles for consumer device brands. Tier-one suppliers operate captive haptic actuator foundries across these demand centers, concentrating manufacturing ownership among cockpit integrators and contract electronics assemblers.
Germany
Automotive cockpit electrification drives procurement of force-feedback controllers for next-generation center consoles at BMW, Mercedes-Benz, and Volkswagen. EU F-Gas Regulation compliance tightens material specifications for electromechanical components in climate control interfaces. Baden-Württemberg and Bavaria host tier-one supplier engineering centers where Continental AG maintains vertical control over haptic driver ICs through captive semiconductor partnerships.
China
Consumer electronics brands in the Yangtze River Delta absorb vibration feedback modules for smartphones, tablets, and wearable devices at compressed cost structures. GB national standards for electronic component safety dictate haptic module certification pathways alongside REACH-aligned substance restrictions for export-bound production. Shenzhen and Dongguan contract manufacturers deploy asset-light leasing models for surface-mount actuator capacity, fragmenting manufacturing ownership across Foxconn and Pegatron operations.
Japan
Piezoelectric ceramic feedstock concentrates among Japanese specialty chemical processors supplying lead zirconate titanate formulations for automotive and industrial applications. METI industrial standards and JIS certification requirements govern haptic module performance specifications for domestic OEM supply. Nagoya and Osaka metropolitan areas anchor Alps Alpine Co., Ltd. manufacturing of ultra-thin mechanical switches for steering interface programs at Toyota, Honda, and Nissan.
United States
Gaming peripheral OEMs pull electromagnetic linear resonant actuators into premium controller hardware at elevated attach rates versus standard vibration motors. FCC electromagnetic emissions standards constrain haptic driver circuit design for consumer electronics and automotive aftermarket channels. California and Washington state design studios specify haptic feedback requirements during product concept development, influencing downstream component selection for Sony and Microsoft platform specifications.
India
Production-linked incentives for electronics manufacturing draw haptic module assembly into Gujarat and Tamil Nadu for domestic smartphone and automotive supply chains. BIS certification requirements and CDSCO medical device pathways clarify regulatory entry for haptic-enabled surgical robotics and diagnostic equipment. Chennai and Ahmedabad industrial corridors attract contract manufacturing investment as brands diversify sourcing beyond China-centric supply networks.
Haptic Feedback Switch and Button Platforms Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers where automotive cockpit integrators and gaming peripheral OEMs dictate specification authority. Tier-one suppliers leverage captive foundries and semiconductor partnerships to sustain upstream control over force-feedback controller ICs, while contract electronics assemblers deploy operational expenditure models to compress entry costs for mid-tier brands. Two strategic archetypes dominate: vertically integrated automotive component houses with platform-level specification influence, and asset-light surface-mount specialists capturing consumer electronics volume through flexible capacity arrangements. Competitive moves concentrate on strategic partnerships for semiconductor access and geographic expansion into India PLI scheme corridors.
Among automotive-centric fabricators, Continental AG exemplifies the vertically integrated archetype through captive semiconductor partnerships, while Alps Alpine Co., Ltd. occupies a specialist position in ultra-thin mechanical switch manufacturing. TDK Corporation represents the electromagnetic feedback module tier dominating premium gaming peripheral channels. These three entities anchor distinct competitive vectors without overlapping core technology positioning.
| Leading Market Players |
|---|
| Continental AG |
| FORVIA |
| Marelli Holdings Co., Ltd. |
| Alps Alpine Co., Ltd. |
| TDK Corporation |
| Valeo SA |
| Visteon Corporation |
| Denso Corporation |
| Immersion Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta actuator foundries is compressing module pricing for consumer electronics brands while tightening margins for European automotive-qualified suppliers. This utilization divergence separates commodity vibration motor procurement from force-feedback controller negotiations, where captive semiconductor partnerships at Continental AG and Alps Alpine sustain premium positioning.
Pricing Analysis
Certification level creates the primary spread across automotive, medical, and consumer tiers. Pricing stratifies across automotive-grade force-feedback modules with ISO 26262 documentation, industrial IP-rated sealed buttons, and economy vibration motors for smartphone confirmation haptics. Cost compression in consumer-tier linear resonant actuators is intensifying because Foxconn and Pegatron deploy asset-light leasing models that fragment manufacturing ownership. Gaming peripheral OEMs exhibit the lowest price sensitivity, while wearable device manufacturers in Shenzhen prioritize unit cost above waveform fidelity.
Supply Chain Analysis
Lead zirconate titanate ceramic feedstock concentrates among Japanese and Chinese specialty chemical processors, exposing module assemblers to raw material allocation risk. Haptic module production draws from piezoelectric ceramic formulations, voice coil motors, and force-sensitive resistive layers as core inputs. Single-source vulnerability runs through Japanese PZT suppliers serving automotive safety-critical applications. Distribution runs through tier-one cockpit integrators who specify modules at platform architecture stage, locking in multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against ultrasonic touch detection and radar-based gesture interfaces that are capturing share in premium vehicle cockpits where haptic confirmation remains optional.
For Market Incumbents: Pre-empt capacitive sensing substitution by deepening electromagnetic feedback R&D for steering wheel interfaces. Secure captive semiconductor partnerships to sustain upstream control over force-feedback controller ICs as automotive SPICE alignment extends certification cycles. Target medical device interfaces where FDA 510(k) pathways now clarify for haptic-enabled Class II devices. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu corridors offer underpenetrated haptic module assembly capacity under PLI scheme incentives. Surgical robotics and diagnostic equipment interfaces remain underserved relative to automotive volumes. Pursue design firm relationships during product concept development to influence downstream component selection before OEM specifications crystallize. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one cockpit integrators with platform-level specification authority and multi-year automotive supply agreements. Over a five-to-ten-year horizon, asset-light contract manufacturers face margin compression while vertically integrated component houses with captive foundries sustain pricing power. Monitor ECHA authorization timelines for lead compound sunset dates as inflection signals for compliant ceramic supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Ceramic Reformulation | ECHA's lead compound restrictions force dual-sourcing from Japanese and Korean specialty manufacturers. |
| Captive Semiconductor Partnership | Continental AG sustains vertical control over force-feedback controller ICs for automotive platform integration. |
| Asset-Light Leasing Deployment | Foxconn and Pegatron fragment manufacturing ownership across Shenzhen and Dongguan contract operations. |
| Medical Device FDA Pathway Navigation | CDSCO and FDA 510(k) clarifications open surgical robotics and diagnostic equipment to haptic module suppliers. |
| India PLI Corridor Expansion | Gujarat and Tamil Nadu production-linked incentives draw module assembly for domestic smartphone and automotive supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and OEM procurement disclosures. Primary interviews engaged tier-one supplier procurement managers, automotive platform engineers, gaming peripheral OEM product directors, and medical device regulatory affairs leads. Secondary validation drew from ECHA authorization registers, FDA 510(k) databases, METI industrial standards documentation, and BIS certification records. Bottom-up shipment modeling triangulated against top-down value chain analysis across the analysis window.
Forecast inputs considered automotive interior electrification roadmaps, gaming controller attach rate trajectories, and REACH compliance timeline impacts. Segmentation dimensions spanned product architecture, sensing modality, feedback technology tier, end-use application, and regional manufacturing cluster. CAGRs derived from curve-fitting historical procurement cycles against platform-level specification velocity. Voice coil motor cost curves and piezoelectric ceramic qualification timelines informed precision haptic segment projections.
Practitioners should monitor ECHA sunset date enforcement, India PLI scheme disbursement velocity, and ultrasonic friction modulation prototyping adoption for early signals of forecast revision. Cross-checking against IHS Markit vehicle production databases and Sensor Tower gaming peripheral shipment estimates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
South Korea Reed Sensors Switches Market
Switches
DC Switchgear Market
Switches
Reed Switches Sensors Market
Switches
Proximity Switches Market
Switches
Global High Voltage Switchgear Market
Switches
Drive Mode Selector Switch and Controller Systems Market
Switches
Pressure Switch Market
Switches
China Switchgear Market
Switches
Solid State Relay Market
Switches
Touchpad Market
Switches
Middle-East and Africa Low Voltage Switchgear Market
Switches
Oil Level Switches Market
Switches
Zero Speed Switch Market
Switches
Italy Reed Sensors Switches Market
Switches
Static Transfer Switches Market
Switches
High-Voltage Disconnect Switch Market