
 Picosecond Lasers Market | 2026-2036
Picosecond Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Picosecond Lasers Market Analytics
Sub-picosecond pulse duration specifications is bifurcating the competitive landscape between premium medical-grade suppliers and industrial precision manufacturers. Coherent leverages its vertically integrated crystal growth capabilities to dominate high-power industrial cutting applications. Alma Lasers anchors its position across dermatology clinics through specialized handpiece ecosystems and service density.
Picosecond lasers generate optical pulses with durations below one trillionth of a second, typically employing neodymium-doped yttrium aluminum garnet (Nd:YAG) gain media at 1064 nm with harmonic conversion to 532 nm for selective photothermolysis in tissue. Solid state architectures currently lead installed base volumes due to proven reliability in tattoo removal and pigmented lesion treatments. Mode-locked technology segments command premium positioning as femtosecond-adjacent pulse control enables finer material ablation thresholds in semiconductor wafer processing.
FDA 510(k) clearance requirements and ISO 13485 medical device quality management standards shape product development timelines and commercialization pathways for aesthetic and surgical laser platforms. The EU Medical Device Regulation imposes additional clinical evidence burdens on picosecond systems marketed for dermatological indications across European member states. Stakeholders must monitor evolving IEC 60825 laser safety classifications and harmonized electromagnetic compatibility testing protocols that determine market access eligibility.
Market Dynamics
Sub-picosecond pulse architectures are compressing technical differentiation windows between medical aesthetic platforms and precision manufacturing systems, forcing suppliers to recalibrate R&D allocation across dual-use applications.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for Nd:YAG-based dermatology devices are expanding clinic-level procurement in the United States.
- Semiconductor wafer processing:Die singulation and microvia drilling applications in Taiwan and South Korea fabs are absorbing high-repetition-rate industrial picosecond systems.
- Harmonic conversion efficiency gains:Improved nonlinear crystal architectures are reducing cost-per-watt at 532 nm for multi-wavelength tattoo removal platforms.
Market Restraints
- Neodymium supply concentration:Rare earth element refining bottlenecks in China create input cost volatility for YAG gain media production.
- ISO 13485 compliance timelines:Medical device quality management certification cycles extend product launch windows by 18-24 months for aesthetic laser OEMs.
- Fiber laser substitution:Continuous-wave and nanosecond fiber platforms capture price-sensitive industrial marking applications below 50W.
Strategic Opportunities
- Ophthalmic refractive surgery:Corneal lenticule extraction protocols are opening femtosecond-adjacent positioning for sub-picosecond platforms in Germany and Japan.
- India PLI scheme:Production-linked incentives for medical device manufacturing are attracting contract assembly investments for Asian market distribution.
- Battery electrode scribing:Lithium-ion cell manufacturing lines in Michigan and Nevada are piloting picosecond sources for cleaner foil cutting.
Industry Challenges
- Mode-locked oscillator alignment:Specialist photonics technicians command premium compensation, constraining production scale-up for emerging suppliers.
- IEC 60825-1 certification:Laser safety classification testing for Class 4 medical devices requires third-party laboratory queues that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Picosecond Lasers Market |
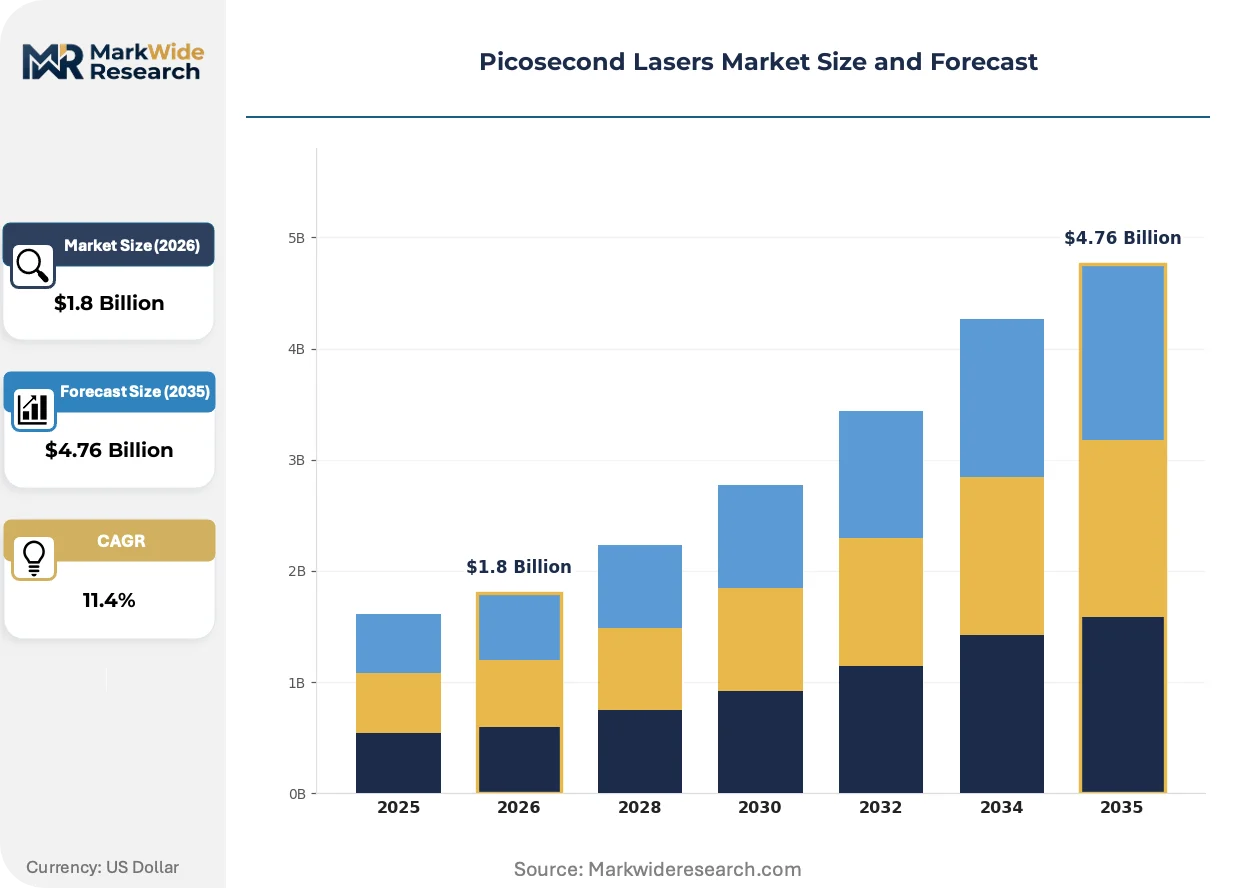
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State, Fiber, Gas, Semiconductor Application: Aerospace, Automotive, Medical, Manufacturing End User: Research Institutions, Hospitals, OEMs, Clinics Technology: Mode-Locked, Amplification, Frequency Conversion, Pulse Shaping |
| Companies Covered | Cynosure, Cutera, Candela Corporation, Fotona, Lutronic, El.En. S.p.A., Alma Lasers, Lumenis, Coherent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Picosecond Lasers Market Evolving Landscape
Active beam delivery systems and solid-state cooling architectures are compressing platform footprints while expanding addressable procedure volumes across ambulatory settings.
Monolithic microchip laser designs are miniaturizing pump and cavity geometries into palm-scale footprints. Dermatology clinics in South Korea and Spain are adopting these reduced-form-factor systems for satellite office deployment. The technology is miniaturizing capital equipment into portable configurations that challenge traditional service-revenue models.
EU Medical Device Regulation clinical evidence requirements are extending post-market surveillance obligations for picosecond systems marketed across European member states. Manufacturers must now maintain periodic safety update reports and vigilance databases that increase regulatory affairs headcount. Aesthetic laser platforms face the steepest compliance burden due to their broad patient-contact indications.
Leasing and pay-per-procedure arrangements are displacing outright capital purchases among US-based dermatology group practices. Equipment financiers and manufacturer captive finance arms are capturing margin that previously accrued to distributor networks. This restructuring concentrates most visibly in Texas and Florida where multi-site clinic rollups dominate aesthetic service delivery.
Picosecond Lasers Market Segmentation
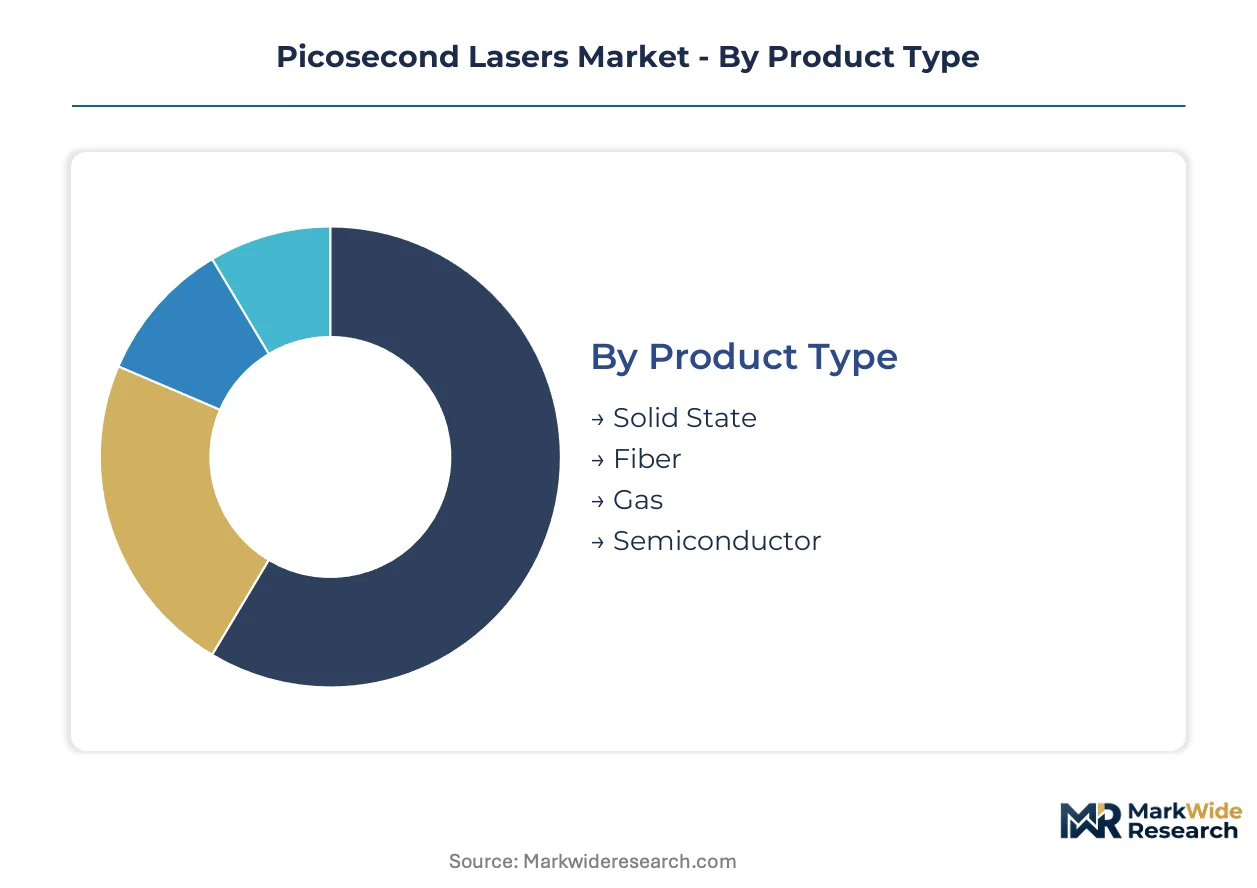
Picosecond laser procurement channels bifurcate sharply between capital-intensive industrial systems and recurring-revenue medical platforms. Understanding which segments flow through direct sales, distributor networks, or leasing arrangements determines go-to-market economics for suppliers.
Product Type:
Solid state architectures dominate direct sales to dermatology clinics through specialized medical device distributors, while fiber and gas systems move through industrial automation integrators serving precision manufacturing clusters.
- Solid State:Nd:YAG gain media with harmonic conversion to 532 nm and 755 nm wavelengths deliver proven reliability for tattoo removal and pigmented lesion treatments. Demand concentrates in Germany and the United States where dermatology group practices prioritize FDA-cleared platforms with established service networks.
- Fiber:Ytterbium-doped silica architectures achieve superior beam quality at lower cost-per-watt for industrial marking and micromachining below 100W. Procurement in Taiwan and South Korea fabs favors these systems for die singulation where thermal damage budgets are tight.
- Gas:Excimer and CO2-pumped designs serve niche UV lithography and materials research applications requiring deep ultraviolet output.
- Semiconductor:Vertical-cavity surface-emitting and edge-emitting diode lasers enable compact, battery-powered portable units for field-deployable medical screening.
By volume, Solid State leads. By growth pace, Fiber systems are expanding most quickly in Asian electronics manufacturing.
Application:
Margin structures vary dramatically across applications, with medical aesthetics commanding premium pricing and aerospace qualification cycles extending payback periods for suppliers.
- Medical:Dermatology clinics in Texas and Florida drive recurring consumable revenue through handpiece replacements and service contracts. Tattoo removal and skin rejuvenation protocols require precise pulse control that justifies capital expenditure despite longer sales cycles.
- Manufacturing:Semiconductor wafer processing in Taiwan fabs and lithium-ion electrode scribing in Michigan absorb high-repetition-rate systems where throughput economics dominate procurement decisions.
- Aerospace:Turbine blade cooling hole drilling and composite trimming applications require extensive qualification testing that extends OEM approval timelines.
- Automotive:Battery cell manufacturing and power electronics packaging are piloting picosecond sources for cleaner edge quality in copper and aluminum processing.
Medical generates highest per-unit margins. Manufacturing shows the steepest volume trajectory as electric vehicle battery capacity expands.
End User:
Research institutions purchase through grant-funded acquisition channels with extended evaluation periods, while hospitals and clinics respond to manufacturer captive financing and pay-per-procedure structures.
- Clinics:Multi-site dermatology rollups in Florida and Texas favor leasing arrangements that convert capital expenditure to operating expense, with equipment financiers capturing margin previously retained by distributors.
- Hospitals:Academic medical centers in Germany and Japan require extensive clinical evidence packages under EU MDR and PMDA frameworks before procurement approval.
- Research Institutions:National laboratories and university physics departments purchase through competitive grant cycles with emphasis on customization and publication support.
- OEMs:Industrial laser system integrators in China and South Korea specify picosecond sources for embedded machine tool applications with multi-year supply agreements.
Clinics drive highest unit velocity. OEM relationships yield the longest contract durations and deepest technical collaboration.
Technology:
Intellectual property concentration in mode-locked oscillator designs creates licensing revenue streams for specialized photonics firms, while amplification and frequency conversion subsystems attract contract manufacturing from Asian component suppliers.
- Mode-Locked:Saturable absorber and Kerr-lens techniques generate sub-picosecond pulse trains with repetition rates exceeding 80 MHz. German and Japanese suppliers dominate this IP-intensive segment through proprietary crystal growth and cavity stabilization methods.
- Frequency Conversion:Nonlinear optical parametric oscillators and second-harmonic generation stages extend wavelength coverage into the visible and ultraviolet. Chinese crystal processing clusters in Fujian province supply beta-barium borate and lithium triborate components to global system integrators.
- Amplification:Regenerative and multipass amplifier architectures boost pulse energy for materials processing while maintaining beam quality.
- Pulse Shaping:Acousto-optic and liquid-crystal modulators enable programmable spectral and temporal profiles for coherent control experiments.
Mode-Locked commands premium pricing. Frequency Conversion shows the fastest supplier base expansion as crystal fabrication capabilities proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in high-precision laser systems concentrate among German and Japanese suppliers, while China and the United States absorb the majority of import volumes for both medical aesthetics and semiconductor manufacturing applications.
United States
FDA 510(k) clearance pathways for Nd:YAG-based dermatology devices are accelerating clinic-level procurement across Texas and Florida, where multi-site dermatology rollups favor leasing arrangements. The IRA's domestic manufacturing incentives are attracting battery electrode scribing pilot programs in Michigan and Nevada fabs.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria drive demand for industrial picosecond systems in automotive power electronics packaging. EU MDR clinical evidence requirements extend post-market surveillance obligations for aesthetic laser platforms marketed across European member states.
China
Rare earth element refining bottlenecks for neodymium-doped YAG gain media create input cost volatility, while NMPA medical device registration pathways tighten safety benchmarks for imported dermatology platforms. Crystal processing clusters in Fujian province supply beta-barium borate components to global system integrators.
South Korea
Semiconductor wafer processing fabs in the Seoul Capital Area and Busan-Ulsan corridor absorb high-repetition-rate industrial picosecond systems for die singulation applications. MFDS medical device approval frameworks require extensive clinical evidence packages before aesthetic laser commercialization.
Japan
Ophthalmic refractive surgery protocols in Tokyo and Osaka are opening femtosecond-adjacent positioning for sub-picosecond platforms in corneal lenticule extraction. METI industrial technology roadmaps prioritize precision photonics manufacturing capabilities in the Chubu-Nagoya region.
Picosecond Lasers Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and regional distribution networks, producing a tiered structure where publicly traded firms control capital-intensive R&D while private entities capture service-intensive medical aesthetics segments. Three archetypes dominate: vertically integrated crystal growers supplying industrial cutting applications, dermatology-focused platform builders with dense service networks, and component specialists licensing mode-locked oscillator IP. Competitive moves concentrate on strategic partnerships with semiconductor fabs and geographic expansion through distributor acquisitions.
Among Israel-based medical device developers, Alma Lasers and Lumenis exemplify the dermatology-platform archetype through specialized handpiece ecosystems. Coherent occupies a position representing the industrial-precision tier, leveraging in-house crystal growth capabilities for high-power manufacturing applications. El.En. S.p.A. anchors the European specialist segment as an Italy-structured laser platform developer.
| Leading Market Players |
|---|
| Cynosure |
| Cutera |
| Candela Corporation |
| Fotona |
| Lutronic |
| El.En. S.p.A. |
| Alma Lasers |
| Lumenis |
| Coherent |
| Others |
Value Network & Pricing Analysis
Ninety-day crystal inventory cycles at Fujian processing clusters concentrate pricing leverage among Nd:YAG gain media suppliers, compressing margin buffers for system integrators while amplifying cost pass-through power for vertically integrated manufacturers with captive rare earth refining.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across high-repetition-rate manufacturing systems, while dermatology clinics absorb premium-mid-economy pricing differentiation driven by FDA certification tier and service bundling density. Price differentiation hinges on ISO 13485 compliance grade and geographic proximity to authorized service hubs. Cost compression in fiber-substituted marking tiers is intensifying because nanosecond platforms capture sub-50W applications. OEM procurement teams in South Korea fabs demonstrate lowest price sensitivity; independent dermatology practices in Florida exhibit highest.
Supply Chain Analysis
Ninety-day crystal inventory cycles expose mode-locked oscillator manufacturers to single-source vulnerability for beta-barium borate and lithium triborate components. Supply concentrates in China for rare earth refining and neodymium-doped YAG substrates, Taiwan for semiconductor-grade nonlinear crystals, and Germany for precision cavity stabilization hardware. Raw material dependencies span neodymium oxide, synthetic sapphire, and specialty optical coatings. Distribution runs through medical device distributors for aesthetic platforms and industrial automation integrators for precision manufacturing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
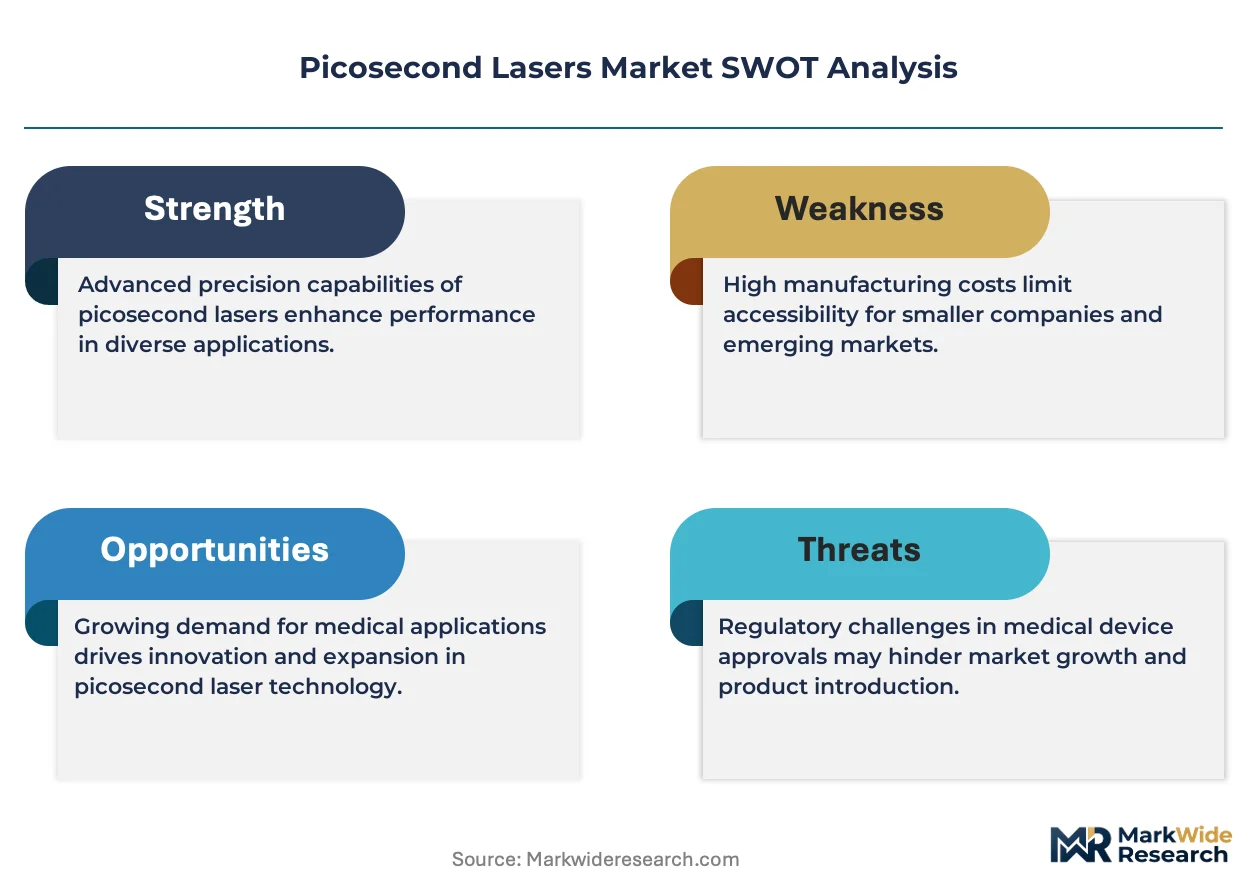
This market functions as a defensive-moat story where FDA 510(k) clearance entrenchment and ISO 13485 certification timelines create switching costs that protect incumbent positioning against emerging suppliers.
For Market Incumbents: Compound service density advantages in Texas and Florida dermatology rollups through captive financing arms that displace distributor margin capture. Deepen backward integration into Nd:YAG crystal growth to insulate against Chinese rare earth volatility. Prioritize IEC 60825-1 certification pipeline acceleration ahead of mode-locked oscillator alignment bottlenecks that constrain production scale-up. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for Nd:YAG-based tattoo removal platforms open white-space penetration in under-served Midwest dermatology markets. Target pay-per-procedure leasing structures that convert capital expenditure barriers for independent clinics. Pursue battery electrode scribing pilot programs in Michigan and Nevada as the most penetrable industrial entry vector. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because clearance backlogs and clinical evidence requirements under EU MDR and PMDA frameworks protect compound annual returns for certified platform holders. Acquisition targets should display mode-locked oscillator IP concentration with established service networks. Watch MFDS and NMPA approval velocity as the signal for Asian market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Captive neodymium-doped YAG supply insulates Coherent against Chinese rare earth export volatility. |
| Pay-per-Procedure Financing Launch | Equipment financiers capture distributor margin in Texas and Florida dermatology rollups. |
| EU MDR Clinical Evidence Investment | Post-market surveillance databases extend competitive moats for Alma Lasers across German clinics. |
| Battery Electrode Scribing Pilot | Lithium-ion manufacturers in Michigan validate picosecond foil cutting against mechanical alternatives. |
| Mode-Locked IP Licensing Expansion | German and Japanese specialists monetize oscillator designs through Asian system integrator royalties. |
Research Methodology
Operator-level perspectives from dermatology clinic owners, biomedical equipment procurement managers, semiconductor fab process engineers, and laser system service technicians anchored the qualitative base. These primary interviews combined with secondary validation from FDA 510(k) clearance databases, EU MDR periodic safety update reports, SEC filings of listed photonics suppliers, and Taiwan semiconductor equipment import records. Bottom-up unit economics triangulated against top-down market sizing across solid state, fiber, and gas architecture segments.
Sensitivity analysis tested forecast robustness across neodymium price volatility scenarios and FDA clearance timeline variations throughout the projection horizon. Segmentation dimensions modeled include product architecture, application vertical, end-user procurement channel, and technology IP concentration. CAGRs derived from procedure volume trajectories in dermatology clinics and wafer processing throughput expansion in Taiwan and South Korea fabs. Mode-locked oscillator alignment labor costs and harmonic conversion efficiency curves served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable rare earth supply assumptions; material deviation in Chinese export policy or IEC 60825 reclassification would warrant model refresh. Forecasts reflect documented base-case parameters including semiconductor capital expenditure continuity and aesthetic service demand elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Asia Pacific Fiber Optics Market
Optics
Europe Laser Interferometer Market
Optics
Fiber-Optic Couplers Market
Optics
Single-Mode Optical Fiber Market
Optics
Smartphone Lenses Market
Optics
Optical Telescope Market
Optics
Optical Fiber Raw Material Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Global High Purity Quartz Glass Market
Optics
Fiber Optic Cable Market
Optics
Sports Optics Market
Optics
Digital Holographic Microscopy Market
Optics
Global Semiconductor Lasers Market
Optics
Tunable Laser Market
Optics
Optical Receivers Market