
 TFT LCD Modules (11-Inch to 17-Inch) Market | 2026-2036
TFT LCD Modules (11-Inch to 17-Inch) Market Size, Share, and Industry Trends Forecast 2026-2036
TFT LCD Modules (11-Inch to 17-Inch) Market Analytics
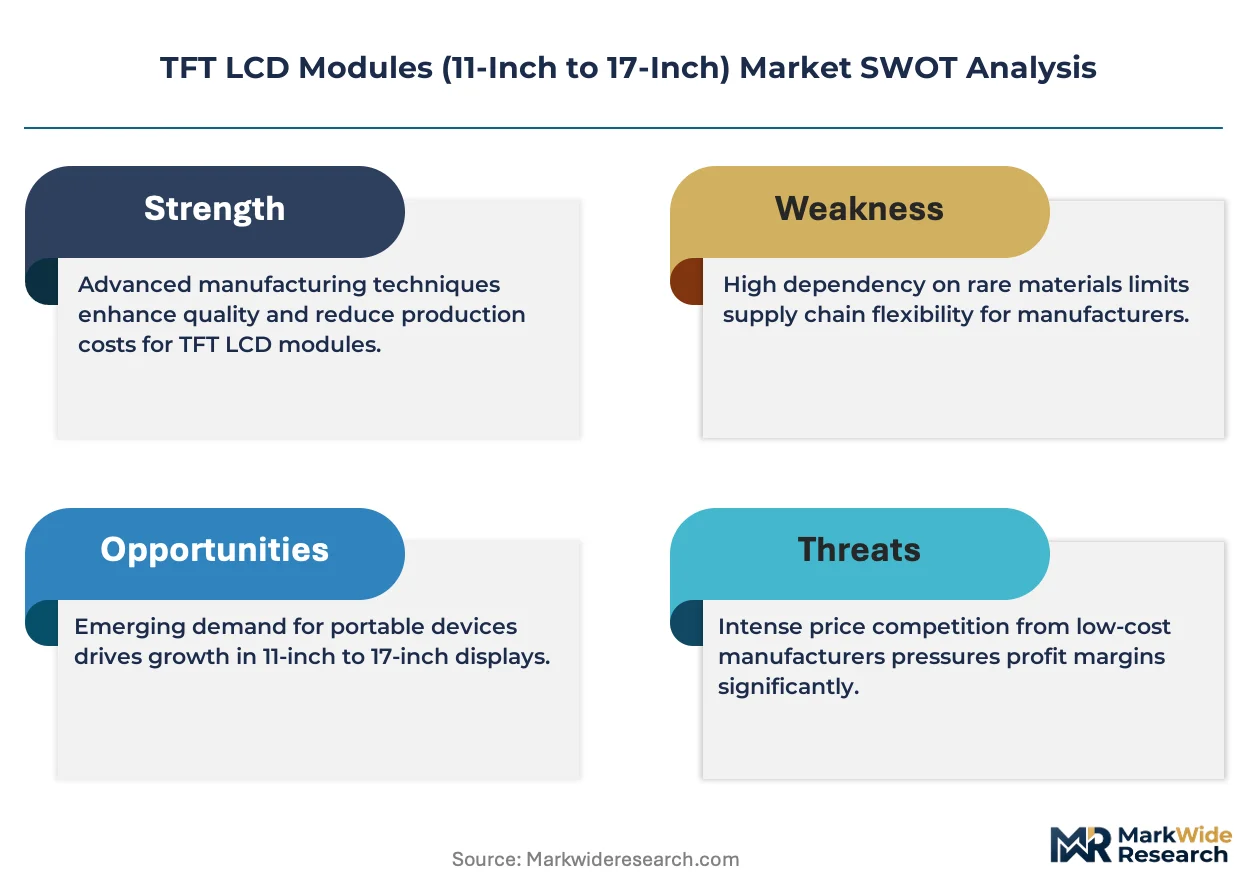
Indium tin oxide is consolidating its role as the dominant transparent conductor in TFT LCD modules, though silver nanowire and metal mesh alternatives are gaining traction in cost-sensitive segments. BOE Technology Group leverages its massive G10.5 fabrication complex in Hefei to anchor supply for automotive and industrial clients. Innolux Corporation competes through specialized VA-panel production for high-contrast medical imaging applications. AU Optronics sustains technology leadership in LTPS backplanes for premium notebook displays.
TFT LCD modules in the 11-inch to 17-inch diagonal range employ thin-film transistor arrays on glass substrates to drive individual pixels at resolutions from HD to 4K, with backlight units typically using edge-lit LED configurations for thickness reduction below 5mm in slim-profile designs. These modules serve as primary human-machine interfaces in laptops, automotive center stacks, industrial HMIs, and portable diagnostic equipment. Touchscreen integration now dominates the consumer electronics application segment as OEMs eliminate separate input layers through in-cell and on-cell bonding processes. IPS technology leads in color-critical medical devices and professional monitors where 178-degree viewing angles eliminate gamma shift. The automotive display segment is expanding fastest as dashboard digitization replaces mechanical gauges across electric and internal-combustion vehicle platforms.
China's MIIT enforces GB standards for display energy consumption and electromagnetic compatibility, while the EU F-Gas Regulation restricts fluorinated greenhouse gases used in certain etching processes during TFT array fabrication. REACH compliance in Europe mandates full material disclosure for imported modules, affecting supply chain documentation burdens for Asian manufacturers. Japan's METI promotes JIS standards for industrial display durability in factory automation settings. Stakeholders must monitor evolving mercury-free backlight requirements and regional content thresholds that could reshape sourcing strategies for panel assembly and driver IC integration.
Market Dynamics
Automotive OEMs are replacing mechanical instrument clusters with digitized center-stack displays, creating a demand surge that is restructuring capacity allocation across East Asian fabrication complexes. This vehicle-platform transition is pulling module specifications toward wider temperature tolerances and curved-form-factor compatibility.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated etching gases are accelerating process innovation in TFT array fabrication, pushing manufacturers toward alternative chemistries that reduce environmental liability.
- In-vehicle infotainment expansion:Electric vehicle platforms are standardizing on 12-inch to 15-inch touch-integrated displays for dashboard consolidation, eliminating discrete gauge clusters.
- LTPS backplane migration:Low-temperature polysilicon technology is enabling higher pixel densities and lower power consumption for premium notebook panels, differentiating supplier capabilities.
Market Restraints
- Indium supply concentration:ITO transparent conductor production depends on limited indium refining capacity concentrated in Chinese smelting operations, exposing cost volatility.
- Silver nanowire technical ceiling:Alternative transparent conductors face haze and oxidation limitations that constrain adoption in high-resolution medical imaging displays.
- Japan METI durability standards:JIS certification requirements for industrial automation displays extend qualification timelines and raise non-recurring engineering costs for factory HMI suppliers.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for domestic electronics manufacturing are creating localized assembly demand for 15-inch operator panels in process control applications.
- On-cell touch integration:Eliminating separate touch sensor layers through direct bonding to color filter glass is compressing module thickness and reducing bill-of-materials complexity.
- EU CSRD disclosure mandates:Corporate sustainability reporting requirements are favoring suppliers with documented conflict-mineral-free supply chains and carbon footprint transparency.
Industry Challenges
- Driver IC talent scarcity:Specialized analog design expertise for high-voltage TFT gate drivers is concentrating among experienced engineering teams in Hsinchu and Seoul, constraining new entrant scaling.
- Backlight unit reconfiguration:Mercury-free LED phosphor transitions are forcing redesigns of edge-lit optical films and diffuser plates, disrupting qualified component libraries.
- REACH documentation burden:Full material disclosure requirements for European imports are fragmenting supply chain data management across multi-tier component sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TFT LCD Modules (11-Inch to 17-Inch) Market |
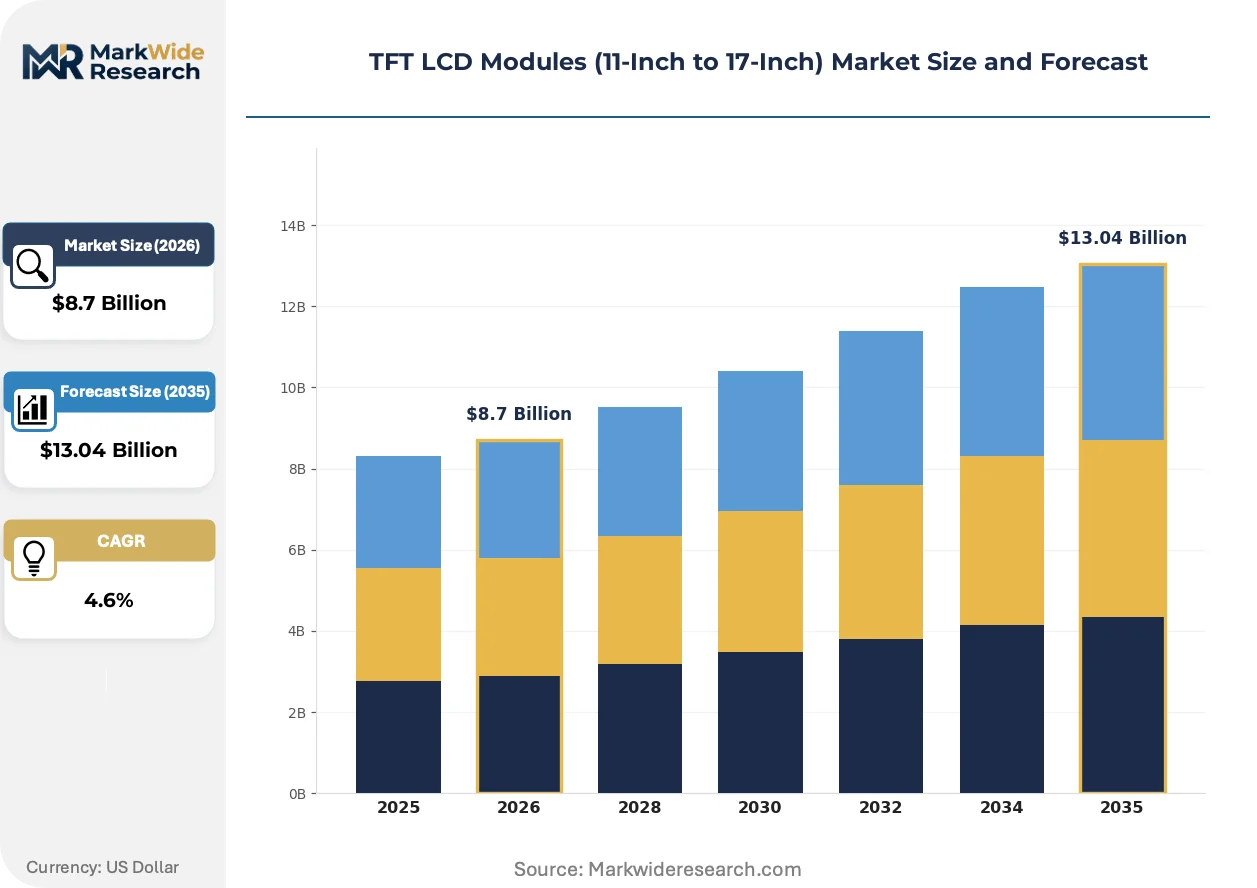
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full HD, Wide Viewing Angle, Touchscreen, Anti-Glare Application: Consumer Electronics, Automotive Displays, Industrial Controls, Medical Devices Technology: LTPS, IPS, VA, TN End User: OEMs, Retailers, Distributors, Aftermarket Providers |
| Companies Covered | Innolux Corporation, AU Optronics Corp., LG Display Co. Ltd, BOE Technology Group Co., Ltd., Samsung Electronics Co., Ltd, Sharp Corporation, Tianma Microelectronics, TCL China Star Optoelectronics Technology, HannStar Display Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TFT LCD Modules (11-Inch to 17-Inch) Market Evolving Landscape
Display module architecture is converging toward system-in-panel integration, where timing controllers, power management, and touch processing migrate onto the glass substrate or flex cable rather than remaining discrete board-mounted components.
In-cell touch technology is automating the elimination of separate touch sensor layers by embedding capacitive electrodes within the TFT array or color filter structure. Automotive Tier 1 suppliers are adopting this architecture aggressively to reduce stack thickness below 3mm for curved dashboard implementations. The structural consequence is compressing the addressable market for external touch controller IC vendors and shifting value capture toward panel manufacturers with integrated process capabilities.
China's MIIT is enforcing progressively stricter GB standards for display energy efficiency and electromagnetic compatibility, with 2024 revisions tightening standby power limits and radiated emission thresholds. Module suppliers are responding by redesigning power circuits and shielding architectures, with notebook and monitor segments facing the steepest compliance redesign cycles. South Korean and Taiwanese manufacturers are establishing dedicated certification laboratories in Suzhou and Shenzhen to accelerate local testing turnaround.
Fleet procurement of industrial HMIs is consolidating around multi-year framework agreements that bundle display modules with embedded computing and software licensing. System integrators are displacing spot-market component purchasing with vendor-managed inventory arrangements tied to uptime guarantees. This pattern is most visible in German automotive manufacturing equipment supply chains, where Siemens and Bosch Rexroth are standardizing panel specifications across plant retrofit programs.
TFT LCD Modules (11-Inch to 17-Inch) Market Segmentation
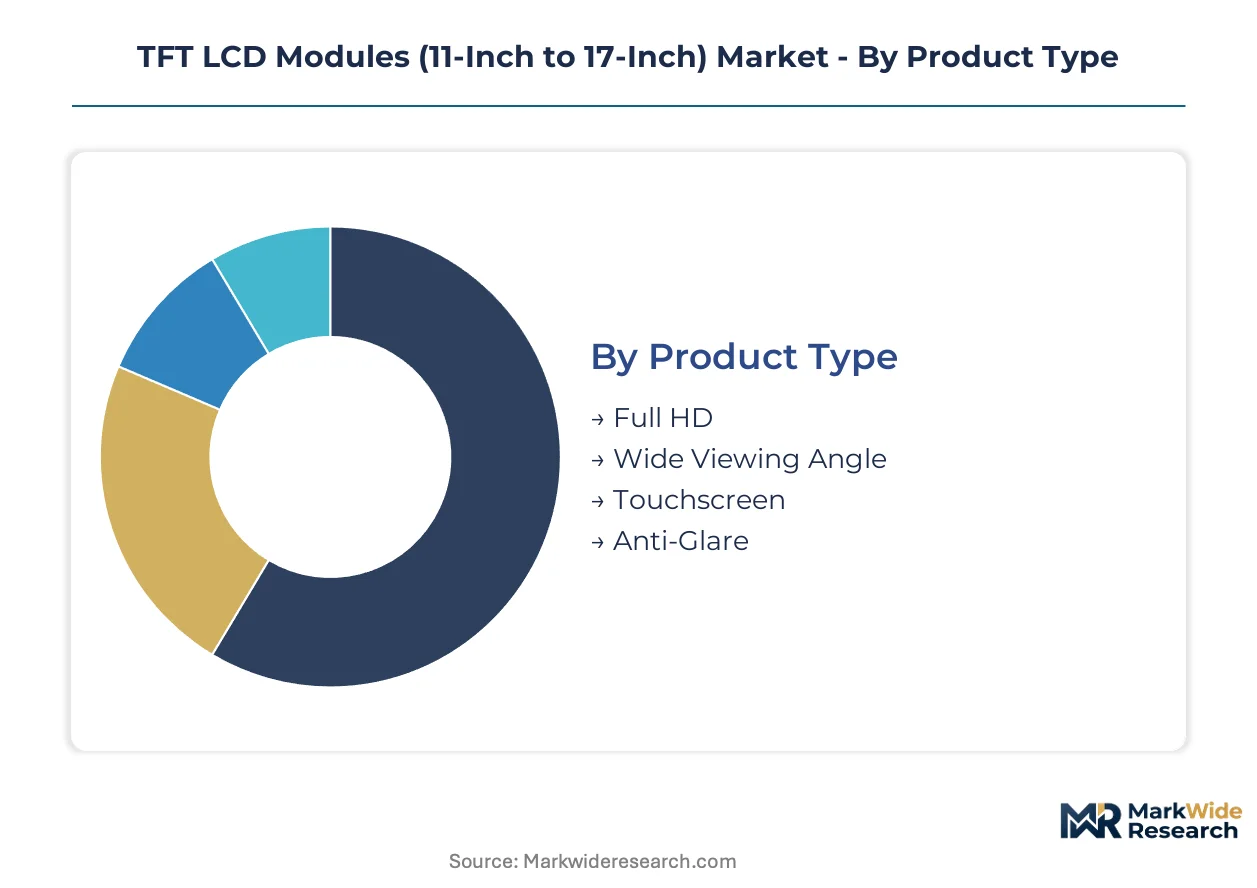
Segmentation in the TFT LCD module market reveals how integration depth varies dramatically across use cases. Standalone displays for consumer electronics demand thin profiles and touch layers, while embedded industrial systems prioritize signal stability over form factor. Understanding these structural splits enables suppliers to align fabrication investments with actual deployment architectures.
Product Type:
Integration depth splits sharply between standalone panels and embedded touch systems, with surface treatments determining outdoor versus indoor viability.
- Full HD:1920x1080 resolution modules dominate notebook and monitor applications where pixel density balances manufacturing yield against visual clarity. Automotive center-stack adoption in Germany and Japan concentrates demand for automotive-grade variants with wider temperature tolerances.
- Touchscreen:Capacitive in-cell and on-cell bonding eliminates discrete sensor layers, compressing stack thickness below 3mm for convertible laptops and curved automotive dashboards. BOE and Innolux are expanding dedicated touchscreen lines in Hefei and Tainan to capture this integration shift.
- Wide Viewing Angle:IPS-derived architectures serve medical imaging and professional monitors where 178-degree viewing eliminates color shift across collaborative workspaces.
- Anti-Glare:Matte surface treatments with diffused light scattering address industrial HMI deployments under factory lighting in South Korea and Taiwan.
Volume placements concentrate in Full HD; the faster expansion belongs to Touchscreen.
Application:
Cost tier differentiation separates premium validated segments from price-sensitive consumer categories, with certification requirements driving margin dispersion.
- Automotive Displays:Digitized instrument clusters and center-stack screens require AEC-Q100 qualification, curved-form-factor compatibility, and operating ranges from -40°C to 85°C. European electric vehicle platforms in Germany and France are standardizing 12-inch to 15-inch touch-integrated units.
- Medical Devices:Diagnostic imaging panels demand DICOM calibration, antimicrobial coatings, and IEC 60601-1-2 electromagnetic immunity. FDA and Japan PMDA compliance timelines extend procurement cycles to 18-24 months.
- Consumer Electronics:Notebook and monitor panels prioritize slim profiles below 5mm and low blue light certifications for retail channels in China and the United States.
- Industrial Controls:Factory automation HMIs require JIS durability standards and 24/7 operation ratings, with procurement consolidating around Siemens and Bosch Rexroth framework agreements in German manufacturing.
Automotive Displays command premium pricing tiers; Medical Devices are climbing the fastest on regulatory-driven replacement cycles.
Technology:
Backplane maturity and manufacturing complexity create distinct capability moats among fabrication specialists.
- LTPS:Low-temperature polysilicon enables higher electron mobility for pixel-dense premium notebooks and power-efficient mobile panels. AU Optronics sustains technology leadership through dedicated G6 LTPS lines in Taichung.
- IPS:In-plane switching dominates color-critical medical and professional applications where off-axis gamma stability is mandatory. LG Display and BOE operate specialized IPS capacity in Paju and Beijing.
- VA:Vertical alignment serves high-contrast industrial and automotive segments with deeper blacks than TN alternatives.
- TN:Twisted nematic retains cost-sensitive entry-level monitor positions where response time outweighs color accuracy.
LTPS captures the highest-margin placements; IPS is expanding most quickly into automotive validation pipelines.
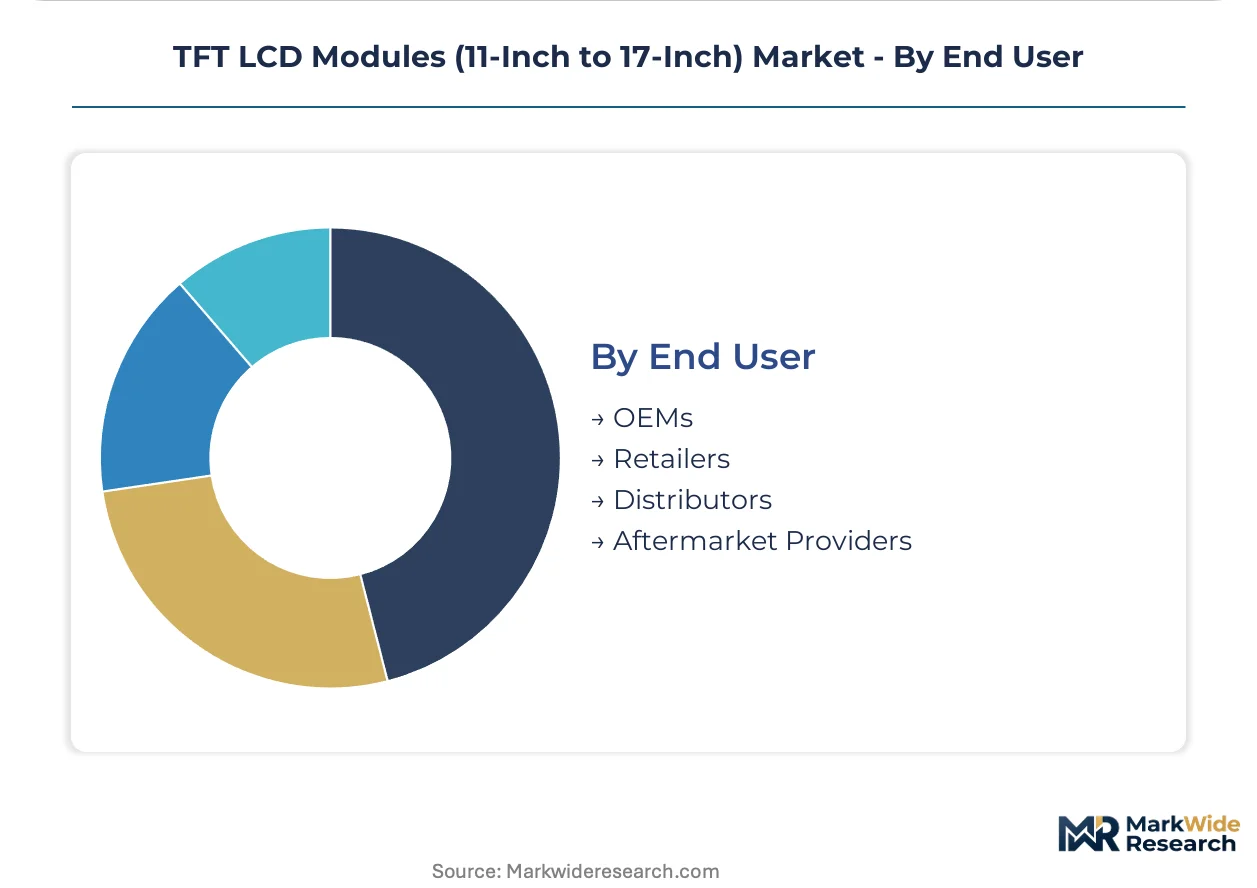
End User:
Customer type determines contract structure, with OEM direct relationships favoring integrated module suppliers over component merchants.
- OEMs:Dell, HP, Lenovo, and automotive Tier 1s source directly through multi-year supply agreements with specified brightness bins and color calibration. These contracts bundle driver IC integration and flex cable assembly to reduce downstream assembly steps.
- Distributors:Arrow Electronics and Avnet maintain regional inventory for industrial and medical replacement markets with shorter lead time requirements.
- Retailers:Best Buy and Amazon channels drive spot-market demand for aftermarket notebook panels and portable monitor accessories.
- Aftermarket Providers:Independent repair networks and refurbishment specialists purchase legacy-compatible modules for out-of-warranty device restoration.
OEMs anchor volume commitments; Distributors are gaining share fastest on industrial automation spare-part demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for 11-inch to 17-inch TFT LCD modules concentrates in East Asian fabrication clusters, with automotive digitization and industrial automation pulling supply toward South Korea, China, and Taiwan. Module procurement patterns diverge sharply between premium validated segments and cost-optimized consumer categories.
China
BOE Technology Group anchors capacity expansion through its G10.5 complex in Hefei, supplying automotive and industrial clients with large-format panels. MIIT enforces progressively stricter GB standards for display energy efficiency and electromagnetic compatibility, forcing power circuit redesigns across notebook and monitor segments. Certification laboratories in Suzhou and Shenzhen accelerate local testing turnaround for South Korean and Taiwanese manufacturers.
South Korea
Samsung Electronics and LG Display drive LTPS backplane migration for premium notebook panels, leveraging electron mobility advantages for pixel-dense applications. The national regulator promotes display industry competitiveness through R&D tax incentives and domestic supply chain consolidation. Seoul and Gyeonggi Province house specialized driver IC design teams whose analog expertise concentrates among experienced engineering cohorts.
Japan
Sharp Corporation sustains industrial display production for factory automation HMIs requiring JIS durability certification. METI standards extend qualification timelines and raise non-recurring engineering costs, filtering supplier participation in process control applications. Nagoya and Osaka manufacturing corridors specialize in high-contrast VA panels for medical imaging equipment.
Germany
Automotive OEMs in Stuttgart and Munich standardize 12-inch to 15-inch touch-integrated displays for electric vehicle dashboard consolidation. EU F-Gas Regulation restricts fluorinated etching gases, pushing TFT array fabricators toward alternative chemistries. Siemens and Bosch Rexroth framework agreements consolidate procurement of industrial HMIs with embedded computing bundles.
United States
Dell, HP, and Lenovo source directly through multi-year supply agreements specifying brightness bins and color calibration for premium notebook panels. EPA and FCC regulations govern standby power limits and radiated emission thresholds for imported modules. Austin and Silicon Valley design centers coordinate specification requirements with Asian fabrication partners.
TFT LCD Modules (11-Inch to 17-Inch) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated panel suppliers capturing value from touch controller displacement while component merchants serve replacement markets. The vendor base organizes around three archetypes: scale-driven G10.5 operators, LTPS technology specialists, and VA-panel niche players. Dominant competitive moves include capacity allocation toward automotive qualification pipelines and in-cell touch integration to compress module thickness.
Among Taiwan-based fabricators, Innolux Corporation and AU Optronics Corp. exemplify divergent specialization strategies. Innolux occupies a position within the high-contrast medical imaging tier, while AU Optronics anchors the LTPS backplane premium notebook segment. BOE Technology Group Co., Ltd. represents the scale-driven archetype with massive substrate generation capacity. These three companies illustrate how geographic clustering and technology focus create distinct competitive positions without overlapping core competencies.
| Leading Market Players |
|---|
| Innolux Corporation |
| AU Optronics Corp. |
| LG Display Co. Ltd |
| BOE Technology Group Co., Ltd. |
| Samsung Electronics Co., Ltd |
| Sharp Corporation |
| Tianma Microelectronics |
| TCL China Star Optoelectronics Technology |
| HannStar Display Corporation |
| Others |
Value Network & Pricing Analysis
Specialized analog design engineers concentrated in Hsinchu and Seoul create labor-cost differentials that widen pricing spreads between premium LTPS notebook panels and commodity TN monitors. Driver IC talent scarcity in these Taiwanese and South Korean hubs forces OEMs to absorb higher engineering premiums for high-voltage gate driver specifications, compressing margins at the economy tier while sustaining premium-mid-economy pricing differentiation across validated automotive and medical segments.
Pricing Analysis
Volume placements concentrate in Full HD notebook panels while margin capture belongs to LTPS and in-cell touch variants. Price differentiation separates AEC-Q100 automotive-grade modules with -40°C to 85°C operating ranges from consumer electronics panels lacking validation. Pricing pressure stems from indium cost volatility tied to Chinese smelting concentration, eroding ITO transparent conductor margins. Distributors serving industrial replacement markets exhibit highest price sensitivity; medical device OEMs accepting 18-24 month qualification cycles show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Dell, HP, and Lenovo through multi-year supply agreements with specified brightness bins. Geographic supply concentrates in China, South Korea, and Taiwan, with BOE's G10.5 Hefei complex and Samsung's LTPS lines in Gyeonggi Province anchoring capacity. Raw material dependencies center on indium for ITO, glass substrates from Corning and AGC, and LED phosphors for mercury-free backlights. Single-source vulnerability in driver IC design talent creates qualification bottlenecks. Distribution runs through Arrow Electronics and Avnet for industrial spare-part demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation erects a cost-of-compliance barrier that filters out sub-scale fabricators unable to fund alternative etching chemistry transitions, entrenching qualified incumbents with environmental liability coverage.
For Market Incumbents: Anchor automotive qualification pipelines through AEC-Q100 certification investments to defend against OLED substitution in center-stack applications. Deepen backward integration into driver IC design capabilities to offset talent scarcity in Hsinchu and Seoul. Prioritize on-cell touch process yields to capture value from displaced external touch controller vendors. For New Entrants and Emerging Players: The premium-to-economy price-point gap in 15-inch industrial HMI panels offers white-space entry through JIS durability certification. Target India's PLI scheme incentives for domestic electronics assembly to bypass established East Asian supply chains. Pursue fleet procurement framework agreements with Siemens and Bosch Rexroth for process control applications. For Investors and Strategic Acquirers: Re-rating potential sits with LTPS technology specialists given premium notebook panel migration and in-cell touch integration acceleration. Long-term viability favors fabricators with captive G6 or larger substrate generation and automotive validation pipelines. Watch for EU CSRD disclosure mandates favoring conflict-mineral-free supply chains as an inflection signal for valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| In-Cell Touch Integration | BOE and Innolux expansion in Hefei and Tainan compresses module thickness below 3mm for curved automotive dashboards. |
| Automotive Qualification Pipeline | AEC-Q100 certification opens 12-inch to 15-inch electric vehicle center-stack procurement with -40°C to 85°C operating ranges. |
| LTPS Backplane Migration | AU Optronics G6 lines in Taichung enable higher pixel densities for premium notebook differentiation against OLED alternatives. |
| Mercury-Free Backlight Transition | LED phosphor redesigns disrupt qualified component libraries but align with tightening EU environmental standards. |
| India PLI Localization | Domestic assembly incentives create captive demand for 15-inch operator panels in process control applications. |
Research Methodology
Document review covered SEC filings from display panel manufacturers, MIIT GB standard publications, EU F-Gas Regulation impact assessments, and automotive OEM procurement disclosures, complemented by interviews with TFT array fabrication engineers, driver IC design leads, automotive Tier 1 procurement managers, industrial HMI system integrators, and medical device regulatory affairs specialists. Secondary sources included customs trade data for indium and glass substrate flows, AEC-Q100 qualification databases, and REACH documentation requirement guidelines. Bottom-up capacity modeling triangulated against top-down demand segmentation across application categories.
Historical shipment data cross-referenced against panel expert input established baseline volumes across the analysis window. The analytical framework modeled segmentation by resolution tier, touch integration depth, backplane technology, application vertical, and end-user contract structure. CAGRs were derived from supply-demand balance projections incorporating automotive digitization adoption curves and notebook replacement cycles. Industry-specific inputs included LTPS yield improvement trajectories, in-cell touch process maturation timelines, and mercury-free backlight conversion rates.
Inputs from automotive OEM procurement teams and medical device regulatory consultants were available through the study window; gaps in real-time indium spot pricing and driver IC talent pool metrics introduce uncertainty bands around cost assumptions. Forecasts reflect documented base-case assumptions regarding EU F-Gas compliance timelines and China MIIT energy efficiency enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Ultra High Definition (UHD) Panel (4K) Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Low Power Next Generation Display Market
Display Technologies
Light Field Display Market
Display Technologies
Projector Screen Market
Display Technologies
Global Projector Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Global UHD Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
Alphanumeric LCD Modules Market
Display Technologies
E-Paper Display Market
Display Technologies
Europe Transparent Conductive Films Market